
 Germany Electric Vehicle Battery Materials Market | 2026-2036
Germany Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Materials Market Insights
Market Context
CE marking under the EU Battery Regulation is redrawing competitive boundaries for cathode and anode material suppliers seeking access to German OEM supply chains. BASF SE leverages its Ludwigshafen integrated production complex to sustain captive precursor output for NMC cathodes. Umicore SA anchors its European refining and materials technology leadership through its Belgian-German operational footprint.
Technical Definition and Segment Structure
Germany electric vehicle battery materials encompass the engineered active and inactive substances—cathode powders, anode graphite, electrolyte salts, separators, and current collectors—that enable electrochemical energy storage in lithium-ion and emerging solid-state cell architectures, with NMC 811 and silicon-doped anode formulations now dominating energy density targets above 300 Wh per kilogram. Lithium-ion material type occupies the largest value pool given its entrenched scale across German OEM platforms, while solid-state chemistry represents the fastest-growing category as BMW and Volkswagen-backed pilot lines advance sulfide and oxide electrolyte qualification. Passenger vehicles application commands the dominant share of material offtake, though energy storage systems is gaining structural importance as grid-scale battery deployments accelerate across Germany's renewable-heavy power network.
Regulatory Framework
The EU Battery Regulation, REACH, and the ECHA-submitted restriction proposals on PFAS in fluorinated electrolyte additives collectively shape material composition mandates, supply chain due diligence obligations, and market access conditions for suppliers serving German cell manufacturers. KBA type-approval processes for battery systems further enforce safety and performance testing protocols that cascade backward into material specifications. Stakeholders must monitor the interplay between delegated acts on recycled content thresholds and the scale-up of domestic hydrometallurgical recycling capacity to secure qualified feedstock pipelines.
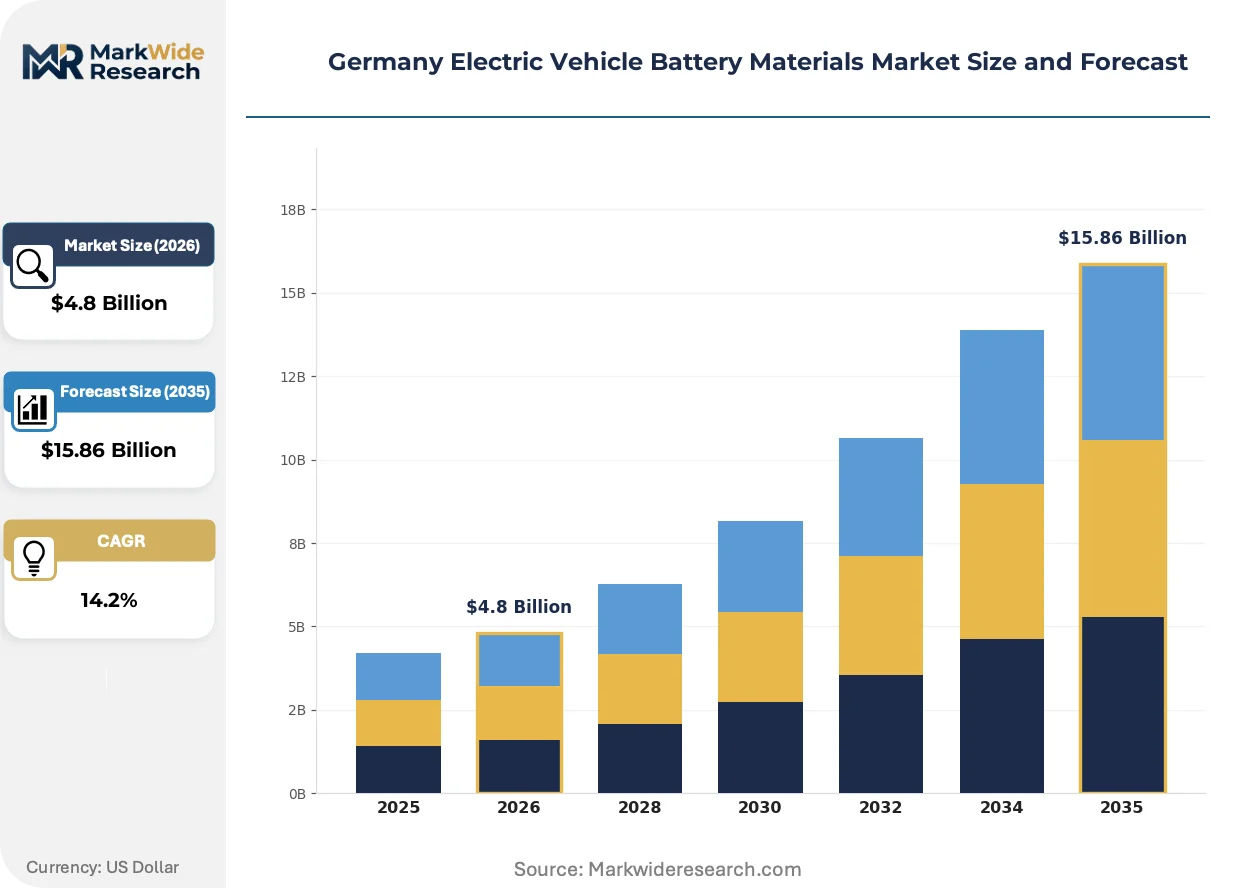
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are compressing qualification timelines for cathode and anode suppliers, forcing simultaneous investment in hydrometallurgical recycling infrastructure and green precursor production.
Growth Catalysts
- EU Battery Regulation recycled quotas:Mandates for minimum recovered lithium, cobalt, and nickel in new cells create certified demand for domestically processed black mass and precursor chemicals.
- Silicon-doped anode chemistry:German OEM energy density targets above 300 Wh per kilogram accelerate qualification of silicon oxide and silicon-carbon composite anodes for premium passenger vehicle platforms.
- Baden-Württemberg cell cluster:Concentrated gigafactory investment near Stuttgart generates localized demand for cathode active material, separator, and electrolyte salt production.
Market Restraints
- Spodumene concentrate dependency:German cell manufacturers rely on Australian and Canadian hard rock lithium feedstock, exposing margins to DDP Rotterdam pricing volatility and ocean freight rate swings.
- PFAS electrolyte additive restrictions:ECHA-submitted restriction proposals on fluorinated compounds threaten supply continuity for LiPF6 salts and functional electrolyte formulations.
- Graphite anode supply concentration:Synthetic and natural graphite processing capacity concentrates in China, creating single-source risk for anode active material qualification under CE marking timelines.
Strategic Opportunities
- Solid-state sulfide electrolyte pilot scale-up:BMW-backed qualification programs create first-mover slots for germanium-doped and argyrodite sulfide electrolyte material suppliers.
- Bavaria energy storage deployment:Grid-scale battery installations for renewable integration generate parallel demand for lithium iron phosphate cathode materials outside passenger vehicle supply chains.
- Domestic hydrometallurgical refining:Black mass processing capacity expansion in Saxony and North Rhine-Westphalia enables closed-loop precursor production aligned with EU Battery Regulation due diligence requirements.
Industry Challenges
- Cell engineering talent scarcity:Electrochemist and solid-state materials scientist recruitment lags behind gigafactory construction timelines, delaying process optimization and yield ramp.
- KBA type-approval cascade timelines:Battery system certification protocols require 18-24 month material qualification cycles that misalign with annual cathode chemistry refresh rates.
- Legacy combustion supply chain displacement:Powertrain supplier restructuring creates friction in workforce transition and facility repurposing for cell component manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Materials Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium-Ion, Nickel-Cobalt, Solid-State, Graphene Battery Technology: Li-ion, Ultra-Capacitors, Flow Batteries, Lead-Acid End User: OEMs, Aftermarket Providers, Research Institutions, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, Energy Storage Systems |
| Companies Covered | Targray Technology International Inc, Solvay SA, BASF SE, Heraeus Group, Mitsubishi Chemical Group Corporation, Umicore SA, Arkema SA, Wacker Chemie AG, Johnson Matthey, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Materials Market Trends and Innovations
Material chemistry roadmaps are diverging across German OEM platforms as energy density targets, cost floors, and regulatory compliance requirements create incompatible optimization paths for cathode and anode formulations.
Silicon-doped anode technology is fragmenting competitive positioning in the anode supply base. German passenger vehicle platforms above 800-volt architecture specify 5-10% silicon oxide loading today, with 20% silicon-carbon composites targeted for 2026 cell designs. This chemistry shift compresses graphite anode incumbent margins while opening qualification windows for metallurgical-grade silicon suppliers and CVD coating specialists.
REACH and the EU Battery Regulation are tightening material composition disclosure and due diligence obligations. Suppliers must now submit full substance inventories for cathode precursors and electrolyte additives, with ECHA SCIP database entries required for recycled content claims. High-nickel NMC cathode producers face accelerated testing protocols for nickel sulfate supply chain verification.
Cell manufacturers are consolidating procurement around qualified material suppliers with integrated carbon accounting. Long-term offtake agreements now specify kg CO2 per kWh thresholds for cathode active material, with third-party verification replacing supplier self-declaration. Bavaria-based energy storage system integrators are extending this requirement to lithium iron phosphate cell imports from non-European sources.
Germany Electric Vehicle Battery Materials Market Segmentation
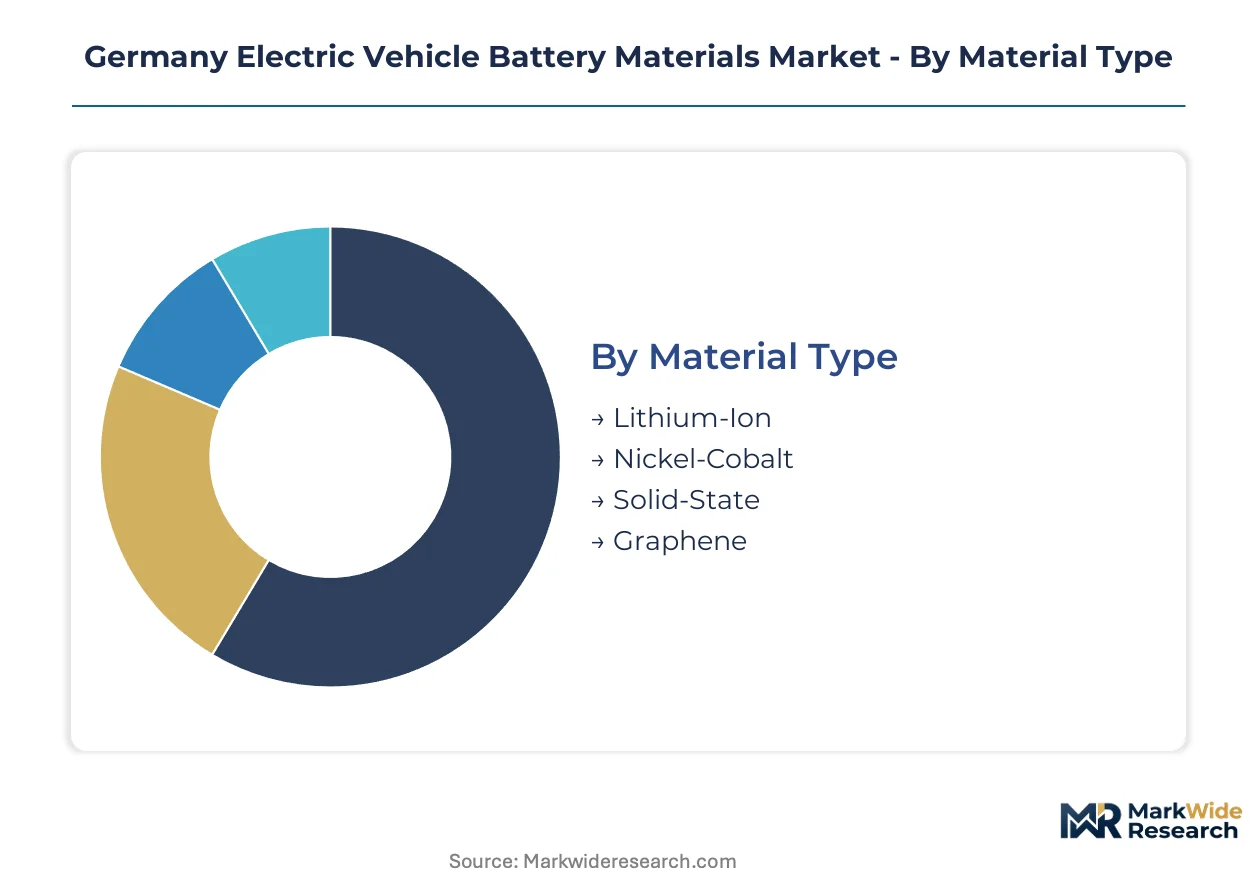
Material chemistry roadmaps diverge across German OEM platforms as energy density targets, cost floors, and regulatory compliance create incompatible optimization paths. Segmentation reveals where substitution pressure concentrates—solid-state chemistry threatening incumbent lithium-ion dominance, fleet operators reshaping procurement patterns distinct from OEM volume contracts.
Material Type:
Substitution pressure from solid-state and graphene formulations is compressing qualification timelines for incumbent cathode and anode suppliers, forcing dual-track investment in next-generation chemistries while scaling proven lithium-ion output.
- Lithium-Ion:NMC 811 and LFP cathode formulations dominate current German cell production, with BASF's Ludwigshafen complex supplying precursors for Stuttgart-area gigafactories. Baden-Württemberg OEM demand concentrates here for 800-volt passenger vehicle platforms requiring 300+ Wh per kilogram energy density.
- Solid-State:Sulfide and oxide electrolyte chemistries advance through BMW-backed pilot lines near Munich, targeting silicon-doped anode compatibility and simplified thermal management. Bavaria-based qualification programs create first-mover supply slots for germanium-doped sulfide electrolyte producers.
- Nickel-Cobalt:High-nickel cathode precursors face EU Battery Regulation recycled content mandates and ECHA due diligence requirements for supply chain verification.
- Graphene:Conductive additive applications in anode and cathode formulations remain nascent, with limited qualified supply from European sources.
Lithium-Ion retains volume leadership; Solid-State holds the steepest expansion curve.
Battery Technology:
Cost tier stratification separates premium lithium-ion cell supply from commoditized lead-acid displacement and emerging ultra-capacitor niche applications.
- Li-ion:Cylindrical, prismatic, and pouch formats serve distinct German OEM platform requirements, with cell-to-pack architectures eliminating module-level material intensity for Stuttgart-produced passenger vehicles.
- Ultra-Capacitors:Fast-charge buffering applications in hybrid commercial vehicle powertrains concentrate demand around Munich-based fleet electrification programs targeting depot-charged municipal transport.
- Flow Batteries:Vanadium and zinc-bromine chemistries address Bavaria grid-scale energy storage deployments requiring 8+ hour discharge duration beyond lithium-ion economic thresholds.
- Lead-Acid:Auxiliary power and starter battery replacement in light commercial vehicles faces accelerating displacement as 48-volt mild-hybrid systems expand across Volkswagen and Mercedes-Benz lineups.
Li-ion commands the dominant value pool; Flow Batteries are climbing fastest in energy storage applications.
End User:
Customer type fragmentation creates divergent procurement specifications—OEMs enforcing CE marking and carbon accounting, fleet operators prioritizing total-cost-of-ownership over upfront cell price.
- OEMs:Volkswagen, BMW, and Mercedes-Benz procurement teams mandate kg CO2 per kWh thresholds with third-party verification, consolidating supply around qualified material suppliers with integrated carbon accounting systems.
- Fleet Operators:Municipal transport authorities and logistics operators in North Rhine-Westphalia negotiate cell leasing and battery-as-a-service contracts that transfer material cost risk upstream to system integrators.
- Aftermarket Providers:Independent repair networks and battery remanufacturers source replacement cells and modules, facing KBA type-approval barriers for non-OEM certified material substitutions.
- Research Institutions:Fraunhofer and university laboratories pilot pre-commercial chemistries, generating limited but strategically significant demand for novel electrolyte salts and separator substrates.
OEMs retain volume leadership; Fleet Operators are gaining share fastest in commercial vehicle electrification.
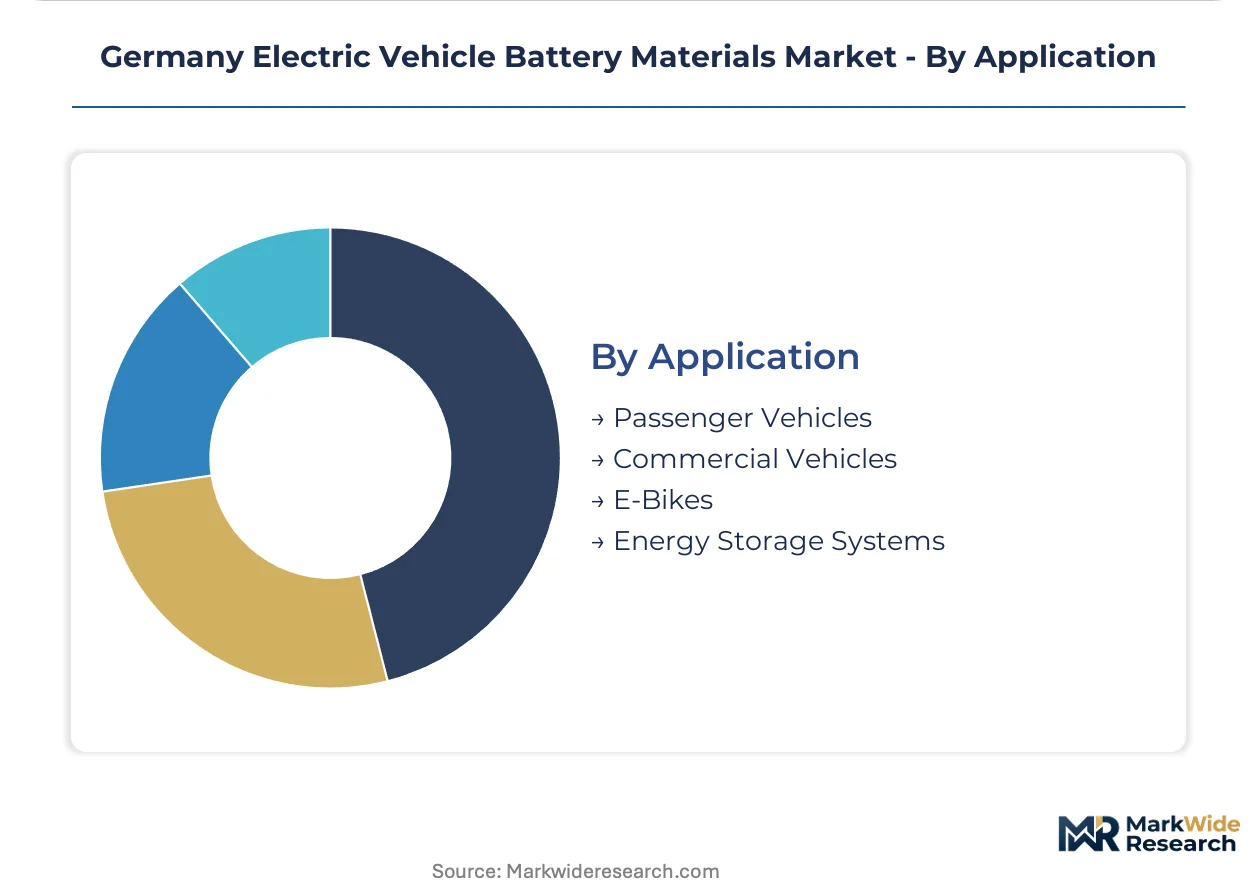
Application:
Application maturity separates established passenger vehicle material demand from emerging energy storage system requirements with distinct cathode chemistry preferences and qualification protocols.
- Passenger Vehicles:Premium German OEM platforms specify high-nickel NMC cathodes and silicon-doped anodes for 800-volt architectures, with material qualification cycles spanning 18-24 months under KBA certification protocols.
- Energy Storage Systems:Grid-scale battery deployments across Bavaria and northern Germany favor lithium iron phosphate cathodes for cycle life economics, with procurement extending carbon accounting requirements to non-European cell imports.
- Commercial Vehicles:Heavy-duty truck and bus electrification in Baden-Württemberg and Lower Saxony drives demand for high-cycle-life LFP and emerging sodium-ion alternatives for depot-charged urban logistics.
- E-Bikes:Light electric vehicle applications concentrate demand for compact cylindrical cell formats with lower material intensity, sourced through distinct supplier channels from automotive-grade material producers.
Passenger Vehicles retains volume leadership; Energy Storage Systems holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's federal incentive framework for cell manufacturing and the EU Battery Regulation's recycled content mandates are redrawing material demand geography across German states. Sub-regional clusters concentrate investment near OEM headquarters and port logistics corridors.
Baden-Württemberg
Stuttgart-centered passenger vehicle electrification drives cathode active material demand for 800-volt platforms. KBA type-approval protocols enforce 18-24 month qualification cycles for high-nickel NMC precursors. The Neckar-Alb region hosts BASF's precursor supply operations serving Mercedes-Benz and Porsche cell programs.
Bavaria
BMW-backed solid-state pilot lines near Munich generate first-mover demand for sulfide electrolyte materials. The state's grid-scale energy storage deployments favor lithium iron phosphate cathodes for renewable integration. Munich's technical university cluster supplies electrochemistry talent for cell engineering roles.
North Rhine-Westphalia
Ruhr Valley industrial restructuring repurposes chemical sites for hydrometallurgical black mass processing. The EU Battery Regulation's due diligence requirements concentrate recycling investment near Duisburg port logistics. Dortmund-based research institutes pilot novel electrolyte salt formulations.
Lower Saxony
Volkswagen's Salzgitter cell factory anchors demand for anode graphite and separator materials. The state's heavy-duty commercial vehicle electrification programs specify high-cycle-life LFP chemistries. Wolfsburg engineering centers coordinate material qualification with KBA certification timelines.
Germany Electric Vehicle Battery Materials Market Competitive Landscape
Listed leaders compete with private specialists across cathode precursor and electrolyte additive supply. The supplier base consolidates around integrated chemical conglomerates with REACH compliance infrastructure and carbon accounting systems. Three archetypes dominate: diversified chemical majors with captive precursor output, specialized battery material pure-plays, and Asian-backed trading houses with raw material origination. Capacity expansion and strategic partnerships constitute the primary competitive vectors as qualification timelines compress.
Among diversified chemical majors, BASF SE and Solvay SA exemplify the integrated production archetype with Ludwigshafen and Brussels-Antwerp corridor operations. Umicore SA occupies a position bridging materials technology and refining specialization. These three listed entities anchor supply relationships with German OEM procurement teams enforcing kg CO2 per kWh thresholds.
| Leading Market Players |
|---|
| Targray Technology International Inc |
| Solvay SA |
| BASF SE |
| Heraeus Group |
| Mitsubishi Chemical Group Corporation |
| Umicore SA |
| Arkema SA |
| Wacker Chemie AG |
| Johnson Matthey |
| Others |
Pricing and Supply Chain Analysis
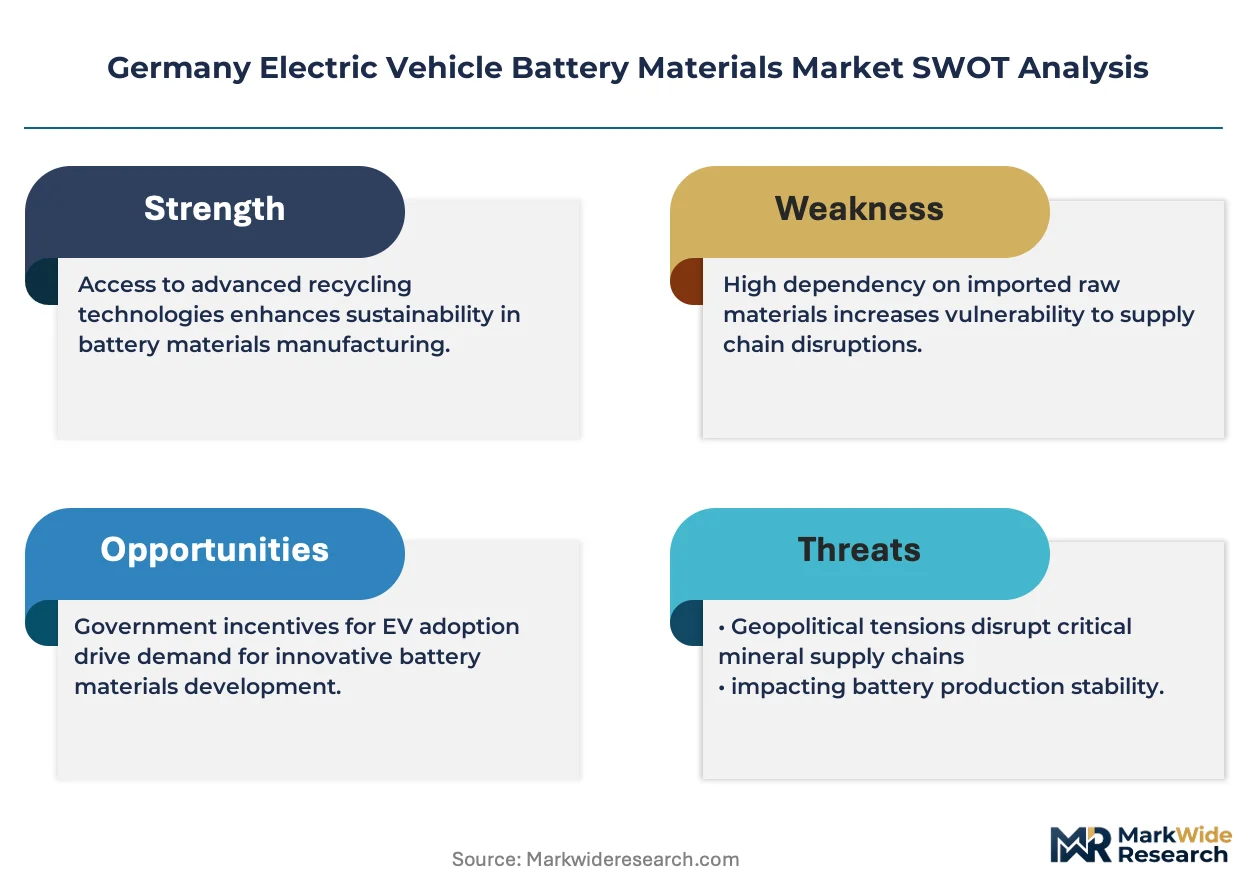
CE marking under the EU Battery Regulation gates both supply qualification and price differentiation simultaneously, forcing cathode and anode suppliers to absorb certification costs while OEM procurement teams enforce kg CO2 per kWh thresholds that stratify material tiers.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified material suppliers in the Germany electric vehicle battery materials market. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by carbon accounting verification and recycled content quotas. Cost compression in high-nickel NMC cathodes intensifies because OEMs consolidate volumes around integrated producers with captive precursor output. Fleet operators and energy storage system integrators exhibit highest price sensitivity, while premium passenger vehicle platforms tolerate elevated material costs for energy density performance.
Supply Chain Analysis
Inventory lead times for spodumene concentrate and synthetic graphite extend qualification cycles beyond 18 months for new suppliers entering German OEM supply chains. Raw material sourcing draws from Australian and Canadian hard rock lithium operations, Chinese graphite processing facilities, and Belgian-German refining corridors. Single-source vulnerability concentrates in anode active material qualification, where synthetic and natural graphite processing capacity remains tethered to Chinese producers. Distribution runs through Rotterdam port logistics and Rhine corridor chemical complexes serving Baden-Württemberg and Bavaria cell clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemist and solid-state materials scientist recruitment lags behind gigafactory construction timelines, creating a capability scarcity that constrains process optimization and yield ramp across German cell manufacturing.
For Market Incumbents: Secure captive black mass processing capacity in Saxony and North Rhine-Westphalia to align precursor output with EU Battery Regulation recycled content mandates. Deepen upstream control over lithium hydroxide refining through partnerships with Australian spodumene producers, defending margin position against emerging Asian trading houses with raw material origination advantages. For New Entrants and Emerging Players: Differentiate on sulfide electrolyte chemistry for BMW-backed solid-state pilot lines near Munich, where first-mover qualification windows remain open. Target Bavaria grid-scale energy storage deployments with lithium iron phosphate cathode materials, leveraging less stringent KBA certification timelines than passenger vehicle applications require. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrometallurgical recycling infrastructure as the EU Battery Regulation tightens due diligence requirements. Mid-cap specialists with integrated carbon accounting systems and REACH compliance infrastructure represent priority acquisition archetypes. Monitor delegated acts on recycled content thresholds as the signal indicating feedstock pipeline viability for closed-loop precursor producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Secures qualified hydroxide feedstock for NMC 811 cathode precursors serving Stuttgart gigafactories. |
| Hydrometallurgical Recycling Scale-Up | Enables closed-loop black mass processing aligned with EU Battery Regulation recycled content mandates. |
| Solid-State Electrolyte Qualification | Creates first-mover supply slots for sulfide chemistry in BMW-backed pilot lines near Munich. |
| Carbon Accounting System Integration | Satisfies OEM procurement requirements for third-party verified kg CO2 per kWh thresholds. |
| Long-Term Cathode Precursor Offtake | Locks in volume commitments from Mercedes-Benz and Volkswagen procurement teams. |
Research Methodology
Desk research of EU regulatory filings, trade customs data, and KBA type-approval databases preceded structured interviews with cathode precursor plant managers, OEM procurement leads, hydrometallurgical recycling operators, and ECHA regulatory affairs specialists. Secondary validation drew from BASF and Umicore SEC disclosures, German federal economic ministry reports, and Fraunhofer battery research publications. Bottom-up cell production forecasts triangulated against top-down OEM electrification targets across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across material type, battery technology, and application segmentation dimensions. CAGRs derived from slope analysis of OEM production schedules and cell chemistry roadmaps, with specific inputs including silicon-doped anode loading trajectories and solid-state pilot line capacity announcements. The modeling period captured divergent qualification timelines for lithium-ion versus next-generation chemistries.
Decision-makers should treat outputs as directional under assumptions of sustained EU Battery Regulation enforcement and stable lithium concentrate supply contracts; material deviation in delegated act timing or spodumene pricing volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium Battery in Myanmar Market