
 Automotive 48-Volt Lithium Ion Battery Market | 2026-2036
Automotive 48-Volt Lithium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 48-Volt Lithium Ion Battery Market Insights
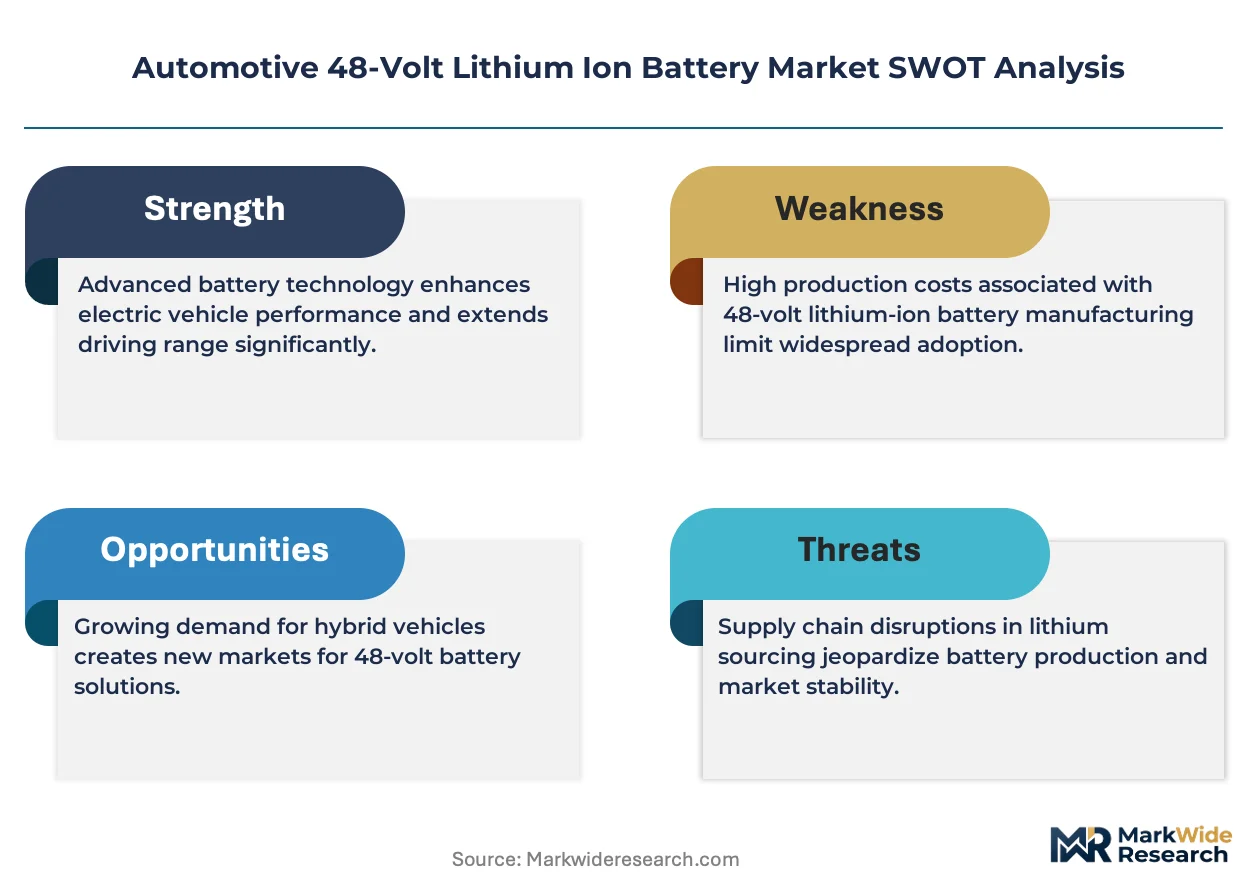
Modular battery pack architecture is recalibrating procurement decisions across the automotive value chain. Robert Bosch GmbH leverages its integrated powertrain portfolio to dominate module assembly for European OEM programs. Continental AG anchors its position through specialized thermal management systems that extend 48V pack durability. BorgWarner Inc. competes by concentrating manufacturing scale in cylindrical cell configurations for North American light-truck applications.
Automotive 48-volt lithium ion batteries are electrochemical energy storage systems operating at 48 volts nominal, typically employing lithium iron phosphate or lithium nickel manganese cobalt cathode chemistries with graphite anodes, designed to deliver peak currents of 10-20 kW for mild-hybrid power assist and regenerative braking recovery. Their primary industrial purpose is to reduce CO2 emissions and improve fuel economy in internal combustion vehicles without the cost burden of full high-voltage electrification. Battery pack assembly leads value capture due to integration complexity, while pouch cell formats represent the fastest-growing segment as automakers prioritize packaging flexibility and weight reduction. Start-stop systems remain the mature application baseline, though electric drive assist is displacing conventional alternator-starter configurations in premium vehicle segments.
The EU Green Deal and F-Gas Regulation are tightening thermal management refrigerant standards, directly influencing 48V pack cooling system design and supplier qualification timelines. China's MIIT dual carbon goals and GB standards for new energy vehicle components are accelerating local content requirements for 48V systems sold into domestic assembly plants. EPA fuel economy rules and NHTSA safety standards in the United States are sustaining OEM investment in mild-hybrid architectures as a compliance pathway. Stakeholders must monitor how battery passport traceability mandates under the EU Battery Regulation reshape supply chain documentation and cell sourcing strategies.
Market Dynamics
The EU Green Deal's CO2 fleet targets are compressing automaker timelines for mild-hybrid integration, forcing 48V system procurement to outpace traditional powertrain development cycles. This regulatory pressure is concentrating supplier qualification decisions around thermal management and cell sourcing capabilities.
Growth Catalysts
- EU Green Deal mandates:Binding CO2 reduction targets for 2030 and 2035 are compelling passenger car OEMs to adopt 48V mild-hybrid architectures as the lowest-cost compliance pathway for internal combustion platforms.
- China MIIT dual carbon goals:Domestic content requirements under GB standards for new energy vehicle components are accelerating local 48V battery assembly capacity expansion for foreign-brand joint ventures.
- Regenerative braking recovery:Advances in lithium iron phosphate cell chemistry are extending cycle life under high-current charge acceptance, enabling broader deployment across C-segment vehicle platforms.
Market Restraints
- Cylindrical cell supply concentration:Manufacturing capacity for high-rate 21700 and 26650 formats clusters among East Asian suppliers, creating single-source risk for North American light-truck programs.
- F-Gas Regulation thermal management costs:The EU's tightening refrigerant standards under the F-Gas framework are forcing costly redesigns of 48V pack cooling circuits and extending supplier qualification timelines.
- Full hybrid substitution:Toyota's parallel hybrid architecture and Honda's two-motor system continue capturing fuel economy-conscious buyers who might otherwise select 48V mild-hybrid configurations.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for advanced chemistry cell manufacturing are attracting 48V module assembly investment to serve Maruti Suzuki and Hyundai Motor India powertrain programs.
- Battery passport traceability:EU Battery Regulation mandates for supply chain documentation are creating first-mover advantage for suppliers with established cell provenance tracking systems.
- Commercial vehicle electrification:Medium-duty truck platforms in Germany and South Korea are emerging as testbeds for 48V starter-generator systems in delivery and urban freight applications.
Industry Challenges
- Thermal runaway containment engineering:Pack designers must satisfy UN ECE R100 propagation test requirements while maintaining the packaging flexibility automakers demand for underfloor and engine-bay mounting.
- Legacy 12V electrical architecture integration:DC-DC converter reliability and voltage transient management are complicating platform engineering for vehicles retaining conventional low-voltage accessory loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 48-Volt Lithium Ion Battery Market |
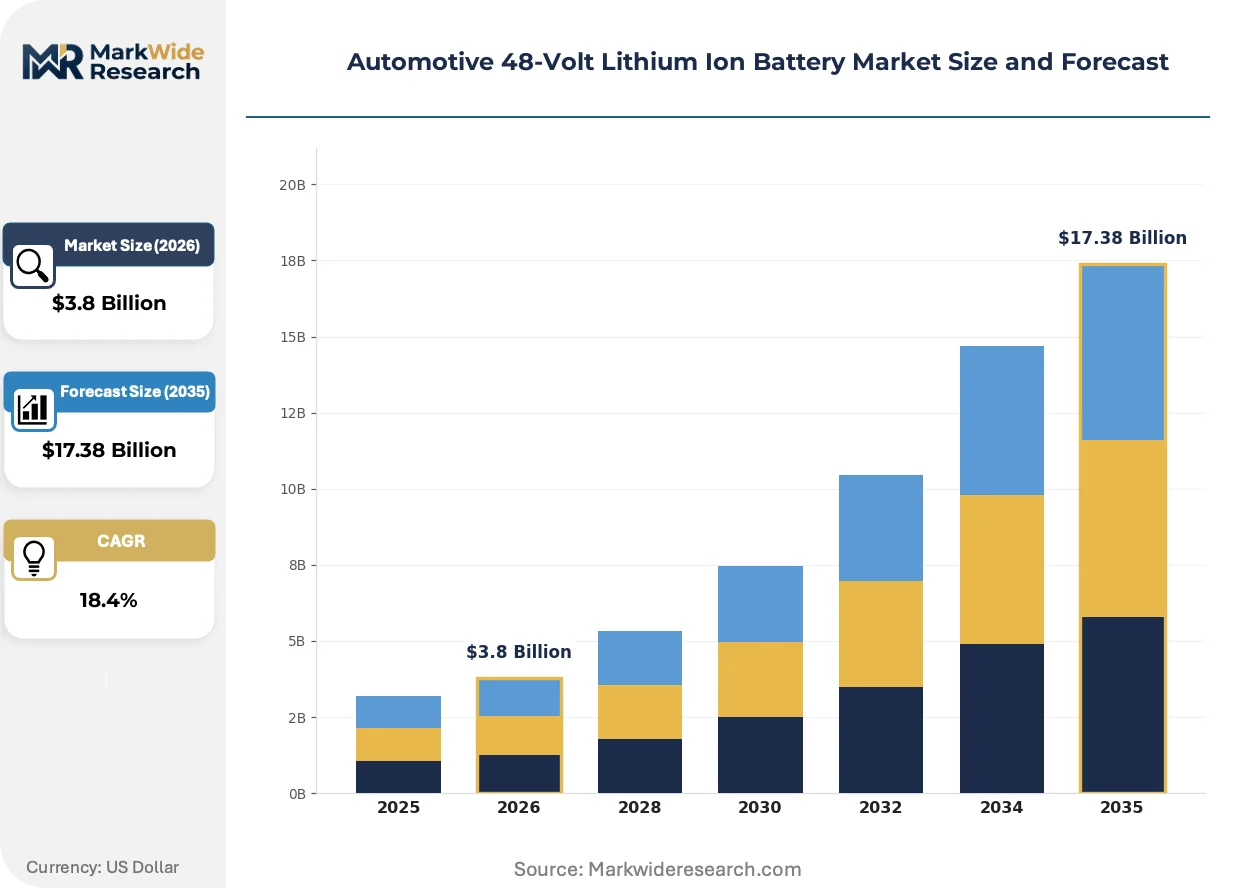
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Pouch Cells, Battery Packs Technology: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Manganese Oxide, Lithium Nickel Manganese Cobalt End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Start-Stop Systems, Electric Drive, Power Accessories, Regenerative Braking |
| Companies Covered | Robert Bosch GmbH, Continental AG, BorgWarner Inc., Valeo SA, Denso Corporation, Mitsubishi Electric Corporation, Hyundai Mobis Co., Ltd., A123 Systems LLC, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 48-Volt Lithium Ion Battery Market Trends and Innovations
Cell-to-pack architectures and intelligent battery management systems are compressing the value chain, blurring traditional boundaries between cell suppliers, module assemblers, and thermal management specialists. These structural shifts are redefining competitive positioning.
Solid-state electrolyte research is converging with 48V system development as automakers seek higher energy density without the thermal management burden of liquid electrolyte cells. BMW and Ford have accelerated their solid-state roadmaps for mild-hybrid applications, targeting 2028 production volumes. This technology convergence is compressing the performance gap between 48V and entry-level high-voltage systems.
The EU Battery Regulation's due diligence and carbon footprint declaration requirements are forcing suppliers to reconfigure documentation systems and upstream auditing protocols. Cell manufacturers must now track and verify cobalt, lithium, and nickel sourcing through smelter and mine levels. German and French OEM programs are most affected, with qualification timelines extending six to twelve months for non-compliant suppliers.
Fleet procurement managers are consolidating 48V battery sourcing across multiple vehicle nameplates to capture volume pricing and simplify service part logistics. This buyer concentration is displacing the program-specific supplier relationships that historically dominated mild-hybrid development. The trend is most visible in South Korea, where Hyundai-Kia's integrated procurement function is standardizing cell specifications across its domestic and export vehicle lines.
Automotive 48-Volt Lithium Ion Battery Market Segmentation
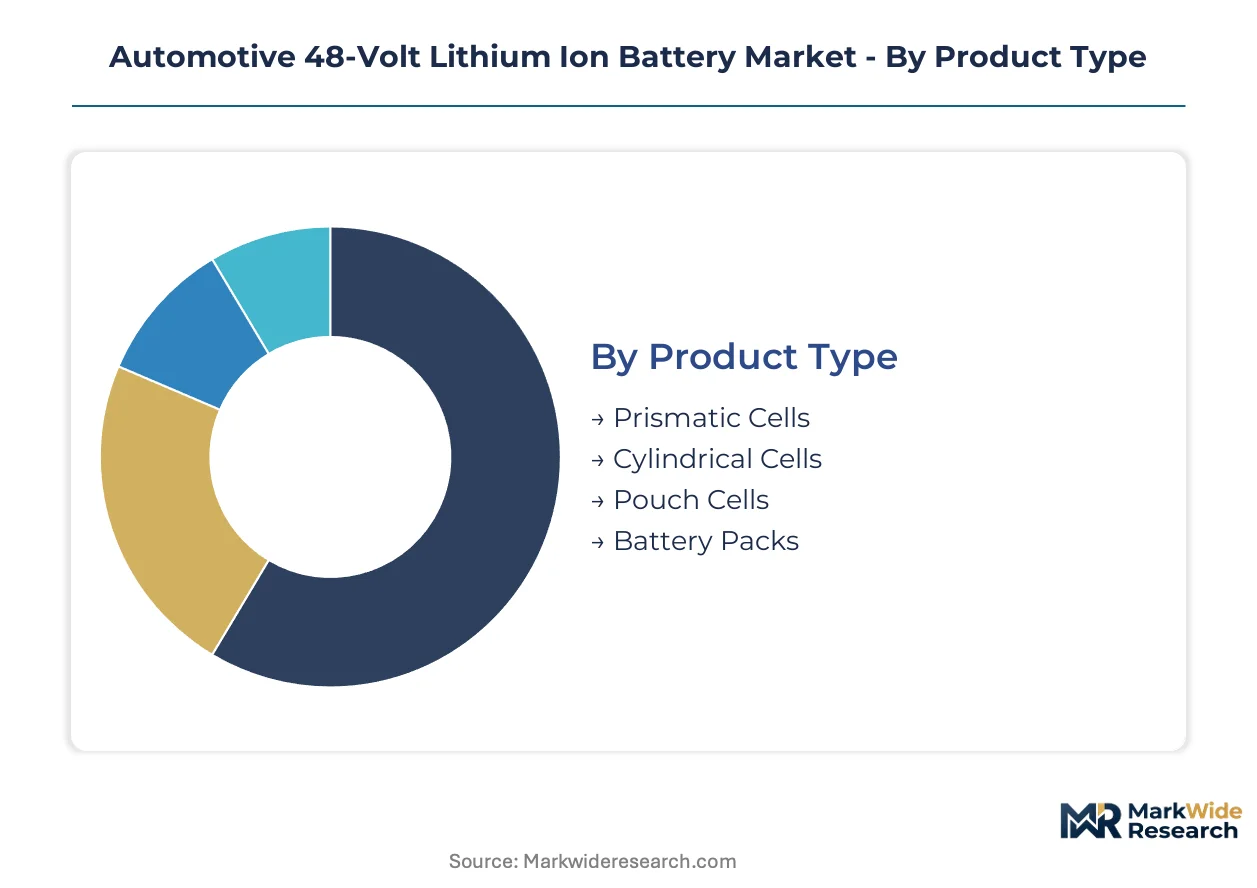
Cell format selection and cathode chemistry choices determine thermal management architecture, procurement cost structures, and pack integration complexity across mild-hybrid platforms. Automakers segment sourcing strategies by manufacturing scale, regulatory exposure, and powertrain electrification intensity.
Product Type:
Packaging geometry dictates cooling circuit design and module assembly automation requirements, with cylindrical formats favoring high-rate cylindrical winding equipment and pouch formats demanding precision lamination lines.
- Battery Packs:Integrated assemblies combining cells, battery management systems, and thermal management hardware deliver 10-20 kW peak power for mild-hybrid assist. German OEM programs concentrate procurement here due to EU Battery Regulation traceability mandates and integrated powertrain sourcing strategies.
- Pouch Cells:Laminated aluminum-laminate enclosures maximize volumetric energy density and packaging flexibility for underfloor mounting. South Korean and Chinese automakers prioritize this format for C-segment vehicle platforms where space constraints dominate design tradeoffs.
- Cylindrical Cells:21700 and 26650 formats with steel can enclosures dominate North American light-truck applications.
- Prismatic Cells:Hard-case aluminum housings suit engine-bay mounting with passive cooling.
Battery Packs lead on scale; Pouch Cells lead on momentum.
Technology:
Cathode chemistry selection balances cycle life, charge acceptance rate, and raw material cost exposure against specific powertrain duty cycles.
- Lithium Iron Phosphate:Olivine crystal structure delivers 3,000-5,000 cycle life with superior thermal stability for high-current regenerative braking recovery. China's MIIT dual carbon goals and GB standards accelerate domestic LFP cell capacity expansion for 48V systems.
- Lithium Nickel Manganese Cobalt:Layered oxide chemistry achieves higher energy density for packaging-constrained applications. EU Battery Regulation due diligence requirements concentrate European OEM procurement on suppliers with verified cobalt and nickel provenance tracking.
- Lithium Manganese Oxide:Spinel structure offers cost-positioned alternatives for entry mild-hybrid systems.
- Lithium Cobalt Oxide:High-voltage chemistry sees limited 48V adoption due to cost and thermal profile.
Lithium Iron Phosphate dominates volume; Lithium Nickel Manganese Cobalt climbs the fastest.
End User:
Procurement authority concentration varies by automaker organizational structure, with integrated powertrain divisions consolidating cell sourcing versus decentralized platform engineering teams.
- OEMs:Volkswagen Group, Hyundai-Kia, and Geely Holding operate captive battery engineering centers that specify cell formats and qualify module assemblers directly. Their integrated procurement functions standardize 48V specifications across multiple nameplates to capture volume pricing.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG supply complete 48V systems to automakers lacking in-house powertrain electrification capabilities.
- Vehicle Assemblers:Contract manufacturers rely on specified supplier lists from brand owners.
- Aftermarket Providers:Service part distributors address warranty replacement and retrofit demand.
OEMs lead on scale; Tier-1 Suppliers lead on momentum.
Application:
Power assist intensity and duty cycle duration determine cell specification, with continuous electric drive applications demanding higher sustained discharge capability than transient start-stop events.
- Electric Drive:Sustained 10-15 kW motor assist for low-speed torque fill and cruising power requires high-rate cell chemistry and active thermal management. Premium German OEMs deploy this configuration in C-segment and D-segment sedans to meet EU Green Deal CO2 fleet targets.
- Regenerative Braking:High-current charge acceptance during deceleration events stresses cell cycle life and drives LFP chemistry preference. South Korean automakers optimize this application for urban driving profiles with frequent stop-start patterns.
- Start-Stop Systems:Transient crank support represents the baseline mild-hybrid function.
- Power Accessories:48V supply for active suspension and electric turbocharging expands electrical load capacity.
Electric Drive leads on scale; Regenerative Braking leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered 48V mild-hybrid system integration through its premium OEM engineering centers, establishing the technical and regulatory template that now shapes procurement patterns across automotive electrification programs worldwide.
Germany
Volkswagen Group and BMW powertrain divisions drive 48V battery specification for EU Green Deal compliance. The F-Gas Regulation tightens refrigerant standards for thermal management systems. Stuttgart and Munich engineering clusters host module assembly qualification programs for domestic and export vehicle lines.
China
Geely Holding and BYD expand 48V production for C-segment platforms targeting domestic fuel economy standards. MIIT dual carbon goals accelerate GB standards enforcement for new energy vehicle components. Yangtze River Delta cell manufacturers scale lithium iron phosphate capacity for joint-venture OEM supply.
South Korea
Hyundai-Kia integrates 48V systems across SUV and sedan nameplates for export markets. MFDS alignment with EU Battery Regulation traceability protocols extends supplier documentation requirements. Busan-Ulsan industrial corridor concentrates cylindrical cell winding capacity for North American light-truck programs.
United States
Ford and General Motors deploy 48V mild-hybrid architectures in full-size pickup trucks to satisfy EPA fuel economy rules. NHTSA safety standards govern pack mounting and crashworthiness validation. Michigan powertrain engineering centers specify thermal management systems for Detroit Three electrification roadmaps.
Automotive 48-Volt Lithium Ion Battery Market Competitive Landscape
The competitive structure tilts toward integrated powertrain conglomerates with captive module assembly capabilities. Supplier qualification decisions concentrate around thermal management engineering and cell sourcing traceability systems. Two strategic archetypes dominate: diversified automotive suppliers leveraging full-system portfolios, and specialized battery manufacturers concentrating on high-rate cell formats. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs compress development timelines.
Among diversified German suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated powertrain archetype, anchoring European OEM procurement through complete 48V system offerings. BorgWarner Inc. occupies a position within the North American specialist tier, representing manufacturing scale concentration in cylindrical configurations for light-truck applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| BorgWarner Inc. |
| Valeo SA |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Hyundai Mobis Co., Ltd. |
| A123 Systems LLC |
| ZF Friedrichshafen |
| Others |
Pricing and Supply Chain Analysis
OEM procurement consolidation across multiple vehicle nameplates is compressing supplier margins and forcing module assemblers to absorb thermal management cost inflation or risk volume displacement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs 48V battery procurement, with EU Battery Regulation traceability certification and active liquid cooling capability separating tiers. Price differentiation hinges on cell provenance documentation depth and thermal management sophistication. Cost compression in economy-tier pouch cell supply is intensifying because Yangtze River Delta manufacturers are scaling lithium iron phosphate capacity faster than demand absorption. Fleet procurement managers at volume OEMs exhibit highest price sensitivity, while premium German OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Freight cost volatility on Asia-Europe routes is reshaping sourcing geography as cell manufacturers accelerate regional module assembly investment. Manufacturing gravity centers on China, South Korea, and Germany, with cylindrical cell winding capacity concentrated in Busan-Ulsan and prismatic assembly clustering in Stuttgart-Munich. The supply chain draws from cobalt and nickel feedstock processed in Indonesia and the Democratic Republic of Congo, creating single-source vulnerability for European OEM programs. Distribution runs through Tier 1 system integrators rather than direct cell-to-OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's binding CO2 fleet targets for 2030 and 2035 compound regulatory demand into a structural growth driver that outpaces conventional powertrain replacement cycles.
For Market Incumbents: Deepen backward integration into lithium iron phosphate cathode material production to offset raw material cost volatility and secure qualification timelines under EU Battery Regulation traceability mandates. Expand module assembly capacity in India to capture PLI scheme benefits and serve Maruti Suzuki powertrain programs before joint-venture suppliers consolidate positions. For New Entrants and Emerging Players: The gap between premium liquid-cooled systems and economy air-cooled configurations creates entry space for mid-tier suppliers offering standardized pouch cell modules with passive thermal management. Target aftermarket warranty replacement channels where documentation requirements are less stringent than OEM qualification. Pursue commercial vehicle electrification programs in Germany and South Korea as testbed customers with lower volume barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal management engineering firms possessing established EU F-Gas Regulation compliance records and active cooling circuit IP. The five-to-ten year viability window favors acquisition targets with cell-to-pack architecture capabilities and battery management system software stacks. Monitor India PLI scheme disbursement velocity as inflection indicator for regional manufacturing investment commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Hyundai-Kia's consolidated procurement function demonstrates volume pricing capture across SUV and sedan nameplates. |
| Battery Supply Agreement | Long-term offtake contracts with Yangtze River Delta cell manufacturers secure lithium iron phosphate allocation for joint-venture programs. |
| Software-Defined Vehicle Investment | Intelligent battery management system development blurs boundaries between module assemblers and thermal management specialists. |
| Geographic Manufacturing Footprint | India PLI scheme localization attracts 48V module assembly investment to serve Maruti Suzuki and Hyundai Motor India. |
| Charging Infrastructure Partnership | Regenerative braking optimization requires collaboration with urban freight fleet operators on duty cycle profiling. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down cell capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, thermal management system designers, and aftermarket distributors were cross-validated against secondary sources including vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and EU Battery Regulation implementation guidance. Supply-side triangulation against cathode material trade flows and module assembly capacity announcements ensures demand estimates anchor in verifiable production commitments.
Input-output matrices map propulsion architecture adoption rates, content per vehicle by mild-hybrid intensity, and regional production cluster output across the analysis window. Segmentation dimensions include cell format geometry, cathode chemistry selection, end-user procurement authority structure, and application duty cycle requirements. CAGRs were derived from slope analysis of year-over-year platform deployment schedules and OEM electrification roadmap disclosures, with lithium iron phosphate cost curves and F-Gas Regulation compliance timelines as industry-specific modifiers.
Caveats apply where EU Battery Regulation traceability mandate enforcement delays or China MIIT dual carbon goal recalibration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market