
 Laminated Lithium Ion Secondary Battery Market | 2026-2036
Laminated Lithium Ion Secondary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Lithium Ion Secondary Battery Market Insights
The EU Battery Regulation is pivoting procurement standards across the European electric vehicle supply chain toward mandatory recycled content thresholds and carbon footprint declarations. LG Energy Solution Ltd. leverages its European plant network to anchor regional compliance capabilities. Samsung SDI Co., Ltd. competes through specialized high-nickel NMC formulations for premium automotive platforms. Panasonic Energy Co., Ltd. sustains manufacturing scale advantages in cylindrical cell architectures for North American EV OEMs.
Laminated lithium ion secondary batteries employ stacked or z-fold electrode layers sealed within aluminum-laminated polymer films, achieving energy densities of 250-300 Wh/kg with thickness profiles below 8mm for space-constrained applications. These cells serve primarily as power sources for electric vehicles, smartphones, and grid-scale storage systems where volumetric efficiency outweighs structural rigidity requirements. Pouch cells capture expanding share in automotive modules due to packaging flexibility and weight optimization, while prismatic formats dominate industrial applications where thermal management integration and mechanical stability prove critical. LFP chemistry segments are gaining traction in renewable energy storage as cycle-life economics improve, contrasting with NMC's continued hold on performance-oriented electric vehicle platforms.
The EU Battery Regulation, China's GB standards administered by SAMR, and EPA hazardous material transport rules collectively reshape cell design, labeling, and end-of-life accountability across major demand centers. ECHA REACH compliance now extends to nickel and cobalt supply chain due diligence, elevating documentation burdens for non-integrated manufacturers. Stakeholders must monitor evolving carbon border adjustment mechanisms and chemistry-specific recycling mandates to preserve market access and procurement eligibility.
Market Dynamics
Fleet electrification mandates and cell-level carbon accounting requirements are compressing procurement cycles across automotive supply chains, forcing laminated cell manufacturers to reconfigure qualification protocols and regional production footprints simultaneously.
Growth Catalysts
- EU Battery Regulation recycled content mandates:OEMs must source minimum recycled lithium, cobalt, and nickel by specified phase-in dates, creating guaranteed offtake for certified cell producers with closed-loop supply partnerships.
- Electric bus fleet conversions in urban transit authorities:Municipal procurement programs in Germany, South Korea, and California specify pouch-format batteries for route flexibility and depot charging infrastructure compatibility.
- Silicon-anode laminated cell architectures:Next-generation electrode formulations boost energy density thresholds for premium passenger EV platforms without sacrificing cycle life under fast-charging protocols.
Market Restraints
- Aluminum-laminated film supply concentration:Japanese and South Korean polymer film suppliers control 70%+ of qualified automotive-grade supply, creating single-source vulnerability for European and North American cell plants.
- High-purity nickel sulfate price volatility:Indonesian nickel processing expansion has not eliminated Class 1 battery-grade supply tightness, squeezing NMC cathode cost structures.
- Cell-to-pack thermal propagation standards:UN ECE R100 and China's GB 38031 testing protocols extend certification timelines and require redundant safety engineering that adds mass and cost.
Strategic Opportunities
- Grid-scale stationary storage in Texas ERCOT and California CAISO markets:LFP laminated cells qualify for IRA domestic content bonuses when assembled in qualified U.S. facilities, opening utility-scale procurement channels.
- Marine electrification for short-haul ferries:Norwegian and Danish maritime regulators are approving pouch-cell battery systems for coastal vessel routes under new IMO-adjacent safety frameworks.
- Second-life battery aggregation platforms:Automotive OEMs and independent operators are building data-driven residual value models to extract secondary revenue from degraded EV packs before recycling.
Industry Challenges
- Electrolyte formulation chemist scarcity:The specialized knowledge required for high-voltage additive packages and solid-state interface engineering concentrates in a handful of research institutions and incumbent firms.
- Gigafactory construction cycle compression:Equipment lead times for electrode coating and formation lines now exceed 24 months, forcing capital commitment before customer qualification completion.
- Cross-border carbon accounting verification:Scope 3 emissions disclosure requirements under EU CBAM and proposed U.S. SEC climate rules demand supplier data infrastructure that many mid-tier material processors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Lithium Ion Secondary Battery Market |
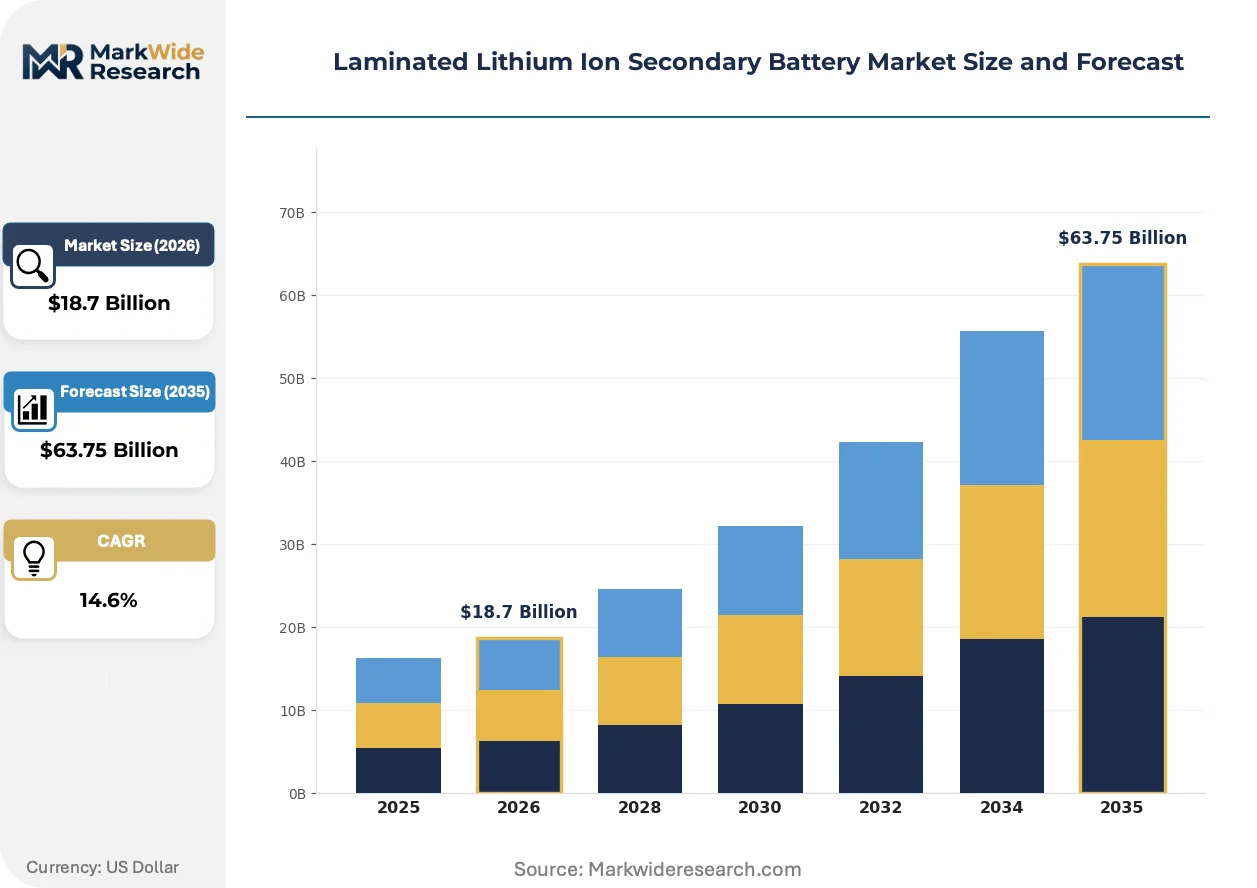
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Pouch Cells, Cylindrical Cells, Modules Technology: LFP, NMC, NCA, LTO End User: Consumer Electronics, Electric Vehicles, Renewable Energy, Industrial Applications Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | LG Energy Solution Ltd., Panasonic Energy Co., Ltd., Samsung SDI Co., Ltd., Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, SK On Co., Ltd., Hitachi Energy Ltd., A123 Systems LLC, Envision AESC Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Lithium Ion Secondary Battery Market Trends and Innovations
Electrode stacking automation and dry-coating electrode processes are collapsing manufacturing energy intensity while cell format flexibility enables module-level design optimization previously constrained by cylindrical architectures.
Dry electrode coating technology eliminates solvent-based slurry processing and reduces electrode production energy consumption by half. BMW and Tesla have qualified dry-coated anodes for pilot production lines. This process is expanding into high-nickel cathode manufacturing where solvent recovery costs previously dominated operational expenditure.
China's GB standards administered by SAMR now mandate thermal runaway propagation resistance testing for all passenger vehicle battery systems, exceeding UN ECE R100 requirements in some test configurations. Cell producers serving the Chinese market must redesign venting pathways and separator materials. European OEMs with Chinese joint ventures are adopting these test protocols globally to simplify variant management.
Fleet operators and energy storage developers are consolidating procurement through long-term offtake agreements with direct cell manufacturer relationships, bypassing traditional tier-one battery pack integrators. This disintermediation concentrates volume with qualified cell plants and shifts technical integration responsibility to in-house engineering teams. The pattern is most visible in North American utility-scale storage and European commercial vehicle segments where total cost of ownership modeling dominates vendor selection.
Laminated Lithium Ion Secondary Battery Market Segmentation
Segmentation in laminated lithium ion batteries reveals how format flexibility, chemistry trade-offs, and channel structures align with diverging customer technical requirements and procurement workflows across automotive, grid storage, and consumer applications.
Product Type:
Upgrade cycles in electric vehicle platforms are compressing format qualification timelines as OEMs revalidate cell-to-pack architectures against revised thermal propagation standards.
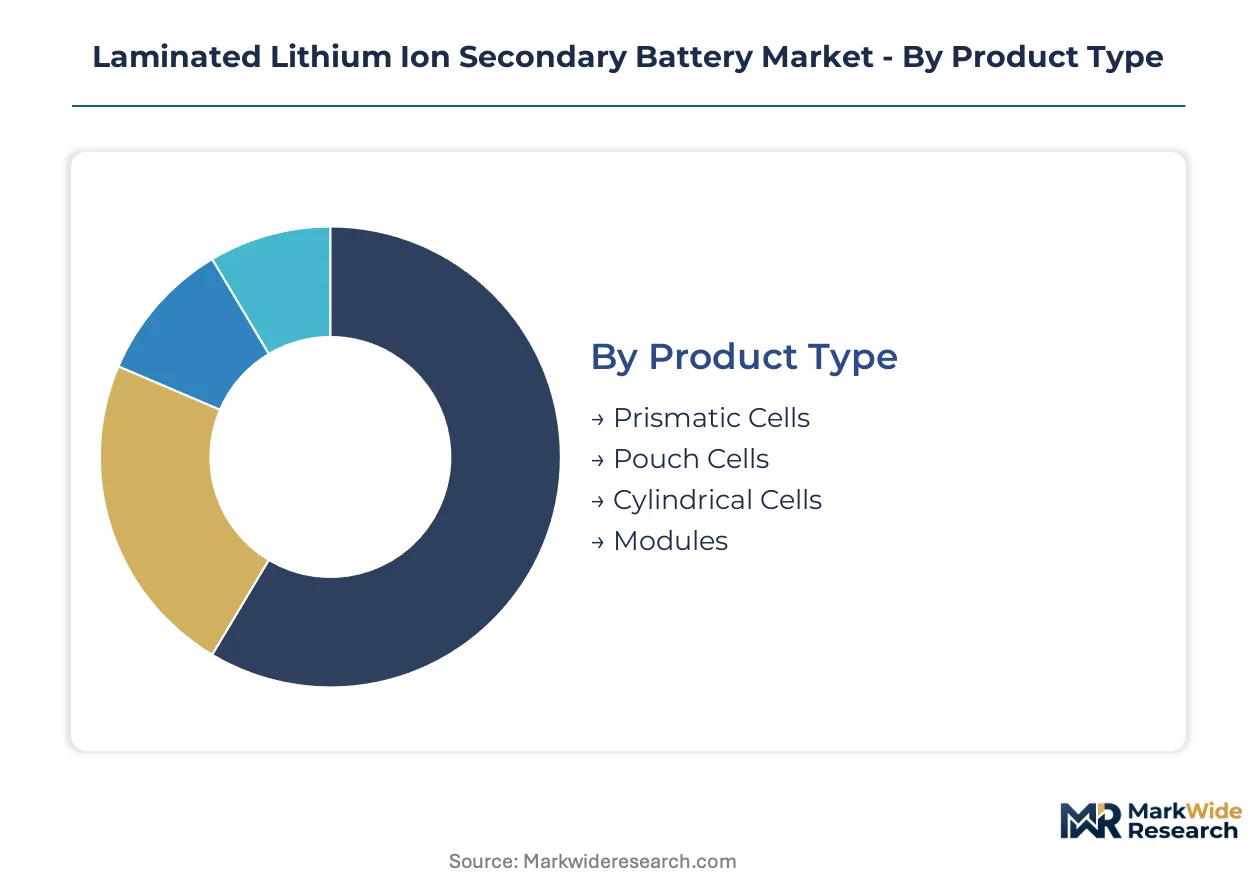
- Pouch Cells:Aluminum-laminated polymer enclosures enable z-fold electrode stacking with thickness profiles below 8mm. European electric bus procurement programs in Germany and Denmark specify pouch formats for depot charging compatibility and route flexibility optimization.
- Prismatic Cells:Hard-cased rectangular formats with stacked electrode layers integrate directly into module thermal management systems. Industrial applications in China and South Korea favor prismatic architectures where mechanical stability and cooling channel integration prove critical for cycle-life economics.
- Cylindrical Cells:Rolled electrode jellyrolls in metal cans dominate North American EV OEM supply agreements through established qualification pathways and automated production scale.
- Modules:Pre-assembled cell arrays with integrated battery management systems accelerate pack assembly for utility-scale storage developers in Texas ERCOT and California CAISO markets.
Pouch cells sit at the top of the volume ranking, with prismatic formats climbing the fastest as industrial and commercial vehicle segments expand procurement.
Technology:
Cost tier differentiation across cathode chemistries is widening as LFP cell prices compress and high-nickel formulations absorb volatile nickel sulfate premiums.
- NMC:Nickel-manganese-cobalt layered oxides deliver 250-300 Wh/kg energy density for premium passenger EV platforms. South Korean cell producers dominate high-nickel NMC supply to European automotive OEMs facing EU Battery Regulation carbon footprint disclosure mandates.
- LFP:Lithium iron phosphate chemistry trades energy density for cycle-life economics and thermal stability. Grid-scale storage deployments in U.S. markets leverage LFP laminated cells for IRA domestic content bonus eligibility.
- NCA:Nickel-cobalt-aluminum formulations target high-performance applications requiring specific power-to-weight ratios in premium electric vehicle segments.
- LTO:Lithium titanate anode systems enable extreme fast-charging cycles for commercial vehicle and industrial equipment applications where charge time minimization outweighs energy density requirements.
NMC retains the dominant revenue position, though LFP is gaining share fastest in stationary storage and entry-level electric vehicle segments.
End User:
Application-specific performance requirements are fragmenting procurement specifications as automotive, grid, and industrial customers impose incompatible validation protocols.
- Electric Vehicles:Passenger and commercial vehicle platforms drive laminated cell demand through cell-to-pack integration trends. China's GB 38031 thermal runaway standards and UN ECE R100 protocols govern qualification requirements for Chinese and European OEM supply agreements.
- Renewable Energy:Utility-scale and distributed storage systems prioritize cycle-life economics over gravimetric energy density. LFP chemistry laminated cells capture expanding share in California and Texas grid interconnection queues.
- Consumer Electronics:Smartphones, laptops, and wearable devices require ultra-thin pouch formats with 250+ Wh/kg energy density for space-constrained industrial design.
- Industrial Applications:Forklifts, material handling equipment, and stationary backup power systems specify prismatic formats with integrated thermal management and mechanical durability.
Electric vehicles anchor current volume leadership, with renewable energy storage demonstrating the steepest expansion trajectory as interconnection backlogs drive procurement urgency.
Distribution Channel:
Customer type and procurement scale are reshaping channel structures as fleet operators and utility developers consolidate direct manufacturer relationships.
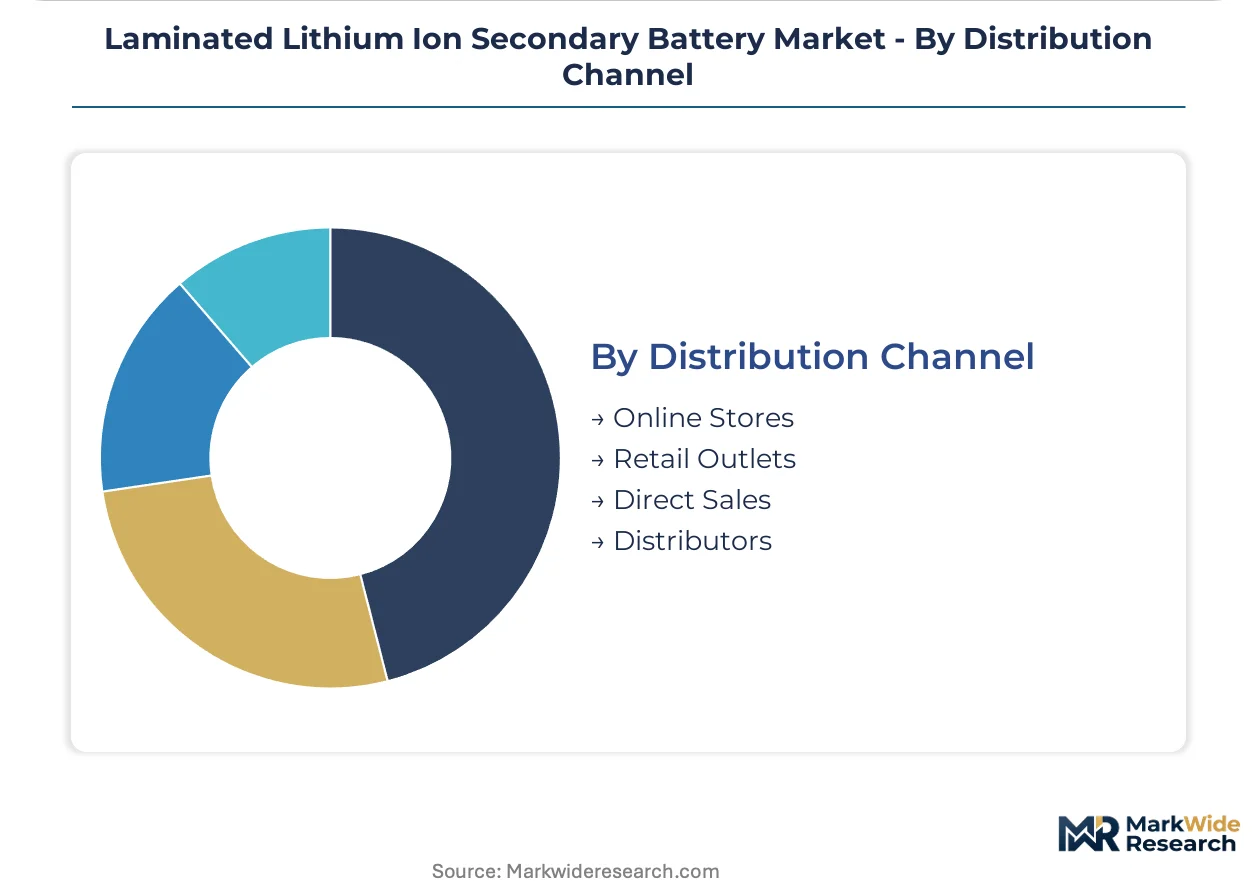
- Direct Sales:Long-term offtake agreements between cell manufacturers and automotive OEMs, energy storage developers, and commercial fleet operators. This channel concentrates high-volume procurement and shifts technical integration responsibility to customer engineering teams.
- Distributors:Regional inventory and technical support networks serve mid-tier industrial customers and aftermarket replacement demand with shorter lead time requirements.
- Online Stores:E-commerce platforms capture small-lot procurement for consumer electronics replacement batteries and hobbyist applications.
- Retail Outlets:Physical storefronts address immediate replacement needs in consumer electronics and limited industrial tool battery segments.
Direct sales channels command the highest volume concentration, with distributor networks expanding most quickly to serve fragmented industrial demand across secondary manufacturing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Sony commercialized the first lithium-ion cell in 1991, establishing East Asia's foundational role in laminated battery manufacturing. Production networks now span three continents as electrification mandates reshape regional procurement patterns.
China
CATL and BYD anchor gigafactory corridors in Fujian and Guangdong provinces serving domestic EV OEMs. SAMR's GB 38031 thermal runaway standards exceed UN ECE R100 in test severity, forcing separator material redesigns. The Yangtze River Delta cluster concentrates electrode coating capacity for export-qualified cell production.
South Korea
LG Energy Solution and Samsung SDI supply high-nickel NMC cells to European premium automotive platforms under EU Battery Regulation carbon disclosure requirements. The government mandates 2030 carbon neutrality for public fleet procurement, accelerating pouch-format qualification. Busan-Ulsan industrial zones host polymer film lamination facilities with automotive-grade certification.
Germany
Volkswagen and BMW procurement programs specify EU-compliant recycled content thresholds for cell supply agreements. The KBA enforces UN ECE R100 thermal propagation standards alongside national battery passport traceability rules. North Rhine-Westphalia's Dortmund corridor hosts pilot dry-electrode coating lines for next-generation anode production.
United States
IRA domestic content bonuses drive LFP cell assembly investments in Texas ERCOT and California CAISO grid storage markets. The EPA hazardous material transport rules govern electrolyte formulation shipping to formation facilities. Michigan and Ohio industrial zones attract Korean and Japanese cell producers seeking tariff-advantaged supply positions.
Japan
Panasonic Energy sustains cylindrical cell scale advantages for North American EV OEM supply agreements. METI funding programs target solid-state interface engineering for silicon-anode laminated architectures. Kansai region Osaka-based suppliers control 70%+ of qualified aluminum-laminated polymer film production for automotive applications.
Laminated Lithium Ion Secondary Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the laminated cell value chain, creating a tiered structure where integrated material processors hold cost advantages over pack-assemblers. Three archetypes dominate: cathode-active-material integrated cell producers, pure-play lamination specialists, and automotive-captive battery divisions. Capacity expansion and strategic partnerships constitute the primary competitive vectors as qualification timelines compress.
Among East Asian integrated producers, LG Energy Solution Ltd., Samsung SDI Co., Ltd., and Panasonic Energy Co., Ltd. occupy positions exemplifying scale-driven, chemistry-specialized, and format-dominant archetypes respectively. These entities anchor regional compliance capabilities against tightening carbon footprint disclosure mandates.
| Leading Market Players |
|---|
| LG Energy Solution Ltd. |
| Panasonic Energy Co., Ltd. |
| Samsung SDI Co., Ltd. |
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Limited |
| SK On Co., Ltd. |
| Hitachi Energy Ltd. |
| A123 Systems LLC |
| Envision AESC Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between automotive-qualified and industrial-grade laminated cells splits pricing power along certification lines, with UN ECE R100 and GB 38031 compliance commanding substantial premiums while commodity pouch formats face relentless cost compression from Chinese electrode coating scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs laminated cell procurement, with automotive OEM qualification status and IRA domestic content bonus eligibility serving as the primary price differentiation drivers. Cost compression in standard-tier NMC formulations is intensifying because Indonesian nickel processing expansion has not eliminated Class 1 battery-grade supply tightness. Fleet operators and utility developers demonstrate the least price sensitivity due to total cost of ownership modeling dominance, while consumer electronics replacement channels exhibit acute sensitivity to per-kWh differentials.
Supply Chain Analysis
Automotive-grade aluminum-laminated film qualification gates concentrate supply leverage among Japanese and South Korean polymer suppliers controlling qualified automotive-grade production. Cell manufacturing draws from high-purity nickel sulfate, lithium carbonate, and polypropylene separator inputs sourced through long-term offtake structures. Single-source vulnerability in qualified film supply creates structural risk for European and North American cell plants seeking to diversify beyond East Asian sources. Distribution runs through direct manufacturer relationships for high-volume automotive and grid storage procurement, with regional distributors serving fragmented industrial aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated lithium ion secondary battery market functions as a regulatory compounder where EU Battery Regulation recycled content mandates and carbon footprint disclosure requirements create structural demand for certified cell producers with closed-loop supply partnerships.
For Market Incumbents: To counter electrolyte formulation chemist scarcity concentrating specialized knowledge in incumbent research institutions, LG Energy Solution and Samsung SDI should deepen backward integration into high-voltage additive package production while expanding European plant networks to anchor regional compliance capabilities against tightening carbon border adjustment mechanisms. For New Entrants and Emerging Players: Launch via second-life battery aggregation platforms targeting utility-scale storage developers in Texas ERCOT and California CAISO markets, where data-driven residual value models for degraded EV packs remain underdeveloped and marine electrification for short-haul ferries offers specialized qualification pathways with lower incumbent saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier material processors lack supplier data infrastructure for Scope 3 emissions disclosure under EU CBAM and proposed SEC climate rules. Long-term viability favors acquiring electrode coating specialists with dry-coating process capabilities, with silicon-anode laminated cell architecture qualification timelines serving as the critical inflection signal for technology differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Scale-Up | BMW and Tesla pilot qualifications validate manufacturing energy consumption reduction for next-generation anode production. |
| European Gigafactory Footprint Expansion | LG Energy Solution leverages regional plant networks to anchor EU Battery Regulation compliance capabilities. |
| Closed-Loop Recycling Partnership | Recycled lithium, cobalt, and nickel sourcing secures guaranteed offtake under mandated phase-in thresholds. |
| Silicon-Anode Architecture Development | Panasonic Energy's METI-funded solid-state interface engineering targets premium passenger EV platform qualification. |
| Marine Certification Pathway Investment | Norwegian and Danish maritime regulator approvals open coastal vessel route procurement under IMO-adjacent safety frameworks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturer procurement directors, automotive OEM platform engineers, utility storage developers, and polymer film lamination specialists with secondary validation against UN ECE R100 filings, SAMR GB standard submissions, EPA hazardous material transport records, and IEA battery supply chain databases. Bottom-up cell production capacity modeling and top-down electric vehicle fleet electrification mandates were triangulated to establish demand baselines.
Segment-weighting approaches distributed volume and value across format type, cathode chemistry, end-use application, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from installed capacity buildout trajectories and chemistry-specific cost curve projections, with silicon-anode adoption curves and LFP cycle-life economics serving as key technology inflection inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum-laminated film supply disruption or Indonesian nickel processing regulatory restriction scenarios. Deviation in EU Battery Regulation enforcement timelines or IRA domestic content bonus qualification criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market