
 Lithium-Air Battery Market | 2026-2036
Lithium-Air Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Air Battery Market Intelligence
Solid-state electrolyte architectures are rebalancing cost-performance tradeoffs for lithium-air systems by reducing dendrite formation risks and extending cycle stability. Toyota Motor Corporation leverages its polymer electrolyte research to anchor Japan's national battery roadmap. LG Energy Solution competes through liquid-electrolyte pilot lines optimized for manufacturing scale. Sion Power specializes in protected lithium anode designs that extend operational life in aerospace configurations.
A lithium-air battery electrochemically reduces oxygen at a porous cathode using metallic lithium at the anode, achieving theoretical energy densities exceeding 3,500 Wh/kg through a non-aqueous or solid electrolyte matrix. The technology targets applications where mass-specific energy dominates total cost of ownership, particularly long-range electric aviation and grid-scale seasonal storage. Secondary battery configurations currently lead product type development due to rechargeability requirements from automotive OEMs, while solid-state technology commands the deepest R&D investment pools as manufacturers seek to eliminate volatile organic electrolytes. Aerospace applications represent the fastest-growing segment as Boeing and regional aviation consortia specify weight targets that only lithium-air architectures can satisfy.
The US Department of Energy's Vehicle Technologies Office shapes domestic R&D priorities through funding thresholds tied to specific energy and cycle life benchmarks. Japan's METI coordinates national consortium standards that align Toyota, Panasonic, and university laboratories under common testing protocols. The EU Battery Regulation and emerging CSRD disclosure requirements are forcing automotive OEMs to document full lifecycle carbon intensity, which advantages lithium-air systems if cathode oxygen sourcing eliminates mined active material dependencies. Stakeholders must monitor which electrolyte platform achieves validated cycle counts above 500 without capacity fade, as this threshold determines automotive qualification timelines and manufacturing investment commitments.
Market Dynamics
Solid-state electrolyte architectures are compressing the timeline for lithium-air commercialization by resolving dendrite-induced short-circuit failures that plagued earlier liquid-electrolyte prototypes. This single technical breakthrough is reordering R&D investment priorities across automotive OEMs and national battery programs.
Growth Catalysts
- EU Battery Regulation lifecycle mandates:Full carbon intensity disclosure requirements advantage lithium-air cathodes that eliminate mined active material dependencies, accelerating OEM qualification programs.
- Long-range electric aviation weight targets:Boeing and regional aviation consortia specify mass-specific energy thresholds that only lithium-air architectures can satisfy, pulling forward demand signals.
- Japan METI national consortium coordination:Aligned testing protocols across Toyota, Panasonic, and university laboratories reduce redundant R&D expenditure and standardize performance benchmarks.
Market Restraints
- Cycle stability ceiling:Current solid-state configurations struggle to exceed 200 validated cycles without capacity fade, blocking automotive qualification timelines.
- Lithium metal supply concentration:Spodumene refining capacity clusters in Western Australia and Chilean brine operations, exposing cell manufacturers to concentrate price volatility.
- Ambient air contamination sensitivity:Moisture and carbon dioxide ingress degrade cathode performance, requiring hermetic sealing systems that add mass and cost.
Strategic Opportunities
- German automotive OEM captive programs:BMW and Volkswagen have established dedicated lithium-air research centers in Munich and Wolfsburg with direct cell maker partnerships.
- Grid-scale seasonal storage arbitrage:Week-long discharge duration requirements favor lithium-air energy density over lithium-ion capital cost economics.
- Solid-liquid hybrid electrolyte convergence:Composite architectures combining ceramic mechanical stability with polymer interfacial conductivity are opening intermediate commercialization pathways.
Industry Challenges
- Electrochemist talent scarcity:The specialized skill set spanning solid-state ionics and gas diffusion electrode design concentrates in national laboratories and select university programs.
- Dry room capex intensity:Lithium metal handling requires sub-1% relative humidity manufacturing environments, multiplying facility construction costs versus lithium-ion.
- UN 38.3 transportation certification timelines:Novel cell chemistries face extended safety testing protocols that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Air Battery Market |
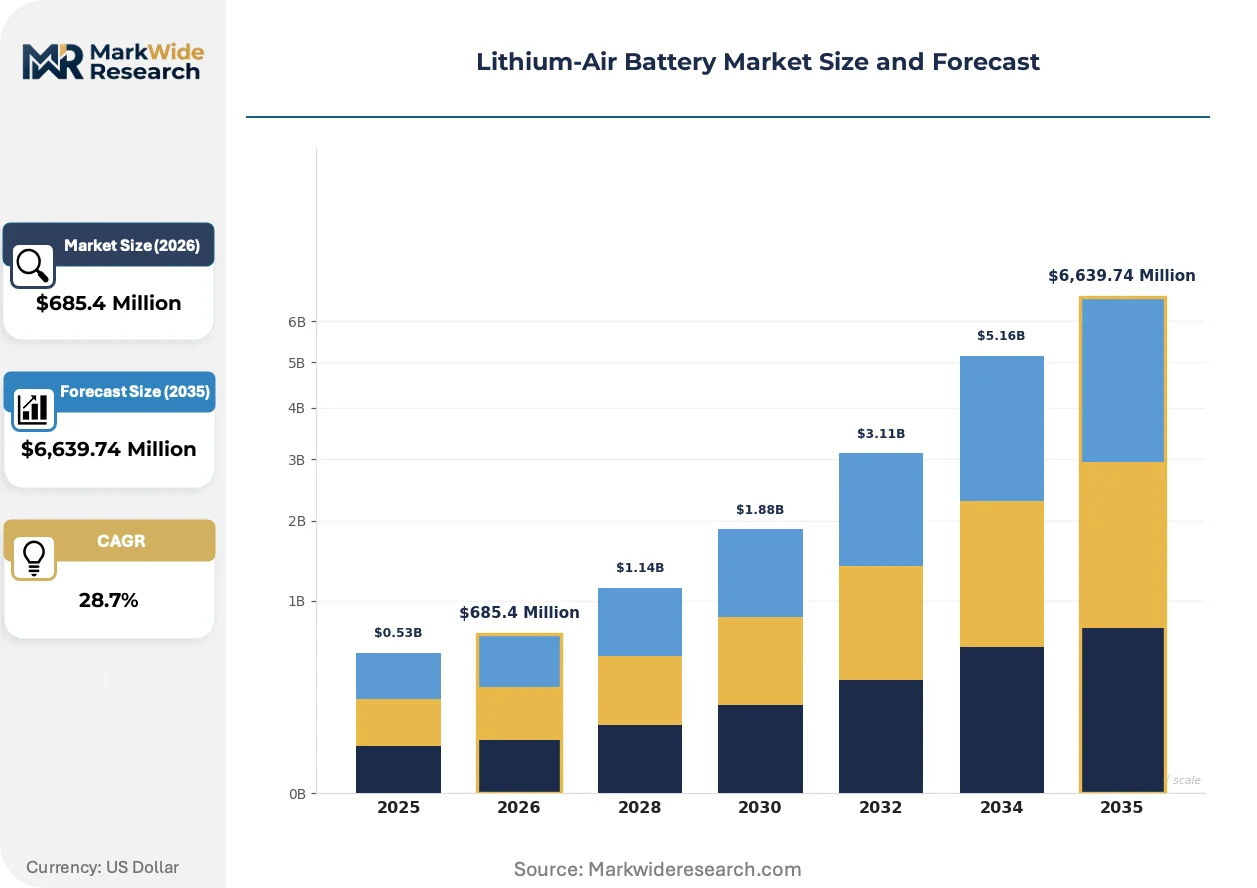
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $6,639.74 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Battery, Secondary Battery, Hybrid Battery, Fuel Cell Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Aerospace Technology: Solid-State, Liquid-Electrolyte, Membrane Technology, Nanotechnology End User: Manufacturers, Research Institutions, Automotive OEMs, Utilities |
| Companies Covered | Toyota Motor Corporation, Tesla, Inc., Boeing, IBM Corporation, LG Energy Solution, Sion Power, Mullen Technologies, Inc., Poly Plus Battery Company, Amprius Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Air Battery Market Strategic Shifts & Innovations
Electrolyte platform selection is emerging as the decisive technical fork that will determine which manufacturing consortia capture first-mover advantage in lithium-air commercialization. Three parallel developments are compressing the path to scaled production.
Solid-state ceramic-polymer composite electrolytes are modularizing cell architecture by enabling bipolar stacking configurations that eliminate current collector mass. Electric aviation developers at Boeing and regional jet consortia are piloting these designs for 2028 service entry targets. The structural consequence is a halving of pack-level gravimetric energy density penalties versus cylindrical liquid-electrolyte formats.
Japan's METI has embedded lithium-air cycle life benchmarks within its national battery roadmap funding gates, forcing Toyota and Panasonic to coordinate validation protocols. This industrial consequence is compressing redundant testing across competing research teams. Automotive applications face the steepest compliance thresholds, with 500-cycle retention requirements now mandatory for production qualification.
Buyer concentration among aerospace OEMs is consolidating procurement leverage toward dedicated long-term supply agreements rather than spot market purchasing. Tier-one cell manufacturers are responding by establishing captive pilot lines with exclusive offtake terms. Germany and South Korea display the most pronounced contract structuring, with direct equity participation from airframers becoming standard.
Lithium-Air Battery Market Segmentation
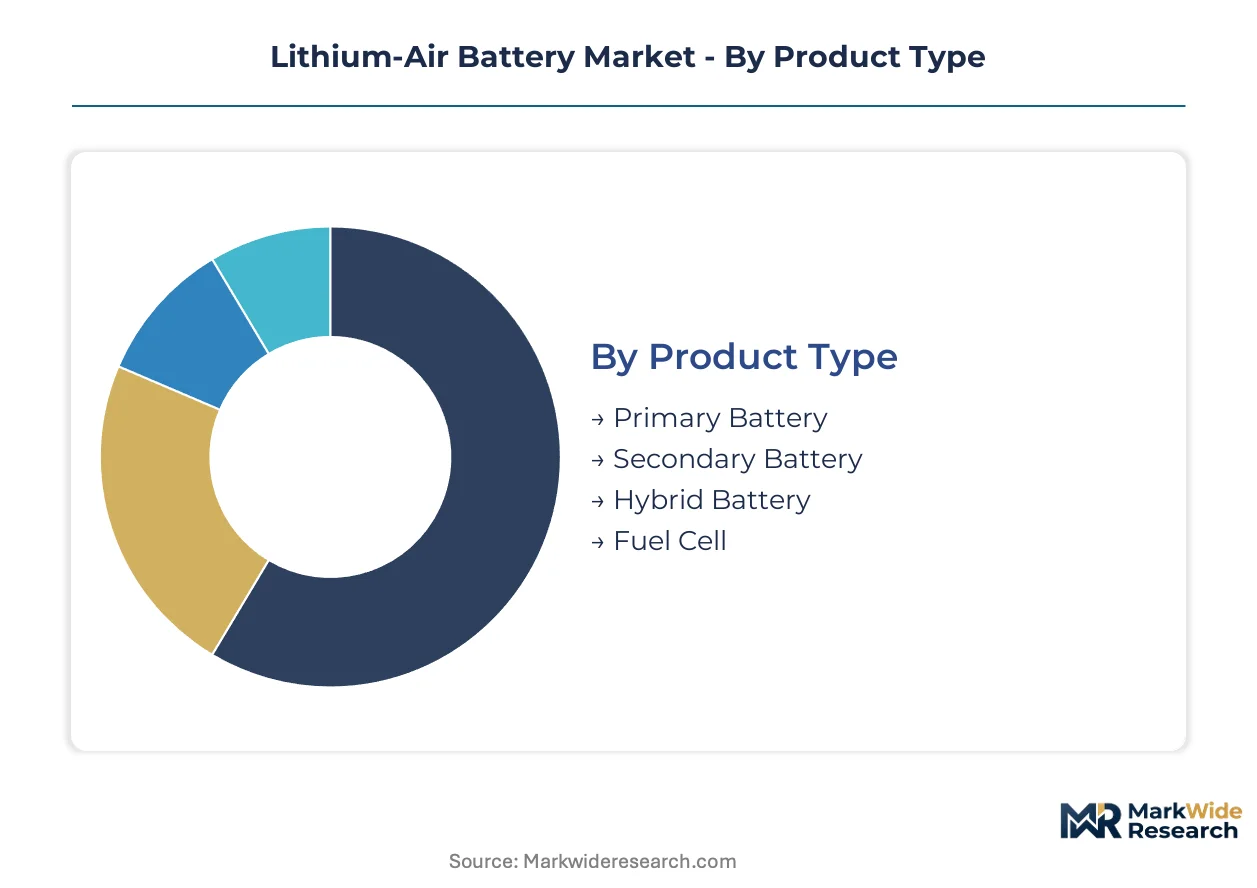
Electrolyte architecture and rechargeability specifications determine where lithium-air systems achieve technical validation versus commercial traction. Product configurations segment sharply between single-use aerospace deployments and automotive-qualified secondary formats demanding cycle stability above 200 validated cycles.
Product Type:
Rechargeability specifications anchor the technology-readiness divide across lithium-air product architectures.
- Secondary Battery:Reversible electrochemical cycling enables automotive qualification programs at Toyota and Panasonic. Japan METI funding gates mandate 500-cycle retention benchmarks for production readiness, concentrating R&D investment in solid-state electrolyte configurations that suppress dendrite formation.
- Primary Battery:Single-discharge architectures eliminate rechargeability complexity, achieving higher energy density through simplified cathode designs. Boeing specifications for long-range electric aviation favor these systems where total cycle count requirements remain minimal.
- Hybrid Battery:Dual-mode configurations combine primary discharge with limited rechargeability for grid-scale seasonal storage applications.
- Fuel Cell:Continuous oxygen feed architectures bypass cathode capacity limitations for stationary power generation.
Mature deployment sits with Primary Battery formats in aerospace testing programs. Newer deployment is concentrated in Secondary Battery configurations as automotive OEMs push cycle stability thresholds.
Application:
Mass-specific energy requirements versus capital cost sensitivity determine application-tier adoption sequencing.
- Aerospace:Regional aviation consortia specify gravimetric energy density thresholds exceeding 1,000 Wh/kg that only lithium-air architectures satisfy. Boeing pilot programs target service entry with solid-state bipolar stacking configurations that halve pack-level mass penalties.
- Electric Vehicles:BMW and Volkswagen captive research centers in Munich and Wolfsburg coordinate direct cell maker partnerships. EU Battery Regulation lifecycle disclosure mandates advantage lithium-air cathodes that eliminate mined active material dependencies.
- Energy Storage Systems:Week-long discharge duration requirements favor energy density economics over lithium-ion capital costs for grid arbitrage.
- Consumer Electronics:Form factor constraints and cost floors limit near-term feasibility for portable device integration.
Volume concentration remains with Electric Vehicles given automotive OEM R&D scale. Steepest expansion trajectory belongs to Aerospace as weight targets harden for electric aviation certification.
Technology:
Electrolyte platform selection functions as the decisive technical fork determining manufacturing consortium first-mover advantage.
- Solid-State:Ceramic-polymer composite architectures enable bipolar stacking that eliminates current collector mass. Toyota leverages polymer electrolyte research to anchor Japan's national battery roadmap.
- Liquid-Electrolyte:LG Energy Solution competes through pilot lines optimized for manufacturing scale, though dendrite-induced short-circuit failures constrain automotive qualification.
- Membrane Technology:Gas diffusion electrode designs from Sion Power extend operational life in protected lithium anode configurations.
- Nanotechnology:Cathode surface engineering reduces moisture sensitivity for ambient air operation without hermetic sealing mass penalties.
Production qualification investment clusters around Solid-State platforms. Liquid-Electrolyte retains scale advantage for intermediate commercialization pathways.
End User:
Procurement authority and technical validation capacity segment end-user influence over development roadmaps.
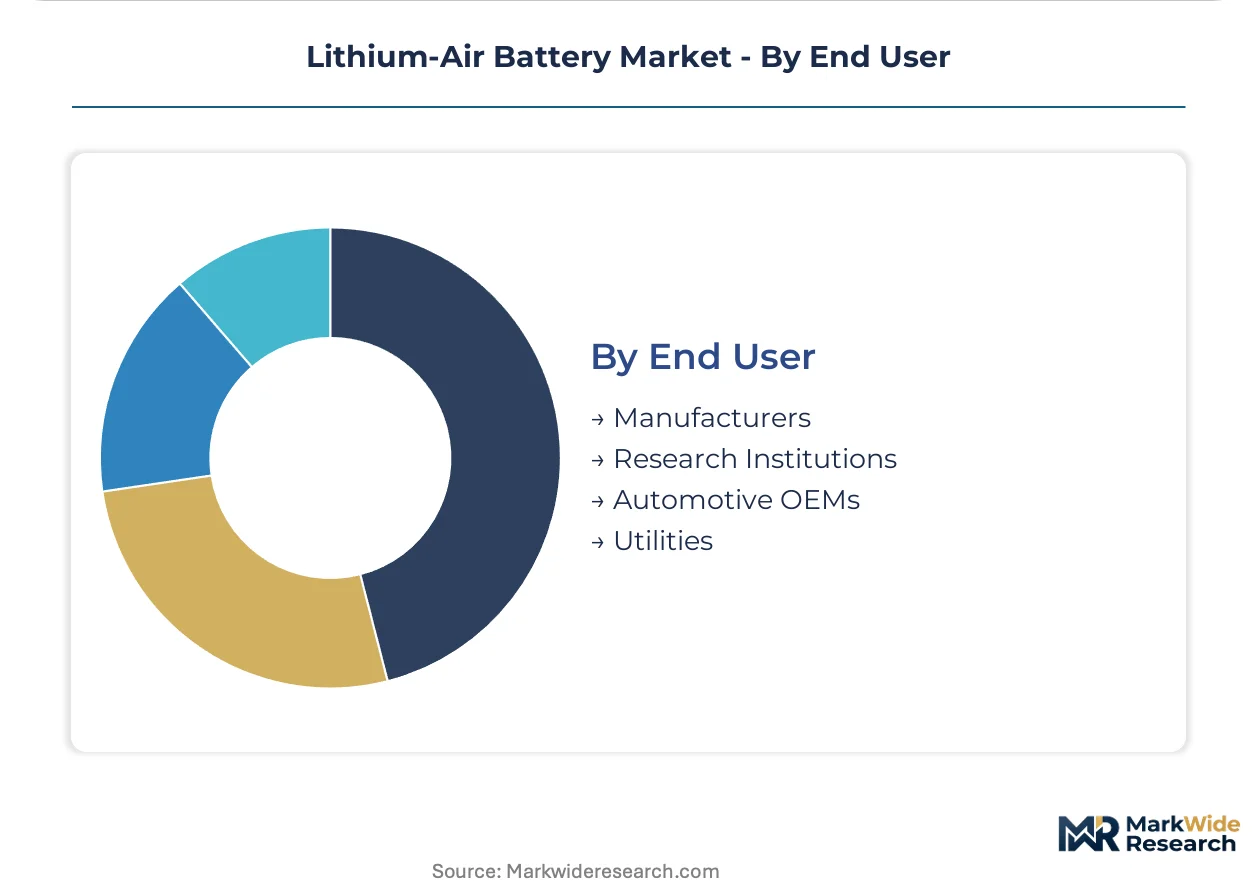
- Automotive OEMs:BMW, Volkswagen, and Toyota direct captive research funding with exclusive offtake terms. Germany and South Korea display pronounced contract structuring with direct equity participation from airframers.
- Research Institutions:University laboratories coordinate under Japan METI testing protocols that compress redundant validation expenditure.
- Utilities:Grid-scale seasonal storage procurement favors week-long discharge economics over lithium-ion capital costs.
- Manufacturers:Tier-one cell makers establish pilot lines with aerospace OEM dedicated supply agreements rather than spot market exposure.
Technical specification authority concentrates with Automotive OEMs. Newer deployment is concentrated in Research Institutions as national consortium coordination standardizes performance benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan, South Korea, and Germany concentrate lithium-air battery development through coordinated automotive OEM and national research institute programs. Each geography anchors distinct electrolyte innovation pathways that determine qualification timelines.
Japan
Toyota Motor Corporation and Panasonic anchor domestic demand through METI-coordinated consortium standards. The Ministry of Economy, Trade and Industry mandates 500-cycle retention benchmarks for production qualification funding. Tokyo-Osaka industrial corridors host university laboratories aligned under common testing protocols that compress redundant validation expenditure.
South Korea
LG Energy Solution drives liquid-electrolyte pilot line scale-up for manufacturing feasibility assessment. The national battery roadmap prioritizes solid-state transition timelines through direct government-industry coordination. Seoul-Daejeon research clusters concentrate electrochemist talent pools for gas diffusion electrode design.
Germany
BMW and Volkswagen captive research centers in Munich and Wolfsburg direct cell maker partnerships with exclusive offtake terms. EU Battery Regulation lifecycle disclosure mandates advantage cathode designs eliminating mined active material dependencies. Bavaria's automotive supplier ecosystem integrates with federal research funding for bipolar stacking configurations.
United States
Boeing specifications pull demand for long-range electric aviation weight targets exceeding 1,000 Wh/kg. The Department of Energy's Vehicle Technologies Office shapes R&D priorities through funding thresholds tied to energy and cycle life benchmarks. Pacific Northwest national laboratories concentrate solid-state ionics expertise for ceramic-polymer composite development.
China
Domestic OEMs monitor solid-state breakthroughs for potential technology licensing rather than indigenous development. MIIT battery industry planning documents reference lithium-air as long-term roadmap positioning without near-term production targets. Yangtze River Delta materials suppliers evaluate lithium metal anode handling infrastructure for future qualification.
Lithium-Air Battery Market Key Industry Players
Strategic partnerships dominate the current landscape as automotive OEMs and aerospace developers secure exclusive technology access through direct research funding and offtake agreements. The vendor base structures across three tiers: diversified conglomerates with captive battery divisions, pure-play electrochemistry specialists, and aerospace-integrated system developers. Two strategic archetypes define positioning: electrolyte platform owners controlling core intellectual property, and application-specific integrators translating cell performance into airframe or vehicle qualification. Competitive moves concentrate on M&A for solid-state talent acquisition and capacity expansion for pilot line validation.
Within the diversified conglomerate tier, Toyota Motor Corporation and LG Energy Solution occupy positions reflecting distinct electrolyte platform bets—polymer solid-state versus liquid-electrolyte scale manufacturing. Sion Power exemplifies the specialist archetype as a protected lithium anode design house serving aerospace qualification programs.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Tesla, Inc. |
| Boeing |
| IBM Corporation |
| LG Energy Solution |
| Sion Power |
| Mullen Technologies, Inc. |
| Poly Plus Battery Company |
| Amprius Technologies |
| Others |
Cost & Logistics Intelligence
Captive lithium metal refining by Australian spodumene processors and Chilean brine operators anchors both supply security and pricing power for cell manufacturers. This upstream control concentrates cost leverage among electrolyte platform owners while exposing downstream integrators to concentrate price volatility.
Pricing Analysis
Volume concentration in automotive OEM qualification programs splits margin capture between premium-tier solid-state configurations and economy-tier liquid-electrolyte pilots. Price differentiation hinges on cycle life certification thresholds and hermetic sealing system complexity. Cost compression in liquid-electrolyte manufacturing is intensifying because dendrite failure rates block automotive qualification premiums. Aerospace developers display the least price sensitivity due to mass-specific energy requirements that override capital cost economics.
Supply Chain Analysis
Single-source vulnerability sits with Western Australian spodumene concentrate and Chilean Atacama brine operations that feed lithium metal anode production. Ceramic-polymer composite electrolytes draw from Japanese specialty chemical suppliers and German precision ceramics manufacturers. Commodity price volatility in lithium carbonate feedstocks threatens cell cost predictability. Distribution runs through captive pilot line partnerships with exclusive offtake terms rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry room manufacturing capacity represents the binding constraint propping pricing premiums for qualified cell supply. Sub-1% relative humidity infrastructure scarcity limits production scale-up regardless of cathode design maturity.
For Market Incumbents: Acquire solid-state electrochemist talent pools concentrated in national laboratories and select university programs. Backward integration into lithium metal anode handling infrastructure defends against spodumene concentrate price volatility. METI-coordinated validation protocols in Japan compress redundant R&D expenditure, threatening first-mover advantage for non-aligned consortia. For New Entrants and Emerging Players: The premium-to-economy price-point gap between aerospace primary battery specifications and automotive secondary qualification requirements opens white-space targeting. Grid-scale seasonal storage applications present the most penetrable segment due to week-long discharge duration requirements that favor energy density economics. Direct equity participation structures from German automotive OEMs offer a proven go-to-market angle for pilot line validation. For Investors and Strategic Acquirers: Exit pathways concentrate in electrolyte platform licensing to diversified conglomerates with captive battery divisions. Long-term viability rests on validated cycle counts exceeding 500 without capacity fade as the threshold for automotive production qualification. Monitor which manufacturing consortium achieves UN 38.3 transportation certification first as the inflection indicator for manufacturing investment commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Platform Licensing | Toyota's polymer solid-state IP anchors Japan's national battery roadmap funding gates. |
| Captive Pilot Line Partnership | BMW and Volkswagen direct cell maker relationships in Munich and Wolfsburg secure exclusive offtake. |
| Backward Integration into Lithium Refining | Western Australian spodumene concentrate exposure threatens margin stability for non-integrated manufacturers. |
| Long-term Supply Agreement Structuring | Boeing specifications for electric aviation consolidate procurement leverage toward dedicated contracts. |
| Cycle Life Certification Investment | METI-mandated 500-cycle retention benchmarks determine automotive qualification timelines and funding access. |
Research Approach
Independent corroboration across cell engineering directors, automotive platform procurement leads, and aerospace power systems engineers underwrites the qualitative findings. Primary interviews with solid-state ionics researchers, gas diffusion electrode specialists, and dry room facility operators combined with secondary validation from METI roadmap documents, EU Battery Regulation disclosure filings, and DOE Vehicle Technologies Office funding announcements. Bottom-up cell cost modeling and top-down automotive OEM R&D expenditure tracking triangulate market sizing.
Rate-of-change decomposition across the analysis window separates electrolyte platform transition effects from application-tier adoption sequencing. Segmentation dimensions modeled include rechargeability specification, electrolyte architecture, end-use application, and regional production cluster alignment. CAGRs were derived from validated cycle count progression curves and automotive qualification timeline compression. Forecast inputs incorporate lithium metal supply concentration risk and solid-state ceramic-polymer composite manufacturing yield trajectories.
Underlying measurement precision varies by segment; aerospace primary battery deployment carries tighter precision than automotive secondary qualification timelines. Forecasts reflect assumptions regarding dendrite suppression breakthroughs and hermetic sealing system mass reduction. Specific risk factors that could revise projections include lithium carbonate feedstock price spikes, UN 38.3 certification delays, and ambient air contamination sensitivity mitigation failures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Battery Wet Separator Market