
 France SLI Battery Market | 2026-2036
France SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
France SLI Battery Market Insights
Aftermarket demand from France's aging passenger vehicle fleet is hardening as the primary volume driver for SLI battery replacements. Clarios leverages its extensive distribution network across French automotive service channels to sustain dominant aftermarket coverage. Varta AG differentiates through specialized AGM products targeting premium European marques with start-stop systems. Exide Technologies competes on manufacturing scale, operating production facilities that supply both OEM and independent repair segments across France.
France SLI Battery refers to starting, lighting, and ignition batteries engineered for internal combustion engine vehicles, typically constructed with lead-acid chemistry featuring six cells at 2.1 volts each to deliver 12.8 volts nominal output, designed to provide high cold-cranking amperage for engine starts while supporting electrical accessory loads. Flooded lead-acid technology anchors the installed base due to its cost position and established recycling infrastructure, though AGM segments are capturing margin pools as start-stop penetration deepens. Enhanced Flooded Battery technology occupies a transitional position, offering improved cycle durability for entry-level start-stop vehicles without full AGM cost premiums.
France's national environmental regulator enforces extended producer responsibility frameworks that mandate battery collection and recycling rates, while EU REACH and RoHS directives restrict hazardous substance thresholds in manufacturing processes. ANSM and CNIL oversight extends to workplace safety and data traceability in supply chain compliance systems. Stakeholders must monitor how forthcoming EU Battery Regulation carbon footprint declarations reshape material sourcing decisions and supplier qualification criteria across French distribution networks.
Market Dynamics
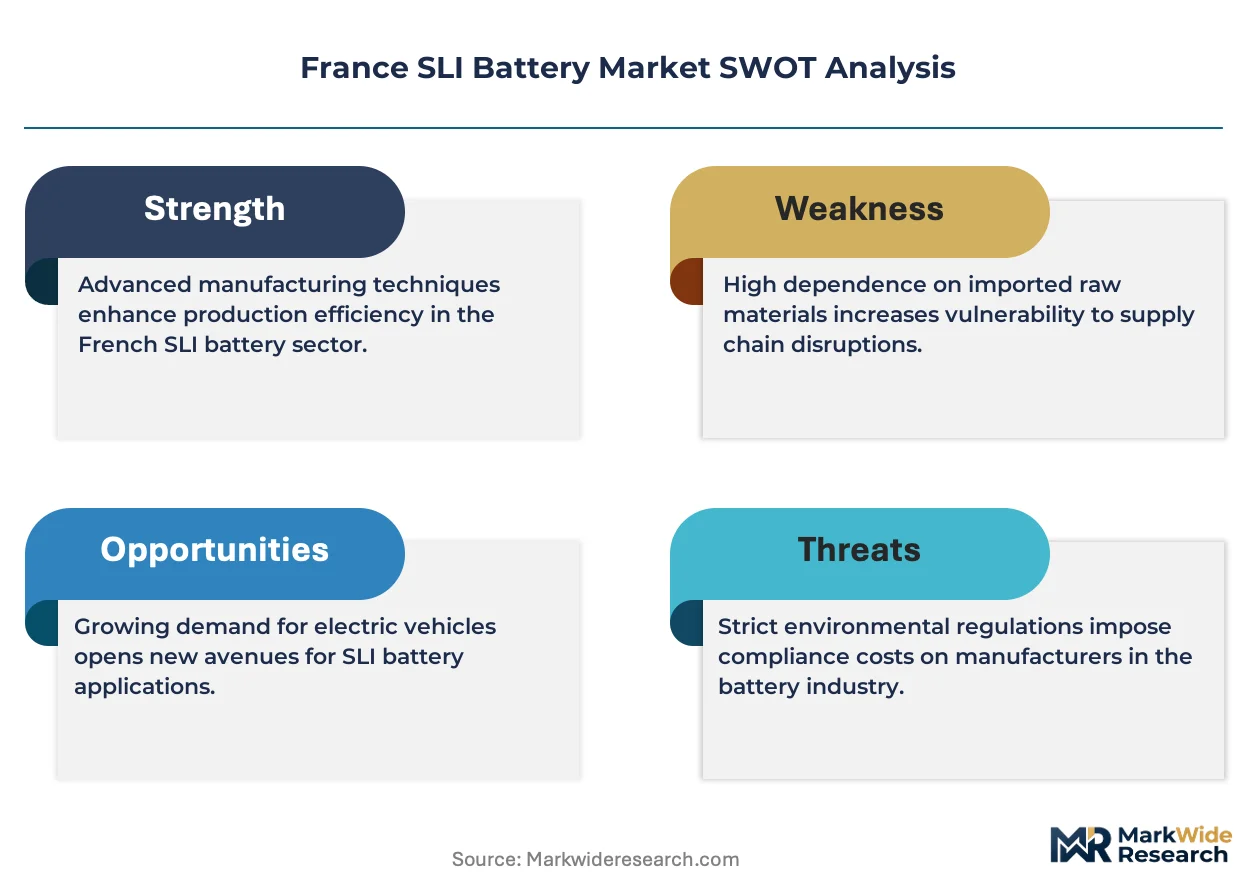
The France SLI Battery Market is being fundamentally restructured by the EU Green Deal's battery sustainability mandates, which are forcing producers to decarbonize manufacturing processes and establish closed-loop recycling systems while maintaining cost competitiveness against Asian imports.
Growth Catalysts
- EU Battery Regulation carbon footprint declarations:Mandates for lifecycle emissions transparency are accelerating investment in low-carbon lead-acid production methods across French manufacturing facilities.
- Île-de-France fleet electrification lag:Commercial vehicle operators in the Paris region continue replacing SLI batteries in aging diesel fleets, sustaining aftermarket volume despite EV transition pressures.
- AGM chemistry:Start-stop system penetration in premium European marques is driving upgrade cycles from flooded lead-acid to absorbed glass mat technology.
Market Restraints
- Lead price volatility:Raw material cost swings in global lead markets compress margin predictability for French battery assemblers dependent on imported primary metal.
- Asian manufacturing concentration:Supply risk concentrates in Chinese and South Korean production hubs, exposing French distributors to geopolitical friction and shipping cost spikes.
- Lithium-ion substitution:Declining costs for lithium iron phosphate chemistry threaten SLI applications in light commercial vehicles with auxiliary power demands.
Strategic Opportunities
- Occitania aftermarket penetration:Rural vehicle aging in southern France regions remains underserved by premium AGM distribution networks.
- EU REACH compliance services:Hazardous substance documentation mandates create advisory revenue streams for testing laboratories supporting French importers.
- Digital fleet management integration:Telematics-enabled battery monitoring is expanding into logistics operator procurement specifications.
Industry Challenges
- Lead-acid technician training gaps:Declining vocational enrollment in battery maintenance skills complicates service network expansion.
- Extended producer responsibility compliance costs:ANSM collection rate enforcement requires capital deployment into reverse logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France SLI Battery Market |
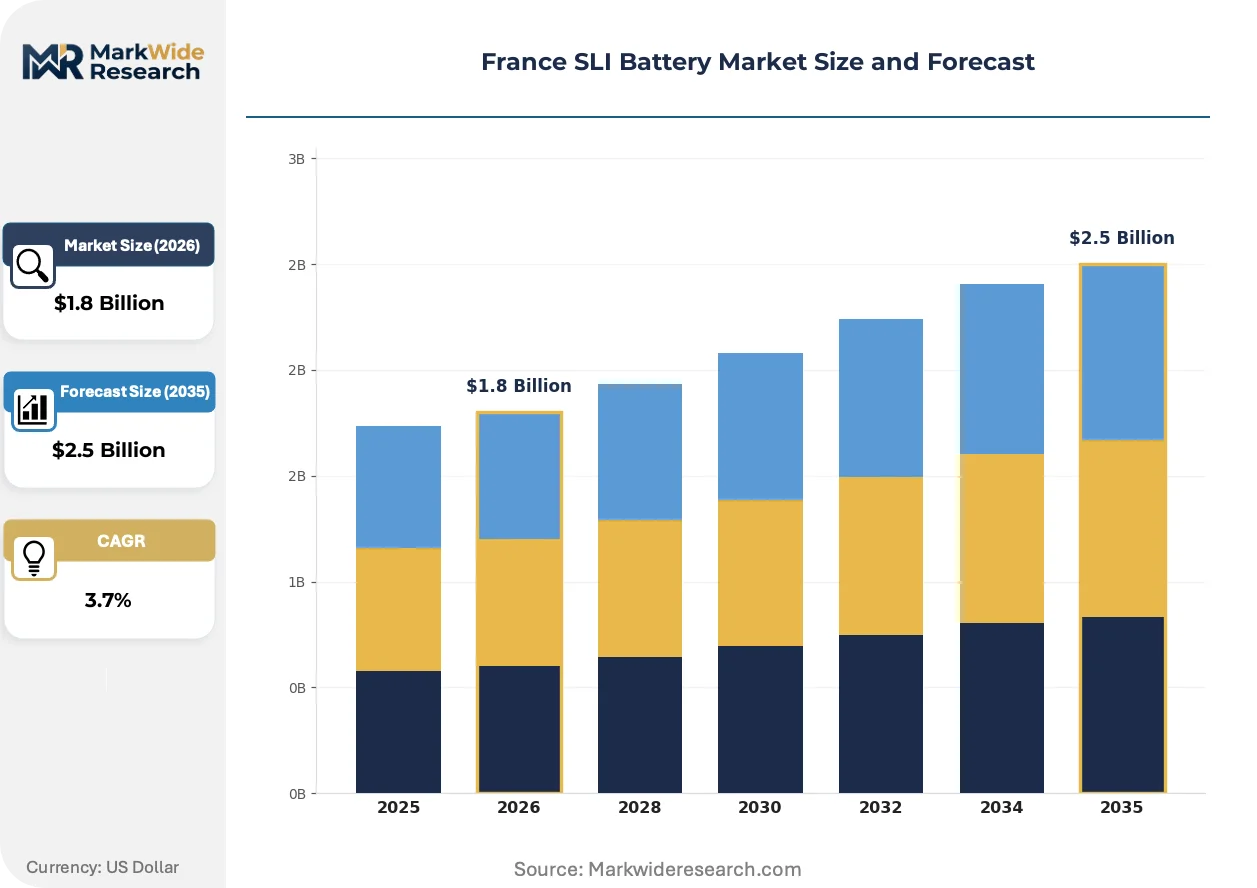
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Absorbent Glass Mat, Gel, Flooded End User: OEMs, Aftermarket Providers, Automotive Manufacturers, Heavy Machinery Capacity: 40 Ah, 60 Ah, 75 Ah, 100 Ah Technology: Start-Stop, Conventional, Enhanced Flooded Battery, Lithium |
| Companies Covered | GS Yuasa International Ltd, Exide Technologies, Johnson Controls International PLC, EnerSys, Varta AG, FIAMM Energy Technology, Clarios, SAFT Groupe SA, HBL Power Systems Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France SLI Battery Market Trends and Innovations
Active transformation in the France SLI Battery Market centers on chemistry evolution, regulatory compliance automation, and procurement model restructuring. These forces are compressing traditional product lifecycles while opening new service revenue streams.
Absorbed glass mat technology is expanding into entry-level passenger segments previously served by flooded lead-acid designs. Mid-market fleet operators in Lyon and Marseille are adopting AGM for improved cycle durability in urban stop-start driving conditions. This chemistry migration is compressing price premiums and forcing flooded battery producers to defend position through enhanced cycle life claims.
EU Green Deal battery sustainability mandates are requiring French distributors to implement blockchain-traceable material sourcing documentation. Manufacturing facilities must now verify recycled lead content percentages and carbon intensity per kilowatt-hour. Independent repair networks are responding by consolidating procurement through certified suppliers with pre-validated compliance packages.
Aftermarket buyers are consolidating purchasing through integrated service platforms rather than fragmented wholesale channels. Multi-brand automotive service chains in the Île-de-France region are negotiating direct supply agreements with battery manufacturers, bypassing traditional distributor markups. This channel compression is most visible among Paris-based commercial fleet operators managing mixed-vehicle inventories.
France SLI Battery Market Segmentation
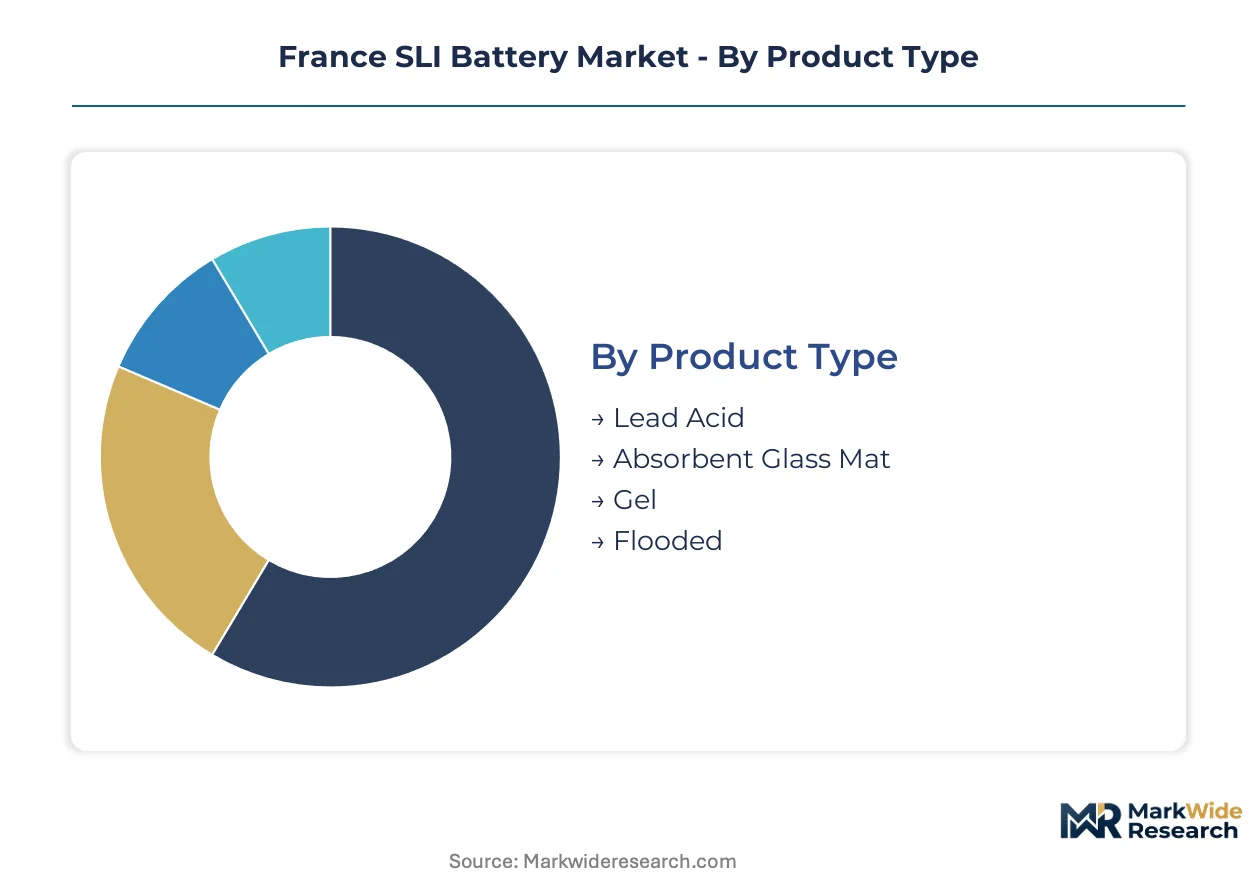
France SLI Battery Market segmentation reveals how chemistry innovation, procurement channel structure, and vehicle electrification timelines are fragmenting demand across distinct technical and commercial axes. Understanding these splits exposes where margin pools are concentrating and which specifications are displacing legacy designs.
Product Type:
Lead-acid chemistry variants dominate procurement specifications, with each construction method carrying distinct cost-performance trade-offs that align to specific vehicle duty cycles and regional fleet operator requirements.
- Lead Acid:Conventional flooded construction with liquid electrolyte remains the volume anchor across French aftermarket channels due to established recycling infrastructure and lowest unit cost. Rural independent repair networks in Occitania and Auvergne-Rhône-Alpes rely on this specification for aging passenger vehicle fleets where replacement frequency justifies minimal upfront investment.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat enables sealed construction with superior vibration resistance and cycle durability for start-stop applications. Île-de-France commercial fleet operators specify AGM for urban delivery vehicles facing frequent engine cycling, driving fastest volume expansion among chemistry variants despite 40-60% price premium over flooded equivalents.
- Gel:Silica-thickened electrolyte formulation delivers deep-cycle resilience for marine and recreational vehicle auxiliary power applications. Niche demand concentrates in Mediterranean coastal regions with significant boating activity.
- Flooded:Traditional vented design with removable caps for electrolyte maintenance occupies economy tier in price-sensitive replacement scenarios. Maintenance requirements limit adoption in sealed-engine-bay modern vehicles.
Lead Acid leads on scale; Absorbent Glass Mat leads on momentum.
End User:
Procurement authority splits between vehicle manufacturers integrating batteries at assembly and post-sale replacement channels, with divergent technical specifications and commercial terms governing each relationship type.
- OEMs:Original equipment manufacturers specify batteries during vehicle assembly, prioritizing warranty alignment and supply security over unit cost minimization. French automotive production facilities in Hauts-de-France and Grand Est regions maintain long-term supply agreements with certified battery assemblers.
- Aftermarket Providers:Independent distributors and service chains manage replacement demand from vehicle owners outside warranty coverage. Consolidation among multi-brand repair networks in Île-de-France is compressing distributor margins while expanding direct manufacturer relationships.
- Automotive Manufacturers:Captive brand service operations specify genuine or approved-equivalent batteries for warranty-compliant replacements. Premium marque dealers in Paris and Lyon metropolitan areas drive AGM upgrade penetration during scheduled maintenance intervals.
- Heavy Machinery:Construction and agricultural equipment operators demand enhanced vibration resistance and extended cycle life for severe-duty applications. Regional equipment dealers in Nouvelle-Aquitaine and Provence-Alpes-Côte d'Azur service farming and vineyard mechanization fleets with specialized specifications.
Aftermarket Providers capture the largest volume flow; Heavy Machinery offers the steepest expansion trajectory as agricultural fleet renewal accelerates.
Capacity:
Ampere-hour ratings segment demand by vehicle electrical load requirements, with engine displacement and accessory content determining minimum specification thresholds across French vehicle parc.
- 40 Ah:Compact passenger vehicles and urban runabouts with minimal electrical accessory loads. Dominates replacement demand for aging small cars in dense metropolitan zones where short-trip driving patterns reduce deep-cycle stress.
- 60 Ah:Mid-size family vehicles and light commercial vans represent the median specification across French replacement demand. Balances cranking performance with reserve capacity for modern infotainment and safety systems.
- 75 Ah:Premium sedans and light SUVs with start-stop systems require enhanced reserve capacity for frequent engine restart cycles. AGM construction typically paired with this rating for thermal management in stop-start traffic conditions.
- 100 Ah:Heavy commercial vehicles, motorhomes, and marine applications with substantial auxiliary electrical demands. Limited volume but highest unit margins due to specialized construction and low manufacturing scale.
60 Ah leads on scale; 75 Ah climbs the fastest as start-stop penetration deepens across French vehicle segments.
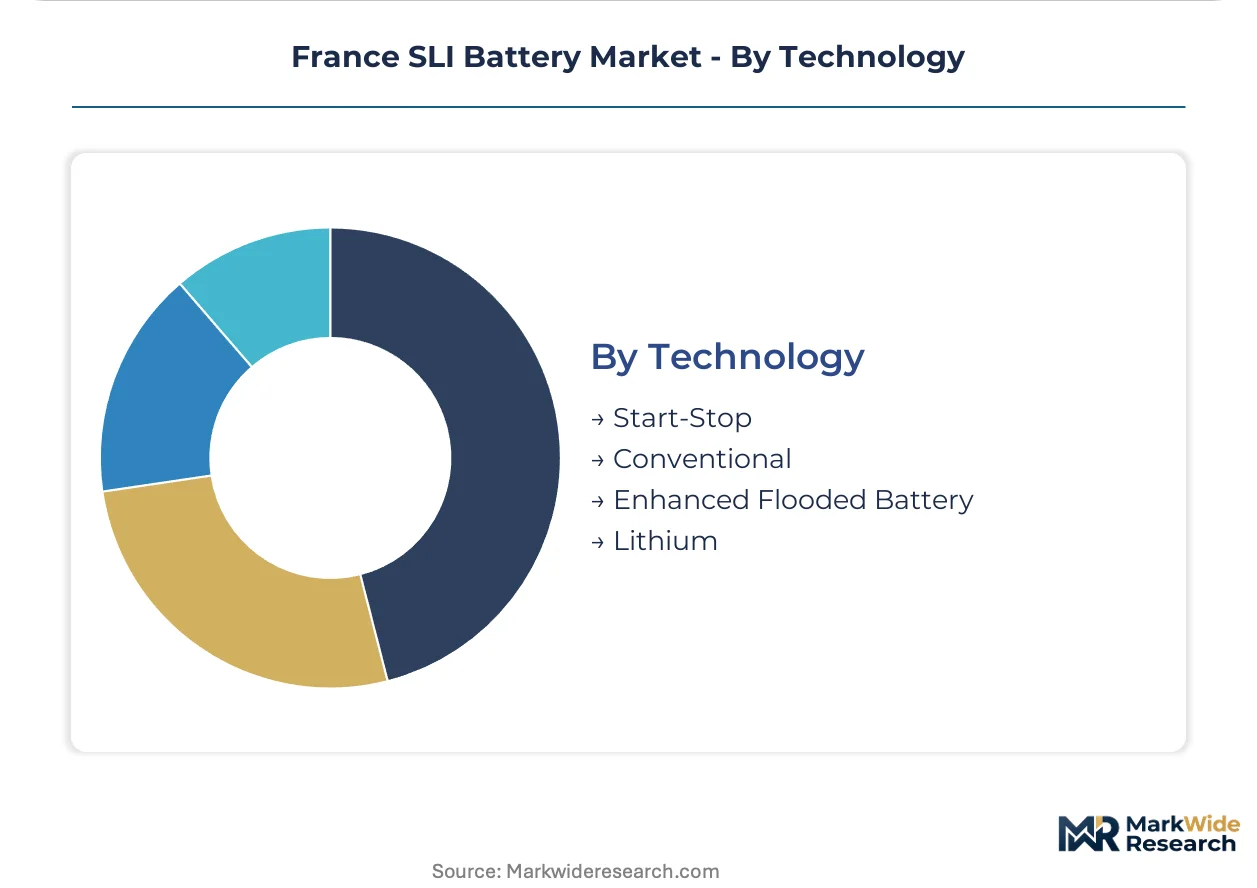
Technology:
System integration requirements segment demand by vehicle electrical architecture complexity, with conventional designs yielding to enhanced specifications supporting fuel efficiency mandates.
- Start-Stop:Integrated systems requiring batteries capable of sustaining 200,000+ engine restart cycles demand AGM or enhanced flooded construction. EU CO2 fleet targets are mandating this technology across new vehicle registrations, expanding replacement demand into secondary ownership cycles.
- Conventional:Basic starting-lighting-ignition function without cycling durability requirements occupies declining share of French replacement demand as vehicle parc ages into start-stop-equipped vintages.
- Enhanced Flooded Battery:Intermediate technology delivering improved cycle life through plate chemistry and separator modifications without full AGM cost. Entry-level start-stop vehicles in B and C segments specify EFB as cost-optimized compliance solution.
- Lithium:Emerging lithium iron phosphate chemistry penetrates auxiliary power applications in light commercial vehicles with significant idle electrical loads. Weight and cycle life advantages offset premium pricing for specific vocational use cases.
Start-Stop leads on scale; Lithium gains share fastest in specialized commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors French SLI battery demand through Paris-based fleet operators and commercial vehicle hubs driving bulk procurement volumes.
Île-de-France
Commercial fleet operators in the Paris metropolitan zone sustain replacement demand for aging diesel vehicle batteries. ANSM enforces extended producer responsibility frameworks mandating collection and recycling rate compliance. Bulk purchasing concentrates among logistics operators managing mixed-vehicle inventories across the capital region.
Auvergne-Rhône-Alpes
Light commercial vehicle density in Lyon and surrounding industrial zones generates steady aftermarket turnover. EU REACH directives restrict hazardous substance thresholds in manufacturing processes. Regional equipment dealers service agricultural mechanization fleets with specialized battery specifications.
Provence-Alpes-Côte d'Azur
Marine and recreational vehicle applications create niche demand for deep-cycle resilient gel battery formulations. The EU Green Deal accelerates shift toward recyclable lead-acid designs across coastal manufacturing facilities. Mediterranean boating activity concentrates procurement in Marseille and Toulon port clusters.
Hauts-de-France
Automotive production facilities maintain long-term supply agreements with certified battery assemblers for OEM integration. CNIL oversight extends to data traceability in supply chain compliance systems. Assembly plants near Lille and Douai anchor volume contracts for warranty-aligned specifications.
Occitanie
Rural vehicle aging in southern France regions sustains flooded lead-acid replacement cycles in price-sensitive segments. Carbon footprint declaration requirements under forthcoming EU Battery Regulation reshape material sourcing decisions. Independent repair networks in Toulouse and Montpellier rely on established recycling infrastructure for cost-positioned procurement.
France SLI Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as established producers retrofit manufacturing lines for low-carbon lead-acid output. The vendor base organizes around three strategic archetypes: integrated multinational assemblers with captive recycling networks, regional specialists serving premium AGM segments, and scale-driven manufacturers competing on unit cost. Geographic expansion into underserved southern regions and portfolio diversification toward enhanced flooded battery technology represent the dominant competitive moves reshaping positioning.
Among Germany-based fabricators, Varta AG exemplifies the premium-tier specialist archetype through its absorbed glass mat product focus. Clarios occupies a position as the integrated multinational anchor leveraging extensive distribution networks across French automotive service channels. Exide Technologies sits within the scale-driven tier, operating production facilities that supply both OEM and independent repair segments.
| Leading Market Players |
|---|
| GS Yuasa International Ltd |
| Exide Technologies |
| Johnson Controls International PLC |
| EnerSys |
| Varta AG |
| FIAMM Energy Technology |
| Clarios |
| SAFT Groupe SA |
| HBL Power Systems Ltd |
| Others |
Pricing and Supply Chain Analysis
Île-de-France commercial fleet operators concentrate procurement authority through direct manufacturer negotiations, compressing traditional distributor markups and forcing three-tier pricing stratification across premium AGM, standard EFB, and economy flooded specifications.
Pricing Analysis
Distributor margin compression in aftermarket channels is accelerating price transparency as multi-brand service chains consolidate purchasing through integrated platforms. Cost differentiation hinges on EU Battery Regulation carbon footprint certification tiers and volume scale commitments from Paris-based logistics operators. Price erosion runs through flooded lead-acid tiers as Asian imports intensify competition. Heavy machinery operators in southern France exhibit lowest price sensitivity due to severe-duty reliability requirements, while rural independent repair networks in Occitania remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Lyon and Marseille anchor hub-and-spoke patterns serving southern France aftermarket networks. Primary lead feedstock draws from Chinese and South Korean smelting operations, with secondary recycled lead sourcing from domestic French collection infrastructure under ANSM extended producer responsibility frameworks. Plastic separator materials and sulfuric acid concentrate supply risk in German and Belgian chemical production clusters. Tariff exposure on imported primary metal creates margin volatility for French assemblers. Distribution runs through certified supplier networks with pre-validated EU REACH compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France SLI Battery Market represents a late-cycle quality story as start-stop system penetration shifts replacement demand toward premium AGM and EFB specifications with superior cycle durability and carbon-certified sourcing.
For Market Incumbents: To counter lithium-ion substitution in light commercial auxiliary power applications, Clarios and Varta AG should deepen backward integration into captive lead recycling networks and expand EFB capacity at existing Hauts-de-France production facilities. Certification investment in EU Battery Regulation carbon footprint declarations will defend margin position against uncertified Asian imports. For New Entrants and Emerging Players: Capture underserved AGM distribution gaps in Occitania's rural aftermarket, where aging vehicle fleets and price-sensitive independent repair networks currently rely on flooded lead-acid replacements. A direct-to-fleet telematics-integrated battery monitoring service offers the most penetrable go-to-market angle for Paris-based commercial operators. For Investors and Strategic Acquirers: Battery recycling specialists with ANSM-licensed collection infrastructure are the most active acquirer in this space, consolidating fragmented reverse logistics capabilities ahead of stricter EU Green Deal mandates. The long-term viability window favors targets with closed-loop lead recovery economics and established OEM qualification status. Watch for lithium iron phosphate cost parity inflection in light commercial auxiliary applications as the critical demand displacement signal.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Network Expansion | ANSM collection rate enforcement requires capital deployment into reverse logistics infrastructure serving Île-de-France fleet operators. |
| EFB Manufacturing Line Retrofit | Entry-level start-stop vehicle penetration in B and C segments demands cost-optimized chemistry between flooded and AGM specifications. |
| Carbon Footprint Certification Investment | EU Battery Regulation mandates lifecycle emissions transparency for supplier qualification across French distribution networks. |
| Direct Fleet Procurement Platform | Telematics-enabled battery monitoring integration meets logistics operator specifications for predictive maintenance contracts. |
| Regional Distribution Center Consolidation | Hub-and-spoke optimization in Lyon and Marseille reduces delivery costs for Occitania and Provence-Alpes-Côte d'Azur aftermarket channels. |
Research Methodology
Multiple input streams — regulatory filings with ANSM and ECHA, French automotive production databases, and customs trade records — were reconciled through primary interviews with aftermarket distributors, OEM procurement teams, and recycling facility operators. Secondary validation drew from EU Battery Regulation implementation guidance, REACH substance restriction updates, and Clarios and Varta AG sustainability disclosures. Bottom-up demand modeling across chemistry variants and capacity tiers was cross-checked against top-down French vehicle parc aging projections.
Historical replacement frequency patterns were cross-referenced against panel input from fleet maintenance directors and independent repair network owners to construct demand elasticity assumptions across the projection horizon. Segmentation dimensions modeled include lead-acid chemistry construction, end-user procurement authority, ampere-hour capacity ratings, and start-stop technology integration. CAGRs were derived from unit volume trajectories weighted by regional vehicle age distribution and EU CO2 fleet target compliance timelines.
Lead price volatility, lithium-ion chemistry cost reduction curves, and EU Green Deal regulatory acceleration are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context and supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Sodium-Ion Battery Market