
 Germany E-Commerce Market | 2026-2036
Germany E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Germany E-Commerce Market Intelligence
Grocery and fresh food delivery is shifting toward digital channels as German households reorder staples through apps. Amazon dominates fulfillment infrastructure with same-day coverage across major urban zones. Zalando specializes in fashion logistics, operating proprietary sizing algorithms and returns processing at scale. Otto anchors traditional catalogue retail transition, leveraging decades of customer data to compete in curated home goods.
Germany E-Commerce encompasses digitally mediated transactions for physical goods, relying on warehouse management systems, last-mile routing optimization, and payment gateway integration to complete sales. Fashion and electronics lead transaction volume, though home goods captures higher average order values through bundled shipping economics. Marketplaces aggregate third-party sellers under unified checkout experiences, while direct-to-consumer channels build proprietary customer relationships with tighter margin control. Subscription services represent the fastest-growing distribution channel, locking recurring revenue in beauty and pet supplies.
The EU Digital Services Act and Germany's Packaging Act shape platform liability and extended producer responsibility for online retailers. BSI technical standards govern IT security baselines for payment processing and customer data handling. Stakeholders must monitor enforcement divergence between federal cartel office scrutiny of marketplace fees and Brussels-mandated algorithmic transparency requirements.
Market Dynamics
The EU Digital Services Act is compressing platform liability timelines while Germany's Packaging Act tightens extended producer responsibility, forcing fulfillment networks to reconfigure last-mile infrastructure around compliance checkpoints rather than pure cost optimization.
Growth Catalysts
- Urban Logistics Corridor Density:Berlin and Rhine-Ruhr metropolitan clusters concentrate same-day delivery demand, enabling hub-and-spoke warehouse placement that reduces per-unit shipping costs below rural benchmarks.
- Verpackungsgesetz Amendments:Germany's Packaging Act mandates recyclable materials and dual-system participation, creating licensed compliance service providers that reduce administrative friction for cross-border sellers.
- Subscription Commerce Mechanics:Beauty and pet supply verticals lock recurring revenue through auto-replenishment algorithms, improving inventory predictability and reducing customer acquisition cost amortization periods.
Market Restraints
- Last-Mile Labor Cost Rigidity:German courier wage floors and collective bargaining agreements compress margin expansion even as automation investments rise, particularly affecting same-day service economics.
- Cross-Border Returns Processing:International sellers face asymmetric cost structures when German consumers exercise 14-day withdrawal rights under BGB consumer protection, creating working capital traps for marketplace third parties.
- Payment Gateway Fragmentation:SEPA direct debit dominance alongside rising instant payment alternatives forces redundant processor integrations, elevating technical debt for mid-market merchants.
Strategic Opportunities
- Fresh Food Cold Chain Gaps:Supermarket incumbents underinvest in temperature-controlled last-mile capacity, opening white space for dedicated grocery logistics operators with pharmaceutical-grade cold storage certification.
- AI-Driven Sizing and Fit Prediction:Computer vision and purchase-history clustering reduce fashion return rates, compressing reverse logistics costs that currently absorb 15-25 percent of category revenue.
- Rural Broadband Infrastructure Rollouts:Federal and state-funded gigabit expansion into eastern German districts unlocks e-commerce penetration in currently underserved postal code clusters.
Industry Challenges
- Warehouse Automation Integration:Legacy WMS platforms resist API-native robotics orchestration, forcing capital-intensive rip-and-replace cycles for mid-cap fulfillment operators.
- Cartel Office Fee Scrutiny:Bundeskartellamt investigations into marketplace commission structures create pricing uncertainty for platform-dependent merchants, complicating multi-year revenue forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany E-Commerce Market |
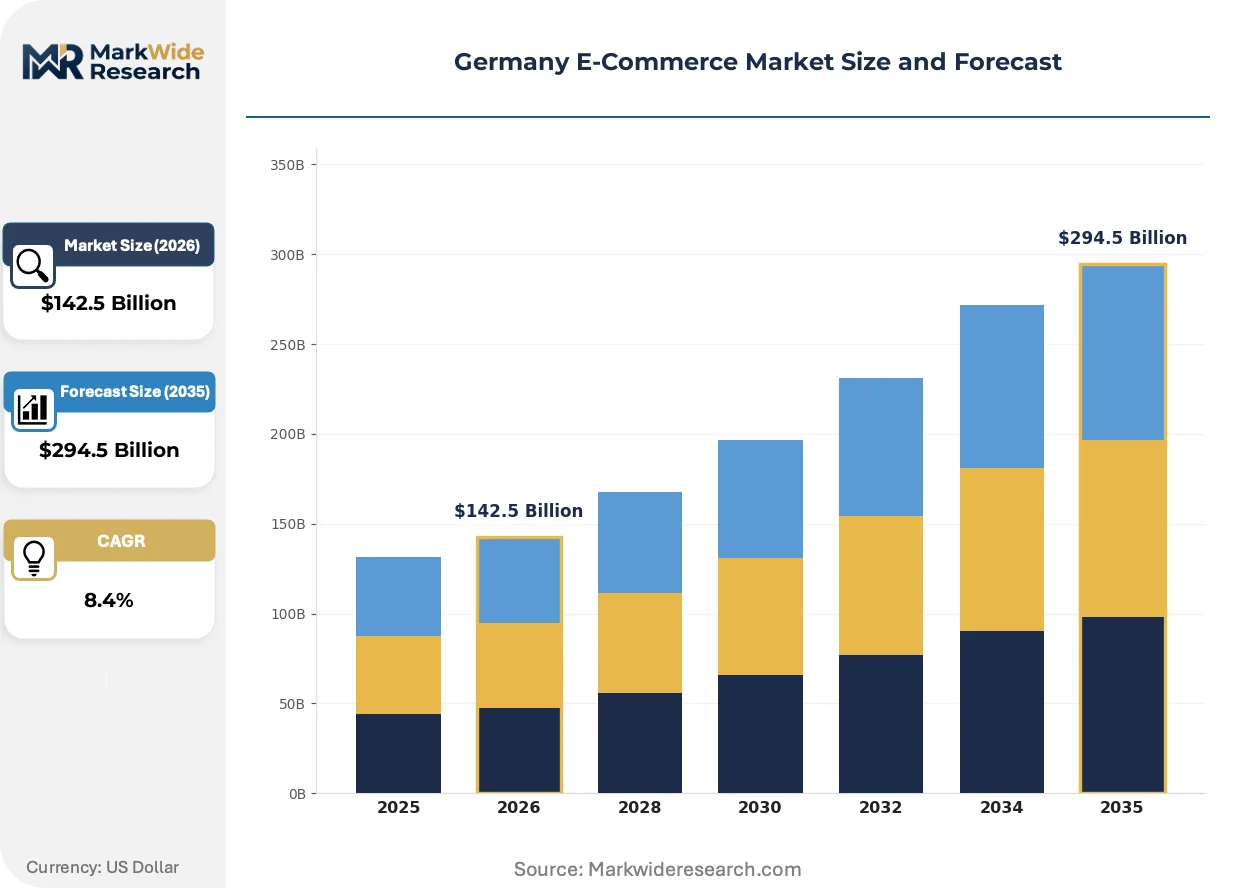
| Market Size in 2026 | $142.5 Billion |
| Market Size in 2035 | $294.5 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Home Goods, Beauty Customer Segment: Millennials, Gen Z, Families, Retirees Payment Method: Credit Card, PayPal, Bank Transfer, Digital Wallets Distribution Channel: Direct Sales, Marketplaces, Subscription Services, Others |
| Companies Covered | Amazon, Decathlon, Zalando, MediaMarkt, Kaufland, About You, eBay, Home24, Otto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany E-Commerce Market Strategic Shifts & Innovations
Algorithmic personalization and predictive inventory positioning are compressing the gap between browse and delivery, while regulatory transparency mandates force operational visibility that was previously proprietary.
Automated warehouse robotics is expanding into German fulfillment centers as labor availability tightens in logistics corridors. Third-party logistics providers deploy autonomous mobile robots for pick-and-pack operations in facilities exceeding 50,000 square meters. This technology is expanding into mid-cap merchant operations previously priced out of automation, compressing fulfillment cost differentials between Amazon-scale and independent sellers.
The EU Digital Services Act mandates algorithmic transparency and rapid illegal content takedown procedures for platforms exceeding 45 million monthly active users. German marketplace operators must disclose recommendation system parameters and suspend non-compliant sellers within 24 hours. Fashion and electronics aggregators face the heaviest compliance burden, diverting engineering resources from feature development to audit infrastructure.
German households now reorder staples through app-based grocery channels that bypass traditional weekly shopping trips. Discounters and full-range supermarkets compete on 15-minute delivery promises in Berlin, Munich, and Hamburg, displacing planned basket purchases with impulse-driven convenience commerce. Rural households lag this shift, maintaining higher in-store purchase frequency due to delivery slot scarcity and minimum order thresholds.
Germany E-Commerce Market Segmentation
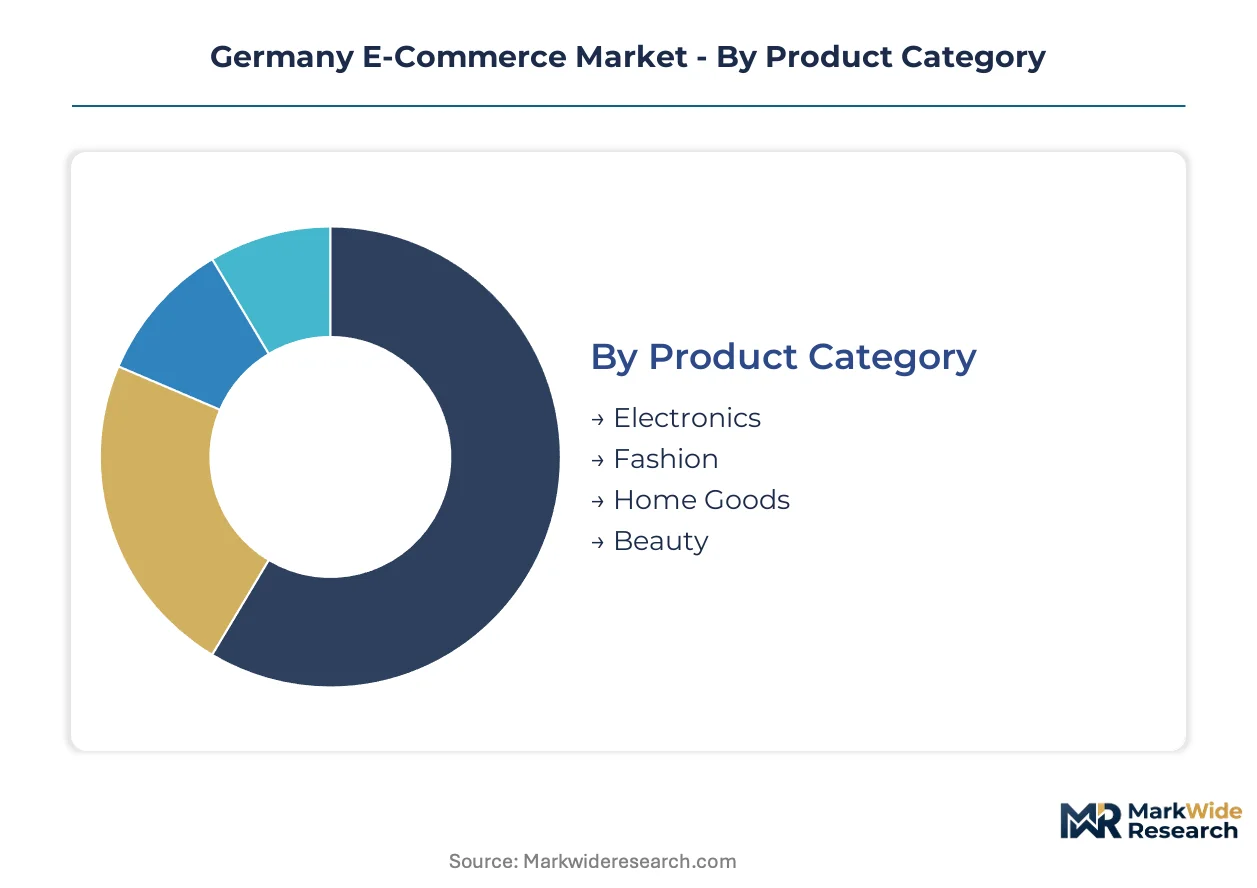
German e-commerce segmentation reveals how purchase cycles, payment preferences, and channel loyalty fragment the market. Understanding these divisions exposes where margin pools concentrate and which upgrade triggers drive repeat transactions.
Product Category:
Upgrade cycles vary dramatically across product types, with replacement frequency and bundling economics determining customer lifetime value trajectories.
- Electronics:Smartphones, laptops, and home entertainment systems carry 18-36 month replacement windows. Berlin and Rhine-Ruhr metropolitan clusters generate concentrated demand for same-day delivery of high-consideration items, though extended producer responsibility under Germany's Packaging Act elevates total cost of ownership disclosures.
- Fashion:Apparel and footwear purchases follow seasonal refresh patterns with elevated return rates. Zalando's proprietary sizing algorithms and Otto catalogue data reduce fit-related friction, compressing reverse logistics costs that otherwise absorb substantial category revenue.
- Home Goods:Furniture and décor command higher average order values through bundled shipping economics. Otto leverages decades of customer data to compete in curated selection, while marketplace aggregators struggle with delivery coordination for bulky items.
- Beauty:Skincare and cosmetics lock recurring revenue through subscription mechanics and auto-replenishment algorithms. Inventory predictability improves as German households shift staple reorders to app-based channels.
Electronics sits at the top of the volume ranking, with Beauty climbing the fastest.
Customer Segment:
Generational cohorts exhibit divergent channel preferences and price sensitivity thresholds that reshape platform merchandising strategies.
- Millennials:Urban professionals aged 28-43 prioritize convenience and same-day delivery availability. This cohort concentrates in Berlin, Munich, and Hamburg, driving demand for grocery and fresh food apps that bypass traditional weekly shopping trips.
- Gen Z:Digital-native consumers under 27 favor marketplaces with social commerce integration and instant payment alternatives. SEPA direct debit familiarity coexists with rising digital wallet adoption, forcing redundant processor integrations for merchants targeting this segment.
- Families:Multi-person households optimize for subscription services in pet supplies and bulk staples. Minimum order thresholds and delivery slot scarcity in rural eastern districts maintain higher in-store purchase frequency compared to urban counterparts.
- Retirees:Older consumers demonstrate stronger loyalty to established catalogue retailers transitioning online. Otto anchors this segment through familiar brand recognition, though payment gateway fragmentation creates technical friction for less digitally fluent users.
Millennials capture the largest transaction volume share, with Gen Z expanding most quickly.
Payment Method:
Settlement infrastructure fragmentation elevates technical debt and determines checkout completion rates across merchant tiers.
- Credit Card:Visa and Mastercard networks dominate high-value transactions with chargeback protection. Cross-border sellers face asymmetric cost structures when German consumers exercise 14-day withdrawal rights under BGB consumer protection.
- PayPal:Digital wallet incumbent with established trust markers for marketplace purchases. Bundeskartellamt scrutiny of platform fee structures creates pricing uncertainty for merchants dependent on this channel.
- Bank Transfer:SEPA direct debit retains dominance in recurring subscription billing. Legacy integration requirements complicate instant payment adoption for mid-market merchants.
- Digital Wallets:Apple Pay and Google Pay penetration accelerates among Gen Z and urban Millennials. BSI technical standards govern IT security baselines for tokenized payment processing and customer data handling.
Bank Transfer maintains the highest transaction frequency, with Digital Wallets gaining share fastest.
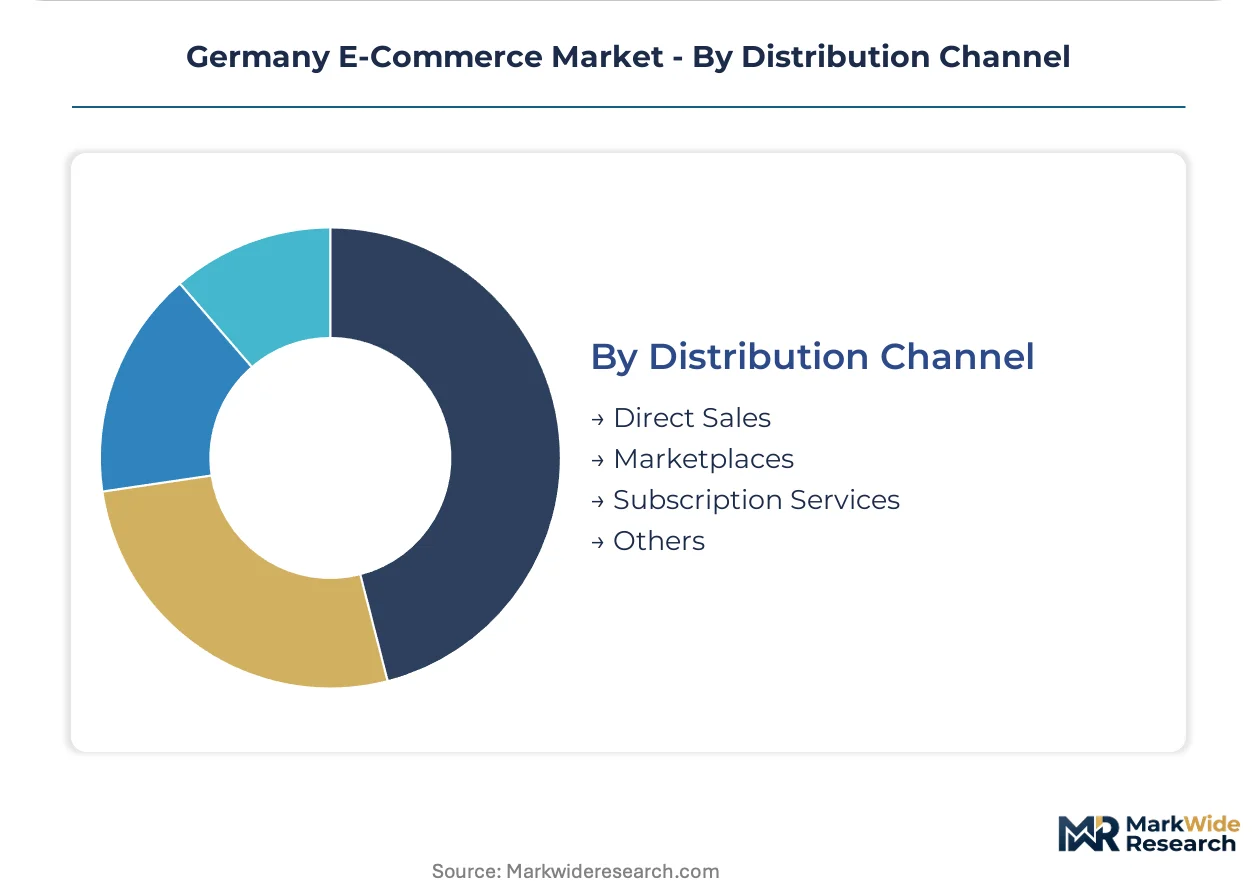
Distribution Channel:
Channel selection determines margin control, customer data ownership, and compliance burden intensity under EU Digital Services Act mandates.
- Direct Sales:Proprietary storefronts build customer relationships with tighter margin control and first-party data access. Warehouse automation integration challenges force capital-intensive WMS replacement cycles for scaling operators.
- Marketplaces:Amazon and Zalando aggregate third-party sellers under unified checkout experiences. Algorithmic transparency requirements and 24-hour takedown obligations divert engineering resources from feature development to audit infrastructure.
- Subscription Services:Auto-replenishment models in beauty and pet supplies improve inventory predictability. Recurring revenue structures reduce customer acquisition cost amortization periods compared to transactional channels.
- Others:Social commerce and live shopping formats emerge as experimental channels. EU Digital Services Act liability timelines compress platform risk assessment for emerging format adoption.
Marketplaces command the dominant volume position, with Subscription Services showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cross-border fulfillment strategies as sellers migrate warehousing investments toward German federal states with streamlined Packaging Act compliance pathways and lower dual-system participation costs.
North Rhine-Westphalia
Rhine-Ruhr metropolitan clusters concentrate same-day delivery demand from dense urban populations. The state's implementation of federal cartel office guidelines on marketplace fee transparency creates operational certainty for third-party logistics providers. Düsseldorf and Cologne anchor fulfillment hub placement that serves both domestic and Benelux cross-border flows.
Bavaria
Munich's affluent consumer base drives premium-category transaction density in electronics and home goods. Bavarian state funding for rural broadband expansion unlocks e-commerce penetration in eastern districts previously constrained by connectivity gaps. Nuremberg logistics corridors specialize in temperature-controlled capacity for pharmaceutical-grade cold chain requirements.
Berlin-Brandenburg
Berlin's urban logistics corridor generates concentrated demand for grocery and fresh food delivery apps. The federal state's dual-system waste management infrastructure reduces administrative friction for marketplace sellers navigating Verpackungsgesetz amendments. Potsdam warehousing clusters benefit from proximity to Berlin's same-day delivery zones while escaping core city congestion charges.
Baden-Württemberg
Stuttgart's manufacturing heritage supports B2B e-commerce channels serving Mittelstand industrial buyers. State-level IT security initiatives align with BSI technical standards for payment gateway certification, reducing compliance costs for regional merchants. Karlsruhe data center concentration underpins cloud-native warehouse management system deployments.
Hesse
Frankfurt's financial infrastructure anchors SEPA direct debit processing and instant payment routing for subscription commerce operators. The state's central geographic position minimizes average shipping distances to all federal regions, compressing per-unit logistics costs. Fulfillment operators leverage Frankfurt Airport cargo capacity for cross-border returns processing efficiency.
Germany E-Commerce Market Key Industry Players
Capacity expansion dominates the current landscape as fulfillment operators race to secure warehouse space in constrained urban logistics corridors. The market structures around three tiers: integrated marketplace platforms with captive logistics networks, specialized vertical retailers with proprietary customer data, and third-party logistics providers serving fragmented merchant bases. Strategic archetypes include technology-heavy automation leaders, catalog-era incumbents transitioning digital infrastructure, and cross-border specialists navigating EU Digital Services Act compliance. Geographic expansion and vertical integration into last-mile delivery represent the dominant competitive moves.
Among integrated marketplace platforms, Amazon and Zalando exemplify divergent specialization strategies, with the former anchoring generalist fulfillment infrastructure and the latter occupying fashion-specific logistics expertise. Otto represents the catalog-retailer archetype transitioning legacy customer relationships into digital channels. These three entities collectively illustrate how scale, vertical focus, and historical data assets create differentiated positioning against mid-cap merchants dependent on shared logistics infrastructure.
| Leading Market Players |
|---|
| Amazon |
| Decathlon |
| Zalando |
| MediaMarkt |
| Kaufland |
| About You |
| eBay |
| Home24 |
| Otto |
| Others |
Cost & Logistics Intelligence
Logistics real estate rental indices in Rhine-Ruhr and Berlin corridors cascade through fulfillment cost structures, compressing margins for marketplace-dependent merchants while enabling premium pricing for operators with captive warehouse networks. This cost pressure stratifies the market into automation-leaders, legacy catalogue transitions, and logistics-dependent mid-caps.
Pricing Analysis
Retailer markup layers in marketplace channels absorb the heaviest compression as Bundeskartellamt fee scrutiny intensifies. Three-tier pricing structure across premium, standard, and economy levels differentiates by delivery speed and returns flexibility, with urban Millennials least price-sensitive on same-day premiums. Cost compression in standard-tier fulfillment is intensifying because warehouse automation capex requirements exclude smaller third-party sellers. Families in rural eastern districts exhibit highest price sensitivity due to minimum order thresholds and delivery slot scarcity.
Supply Chain Analysis
Warehouse management system software supply rests on German and Dutch enterprise software providers, with robotics hardware feeding from Chinese and Danish automation specialists. Cloud infrastructure dependencies center on Frankfurt and Karlsruhe data center clusters, while last-mile courier capacity draws from regional German logistics networks. Single-source vulnerability concentrates in proprietary sizing algorithm providers serving fashion verticals. Distribution runs through hub-and-spoke networks anchored in North Rhine-Westphalia and Berlin-Brandenburg corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
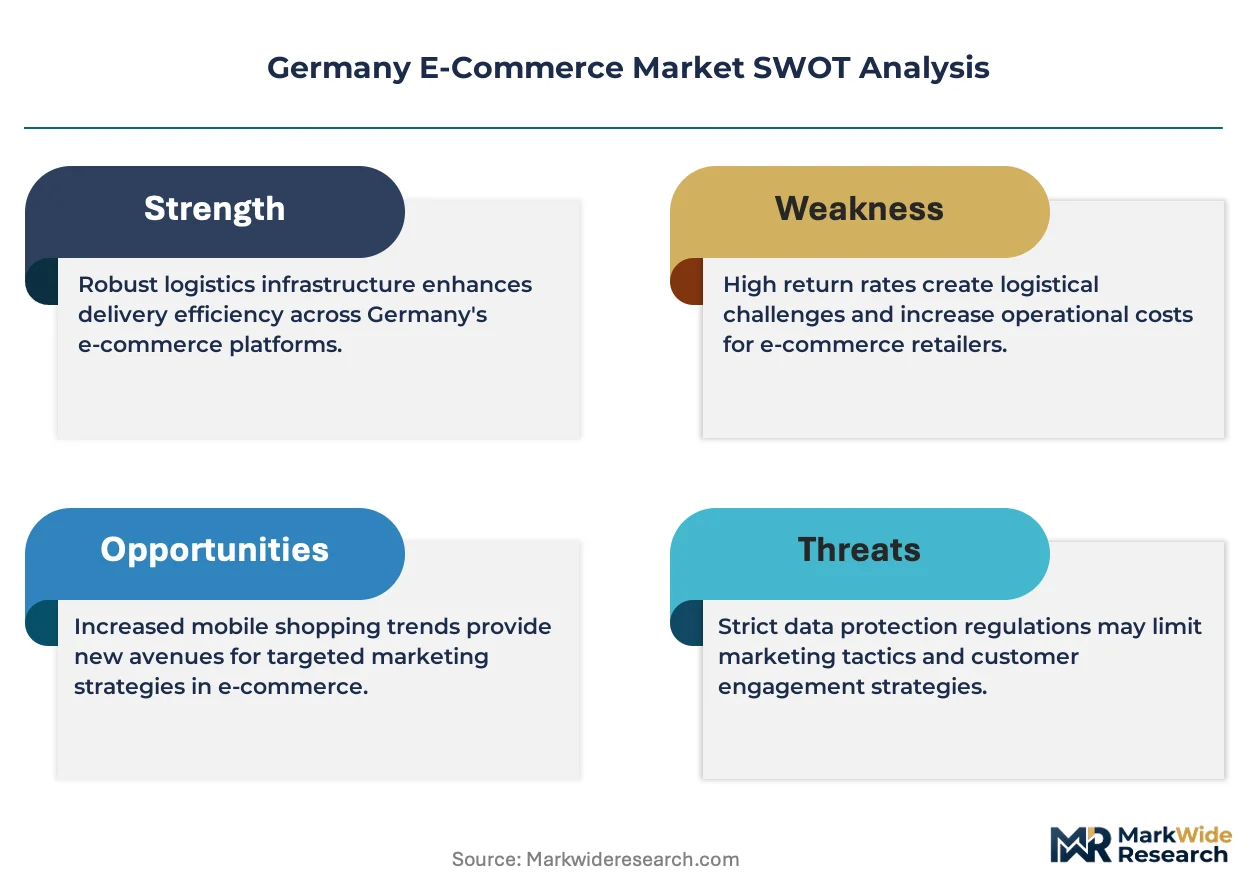
German e-commerce offers margin expansion through automation-led fulfillment cost reduction and subscription commerce premiumization. Cold chain infrastructure gaps and AI-driven returns prevention represent the most actionable premium-tier shifts.
For Market Incumbents: Anchor defensive positioning through proprietary warehouse automation in Rhine-Ruhr corridors and backward integration into last-mile courier networks. The EU Digital Services Act takedown obligations threaten marketplace-dependent revenue streams, making first-party data assets and direct channel control the priority defensive lever. Incumbents should consolidate Berlin logistics real estate before rental indices reset upward. For New Entrants and Emerging Players: The EU Digital Services Act in Germany opens a window for compliance-native marketplace architectures that embed algorithmic transparency and rapid seller suspension infrastructure from launch. Fresh food cold chain gaps in Bavarian and eastern rural districts represent the most penetrable white space, with pharmaceutical-grade certification as the distinguishing go-to-market angle. Subscription mechanics in pet supplies and beauty offer recurring revenue structures with lower customer acquisition cost amortization than transactional entry. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical AI specialists in sizing prediction and returns reduction software. The five-to-ten year viability window favors acquisition targets with proprietary logistics data assets and Berlin-Brandenburg warehouse footprints. Watch Bundeskartellamt enforcement patterns on marketplace fees as the inflection signal for platform-dependent merchant margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Deployment | Autonomous mobile robots in Rhine-Ruhr facilities compress per-unit fulfillment costs below shared logistics benchmarks. |
| Cold Chain Infrastructure Buildout | Pharmaceutical-grade temperature-controlled capacity in Bavaria captures grocery and fresh food delivery premium tiers. |
| AI-Driven Returns Prevention | Computer vision sizing algorithms reduce fashion reverse logistics costs that currently absorb substantial category revenue. |
| Subscription Commerce Platform | Auto-replenishment mechanics in beauty and pet supplies lock recurring revenue with superior inventory predictability. |
| Regulatory Compliance Infrastructure | EU Digital Services Act-native audit systems divert engineering resources from feature development but create competitive moats. |
Research Approach
Multiple input streams — fulfillment operator interviews, merchant platform data, and regulatory filing analysis — were reconciled to construct this market view. Primary conversations with warehouse automation vendors, third-party logistics procurement leads, marketplace seller operations heads, and Bundesnetzagentur policy specialists informed operational cost structures. Secondary validation drew from German Federal Cartel Office proceedings, EU Digital Services Act implementation guidance, Verpackungsgesetz compliance databases, and logistics real estate rental indices. Bottom-up merchant revenue aggregation and top-down macro consumption trend analysis were cross-checked for triangulation.
Data-stream reconciliation across product category, customer segment, payment method, and distribution channel dimensions shaped the analytical framework. Modeled variables included replacement cycle frequency, return rate differentials, and subscription penetration curves across the projection horizon. CAGRs were derived from logistic adoption curve fitting and urban logistics corridor density projections. Forecast inputs incorporated SEPA payment infrastructure evolution and dual-system packaging compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Bundeskartellamt fee restructuring scenarios and courier collective bargaining renegotiations. Forecasts reflect assumptions on automation capex depreciation schedules and cold chain infrastructure buildout pacing. A small set of named triggers — rural broadband completion rates, algorithmic transparency enforcement intensity, and warehouse robotics integration failure rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Japan Same Day Delivery Market