
 Malaysia Robotics Market | 2026-2036
Malaysia Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Robotics Market Foresight
Malaysia's Industry4WRD policy framework is broadening the addressable market for robotics across Malaysian manufacturing zones. ABB leverages its regional service infrastructure to anchor automation deployments in Penang's semiconductor cluster. Yaskawa Electric Corporation sustains its position through dedicated distribution partnerships serving Johor's medical device factories. Epson Robotics specializes in compact SCARA systems that dominate precision assembly lines in Selangor electronics plants.
Robotics encompasses programmable electromechanical machines with articulated joints, servo motors, and control systems operating at repeatability tolerances below 0.1 millimeter for industrial tasks. These systems execute welding, material transport, quality inspection, and component assembly with speed and precision exceeding human capability in repetitive manufacturing environments. Industrial robots retain the largest installed base across Malaysian automotive and electronics sectors, while autonomous mobile robots represent the fastest-expanding category as warehouses in Shah Alam and Port Klang adopt fleet-based logistics automation. Artificial Intelligence integration sits at the highest margin tier, commanding premium pricing for vision-guided picking and adaptive path-planning functions.
Malaysia's Department of Standards enforces MS IEC 61508 functional safety requirements for robotic installations, while SIRIM QAS International administers conformity assessment protocols that shape product certification timelines. The Ministry of International Trade and Industry coordinates Industry4WRD incentives that directly condition capital expenditure decisions among domestic manufacturers. Stakeholders must monitor BIS-equivalent standard harmonization progress and PLI scheme eligibility criteria to secure competitive positioning in federally supported automation tenders.
Market Dynamics
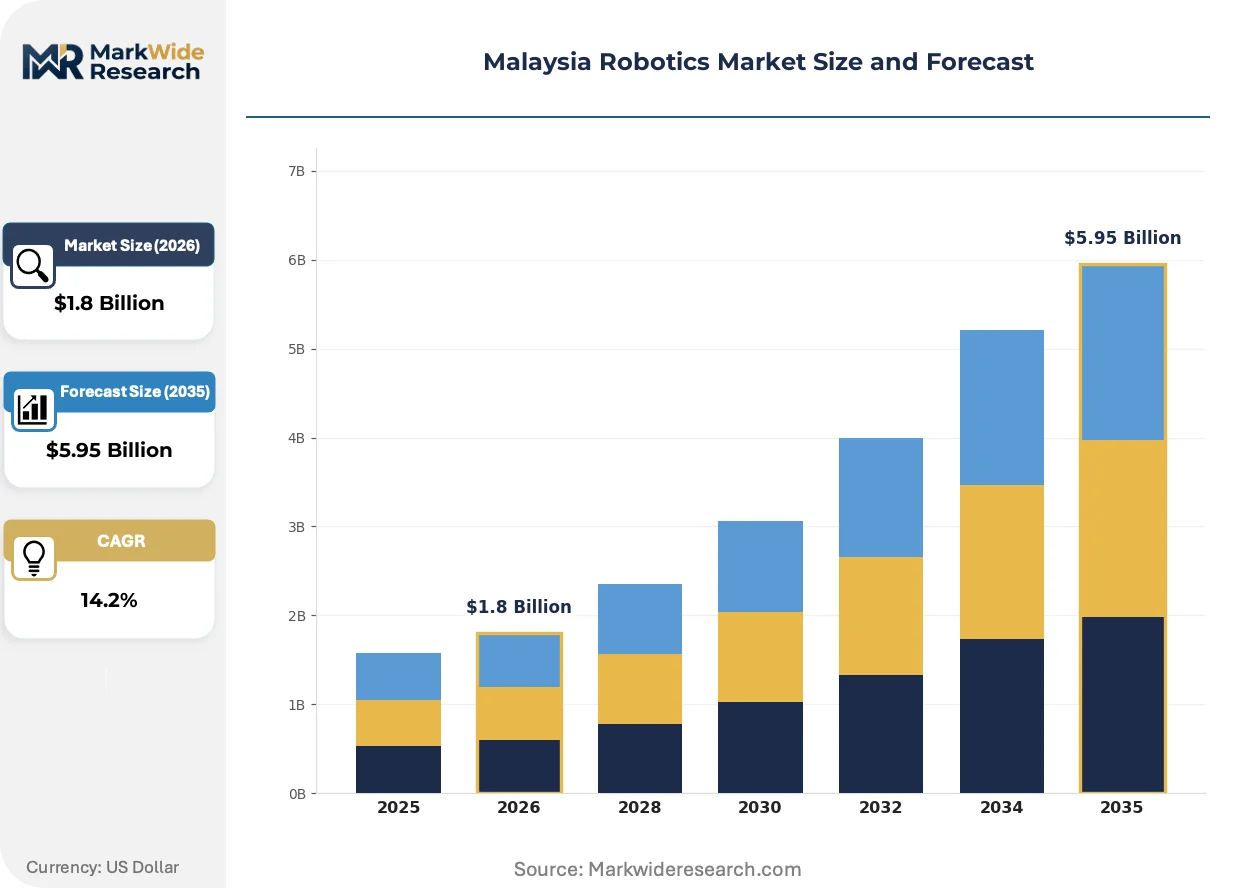
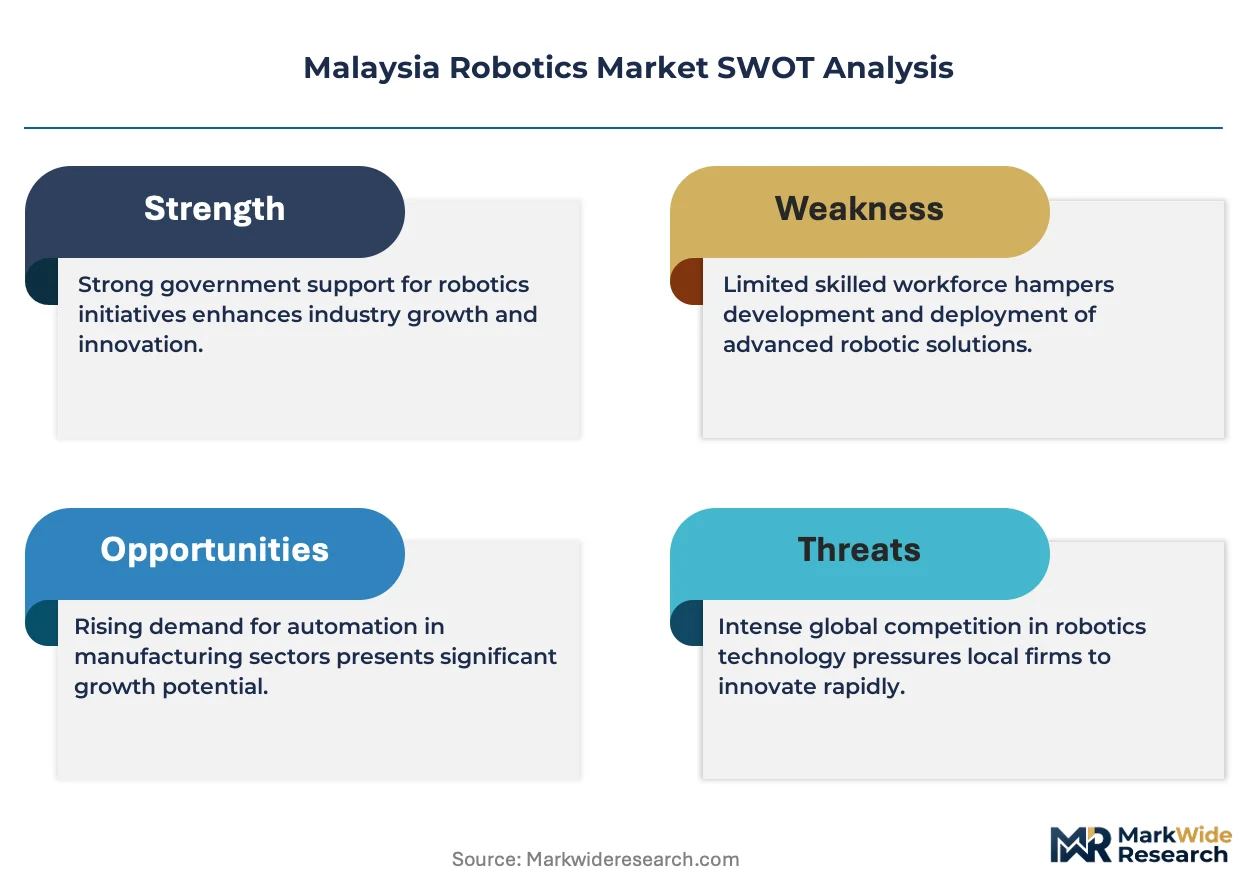
Malaysia's Industry4WRD policy framework is compressing automation procurement cycles as federal incentives front-load capital expenditure decisions across Penang and Selangor manufacturing zones. Electronics contract manufacturers now embed robotics specifications into greenfield facility designs rather than retrofitting existing lines.
Growth Catalysts
- Industry4WRD Incentive Structure:The Ministry of International Trade and Industry coordinates tax allowances and automation grants that directly reduce payback periods for robotic system investments in qualified manufacturing facilities.
- Electronics Manufacturing Concentration:Penang's semiconductor packaging plants and Selangor's precision assembly operations generate sustained demand for collaborative robots and SCARA systems with sub-millimeter repeatability specifications.
- Autonomous Mobile Robot Fleet Adoption:Warehousing and logistics operators in Shah Alam and Port Klang are deploying AMR fleets to address labor availability constraints in material transport operations.
Market Restraints
- MS IEC 61508 Certification Friction:SIRIM QAS International conformity assessment protocols extend deployment timelines for safety-critical robotic installations by six to twelve months.
- Specialized Integration Talent Scarcity:System integrators capable of programming adaptive path-planning and vision-guided functions command premium rates that inflate total project costs.
- Imported Component Dependency:Servo motors, precision reducers, and machine vision sensors concentrate supply in Japanese and German manufacturing bases, exposing Malaysian integrators to currency and shipping volatility.
Strategic Opportunities
- Johor Medical Device Manufacturing:Sterile assembly and packaging automation remains underpenetrated in Iskandar Malaysia's growing medical technology corridor.
- AI-Vision Convergence:Machine learning-enabled defect detection systems create premium service attach opportunities for integrators serving quality-critical electronics lines.
- Rental and Subscription Models:Capital-constrained small and medium manufacturers in Perak and Kedah represent addressable demand for robotics-as-a-service arrangements.
Industry Challenges
- Legacy Control System Integration:Proprietary communication protocols in existing programmable logic controllers complicate unified fleet management for mixed-vendor robot deployments.
- Functional Safety Engineering Shortage:Certified safety engineers capable of designing compliant safety-rated monitored stop and speed separation systems remain concentrated in Kuala Lumpur and Penang.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Robotics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots End User: Manufacturing, Healthcare, Logistics, Agriculture Technology: Artificial Intelligence, Machine Learning, Computer Vision, Automation Software Application: Welding, Assembly, Inspection, Material Handling |
| Companies Covered | ABB, Yaskawa Electric Corporation, Epson Robotics, Midea Group, SMC Corporation, Festo AG & Co. KG, Omron Adept, THK Co., Ltd., Jorvix Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Robotics Market Shifts & Advancements
Artificial intelligence integration is restructuring competitive differentiation across Malaysian robotics deployments. Vision systems now adapt to product variations without reprogramming, compressing changeover intervals and enabling smaller batch economics.
Collaborative robots with integrated force-torque sensors and adaptive control algorithms are overtaking traditional caged industrial robots in electronics assembly applications. Penang semiconductor packaging facilities deploy these systems for delicate component placement tasks. The technology is compressing minimum viable automation thresholds downward, enabling mid-volume manufacturers to justify robotic investment.
Malaysia's Department of Standards is harmonizing functional safety requirements with IEC 61508 international frameworks. SIRIM QAS International administers updated conformity assessment protocols that streamline certification for multinational vendors. Medical device manufacturers in Johor face the most stringent compliance timelines as they navigate both MS IEC 61508 and ISO 13485 quality system requirements simultaneously.
Electronics manufacturers are unbundling after-sales service contracts from initial equipment purchases. Procurement teams in Selangor now negotiate separate maintenance, spare parts, and software upgrade agreements with third-party integrators. This shift is most visible among multinational contract manufacturers operating in the Klang Valley industrial corridor, where internal engineering teams assume direct vendor management responsibilities.
Malaysia Robotics Market Segmentation
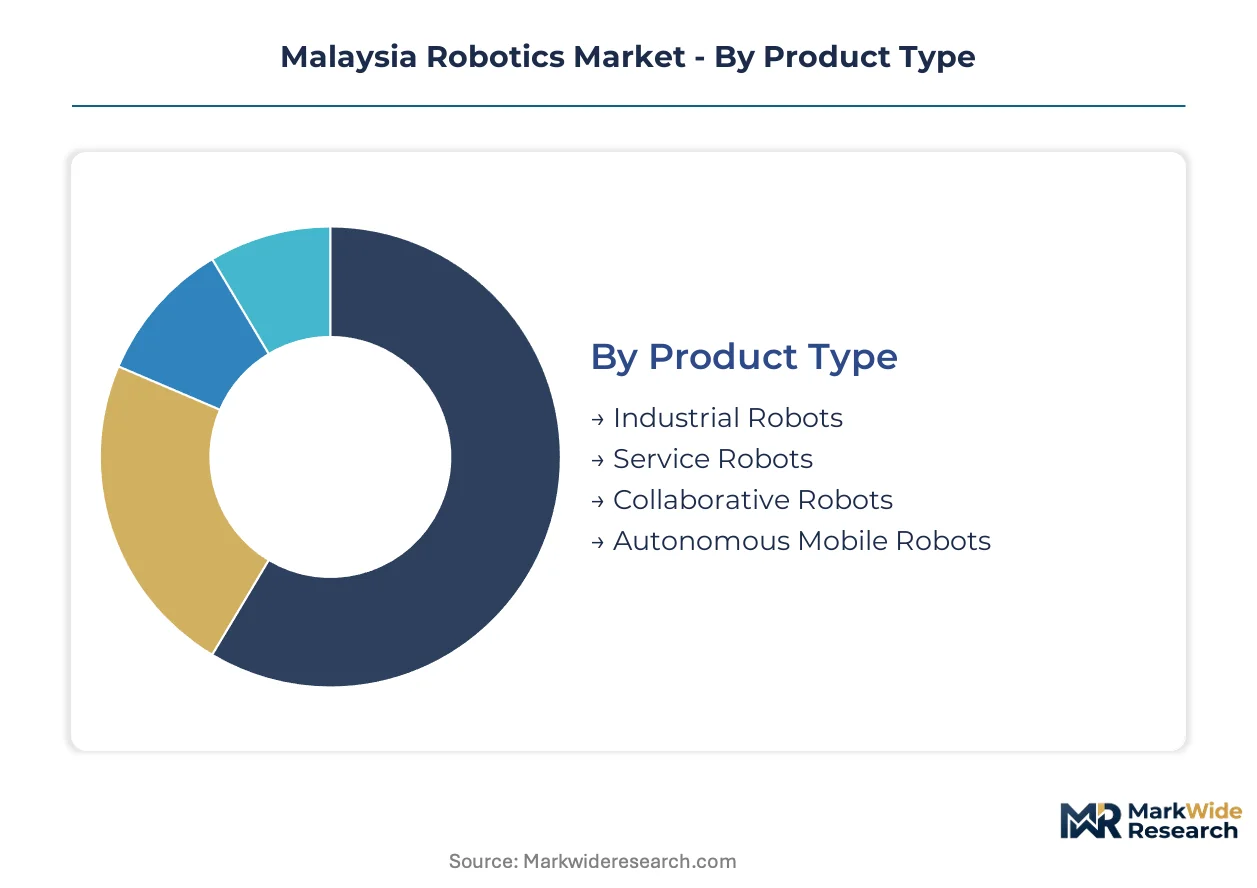
Malaysia's robotics market segments along four distinct axes that reflect procurement priorities across Penang semiconductor plants, Selangor electronics assembly lines, and Johor medical device facilities. Each segmentation dimension captures different decision-maker concerns spanning capital intensity, integration complexity, and operational risk tolerance.
Product Type:
Articulation architecture and payload specifications define procurement categories across Malaysian manufacturing zones.
- Industrial Robots:Six-axis articulated systems with servo-driven precision exceeding 0.1 millimeter repeatability dominate automotive welding and heavy-payload material transport. Penang semiconductor packaging plants deploy these for die-bonding operations requiring sustained throughput under cleanroom conditions.
- Collaborative Robots:Force-torque sensing and adaptive control algorithms enable fenceless deployment alongside human operators. Selangor electronics contract manufacturers favor these for delicate component placement where changeover frequency exceeds traditional automation economics.
- Autonomous Mobile Robots:Fleet-based navigation systems address labor availability constraints in Shah Alam and Port Klang warehousing corridors.
- Service Robots:Non-industrial deployment categories span healthcare assistance and hospitality functions with limited current penetration in Malaysian end-use markets.
Industrial robots lead on scale; autonomous mobile robots lead on momentum.
End User:
Operational environment and regulatory exposure shape buyer specifications across sectoral boundaries.
- Manufacturing:Electronics contract manufacturers in the Klang Valley industrial corridor generate concentrated demand for SCARA systems and collaborative robots with sub-millimeter placement accuracy. MS IEC 61508 functional safety compliance requirements extend procurement cycles for safety-critical installations.
- Logistics:Warehousing operators in Port Klang and Shah Alam deploy AMR fleets for pallet transport and order fulfillment automation. Labor cost pressures and throughput targets drive adoption ahead of other end-use categories.
- Healthcare:Sterile assembly automation in Johor's Iskandar Malaysia medical technology corridor remains underpenetrated relative to electronics manufacturing intensity.
- Agriculture:Precision harvesting and greenhouse automation applications show nascent deployment in Malaysian palm oil and vegetable production regions.
Manufacturing commands installed base dominance; logistics exhibits the steepest expansion trajectory.
Technology:
Intelligence layer integration determines margin capture and competitive differentiation for system vendors.
- Computer Vision:Camera-based defect detection and guidance systems enable adaptive quality control without mechanical fixturing. Selangor electronics plants deploy these for real-time solder joint inspection.
- Artificial Intelligence:Machine learning-enabled path planning and predictive maintenance commands premium pricing tiers. Malaysian integrators with AI capabilities capture service attach revenue beyond hardware margins.
- Machine Learning:Algorithmic adaptation to product variation compresses changeover intervals for mid-volume manufacturers.
- Automation Software:Fleet management and unified control platforms address integration complexity in mixed-vendor robot deployments.
Computer vision leads on deployment penetration; artificial intelligence leads on value capture potential.
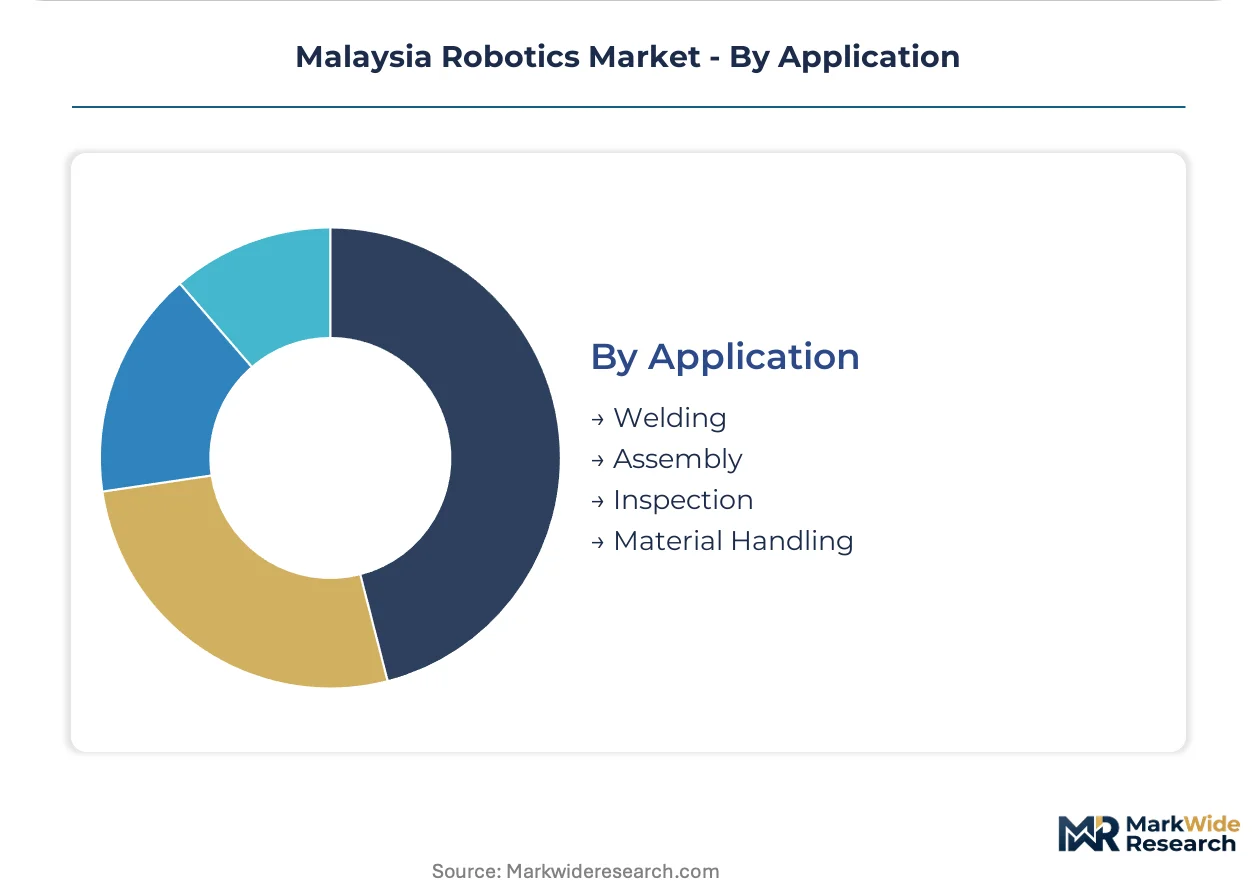
Application:
Process step requirements dictate robot morphology and end-effector specifications.
- Assembly:Precision component placement tasks in Selangor electronics facilities demand SCARA and collaborative robot configurations with force-limiting capabilities. Miniaturization trends in semiconductor packaging drive specification tightening.
- Material Handling:Pallet transport, bin picking, and kitting operations in Port Klang logistics hubs favor AMR and gantry robot deployments. Throughput targets and labor substitution economics justify capital expenditure.
- Welding:Automotive and metal fabrication applications in Malaysian industrial zones utilize articulated industrial robots with specialized torch configurations.
- Inspection:Vision-guided quality verification functions increasingly unbundle from dedicated metrology equipment into integrated robotic workcells.
Assembly leads on specification complexity; material handling leads on volume scaling potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial robotics originated in the United States and Japan during the 1960s, with Unimate's deployment at General Motors establishing the foundational architecture that Malaysian manufacturers now adopt under Industry4WRD modernization programs.
Selangor
Electronics contract manufacturers in the Klang Valley industrial corridor generate concentrated demand for SCARA systems and collaborative robots with sub-millimeter repeatability specifications. The Ministry of International Trade and Industry coordinates Industry4WRD tax allowances that reduce capital expenditure payback periods for qualified facilities. Shah Alam warehousing operators deploy autonomous mobile robot fleets to address labor availability constraints in material transport operations.
Penang
Semiconductor packaging plants anchor end-use demand for six-axis articulated systems operating under cleanroom conditions with sustained throughput requirements. MS IEC 61508 functional safety requirements enforced by the Department of Standards extend procurement cycles for safety-critical installations. Bayan Lepas and Kulim industrial zones concentrate precision assembly automation deployments serving multinational electronics supply chains.
Johor
Medical device manufacturers in Iskandar Malaysia's growing technology corridor generate emerging demand for sterile assembly and packaging automation systems. Dual compliance requirements spanning MS IEC 61508 and ISO 13485 quality systems create extended certification timelines for safety-rated installations. Pasir Gudang industrial area hosts underpenetrated automation opportunities relative to electronics manufacturing intensity in northern states.
Kedah and Perak
Capital-constrained small and medium manufacturers in northern peninsular states represent addressable demand for robotics-as-a-service subscription arrangements. Industry4WRD incentive structures extend federal automation grants to qualified facilities outside core industrial corridors. Kulim and Ipoh manufacturing zones exhibit nascent collaborative robot adoption for mid-volume precision assembly applications.
Malaysia Robotics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with artificial intelligence-enabled vision systems commanding pricing multiples over standard automation hardware. The vendor base concentrates around three strategic archetypes: multinational industrial automation conglomerates with regional service infrastructure, specialized robotics manufacturers with focused articulation architectures, and domestic system integrators with localized deployment capabilities. Competitive dynamics center on strategic partnerships for distribution reach and portfolio diversification into adjacent automation software categories.
Among multinational industrial automation conglomerates, ABB and Yaskawa Electric Corporation exemplify the premium-tier positioning anchored by regional service infrastructure. Epson Robotics occupies a specialist position within compact SCARA system manufacturing. Domestic integrators including Jorvix Sdn Bhd represent the localization-focused tier serving mid-market manufacturers with deployment and programming services. These three archetypes collectively structure competitive positioning across Penang semiconductor clusters and Selangor electronics assembly corridors.
| Leading Market Players |
|---|
| ABB |
| Yaskawa Electric Corporation |
| Epson Robotics |
| Midea Group |
| SMC Corporation |
| Festo AG & Co. KG |
| Omron Adept |
| THK Co., Ltd. |
| Jorvix Sdn Bhd |
| Others |
Supply & Pricing Matrix
Precision reducer and servo motor costs originating from Japanese and German manufacturing bases cascade through three distinct pricing tiers before reaching Malaysian electronics contract manufacturers in Selangor and Penang. Currency volatility and shipping rate fluctuations compress margins for domestic system integrators while amplifying price differentiation between premium AI-enabled systems and standard automation hardware.
Pricing Analysis
Project-based contracting with modular software licensing dominates Malaysian robotics procurement, separating AI-vision integrated workcells from basic SCARA deployments through certification grade and after-sales service bundling. Price differentiation rests on MS IEC 61508 functional safety compliance and adaptive path-planning capabilities. Cost compression in mid-tier collaborative robot segments is intensifying because domestic integrators compete aggressively on deployment services. Small and medium manufacturers in Kedah and Perak exhibit highest price sensitivity, while multinational semiconductor packaging facilities in Penang prioritize performance specifications over capital outlay.
Supply Chain Analysis
Regional distribution centers in Singapore and Kuala Lumpur operate hub-and-spoke patterns serving Penang semiconductor clusters and Johor medical device corridors. Servo motors, harmonic drives, and machine vision sensors draw from concentrated manufacturing in Japan, Germany, and South Korea. Single-source vulnerability in precision reducer supply creates exposure to export control adjustments. Distribution runs through authorized distributor networks with localized spare parts warehousing for maintenance contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian robotics margins expand as AI-vision software attach rates climb and Industry4WRD incentives compress customer payback periods. Component localization and rental model innovation further reduce customer acquisition costs.
For Market Incumbents: Extend regional service infrastructure into Johor's medical device corridor before specialized integrators establish entrenched relationships. Deepen backward integration into machine vision software development to defend against pure-play AI entrants. Lock in exclusive distribution partnerships with SIRIM QAS International-certified safety engineers concentrated in Kuala Lumpur and Penang. For New Entrants and Emerging Players: Capital-constrained small and medium manufacturers in northern peninsular states represent the most penetrable buyer archetype for robotics-as-a-service subscription models. Target sterile assembly automation in Iskandar Malaysia's underpenetrated medical technology zone. Lead with flexible rental terms and rapid deployment capabilities rather than competing on specification breadth. For Investors and Strategic Acquirers: Consolidation pressure builds where AI-vision capabilities concentrate among a handful of domestic integrators with proven Industry4WRD deployment track records. Long-term viability favors specialists with certified safety engineering depth and recurring software revenue streams. Watch SIRIM QAS International certification timeline compression as the signal for vendor scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Vision Software Development | Machine learning-enabled defect detection commands premium pricing in Selangor electronics quality lines. |
| Regional Service Hub Expansion | Johor medical device manufacturers require localized sterile assembly automation expertise currently concentrated northward. |
| Robotics-as-a-Service Launch | Subscription models unlock capital-constrained manufacturers in Kedah and Perak outside core industrial corridors. |
| Safety Engineering Certification Investment | MS IEC 61508 compliance capabilities differentiate vendors in federally supported Industry4WRD tenders. |
| Backward Integration into Precision Components | In-house production of servo systems reduces exposure to Japanese and German supply volatility. |
Research Methodology
Direct dialogue with robotics system integrators, plant engineers at electronics contract manufacturers, SIRIM QAS International certification officers, and Industry4WRD program administrators grounded qualitative findings. Secondary validation drew from MITI incentive disclosure records, Department of Standards regulatory filings, customs import data for precision automation components, and multinational vendor regional revenue statements. Bottom-up deployment counts across Penang, Selangor, and Johor manufacturing zones triangulated against top-down market sizing from federal industrial automation expenditure tracking.
Installed base projections and value estimates emerged from segment-level modeling across product type, end-use sector, technology integration depth, and application function throughout the forecast period. CAGRs were derived from historical automation capital expenditure patterns and Industry4WRD incentive uptake trajectories. Forecast inputs incorporated electronics manufacturing foreign direct investment flows and AMR fleet adoption rates in Port Klang logistics corridors.
Underlying measurement precision varies by segment; collaborative robot and AMR deployment counts carry tighter precision than AI-vision software attach rate estimates. Forecasts reflect documented assumptions regarding Industry4WRD incentive continuity and MS IEC 61508 harmonization progress. Supply chain disruption or regulatory timeline extension could materially revise trajectory projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Healthcare Mobile Robots Market