
 Global Subscription E-Commerce Platform Market | 2026-2036
Global Subscription E-Commerce Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subscription E-Commerce Platform Market Foresight
GDPR enforcement is shifting the cost-of-entry calculus for subscription e-commerce platforms serving European consumers. Shopify Inc. leverages its native compliance tooling to reduce merchant onboarding friction across jurisdictions. Amazon.com Inc. anchors its subscription dominance through Prime's integrated logistics and payment infrastructure. Stripe Inc. differentiates via developer-first APIs that embed recurring billing into custom storefronts.
A subscription e-commerce platform is a software architecture enabling merchants to automate recurring billing, manage subscriber lifecycles, and orchestrate fulfillment workflows through API-connected payment gateways and inventory systems. These platforms process tokenized payment credentials, apply dunning management for failed transactions, and synchronize subscription states with warehouse management systems to sustain predictable revenue streams. Cloud-Based deployment leads structural adoption due to elastic scaling during promotional surges and reduced capital expenditure for mid-market merchants. Service Subscription offerings within the Subscription Offering dimension capture expanding margin pools as brands bundle advisory, repair, and digital content alongside physical goods.
The EU AI Act and FDA guidelines for direct-to-consumer health product claims shape platform content moderation and product listing standards in their respective jurisdictions. ISO 27001 certification and PCI DSS Level 1 compliance function as baseline market-access requirements for enterprise procurement. Stakeholders must monitor evolving state-level automatic renewal laws in the United States and emerging digital consumer protection frameworks in Asia-Pacific markets to preempt compliance-driven platform migrations.
Market Dynamics
Recurring billing automation is rewriting merchant economics by compressing customer acquisition costs into predictable lifetime value equations. Platform vendors now engineer around GDPR data residency mandates and PCI DSS tokenization requirements as baseline architectural constraints.
Growth Catalysts
- Beauty and personal care subscription adoption:Direct-to-consumer brands in cosmetics and skincare deploy automated replenishment to lock in repeat purchase behavior. Subscription bundling raises average order values while reducing churn through personalized curation algorithms.
- EU Digital Services Act compliance tooling:Platform providers invest in localized data governance modules to maintain market access across member states. This regulatory pressure creates vendor stickiness as merchants avoid migration costs.
- Cloud-native elastic scaling:Mid-market retailers adopt serverless architectures to handle promotional traffic surges without capital-intensive infrastructure. Pay-per-use models align platform costs with revenue volatility.
Market Restraints
- Payment processor concentration:Tokenized credential storage depends on a narrow tier of PCI DSS Level 1 certified gateways. Single-provider dependency creates operational fragility during outages.
- State-level automatic renewal law fragmentation:California, New York, and Illinois maintain divergent disclosure and cancellation requirements. Multi-jurisdiction compliance multiplies legal engineering overhead.
- Legacy ERP integration friction:Subscription state synchronization with on-premise inventory systems requires custom middleware development. Technical debt accumulates in hybrid cloud environments.
Strategic Opportunities
- Service subscription bundling:Physical goods merchants layer digital content, repair services, and advisory access onto core offerings. This margin expansion strategy differentiates against pure product competitors.
- FDA direct-to-consumer health guidelines:Compliant platforms capture emerging verticals in personalized nutrition and telehealth-adjacent products. Regulatory clarity enables category-specific feature development.
- Headless commerce API convergence:Developer-first architectures merge with subscription lifecycle management to enable custom storefront experiences. Technical buyers prioritize composable stack flexibility over monolithic suites.
Industry Challenges
- Dunning management engineering:Failed payment recovery requires sophisticated retry logic and customer communication orchestration. Talent scarcity in subscription-specific data science constrains optimization.
- Cross-border tax calculation complexity:Real-time VAT and sales tax determination across 190+ jurisdictions demands continuous regulatory monitoring. Platform providers absorb compliance maintenance as a cost of retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subscription E-Commerce Platform Market |
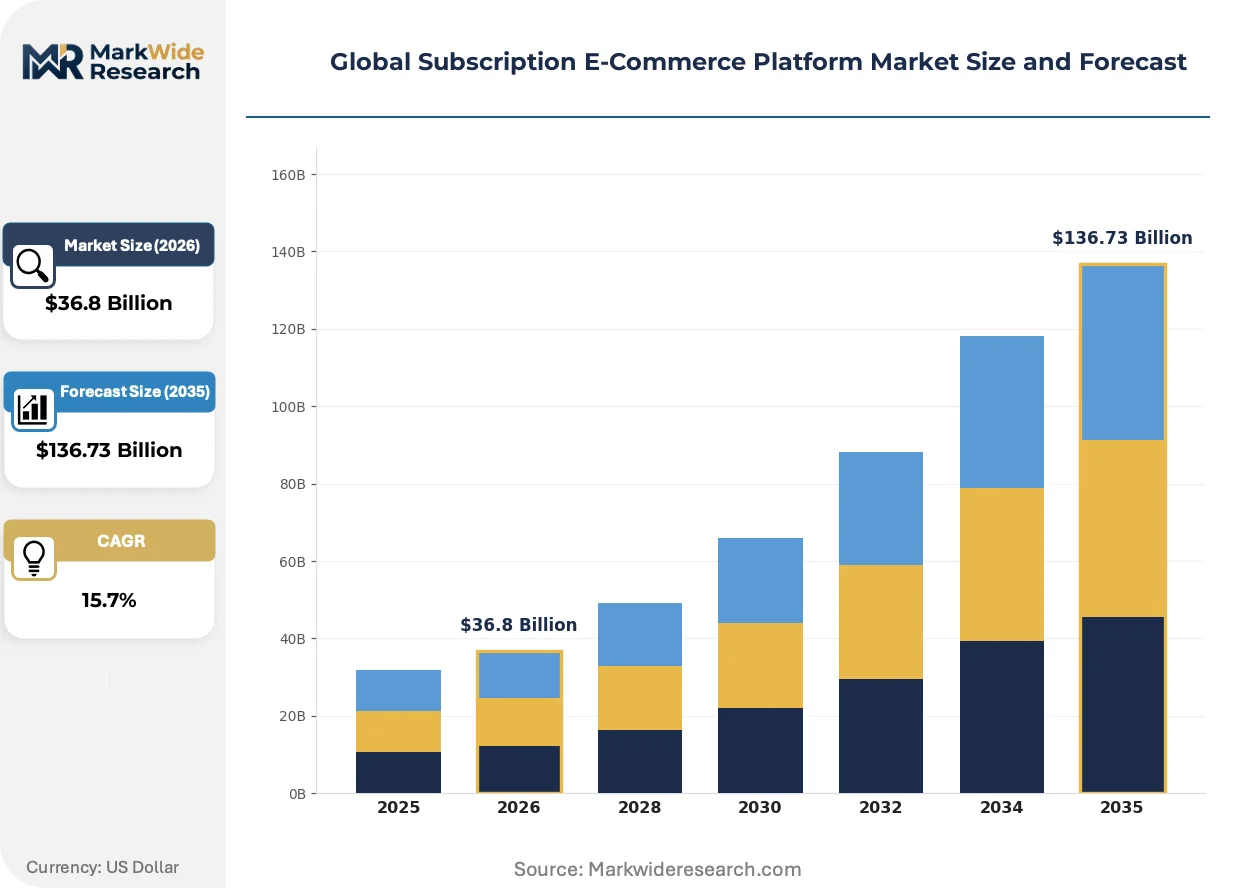
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $136.73 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Direct-to-Consumer, Whitelabel, Hybrid, Affiliate Deployment Type: Cloud-Based, On-Premise, Hybrid Cloud, SaaS End Use Industry: Consumer Electronics, Personal Care, Food & Beverage, Fashion & Apparel Subscription Offering: Product Subscription, Service Subscription, Content Subscription, Membership Subscription |
| Companies Covered | Shopify Inc., BigCommerce Holdings Inc., Adobe Inc., Chargebee Inc., Stripe Inc., Recurly Inc., Wix.com Inc., Amazon.com Inc., Automattic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subscription E-Commerce Platform Market Shifts & Advancements
Embedded finance capabilities are dissolving the boundary between payment infrastructure and merchant software. Platform differentiation now hinges on developer experience and compliance automation depth rather than feature breadth alone.
Headless subscription APIs are rewriting how merchants architect customer experiences. Direct-to-consumer brands in Germany and France adopt decoupled frontend frameworks to customize checkout flows while maintaining PCI-compliant tokenization. This architectural shift compresses time-to-market for differentiated subscription models.
EU AI Act algorithmic transparency mandates reshape recommendation engine deployment. Subscription platforms serving European consumers must document automated decision-making logic for personalized product curation. Beauty and personal care verticals face heightened scrutiny on claim substantiation when AI drives subscription box composition.
Buyer expectations for instant cancellation are forcing contract term redesign. United States consumers increasingly demand one-click pause and termination controls, displacing traditional annual-commitment models. Platform vendors embed friction-reduction tools to preempt regulatory intervention under emerging state consumer protection frameworks.
Global Subscription E-Commerce Platform Market Segmentation
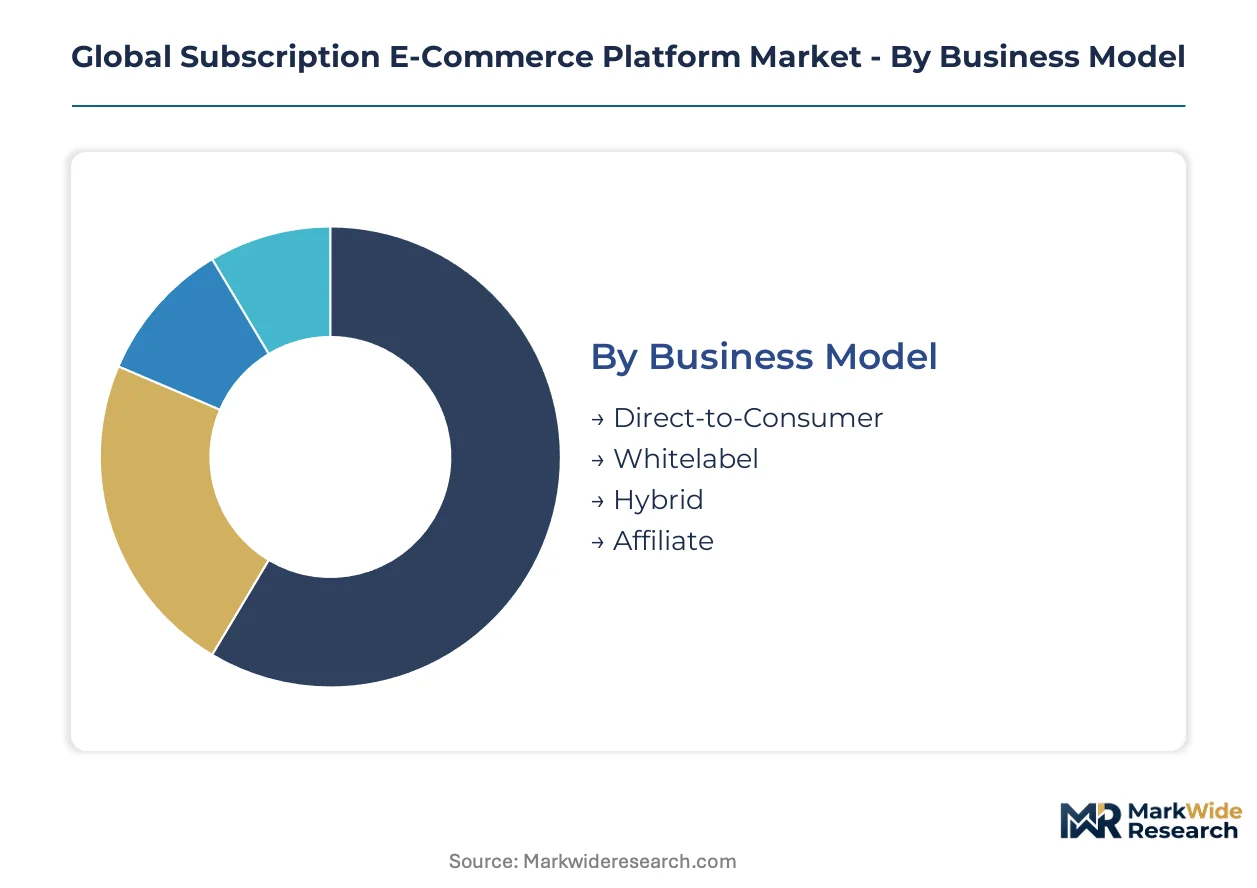
Platform buyers select subscription infrastructure based on technical architecture, commercial model flexibility, and vertical-specific compliance requirements. Segmentation reveals where merchant priorities diverge between developer control, regulatory coverage, and margin expansion potential.
Business Model:
Merchant scale and brand maturity determine whether in-house development or third-party orchestration delivers superior unit economics.
- Direct-to-Consumer:Merchants own the entire subscriber relationship, capturing first-party data and margin that would otherwise accrue to intermediaries. Beauty brands in the United States deploy proprietary subscription stacks to maximize customer lifetime value through personalized replenishment algorithms.
- Whitelabel:Retailers rebrand third-party platform infrastructure under their own identity, accelerating time-to-market without engineering investment. European grocers leverage whitelabel solutions to meet GDPR data residency mandates without building localized compliance modules from scratch.
- Hybrid:Combines owned storefront layers with outsourced payment tokenization and fulfillment orchestration. Mid-market merchants in Germany adopt hybrid architectures to balance customization needs against PCI DSS certification costs.
- Affiliate:Publishers and influencers monetize audiences through curated subscription referrals without inventory risk. Content creators in France bundle affiliate subscription links with algorithmic product recommendations subject to EU AI Act transparency requirements.
Volume sits with Direct-to-Consumer; growth tilts toward Hybrid as merchants seek architectural flexibility without full capital commitment.
Deployment Type:
Capital constraints and traffic volatility shape infrastructure decisions across merchant maturity tiers.
- Cloud-Based:Elastic compute resources scale automatically during promotional surges without upfront hardware investment. Personal care brands processing subscription spikes around seasonal beauty launches depend on cloud-native autoscaling to maintain checkout performance.
- On-Premise:Dedicated hardware installation satisfies data sovereignty requirements in regulated jurisdictions. Financial services adjacent subscription providers in Switzerland maintain on-premise deployments to satisfy Swissmedic and banking regulator audit protocols.
- Hybrid Cloud:Sensitive subscriber data remains on-premise while compute-intensive operations burst to public cloud. Japanese merchants under METI cybersecurity guidelines partition payment credentials locally while scaling recommendation engines externally.
- SaaS:Fully managed software delivery eliminates infrastructure administration entirely. Small merchants across India adopt SaaS subscription platforms to bypass BIS certification complexity for self-hosted payment systems.
Revenue concentrates in Cloud-Based; steepest expansion trajectory belongs to SaaS as vendor-managed compliance reduces merchant legal engineering.
End Use Industry:
Vertical-specific replenishment patterns and regulatory exposure differentiate platform feature requirements.
- Consumer Electronics:Warranty bundling and trade-in programs integrate with subscription billing cycles. Electronics retailers in South Korea under MFDS guidelines structure device-as-a-service offerings with embedded repair and recycling compliance.
- Personal Care:Automated replenishment algorithms predict consumption rates from purchase history and seasonal patterns. Skincare brands in California navigate state automatic renewal disclosure laws while optimizing subscription box curation.
- Food & Beverage:Perishable inventory synchronization demands real-time subscription state integration with cold chain logistics. Meal kit providers in Brazil align ANVISA food safety tracking with subscriber preference profiles.
- Fashion & Apparel:Size rotation and rental-return workflows require specialized reverse logistics orchestration. Circular fashion platforms in the United Kingdom embed carbon accounting into subscription billing under CSRD reporting obligations.
Transaction volume clusters in Personal Care; Fashion & Apparel claims the fastest share gain as circular economy regulation accelerates rental model adoption.
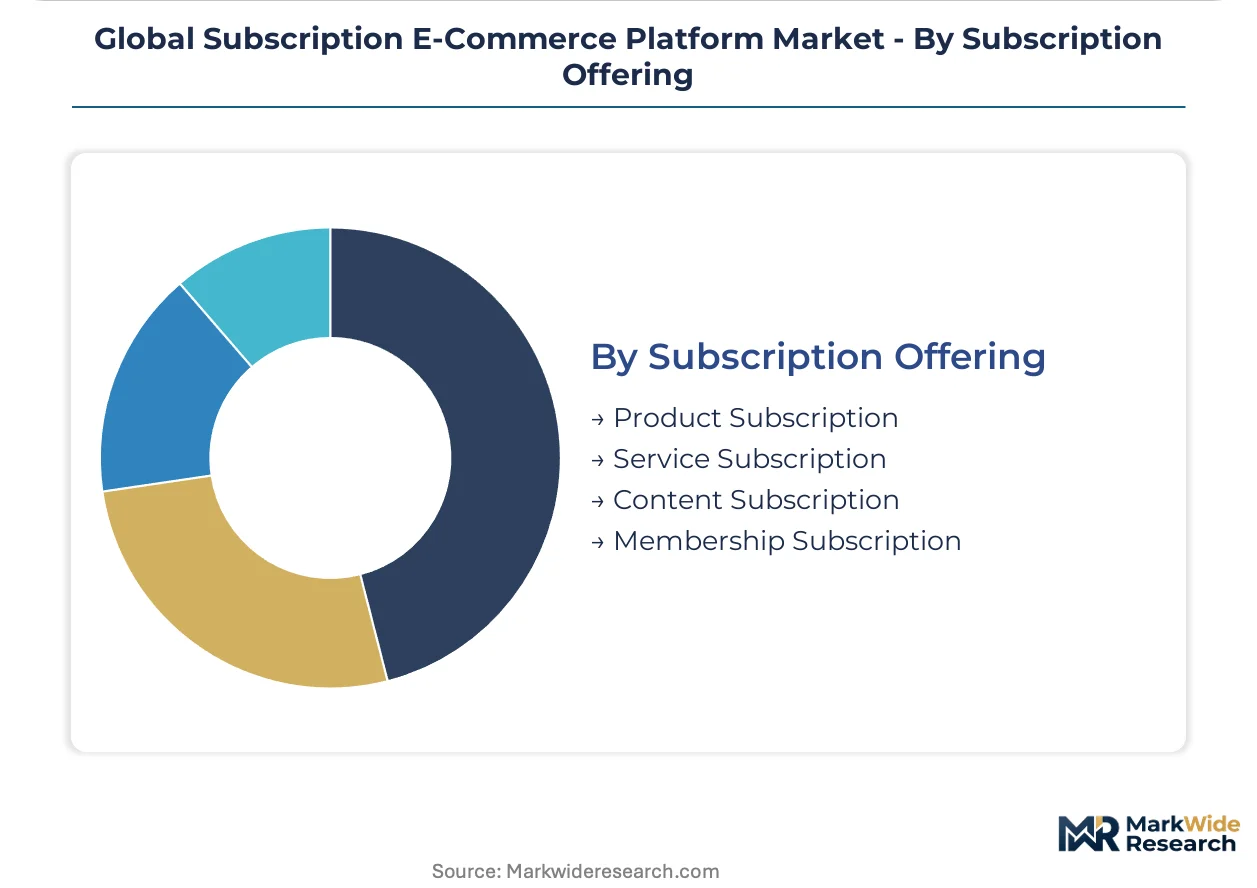
Subscription Offering:
Margin structure and churn dynamics vary dramatically between physical goods, intangible services, and access-based membership tiers.
- Product Subscription:Physical goods delivered on recurring schedules with inventory-backed fulfillment constraints. German automotive parts distributors leverage product subscriptions to lock in aftermarket demand while managing KBA compliance documentation.
- Service Subscription:Repair, advisory, and maintenance services bundled alongside or independent of product sales. Telehealth-adjacent platforms in the United States align FDA direct-to-consumer health guidelines with recurring consultation billing.
- Content Subscription:Digital media, educational material, and software access delivered without logistics overhead. French publishers structure content subscriptions to satisfy CNIL algorithmic transparency mandates for personalized recommendation engines.
- Membership Subscription:Access privileges and community features layered atop core product or service relationships. Premium retailers in the UAE deploy membership tiers to differentiate MOHAP-regulated health product access from standard consumer channels.
Merchant count peaks with Product Subscription; margin expansion concentrates in Service Subscription as brands seek recurring revenue beyond physical goods commoditization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dubai Internet City concentrate subscription platform development through tax-advantaged R&D facilities. These zones attract merchant onboarding infrastructure and compliance engineering talent pools.
United States
Direct-to-consumer beauty brands in Los Angeles and New York deploy automated replenishment algorithms to maximize customer lifetime value. California's automatic renewal disclosure laws impose strict cancellation workflow requirements on platform architecture. The San Francisco Bay Area anchors developer-first API innovation for headless commerce stacks.
Germany
GDPR data residency mandates drive merchant demand for localized hosting and tokenized payment storage. The KBA regulates automotive aftermarket subscription parts distribution with compliance documentation requirements. Berlin hosts emerging SaaS subscription infrastructure providers serving DACH-region merchants.
China
Cross-border e-commerce zones in Hangzhou and Shanghai enable foreign brand subscription entry through bonded warehouse integration. MIIT cybersecurity guidelines shape cloud deployment architectures for consumer data handling. The Yangtze River Delta concentrates platform engineering talent for elastic scaling infrastructure.
United Kingdom
Fashion rental platforms in London embed carbon accounting into subscription billing under CSRD reporting obligations. The FCA monitors embedded finance integrations between subscription platforms and lending products. Manchester hosts mid-market merchant operations seeking hybrid cloud deployment flexibility.
India
SaaS subscription platforms in Bangalore and Hyderabad bypass BIS certification complexity for small merchants through fully managed infrastructure. RBI payment aggregator guidelines structure recurring billing authorization workflows. The Delhi-NCR corridor concentrates enterprise procurement decisions for cloud-native subscription stacks.
Global Subscription E-Commerce Platform Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the subscription e-commerce platform landscape. The vendor base organizes into three tiers: full-stack commerce suites, payment-centric billing engines, and vertical-specific subscription tools. Strategic archetypes include developer-first API providers, merchant-facing SaaS operators, and infrastructure-anchored logistics integrators. Competitive moves concentrate on headless architecture partnerships and embedded finance capability expansion.
Within the infrastructure-anchored tier, Amazon.com Inc. and Shopify Inc. exemplify divergent approaches to subscription merchant capture. Stripe Inc. occupies a position bridging payment tokenization with developer tooling for custom subscription implementations. These three entities represent the dominant competitive vectors shaping platform differentiation through compliance automation depth and API flexibility rather than feature breadth alone.
| Leading Market Players |
|---|
| Shopify Inc. |
| BigCommerce Holdings Inc. |
| Adobe Inc. |
| Chargebee Inc. |
| Stripe Inc. |
| Recurly Inc. |
| Wix.com Inc. |
| Amazon.com Inc. |
| Automattic Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices cascade through subscription platform economics, compressing margins for SaaS-tiered providers while amplifying pricing power for vendors with captive data center capacity in Germany and India. PCI DSS certification costs concentrate in payment tokenization layers, forcing tiered pricing stratification across compliant and non-compliant merchant segments.
Pricing Analysis
Short lead-time provisioning commands premium pricing in cloud-native deployment tiers, while annual contract commitments unlock standard-rate access to elastic compute pools. Three-tier pricing structure across premium, standard, and economy levels differentiates by GDPR data residency certification, API call volume thresholds, and embedded finance integration depth. Cost compression in economy tiers intensifies because hyperscaler commoditization of container orchestration erodes vendor differentiation. Mid-market merchants in the United States exhibit highest price sensitivity, while enterprise procurement teams in Switzerland prioritize compliance certification over unit cost.
Supply Chain Analysis
Platform engineering talent scarcity in Bangalore, Berlin, and Shenzhen constrains delivery velocity for custom subscription implementations. Cloud infrastructure draws from Taiwan semiconductor foundries, Irish data center fiber networks, and Singapore subsea cable landing stations. Single-source vulnerability concentrates in PCI DSS Level 1 certified payment gateways, where tokenization service outages cascade across merchant billing operations. Distribution runs through API-first developer marketplaces and direct enterprise sales channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where GDPR data residency mandates erect barrier-to-entry moats favoring vendors with pre-built localized governance modules.
For Market Incumbents: Acquire specialized dunning management engineering teams to fortify failed-payment recovery capabilities against Stripe's developer-first API expansion. Consolidate hybrid cloud deployment expertise through targeted hiring in Manchester and Tokyo, where METI cybersecurity guidelines create talent scarcity. Channel control over embedded finance partnerships with RBI-licensed payment aggregators in India anchors retention in high-growth merchant segments. For New Entrants and Emerging Players: Begin with whitelabel subscription infrastructure serving European grocers navigating GDPR compliance without engineering investment, the most penetrable white-space in current competitive coverage. Target affiliate subscription monetization for French content creators subject to CNIL algorithmic transparency mandates, where incumbent platform coverage remains thin. A developer relations-led go-to-market angle captures headless commerce API demand from direct-to-consumer beauty brands in Los Angeles. For Investors and Strategic Acquirers: The window for entry favors vertical-specific subscription tools with pre-built FDA compliance pathways for telehealth-adjacent merchants. Long-term viability rests on category-specific feature depth rather than horizontal platform breadth, as regulatory fragmentation favors specialized vendors. ISO 27001 certification velocity serves as the critical signal to watch for platform readiness in enterprise procurement pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR Compliance Module Development | Localized data governance in Germany satisfies BfDI audit requirements and locks in EU merchant retention. |
| Headless API Platform Launch | Decoupled frontend architectures enable California beauty brands to customize checkout while maintaining PCI tokenization. |
| Embedded Finance Partnership | Integration with FCA-regulated lending products in the United Kingdom expands revenue per merchant beyond SaaS fees. |
| Vertical Acquisition in Personal Care | Consumption-rate prediction algorithms from skincare specialists accelerate time-to-value for replenishment automation. |
| Hybrid Cloud Capacity Expansion | Tokyo data center investment satisfies METI cybersecurity guidelines for Japanese financial services adjacent subscriptions. |
Research Methodology
Document review covered SEC filings from Shopify and Stripe, EU Digital Services Act implementation guidance, and PCI DSS certification databases, complemented by interviews with platform engineering directors, merchant payment operations leads, and regulatory compliance officers at cloud infrastructure providers. Bottom-up merchant count estimates triangulated against top-down addressable market calculations from hyperscaler capex disclosures and BIS certification records in India.
Cross-referencing historical adoption curves against panel input from subscription billing specialists shaped the analytical framework across deployment model, merchant size tier, and vertical regulatory complexity. CAGRs derived from segment-level growth rate convergence across the projection horizon, with cloud-native elastic scaling demand and state-level automatic renewal law proliferation serving as primary forecast inputs.
Underlying measurement precision varies by segment; Cloud-Based and SaaS deployment types carry tighter precision than On-Premise due to vendor disclosure practices. Forecasts reflect assumptions around GDPR enforcement intensity and PCI DSS certification timeline stability. Material deviation in FDA direct-to-consumer health guideline finalization or EU AI Act algorithmic transparency implementation schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Global Live E-Commerce Market