
 Europe Dropshipping Market | 2026-2036
Europe Dropshipping Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dropshipping Market Insights
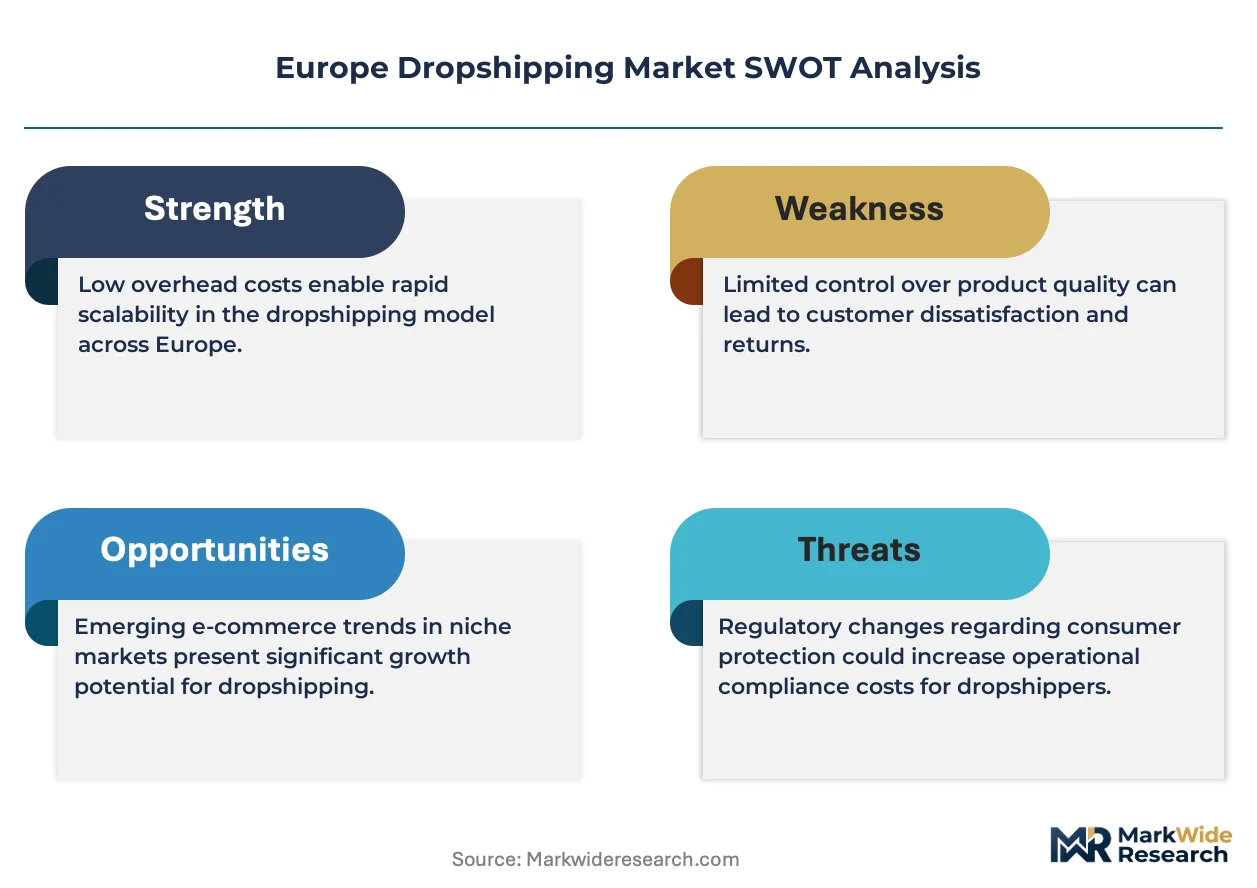
Freight logistics expertise is unwinding as a bottleneck across the Europe dropshipping landscape, with specialized warehousing talent shortages in the Netherlands and Poland delaying same-day fulfillment promises. BigBuy leverages its Barcelona-based European distribution network to sustain rapid cross-border delivery. BrandsGateway anchors luxury fashion dropshipping through direct supplier relationships with Italian manufacturers. Syncee competes by aggregating vetted European suppliers into a unified catalog platform.
Europe dropshipping denotes a retail fulfillment method where sellers accept customer orders without holding inventory, instead routing purchases directly from third-party suppliers to end buyers, typically requiring integrated order-management software and real-time stock synchronization. The primary commercial purpose centers on minimizing capital lock-up in inventory while enabling rapid assortment scaling across digital storefronts. Apparel dominates product type segmentation due to high-margin potential and repeat purchase frequency, though electronics gains traction as supplier quality certification standards mature. Direct shipping remains the prevailing fulfillment method for cost-sensitive retail consumers, while third-party logistics expands among large enterprises seeking branded packaging control.
GDPR compliance obligations enforced by national data protection authorities reshape how dropshipping platforms handle cross-border customer data flows, particularly for social media-originated sales. The EU's Digital Services Act and national consumer protection frameworks in France and Germany impose escalating transparency requirements on marketplace operators regarding seller identity and product provenance. REACH chemical safety standards affect beauty products and electronics sourcing decisions, filtering non-compliant Asian suppliers from European-bound catalogs. Stakeholders must weigh the trade-off between supplier geographic diversification and regulatory compliance centralization as enforcement harmonization proceeds unevenly across member states.
Market Dynamics
The EU's Digital Services Act is compressing platform liability timelines, forcing dropshipping operators to pre-verify supplier identities and product provenance before listing rather than relying on post-hoc takedown mechanisms. This regulatory compression is restructuring how inventory-light retailers select cross-border partners and manage compliance documentation.
Growth Catalysts
- GDPR-mandated data localization:Dropshipping platforms investing in EU-based server infrastructure capture merchant trust through demonstrable compliance with national data protection authorities.
- SME digitalization in Germany:Mid-sized retailers adopting integrated order-management software expand dropship catalog breadth without warehousing capital deployment.
- REACH chemical safety standards:Beauty and electronics suppliers achieving EU certification gain preferential placement in platform catalogs, filtering non-compliant competitors.
Market Restraints
- Specialized warehousing talent shortages:Netherlands and Poland face acute deficits in same-day fulfillment operations, delaying delivery promises and inflating labor costs.
- Cross-border VAT complexity:Divergent national implementation of EU e-commerce VAT rules creates accounting friction for multi-territory sellers.
- Platform liability concentration:The Digital Services Act shifts legal exposure to marketplace operators, raising insurance and legal review costs for catalog aggregators.
Strategic Opportunities
- Italian luxury manufacturing direct access:Dropshipping platforms establishing direct supplier relationships with Milan and Florence apparel producers bypass wholesale margin stacking.
- CSRD sustainability reporting:Early compliance with corporate sustainability disclosure requirements attracts ESG-focused institutional merchant capital.
- AI-powered demand forecasting:Machine learning integration with real-time inventory APIs reduces stockout penalties and improves supplier allocation efficiency.
Industry Challenges
- Real-time synchronization engineering:Legacy ERP systems at established retailers resist API integration with dropship supplier networks, requiring middleware development.
- CE marking documentation verification:Electronics sellers face supplier audit burdens to confirm conformity assessment validity before platform listing approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dropshipping Market |
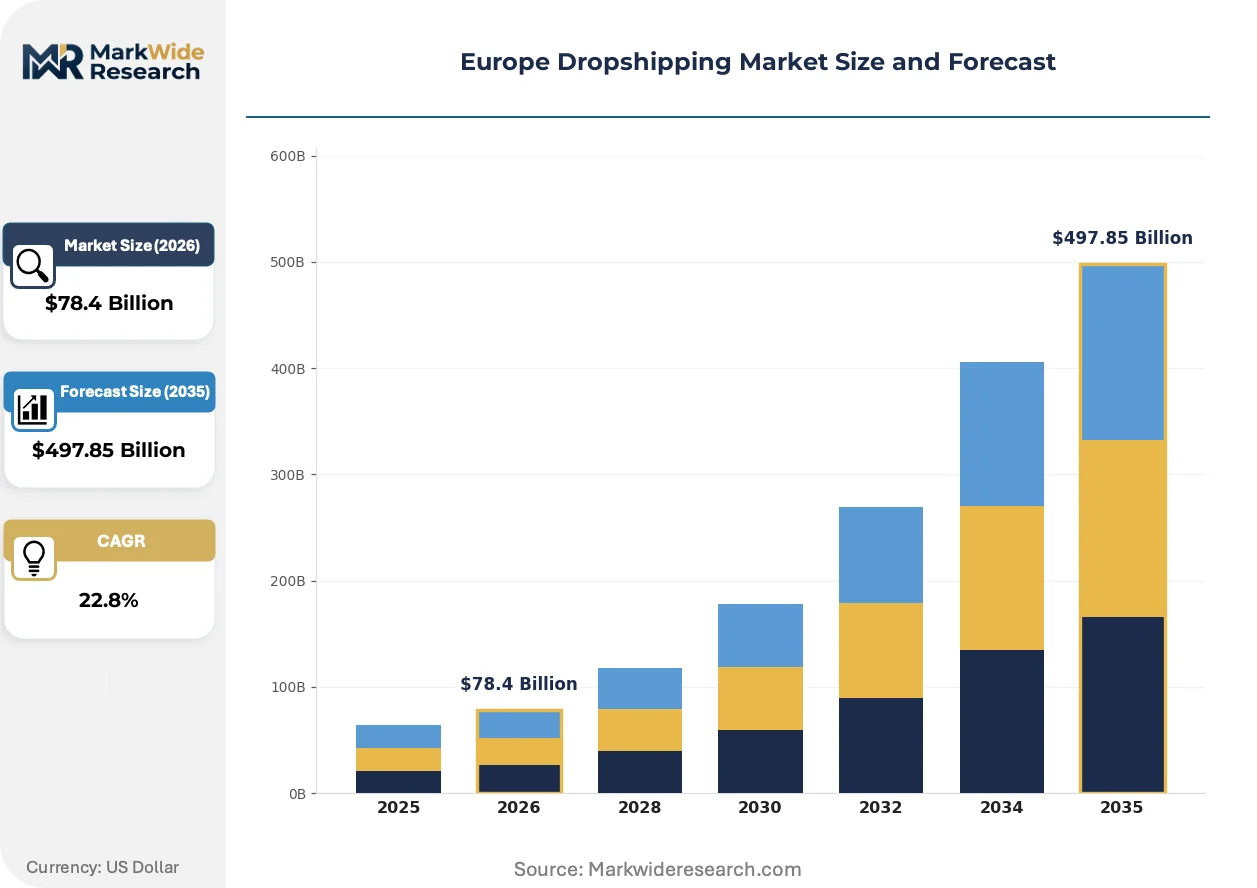
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $497.85 Billion |
| CAGR (2026 – 2036) | 22.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Beauty Products Sales Channel: Online Marketplace, E-commerce Website, Social Media, Mobile App Customer Type: Retail Consumers, Small Businesses, Wholesalers, Large Enterprises Fulfillment Method: Direct Shipping, Third-party Logistics, Print-on-Demand, Subscription Service |
| Companies Covered | BigBuy, Spocket, CJdropshipping, BrandsGateway, Syncee, Zentrada, Megagoods, dropXL, Orderchamp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dropshipping Market Trends and Innovations
Platform architecture is fragmenting from monolithic suites toward modular API ecosystems, enabling retailers to compose specialized fulfillment stacks without vendor lock-in. This composability is accelerating experimentation with hybrid inventory models.
Headless commerce infrastructure is decomposing the traditional storefront-fulfillment bond, allowing German fashion retailers to maintain branded customer experiences while routing orders to Barcelona-based distribution networks. Mid-market sellers are adopting this architecture fastest, compressing time-to-market for cross-border assortment expansion from quarters to weeks.
REACH enforcement harmonization is proceeding unevenly across member states, with ECHA coordinating national competent authorities while France and Germany maintain stricter substance notification timelines. Beauty dropshippers are consolidating supplier bases to jurisdictions with established compliance documentation, reducing catalog diversity but lowering regulatory seizure risk.
Social commerce origination is displacing search-driven discovery, with Instagram and TikTok storefronts capturing merchant attention and redirecting fulfillment expectations toward impulse-delivery speed. French and Spanish consumers exhibit highest conversion rates from platform-native checkout, pressuring dropshipping operators to compress supplier-to-door timelines below 72 hours.
Europe Dropshipping Market Segmentation
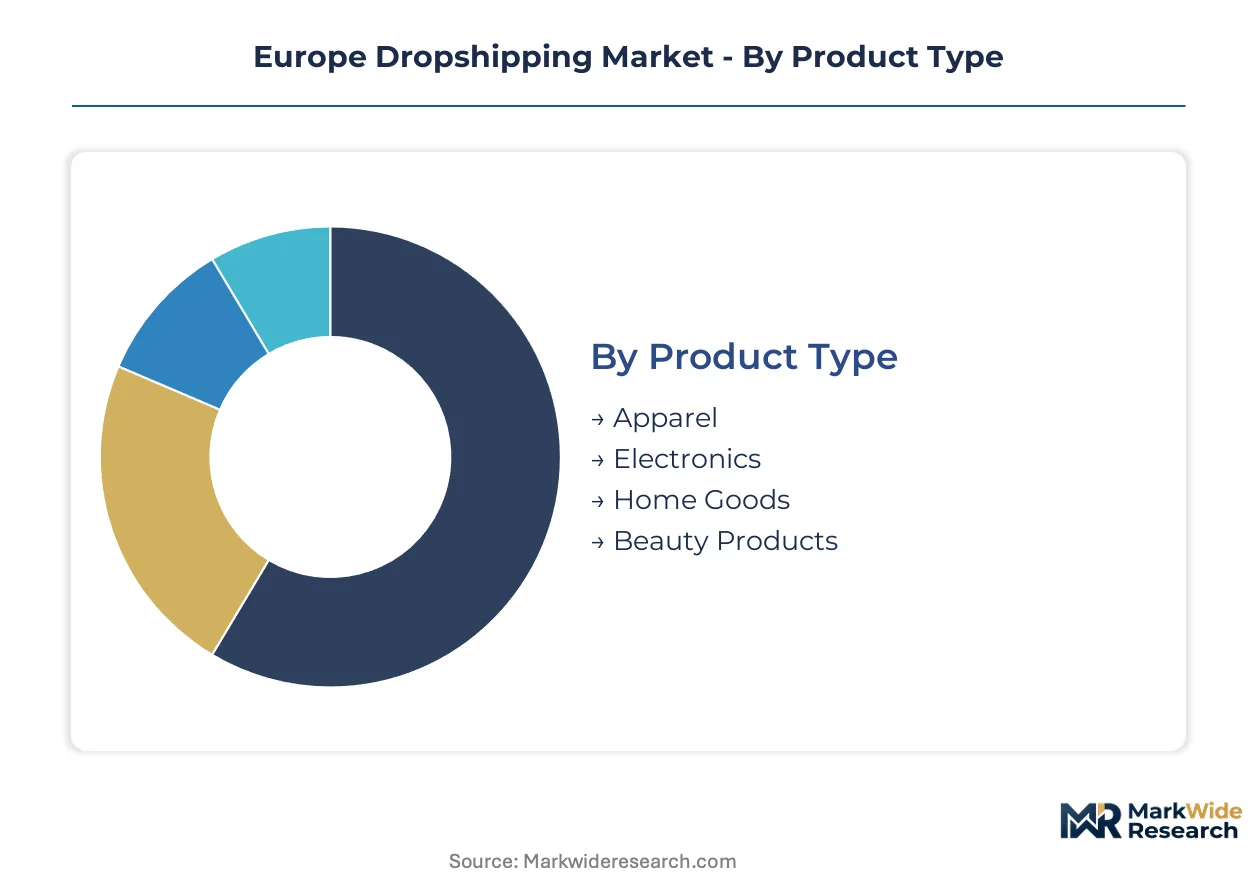
Segmentation in the Europe dropshipping market reveals distinct operational profiles across product categories and fulfillment methods. German SME digitalization and French social commerce adoption concentrate demand in specific channel-customer combinations. Regulatory compliance requirements fragment supplier eligibility differently across each segment boundary.
Product Type:
Domestic European manufacturing anchors apparel and beauty sourcing, while electronics and home goods lean heavily on Asian supplier networks with REACH and CE marking documentation hurdles.
- Apparel:High-margin fashion items with rapid style turnover dominate platform catalog prioritization. German and French retailers drive demand through integrated order-management systems that synchronize with Italian and Spanish supplier networks. GDPR-compliant data flows enable personalized sizing recommendations that reduce return rates.
- Electronics:CE marking conformity assessment requirements filter supplier pools aggressively. Demand concentrates in Germany and the Netherlands where tech-savvy consumers prioritize certified safety documentation over price minimization. ECHA coordination of national competent authorities creates uneven enforcement exposure across member states.
- Home Goods:Bulky items with higher shipping cost sensitivity. Nordic markets favor sustainable material certifications.
- Beauty Products:REACH substance notification timelines restrict formulation flexibility. French ANSM maintains stricter documentation requirements than southern European regulators.
Apparel holds the largest share; momentum sits with electronics as certification standardization matures.
Sales Channel:
Cost tier differentiation separates high-touch owned platforms from commission-based marketplace dependency, with social commerce commanding premium fulfillment speed investments.
- Online Marketplace:Aggregator platforms bearing Digital Services Act liability exposure. German and French implementation of seller verification requirements raises operational overhead.
- E-commerce Website:Branded storefronts with direct customer data ownership. Mid-market retailers in Spain and Italy adopt headless commerce architecture fastest.
- Social Media:Instagram and TikTok storefronts with impulse-purchase psychology driving sub-72-hour delivery expectations. French and Spanish consumers exhibit highest conversion rates from platform-native checkout.
- Mobile App:Push-notification engagement with location-based fulfillment optimization. Nordic markets lead in-app purchase frequency.
Online marketplace volume dominates current transaction value; social media is expanding most quickly among merchant acquisition channels.
Customer Type:
Volume scale and margin structure diverge sharply between individual retail consumers and institutional procurement patterns.
- Retail Consumers:Price-sensitive individual purchasers with high return rate tolerance. German consumers demand fastest delivery speeds.
- Small Businesses:B2B procurement with recurring order patterns and negotiated payment terms. Benelux markets concentrate this segment.
- Wholesalers:Bulk aggregation with private label customization requirements. Italian manufacturing relationships anchor supplier selection.
- Large Enterprises:Branded packaging control and API-driven ERP integration. Third-party logistics partnerships predominate.
Retail consumers generate highest transaction frequency; large enterprises deliver steepest expansion trajectory for platform revenue per merchant.
Fulfillment Method:
Supply concentration in specialized warehousing clusters determines viable service level commitments.
- Direct Shipping:Supplier-to-consumer routing without intermediary handling. Cost-sensitive retail consumers in southern Europe accept longer timelines.
- Third-party Logistics:Branded packaging and quality control insertion. Netherlands and Poland talent shortages constrain same-day promise scalability.
- Print-on-Demand:Zero inventory risk with localized production. Barcelona and Milan hubs serve cross-border demand.
- Subscription Service:Predictable replenishment with locked-in supplier allocation. Beauty and apparel verticals adopt this fastest.
Direct shipping maintains widest merchant adoption; third-party logistics is gaining share fastest among enterprise segment migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Cartel Office and national data protection authorities anchor the regulatory environment shaping cross-border e-commerce compliance across the continent's largest economy.
Germany
SME digitalization accelerates fastest among EU member states, with mid-sized retailers adopting integrated order-management software to expand catalog breadth without warehousing capital. The country's implementation of the Digital Services Act imposes strict seller verification timelines on marketplace operators. Berlin and Hamburg concentrate third-party logistics partnerships serving enterprise clients seeking branded packaging control.
France
Social commerce adoption drives highest conversion rates from Instagram and TikTok storefronts, pressuring fulfillment speed expectations below 72 hours. ANSM maintains stricter REACH documentation requirements for beauty products than southern European regulators. Paris anchors luxury fashion dropshipping networks with direct supplier relationships to Italian manufacturers.
Netherlands
Specialized warehousing talent shortages delay same-day fulfillment promises and inflate labor costs for logistics operators. ECHA coordination of national competent authorities creates compliance documentation advantages for REACH-certified suppliers. Rotterdam and Amsterdam clusters serve as primary distribution hubs for cross-border Benelux fulfillment.
Spain
Barcelona-based European distribution networks sustain rapid cross-border delivery timelines to southern European markets. Mid-market retailers adopt headless commerce architecture fastest, compressing time-to-market for assortment expansion. Madrid concentrates social commerce merchant acquisition with platform-native checkout optimization.
Italy
Direct supplier relationships with Milan and Florence apparel producers bypass wholesale margin stacking for luxury fashion dropshipping. CE marking conformity assessment requirements filter electronics supplier pools aggressively. Northern manufacturing clusters anchor print-on-demand production serving cross-border demand.
Poland
Acute deficits in same-day fulfillment operations constrain scalability of rapid delivery promises to central European markets. National implementation of EU e-commerce VAT rules creates accounting friction for multi-territory sellers. Warsaw and Krakow logistics hubs face talent competition from Western European markets.
Europe Dropshipping Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe dropshipping landscape. The vendor base concentrates around catalog aggregators, distribution network operators, and supplier relationship specialists rather than fragmented single-service providers. Three strategic archetypes dominate: platform-based catalog aggregators with vetted supplier networks, vertically integrated distributors with owned warehousing infrastructure, and niche specialists targeting luxury or vertical product categories. Competitive moves center on strategic partnerships with manufacturers and geographic expansion of fulfillment footprints.
Within the distribution network tier, BigBuy leverages its Barcelona-based European infrastructure to sustain rapid cross-border delivery timelines. BrandsGateway anchors luxury fashion dropshipping through direct supplier relationships with Italian manufacturers. Syncee competes by aggregating vetted European suppliers into a unified catalog platform accessible to mid-market retailers.
| Leading Market Players |
|---|
| BigBuy |
| Spocket |
| CJdropshipping |
| BrandsGateway |
| Syncee |
| Zentrada |
| Megagoods |
| dropXL |
| Orderchamp |
| Others |
Pricing and Supply Chain Analysis
Barcelona-based distribution capacity utilization above 85 percent compresses cross-border delivery cost floors while concentrating supplier pricing power among Spanish and Italian network operators. This scale dynamic shapes margin structures across the continent, with smaller German and French retailers facing asymmetric negotiation leverage against consolidated southern European fulfillment clusters.
Pricing Analysis
Geographic price spreads between German same-day delivery premiums and southern European standard shipping rates reach 40-60 percent differentials. Three-tier pricing structure across premium, standard, and economy levels separates enterprise clients with branded packaging requirements from cost-sensitive retail consumers. Pricing pressure stems from specialized warehousing talent shortages in the Netherlands and Poland inflating labor costs. Retail consumers exhibit highest price sensitivity, while large enterprises prioritize API integration and compliance documentation over unit cost minimization.
Supply Chain Analysis
Inventory-light strategies dominate apparel and beauty verticals, while electronics sellers maintain strategic safety stock to buffer CE marking documentation delays. Supply concentrates in Spain, Italy, and Poland for European-sourced goods, with Asian networks feeding electronics and home goods segments. Raw material dependencies include REACH-compliant chemical formulations, Italian luxury textiles, and electronics components requiring conformity assessment. Single-source vulnerability runs through Barcelona-based distribution networks serving cross-border demand. Distribution runs through third-party logistics partnerships for enterprise clients and direct supplier routing for cost-optimized retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of specialized warehousing talent in Benelux and central European markets creates a capability bottleneck that reshapes competitive returns. Platforms that solve this talent scarcity through automation partnerships or geographic arbitrage capture disproportionate merchant retention.
For Market Incumbents: Shield catalog breadth advantages by deepening direct supplier relationships with Milan and Florence apparel manufacturers before wholesale margin compression accelerates. Invest in GDPR-compliant EU server infrastructure to defend against emerging platform competitors leveraging compliance as a trust signal. Prioritize automation deployment in Barcelona and Rotterdam distribution nodes to offset warehousing labor cost inflation.
For New Entrants and Emerging Players: REACH certification fast-track programs for beauty and electronics suppliers unlock preferential catalog placement as ECHA coordination tightens enforcement harmonization. White-space opportunities concentrate in B2B small business procurement across Benelux markets, where recurring order patterns and negotiated terms remain underpenetrated by incumbent aggregators. Go-to-market positioning should emphasize AI-powered demand forecasting integration with real-time inventory APIs to differentiate from legacy platform architectures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated distributors with owned warehousing infrastructure over pure-play catalog aggregators facing Digital Services Act liability concentration. Long-term viability across the projection horizon rests on platforms combining headless commerce architecture with direct Italian manufacturing relationships. Acquisition target archetypes include niche specialists in luxury fashion dropshipping and AI-native demand forecasting providers. The signal to watch is cross-border VAT rule harmonization progress, which would compress accounting friction costs and revalue multi-territory platform assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Supplier Relationship Expansion | Bypasses wholesale margin stacking with Milan and Florence manufacturers. |
| AI-Powered Demand Forecasting Integration | Reduces stockout penalties through machine learning inventory allocation. |
| Headless Commerce Architecture Adoption | Enables German retailers to route orders through Barcelona networks. |
| GDPR-Compliant EU Server Infrastructure | Captures merchant trust through demonstrable data protection compliance. |
| REACH Certification Fast-Track Programs | Secures preferential catalog placement as ECHA enforcement harmonizes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, customs trade data, platform operator disclosures, and national data protection authority guidance. Interviews with dropshipping platform executives, third-party logistics operators, Italian apparel manufacturers, and German mid-market retailers informed operational assumptions. Secondary validation drew from Digital Services Act implementation documents, ECHA REACH substance databases, and Benelux logistics employment statistics. Bottom-up merchant adoption modeling triangulated against top-down e-commerce market sizing.
Segmentation dimensions modeled include product category, sales channel, customer type, and fulfillment method across the analysis window. The analytical framework incorporated SME digitalization rates, social commerce conversion benchmarks, and cross-border delivery speed elasticity. CAGRs derived from logistic curve adoption modeling and regulatory compliance cost trajectory assumptions. Industry-specific forecast inputs captured Digital Services Act liability cost pass-through and warehousing talent supply constraints.
Underlying assumptions cover regulatory enforcement harmonization pace and automation adoption timelines, with deviation risk concentrated in VAT rule implementation variance and REACH substance notification delays. Revision becomes warranted when cross-border fulfillment cost inflation crosses thresholds that trigger merchant platform switching.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market