
 E-Commerce Ecosystem Market | 2026-2036
E-Commerce Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Ecosystem Market Foresight
SME merchants is reorganizing demand flows across the E-Commerce Ecosystem Market as enterprise-grade tools democratize at lower price points. Amazon leverages fulfillment density to sustain same-day delivery promises across North American urban corridors. JD.com anchors supply chain control through captive warehouse robotics and in-house last-mile fleets. Alibaba Group dominates cross-border trade infrastructure with AliExpress and Tmall Global platforms serving non-Chinese consumers.
The E-Commerce Ecosystem encompasses the integrated digital infrastructure enabling online commercial transactions, spanning payment gateways, inventory systems, customer relationship management software, and logistics orchestration layers that process order-to-delivery cycles in under 72 hours for standard fulfillment. Its primary commercial purpose is reducing friction between product discovery and final receipt while generating actionable behavioral data for sellers. Platform Type segments reveal structural divergence: online marketplaces capture the highest transaction volume globally, yet self-hosted stores extract superior per-unit margins through direct customer ownership and reduced commission structures. Customer Type dynamics show B2B procurement portals expanding faster than B2C channels as industrial buyers migrate purchase orders to digital workflows.
FDA oversight of health product claims on platforms, EU GDPR constraints on cross-border consumer data transfers, and China's SAMR antitrust enforcement against dominant platforms collectively elevate compliance costs while creating barriers for new entrants lacking legal infrastructure. The EU AI Act adds algorithmic transparency mandates for recommendation engines that shape product visibility and pricing. Stakeholders must monitor regulatory fragmentation between data localization requirements and open digital commerce principles when allocating platform development resources.
Market Dynamics
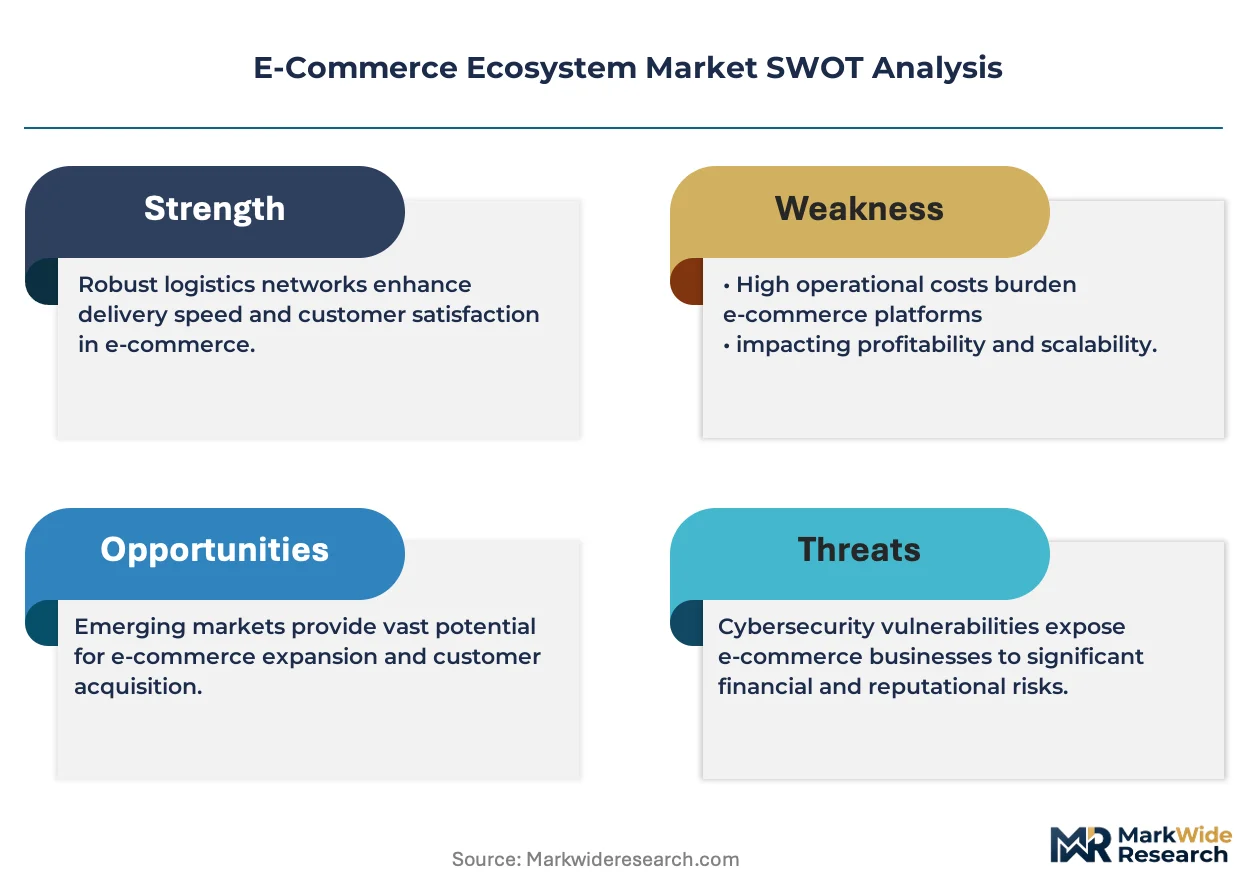
Platform consolidation around fulfillment infrastructure is compressing merchant margins while elevating consumer delivery expectations. Captive logistics networks now determine competitive viability more than storefront technology.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for recommendation engines are forcing platform operators to document product-ranking logic, creating audit-ready infrastructure that attracts risk-averse enterprise merchants.
- SME digital adoption:Cloud-native inventory and payment tools at sub-enterprise price points are enabling smaller merchants to operate multi-channel storefronts without dedicated technical staff.
- Mobile-first penetration:Indonesia, Vietnam, and the Philippines exhibit deepening smartphone commerce habits that bypass desktop-era infrastructure entirely.
Market Restraints
- GDPR cross-border data friction:EU consumer data localization requirements impose architectural costs on platforms serving transnational merchant bases.
- Last-mile labor concentration:Dense urban delivery networks depend on gig-economy workforce pools concentrated in specific metropolitan corridors.
- SAMR antitrust enforcement:China's State Administration for Market Regulation imposes structural penalties on dominant platform operators that constrain pricing autonomy.
Strategic Opportunities
- Philippines archipelago logistics:Maritime fulfillment infrastructure remains underdeveloped relative to demand density, creating first-mover advantages for integrated supply chain investors.
- ISO 27001 certification convergence:Information security standards are becoming table stakes for B2B procurement portals serving industrial buyers.
- Live-stream commerce integration:Real-time video selling formats are merging with traditional checkout flows in Southeast Asian markets.
Industry Challenges
- Legacy ERP integration:Merchant migration from on-premise inventory systems to API-native platforms requires custom middleware development.
- FDA health claim verification:Supplement and medical device sellers face extended review timelines for platform-compliant product listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Ecosystem Market |
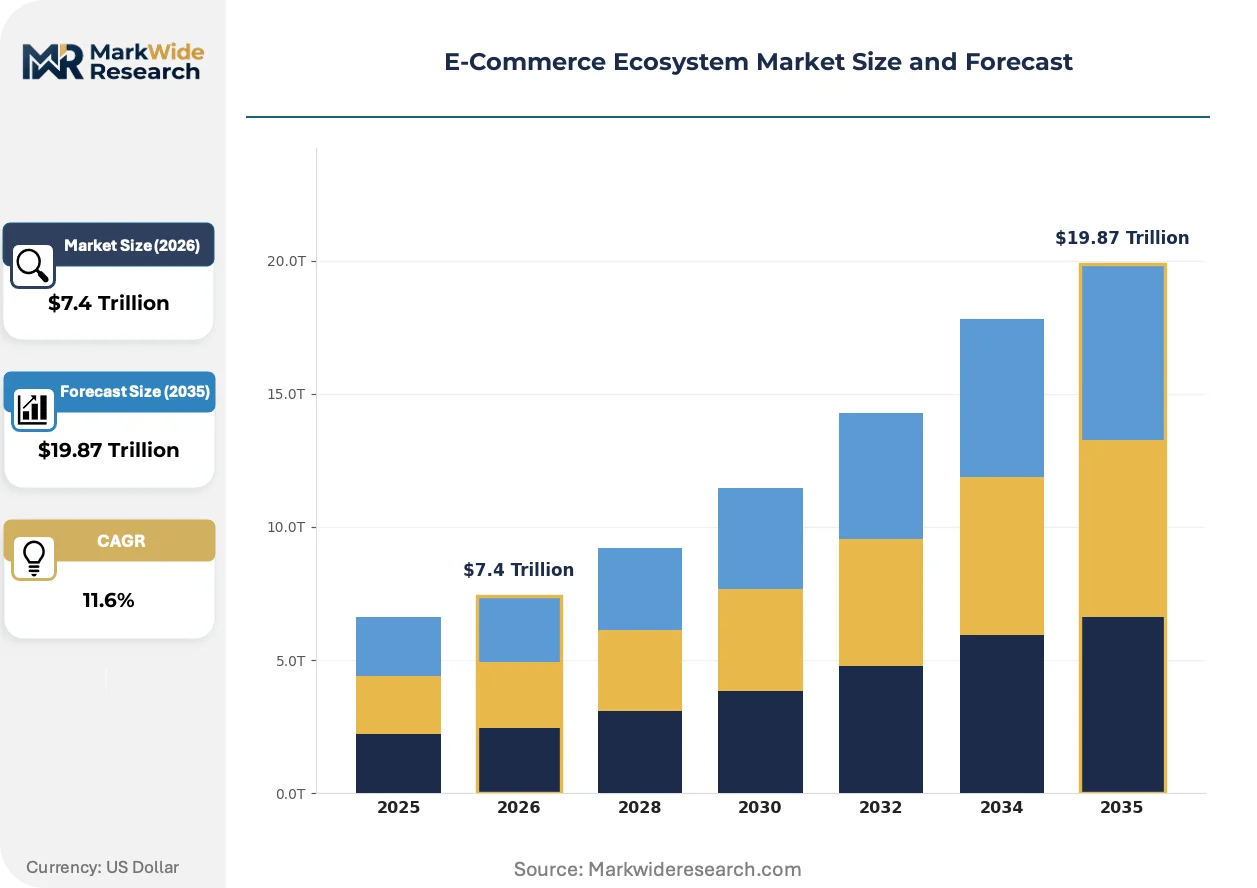
| Market Size in 2026 | $7.4 Trillion |
| Market Size in 2035 | $19.87 Trillion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Order Fulfillment, Data Analytics, Logistics Management Customer Type: B2C, B2B, C2C, D2C Platform Type: Online Marketplaces, Self-Hosted Stores, Social Commerce, Mobile Apps Technology: AI Chatbots, Cloud Computing, Blockchain, Augmented Reality |
| Companies Covered | Shopify, MercadoLibre, Amazon, JD.com, Shopee, Alibaba Group, PDD Holdings, eBay, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Ecosystem Market Shifts & Advancements
Headless commerce architecture is separating frontend presentation layers from backend transaction processing, enabling merchants to deploy experiences across emerging touchpoints without infrastructure rebuilds.
Composable commerce stacks are decomposing monolithic platform functions into interchangeable microservices. Mid-market merchants in North America and Western Europe are adopting API-first cart and checkout modules at accelerating pace. This modularity is decomposing vendor lock-in, allowing sellers to switch fulfillment or payment providers without migrating entire storefronts.
REACH substance restrictions on packaging materials are compelling platform operators to requalify third-party logistics partners across European fulfillment networks. Sellers listing through German and French marketplaces must document compliance with extended producer responsibility frameworks. Electronics and apparel categories face the steepest documentation burdens, with some operators restricting SKU eligibility to pre-certified suppliers.
Social discovery-to-purchase pathways are compressing traditional funnel stages. Younger consumer cohorts in Indonesia and Vietnam complete transactions within native video applications rather than redirecting to standalone storefronts. Beauty and consumer electronics verticals exhibit the highest conversion rates through this channel, with merchant advertising budgets following audience attention shifts.
E-Commerce Ecosystem Market Segmentation
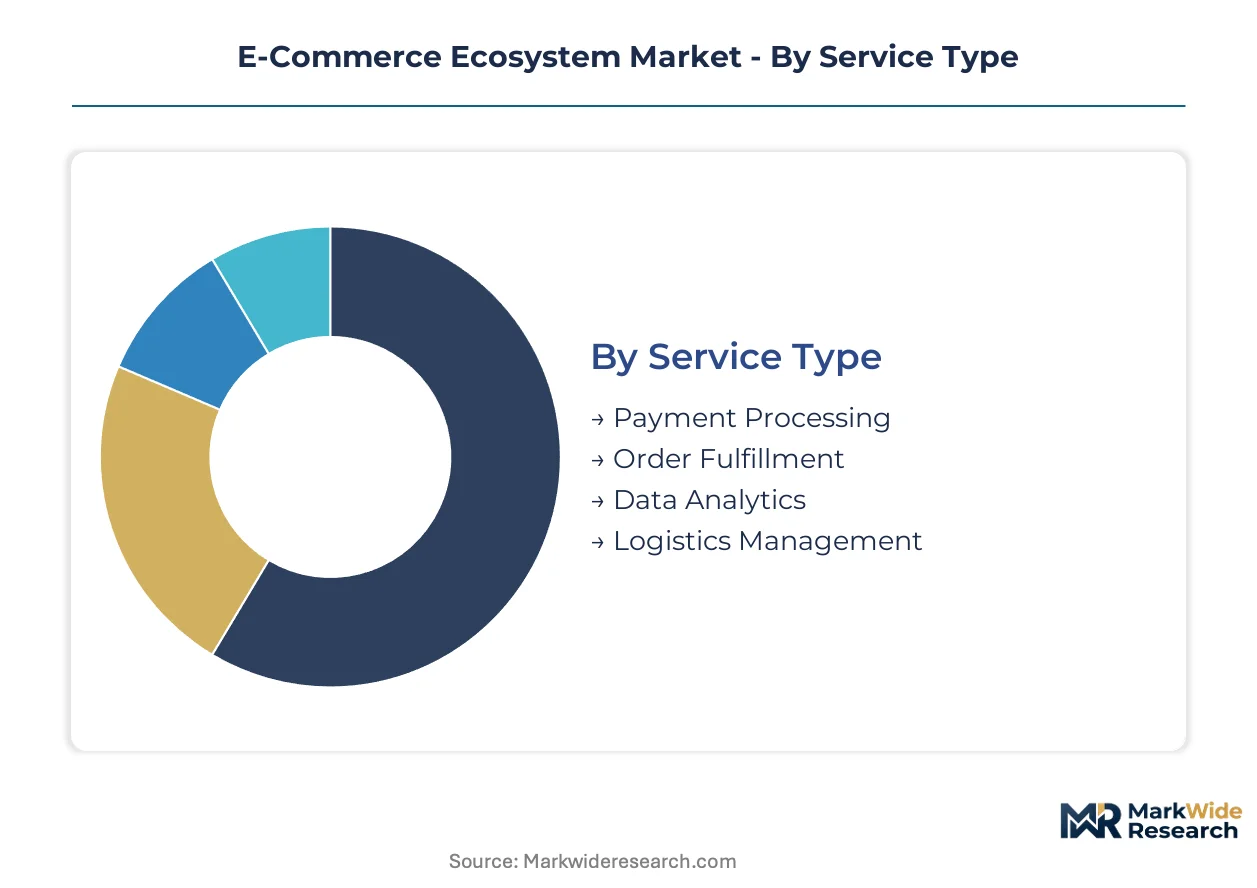
E-Commerce ecosystem segmentation reveals how infrastructure investments cluster around fulfillment velocity and data sovereignty requirements. Service configurations vary sharply between domestic-first merchants and cross-border operators navigating divergent regulatory environments.
Service Type:
Domestic merchants prioritize payment processing and order fulfillment, while export-led sellers invest disproportionately in data analytics and logistics management to manage multi-jurisdiction compliance.
- Payment Processing:Gateway infrastructure handles multi-currency settlement with PCI-DSS Level 1 certification as baseline for card network access. Demand concentrates in Southeast Asian markets where mobile wallet integration outpaces traditional card rails, driven by unbanked population digital onboarding.
- Order Fulfillment:Warehouse management systems coordinate pick-pack-ship workflows with SLA guarantees below 24 hours for urban zones. European merchants face the steepest architectural costs as GDPR data localization requirements fragment inventory visibility across national boundaries.
- Data Analytics:Behavioral prediction engines process clickstream data for personalization and demand forecasting.
- Logistics Management:Multi-carrier orchestration platforms optimize last-mile routing across heterogeneous delivery networks.
Payment processing holds the largest share; momentum sits with order fulfillment as same-day delivery becomes table stakes.
Customer Type:
Volume concentration favors B2C transactions, yet margin extraction and contract duration skew toward B2B procurement portals with annual recurring revenue models.
- B2C:Direct-to-consumer transactions dominate transaction counts with impulse purchase optimization and one-click checkout as core technical requirements. Indonesian and Vietnamese mobile-first consumers bypass desktop infrastructure entirely, creating native-app dependency for merchant storefronts.
- B2B:Industrial procurement portals manage purchase orders, invoice reconciliation, and volume-based pricing tiers with ERP integration as mandatory. ISO 27001 certification is becoming table stakes for platform access as cybersecurity insurance requirements harden.
- C2C:Peer-to-peer marketplaces enable individual sellers with minimal onboarding friction and escrow-mediated trust mechanisms.
- D2C:Brand-owned channels bypass marketplace commissions through captive storefronts and first-party data collection.
B2C commands transaction volume; B2B is climbing the fastest on per-contract value expansion.
Platform Type:
Cost tier stratification separates high-commission marketplace access from capital-intensive self-hosted infrastructure requiring dedicated technical staffing.
- Online Marketplaces:Aggregator platforms consolidate demand and supply with search algorithm governance determining merchant visibility. Amazon's fulfillment density sustains same-day delivery promises across dense North American urban corridors, compressing independent merchant margins.
- Self-Hosted Stores:Merchant-controlled infrastructure enables direct customer ownership and reduced commission structures through Shopify or WooCommerce deployments. Mid-market adopters in Western Europe favor headless architectures separating frontend presentation from backend transaction processing.
- Social Commerce:Native purchase completion within video and messaging applications eliminates redirect friction.
- Mobile Apps:Smartphone-optimized experiences dominate in markets with limited desktop penetration.
Online marketplaces retain the largest share; self-hosted stores are gaining share fastest on margin preservation.
Technology:
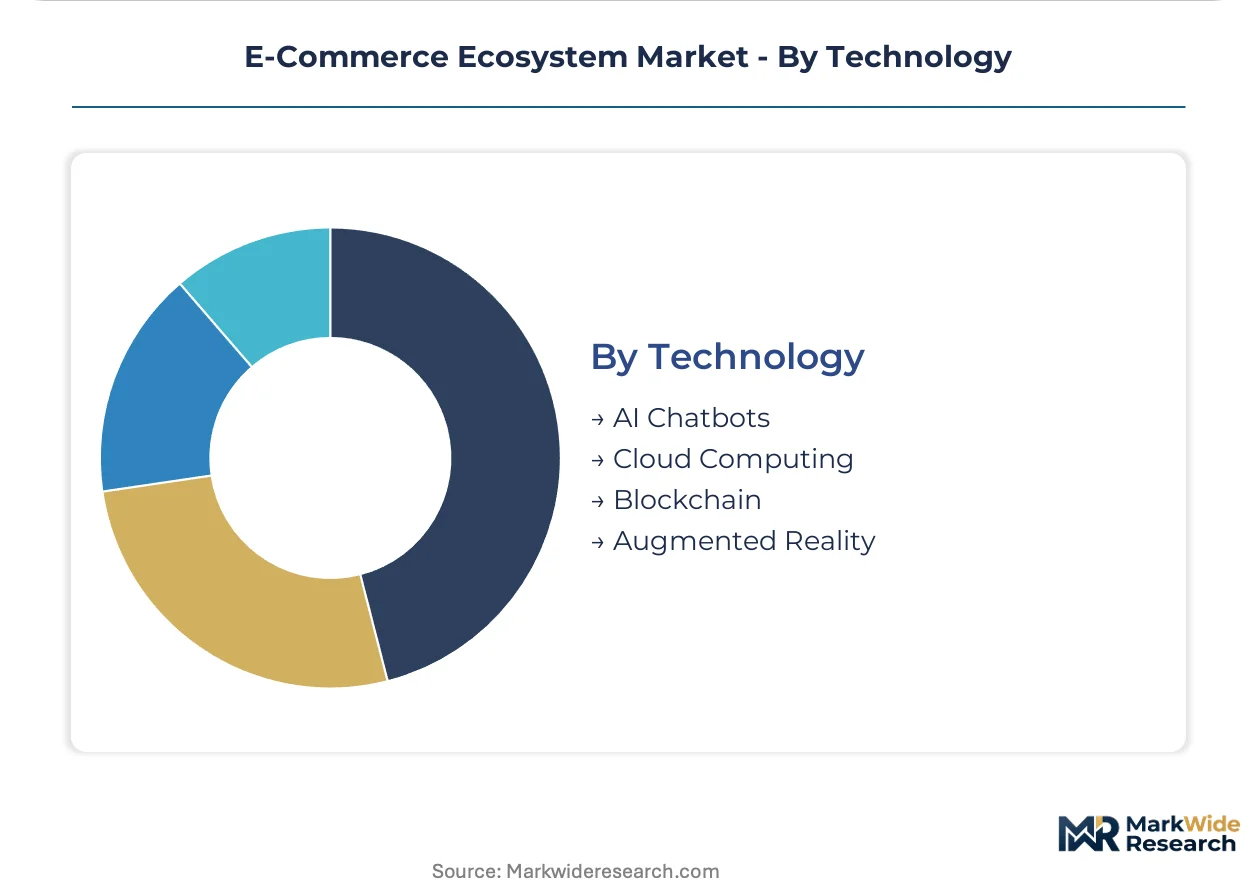
Maturity curves separate deployed-at-scale cloud infrastructure from experimental augmented reality implementations awaiting hardware penetration.
- AI Chatbots:Natural language interfaces handle customer service inquiries and purchase assistance with GPT-based models reducing escalation rates. EU AI Act transparency mandates force documentation of recommendation logic, creating audit-ready infrastructure that attracts risk-averse enterprise merchants.
- Cloud Computing:Elastic infrastructure provisioning enables demand spike absorption without capital-heavy server ownership. Southeast Asian platform operators leverage Singapore and Jakarta data center clusters to minimize latency for archipelago logistics coordination.
- Blockchain:Distributed ledger applications address provenance verification and cross-border payment settlement.
- Augmented Reality:Virtual try-on and spatial visualization tools reduce return rates for apparel and furniture categories.
Cloud computing holds the largest share; AI chatbots show the steepest expansion trajectory on labor cost displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SME merchants now represent the fastest-expanding buyer archetype across the E-Commerce Ecosystem Market, with digital storefront adoption accelerating most sharply in Southeast Asian markets where mobile-first commerce penetration bypasses legacy infrastructure entirely.
United States
Fulfillment density investments by dominant platforms sustain same-day delivery promises across dense urban corridors. FDA oversight of health product claims imposes extended review timelines for supplement and medical device sellers. The Pacific Northwest and Greater Boston clusters concentrate cloud-native merchant tooling development, with API-first inventory systems displacing legacy ERP installations.
Germany
REACH substance restrictions on packaging materials compel platform operators to requalify third-party logistics partners across European fulfillment networks. The EU AI Act mandates algorithmic transparency for recommendation engines, forcing documentation of product-ranking logic. The Rhine-Ruhr industrial corridor anchors B2B procurement portal expansion as ISO 27001 certification becomes mandatory for industrial buyer access.
China
SAMR antitrust enforcement constrains pricing autonomy for dominant platform operators while industrial buyers migrate purchase orders to digital workflows. GB standards and dual carbon goals reshape warehouse robotics deployment criteria. The Yangtze River Delta and Pearl River Delta clusters concentrate captive supply chain control through in-house last-mile fleets and automated fulfillment centers.
Indonesia
Mobile wallet integration outpaces traditional card rails as unbanked populations complete digital onboarding at scale. The country's national telecommunications regulator shapes data localization requirements for cross-border consumer transfers. Jakarta and Surabaya metropolitan zones exhibit deepening smartphone commerce habits that bypass desktop-era infrastructure entirely.
Vietnam
Live-stream commerce integration merges real-time video selling formats with traditional checkout flows across beauty and consumer electronics verticals. The central bank's digital payment frameworks accelerate mobile-first transaction completion. Ho Chi Minh City and Hanoi urban corridors concentrate merchant advertising budget shifts toward native video applications.
E-Commerce Ecosystem Market Competitive Landscape
Player mix skews toward integrated platform operators with captive logistics networks, creating tiered competition between fulfillment-heavy aggregators and margin-focused self-hosted infrastructure providers. The vendor base separates into three strategic archetypes: marketplace aggregators governing search algorithm visibility, modular commerce stack vendors enabling API-first merchant flexibility, and social-native platforms compressing discovery-to-purchase pathways. Dominant competitive moves include backward integration into warehouse robotics and geographic expansion through archipelago logistics infrastructure.
Within the integrated platform tier, Amazon and JD.com exemplify fulfillment-density strategies, while Shopify occupies a position enabling merchant-controlled infrastructure through headless architecture adoption. Alibaba Group anchors cross-border trade infrastructure serving non-Chinese consumers, representing the marketplace-aggregator archetype with transnational merchant base governance.
| Leading Market Players |
|---|
| Shopify |
| MercadoLibre |
| Amazon |
| JD.com |
| Shopee |
| Alibaba Group |
| PDD Holdings |
| eBay |
| Walmart |
| Others |
Supply & Pricing Matrix
Cloud-native inventory tools replacing on-premise ERP systems simultaneously relocate supply chain control to Southeast Asian data center clusters and compress merchant technology costs below legacy deployment thresholds. This substitution dynamic redistributes pricing power toward platform operators with captive logistics networks while eroding margins for merchants dependent on third-party fulfillment.
Pricing Analysis
Next-generation headless commerce architectures command premium positioning against legacy monolithic platforms and emerging API-first modular stacks. Three-tier pricing structure across enterprise-grade fulfillment bundles, mid-market SaaS subscriptions, and basic self-hosted licenses stratifies the vendor landscape. Pricing pressure stems from Amazon's fulfillment density investments compressing independent merchant margins across North American urban corridors. SME merchants exhibit highest price sensitivity due to thin working capital buffers, while enterprise procurement portals prioritize ISO 27001 certification over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate merchant fulfillment preferences, though archipelago logistics in Indonesia and the Philippines force strategic stockpiling at maritime hub ports. Supply chain configuration draws from China for warehouse robotics manufacturing, Vietnam for apparel fulfillment labor pools, and Singapore for cloud infrastructure provisioning. Single-source vulnerability concentrates in last-mile gig-economy workforce pools across dense metropolitan corridors. Distribution runs through integrated platform operators with captive logistics networks rather than independent carrier aggregations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation around fulfillment infrastructure has created acute scarcity of merchant-facing technical talent capable of orchestrating multi-jurisdiction compliance architectures. Organizations lacking in-house API integration expertise face structural barriers to margin preservation.
For Market Incumbents: Secure fulfillment density advantages through backward integration into warehouse robotics deployment across Southeast Asian archipelago markets. Defend against modular commerce stack vendors by embedding ISO 27001 certification as mandatory access criteria for enterprise procurement portals. Prioritize GDPR-compliant data localization infrastructure to preempt regulatory displacement. For New Entrants and Emerging Players: Anchor in Philippine maritime logistics infrastructure where integrated supply chain investment remains underdeveloped relative to demand density. Target Vietnamese live-stream commerce verticals where native video application transactions bypass established marketplace gatekeepers. Pursue headless architecture specialization enabling merchant migration without infrastructure rebuilds. For Investors and Strategic Acquirers: EU AI Act transparency mandates reshape the acquisition landscape by elevating audit-ready algorithmic documentation to core asset value. Long-term viability centers on platform operators with demonstrated cross-border data governance infrastructure spanning GDPR and SAMR jurisdictions. Monitor SAMR enforcement intensity as inflection signal for Chinese platform valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Headless Architecture Deployment | Separates frontend presentation from JD.com's backend transaction processing for multi-channel flexibility. |
| Captive Logistics Network Expansion | JD.com anchors supply chain control through warehouse robotics and in-house last-mile fleet deployment. |
| Cross-Border Compliance Certification | GDPR and EU AI Act documentation attracts risk-averse enterprise merchants to Alibaba Group platforms. |
| Live-Stream Commerce Integration | Shopee merges real-time video selling with checkout flows in Indonesian and Vietnamese mobile-first markets. |
| ISO 27001 Security Standardization | Shopify enables merchant-controlled infrastructure with audit-ready certification for B2B procurement access. |
Research Methodology
Operator-level perspectives from platform engineering directors, merchant onboarding specialists, logistics network planners, and cross-border compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade flow databases, hyperscaler capex disclosures, and EU regulatory implementation notices. Bottom-up merchant adoption modeling triangulated against top-down platform revenue aggregation.
Sensitivity analysis tested forecast outputs against variable penetration rates for mobile-first commerce and divergent regulatory enforcement timelines across the projection horizon. Segmentation dimensions modeled include platform type, customer archetype, service configuration, and regional data sovereignty requirements. CAGRs derived from logistic curve fitting to SME digital adoption patterns and cloud infrastructure deployment trajectories. Industry-specific inputs incorporated GDPR implementation lag effects and SAMR penalty probability distributions.
Decision-makers should treat outputs as directional under assumptions of sustained mobile wallet penetration in Southeast Asia and stable EU-U.S. data transfer mechanisms; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside assumed cloud infrastructure cost curves. Revision becomes warranted when SAMR enforcement intensity or REACH packaging compliance thresholds cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Iceland E-Commerce Market
E-Commerce Solutions
US Social Commerce Market