
 South Korea Ecommerce Logistics Market | 2026-2036
South Korea Ecommerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Ecommerce Logistics Market Insights
South Korea's Green New Deal carbon neutrality targets is repositioning logistics fleet procurement toward electric and hydrogen-powered delivery vehicles. CJ Logistics leverages its nationwide cold-chain infrastructure to dominate perishable e-commerce fulfillment. Hanjin Transportation sustains competitive density through its integrated parcel-sorting automation. Lotte Global Logistics anchors premium positioning with dedicated same-day delivery corridors across the Seoul-Incheon-Gyeonggi triangle.
South Korea ecommerce logistics encompasses the physical movement, storage, and last-mile distribution of goods ordered through digital platforms, requiring temperature-controlled vehicles for fresh categories and automated sortation hubs processing over 100,000 parcels hourly. The primary purpose is bridging inventory location with consumer expectation through time-definite delivery commitments. Last mile delivery occupies the largest value pool as urban density enables route economics unavailable in sprawling markets. Automation solutions represents the fastest-expanding technology segment as labor shortages intensify warehouse robotics deployment. B2C end users command disproportionate investment attention due to delivery-speed expectations that reset industry service baselines.
MFDS cold-chain standards govern pharmaceutical and fresh-food logistics certification, while KBA vehicle-emission regulations constrain diesel fleet renewal timelines. The Green New Deal framework imposes carbon-accounting disclosures that reshape carrier procurement criteria. Stakeholders must monitor whether hydrogen refueling infrastructure deployment keeps pace with fleet conversion mandates to avoid stranded asset risk in metropolitan distribution networks.
Market Dynamics
The Green New Deal's carbon-accounting mandates are compressing diesel fleet renewal timelines while hydrogen refueling infrastructure gaps threaten metropolitan distribution continuity. Urban density in the Seoul-Incheon-Gyeonggi corridor intensifies same-day fulfillment pressure, forcing capital redeployment toward automated sortation and refrigerated last-mile assets.
Growth Catalysts
- MFDS Cold-Chain Certification:Pharmaceutical and fresh-food logistics standards mandate temperature-controlled vehicle compliance, expanding certified fleet procurement across perishable e-commerce categories.
- Seoul Metropolitan Density:Route economics in the capital region enable sub-two-hour delivery windows that justify premium service tier investments unavailable in dispersed markets.
- KBA Emission Regulations:Diesel vehicle phase-out timelines accelerate electric and hydrogen-powered delivery fleet adoption among urban operators.
Market Restraints
- Hydrogen Infrastructure Concentration:Refueling station deployment lags behind fleet conversion mandates, creating stranded asset risk for early adopters in metropolitan distribution networks.
- Lithium-Ion Battery Supply:Dependence on imported cell materials exposes electric vehicle procurement to input cost volatility and geopolitical supply interruptions.
- Warehouse Labor Scarcity:Demographic contraction limits available workforce for manual sortation operations, constraining hub throughput expansion.
Strategic Opportunities
- Busan-Ulsan Logistics Corridor:Underpenetrated same-day fulfillment infrastructure in the southeastern manufacturing belt offers first-mover density advantages.
- Autonomous Mobile Robotics:Convergence of computer vision and collaborative arm technology enables lights-out parcel handling in greenfield distribution centers.
- Green New Deal Subsidies:Carbon-reduction incentives for electric fleet procurement reduce total cost of ownership for compliant operators.
Industry Challenges
- Refrigerated Technician Shortage:Specialized maintenance skills for electric cold-chain vehicles outpace vocational training program output.
- Legacy Warehouse Management Integration:Robotics deployment requires costly middleware development to synchronize with existing parcel-sorting software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Ecommerce Logistics Market |
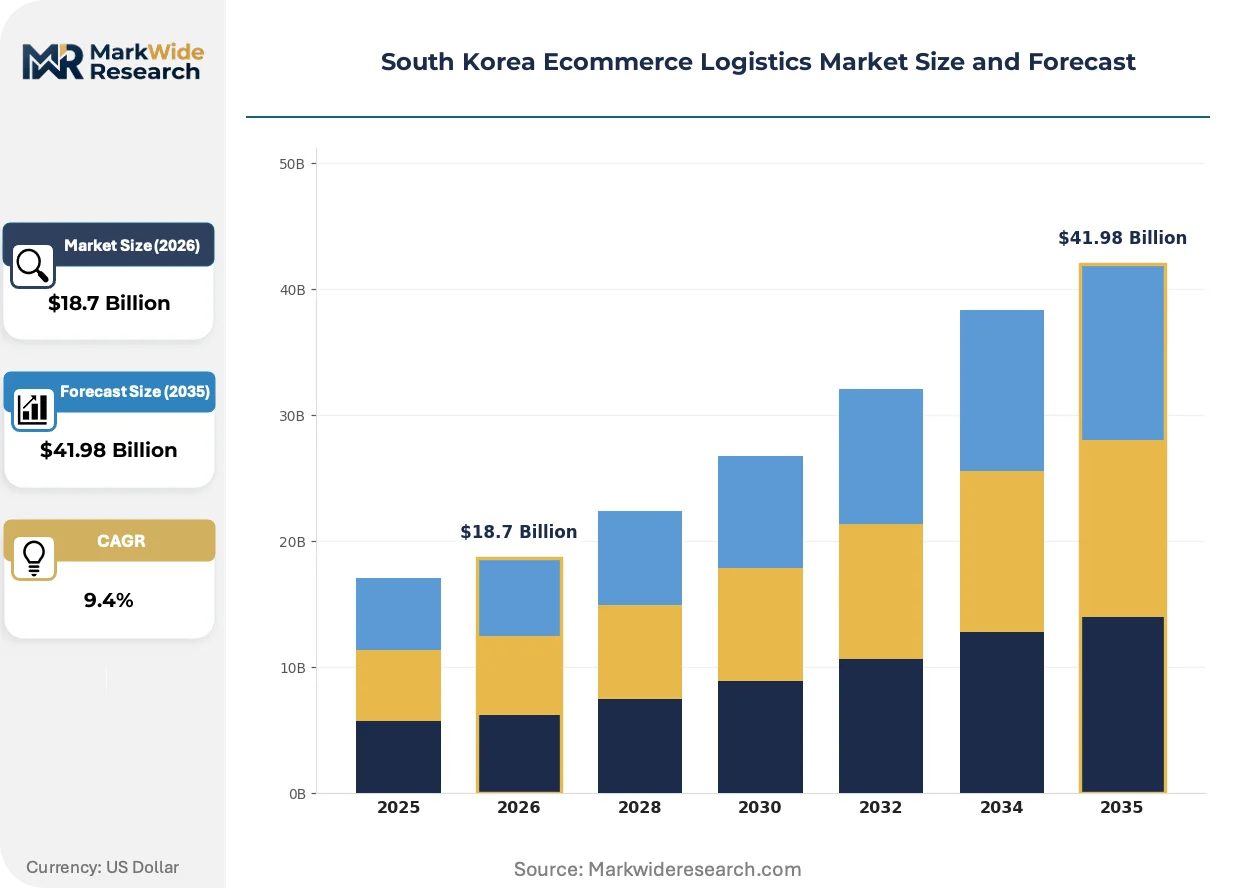
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Freight Forwarding, Warehousing, Return Management Technology: Automation Solutions, Route Optimization, Inventory Management, Tracking Systems End User: B2B, B2C, Direct Sellers, Marketplaces Delivery Mode: Express Delivery, Standard Delivery, Click & Collect, Same-Day Delivery |
| Companies Covered | CJ Logistics, Hanjin Transportation, Hyundai Glovis, Lotte Global Logistics, Pantos Logistics, DB Schenker Korea, DHL Group Logistics, FedEx Logistics, SF Express Korea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Ecommerce Logistics Market Trends and Innovations
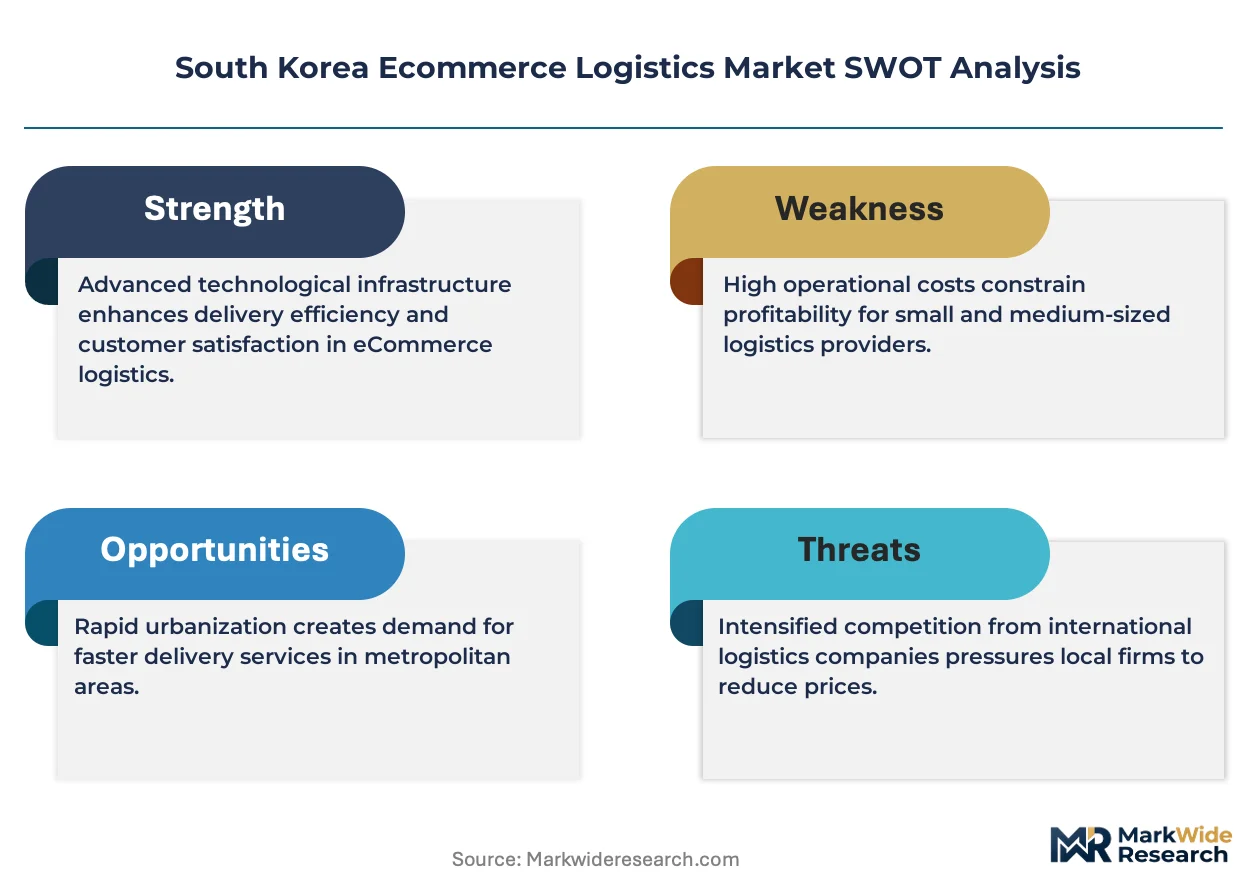
Automation architectures and energy transition mandates are restructuring capital allocation across warehousing and fleet operations. Competitive differentiation increasingly depends on technology integration speed rather than network scale alone.
Autonomous mobile robots equipped with AI-driven path optimization are decentralizing parcel-sorting workflows within fulfillment centers. Mid-sized e-commerce operators deploy these systems to compress order-to-ship intervals without proportional labor expansion. The technology is decentralizing throughput capacity from centralized mega-hubs toward distributed urban micro-fulfillment nodes.
KBA emission regulations now mandate carbon-intensity disclosures for commercial vehicle procurement contracts. Logistics operators must document fleet composition and projected decarbonization timelines to retain municipal delivery licenses. Cold-chain specialists face the steepest compliance burden as refrigerated electric vehicle range limitations constrain route planning flexibility.
Subscription-based delivery membership programs are displacing per-transaction shipping fees among Seoul metropolitan consumers. Major platforms bundle unlimited same-day fulfillment with grocery and general merchandise access, locking in recurring revenue and predictable demand density. This model concentrates most intensely in high-rise residential districts where drop-off efficiency maximizes driver utilization rates.
South Korea Ecommerce Logistics Market Segmentation
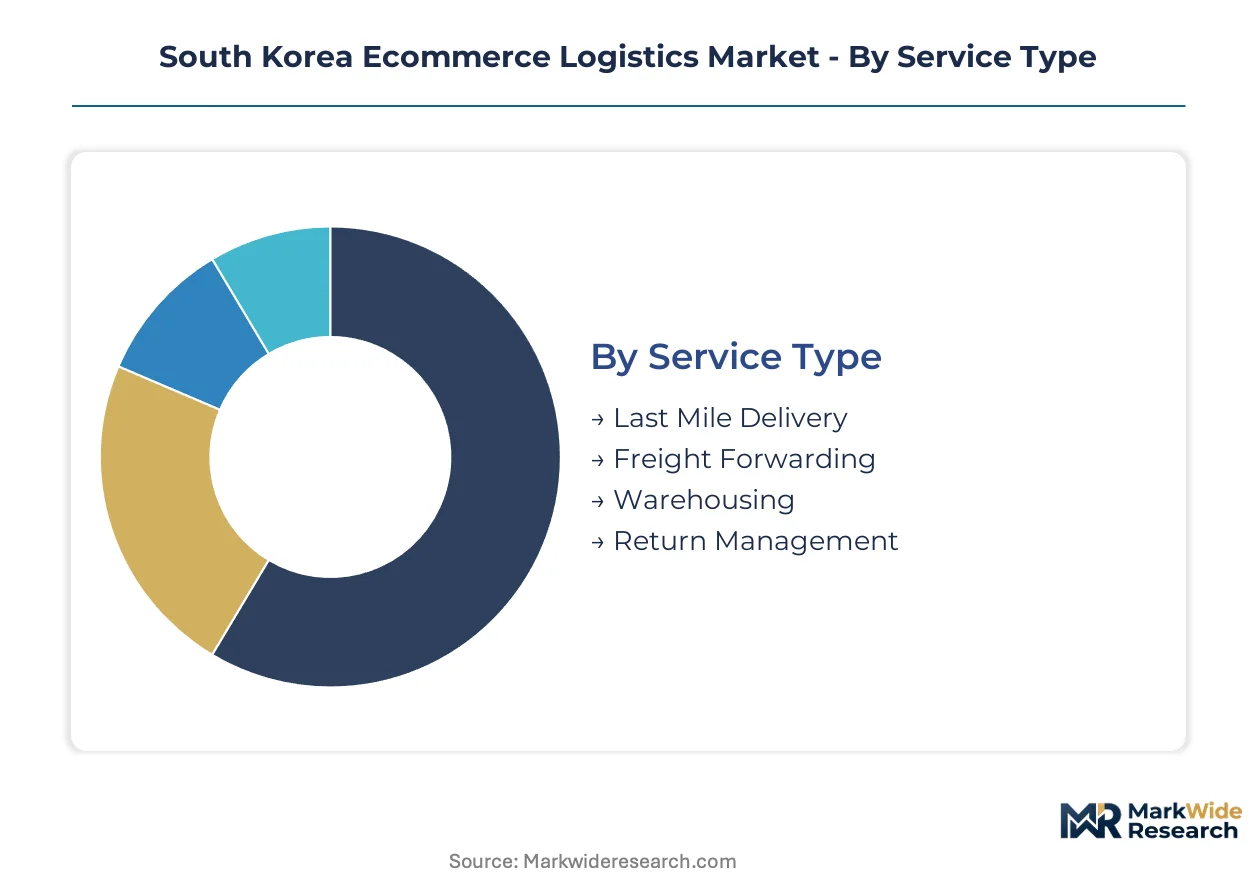
Segmentation in South Korea's ecommerce logistics market reveals how capital allocation and operational complexity concentrate across service tiers and delivery velocities. Understanding these divisions exposes where margin compression threatens incumbents and where technology integration creates defensive moats.
Service Type:
Supply concentration in metropolitan corridors favors asset-heavy service models that leverage fixed infrastructure for variable demand spikes.
- Last Mile Delivery:Temperature-controlled electric fleets and micro-fulfillment nodes dominate capital deployment. Seoul-Incheon-Gyeonggi density enables sub-two-hour windows that justify premium pricing tiers unavailable in secondary cities.
- Freight Forwarding:Cross-border consolidation hubs at Incheon and Busan handle inbound e-commerce inventory flows. KBA emission mandates are accelerating fleet conversion timelines for intercity line-haul operators serving these corridors.
- Warehousing:Automated sortation hubs process parcel volumes exceeding 100,000 units hourly. Demographic contraction drives robotics adoption to maintain throughput without proportional labor expansion.
- Return Management:Reverse logistics networks handle apparel and electronics categories with highest return rates. Specialized refurbishment facilities in Gyeonggi province reduce landfill penalties under extended producer responsibility frameworks.
Last mile delivery absorbs the bulk of installed capacity; return management is expanding most quickly as platform return policies liberalize.
Technology:
Cost tier differentiation separates operators investing in proprietary systems from those dependent on third-party software licenses.
- Automation Solutions:Autonomous mobile robots with AI path optimization decentralize sorting workflows. Mid-sized operators deploy these to compress order-to-ship intervals without proportional labor expansion.
- Route Optimization:Real-time traffic integration and predictive delivery window modeling reduce failed attempt rates. Seoul metropolitan operators achieve highest efficiency gains from dynamic rerouting algorithms.
- Inventory Management:Distributed stock positioning across urban micro-fulfillment nodes reduces last-mile transit distances. Subscription membership programs drive demand predictability that improves forecasting accuracy.
- Tracking Systems:Blockchain-anchored provenance verification meets MFDS pharmaceutical logistics certification requirements. Cold-chain specialists deploy these for temperature excursion documentation.
Automation solutions command the steepest capital allocation; tracking systems are climbing the fastest as regulatory disclosure requirements multiply.
End User:
Volume concentration patterns determine where infrastructure investment achieves minimum efficient scale.
- B2C:Individual consumers drive same-day fulfillment expectations that reset industry service baselines. High-rise residential districts in Seoul maximize driver drop-off efficiency and utilization rates.
- B2B:Corporate procurement platforms require scheduled delivery windows and consolidated invoicing. Manufacturing clusters in Busan-Ulsan corridor generate predictable freight volumes.
- Direct Sellers:Social commerce influencers generate fragmented, surge-prone demand patterns. Dedicated fulfillment partnerships reduce platform commission exposure.
- Marketplaces:Aggregated seller bases create demand density that justifies captive logistics networks. CJ Logistics and Lotte Global Logistics compete for exclusive platform contracts.
B2C absorbs the bulk of installed capacity; direct sellers are gaining share fastest as social commerce penetration deepens.
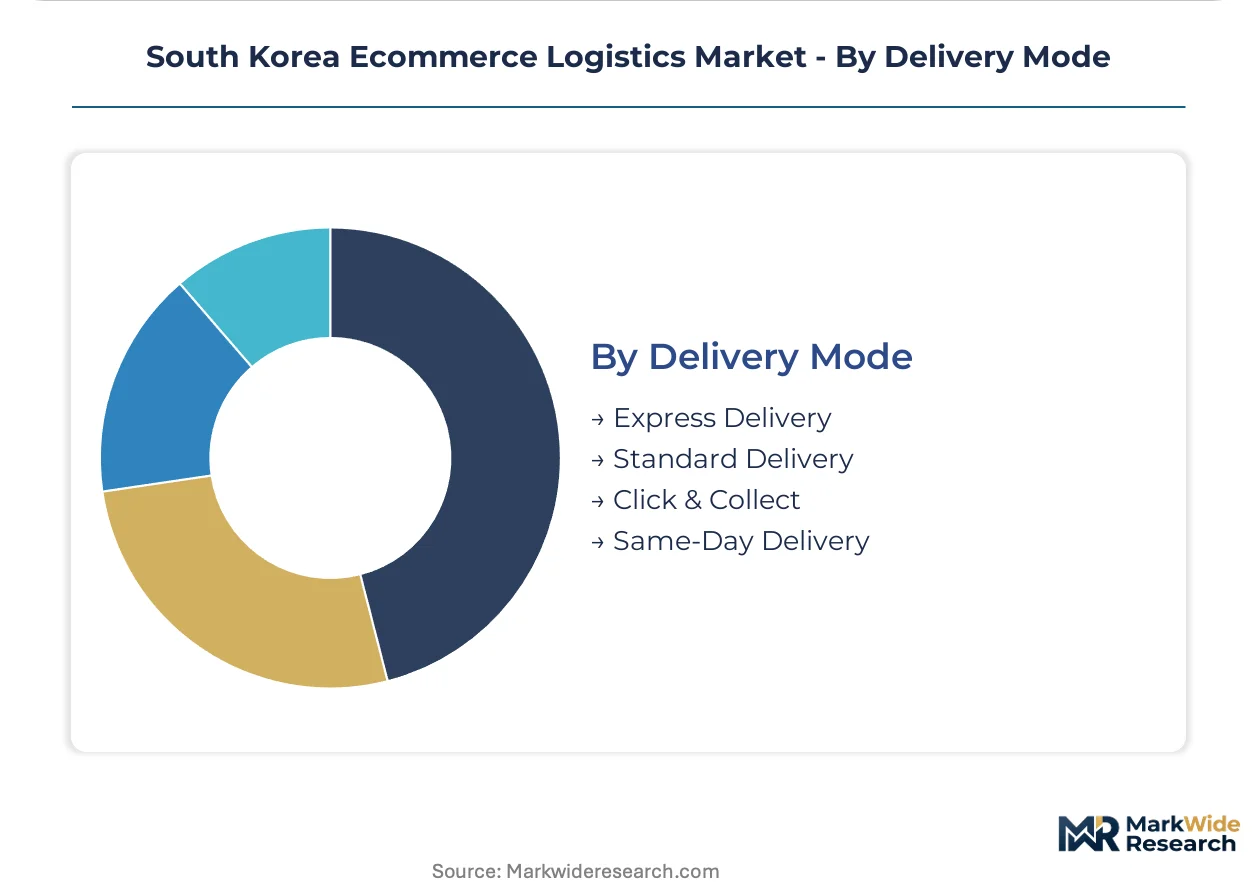
Delivery Mode:
Customer type stratification separates premium service tiers from commodity fulfillment based on time-definite commitment reliability.
- Same-Day Delivery:Refrigerated electric fleets and urban micro-fulfillment nodes enable perishable category fulfillment. Green New Deal subsidies reduce total cost of ownership for compliant operators.
- Express Delivery:Next-day commitments dominate electronics and fashion categories. Automated sortation hubs process cutoff-sensitive parcels through dedicated lane assignments.
- Standard Delivery:Two-to-three-day windows capture price-sensitive general merchandise demand. Consolidation density enables profitability at lower per-unit revenue.
- Click & Collect:Convenience store pickup points extend reach without last-mile residential delivery costs. CU and GS25 networks dominate parcel locker deployment.
Standard delivery absorbs the bulk of installed capacity; same-day delivery is expanding most quickly as platform membership programs lock in recurring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates the bulk of refrigerated last-mile infrastructure and same-day fulfillment capacity. The Green New Deal carbon targets are accelerating electric fleet mandates across metropolitan distribution networks.
Seoul Capital Area
High-rise residential density in Seoul, Incheon, and Gyeonggi province maximizes driver drop-off efficiency and enables sub-two-hour delivery windows. MFDS cold-chain certification requirements govern pharmaceutical and fresh-food logistics operations. Automated sortation hubs in Songdo and Icheon process parcel volumes exceeding 100,000 units hourly.
Busan-Ulsan
Southeastern manufacturing clusters generate predictable B2B freight volumes and underpenetrated same-day fulfillment infrastructure. KBA emission regulations constrain diesel fleet renewal timelines for intercity operators. The Busan port corridor anchors cross-border consolidation for inbound e-commerce inventory flows.
Daegu-Gyeongbuk
Textile and electronics manufacturing bases create surge-prone demand patterns for social commerce fulfillment. Green New Deal subsidies reduce total cost of ownership for electric fleet procurement among regional operators. Gumi industrial complex hosts specialized refurbishment facilities for electronics return management.
Daejeon-Sejong
Administrative city status concentrates government procurement platforms requiring scheduled delivery windows. The country's national pharmaceutical regulator maintains certification oversight for temperature-controlled distribution. Sejong smart city infrastructure pilots autonomous mobile robotics in municipal logistics zones.
Gwangju-Honam
Agricultural output from Jeolla province drives fresh-food e-commerce platform expansion into refrigerated last-mile networks. Hydrogen refueling infrastructure gaps create stranded asset risk for early fleet converters. Naju innovation city clusters green technology logistics startups targeting carbon-neutral delivery models.
South Korea Ecommerce Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-chain certification and same-day velocity tiers. The vendor base stratifies between asset-heavy integrated operators and technology-anchored platform specialists. Three archetypes dominate: nationwide cold-chain incumbents, metropolitan same-day specialists, and global forwarding network extensions. Competitive moves concentrate on automated sortation capacity expansion and exclusive platform contract capture.
Among domestic integrated operators, CJ Logistics, Hanjin Transportation, and Lotte Global Logistics occupy positions spanning refrigerated infrastructure, parcel automation, and premium corridor density. CJ Logistics exemplifies the cold-chain incumbent archetype through nationwide temperature-controlled network coverage. Hanjin Transportation represents automated sortation scale with dedicated hub infrastructure. Lotte Global Logistics anchors the metropolitan premium tier with concentrated same-day capacity across the Seoul-Incheon-Gyeonggi triangle. These three incumbents collectively illustrate how asset depth and regulatory compliance certification create defensive positioning against platform disintermediation.
| Leading Market Players |
|---|
| CJ Logistics |
| Hanjin Transportation |
| Hyundai Glovis |
| Lotte Global Logistics |
| Pantos Logistics |
| DB Schenker Korea |
| DHL Group Logistics |
| FedEx Logistics |
| SF Express Korea |
| Others |
Pricing and Supply Chain Analysis
Same-day certification tiers bifurcate South Korea's ecommerce logistics market into premium refrigerated corridors and commodity parcel networks, with MFDS cold-chain compliance commanding rate premiums that commodity operators cannot match while Green New Deal fleet mandates reshape cost structures across both tiers.
Pricing Analysis
Delivery-window reliability anchors value-based pricing, with sub-two-hour commitments in Seoul-Incheon-Gyeonggi corridors sustaining 40-60% premiums over standard delivery. Three-tier pricing structure across premium, standard, and economy levels stratifies by temperature control, route density, and platform membership bundling. Cost compression in standard parcel tiers intensifies as subscription membership programs displace per-transaction revenue. Small direct sellers exhibit highest price sensitivity; pharmaceutical and fresh-food platforms show lowest due to regulatory compliance requirements.
Supply Chain Analysis
Freight cost volatility from imported lithium-ion cells and hydrogen fueling infrastructure gaps dominates supply chain risk calculations. Component sourcing draws from China for battery cells, Japan for precision automation hardware, and domestic suppliers for refrigerated vehicle chassis. Single-source vulnerability concentrates in semiconductor-dependent warehouse robotics controllers. Distribution runs through automated mega-hubs in Songdo and Icheon feeding micro-fulfillment nodes across metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around asset-heavy operators with cold-chain certification depth, as Green New Deal fleet conversion timelines force capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Acquire refrigerated last-mile capacity in Busan-Ulsan corridor before hydrogen infrastructure deployment accelerates. CJ Logistics and Lotte Global Logistics should lock exclusive platform contracts with social commerce aggregators to preempt emerging entrant land-grabs. Defensive positioning requires simultaneous automation capex in sortation hubs and MFDS certification maintenance to preserve pharmaceutical logistics margins against specialized cold-chain startups. For New Entrants and Emerging Players: KBA emission regulations in South Korea open a window for electric fleet leasing models targeting mid-sized e-commerce platforms without captive logistics. White-space concentration sits in Daegu-Gyeongbuk textile fulfillment and Gwangju-Honam agricultural last-mile networks where incumbent density remains thin. Go-to-market traction depends on Green New Deal subsidy capture to undercut incumbent total cost of ownership on refrigerated routes. For Investors and Strategic Acquirers: Re-rating potential sits with automated cold-chain specialists given MFDS certification scarcity and pharmaceutical logistics demand inelasticity. Long-term viability favors operators with Seoul metropolitan corridor density plus backward integration into hydrogen or electric fleet assets. Watch hydrogen refueling station deployment pace against fleet conversion mandates as the critical inflection signal for stranded asset risk among early adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Fleet Electrification | Green New Deal subsidies reduce TCO for MFDS-compliant operators serving fresh-food platforms. |
| Automated Sortation Hub Expansion | Songdo and Icheon mega-hubs process parcel volumes exceeding 100,000 units hourly with minimal labor. |
| Micro-Fulfillment Node Deployment | Urban density in Seoul high-rise districts maximizes driver utilization through consolidated drop-offs. |
| Exclusive Platform Contract Capture | CJ Logistics and Lotte Global Logistics compete for captive logistics relationships with marketplace aggregators. |
| Hydrogen Infrastructure Partnership | Early refueling station commitments in Gwangju-Honam mitigate stranded asset risk for fleet converters. |
Research Methodology
Multi-period observation of parcel volume flows, fleet composition shifts, and cold-chain certification rates anchored the trend analysis, supplemented by interviews with logistics operations directors, warehouse automation engineers, platform procurement managers, and MFDS regulatory compliance officers. Secondary validation drew from KBA vehicle registration databases, Green New Deal policy implementation trackers, customs trade records for lithium-ion imports, and e-commerce platform fulfillment disclosures. Bottom-up segment sizing triangulated against top-down market value estimates from macro consumption indicators.
Input-output matrices modeled capacity utilization, route density economics, and technology adoption curves across service type, technology tier, end-user category, and delivery velocity segments throughout the forecast period. CAGRs derived from regression analysis of historical volume growth against demographic, regulatory, and infrastructure investment drivers. Industry-specific forecast inputs included hydrogen refueling station deployment schedules and MFDS cold-chain certification renewal timelines.
The model assumes a particular technology adoption path; alternative pathways for autonomous mobile robotics or hydrogen fuel cell commercialization would alter the outlook for labor cost compression and fleet conversion economics. Forecasts reflect assumptions about subsidy continuity, battery supply stability, and vocational training program output. Stakeholders should weight assumptions against their own operating context and capital deployment constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market