
 Qatar E-Commerce Market | 2026-2036
Qatar E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar E-Commerce Market Outlook
Cash-on-delivery is realigning toward digital payment rails as mobile wallet penetration deepens across Qatar's retail ecosystem. Talabat.com leverages its captive logistics network to sustain same-day delivery dominance in food and grocery verticals. Amazon.com, Inc. anchors cross-border fulfillment capacity through its UAE hub operations serving Qatari consumers. Snoonu competes on hyperlocal speed, positioning its dark-store model as the default for urgent household replenishment.
Qatar E-Commerce denotes digitally mediated transactions for goods and services executed through web-based platforms and native mobile applications, typically integrating encrypted payment gateways, real-time inventory APIs, and last-mile tracking protocols to enable remote purchasing without physical storefront interaction. Electronics and fashion categories currently occupy the largest transaction volume pools, reflecting high-margin import-dependent retail structures and young demographic purchasing patterns. Social commerce channels are registering the fastest trajectory among sales channels, driven by Instagram and TikTok-native merchant onboarding that bypasses traditional marketplace fee structures.
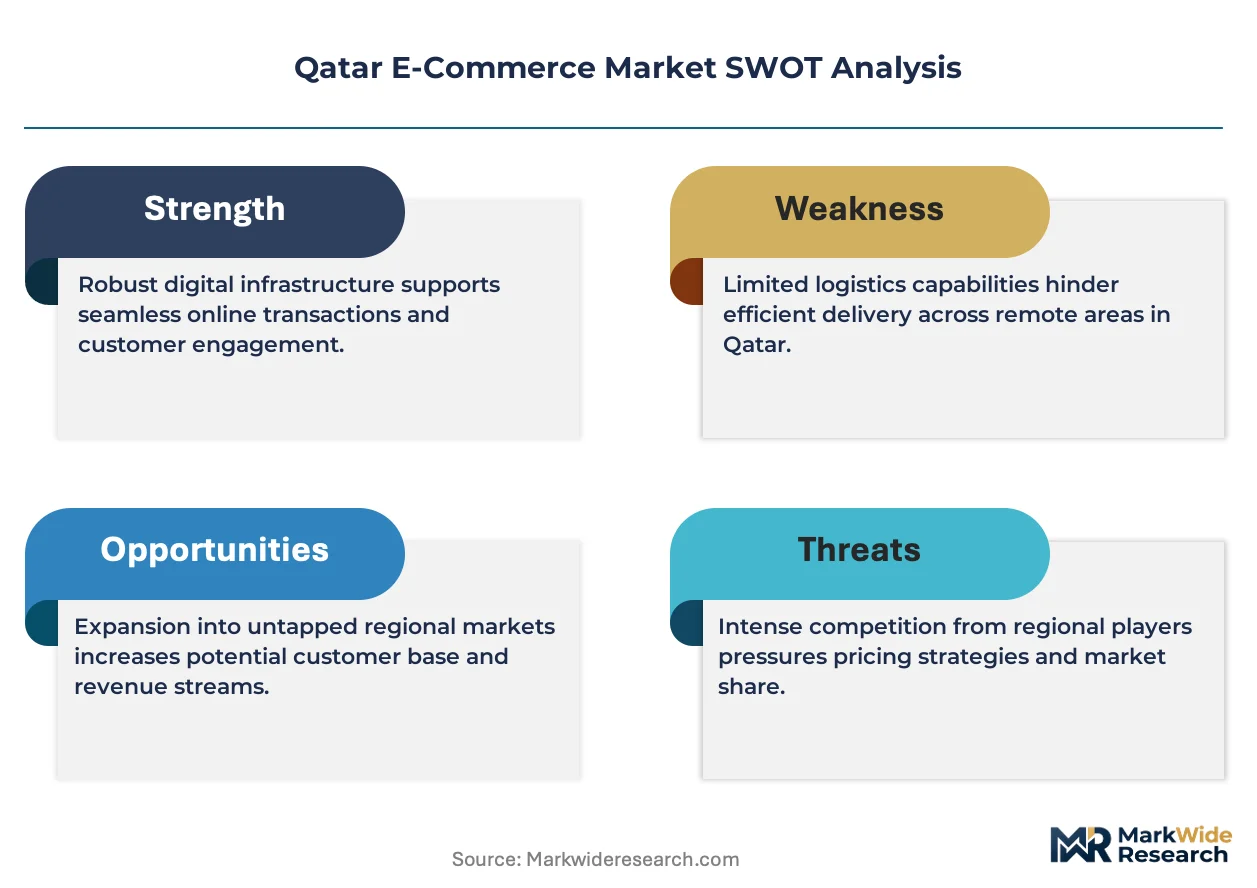
Qatar Central Bank's fintech licensing regime and the Qatar Communications Regulatory Authority's cybersecurity standards jointly determine platform compliance burdens and consumer trust thresholds for market entry. The Ministry of Commerce and Industry enforces consumer protection mandates that shape return policies and dispute resolution architectures across domestic operators. Stakeholders must monitor regulatory clarity on cross-border data localization requirements as a decisive factor for international platform expansion strategies.
Market Dynamics
Qatar Central Bank's digital wallet licensing regime is compressing settlement infrastructure timelines, forcing platform operators to rebuild payment architectures around real-time clearing protocols rather than legacy batch processing systems.
Growth Catalysts
- Digital Wallet Framework:Qatar Central Bank's regulatory sandbox accelerates fintech onboarding, reducing merchant integration cycles from months to weeks for licensed payment aggregators.
- Young Professional Demographics:Doha's expatriate workforce concentrates purchasing power in mobile-native channels, driving same-day delivery demand across grocery and electronics categories.
- Dark-Store Infrastructure:Hyperlocal fulfillment nodes positioned in Al Sadd and West Bay micro-fulfillment zones compress last-mile delivery windows to under thirty minutes for household replenishment.
Market Restraints
- Import-Dependent Electronics Supply:High-margin consumer electronics rely on UAE and Far East manufacturing clusters, exposing inventory cycles to Red Sea shipping volatility and customs clearance bottlenecks at Hamad Port.
- Cross-Border Data Localization Ambiguity:Unclear mandates from the Qatar Communications Regulatory Authority on server location requirements create compliance uncertainty for international marketplace operators.
- Cash-to-Digital Transition Friction:Migrant worker segments without residency-linked banking access remain tethered to cash-on-delivery, inflating return-to-origin rates and logistics cost structures.
Strategic Opportunities
- Social Commerce Channels:Instagram and TikTok-native merchant onboarding bypasses traditional marketplace fee structures, capturing transaction volume from fashion micro-brands targeting Gulf Cooperation Council consumers.
- Ministry of Commerce Consumer Protection Alignment:Return policy standardization creates trust infrastructure for cross-border sellers entering under Qatar's dispute resolution mandates.
- Logistics-Tech Convergence:Integration of real-time inventory APIs with captive fleet management compresses stockout windows for perishable grocery verticals in Lusail and The Pearl developments.
Industry Challenges
- API Integration Complexity:Legacy ERP systems at traditional retailers resist real-time synchronization with marketplace inventory feeds, creating phantom stock situations and cancellation penalties.
- Cybersecurity Certification Timelines:Qatar Communications Regulatory Authority penetration testing requirements extend platform launch schedules, particularly for cross-border operators unfamiliar with localized audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar E-Commerce Market |
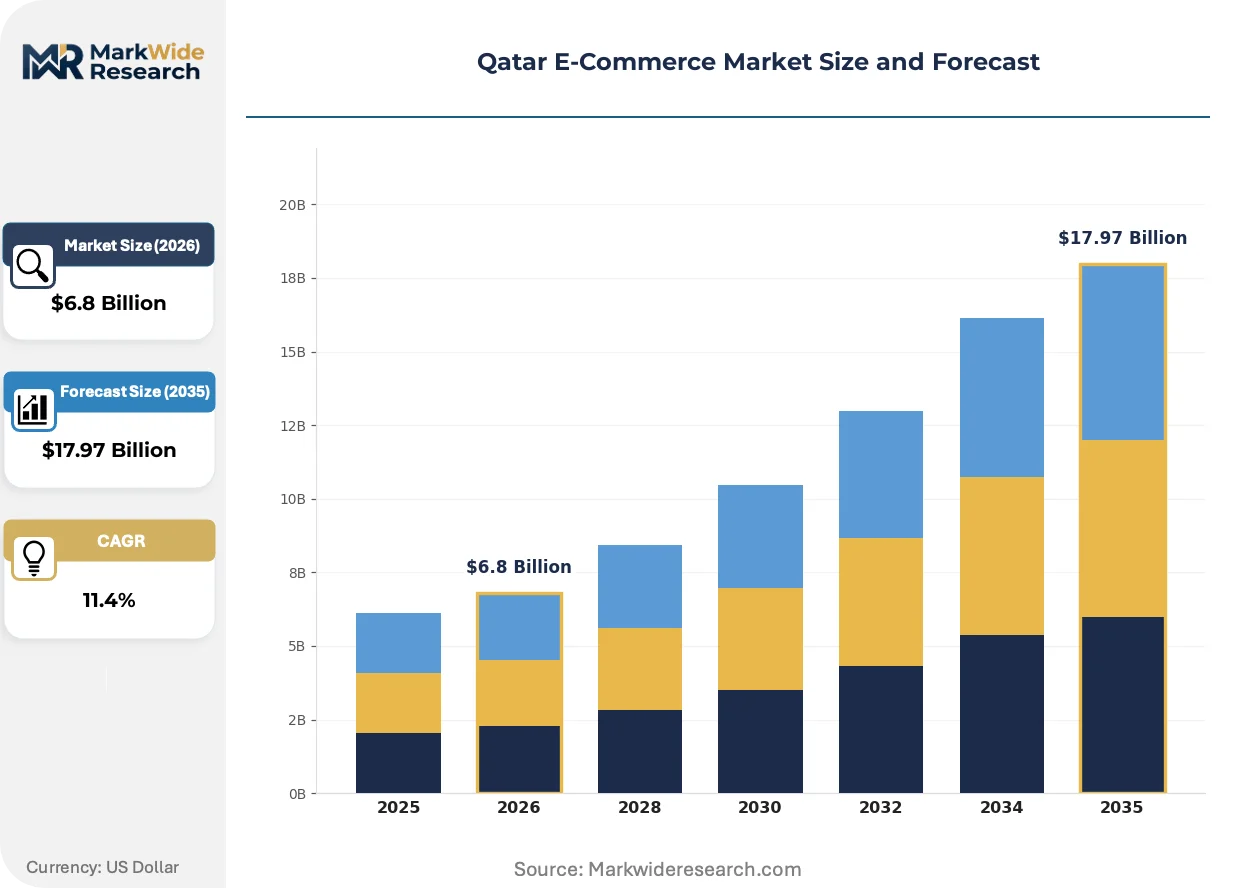
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Beauty, Home Goods Payment Method: Credit Cards, Mobile Wallets, Bank Transfers, Cash on Delivery Customer Type: Individuals, Small Businesses, Corporates, Startups Sales Channel: Online Marketplaces, Brand Websites, Social Commerce, Direct Sales |
| Companies Covered | Talabat.com, Snoonu, Amazon.com, Inc., Al Anees Electronics, Noon, Carrefour Qatar, AliExpress.com, Jazp.com, Lulu Hypermarket, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar E-Commerce Market Strategic Shifts
Platform economics in Qatar are pivoting from transaction fee extraction toward embedded financial services and logistics monetization, compressing the traditional marketplace model into vertically integrated retail stacks.
Real-time inventory APIs are consolidating operational visibility across fragmented seller bases. Mid-sized fashion merchants in Doha's wholesale districts adopt cloud-based stock synchronization to prevent overselling on multi-channel listings. This consolidation eliminates manual reconciliation delays that previously drove cancellation rates above regional benchmarks.
Qatar Central Bank's fintech licensing regime tightens capital adequacy requirements for payment aggregators, elevating compliance costs for unlicensed wallet operators. Domestic platforms accelerate partnerships with licensed banks to maintain transaction processing continuity. Electronics and high-value goods categories face heightened scrutiny under enhanced know-your-customer protocols.
Buyer behavior is fragmenting across discovery channels, with product research originating on social platforms before converting through native checkout experiences. Traditional marketplace search is losing share to algorithmic feeds on TikTok and Instagram. Young professionals in Lusail and Education City exhibit the strongest channel-switching velocity, completing purchases within single-session mobile journeys.
Qatar E-Commerce Market Segmentation
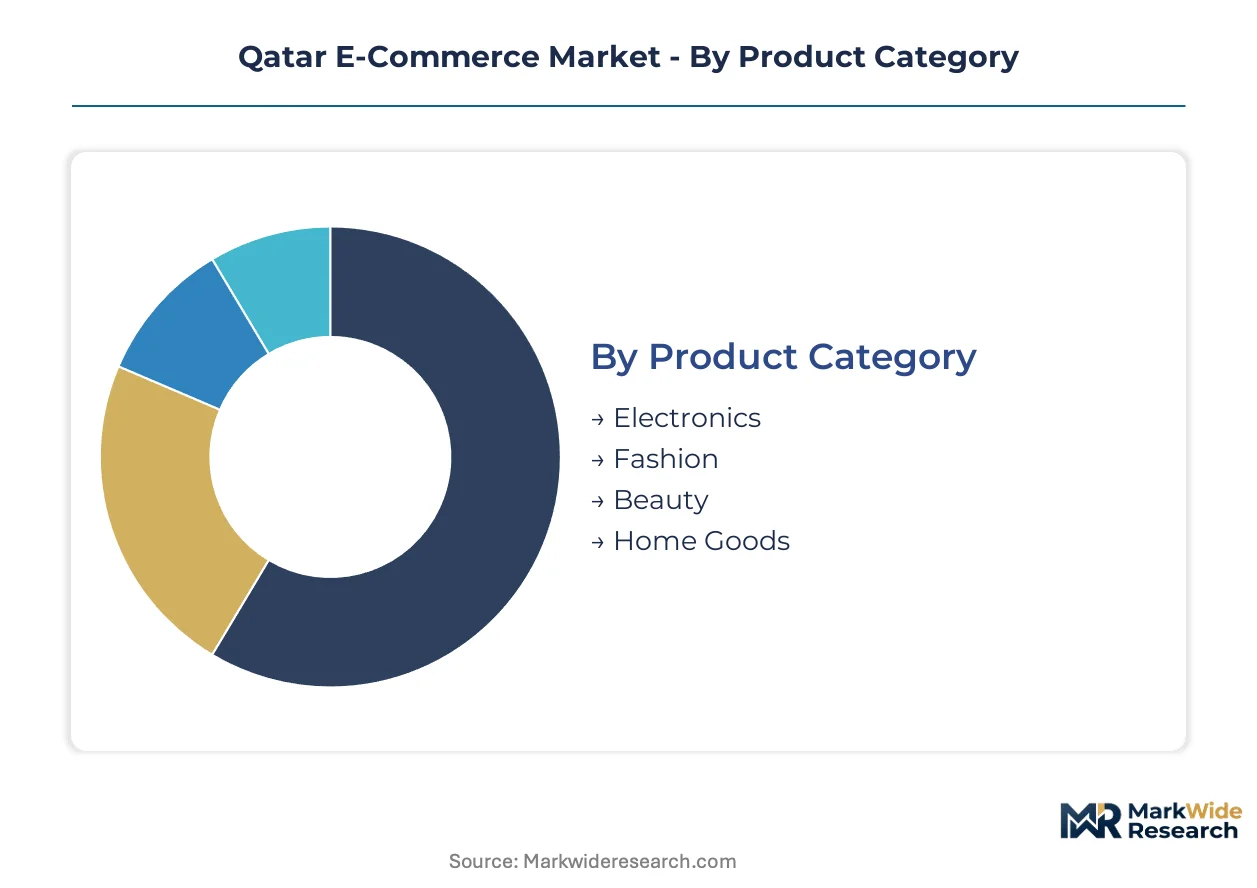
Qatar's e-commerce architecture fragments across four operational dimensions that determine platform investment priorities and margin structures. Each segmentation layer reveals distinct capital requirements, regulatory exposure, and customer acquisition economics that shape competitive positioning.
Product Category:
Electronics and fashion command the heaviest upfront inventory investment, locking working capital in import-dependent supply chains with extended procurement cycles.
- Electronics:High-value consumer devices and computing equipment dominate transaction value pools. Demand concentrates among young professionals in Lusail and West Bay, driven by frequent device refresh cycles and limited domestic manufacturing capacity that necessitates UAE-hub fulfillment.
- Fashion:Apparel and accessories leverage social discovery channels with rapid inventory turnover. Micro-brands targeting Gulf Cooperation Council consumers through Instagram and TikTok-native onboarding are capturing volume from traditional marketplace fee structures.
- Beauty:Cosmetics and personal care products require specialized cold-chain logistics for premium skincare formulations.
- Home Goods:Furniture and household furnishings face elongated delivery windows due to bulky last-mile handling constraints.
Electronics absorbs the bulk of installed capacity; fashion is expanding most quickly.
Payment Method:
Settlement infrastructure investments vary sharply by channel, with mobile wallets demanding the deepest technical integration with Qatar Central Bank protocols.
- Credit Cards:Traditional card networks remain dominant for high-value electronics purchases. Corporate procurement and affluent individual segments in The Pearl and Education City sustain this channel despite interchange fee compression.
- Mobile Wallets:Qatar Central Bank's licensed digital wallet framework is compressing settlement timelines from batch to real-time clearing. Young professionals and tech-native consumers are migrating fastest to Apple Pay and local licensed aggregators.
- Bank Transfers:Direct debit arrangements persist for B2B transactions and large-ticket corporate purchases.
- Cash on Delivery:Migrant worker segments without residency-linked banking access maintain this channel, inflating return-to-origin rates and logistics cost structures for platforms serving industrial zone labor camps.
Credit cards retain the largest transaction volume; mobile wallets are gaining share fastest.
Customer Type:
Acquisition costs and lifetime value calculations diverge substantially across buyer organizational forms, with corporates demanding bespoke procurement portals.
- Individuals:Mobile-native consumers drive frequency in grocery and fashion verticals. Same-day delivery expectations from Doha's expatriate workforce concentrate purchasing power in platform apps with captive logistics networks.
- Small Businesses:Procurement digitization among retail and hospitality operators creates bulk replenishment demand. Dark-store infrastructure in Al Sadd micro-fulfillment zones serves this segment with compressed delivery windows.
- Corporates:Enterprise procurement requires API integration with legacy ERP systems, creating phantom stock synchronization challenges.
- Startups:Early-stage ventures exhibit high channel-switching velocity and price sensitivity.
Individuals generate the highest transaction frequency; small businesses show the steepest expansion trajectory.
Sales Channel:
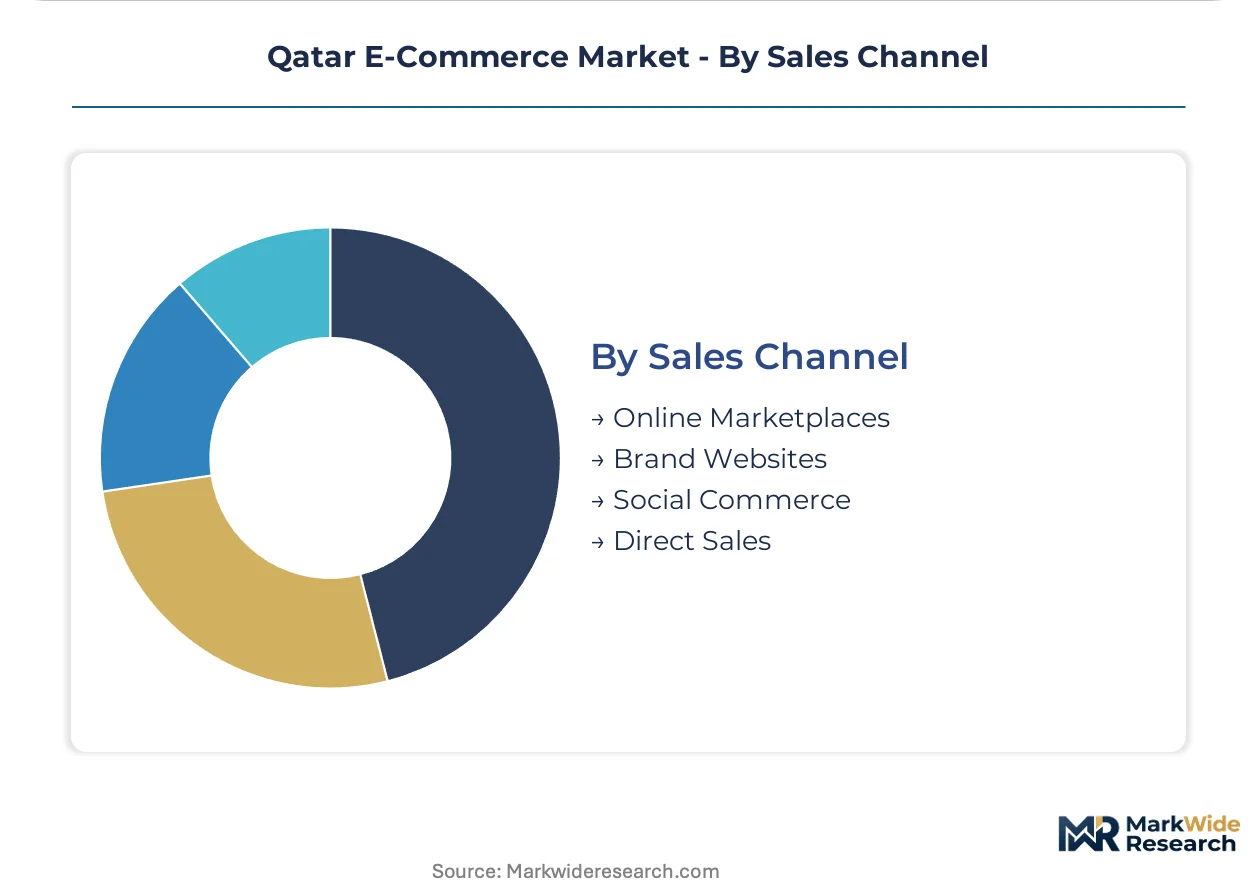
Platform development costs scale with integration complexity, from lightweight social storefronts to full-stack marketplace architectures.
- Online Marketplaces:Aggregator platforms with multi-seller infrastructure require substantial investment in real-time inventory APIs and dispute resolution architectures. Electronics and fashion verticals concentrate here due to discovery efficiency and trust infrastructure.
- Brand Websites:Direct-to-consumer channels bypass marketplace fee extraction. Premium beauty and electronics brands in Lusail are investing in proprietary fulfillment to capture margin and customer data.
- Social Commerce:Algorithmic feeds on TikTok and Instagram are displacing traditional search-based discovery. Fashion micro-brands leverage native checkout experiences to complete purchases within single-session mobile journeys.
- Direct Sales:B2B procurement portals and corporate account management sustain this channel for bulk household and office supply replenishment.
Online marketplaces capture the majority of transaction volume; social commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in Doha concentrate purchasing power in mobile-native channels, driving same-day delivery demand across grocery and electronics categories. Qatar Central Bank's digital wallet licensing framework accelerates fintech onboarding, compressing settlement infrastructure timelines. The analysis examines five key sub-regions within Qatar.
Doha Metropolitan Area
Expatriate workforce clusters in West Bay and Al Sadd drive frequency in fashion and electronics verticals. Qatar Central Bank's regulatory sandbox reduces merchant integration cycles for licensed payment aggregators. Dark-store infrastructure in Al Sadd micro-fulfillment zones compresses last-mile delivery windows to under thirty minutes.
Lusail Development
Education City and residential towers attract tech-native consumers with high channel-switching velocity. The Ministry of Commerce and Industry enforces consumer protection mandates that shape return policies across domestic operators. Premium beauty and electronics brands invest in proprietary fulfillment to capture margin and customer data.
The Pearl-Qatar
Affluent individual segments sustain credit card dominance for high-value electronics purchases. Qatar Communications Regulatory Authority cybersecurity standards determine platform compliance burdens for market entry. Corporate procurement and luxury retail concentrate in this artificial island development.
Al Wakrah and Industrial Corridor
Migrant worker segments without residency-linked banking access maintain cash-on-delivery channels. Unclear mandates from the Qatar Communications Regulatory Authority on server location requirements create compliance uncertainty. Industrial zone labor camps inflate return-to-origin rates and logistics cost structures for platforms.
Al Khor and Northern Municipalities
Small business procurement digitization among retail and hospitality operators creates bulk replenishment demand. Qatar Central Bank's fintech licensing regime tightens capital adequacy requirements for payment aggregators. Hyperlocal fulfillment nodes serve household replenishment with compressed delivery windows.
Qatar E-Commerce Market Competitive Environment
Strategic partnerships dominate the current landscape as platforms rebuild payment architectures around real-time clearing protocols. The vendor base clusters around three archetypes: captive logistics networks, cross-border fulfillment anchors, and hyperlocal speed specialists. Consolidation pressures intensify as mobile wallet penetration deepens. M&A activity and technology licensing agreements represent the dominant competitive moves.
Among Gulf Cooperation Council-based operators, Talabat.com and Snoonu exemplify the captive logistics archetype, while Amazon.com, Inc. anchors cross-border fulfillment capacity through UAE hub operations. These three companies occupy distinct positioning vectors—same-day delivery dominance, hyperlocal speed, and regional hub economics—reflecting the market's segmentation across food, grocery, and general merchandise verticals.
| Leading Market Players |
|---|
| Talabat.com |
| Snoonu |
| Amazon.com, Inc. |
| Al Anees Electronics |
| Noon |
| Carrefour Qatar |
| AliExpress.com |
| Jazp.com |
| Lulu Hypermarket |
| Others |
Value Chain & Pricing Dynamics
Sovereign wealth-backed logistics operators and family-owned retail conglomerates anchor Qatar's e-commerce infrastructure, compressing procurement timelines through captive fulfillment networks while maintaining pricing discipline via exclusive distribution arrangements with UAE and Far East manufacturing clusters.
Pricing Analysis
Volume pools concentrate in mass-market electronics and fast fashion where per-unit margins compress under import duty exposure and last-mile cost inflation, while premium beauty and high-value computing equipment sustain markup structures through brand exclusivity and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with young professionals in Lusail and Education City exhibiting lowest price sensitivity for convenience-positioned offerings. Cost compression in economy-tier household replenishment is intensifying because dark-store operators compete on hyperlocal speed rather than product margin. Migrant worker segments in industrial zones demonstrate highest price elasticity, driving cash-on-delivery preference that inflates logistics overhead and erodes platform net revenue per transaction.
Supply Chain Analysis
Dual-sourcing mandates from Qatar Central Bank's fintech licensing regime force payment aggregators to maintain redundant banking partnerships, while marketplace operators qualify multiple logistics providers to mitigate single-point failure in last-mile fulfillment. Electronics inventory draws from China, South Korea, and Vietnam manufacturing hubs, with fashion apparel sourcing from Bangladesh, Turkey, and India textile clusters. Semiconductor components, lithium-ion cells, and premium packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in UAE-hub cross-border fulfillment where Red Sea shipping volatility and Hamad Port customs clearance bottlenecks extend procurement cycles. Distribution runs through captive fleet networks for grocery and perishables, while third-party logistics handles bulky home goods and cross-border general merchandise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's e-commerce landscape is consolidating into vertically integrated retail stacks where control over captive logistics and licensed payment infrastructure determines competitive survival. Players are racing to own hyperlocal fulfillment nodes and real-time settlement protocols as the decisive downstream levers.
For Market Incumbents: Acquire dark-store real estate in Al Sadd and West Bay micro-fulfillment zones to compress delivery windows below thirty minutes and defend against Snoonu's hyperlocal speed positioning. License payment aggregator status under Qatar Central Bank's regulatory sandbox before capital adequacy requirements tighten further, eliminating unlicensed wallet operators from the competitive set. Integrate real-time inventory APIs with legacy ERP systems at traditional retailers to eliminate phantom stock situations that drive cancellation penalties.
For New Entrants and Emerging Players: The gap between premium same-day delivery and economy-tier next-day fulfillment in northern municipalities and industrial corridor labor camps offers white-space entry with localized cash-handling infrastructure. Target migrant worker segments in Al Wakrah with Arabic-language interfaces and cash-on-delivery optimization to capture volume abandoned by platforms pursuing digital-wallet-only strategies. Partner with established logistics networks rather than building captive fleets to minimize fixed-cost exposure in low-margin household replenishment categories.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap marketplace operators with licensed payment infrastructure and existing Qatar Communications Regulatory Authority cybersecurity certification in Doha metropolitan area and Lusail development corridors. Long-term viability hinges on backward integration into fulfillment real estate and forward integration into embedded financial services rather than pure transaction fee extraction. Watch Qatar Central Bank's cross-border data localization rulings as the signal for international platform expansion feasibility and compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Captive micro-fulfillment nodes in Al Sadd compress delivery windows under Qatar Central Bank's real-time settlement protocols. |
| Payment Aggregator Licensing | Qatar Central Bank's fintech sandbox reduces merchant onboarding cycles while tightening capital adequacy requirements for unlicensed operators. |
| Social Commerce Platform Integration | Native checkout experiences on TikTok and Instagram bypass traditional marketplace fee structures for fashion micro-brands targeting Gulf Cooperation Council consumers. |
| Real-Time Inventory API Deployment | Cloud-based stock synchronization prevents overselling on multi-channel listings and eliminates manual reconciliation delays. |
| Cybersecurity Certification Investment | Qatar Communications Regulatory Authority penetration testing compliance accelerates platform launch schedules for cross-border operators. |
Study Parameters
Multi-period observation of mobile wallet penetration rates, dark-store deployment timelines, and social commerce transaction flows anchored the trend analysis, supplemented by interviews with platform operations executives, fintech licensing specialists, logistics fleet managers, and consumer protection officers at the Ministry of Commerce and Industry. Secondary validation drew from Qatar Central Bank regulatory filings, Qatar Communications Regulatory Authority cybersecurity standards documentation, customs clearance data at Hamad Port, and marketplace operator disclosures. Bottom-up seller-base enumeration triangulated against top-down household expenditure surveys to constrain total addressable market estimates.
Input-output matrix framing connected payment method adoption curves to fulfillment infrastructure capacity constraints across product category segments. The analytical framework modeled electronics, fashion, beauty, and home goods verticals alongside customer type, sales channel, and regional sub-market dimensions throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to mobile wallet transaction data and same-day delivery frequency benchmarks. Forecast inputs included Qatar Central Bank licensing throughput rates and Red Sea shipping lane reliability indices.
Inputs from platform operator disclosures and regulatory filing databases were available through the study window; gaps in real-time social commerce transaction data and cash-on-delivery return-rate reporting introduce uncertainty bands around segment-level estimates. Deviation in Qatar Central Bank's cross-border data localization mandates or Red Sea logistics chokepoint severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market