
 Pharmaceutical E-Commerce Market | 2026-2036
Pharmaceutical E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical E-Commerce Market Analytics
FDA's Drug Supply Chain Security Act is shifting the cost-of-entry calculus for online pharmacies by mandating unit-level traceability. CVS Health leverages its PBM infrastructure to sustain end-to-end prescription verification. Amazon Pharmacy competes through same-day delivery density in metropolitan corridors. DocMorris anchors cross-border fulfillment within the European Economic Area.
Pharmaceutical E-Commerce denotes the digital sale and distribution of prescription and non-prescription medicinal products through verified online platforms, requiring cold-chain logistics for biologics and tamper-evident packaging for controlled substances. Its primary purpose is to reduce patient friction in medication access while maintaining chain-of-custody documentation. Prescription Drugs generate the dominant revenue pool due to recurring refill economics, while Over-the-Counter Products carry higher per-unit margins through impulse-driven digital merchandising. Third-Party Platforms attract the fastest traffic growth by aggregating multiple pharmacy inventories, though Hospital Pharmacies retain institutional purchasing power through group purchasing organization contracts.
FDA, EMA, and India's CDSCO enforce divergent serialization and patient-data protocols that fragment platform compliance architecture. HIPAA in the United States and GDPR in Europe impose contradictory consent frameworks for prescription history targeting. Stakeholders must monitor whether regulator harmonization around digital pharmacy licensure emerges faster than platform technology can adapt to patchwork requirements.
Market Dynamics
Telehealth-integrated e-prescribing is collapsing the traditional pharmacy visit into a single digital workflow, redirecting fulfillment volume toward platforms capable of real-time insurance verification and same-day logistics.
Growth Catalysts
- Chronic disease refill automation:Diabetes and hypertension patients in the United States generate recurring prescription volumes that digital pharmacies capture through auto-refill algorithms and adherence monitoring.
- GDPR-compliant data portability:European patients exercising data-transfer rights under GDPR Article 20 are migrating prescription histories between platforms, reducing switching friction and expanding addressable user bases.
- Cold-chain biologics expansion:Temperature-controlled last-mile infrastructure originally built for vaccine distribution is now repurposed for monoclonal antibody home delivery, opening high-margin therapeutic categories.
Market Restraints
- FDA DSCSA unit-level serialization:The Drug Supply Chain Security Act mandates interoperable track-and-trace systems by 2024, forcing smaller online pharmacies into costly compliance infrastructure or exit.
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces create geographic single-point-of-failure risk for generic e-commerce fulfillment.
- Controlled substance custody documentation:DEA regulations require tamper-evident packaging and signature verification for Schedule II-V drugs, adding per-unit handling costs that erode margin on low-value prescriptions.
Strategic Opportunities
- Rural India broadband penetration:The BharatNet fiber expansion into 600,000 villages creates first-time digital pharmacy access for populations previously dependent on distant brick-and-mortar dispensaries.
- Remote patient monitoring convergence:Integration of continuous glucose monitors with automatic insulin refill APIs enables closed-loop chronic disease management platforms.
- German digital health app reimbursement:Germany's DiGA fast-track approval pathway reimburses prescription-integrated wellness applications, creating bundled pharmacy-service revenue streams.
Industry Challenges
- Pharmacist verification bandwidth:State-level telepharmacy regulations in the United States require licensed pharmacists to review every e-prescription, creating human capital bottlenecks during peak refill windows.
- Legacy ERP integration:Hospital pharmacy systems running on 1990s-era inventory platforms require expensive middleware development to synchronize with third-party e-commerce frontends.
- Cross-border customs classification:Temperature-sensitive biologics shipped from Swissmedic-authorized facilities face inconsistent tariff coding at EU entry points, delaying patient delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical E-Commerce Market |
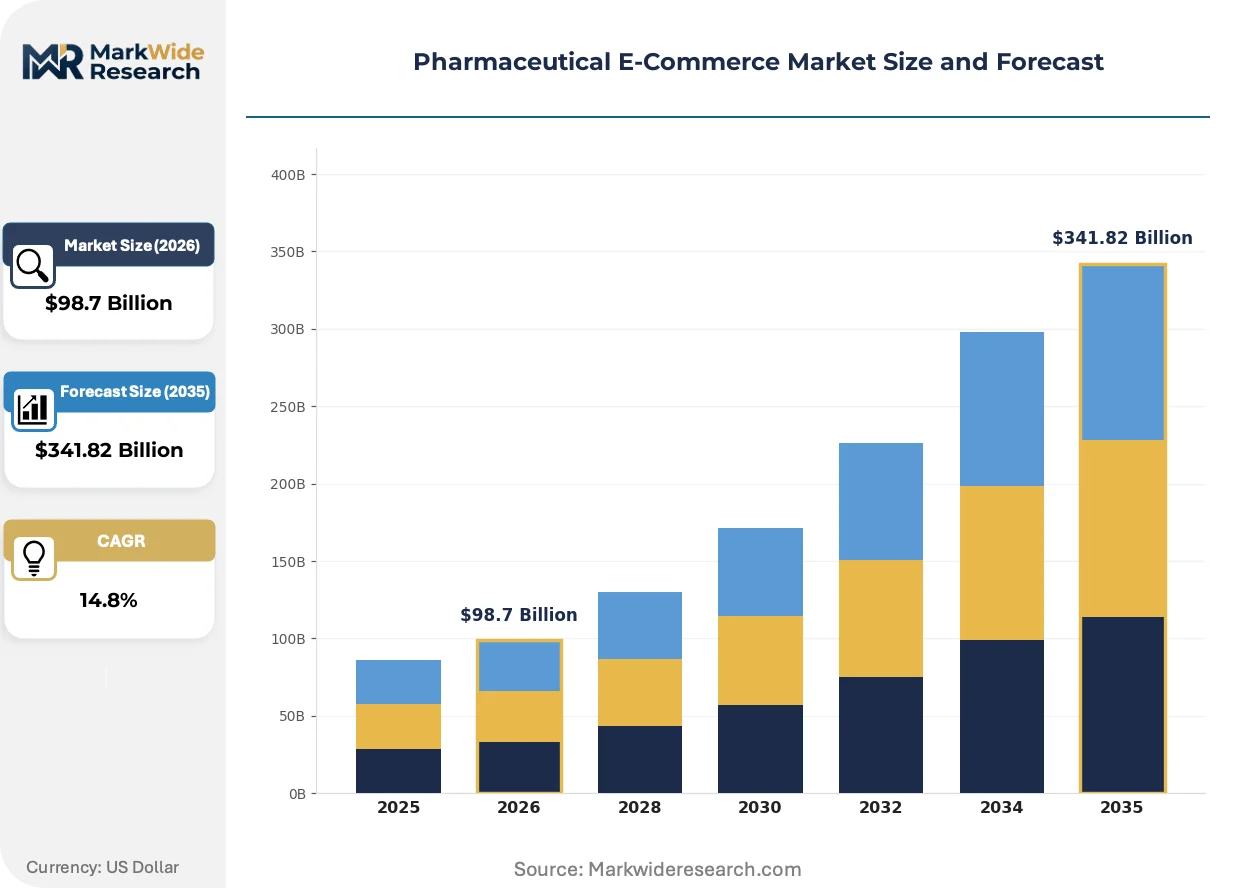
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $341.82 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Products, Vitamins & Supplements, Herbal Remedies Sales Channel: Direct-to-Consumer, Third-Party Platforms, Hospital Pharmacies, Retail Pharmacies Payment Method: Credit/Debit Cards, Digital Wallets, Bank Transfers, Cash on Delivery Customer Type: Individuals, Healthcare Providers, Pharmacies, Institutions |
| Companies Covered | CVS Health, Walgreens Boots Alliance, Amazon Pharmacy, Walmart Inc., Express Scripts, DocMorris, OptumRx, Giant Eagle, Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical E-Commerce Market Evolving Landscape
Artificial intelligence is penetrating pharmaceutical logistics at the warehouse and patient interface simultaneously, compressing fulfillment timelines while personalizing medication adherence interventions.
Blockchain-based serialization infrastructure is absorbing verification workload from human pharmacists and customs inspectors alike. European wholesalers adopting MediLedger protocols are reducing counterfeit detection time from days to minutes. This compression is absorbing compliance labor costs while enabling real-time cross-border shipment clearance.
The FDA's finalized guidance on distributed manufacturing permits 3D-printed dosage form production at hospital-affiliated pharmacies, bypassing centralized compounding facilities. This regulatory opening is fragmenting production geography and shortening supply chains for personalized medicine. Oncology centers in the United States are piloting on-demand tablet production for narrow therapeutic index drugs.
Subscription-based medication procurement is displacing per-transaction purchasing among chronic disease cohorts. Auto-ship algorithms tied to insurance renewal cycles are capturing patient lifetime value previously distributed across multiple retail touchpoints. This behavioral shift concentrates fulfillment volume with platforms possessing sophisticated predictive analytics capabilities, visible most acutely in United States Medicare Part D populations.
Pharmaceutical E-Commerce Market Segmentation
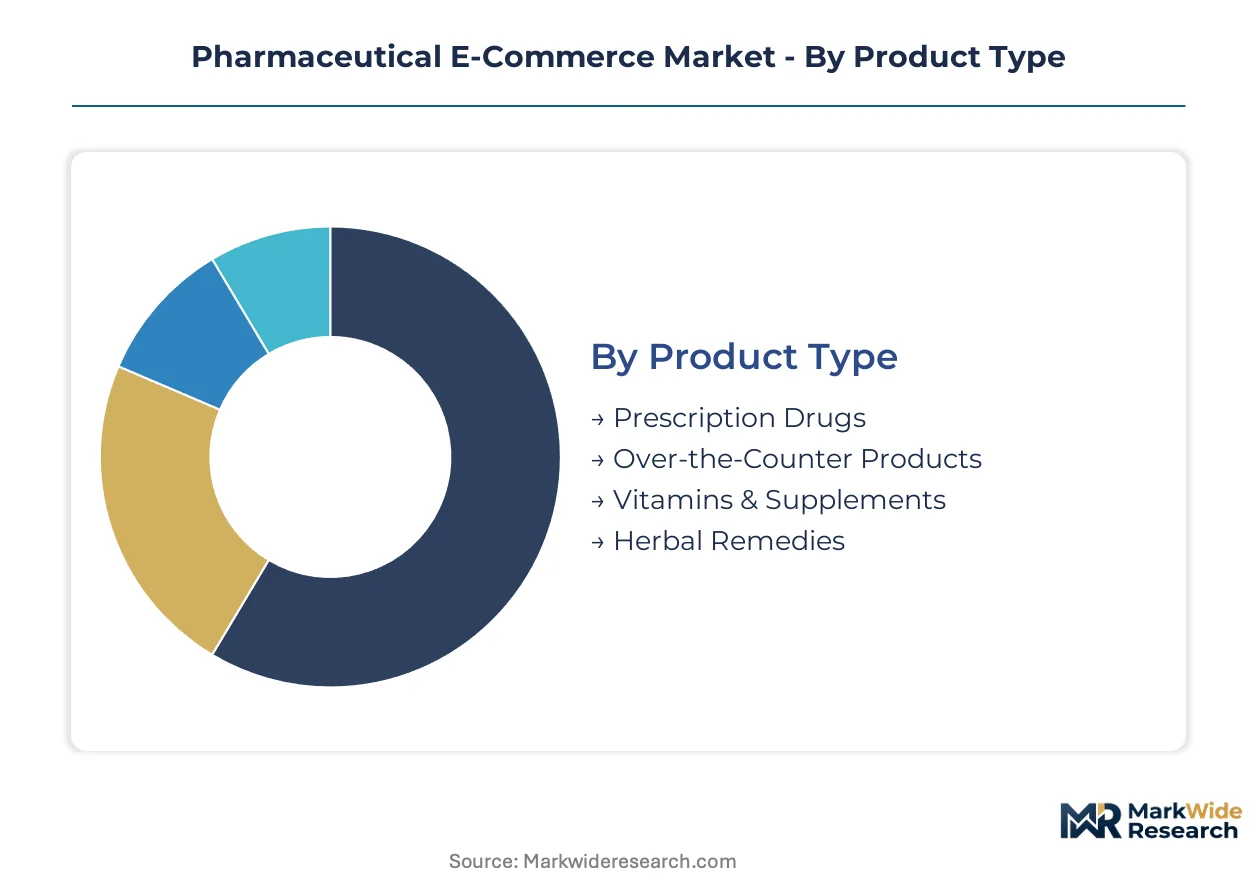
Pharmaceutical E-Commerce segmentation reveals how fulfillment economics and regulatory custody requirements fragment platform architectures. Each category maps distinct margin profiles against compliance infrastructure investments, separating scalable digital operators from legacy dispensary networks.
Product Type:
Supply concentration in cold-chain biologics and controlled substance handling creates divergent platform capabilities across therapeutic categories.
- Prescription Drugs:Unit-dose packaging with tamper-evident seals and chain-of-custody documentation satisfies DEA Schedule II-V requirements. Demand concentrates in United States Medicare Part D populations where auto-refill algorithms capture recurring hypertension and diabetes volumes.
- Over-the-Counter Products:Impulse-driven digital merchandising of analgesics and antihistamines carries higher per-unit margins through bundle pricing and subscription conversion. European platforms leverage GDPR Article 20 data portability to migrate purchase histories and reduce switching friction.
- Vitamins & Supplements:Nutraceutical fulfillment bypasses prescription verification bottlenecks, enabling same-day delivery density in metropolitan corridors without pharmacist review requirements.
- Herbal Remedies:Ayurvedic and traditional medicine categories in India face CDSCO quality certification requirements that filter uncertified sellers from platform listings.
Today's leader: Prescription Drugs. Tomorrow's challenger: Over-the-Counter Products.
Sales Channel:
Cost tier separation distinguishes capital-intensive logistics operators from lightweight marketplace aggregators.
- Direct-to-Consumer:Manufacturer-owned portals bypass intermediary margins but require captive cold-chain infrastructure for biologics. United States specialty pharmacy operators dominate oncology and rare disease categories.
- Third-Party Platforms:Inventory aggregation across multiple pharmacy networks attracts fastest traffic growth through price transparency engines. German platforms leverage DiGA reimbursement pathways to bundle prescription-integrated wellness applications.
- Hospital Pharmacies:Group purchasing organization contracts retain institutional purchasing power for inpatient discharge medications and 340B eligible prescriptions.
- Retail Pharmacies:Brick-and-mortar networks with digital frontends exploit existing DEA registrations and state licensure for controlled substance legitimacy.
Volume concentrates with Third-Party Platforms. Margin protection favors Hospital Pharmacies.
Payment Method:
Customer type and geography determine payment infrastructure requirements, with cash-preferred segments demanding distinct fulfillment verification.
- Credit/Debit Cards:Real-time insurance co-pay processing dominates United States transactions, requiring PCI-DSS compliance and HSA/FSA eligibility verification at checkout.
- Digital Wallets:UPI integration in India and Alipay penetration in China enable low-friction recurring payments for chronic disease refill automation.
- Bank Transfers:SEPA direct debit predominates in German prescription fulfillment, aligning with statutory health insurance reimbursement cycles.
- Cash on Delivery:Rural India broadband expansion through BharatNet creates first-time digital pharmacy access where banking penetration lags smartphone adoption.
Dominant today: Credit/Debit Cards. Expanding most quickly: Digital Wallets.
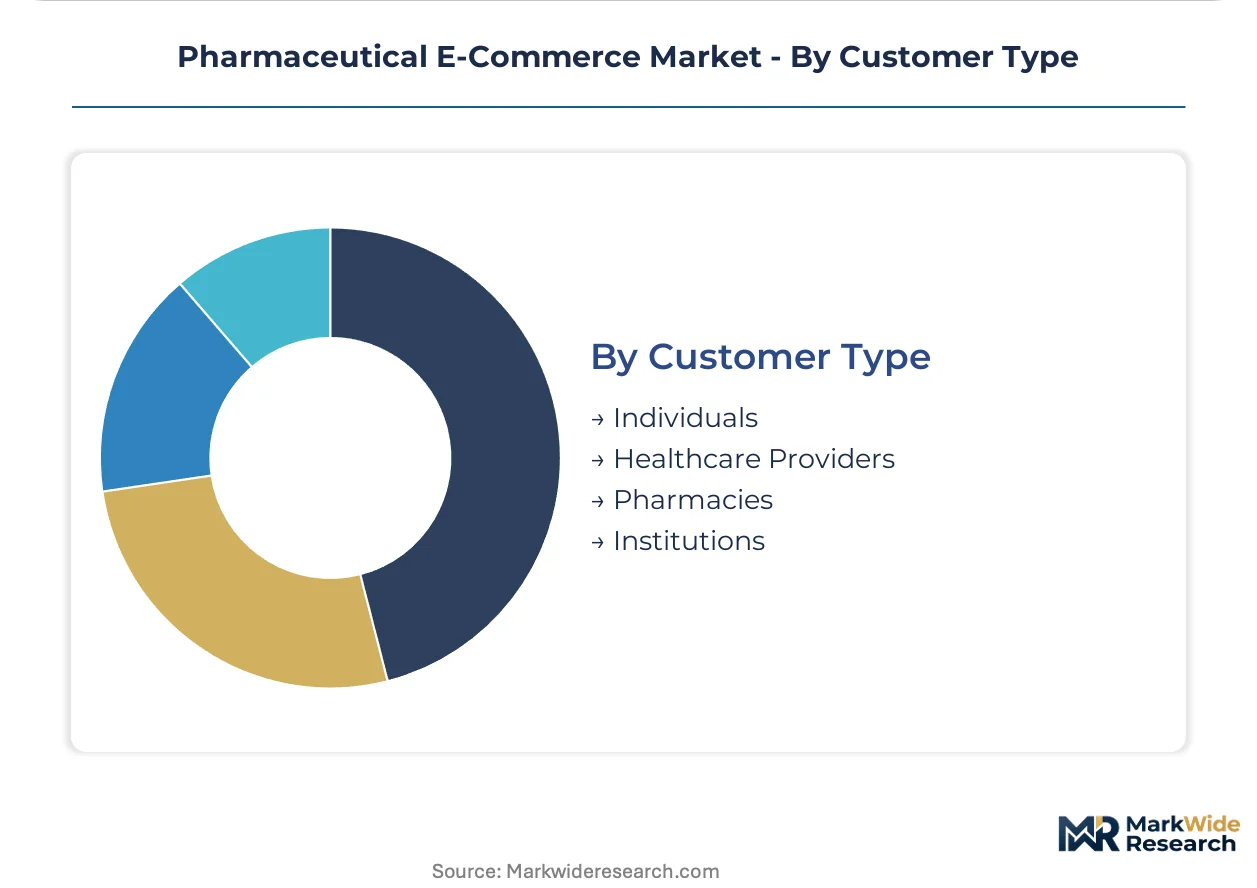
Customer Type:
Maturity differentiation separates individual chronic disease management from institutional procurement workflows.
- Individuals:Patient-directed ordering of maintenance medications drives subscription-based procurement displacement, with auto-ship algorithms capturing lifetime value previously distributed across retail touchpoints.
- Healthcare Providers:E-prescribing integration with telehealth platforms redirects fulfillment volume toward operators capable of real-time eligibility verification and same-day logistics.
- Pharmacies:Independent dispensaries utilize third-party platform infrastructure to access national inventory pools without proprietary technology investment.
- Institutions:Nursing homes and correctional facilities require bulk packaging and extended-dating inventory management distinct from unit-dose retail fulfillment.
Current anchor: Individuals. Emerging volume: Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pharmaceutical e-commerce sector traces its commercial lineage to United States mail-order pharmacy expansion during the 1990s, when PBMs first digitized prescription fulfillment at scale. Digital pharmacy infrastructure subsequently diffused through German statutory health insurance networks and India's urban corridor expansion.
United States
Medicare Part D auto-refill algorithms and chronic disease management platforms drive prescription volume concentration. FDA DSCSA unit-level serialization mandates reshape compliance infrastructure for online dispensaries. The Philadelphia-Camden corridor anchors PBM-operated fulfillment centers serving northeastern metropolitan density.
Germany
Statutory health insurance reimbursement cycles and DiGA fast-track approval for prescription-integrated wellness applications expand addressable digital pharmacy services. EMA serialization protocols align with national pharmacy licensure requirements. The Cologne-Düsseldorf-Ruhr cluster concentrates third-party platform headquarters and cross-border fulfillment coordination.
India
BharatNet fiber expansion into 600,000 villages creates first-time digital pharmacy access for previously underserved rural populations. CDSCO quality certification requirements filter uncertified Ayurvedic sellers from platform listings. The Mumbai-Pune corridor hosts inventory aggregation platforms serving western India demand concentration.
United Kingdom
NHS e-prescription rollout and pharmacy-first service models redirect primary care medication fulfillment toward digital channels. GDPR Article 20 data portability reduces patient switching friction between competing platforms. The Greater London area dominates same-day delivery density and cold-chain logistics infrastructure deployment.
Switzerland
Swissmedic-authorized biologics manufacturing and precision medicine specialization create high-value cross-border shipment corridors into EU markets. Temperature-controlled customs classification protocols at Basel and Geneva entry points influence delivery timeline reliability. The Basel-Zurich corridor anchors specialty pharmacy distribution for monoclonal antibody therapies.
Pharmaceutical E-Commerce Market Competitive Landscape
The competitive structure tilts toward vertically integrated healthcare conglomerates with captive PBM infrastructure. Market concentration reflects regulatory barriers to DEA registration and state-level pharmacy licensure that favor incumbents with existing compliance architecture. Two strategic archetypes dominate: pharmacy-retail hybrids leveraging brick-and-mortar footprints for same-day fulfillment, and technology-native platforms optimizing metropolitan delivery density. Competitive moves center on telehealth integration partnerships and cold-chain capacity expansion for biologics.
Within the pharmacy-retail hybrid tier, CVS Health and Walgreens Boots Alliance occupy positions defined by PBM-captive prescription volumes and existing DEA registration portfolios. Amazon Pharmacy exemplifies the technology-native archetype, anchoring metropolitan same-day delivery density without legacy retail footprint dependency. DocMorris represents cross-border specialization within European Economic Area regulatory harmonization.
| Leading Market Players |
|---|
| CVS Health |
| Walgreens Boots Alliance |
| Amazon Pharmacy |
| Walmart Inc. |
| Express Scripts |
| DocMorris |
| OptumRx |
| Giant Eagle, Inc. |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Telehealth-integrated e-prescribing is collapsing fulfillment workflows into unified digital platforms, simultaneously compressing per-transaction costs and concentrating volume with operators possessing real-time insurance verification infrastructure. This technological shift rewards scaled players with captive PBM networks while marginalizing smaller dispensaries lacking automated prior authorization capabilities.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning in pharmaceutical e-commerce. Subscription-based auto-refill models dominate chronic disease categories, capturing patient lifetime value through adherence algorithms tied to Medicare Part D cycles. Price differentiation hinges on cold-chain certification tier and same-day delivery density in metropolitan corridors. Cost compression in generic fulfillment is intensifying because Amazon Pharmacy and technology-native platforms exploit metropolitan logistics networks without legacy retail overhead. Individual chronic disease patients exhibit highest price sensitivity, while hospital systems and nursing homes prioritize custody documentation and formulary compliance over unit cost.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on manufacturing clusters in Zhejiang and Jiangsu provinces of China, with secondary concentration in Indian API producers at Hyderabad and Ahmedabad. Cold-chain biologics hinge on temperature-controlled last-mile infrastructure originally built for vaccine distribution, now repurposed for monoclonal antibody home delivery. Single-source vulnerability in Chinese API production creates geographic concentration risk for generic e-commerce fulfillment. Distribution runs through PBM-operated fulfillment centers in the Philadelphia-Camden corridor and third-party platform aggregation hubs in the Cologne-Düsseldorf-Ruhr cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical e-commerce functions as a stable compounder, with chronic disease refill automation generating recurring revenue pools that resist economic cyclicality. The underlying demand for maintenance medications creates predictable cash flow characteristics attractive to long-term capital deployment.
For Market Incumbents: To counter technology-native platforms exploiting metropolitan delivery density without legacy retail overhead, CVS Health and Walgreens Boots Alliance must deepen backward integration into specialty pharmacy distribution and expand cold-chain capacity for biologics. DEA registration portfolios and existing state licensure provide defensive moats, but automation investment in pharmacist verification workflows remains essential to address human capital bottlenecks during peak refill windows.
For New Entrants and Emerging Players: Capture underserved rural demand in India where BharatNet fiber expansion creates first-time digital pharmacy access without incumbent retail presence. White-space opportunities concentrate in remote patient monitoring convergence, integrating continuous glucose monitors with automatic insulin refill APIs for closed-loop chronic disease management. A platform partnership with telehealth providers offers the most penetrable go-to-market angle, bypassing standalone customer acquisition costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent specialty pharmacy operators with captive cold-chain infrastructure but limited technology investment. Long-term viability over a five-to-ten year window favors platforms with integrated PBM relationships and Medicare Part D auto-refill algorithms. The signal to watch is regulator harmonization around digital pharmacy licensure, which would compress compliance costs and accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Temperature-controlled infrastructure for biologics opens high-margin therapeutic categories beyond traditional generic fulfillment. |
| Telehealth Platform Integration | E-prescribing partnerships redirect fulfillment volume toward operators with real-time insurance verification capabilities. |
| API Supply Diversification | Reducing concentration in Zhejiang and Jiangsu provinces mitigates geographic single-point-of-failure risk for generic fulfillment. |
| Subscription Model Deployment | Auto-ship algorithms capture patient lifetime value previously distributed across multiple retail touchpoints. |
| Blockchain Serialization Investment | MediLedger protocols reduce counterfeit detection time from days to minutes, absorbing compliance labor costs. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Switzerland, with primary inputs from each market informing cross-border pattern identification. The research combines structured interviews with pharmacy benefit managers, telehealth platform executives, cold-chain logistics operators, and regulatory affairs specialists with secondary validation through FDA DSCSA guidance documents, EMA serialization protocols, CDSCO quality certification requirements, and CMS Medicare Part D enrollment data. Bottom-up prescription volume modeling and top-down market sizing triangulate demand estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics and mix shifts across product type, sales channel, payment method, and customer type segmentation. The analytical framework incorporates patient population demographics, reimbursement cycle timing, and broadband penetration trajectories as industry-specific forecast inputs. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in comparable digital health categories.
Regulatory enforcement divergence, API supply disruption, and telehealth reimbursement policy shifts are the dominant revision risks to modeled projections. Forecasts reflect assumptions about licensure harmonization velocity and cold-chain infrastructure deployment timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market