
 China E-Commerce Market | 2026-2036
China E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
China E-Commerce Market Analysis
Live-stream product bundling is realigning how Chinese consumers discover and purchase goods across digital storefronts. Alibaba Group leverages its Taobao Live infrastructure to anchor seller-buyer engagement through real-time interactive formats. JD.com sustains competitive density by controlling its proprietary logistics network for bundled same-day delivery promises. Pinduoduo differentiates through group-buying configurations that collapse unit economics for price-sensitive buyers in county-level markets.
China E-Commerce denotes the digital exchange of goods and services conducted through internet-connected platforms, encompassing transaction processing, inventory synchronization, and last-mile fulfillment orchestration via automated sorting hubs and route-optimization algorithms. Its primary commercial purpose is to disintermediate traditional retail layers while capturing granular consumer behavioral data for demand forecasting. Electronics and home goods categories now lead transaction volume as replacement cycles compress for smartphones and smart appliances. Social commerce represents the fastest-expanding sales channel as Douyin and Xiaohongshu convert content engagement directly into closed-loop transactions. Mobile apps remain the dominant access layer, though drone delivery pilots signal emerging infrastructure bets for remote mountainous regions.
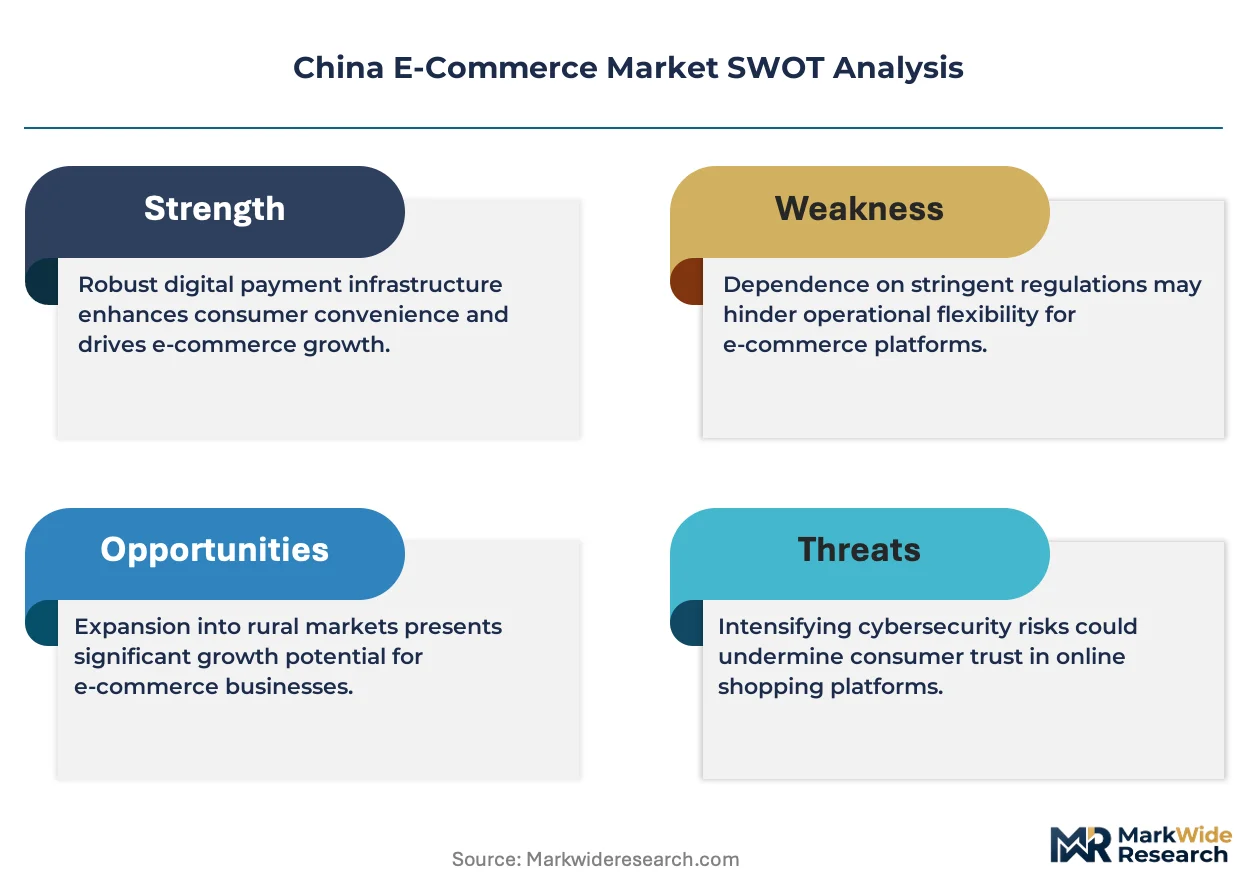
SAMR's anti-monopoly enforcement and data security mandates under China's Personal Information Protection Law constrain platform pricing algorithms and cross-border data flows. GB standards for live-streaming commerce quality disclosure impose product certification burdens on beauty and electronics sellers operating through KOL-hosted channels. Stakeholders must monitor regulatory tightening around algorithmic recommendation transparency while recalibrating fulfillment investments toward lower-tier city density.
Market Dynamics
SAMR's algorithmic transparency mandates are forcing platforms to restructure recommendation engines and seller ranking systems. Live-stream commerce infrastructure investments now dominate capital allocation as rural user acquisition costs fall below urban benchmarks.
Growth Catalysts
- MIIT rural broadband expansion:County-level 5G coverage enables real-time streaming commerce in previously underserved prefectures, collapsing delivery promise gaps between coastal and interior provinces.
- Smart appliance replacement cycles:IoT-enabled home devices drive recurring platform traffic as consumers purchase compatible peripherals and subscription services through integrated app ecosystems.
- Group-buying mechanics:Social裂变 models reduce per-unit logistics costs for agricultural produce, unlocking fresh food categories previously excluded from remote fulfillment economics.
Market Restraints
- Cross-border data localization:Personal Information Protection Law mandates domestic server storage, increasing compliance overhead for platforms with international cloud architectures.
- Beauty product certification backlog:NMPA registration queues for imported cosmetics extend seller onboarding timelines, constraining KOL-hosted category expansion.
- Last-mile labor cost inflation:Courier wage pressures in tier-one cities erode margin structures for same-day delivery promises without volume density offsets.
Strategic Opportunities
- Drone delivery corridors:Civil Aviation Administration pilot zones in Yunnan and Sichuan mountainous terrain enable 30-minute fulfillment to villages unreachable by ground transport.
- Carbon-neutral fulfillment mandates:Dual carbon goals incentivize electric vehicle fleet conversion and packaging material innovation, creating green premium positioning.
- AR-enabled virtual try-on:Convergence of spatial computing and payment systems reduces return rates for apparel categories, unlocking higher-margin fashion verticals.
Industry Challenges
- Live-stream host compliance training:GB standards for product disclosure require certified training programs, creating talent pipeline bottlenecks as qualified anchors command premium contracts.
- Legacy ERP integration:County-level distributors migrating from offline wholesale systems face data synchronization failures with platform APIs, delaying inventory visibility.
- Algorithm audit documentation:SAMR's explainability requirements demand engineering resources for real-time decision logging, diverting R&D capacity from recommendation optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China E-Commerce Market |
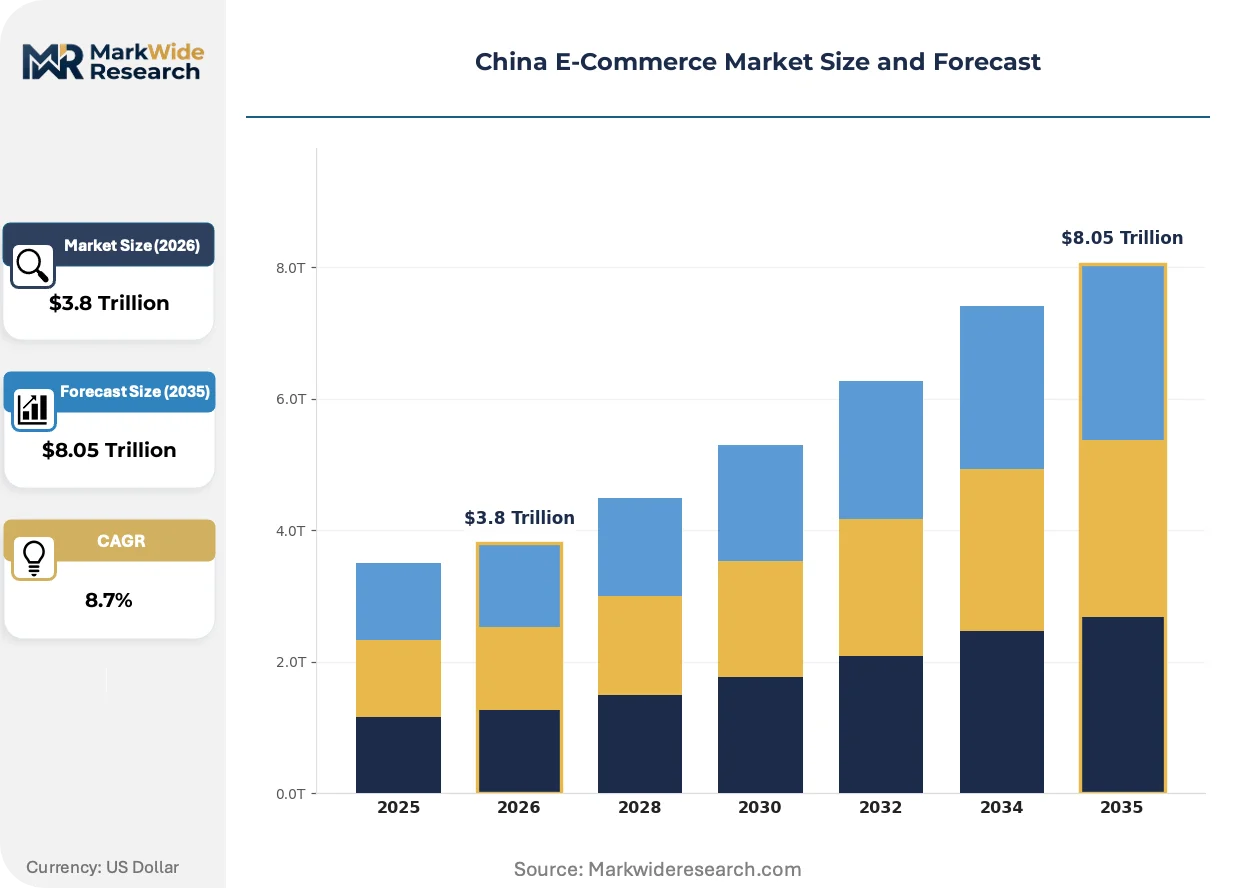
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $8.05 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Home Goods, Beauty Products Sales Channel: Mobile Apps, E-marketplaces, Brand Websites, Social Commerce Customer Type: Individuals, Small Businesses, Enterprises, Government Entities Delivery Mode: Same-day Delivery, Standard Shipping, In-store Pickup, Drone Delivery |
| Companies Covered | Alibaba Group, JD.com, Pinduoduo, Douyin, Xiaohongshu, Vipshop Holdings, Suning.com, Meituan, Shein, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China E-Commerce Market Emerging Trajectories
Platform infrastructure is pivoting toward immersive commerce formats that collapse discovery-to-purchase latency. Regulatory pressure on data governance and algorithmic accountability is reshaping technical architecture priorities.
Live-stream commerce is overtaking static storefront browsing as the primary product discovery mechanism. County-level consumers in Sichuan and Henan provinces now initiate purchases through KOL-hosted sessions at triple the rate of traditional search-based shopping. This format compresses consideration cycles from days to minutes while elevating impulse-driven basket composition.
SAMR's anti-monopoly guidelines on algorithmic recommendation transparency constrain platform pricing power. Sellers gain audit rights over ranking factors, forcing disclosure of commission-weighted prominence logic. Beauty and electronics verticals face immediate compliance burdens as disclosure deadlines precede peak shopping calendar windows.
Social commerce engagement patterns are fragmenting across generational cohorts. Gen Z buyers on Xiaohongshu prioritize user-generated content authenticity over promotional density, while older consumers on Douyin respond to limited-time scarcity mechanics. This behavioral divergence forces platforms to maintain parallel content strategies rather than unified feed algorithms.
China E-Commerce Market Segmentation
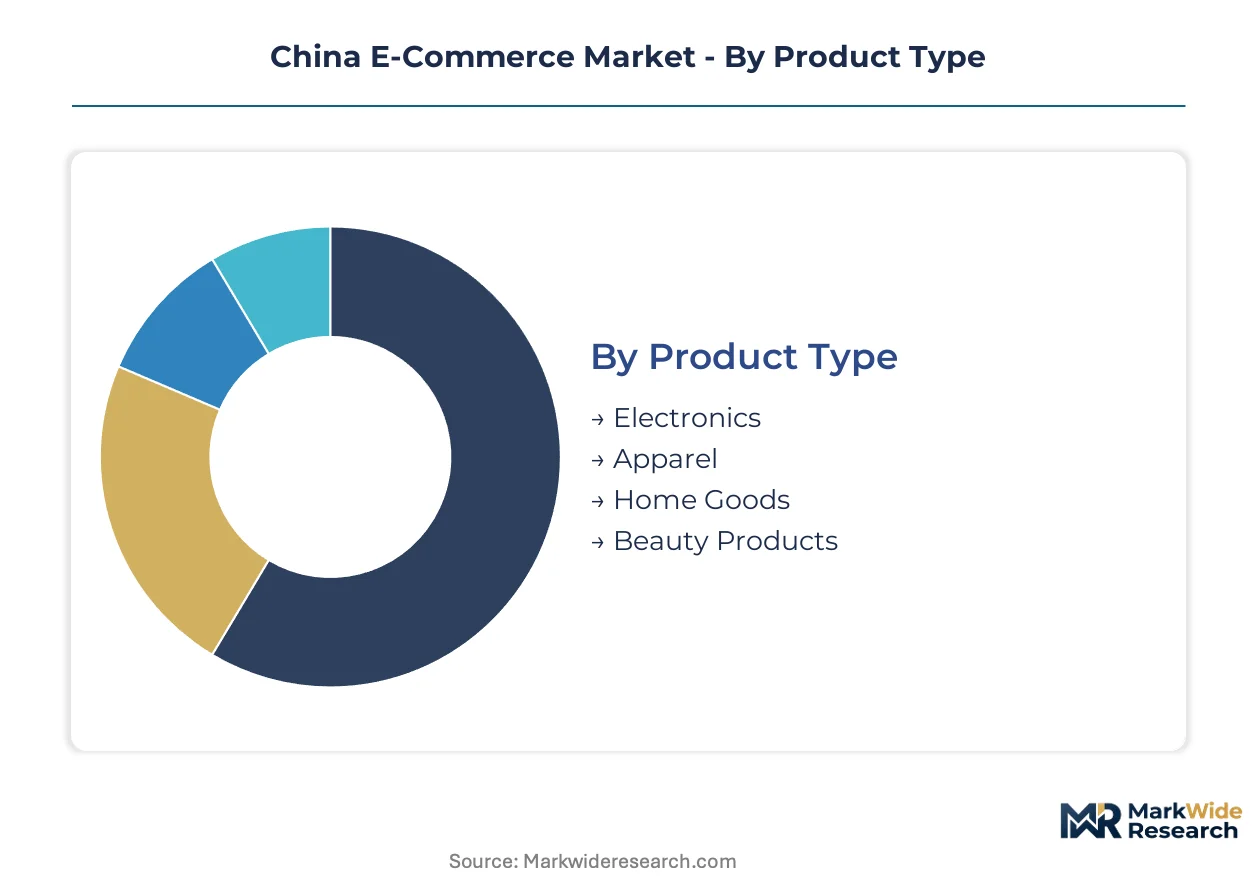
China's e-commerce segmentation reveals how platform monetization mechanics diverge across purchase contexts and fulfillment expectations. Each dimension captures distinct operational constraints that dictate inventory positioning, payment integration depth, and last-mile infrastructure investments.
Product Type:
Consumer risk tolerance and replacement frequency determine platform commission structures and seller verification intensity.
- Electronics:High-value transactions with standardized SKUs enable automated quality authentication through serial number verification. Demand concentrates in tier-one cities where smartphone replacement cycles compress below 24 months, though SAMR's extended warranty disclosure mandates raise seller compliance costs.
- Apparel:Size variability and seasonal obsolescence drive return rate volatility that erodes margin structures. Demand concentrates in lower-tier cities where live-stream KOLs collapse discovery friction for private-label manufacturers in Guangdong and Zhejiang production clusters.
- Home Goods:Bulky logistics requirements favor platforms with proprietary warehousing networks. Furniture assembly services now differentiate seller retention on JD.com and Tmall.
- Beauty Products:NMPA registration requirements for imported cosmetics create seller onboarding bottlenecks. Domestic brands exploit faster certification timelines to capture KOL-hosted live-stream slots.
Electronics leads on scale; beauty products lead on momentum.
Sales Channel:
Traffic acquisition economics and data sovereignty obligations reshape platform architecture priorities across access layers.
- Mobile Apps:Super-app ecosystems integrate payment, social, and discovery functions through single-sign-on architectures. Douyin and Xiaohongshu convert content engagement directly into closed-loop transactions without external browser handoffs.
- E-marketplaces:Aggregated seller density enables price comparison algorithms that compress margin structures. Taobao and Pinduoduo dominate county-level penetration through lightweight app variants optimized for 2G fallback connectivity.
- Brand Websites:Direct-to-consumer channels capture first-party behavioral data for demand forecasting. Lululemon and Apple operate flagship stores with membership-tiered early access mechanics.
- Social Commerce:WeChat mini-programs leverage existing social graph density to reduce customer acquisition costs below marketplace benchmarks. Group-buying mechanics in county-level WeChat communities unlock agricultural produce categories.
E-marketplaces lead on scale; social commerce leads on momentum.
Customer Type:
Procurement volume and payment terms dictate platform service tier eligibility and credit facility access.
- Individuals:Fragmented demand patterns require algorithmic personalization to sustain engagement. Gen Z buyers on Xiaohongshu prioritize user-generated authenticity over promotional density.
- Small Businesses:B2B procurement through 1688.com enables inventory sourcing with quantity-tiered pricing. County-level retailers migrate from offline wholesale systems to platform APIs for real-time stock visibility.
- Enterprises:Centralized procurement contracts demand invoice automation and VAT compliance integration. SAP and Oracle ERP connectors determine platform eligibility for state-owned enterprise vendor lists.
- Government Entities:Public tender transparency requirements favor platforms with SAMR-certified audit trails. Military and healthcare procurement operates through isolated procurement portals with air-gapped payment systems.
Individuals lead on scale; small businesses lead on momentum.
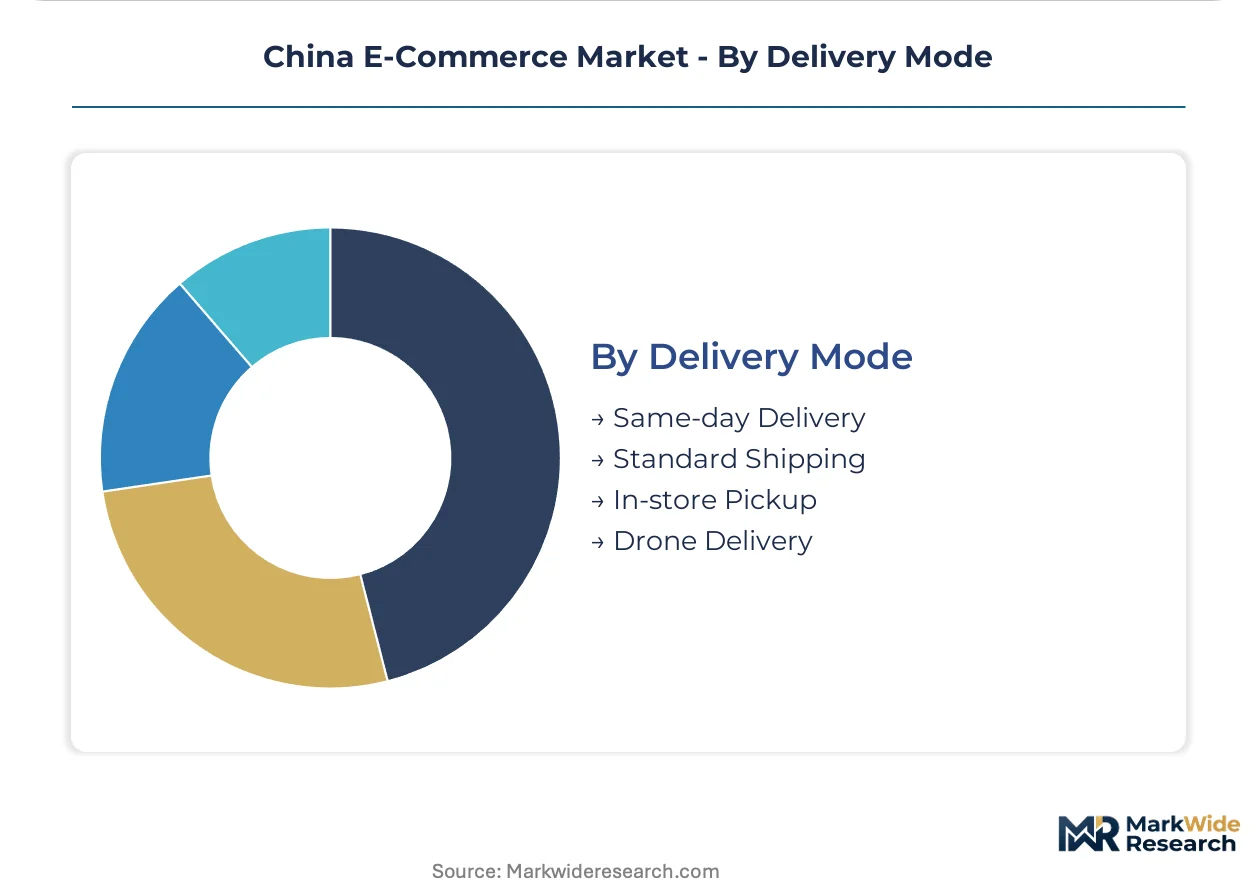
Delivery Mode:
Fulfillment speed promises and infrastructure capital requirements segment platform competitive positioning.
- Same-day Delivery:Urban density thresholds determine economic viability for automated sorting hub deployment. JD.com sustains competitive density through proprietary logistics networks in Beijing and Shanghai.
- Standard Shipping:Cost-optimized routing through third-party courier networks dominates inter-provincial fulfillment. ZTO and YTO Express operate volume-discounted contracts with platform aggregators.
- In-store Pickup:Click-and-collect reduces last-mile failure rates for high-value electronics. Suning and Gome integrate offline inventory visibility with online payment confirmation.
- Drone Delivery:Civil Aviation Administration pilot zones in Yunnan and Sichuan enable 30-minute fulfillment to mountainous villages unreachable by ground transport.
Standard shipping leads on scale; drone delivery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce in China traces its commercial lineage to Alibaba's 1999 founding in Hangzhou, which established the digital marketplace template that would scale across provincial economies before mobile infrastructure enabled county-level penetration.
Beijing-Tianjin-Hebei
Enterprise procurement contracts and government digitalization initiatives concentrate platform B2B operations in this corridor. SAMR's vendor audit requirements for state-owned enterprise procurement favor platforms with certified compliance infrastructure. Beijing anchors headquarters operations for JD.com and Meituan, while Tianjin's automated port logistics enable cross-border fulfillment throughput.
Yangtze River Delta
Manufacturing density in Zhejiang and Jiangsu provinces supplies apparel and electronics inventory for live-stream commerce hosts. MIIT's industrial internet integration subsidies accelerate factory-to-consumer data pipeline construction. Hangzhou maintains Alibaba's core marketplace engineering operations, with Ningbo's deepwater port handling bulk import logistics for beauty product sellers.
Pearl River Delta
Consumer electronics manufacturing clusters in Shenzhen and Dongguan compress replacement cycle delivery promises to same-day thresholds. Guangdong province's consumer protection bureau enforces GB standards for smartphone warranty disclosure that elevate seller documentation burdens. Shein's supply chain coordination operates from Guangzhou, leveraging the region's garment production density for rapid style turnaround.
Sichuan-Chongqing
Mountainous terrain and interior location make this cluster the primary testing ground for drone delivery pilots under Civil Aviation Administration authorization. County-level consumers in Sichuan initiate live-stream purchases at penetration rates exceeding coastal benchmarks. Chongqing's automated sorting hub serves as the western terminus for inter-provincial courier networks.
Western China
Rural broadband expansion under MIIT's universal service fund enables real-time streaming commerce in Xinjiang and Gansu prefectures previously excluded from platform economics. Agricultural produce group-buying unlocks fresh food categories through WeChat community coordination. Lanzhou and Ürümqi function as distribution nodes for cross-border e-commerce into Central Asian markets.
China E-Commerce Market Vendor Landscape
The competitive structure tilts toward integrated platform ecosystems that control logistics, payment, and discovery layers within single architectures. Three archetypes dominate: marketplace aggregators with third-party seller density, vertically integrated retailers with captive fulfillment networks, and social content platforms with closed-loop transaction conversion. Competitive moves concentrate on rural infrastructure deployment and live-stream host talent acquisition.
Among integrated retail platforms, JD.com exemplifies the logistics-captive archetype through proprietary delivery network control. Alibaba Group anchors the marketplace-aggregator position with Taobao Live infrastructure. Pinduoduo occupies the social-commerce tier, representing group-buying mechanics that collapse unit economics for price-sensitive buyers. Douyin and Xiaohongshu sit within the content-to-commerce conversion layer, converting engagement into transaction without external handoffs.
| Leading Market Players |
|---|
| Alibaba Group |
| JD.com |
| Pinduoduo |
| Douyin |
| Xiaohongshu |
| Vipshop Holdings |
| Suning.com |
| Meituan |
| Shein |
| Others |
Supply Flow & Price Mechanics
Captive logistics networks anchor both cost structures and pricing power across China's e-commerce landscape. JD.com's proprietary delivery infrastructure enables same-day premium pricing in Beijing and Shanghai while compressing margin structures for competitors reliant on third-party couriers. SAMR's anti-monopoly enforcement constrains algorithmic price discrimination, forcing platforms to disclose commission-weighted ranking logic that shapes seller fee negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates platform monetization. Premium tiers capture same-day delivery promises and KOL-hosted live-stream slots; standard tiers rely on inter-provincial courier networks with 48-72 hour windows; economy tiers deploy group-buying mechanics that collapse unit economics for county-level agricultural produce. Price differentiation hinges on fulfillment speed promises and KOL certification tier. Cost compression in standard shipping intensifies as ZTO and YTO Express wage pressures erode margin structures without volume density offsets. County-level consumers exhibit highest price sensitivity; enterprise procurement contracts show lowest elasticity due to invoice automation and VAT compliance integration requirements.
Supply Chain Analysis
MIIT's domestic server storage mandates under the Personal Information Protection Law reshape cloud architecture sourcing decisions. Manufacturing concentration centers on Zhejiang and Jiangsu provinces for apparel and electronics inventory, Guangdong for consumer electronics assembly, and Sichuan-Chongqing for drone delivery pilot infrastructure. Raw material dependencies span lithium-ion cells for electric delivery fleets, packaging substrates for carbon-neutral fulfillment mandates, and semiconductor components for automated sorting hub equipment. Single-source vulnerability runs through Civil Aviation Administration authorization corridors for drone delivery in mountainous terrain. Distribution runs through proprietary logistics networks for premium tiers and third-party courier aggregators for standard fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's e-commerce market represents a late-cycle quality story as replacement-driven demand for smart appliances elevates platform traffic through integrated app ecosystems. Consumer procurement shifts toward certified KOL-hosted channels favor sellers with NMPA registration completion and GB standards compliance infrastructure.
For Market Incumbents: To counter live-stream host talent scarcity, JD.com and Alibaba Group should accelerate certified anchor training program deployment while securing exclusive contracts with qualified KOLs. Backward integration into electric vehicle fleet conversion captures carbon-neutral fulfillment mandates. Channel control over county-level distributor ERP API synchronization reduces inventory visibility delays that plague platform onboarding.
For New Entrants and Emerging Players: Agricultural produce group-buying in Xinjiang and Gansu prefectures offers the most penetrable white-space target as MIIT rural broadband expansion collapses delivery promise gaps. WeChat mini-program community coordination unlocks fresh food categories previously excluded from remote fulfillment economics. Go-to-market positioning should emphasize social裂变 mechanics that reduce per-unit logistics costs below marketplace benchmarks.
For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated logistics-captive platforms because SAMR's algorithmic transparency mandates favor incumbents with engineering resources for real-time decision logging. Long-term viability hinges on drone delivery corridor authorization expansion and AR-enabled virtual try-on technology maturation. Acquisition target archetype: county-level distributors with legacy offline wholesale relationships migrating to platform API integration. Signal to watch: Civil Aviation Administration pilot zone expansion beyond Yunnan and Sichuan into Qinghai and Tibet terrain.
| Strategic Initiative | Industry Significance |
|---|---|
| Live-Stream Host Certification Investment | GB standards compliance creates defensible KOL talent pipelines ahead of peak shopping calendar windows. |
| Drone Delivery Corridor Expansion | Civil Aviation Administration authorization unlocks 30-minute fulfillment to villages unreachable by ground transport. |
| Electric Vehicle Fleet Conversion | Dual carbon goals incentivize green premium positioning for carbon-neutral fulfillment mandates. |
| AR-Enabled Virtual Try-On Deployment | Spatial computing convergence reduces return rates for apparel categories in higher-margin fashion verticals. |
| County-Level ERP API Integration | Real-time inventory visibility accelerates distributor migration from offline wholesale systems. |
Methodological Framework
Bottom-up live-stream commerce modeling reconciled against top-down logistics infrastructure tracking forms the analytical core of this study. Primary interviews with platform engineering directors, KOL talent agency operators, county-level distributor migration specialists, and SAMR compliance officers combined with secondary validation against MIIT broadband deployment disclosures, SAMR anti-monopoly enforcement records, Civil Aviation Administration pilot zone authorizations, and NMPA cosmetics registration queue data. Cross-referencing supplier procurement patterns with consumer transaction flow data enables triangulation between supply-side capacity and demand-side adoption curves.
Input-output matrices map fulfillment speed promises to infrastructure capital requirements across the projection horizon. Segmentation dimensions modeled include product type, sales channel, customer type, and delivery mode, with additional granularity on KOL certification tier and county-level 5G coverage penetration. CAGRs derive from logistic curve fitting to live-stream commerce adoption rates and replacement cycle compression patterns for smart appliances. Industry-specific forecast inputs incorporate MIIT rural broadband expansion timelines and SAMR algorithmic audit documentation implementation schedules.
Revisions become necessary when SAMR enforcement intensity exceeds modeled scenarios, drone delivery authorization timelines accelerate or stall, or cross-border data localization mandates expand beyond current Personal Information Protection Law scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market