
 Hyperlocal Delivery App Market | 2026-2036
Hyperlocal Delivery App Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperlocal Delivery App Market Insights
Grocery delivery is expanding as a share of total hyperlocal order volume, pulling platform investment away from pure-play restaurant focus. DoorDash sustains geographic dominance across North American suburbs through dense courier networks. Instacart specializes in grocery-centric logistics with established retailer partnerships. Delivery Hero SE anchors European and emerging-market operations through localized brand portfolios.
A hyperlocal delivery app is a location-based mobile software platform that matches consumer orders with independent or employed couriers within a radius of approximately five to fifteen kilometers, utilizing GPS tracking and AI routing to optimize dispatch timing and minimize per-unit delivery cost. Its primary commercial purpose is to collapse the fulfillment lag between local inventory and immediate consumer demand. Food delivery retains the largest transaction volume across platforms, though grocery delivery is capturing faster user growth as household stockpiling behavior normalizes post-pandemic. Commission-based payment models still dominate revenue architecture, while subscription tiers concentrate among high-frequency urban users.
The EU Platform Work Directive reclassifies algorithmic management practices, forcing operators to restructure courier employment terms across Germany, France, and the Netherlands. India's FSSAI mandates real-time hygiene ratings for restaurant partners, raising compliance barriers for platform onboarding. The US Department of Labor's evolving independent-contractor test under FLSA creates jurisdictional uncertainty for gig workforce models. Stakeholders must monitor regulatory fragmentation across operating geographies while calibrating courier cost structures against subscription revenue durability.
Market Dynamics
Platform operators face a structural squeeze between India's PLI scheme for logistics technology, which subsidizes automation investment, and the EU Platform Work Directive's reclassification mandates, which inflate courier employment costs across Germany, France, and the Netherlands.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for logistics technology reduce capital barriers for automated dispatch systems in Mumbai, Bangalore, and Delhi corridors.
- Cloud Kitchen Proliferation:Asset-light food preparation facilities generate concentrated order density, improving courier utilization rates and reducing per-unit delivery costs.
- EU Green Deal:Emissions reduction frameworks accelerate electric two-wheeler adoption for last-mile fleets in urban Netherlands and Danish municipalities.
Market Restraints
- EU Platform Work Directive:Reclassification of algorithmic management practices forces employment term restructuring, adding payroll tax and benefit obligations across German and French operations.
- Courier Supply Concentration:Urban labor pools in Indian metropolitan corridors face recruitment saturation, inflating incentive costs for Swiggy and Zomato during peak demand windows.
- FSSAI Real-Time Compliance:India's hygiene rating mandates require continuous monitoring infrastructure, raising onboarding friction for small restaurant partners.
Strategic Opportunities
- US Suburban Penetration:DoorDash's courier density models remain underreplicated in exurban zones surrounding Dallas, Atlanta, and Phoenix metropolitan areas.
- Grocery-Retailer Integration:Instacart's established partnerships with Kroger and Albertsons demonstrate scalable inventory synchronization protocols applicable to European supermarket chains.
- AI Routing Convergence:Machine learning dispatch optimization merges with predictive demand modeling to compress fulfillment windows in high-frequency urban corridors.
Industry Challenges
- Algorithmic Workforce Management:Balancing courier earnings guarantees against route efficiency targets requires recalibrating incentive structures without triggering regulatory scrutiny.
- Subscription Revenue Durability:High-frequency user tiers concentrate in dense urban cores, leaving platforms exposed to churn when delivery frequency normalizes post-pandemic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperlocal Delivery App Market |
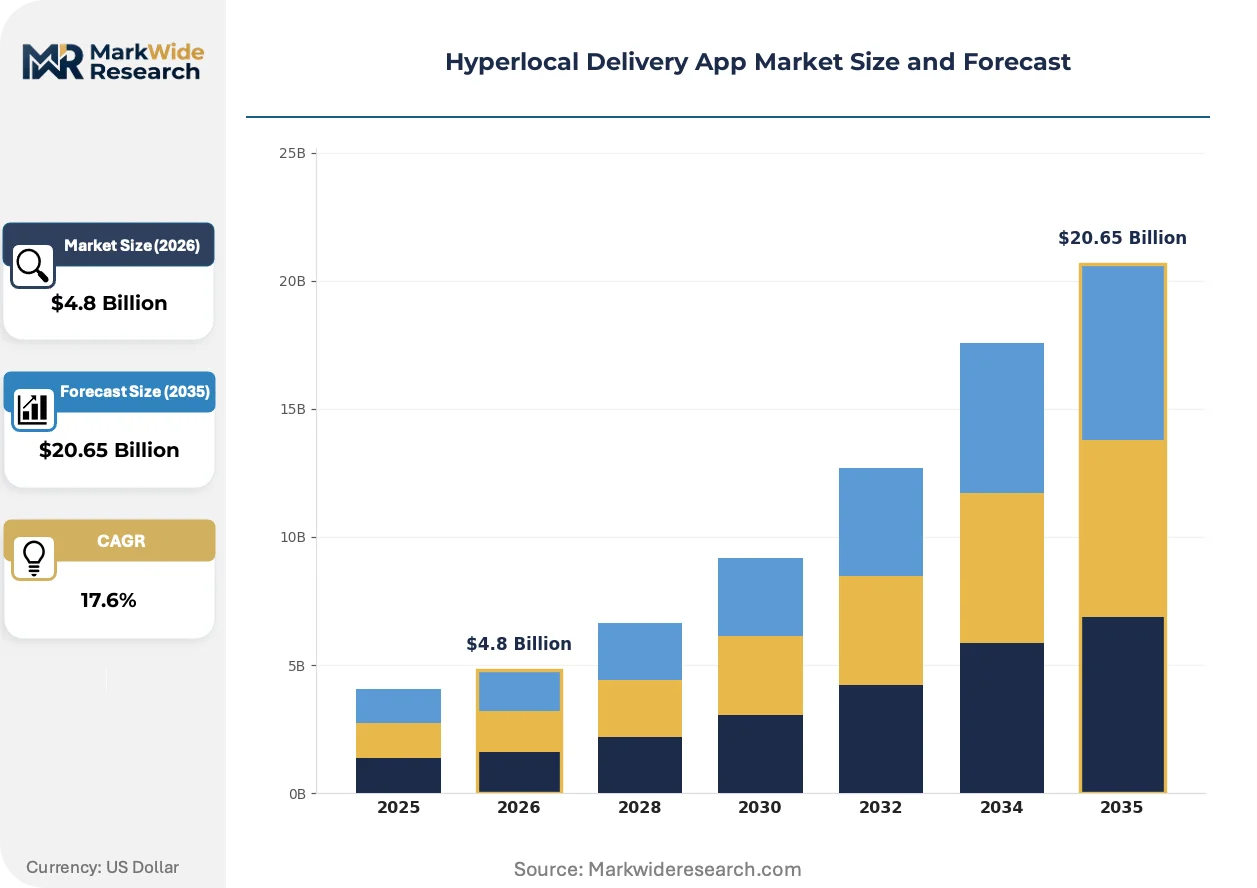
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Type: Food Delivery, Grocery Delivery, Package Delivery, Pharmacy Delivery Technology: GPS Tracking, Mobile App, Cloud Computing, AI Routing End User: Consumers, Businesses, Restaurants, Retailers Payment Model: Subscription, Pay-per-Delivery, Commission-Based, Advertising |
| Companies Covered | Uber Technologies Inc., DoorDash Inc., Delivery Hero SE, Zomato Ltd., Swiggy, Grubhub Inc., Just Eat Takeaway.com, Deliveroo, Instacart Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperlocal Delivery App Market Trends and Innovations
Delivery platforms are pivoting from pure-play restaurant aggregation toward multi-category fulfillment, with grocery and convenience retail absorbing disproportionate capital allocation and technology development resources.
Artificial intelligence dispatch optimization is absorbing courier pool variability across Indian and North American operations. Swiggy and Zomato deploy predictive routing to match floating driver supply with localized demand spikes. This compression of matching latency is absorbing excess capacity during off-peak windows, improving unit economics for platforms operating in Bangalore and Mumbai corridors.
The EU Platform Work Directive mandates transparent algorithmic decision-making for courier assignments and earnings calculations. German and Dutch operators must now document how automated systems distribute orders and calculate pay. Food delivery platforms in Berlin and Amsterdam are responding by hybridizing human supervisor oversight with automated dispatch, adding compliance infrastructure without fully abandoning gig-economy flexibility.
Household stockpiling behavior normalized post-pandemic has rotated grocery delivery toward scheduled replenishment rather than impulse purchasing. Subscription-based ordering is displacing transaction-by-transaction selection in Indian metropolitan households and North American suburban zones. This shift is most visible in Mumbai and Dallas corridors, where platforms report higher basket sizes and lower per-order delivery costs for recurring grocery slots.
Hyperlocal Delivery App Market Segmentation
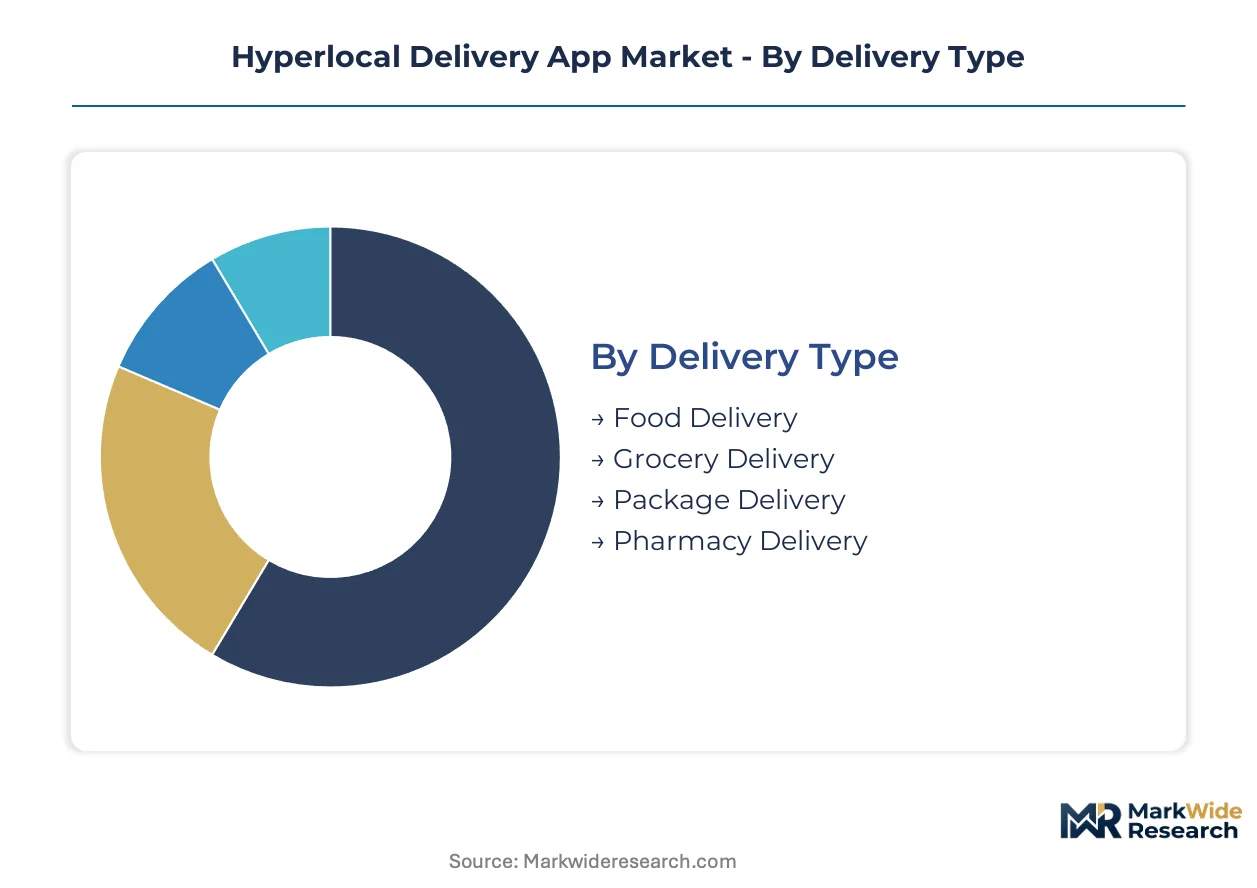
Hyperlocal delivery platforms require distinct operational architectures across delivery types, technology stacks, and payment models. Segmentation reveals where capital allocation concentrates and which user cohorts drive sustainable unit economics.
Delivery Type:
FSSAI hygiene ratings govern food delivery onboarding in India. Pharmacy delivery requires CDSCO compliance for scheduled medicines. Package delivery faces minimal certification barriers but demands courier insurance frameworks.
- Food Delivery:Restaurant aggregation with real-time order matching dominates transaction volume. Demand clusters in Mumbai, Bangalore, and Delhi corridors where Swiggy and Zomato compete for frequency share. Cloud kitchen proliferation compresses fulfillment windows and improves courier utilization.
- Grocery Delivery:Scheduled replenishment models displace impulse purchasing post-pandemic. Household stockpiling normalization drives subscription adoption in Dallas and Phoenix suburbs where Instacart maintains retailer partnerships.
- Package Delivery:Same-day courier services for e-commerce returns and local business logistics. Courier density requirements limit profitability outside dense urban cores.
- Pharmacy Delivery:Temperature-controlled transport for prescription medications with regulatory documentation. CDSCO mandates restrict platform eligibility for controlled substance distribution.
Leading the category by volume: Food Delivery. Growing fastest: Grocery Delivery.
Technology:
Technology investments stratify by automation depth and capital intensity. India's PLI scheme subsidizes advanced logistics systems in metropolitan corridors.
- AI Routing:Machine learning dispatch optimization matches floating driver supply with localized demand spikes. Predictive algorithms absorb excess capacity during off-peak windows in Bangalore and Mumbai operations.
- Cloud Computing:Scalable infrastructure supports order surge handling and real-time inventory synchronization. Kroger and Albertsons partnerships demonstrate retailer integration protocols.
- GPS Tracking:Location services enable five-to-fifteen kilometer radius matching with estimated arrival transparency. Consumer expectation of minute-level accuracy drives infrastructure investment.
- Mobile App:Consumer-facing interface with payment integration and order customization. Subscription tier concentration depends on app engagement frequency in urban cores.
Absorbing capital fastest: AI Routing. Widest deployment: Mobile App.
End User:
User type determines pricing power and retention economics. Business accounts yield higher basket values but require dedicated support infrastructure.
- Consumers:Individual households ordering food, groceries, and convenience items. Subscription tiers concentrate among high-frequency users in dense metropolitan zones.
- Restaurants:Partner kitchens relying on platforms for demand generation and logistics. Commission structures absorb fifteen to thirty percent of order value.
- Retailers:Supermarket chains and convenience stores outsourcing last-mile fulfillment. Inventory synchronization requirements strain smaller operator technical capacity.
- Businesses:Corporate catering and office supply procurement with contracted pricing. Volume commitments justify dedicated courier allocation during peak windows.
Highest frequency: Consumers. Steepest expansion trajectory: Retailers.
Payment Model:
Revenue architecture varies by user predictability and platform risk exposure. EU Platform Work Directive compliance costs pressure model selection.
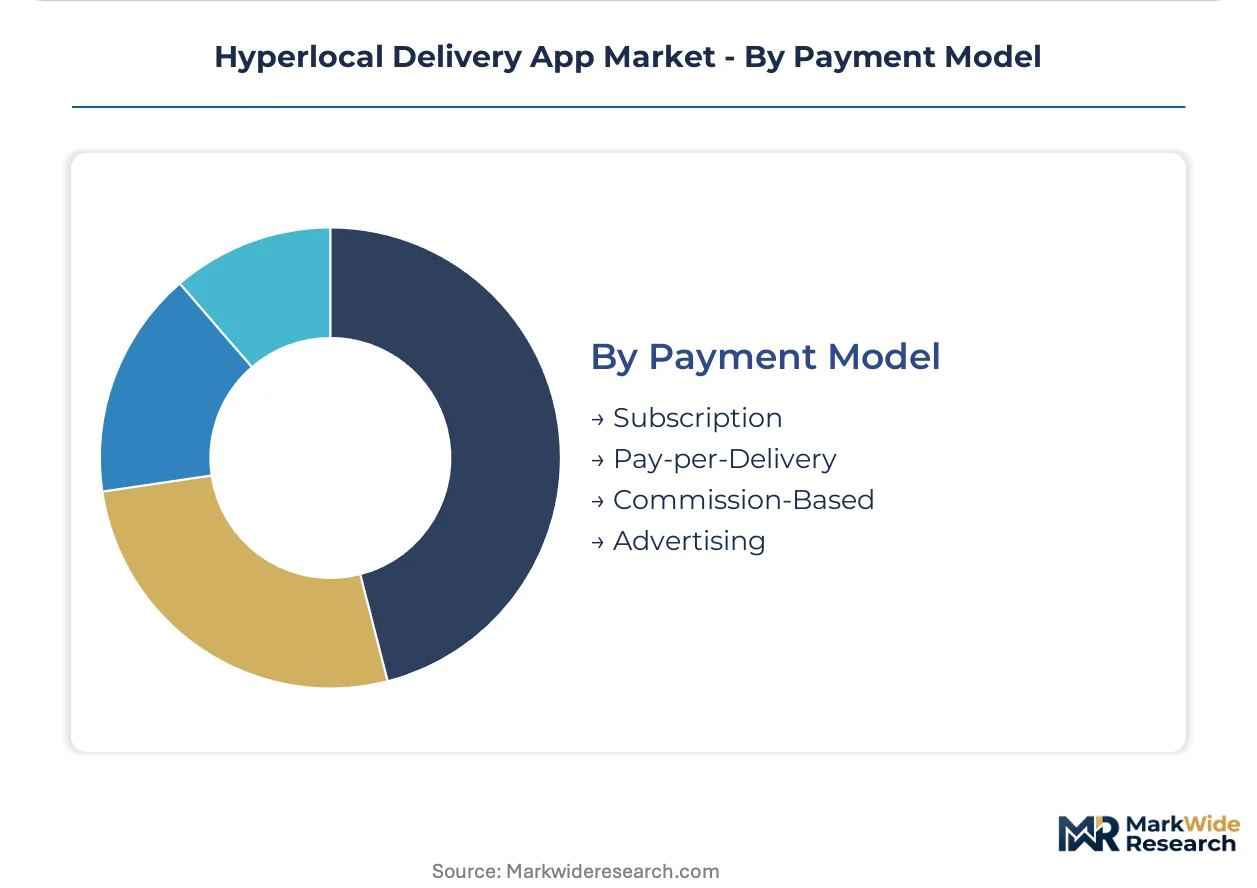
- Commission-Based:Percentage fee on transaction value from restaurant and retail partners. Dominates revenue architecture across DoorDash and Delivery Hero operations.
- Subscription:Monthly fee for reduced delivery charges and priority service. Churn exposure rises when post-pandemic frequency normalizes.
- Pay-per-Delivery:Per-order fee structure for occasional users. Price sensitivity limits penetration in suburban zones with lower order density.
- Advertising:Promoted placement and sponsored listings within app interfaces. Restaurant chains bid for search visibility in competitive corridors.
Primary revenue source: Commission-Based. Gaining share fastest: Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for logistics technology has concentrated platform investment in designated metropolitan corridors, creating tax-advantaged zones for automated dispatch infrastructure deployment.
United States
DoorDash sustains courier density dominance across suburban Dallas and Phoenix corridors where household stockpiling behavior drives scheduled grocery replenishment. The Department of Labor's evolving independent-contractor test under FLSA generates jurisdictional uncertainty for gig workforce classification. Atlanta's exurban zones remain underpenetrated relative to established metropolitan networks.
Germany
Delivery Hero SE anchors European operations through localized brand portfolios serving dense urban demand clusters. The EU Platform Work Directive forces restructuring of algorithmic management practices, adding payroll tax obligations for courier employment. Berlin operators hybridize human supervisor oversight with automated dispatch to maintain compliance infrastructure.
India
Swiggy and Zomato compete for frequency share across Mumbai, Bangalore, and Delhi corridors where cloud kitchen proliferation compresses fulfillment windows. FSSAI mandates real-time hygiene ratings for restaurant partners, raising onboarding friction for smaller operators. The PLI scheme subsidizes automated dispatch systems in designated logistics technology zones.
Netherlands
Amsterdam and Dutch municipalities accelerate electric two-wheeler adoption under EU Green Deal emissions frameworks for last-mile fleets. The Platform Work Directive mandates transparent algorithmic decision-making for courier assignments and earnings calculations. Rotterdam operators document automated order distribution systems to satisfy regulatory documentation requirements.
United Kingdom
Deliveroo and Just Eat Takeaway.com serve London's concentrated urban consumer base with subscription tiers among high-frequency users. GDPR and emerging platform work regulations reshape courier data handling and employment term transparency. Greater Manchester and Birmingham corridors show expanding grocery delivery adoption post-pandemic normalization.
Hyperlocal Delivery App Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform operators commanding frequency-heavy urban corridors while pure-play logistics providers capture suburban grocery expansion. Market structure tilts toward consolidation at the national level, though regional specialists retain defensible positions in metropolitan clusters with distinct regulatory environments. Three archetypes dominate: vertically integrated super-app operators, grocery-specialized fulfillment platforms, and restaurant-centric aggregation networks. Competitive intensity centers on M&A activity for cloud kitchen infrastructure and strategic partnerships with supermarket chains for inventory synchronization.
Within the super-app tier, Uber Technologies Inc. exemplifies cross-category expansion beyond mobility into food and grocery fulfillment. DoorDash Inc. anchors North American suburban penetration through dense courier network economics. Delivery Hero SE occupies a position bridging European regulatory complexity with emerging-market growth corridors. These three operators represent distinct geographic and regulatory positioning strategies without overlapping core market concentration.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| DoorDash Inc. |
| Delivery Hero SE |
| Zomato Ltd. |
| Swiggy |
| Grubhub Inc. |
| Just Eat Takeaway.com |
| Deliveroo |
| Instacart Inc. |
| Others |
Pricing and Supply Chain Analysis
Post-pandemic subscription fatigue among high-frequency urban households forces platforms to restructure delivery fee architectures, compressing margins and accelerating automation investment in Indian and North American corridors.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with expedited sub-hour delivery commanding surcharges in Mumbai and Dallas corridors. Commission-based revenue from restaurant partners absorbs fifteen to thirty percent of order value, while subscription tiers face churn pressure as household delivery frequency normalizes. Price differentiation hinges on courier density and AI routing sophistication, with suburban zones exhibiting highest price sensitivity due to lower order concentration.
Supply Chain Analysis
Single-source vulnerability sits with cloud kitchen infrastructure providers concentrated in Bangalore, Dubai, and Singapore, where specialized real estate operators control premium urban locations. Platform logistics draw from electric two-wheeler manufacturers in China and Vietnam, alongside AI dispatch software development anchored in India and the United States. Tariff exposure on hardware components threatens fleet electrification timelines. Distribution runs through metropolitan courier pools with limited inter-city redundancy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cloud kitchen real estate and captive courier fleet ownership has become the defining competitive race, as platforms seek to escape margin compression from third-party infrastructure providers.
For Market Incumbents: Extend cloud kitchen network ownership in Mumbai and Bangalore corridors to lock in fulfillment density before regulatory caps on algorithmic management tighten. Consolidate AI routing capabilities through targeted engineering hires in designated PLI zones, insulating against EU Platform Work Directive cost inflation. For New Entrants and Emerging Players: India's PLI scheme for logistics technology opens a window for automated dispatch specialists to capture subsidy-advantaged infrastructure contracts in Delhi and Hyderabad. Target pharmacy delivery segments where CDSCO compliance barriers deter generalist platforms, leveraging temperature-controlled transport partnerships as the entry wedge. For Investors and Strategic Acquirers: The window for entry favors vertically integrated regional operators with captive cloud kitchen assets and established retailer synchronization protocols. Long-term viability centers on subscription revenue durability and regulatory navigation capability across fragmented employment classification regimes. Watch EU member state implementation variance on Platform Work Directive as the signal for geographic winner-loser redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Network Expansion | Captive fulfillment density in Mumbai and Bangalore corridors reduces per-unit delivery costs below competitor thresholds. |
| AI Dispatch Platform Development | Predictive routing optimization absorbs courier pool variability across Indian metropolitan operations. |
| Electric Fleet Transition | EU Green Deal subsidies in Amsterdam and Rotterdam accelerate two-wheeler electrification compliance. |
| Retailer Inventory Synchronization | Real-time API integration with Kroger and Albertsons protocols enables grocery replenishment scaling. |
| Regulatory Compliance Infrastructure | Hybrid human-AI supervision systems satisfy Berlin and Amsterdam algorithmic transparency mandates. |
Research Methodology
SEC filings, EU regulatory databases, and Indian PLI scheme documentation formed the secondary backbone, supplemented by primary interviews with platform operations executives, cloud kitchen real estate developers, and logistics technology procurement officers. Bottom-up and top-down triangulation validated order volume estimates against courier density metrics and subscription tier penetration rates.
Bottom-up modeling aggregated metropolitan corridor transaction data, while top-down analysis calibrated aggregate market expansion against cloud kitchen capacity buildouts and electric fleet deployment schedules across the projection horizon. Segmentation dimensions included delivery type, technology stack, end-user archetype, and payment model, with CAGRs derived from courier utilization rate trajectories and subscription churn assumptions.
The model assumes a particular technology adoption path; alternative pathways for autonomous dispatch would alter the outlook. Forecasts reflect assumptions on regulatory implementation timing and consumer frequency normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Australia E-Commerce Market