
 Enterprise 2.0 Technologies Market | 2026-2036
Enterprise 2.0 Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise 2.0 Technologies Market Analysis
The direct enterprise sales channel is narrowing as vendor-customer relationships consolidate around cloud marketplaces and managed service intermediaries. Microsoft Corporation leverages its Azure ecosystem to bundle collaboration tools with infrastructure services, sustaining platform stickiness across large accounts. IBM Corporation anchors its position through Watson-enabled workflow automation that integrates with legacy enterprise systems. Oracle Corporation competes by extending database-centric collaboration suites that exploit existing customer data architectures.
Enterprise 2.0 Technologies encompass software platforms that enable networked collaboration, knowledge sharing, and collective intelligence within organizations through web-based architectures including real-time messaging, social graph analytics, and federated content repositories. These systems typically operate via RESTful APIs and microservices architectures designed to interoperate with existing identity management and security frameworks, serving the primary purpose of replacing siloed communication with transparent, searchable, and algorithmically enhanced workflows. Collaboration Tools and Cloud-Based deployment models capture the dominant margin pools as enterprises abandon on-premises maintenance burdens, while Artificial Intelligence integration within Communication Platforms represents the fastest-expanding capability layer as natural language processing automates meeting transcription, sentiment analysis, and predictive task routing.
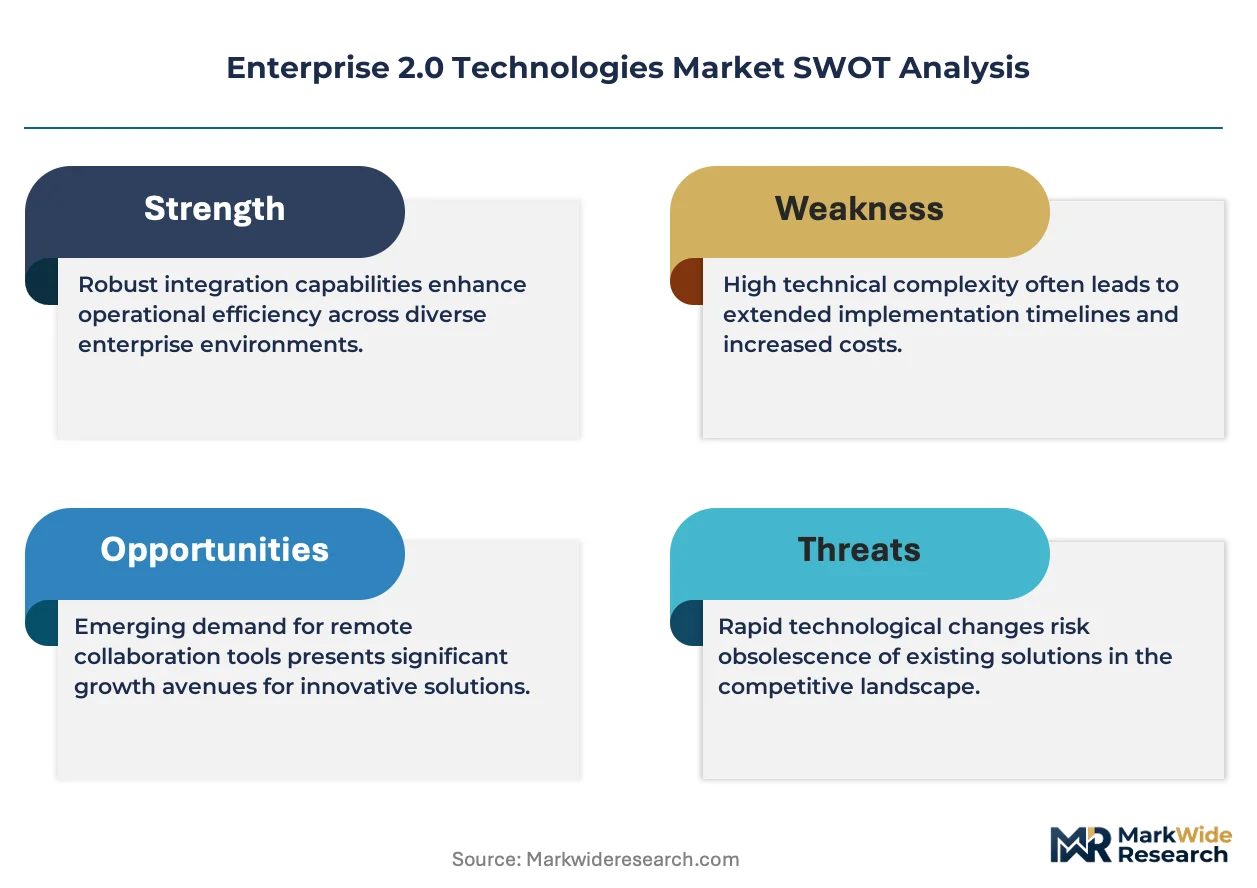
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps by mandating explainable algorithms, data residency controls, and incident reporting mechanisms that inflate compliance costs but create barriers for non-compliant entrants. ISO 27001 and SOC 2 Type II certifications have become table stakes for vendor selection in regulated sectors, with procurement teams treating framework adherence as a primary filter before technical evaluation. Stakeholders must monitor the divergence between European risk-based AI classifications and US sectoral approaches, as this regulatory fragmentation will determine which platform architectures achieve cross-border deployability.
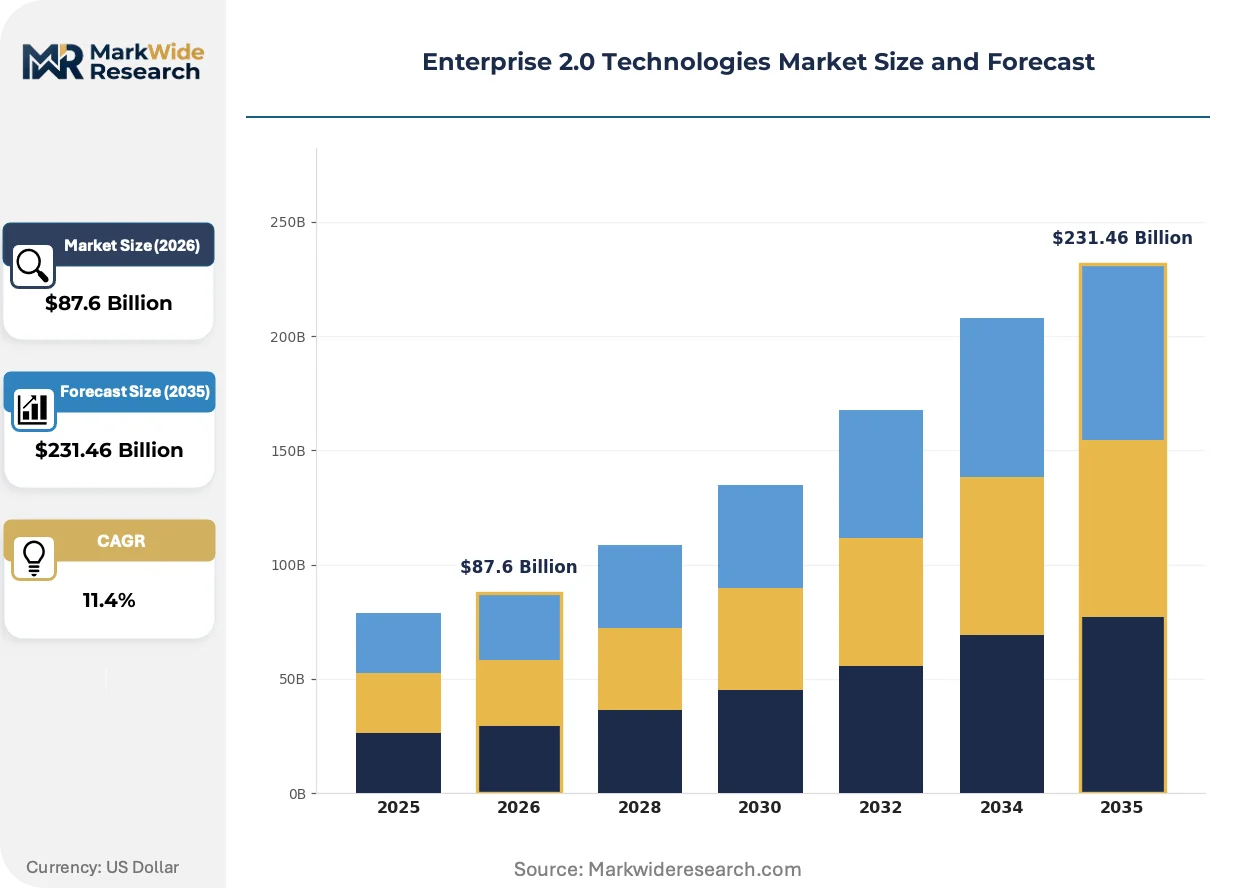
Market Dynamics
The migration from on-premises collaboration infrastructure to sovereign cloud architectures constitutes the dominant structural force reshaping vendor-customer relationships and procurement criteria across enterprise technology stacks.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and healthcare enterprises in Germany and France are accelerating replacement of legacy communication systems to satisfy algorithmic transparency and data residency requirements.
- Real-time workforce orchestration:Distributed engineering teams across United States technology firms are demanding unified platforms that collapse email, video conferencing, and project management into searchable knowledge graphs.
- Microservices architecture maturation:Containerized deployment patterns are reducing integration friction between collaboration tools and existing identity management frameworks, lowering switching costs for mid-market adopters.
Market Restraints
- Specialized compliance engineering talent scarcity:The shallow labor pool for professionals versed in both ISO 27001 implementation and natural language processing pipeline security inflates implementation timelines.
- Input concentration in hyperscale cloud infrastructure:Three providers control the underlying compute and storage layers that power most Enterprise 2.0 deployments, creating vendor lock-in risk and pricing power asymmetries.
- Technical debt in legacy ERP integration:Decades-old SAP and Oracle database architectures resist seamless API connectivity, forcing expensive middleware development for comprehensive workflow automation.
Strategic Opportunities
- Indian manufacturing sector penetration:Discrete and process manufacturers in Maharashtra and Gujarat remain underpenetrated by AI-enhanced collaboration platforms, presenting first-mover advantages for localized deployment models.
- Convergence of graph analytics and semantic search:Platforms combining social network analysis with enterprise knowledge retrieval are creating new product categories between traditional intranets and external intelligence services.
- SEC cybersecurity disclosure rules:Mandated incident reporting and board-level accountability for data breaches are converting compliance budgets into platform upgrade cycles across publicly traded United States corporations.
Industry Challenges
- Multi-framework certification sequencing:Achieving concurrent SOC 2 Type II, ISO 27001, and sector-specific attestations stretches product engineering timelines and diverts resources from feature development.
- Fragmented identity provider landscape:Enterprises operate hybrid environments mixing Active Directory, Okta, and emerging decentralized identity standards, complicating single sign-on implementation and access governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise 2.0 Technologies Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collaboration Tools, Social Software, Content Management Systems, Communication Platforms Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, SMEs, Educational Institutions, Government Agencies Technology: APIs, Artificial Intelligence, Machine Learning, Blockchain |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, Cisco Systems Inc, Dell Inc, Enghouse Systems, Avaya Inc, CafeX Communications Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise 2.0 Technologies Market Emerging Trajectories
Generative AI capabilities are compressing the traditional boundaries between content creation, knowledge retrieval, and task automation within enterprise collaboration environments. This convergence is forcing platform providers to rearchitect core products around predictive assistance rather than reactive toolsets.
Natural language processing engines embedded in meeting platforms are digitizing the capture and structuring of institutional knowledge that previously required manual documentation or was lost entirely. Financial services compliance teams in London and New York are adopting these systems fastest, driven by regulatory pressure to maintain searchable records of client interactions. The technology is digitizing voice and video content into queryable data assets, transforming ephemeral communication into permanent organizational memory.
The EU AI Act's risk-based classification system is compelling platform vendors to engineer explainability features into algorithmic recommendation engines and sentiment analysis modules. Product teams must now document decision pathways for automated task routing and content prioritization. German automotive and industrial conglomerates, with their stringent internal governance cultures, are emerging as the most demanding reference customers for these transparent-by-design architectures.
Enterprise buyers are consolidating vendor relationships around integrated suites that bundle infrastructure, security, and collaboration functions under unified contracts. Procurement teams in United States healthcare and federal sectors are rejecting point solutions in favor of platform ecosystems that reduce integration overhead and simplify compliance auditing. This concentration favors incumbent cloud providers with broad service portfolios while marginalizing specialized collaboration vendors dependent on interoperability partnerships.
Enterprise 2.0 Technologies Market Segmentation
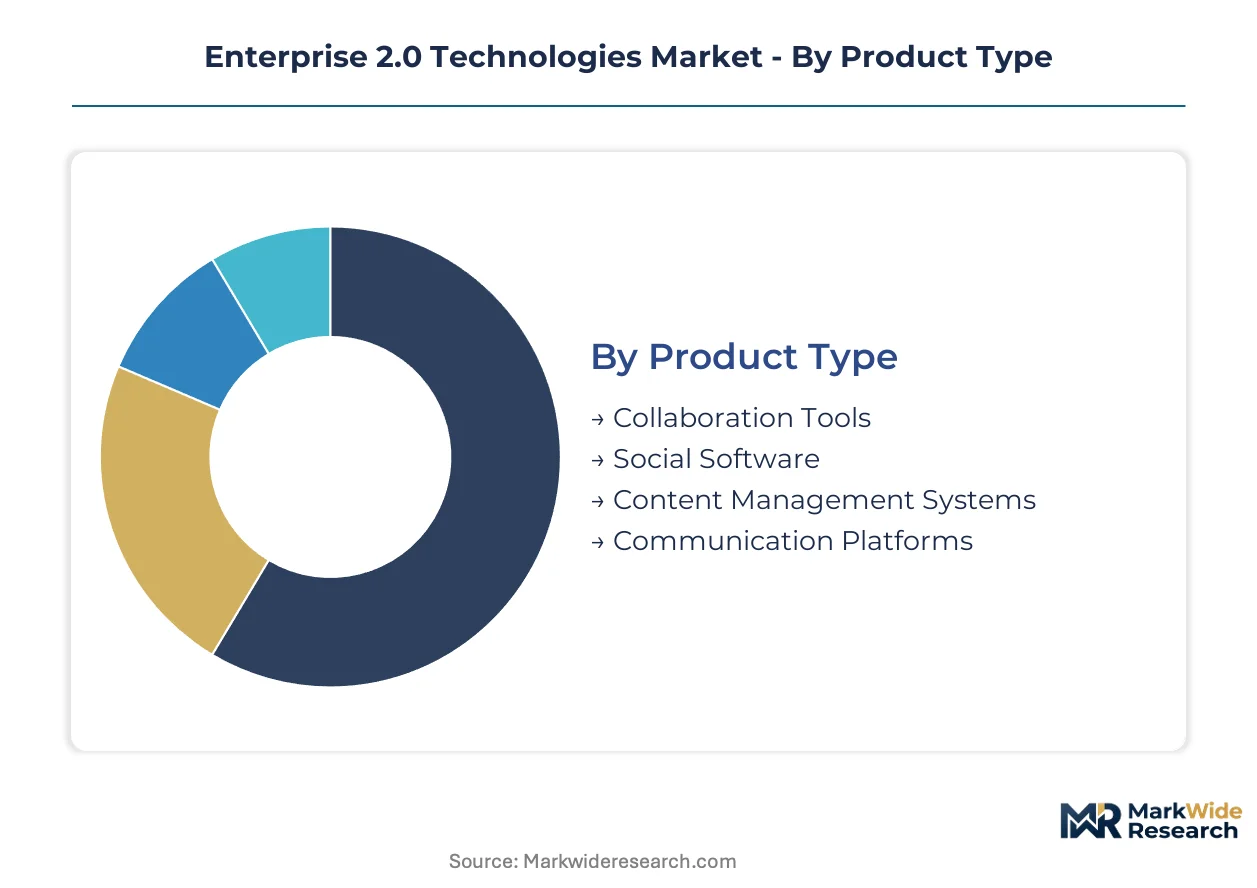
Enterprise 2.0 Technologies market segmentation reveals distinct capability layers where deployment architecture and intelligence integration determine procurement priorities. Product configuration, hosting strategy, and user scale collectively shape vendor-customer contract structures and renewal economics.
Product Type:
After-sales service intensity varies dramatically across product categories, with Communication Platforms requiring continuous algorithm tuning and Collaboration Tools demanding persistent user enablement support.
- Collaboration Tools:These platforms integrate real-time messaging, document co-authoring, and project workspace orchestration into unified interfaces. Financial services firms in New York and London concentrate procurement here, driven by SEC record-keeping mandates and FCA conduct supervision requirements that demand searchable audit trails.
- Communication Platforms:Systems embedding video conferencing, voice transcription, and sentiment analytics through natural language processing engines. German automotive conglomerates in Stuttgart and Munich represent the most demanding reference customers, requiring EU AI Act-compliant explainability features for automated meeting summarization and task extraction.
- Social Software:Enterprise networking platforms enabling internal knowledge graphs and expert location.
- Content Management Systems:Federated repositories with semantic search and automated metadata tagging.
Collaboration Tools hold the largest share; momentum sits with Communication Platforms.
Deployment Model:
Cost tier stratification separates enterprise-grade sovereign cloud deployments from mid-market SaaS subscriptions, with hybrid architectures occupying a complex middle band requiring specialized integration engineering.
- Cloud-Based:Fully managed multi-tenant infrastructure with automatic scaling and shared security operations. Healthcare systems across the United States are migrating here fastest, compelled by HHS cybersecurity guidance and the operational impossibility of maintaining on-premises resilience.
- SaaS:Browser-accessible applications with zero local infrastructure footprint. Indian IT services firms in Bengaluru and Hyderabad favor this model for rapid global team provisioning without capital expenditure approval cycles.
- On-Premises:Self-hosted installations maintaining complete data sovereignty.
- Hybrid:Split architectures keeping sensitive workloads local while leveraging cloud burst capacity.
Cloud-Based deployments command the largest share; SaaS offerings are climbing the fastest.
End User:
Volume concentration patterns diverge sharply between massive enterprise deployments spanning hundreds of thousands of seats and SME adoptions where per-user economics determine platform viability.
- Enterprises:Organizations with 10,000+ employees requiring custom compliance configurations and dedicated customer success management. United States federal agencies and defense contractors represent the most stringent procurement segment, with FedRAMP authorization and CMMC certification serving as non-negotiable gates.
- SMEs:Mid-sized entities prioritizing rapid deployment and predictable per-seat pricing over customization depth. Professional services firms in Singapore and Sydney are expanding fastest here, attracted by out-of-box integrations with existing productivity suites.
- Educational Institutions:Universities and research consortia with unique intellectual property protection needs.
- Government Agencies:Public sector bodies with sovereign data requirements and classified information handling protocols.
Enterprises hold the largest share; SMEs are gaining share fastest.
Technology:
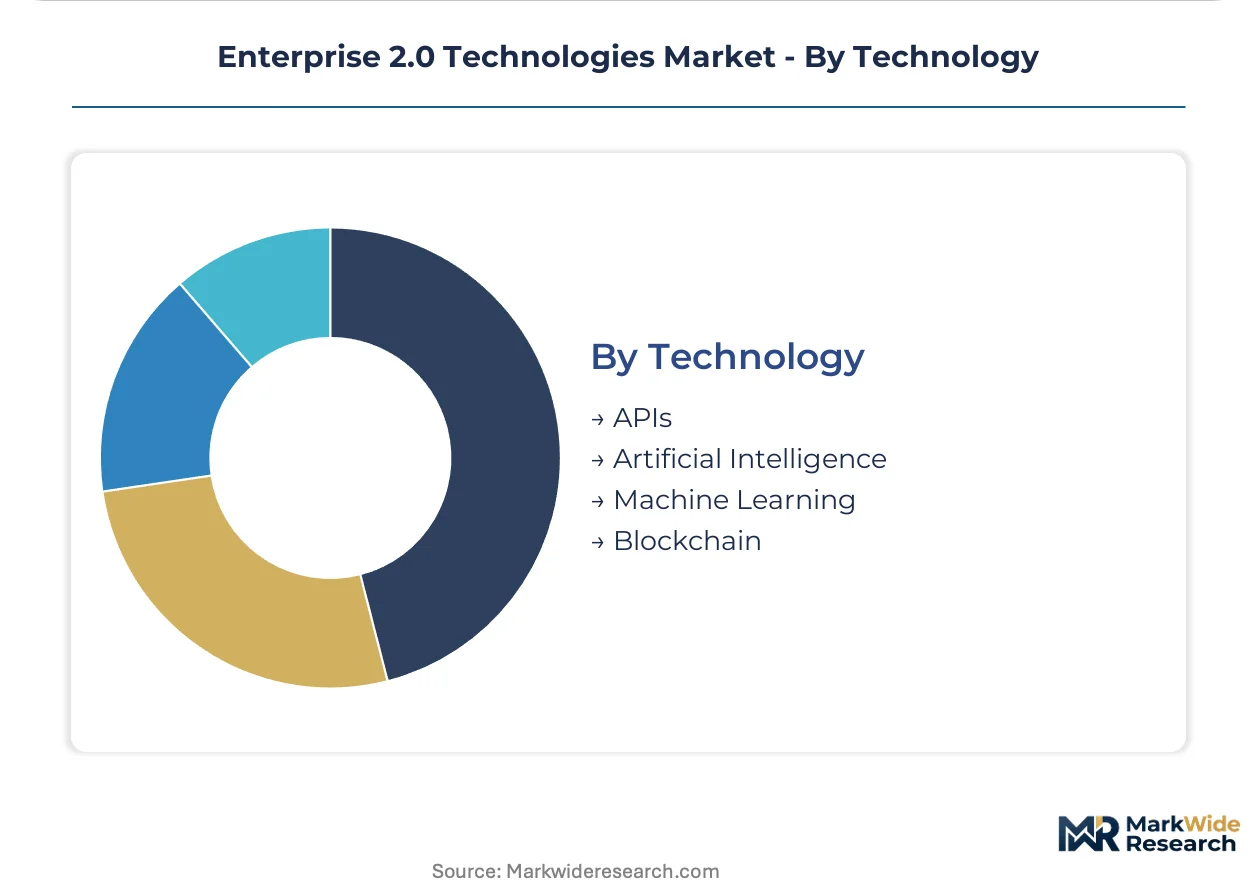
Margin architecture concentrates in AI-enhanced capabilities where proprietary model training and fine-tuning create differentiation, while API infrastructure commoditizes toward utility pricing.
- Artificial Intelligence:Predictive assistance, automated content generation, and intelligent workflow routing embedded throughout collaboration stacks. French banking groups in Paris are deploying these capabilities most aggressively, responding to ECB operational resilience expectations and ACPR digital governance guidelines.
- Machine Learning:Pattern recognition systems for anomaly detection in communication metadata and predictive resource allocation. Manufacturing enterprises in Gujarat, India are adopting these for supply chain coordination across distributed supplier networks.
- APIs:RESTful and GraphQL interfaces enabling third-party integration and custom application development.
- Blockchain:Distributed ledger implementations for immutable audit trails and decentralized identity verification.
Artificial Intelligence holds the largest share; Machine Learning shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act and SEC cybersecurity disclosure rules are redirecting procurement budgets toward compliant cloud architectures across major economies. Financial services and manufacturing enterprises in Germany, the United States, and India are accelerating platform replacements to satisfy algorithmic transparency mandates. Sovereign data requirements and workforce distribution patterns are reshaping vendor selection criteria in each market.
United States
Healthcare systems and federal contractors are consolidating vendor relationships around FedRAMP-authorized platforms that bundle security, infrastructure, and collaboration functions. SEC cybersecurity disclosure rules mandate board-level accountability for data breaches, converting compliance budgets into upgrade cycles. Technology clusters in Seattle and San Francisco are driving demand for unified platforms that collapse email, video conferencing, and project management into searchable knowledge graphs.
Germany
Automotive and industrial conglomerates in Stuttgart and Munich require EU AI Act-compliant explainability features for automated workflow systems. The country's risk-based AI classification system compels vendors to document decision pathways for algorithmic recommendation engines. Financial services firms in Frankfurt are replacing legacy communication infrastructure to satisfy ECB operational resilience expectations and data residency controls.
India
IT services firms in Bengaluru and Hyderabad favor SaaS deployment models for rapid global team provisioning without capital expenditure cycles. Discrete and process manufacturers in Maharashtra and Gujarat remain underpenetrated by AI-enhanced collaboration platforms, presenting first-mover opportunities. The RBI's operational resilience guidelines for financial institutions are accelerating cloud migration timelines among Mumbai-based banking groups.
France
Banking groups in Paris are deploying AI-enhanced capabilities most aggressively, responding to ACPR digital governance guidelines and algorithmic transparency requirements. The CNIL's enforcement posture on automated decision-making is shaping procurement specifications for explainable AI features. Industrial clusters in Lyon are adopting semantic search and enterprise knowledge retrieval systems to replace traditional intranet architectures.
United Kingdom
Financial services compliance teams in London are adopting natural language processing engines fastest, driven by FCA conduct supervision requirements for searchable client interaction records. The Financial Services and Markets Act provisions on operational resilience are compelling platform upgrades among City-based institutions. Professional services firms are expanding mid-market SaaS adoption, attracted by out-of-box integrations with existing productivity suites.
Enterprise 2.0 Technologies Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform ecosystems that bundle infrastructure, security, and collaboration functions under unified contracts. Hyperscale cloud providers and legacy enterprise software vendors dominate procurement shortlists in regulated sectors. Three strategic archetypes have emerged: cloud-native collaboration suites, Watson-enabled workflow automation platforms, and database-centric collaboration extensions. Competitive positioning depends on M&A activity to acquire AI capabilities and strategic partnerships to achieve multi-framework certification compliance.
Within the integrated platform tier, Microsoft Corporation, IBM Corporation, and Oracle Corporation occupy anchor positions representing distinct ecosystem strategies. Microsoft leverages its Azure infrastructure to bundle collaboration tools with compute and storage services, sustaining platform stickiness across large enterprise accounts. IBM anchors its market presence through workflow automation that integrates with legacy enterprise systems, while Oracle extends database-centric collaboration suites that exploit existing customer data architectures. These three exemplify how vendor-customer relationships are consolidating around cloud marketplaces and managed service intermediaries rather than direct enterprise sales channels.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Cisco Systems Inc |
| Dell Inc |
| Enghouse Systems |
| Avaya Inc |
| CafeX Communications Inc |
| Others |
Supply Flow & Price Mechanics
Bengaluru's hyperscale cloud infrastructure concentration shapes downstream pricing power for Enterprise 2.0 deployments, with compute scarcity in Indian data centers feeding margin compression into SaaS subscription tiers. The interplay between sovereign cloud capacity limitations and compliance-driven procurement urgency concentrates vendor leverage in regulated markets.
Pricing Analysis
Certification level (ISO 27001/SOC 2 Type II/FedRAMP-grade) creates the primary spread between enterprise and mid-market subscription tiers. Three-tier pricing structure across premium compliance-bundled, standard certified, and economy self-serve levels dominates contract structures. Pricing pressure stems from hyperscale cloud infrastructure input concentration, with AWS, Azure, and GCP controlling underlying compute layers. SMEs exhibit highest price sensitivity, while United States federal contractors accept premium tiers for FedRAMP authorization.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing and Samsung Foundry hold dominant capacity for AI accelerator chips powering NLP engines in communication platforms. Component sourcing draws from Taiwan, South Korea, and United States for advanced semiconductors, with memory modules anchored in South Korea and Japan. Single-source vulnerability in GPU supply creates bottleneck risk for generative AI feature rollouts. Distribution runs through hyperscale cloud marketplaces and managed service provider intermediaries rather than direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as regulatory divergence between EU AI Act risk classifications and US sectoral approaches creates architecture-specific niches. Procurement consolidation around integrated platforms has not eliminated white space for specialized compliance-native vendors.
For Market Incumbents: Pre-empt margin erosion in collaboration tools by embedding Watson-style workflow automation deeper into legacy ERP architectures. Defend against cloud-native entrants through backward integration into sovereign cloud infrastructure in Frankfurt and Singapore data centers. Certification investment in concurrent ISO 27001 and EU AI Act conformity assessment remains essential for regulated sector retention.
For New Entrants and Emerging Players: Build out localized deployment capabilities targeting Maharashtra and Gujarat manufacturing clusters, where AI-enhanced collaboration platforms remain underpenetrated. SaaS-native positioning with rapid provisioning avoids capital expenditure friction that slows incumbent sales cycles. Channel partnership with Indian IT services firms accelerates global team onboarding without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-engineering specialists with pre-built explainability frameworks for EU AI Act high-risk system classifications. Long-term viability hinges on cross-border deployability as regulatory fragmentation persists. Acquisition targets should demonstrate concurrent SOC 2 Type II and sector-specific attestation capabilities. Signal to monitor: divergence between ECB operational resilience enforcement and SEC cybersecurity disclosure implementation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified bundling of Azure infrastructure with Teams collaboration reduces procurement friction for United States healthcare systems. |
| Acquisition of Specialist Firm | Watson-enabled workflow automation purchases fill legacy ERP connectivity gaps for IBM's enterprise installed base. |
| Geographic Expansion | Localized sovereign cloud deployments in Stuttgart satisfy German automotive conglomerates' EU AI Act explainability mandates. |
| Strategic Partnership | Managed service provider alliances bypass direct sales channel consolidation for mid-market SaaS penetration. |
| Product Launch | Semantic search modules targeting Lyon industrial clusters replace traditional intranet architectures with knowledge graph capabilities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers, IT procurement officers, platform integration specialists, and compliance engineering leads at financial services and manufacturing enterprises. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and ISO certification registry data. Bottom-up deployment model sizing triangulated against top-down enterprise software spending analysis.
Calibration against historical adoption curves in collaboration technology and cloud migration patterns anchored projections across the analysis window. Segmentation dimensions modeled include deployment architecture, organization scale, vertical regulatory intensity, AI integration depth, and regional compliance framework. CAGRs derived from slope-consistent extrapolation of certified vendor penetration rates and sovereign cloud capacity expansion timelines. Forecast inputs incorporated EU AI Act enforcement phase transitions and SEC disclosure rule compliance deadlines.
Sensitivities concentrate around regulatory enforcement timing divergence and hyperscale cloud pricing power shifts. Forecasts embed assumptions regarding certification timeline standardization and legacy ERP API connectivity maturation. Quarterly review of FedRAMP authorization queues and EU AI Act high-risk system registration volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Contact Center Transformation Market