
 India Digital Transformation Market | 2026-2036
India Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Transformation Market Insights
The gap between premium digital consulting and commodity IT services is hardening as enterprise clients demand outcome-based contracts. Tata Consultancy Services anchors large-scale transformation programs across BFSI and manufacturing verticals. Infosys leverages its Cobalt cloud ecosystem to differentiate platform-led engagements. Wipro sustains competitive pressure through verticalized industry solutions and strategic partnerships.
India Digital Transformation encompasses the integration of cloud computing, artificial intelligence, Internet of Things, and big data analytics into enterprise operations to restructure business processes, customer engagement models, and decision architectures. The discipline requires API-first system design, microservices orchestration, and real-time data pipeline engineering to enable continuous operational feedback loops. Cloud computing dominates technology spending as enterprises exit legacy data center commitments. AI segments within enterprise resource planning and customer relationship management capture disproportionate margin pools due to scarcity of trained implementation specialists. Manufacturing end users lag retail and BFSI in deployment velocity, creating a structural expansion corridor for system integrators.
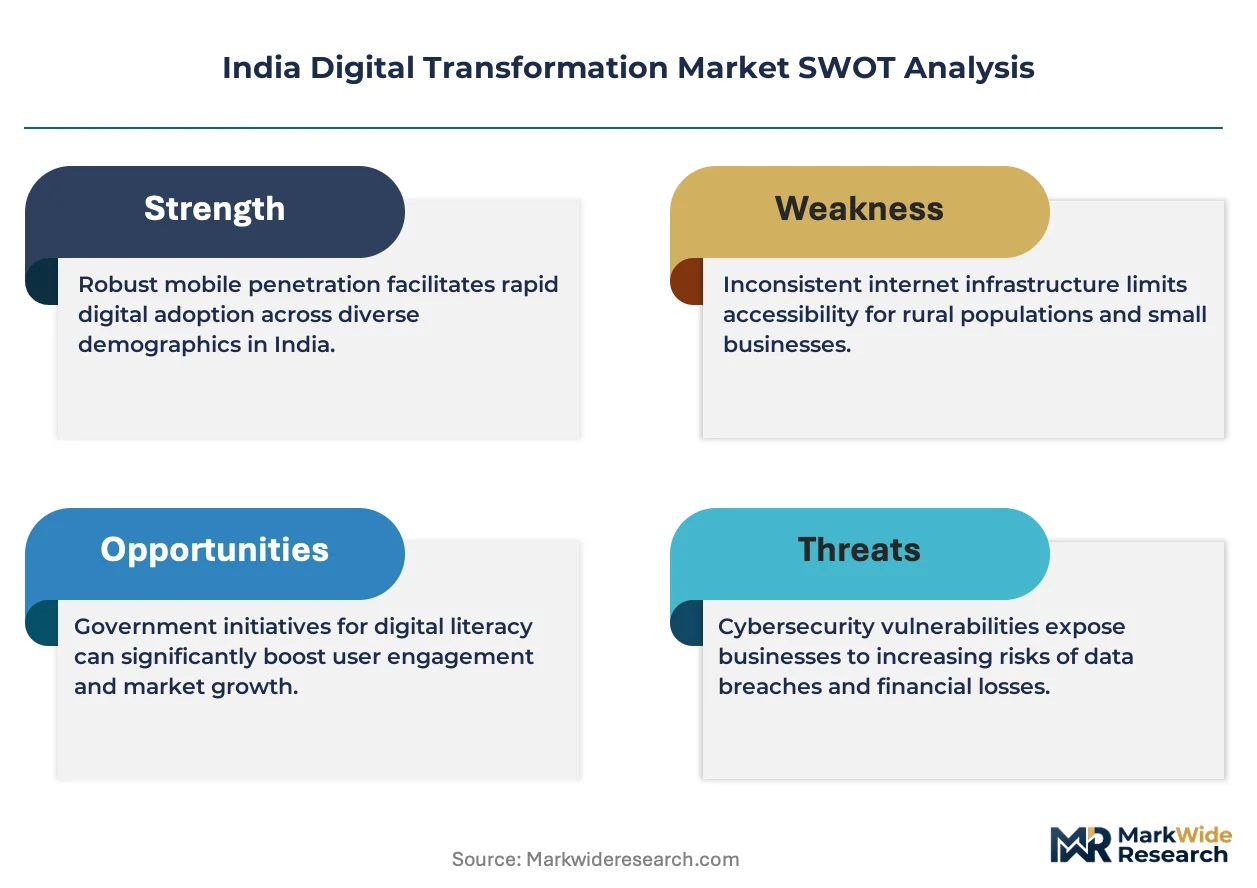
India's digital transformation agenda operates under RBI guidelines for digital lending, BIS standards for data localization, and TRAI frameworks governing cloud interconnection and telecom infrastructure. RBI's regulatory sandbox approach shapes product development timelines for fintech-integrated enterprise platforms. Stakeholders must monitor how CDSCO's emerging digital health record standards and state-level data center policies reshape compliance costs for healthcare and public sector verticals.
Market Dynamics
RBI's digital lending guidelines are compressing legacy core banking modernization timelines, forcing financial institutions into API-first architectures and cloud-native infrastructure commitments ahead of depreciation cycles.
Growth Catalysts
- Cloud Migration Mandates:BFSI enterprises in Maharashtra and Karnataka are exiting on-premise data center contracts under RBI's operational resilience directives, creating concentrated demand for hyperscale infrastructure.
- PLI Scheme Incentives:India's production-linked incentive scheme for IT hardware manufacturing is reducing server and networking equipment procurement costs for domestic system integrators.
- API-First Architecture:Microservices orchestration is displacing monolithic ERP deployments across retail and manufacturing verticals, enabling real-time inventory and customer data synchronization.
Market Restraints
- Data Localization Compliance:BIS standards for sensitive data storage within Indian territory are inflating infrastructure capex for multinational cloud providers establishing Mumbai and Chennai regions.
- Specialist Talent Scarcity:Implementation engineers certified in AI-integrated ERP and CRM platforms command compensation premiums that compress system integrator margins on fixed-price contracts.
- Legacy Technical Debt:COBOL and mainframe-dependent public sector banks face 18-24 month migration timelines that delay revenue recognition for transformation vendors.
Strategic Opportunities
- Manufacturing Vertical Expansion:Industrial IoT and predictive maintenance deployments in Gujarat and Tamil Nadu automotive clusters lag retail and BFSI adoption by 3-4 years, creating whitespace for verticalized solution providers.
- Digital Health Record Standards:CDSCO's emerging interoperability frameworks for hospital information systems will mandate nationwide EMR upgrades, opening healthcare infrastructure contracts.
- Edge Computing Convergence:5G network slicing combined with containerized microservices is enabling low-latency factory automation in Pune and Hosur industrial corridors.
Industry Challenges
- Certification Bottlenecks:TRAI's cloud service provider licensing requirements and BIS cybersecurity certifications extend vendor onboarding timelines by 6-9 months, delaying project kickoffs.
- Interoperability Complexity:State-level data center policies in Telangana and Uttar Pradesh create fragmented compliance architectures that inflate integration engineering hours for national deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Transformation Market |
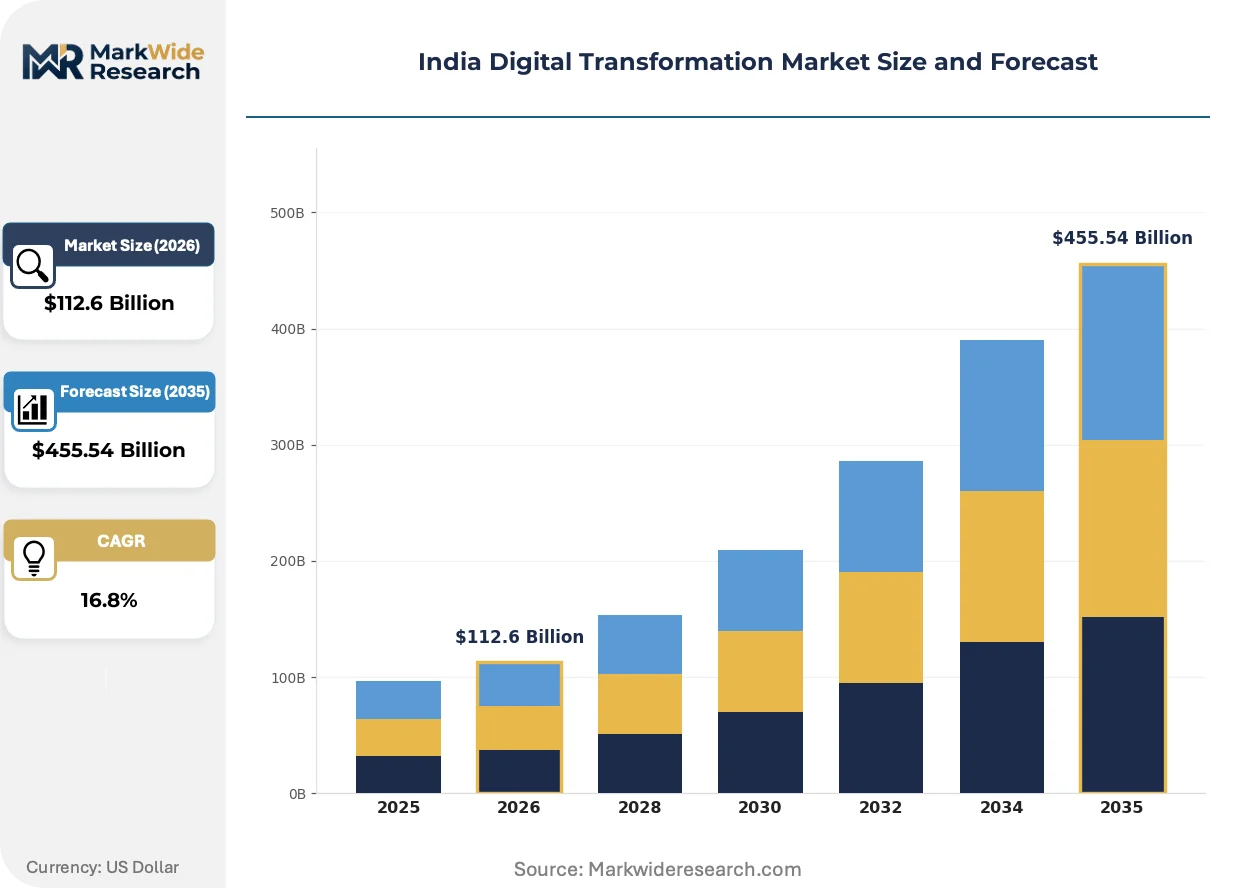
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $455.54 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, AI, IoT, Big Data Application: Enterprise Resource Planning, Customer Relationship Management, Supply Chain Management, E-Commerce End User: Manufacturing, Retail, BFSI, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Tata Consultancy Services, Infosys, Wipro, HCL Technologies, Tech Mahindra, Accenture, Larsen & Toubro Infotech, IBM, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Transformation Market Trends and Innovations
Generative AI copilots are compressing enterprise software implementation cycles, while regulatory sandboxes accelerate fintech product validation. Sovereign cloud requirements are reshaping vendor selection criteria across public sector procurement.
Agentic AI is integrating into ERP and CRM workflows to automate exception handling and predictive forecasting. Mid-market manufacturing enterprises in Coimbatore and Nagpur are piloting these capabilities at 40% faster deployment velocity than tier-1 counterparts. The technology is integrating operational data lakes with natural language interfaces, collapsing the business analyst layer between line managers and system outputs.
SEBI's framework for cloud adoption by market infrastructure institutions mandates multi-region disaster recovery and encryption standards for capital markets data. Asset management companies and stockbrokers must re-architect trading platforms to meet these specifications by Q4 2025. Compliance costs are concentrating among smaller broker-dealers in Ahmedabad and Indore, triggering consolidation into technology-sharing networks.
Enterprise buyers are unbundling transformation contracts into discrete outcome-based work packages with penalty clauses for milestone slippage. System integrators now compete for individual sprint deliverables rather than multi-year program mandates. This pattern is most visible in Karnataka's technology services procurement, where state government digitalization projects require weekly velocity demonstrations and automatic termination triggers.
India Digital Transformation Market Segmentation
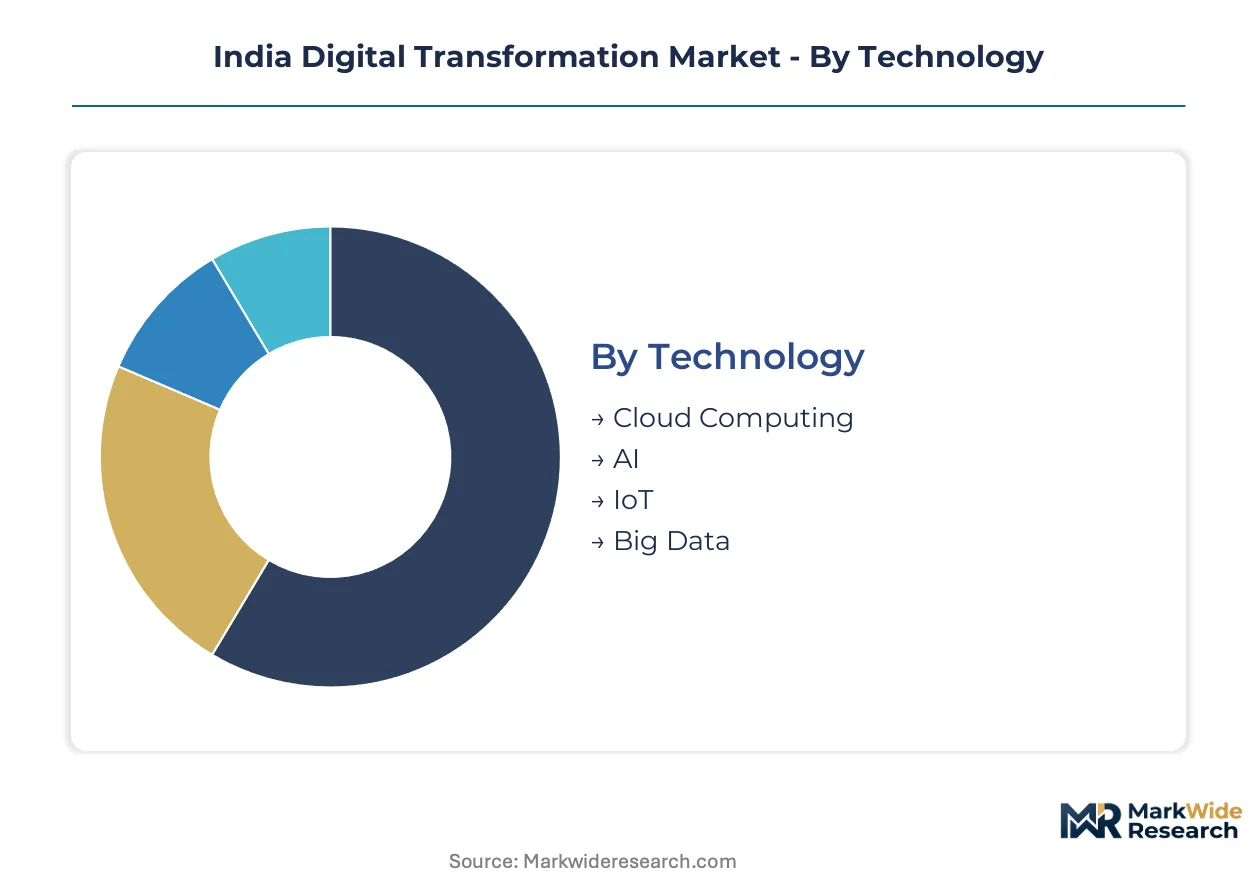
Segmentation in India's digital transformation market reveals how capital allocation, regulatory pressure, and operational maturity create divergent investment patterns across technology layers and deployment models. Understanding these fault lines helps vendors calibrate solution architectures and pricing frameworks to specific buyer readiness levels.
Technology:
Cloud computing demands the heaviest upfront infrastructure commitment among all technology segments, with hyperscale capacity expansion in Mumbai and Bangalore consuming disproportionate capex relative to software-only deployments.
- Cloud Computing:Hyperscale infrastructure and distributed data center networks form the foundational layer for enterprise workload migration. Maharashtra and Karnataka enterprises under RBI operational resilience directives are driving concentrated demand for multi-availability-zone architectures.
- AI:Machine learning operations platforms and generative AI copilots require specialized GPU clusters and MLOps engineering talent that commands compensation premiums. BFSI institutions in Mumbai deploy these capabilities for credit risk modeling and fraud detection at scale.
- IoT:Sensor networks and edge gateway deployments enable predictive maintenance in industrial settings. Gujarat automotive clusters pilot these systems for supply chain visibility.
- Big Data:Data lake architectures and real-time pipeline engineering support operational analytics. Retail enterprises leverage these platforms for customer segmentation and inventory optimization.
Cloud computing absorbs the bulk of installed capacity; AI is expanding most quickly.
Application:
Enterprise resource planning implementations carry the longest payback periods and highest change management costs, creating natural segmentation between tier-1 manufacturers and mid-market adopters.
- Enterprise Resource Planning:Core financial and operational modules require 18-24 month deployment cycles with extensive legacy system integration. Manufacturing verticals in Tamil Nadu and Pune industrial corridors represent the primary demand concentration for cloud-native ERP replacements.
- Customer Relationship Management:Sales force automation and service desk platforms deploy faster with lower customization overhead. Retail and BFSI verticals adopt these systems to unify omnichannel customer touchpoints and comply with RBI data localization mandates.
- Supply Chain Management:Inventory optimization and logistics orchestration tools address fragmentation in multi-tier supplier networks. Automotive and electronics manufacturers deploy these solutions for just-in-time coordination.
- E-Commerce:Digital storefront and payment gateway integrations serve direct-to-consumer business models. Mid-market retailers in tier-2 cities accelerate adoption post-PLI scheme incentives for logistics infrastructure.
Enterprise resource planning dominates current spending; customer relationship management is gaining share fastest.
End User:
BFSI institutions face the most compressed modernization timelines due to regulatory mandates, while manufacturing exhibits the widest gap between leader and laggard adoption curves.
- BFSI:Banks and insurance carriers modernize core banking platforms under RBI digital lending guidelines and SEBI cloud adoption frameworks. Public sector banks with COBOL dependencies face 18-24 month migration timelines that delay vendor revenue recognition.
- Retail:Omnichannel commerce and inventory synchronization drive technology spending. Organized retailers deploy AI-powered demand forecasting ahead of traditional competitors.
- Manufacturing:Industrial IoT and predictive maintenance adoption lags retail and BFSI by 3-4 years, creating whitespace for verticalized solution providers in Gujarat and Tamil Nadu automotive clusters.
- Healthcare:Hospital information systems and electronic medical record platforms await CDSCO interoperability standards. Diagnostic chains and multi-specialty hospitals pilot digital health infrastructure ahead of nationwide mandates.
BFSI captures the largest share of transformation budgets; manufacturing shows the steepest expansion trajectory.
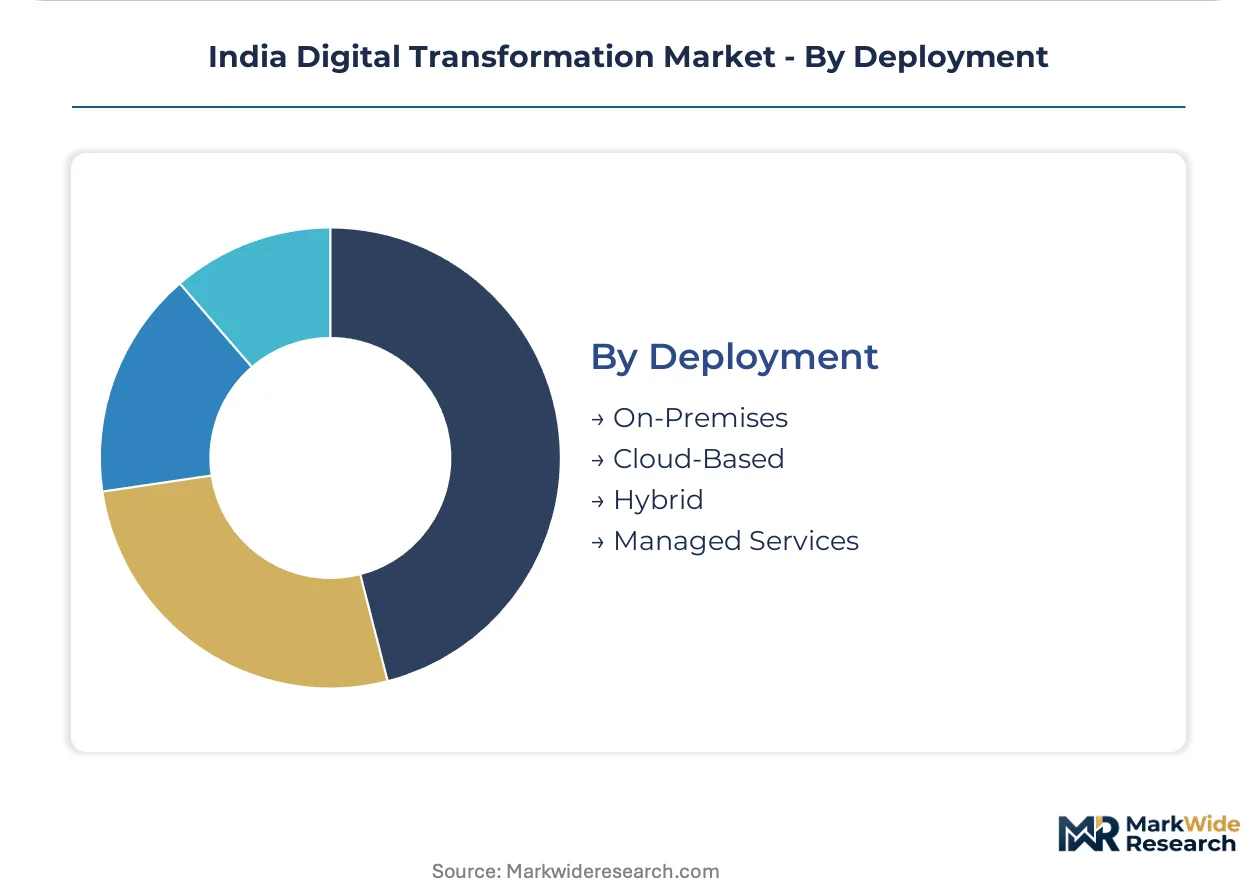
Deployment:
Managed services models concentrate recurring revenue with system integrators, while hybrid deployments split infrastructure ownership between enterprise IT and cloud providers.
- Cloud-Based:Fully outsourced infrastructure eliminates data center ownership costs and enables consumption-based scaling. BFSI enterprises in Maharashtra and Karnataka exit on-premise contracts under RBI operational resilience directives.
- Hybrid:Split workloads between private infrastructure and public cloud preserve sensitive data on-premises while leveraging elastic compute. Manufacturing enterprises favor this model for intellectual property protection.
- On-Premises:Legacy data center retention persists in public sector banks and defense-adjacent industries with stringent security requirements. These deployments face depreciation cycle lock-in that delays cloud migration decisions.
- Managed Services:Third-party operation of infrastructure and application layers transfers operational risk to specialized providers. Mid-market enterprises adopt this model to overcome internal talent scarcity.
Cloud-based deployment holds the majority of new project starts; managed services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Bangalore host the densest enterprise data center clusters in India, driving concentrated cloud migration demand across Maharashtra and Karnataka. State-level data center policies and RBI operational resilience directives are reshaping infrastructure deployment patterns nationwide.
Maharashtra
BFSI enterprises in Mumbai are exiting on-premise data center contracts under RBI's digital lending guidelines and operational resilience directives. The state's data center policy offers power tariff incentives and single-window clearances for hyperscale facilities. Mumbai's financial district anchors multi-availability-zone cloud architectures for banks modernizing core systems.
Karnataka
Technology services procurement in Bangalore demands weekly velocity demonstrations and automatic termination triggers on state government digitalization projects. The state's startup policy and IT park infrastructure attract system integrators building AI-integrated ERP platforms. Bangalore's enterprise corridor concentrates managed services adoption among mid-market manufacturers.
Gujarat
Automotive clusters in Sanand and Halol pilot industrial IoT and predictive maintenance systems for supply chain visibility. The state's electronics manufacturing policy complements PLI scheme incentives for IT hardware procurement. Ahmedabad's smaller broker-dealers face SEBI cloud compliance cost concentration, triggering technology-sharing network consolidation.
Tamil Nadu
Pune and Hosur industrial corridors enable 5G network slicing combined with containerized microservices for low-latency factory automation. The state's electronics and hardware manufacturing policy reduces server procurement costs for domestic system integrators. Chennai's automotive belt lags retail and BFSI adoption by 3-4 years, creating whitespace for verticalized solution providers.
Telangana
State-level data center policies in Hyderabad create fragmented compliance architectures that inflate integration engineering hours for national deployments. TRAI's cloud service provider licensing requirements extend vendor onboarding timelines by 6-9 months. The city's pharmaceutical and IT corridor awaits CDSCO digital health record standards for nationwide EMR upgrade mandates.
India Digital Transformation Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform architects for enterprise transformation budgets. The vendor base separates into three strategic tiers: hyperscale cloud providers owning data center assets, system integrators orchestrating multi-vendor implementations, and boutique specialists delivering vertical-specific solutions. Consolidation pressures concentrate among mid-tier players as outcome-based contracting compresses margin pools. Dominant competitive moves include strategic partnerships for sovereign cloud compliance and verticalized industry solution development.
Within the system integrator tier, Tata Consultancy Services, Infosys, and Wipro occupy anchor positions representing distinct competitive approaches. Tata Consultancy Services exemplifies large-scale program delivery across regulated verticals. Infosys occupies a platform-led differentiation position through cloud ecosystem investments. Wipro represents verticalized solution specialization with partnership-heavy market access. These three Indian-origin limited companies compete against multinational technology corporations including Accenture, IBM, and Microsoft for BFSI and manufacturing transformation contracts.
| Leading Market Players |
|---|
| Tata Consultancy Services |
| Infosys |
| Wipro |
| HCL Technologies |
| Tech Mahindra |
| Accenture |
| Larsen & Toubro Infotech |
| IBM |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
AI-ML engineering talent concentration in Bangalore and Hyderabad widens pricing spreads between premium outcome-based contracts and fixed-scope engagements. Labor-cost differentials between certified MLOps specialists and commodity implementation engineers force tiered service pricing across Maharashtra and Karnataka enterprise buyers.
Pricing Analysis
Outcome-based pricing anchored to system uptime and transaction throughput dominates BFSI transformation contracts under RBI operational resilience mandates. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale cloud-native deployments from lift-and-shift migrations and maintenance-only engagements. Pricing pressure stems from outcome-based penalty clauses and automatic termination triggers in Karnataka state procurement. Mid-market manufacturers in tier-2 cities exhibit highest price sensitivity; Mumbai financial institutions show lowest.
Supply Chain Analysis
Dual-sourcing requirements for GPU clusters and hyperscale infrastructure mandate multi-cloud qualification across AWS, Azure, and domestic sovereign cloud providers. Hardware supply concentrates in China, Taiwan, and South Korea for server components and networking equipment. Software licensing draws from US, Ireland, and India-based ISVs. Single-source vulnerability in specialized AI chip supply creates procurement risk. Distribution runs through system integrator-led consortia with hyperscaler direct contracts for largest BFSI accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India digital transformation market is becoming a vertical-integration race as system integrators pursue captive cloud infrastructure assets to defend margin pools against hyperscaler disintermediation.
For Market Incumbents: Acquire sovereign cloud certification capabilities and Mumbai-Chennai data center assets to meet BIS localization mandates. Lock in multi-year managed services contracts with public sector banks before COBOL migration timelines compress. Defend against boutique AI specialists by embedding generative AI copilots into existing ERP maintenance relationships.
For New Entrants and Emerging Players: RBI's digital lending guidelines in India open a window for API-first core banking specialists to target regional banks in Gujarat and Tamil Nadu underserved by tier-1 integrators. Focus manufacturing IoT deployments on predictive maintenance whitespace in Pune and Hosur automotive clusters. Go-to-market through technology-sharing networks consolidating Ahmedabad broker-dealers facing SEBI compliance cost pressure.
For Investors and Strategic Acquirers: Re-rating potential sits with verticalized healthcare IT specialists given CDSCO's emerging digital health record interoperability mandates. Long-term viability favors platform-agnostic system integrators with sovereign cloud credentials and state-level procurement relationships. Watch SEBI enforcement action on cloud adoption deadlines as inflection indicator for consolidation velocity among capital markets technology providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BIS data localization compliance unlocks public sector contracts restricted to domestic infrastructure. |
| Vertical AI Platform Development | Generative AI copilots embedded in ERP workflows capture manufacturing clients ahead of CDSCO mandates. |
| Hyperscale Partnership Restructuring | Revised revenue-sharing with AWS and Azure preserves margins on outcome-based BFSI engagements. |
| Edge Computing Infrastructure Buildout | 5G network slicing deployments in Pune industrial corridors enable low-latency factory automation contracts. |
| Regulatory Sandbox Participation | RBI sandbox access accelerates fintech-integrated product validation for banking transformation programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with RBI circulars, SEBI disclosure filings, TRAI licensing databases, and hyperscaler capex disclosures. Bottom-up project pipeline analysis triangulated against top-down technology spending estimates from BFSI and manufacturing verticals.
Segment-level modeling addressed deployment model, organization size, vertical, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from weighted technology diffusion curves and regulatory deadline impacts. Forecast inputs included RBI digital lending compliance timelines, PLI scheme incentive trajectories, and state-level data center policy implementation rates.
The model assumes a particular technology adoption path; alternative pathways for agentic AI integration would alter the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and hyperscaler infrastructure expansion commitments. Deviation in BIS certification timelines or TRAI licensing processing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Global Design Thinking Market