
 Vehicle Routing and Scheduling Market | 2026-2036
Vehicle Routing and Scheduling Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Routing and Scheduling Market Analysis
E-commerce retailers is redrawing procurement priorities across the Vehicle Routing and Scheduling landscape as last-mile complexity outpaces legacy planning tools. Verizon Connect anchors its position through deep integration with telematics hardware, while ORTEC specializes in high-constraint optimization for parcel and grocery delivery networks. The Descartes Systems Group Inc. extends its footprint by controlling customs and trade compliance data streams that feed directly into routing engines.
Vehicle Routing and Scheduling encompasses algorithmic systems that compute optimal path sequences, load assignments, and time-window adherence for commercial fleets, typically processing real-time traffic, vehicle capacity, and driver-hour constraints through mixed-integer programming or metaheuristic engines. Its primary purpose is minimizing total transportation cost while satisfying service-level agreements across distributed supply networks. Optimization Software captures the dominant margin pool as shippers prioritize fuel and labor savings over visibility layers, while Cloud-Based deployment is gaining fastest among mid-market freight carriers seeking lower total cost of ownership. Fleet Management Systems remain mature with slower growth as hardware-software bundling compresses differentiation.
The EPA shapes product standards through emissions compliance mandates that require verifiable fuel-reduction documentation, while the EMA's transport-related sustainability disclosure rules under CSRD extend accountability to European logistics chains. The KBA enforces Germany's CO2 fleet targets, creating market access barriers for routing vendors lacking emissions verification modules. Stakeholders must decide whether to build in-house optimization stacks or partner with specialists as regulatory granularity tightens across jurisdictions.
Market Dynamics
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are forcing fleet operators to adopt algorithmic route optimization as a verifiable compliance mechanism, transforming routing software from cost-saving tool to regulatory infrastructure.
Growth Catalysts
- Last-mile complexity surge:E-commerce order fragmentation exceeds legacy planning capacity, driving third-party logistics providers toward multi-modal optimization platforms that synchronize parcel, grocery, and same-day delivery networks.
- CSRD disclosure mandates:The EMA's transport-related sustainability reporting rules under CSRD extend emissions accountability to European logistics chains, requiring documented fuel-reduction per shipment.
- German enforcement density:The KBA's strict CO2 fleet targets in Germany create procurement urgency for routing vendors with embedded emissions verification modules.
Market Restraints
- Telematics hardware bundling:Fleet Management Systems face margin compression as hardware-software integration locks customers into bundled contracts with limited optimization flexibility.
- Legacy system integration costs:Enterprise shippers with entrenched ERP and TMS platforms face high switching costs to deploy cloud-native routing engines requiring real-time data architecture overhaul.
- Driver-hour constraint rigidity:EU Working Time Directive enforcement limits algorithmic flexibility in European operations, capping potential efficiency gains from route optimization alone.
Strategic Opportunities
- Mid-market cloud migration:Freight carriers in the 50-500 vehicle segment seek lower total cost of ownership through SaaS deployment models, bypassing capital-intensive on-premise installations.
- Customs-data convergence:Trade compliance data streams from cross-border operations can feed directly into routing engines, enabling dynamic re-routing around port congestion and documentation delays.
- AI-act readiness:The EU AI Act's risk classification for automated decision-making systems creates first-mover advantage for vendors with explainable optimization algorithms and audit-ready documentation.
Industry Challenges
- Operations research talent scarcity:Mixed-integer programming and metaheuristic expertise concentrates in academic and specialized consulting channels, limiting vendor scaling velocity.
- Real-time data latency:Traffic feed integration and telematics synchronization require sub-second processing infrastructure that strains legacy carrier IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Routing and Scheduling Market |
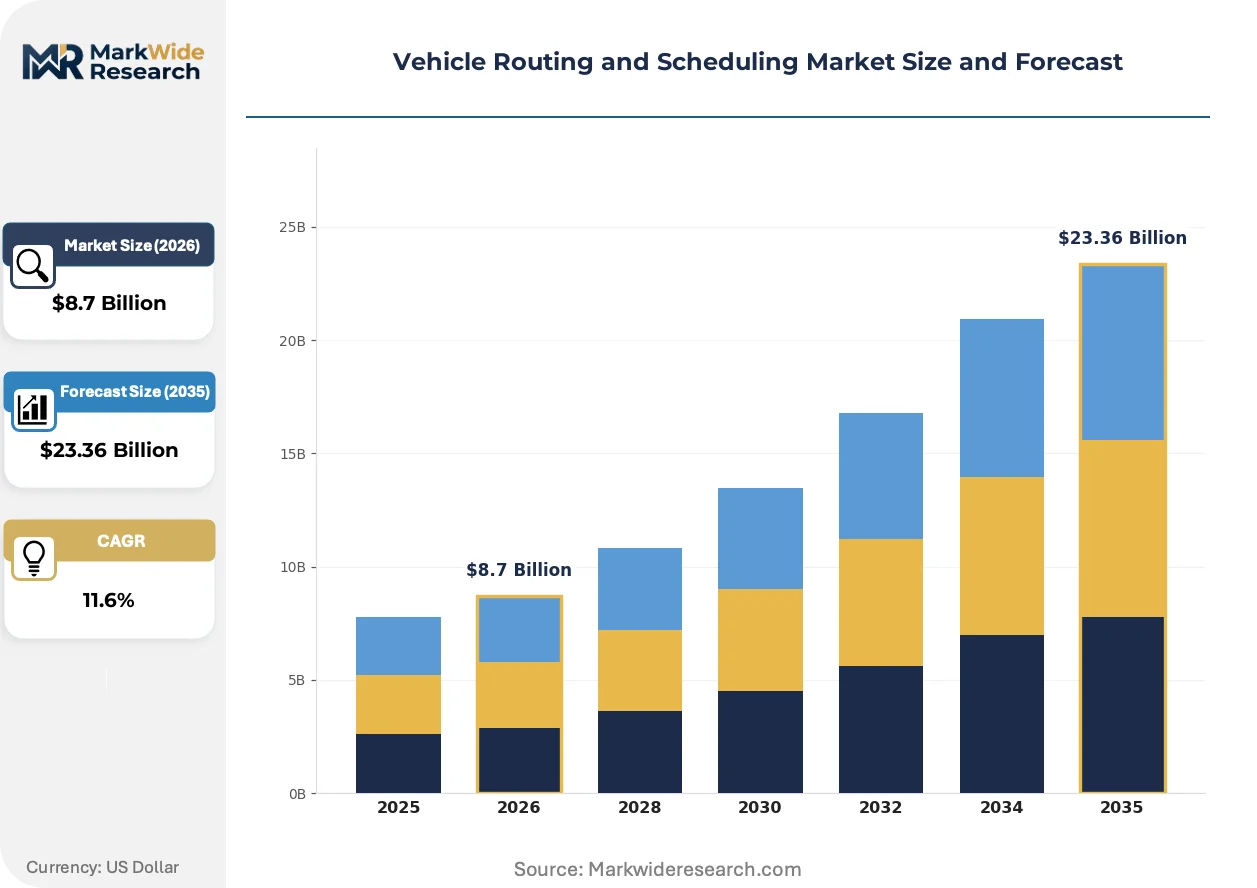
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Optimization Software, Fleet Management Systems, Real-Time Tracking, Route Planning Tools Deployment Model: On-Premise, Cloud-Based, Hybrid, Enterprise Solutions End User: Logistics Providers, Freight Carriers, E-Commerce Retailers, Public Transportation Vehicle Type: Light-Duty Vehicles, Heavy-Duty Trucks, Buses, Delivery Vans |
| Companies Covered | OptimoRoute, Inc., Verizon Connect, Route4Me, Inc., The Descartes Systems Group Inc., ORTEC, Trimble Inc., Paragon Software Systems plc, Omnitracs, Manhattan Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Routing and Scheduling Market Emerging Trajectories
Algorithmic decision-making is penetrating deeper into fleet operations, with optimization engines now governing not just routing but load consolidation, driver scheduling, and predictive maintenance sequencing.
Quantum-inspired optimization is decomposing traditional heuristic approaches to vehicle routing problems. D-Wave and classical quantum annealing hybrids process multi-constraint scenarios—time windows, capacity limits, driver regulations—faster than conventional solvers. Parcel carriers with high-density urban networks are piloting these systems for same-day delivery windows. The technology is decomposing the competitive advantage of established vendors whose metaheuristic engines cannot scale to million-node problem sets.
The EPA's SmartWay verification program now requires documented fuel-reduction methodologies for participating carriers, elevating algorithmic route optimization from operational preference to compliance infrastructure. Heavy-duty fleet operators must submit verifiable per-mile consumption improvements to maintain program standing. Long-haul trucking segments in the US are responding by mandating optimization software procurement in RFP processes for contracted lanes.
Shippers are unbundling visibility and optimization contracts, rejecting bundled telematics-routing packages in favor of best-of-breed algorithmic engines. Large retailers with private fleets now separate hardware procurement from software licensing, selecting routing vendors on constraint-handling capability rather than device integration. This pattern is most visible in Germany, where logistics density supports specialized vendor evaluation and the KBA's emissions documentation requirements favor modular, auditable systems over bundled offerings.
Vehicle Routing and Scheduling Market Segmentation
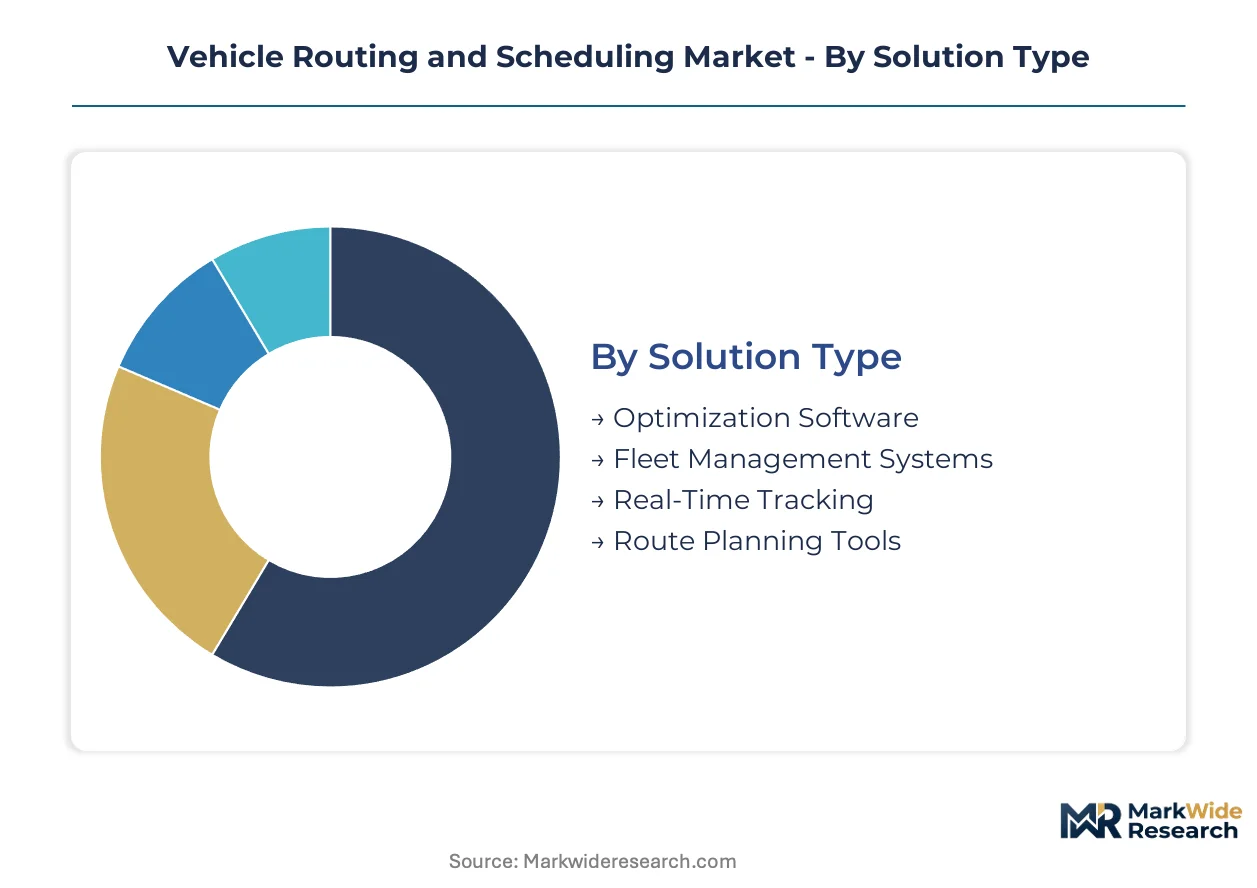
Segmentation in vehicle routing and scheduling reveals how procurement priorities diverge across operational scales and regulatory exposure. Fleet operators select solution architectures based on constraint complexity, while deployment preferences track IT maturity and capital availability.
Solution Type:
Margin pools concentrate in algorithmic optimization layers where fuel and labor savings translate directly to operating income, while hardware-coupled systems face commoditization pressure.
- Optimization Software:Mixed-integer programming and metaheuristic engines process multi-constraint scenarios including time windows, capacity limits, and driver-hour regulations. Third-party logistics providers in Germany are prioritizing procurement here as the KBA's emissions documentation requirements demand verifiable fuel-reduction methodologies per shipment.
- Fleet Management Systems:Telematics hardware-software bundles dominate installed base but face margin compression as shippers unbundle visibility from optimization contracts. EPA SmartWay verification requirements are accelerating separation of routing algorithms from device-centric platforms.
- Real-Time Tracking:GPS and sensor-based location services provide positional awareness without path optimization.
- Route Planning Tools:Static sequence calculators serve smaller fleets with predictable demand patterns.
The dominant share belongs to Optimization Software, while Real-Time Tracking is closing the gap fastest as e-commerce fragmentation demands granular shipment visibility.
Deployment Model:
Cost tier structure separates capital-intensive infrastructure from recurring SaaS expenditure, with hybrid architectures capturing operators navigating legacy system transitions.
- Cloud-Based:Subscription models eliminate upfront server investment and accelerate deployment for mid-market freight carriers. The 50-500 vehicle segment across European logistics corridors is migrating here to bypass on-premise installation complexity and satisfy CSRD audit trail requirements through vendor-managed infrastructure.
- On-Premise:Dedicated server installations persist among defense contractors and classified cargo operators with data sovereignty mandates.
- Hybrid:Split processing architectures keep sensitive route data local while leveraging cloud scalability for computation-heavy optimization runs.
- Enterprise Solutions:Custom-configured deployments serve multinational retailers with private fleet operations requiring ERP integration.
Cloud-Based deployment is expanding most quickly among mid-market carriers, though Enterprise Solutions retain the highest contract values per seat.
End User:
Application intensity varies sharply by sector, with parcel networks demanding sub-minute re-optimization while public transit operates on fixed-schedule horizons.
- Logistics Providers:Third-party operators managing multi-modal freight networks require constraint-handling across parcel, grocery, and same-day delivery verticals.
- E-Commerce Retailers:Order fragmentation and customer delivery windows drive algorithmic procurement for last-mile density. Large retailers with private fleets are separating hardware from software licensing, selecting vendors on optimization capability rather than device integration.
- Freight Carriers:Long-haul trucking segments are mandating optimization software in RFP processes for contracted lanes to satisfy EPA SmartWay fuel-reduction documentation.
- Public Transportation:Fixed-route operators prioritize schedule adherence over dynamic re-routing, constraining algorithmic sophistication requirements.
E-Commerce Retailers command the steepest expansion trajectory, while Public Transportation offers limited growth due to budget cycles and procurement rigidity.
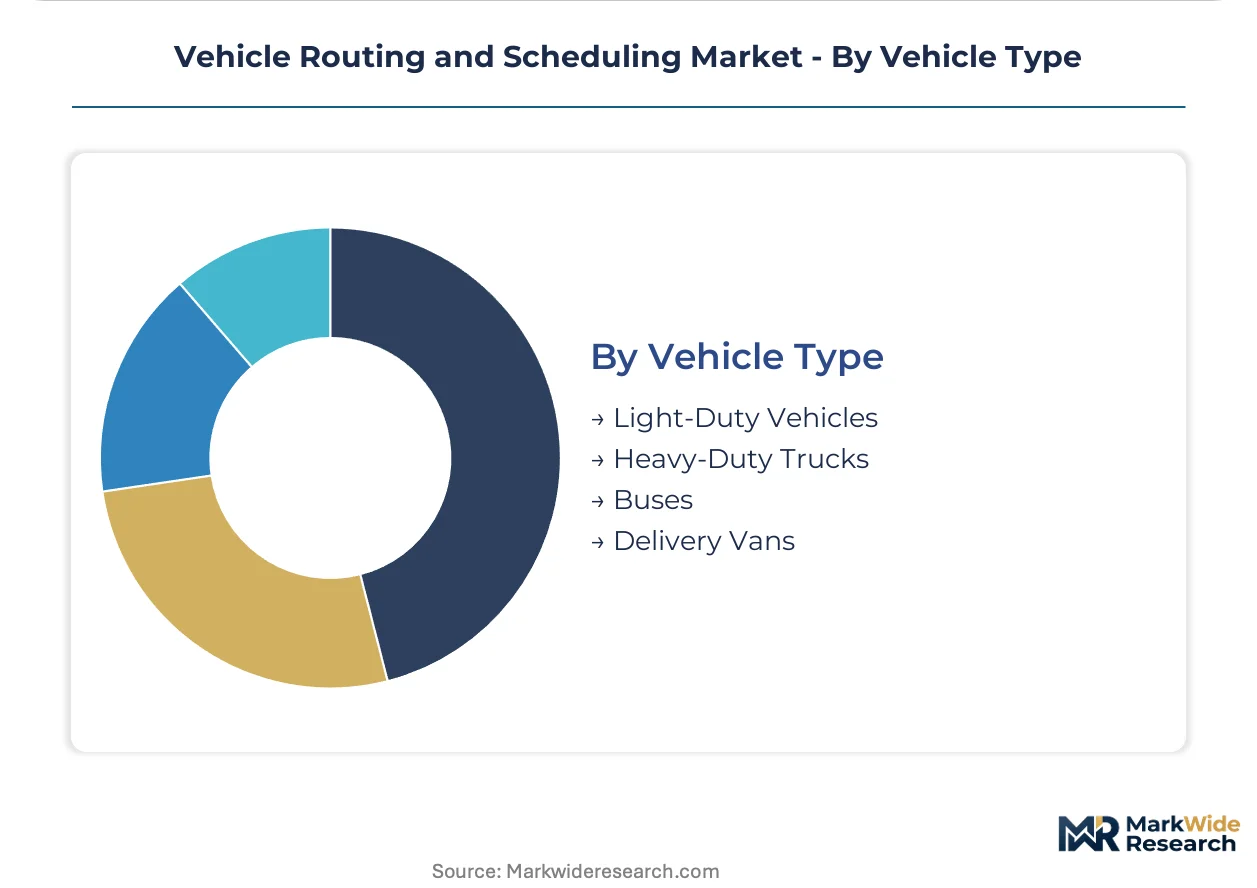
Vehicle Type:
Regulatory load differs dramatically by weight class, with heavy-duty segments facing EPA Phase 3 compliance pressure that light-duty operators largely avoid.
- Heavy-Duty Trucks:Class 8 vehicles face the strictest emissions accountability under EPA greenhouse gas standards. Fleet operators must submit verifiable per-mile consumption improvements, transforming routing software from cost-saving tool to compliance infrastructure.
- Delivery Vans:Urban parcel density supports electric vehicle transition where range optimization algorithms maximize battery utilization. German grocery and parcel networks are piloting quantum-inspired solvers for same-day window compliance.
- Light-Duty Vehicles:Service technician and sales fleets prioritize driver productivity over fuel minimization.
- Buses:Fixed-route public transit operates on published schedules with limited dynamic optimization scope.
Heavy-Duty Trucks anchor current revenue concentration, though Delivery Vans are gaining share fastest as electrification multiplies the value of range-optimizing algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algorithmic routing vendors cluster in Germany, the United States, and the Netherlands where logistics density and regulatory pressure converge. The KBA, EPA, and EMA have each imposed emissions accountability frameworks that transform route optimization from cost-saving tool to compliance infrastructure.
Germany
The KBA enforces CO2 fleet targets that demand documented fuel-reduction per shipment, accelerating procurement of optimization software with embedded emissions verification. Third-party logistics providers in the Ruhr logistics corridor and Frankfurt Rhine-Main region are unbundling hardware-software contracts to select vendors on constraint-handling capability alone. Parcel and grocery networks in Berlin and Hamburg are piloting quantum-inspired solvers for same-day delivery windows.
United States
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles mandate verifiable per-mile consumption improvements, elevating routing software to regulatory infrastructure. Long-haul trucking segments now require optimization software in RFP processes for contracted lanes to maintain SmartWay program standing. Fleet operators in the Chicago freight hub and Los Angeles-Long Beach port complex are deploying cloud-native engines to satisfy documentation requirements.
Netherlands
The EMA's transport-related sustainability disclosure rules under CSRD extend emissions accountability to European logistics chains headquartered in Rotterdam and Amsterdam. Mid-market freight carriers in the 50-500 vehicle segment are migrating to SaaS deployment models to bypass capital-intensive installations. The Randstad logistics cluster supports specialized vendor evaluation where modular, auditable systems displace bundled telematics offerings.
United Kingdom
CSRD-aligned sustainability reporting pressures logistics operators to document fuel-reduction methodologies across distributed supply networks. E-commerce retailers with private fleets in the Midlands distribution belt are separating hardware procurement from software licensing. London's last-mile density is driving algorithmic procurement for parcel networks managing order fragmentation and customer delivery windows.
France
ANSM and CNIL oversight creates dual compliance pressure for automated decision-making systems in logistics operations. Île-de-France grocery and parcel networks require constraint-handling across multi-modal freight corridors. The Auvergne-Rhône-Alpes manufacturing belt is generating demand for optimization engines that synchronize production schedules with fleet routing.
Vehicle Routing and Scheduling Market Vendor Landscape
Concentration sits with specialized optimization vendors rather than bundled telematics providers. The vendor base spans three tiers: algorithmic specialists processing multi-constraint scenarios through mixed-integer programming, hardware-coupled platforms facing margin compression from unbundling trends, and cloud-native entrants targeting mid-market SaaS migration. Dominant competitive moves include strategic partnerships with trade compliance data providers and portfolio diversification into predictive maintenance sequencing.
Among Netherlands-based optimization specialists, ORTEC exemplifies the high-constraint algorithmic tier with deep expertise in parcel and grocery delivery networks. Verizon Connect anchors the telematics-integrated segment through hardware-software bundling that now faces procurement resistance from large retailers. The Descartes Systems Group Inc. occupies a position at the customs-data convergence point, where trade compliance streams feed directly into routing engines for dynamic re-routing around port congestion.
| Leading Market Players |
|---|
| OptimoRoute, Inc. |
| Verizon Connect |
| Route4Me, Inc. |
| The Descartes Systems Group Inc. |
| ORTEC |
| Trimble Inc. |
| Paragon Software Systems plc |
| Omnitracs |
| Manhattan Associates |
| Others |
Supply Flow & Price Mechanics
Fourteen-day implementation cycles for cloud-native routing engines concentrate procurement leverage among German third-party logistics providers, compressing margins for vendors without embedded emissions verification while amplifying pricing power for optimization specialists with KBA-compliant audit trails.
Pricing Analysis
EPA SmartWay verification dictates the pricing tier structure across the Vehicle Routing and Scheduling landscape, separating bundled telematics-routing packages from modular algorithmic engines. Three-tier pricing structure across premium, standard, and economy levels stratifies by constraint-handling sophistication and CSRD audit-readiness, with premium tiers commanding differentiation through quantum-inspired solver capabilities. Cost compression in standard tiers is intensifying because mid-market carriers migrate to SaaS models with lower switching costs. Freight carriers in the 50-500 vehicle segment exhibit highest price sensitivity, while multinational retailers with private fleets prioritize optimization capability over per-seat licensing costs.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native routing procurement, though strategic stockpiling of operations research talent persists among algorithmic specialists building constraint-handling moats. Software development concentrates in the Netherlands, Germany, and the United States, where logistics density supports specialized vendor ecosystems. The supply chain draws from cloud infrastructure providers, telematics hardware manufacturers, and academic consulting channels for mixed-integer programming expertise. Single-source vulnerability sits with concentrated operations research talent pools in specialized consulting channels. Distribution runs through direct enterprise sales for large fleets and channel partners serving mid-market carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic optimization layers expand faster than hardware-coupled visibility platforms, positioning routing software as a service-attach opportunity where recurring SaaS revenue displaces one-time telematics bundling.
For Market Incumbents: Fortify constraint-handling capabilities in high-complexity verticals like grocery and parcel networks before quantum-inspired solvers erode metaheuristic advantages. Deepen backward integration into trade compliance data streams to mirror Descartes' customs-data convergence model. Prioritize KBA emissions verification module development as regulatory granularity tightens across European jurisdictions. For New Entrants and Emerging Players: Lead with explainable optimization algorithms targeting EU AI Act risk classification requirements, where audit-ready documentation creates first-mover advantage over black-box incumbent systems. Target mid-market freight carriers in the 50-500 vehicle segment across the Randstad and Ruhr logistics corridors, where SaaS deployment models bypass capital-intensive on-premise barriers. Anchor go-to-market through channel partnerships with ERP integration specialists serving CSRD-mandated disclosure workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from telematics-hardware parents whose bundled routing software faces procurement resistance from unbundling trends. Long-term viability centers on algorithmic specialization rather than device integration, favoring vendors with deep operations research talent and vertical-specific constraint libraries. Watch EPA Phase 3 enforcement intensity as inflection indicator for compliance-driven procurement acceleration in heavy-duty trucking segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep telematics-routing unbundling lets large retailers select optimization vendors on algorithmic merit alone. |
| Strategic Partnership | Trade compliance data convergence with customs platforms enables dynamic re-routing around port congestion. |
| Acquisition of Specialist Firm | Operations research talent scarcity makes mixed-integer programming boutiques attractive capability purchases. |
| Geographic Expansion | German KBA enforcement density creates procurement urgency for vendors with embedded emissions verification. |
| Product Launch | Quantum-inspired solvers for same-day delivery windows decompose established metaheuristic competitive advantages. |
Methodological Framework
Operator-level perspectives from fleet operations directors, third-party logistics procurement leads, telematics platform engineers, and EPA SmartWay program administrators anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, EIA freight movement data, KBA emissions compliance reports, and CSRD disclosure frameworks. Bottom-up carrier deployment surveys triangulated against top-down software vendor revenue segmentation.
Sensitivity analysis tested forecast robustness across deployment model migration rates, regulatory enforcement intensity variations, and quantum-inspired solver adoption curves. The analytical framework modeled solution type, deployment model, end-user vertical, and vehicle weight class dimensions across the projection horizon. CAGRs derived from logistic curve fitting to technology adoption patterns, with inputs including e-commerce order fragmentation indices and EPA compliance documentation requirements.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure or cloud infrastructure cost trajectories would require recalibration. Forecasts reflect assumptions about CSRD disclosure mandate adherence and mid-market SaaS migration velocity. Revision becomes warranted when EPA Phase 3 verification thresholds or EU AI Act risk classifications cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Canada Freight and Logistics Market