
 Global Glass Bottles and Containers Market | 2026-2036
Global Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Bottles and Containers Market Intelligence
Market Context
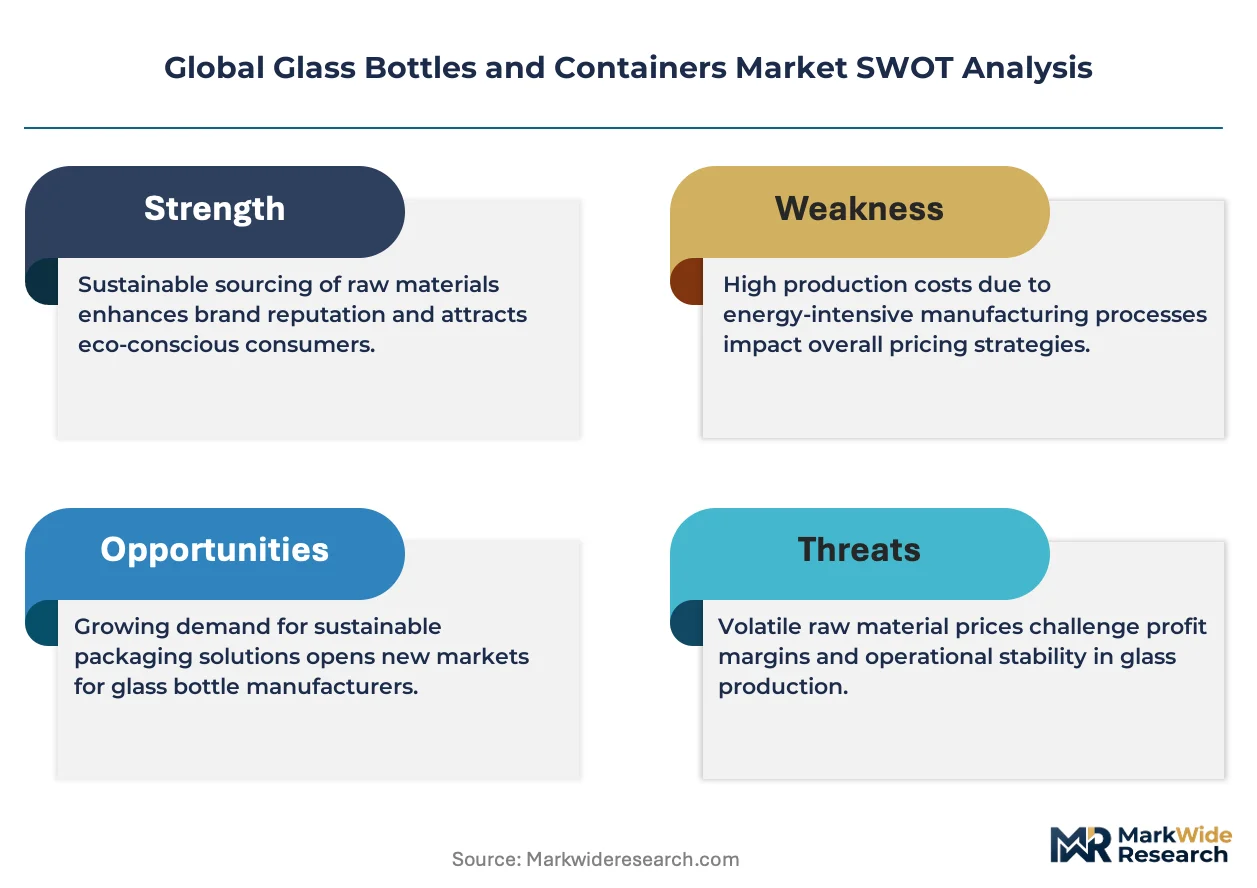
ISO 15378 certification for primary packaging materials is unwinding the competitive landscape, forcing smaller molders to exit pharmaceutical supply chains. Gerresheimer leverages its three-continent furnace network to sustain high-barrier borosilicate output for biologics. O-I Glass anchors North American beverage demand through lightweighting technology that cuts transport costs. Ardagh Group competes across European wine and spirits channels with colored glass specialization.
Technical and Segment Structure
Glass bottles and containers are silica-based rigid packaging formed through blow-and-blow or press-and-blow processes, typically containing 70-75% silicon dioxide with soda ash and limestone fluxes to achieve chemical durability and thermal stability for liquid and semi-solid containment. Soda-lime glass dominates volume across beverage and food jars due to cost-efficient melting profiles, while borosilicate glass captures premium margin pools in pharmaceutical vials where thermal shock resistance meets USP Type I standards. Wine bottles retain structural leadership in value terms, though pharmaceutical vials exhibit the steepest growth trajectory as injectable drug portfolios expand.
Regulatory Frame and Outlook
The EU F-Gas Regulation and REACH compliance protocols reshape furnace emissions standards and raw material traceability across European production bases, while FDA's Container Closure Guidance and USP <660> glass grain testing govern pharmaceutical market access in the United States. India's BIS certification for food-contact glass and China's GB 4806.5 national food safety standards add layered compliance costs for exporters targeting Asia-Pacific contract manufacturing. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and pending state-level bottle deposit expansions across the United States to anticipate capacity allocation and recycling feedstock economics.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing furnace operators to decarbonize melting processes while pharmaceutical buyers consolidate supply chains around ISO 15378-certified molders, compressing viable supplier counts.
Growth Catalysts
- EU F-Gas Regulation:Emissions caps on fluorinated greenhouse gases from glass melting furnaces are accelerating electric furnace retrofits and biofuel adoption across European production bases.
- Injectable biologics expansion:Biopharma pipelines are pulling demand for USP Type I borosilicate vials with superior thermal shock resistance for cold-chain storage.
- Lightweighting technology:Thin-wall forming processes are cutting transport costs and carbon intensity for beverage distributors in Germany and France.
Market Restraints
- Natural gas price volatility:Furnace operators face margin compression from energy input cost swings, particularly in Germany where pipeline supply disruptions persist.
- Specialized mold supply concentration:High-precision pharmaceutical mold fabrication concentrates among German and Italian toolmakers, creating bottleneck risk.
- Plastic substitution in food jars:PET and rPET packaging is capturing shelf-stable food segments where barrier requirements permit material switching.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDMO expansion under PLI schemes is creating demand for imported borosilicate vials as domestic molding capacity lags.
- Deposit-return scheme expansion:Pending state-level bottle bill adoptions across the United States would tighten closed-loop supply chains and secure cullet feedstock.
- Digital printing integration:Direct-to-glass inkjet decoration combined with lightweighting is enabling SKU proliferation without mold changeover costs.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical packaging qualification cycles stretch 18-24 months, locking out uncertified molders from biologics supply chains.
- Furnace reconfiguration capex:Electric melting and oxy-fuel conversions require capital deployment that mid-cap operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Bottles and Containers Market |
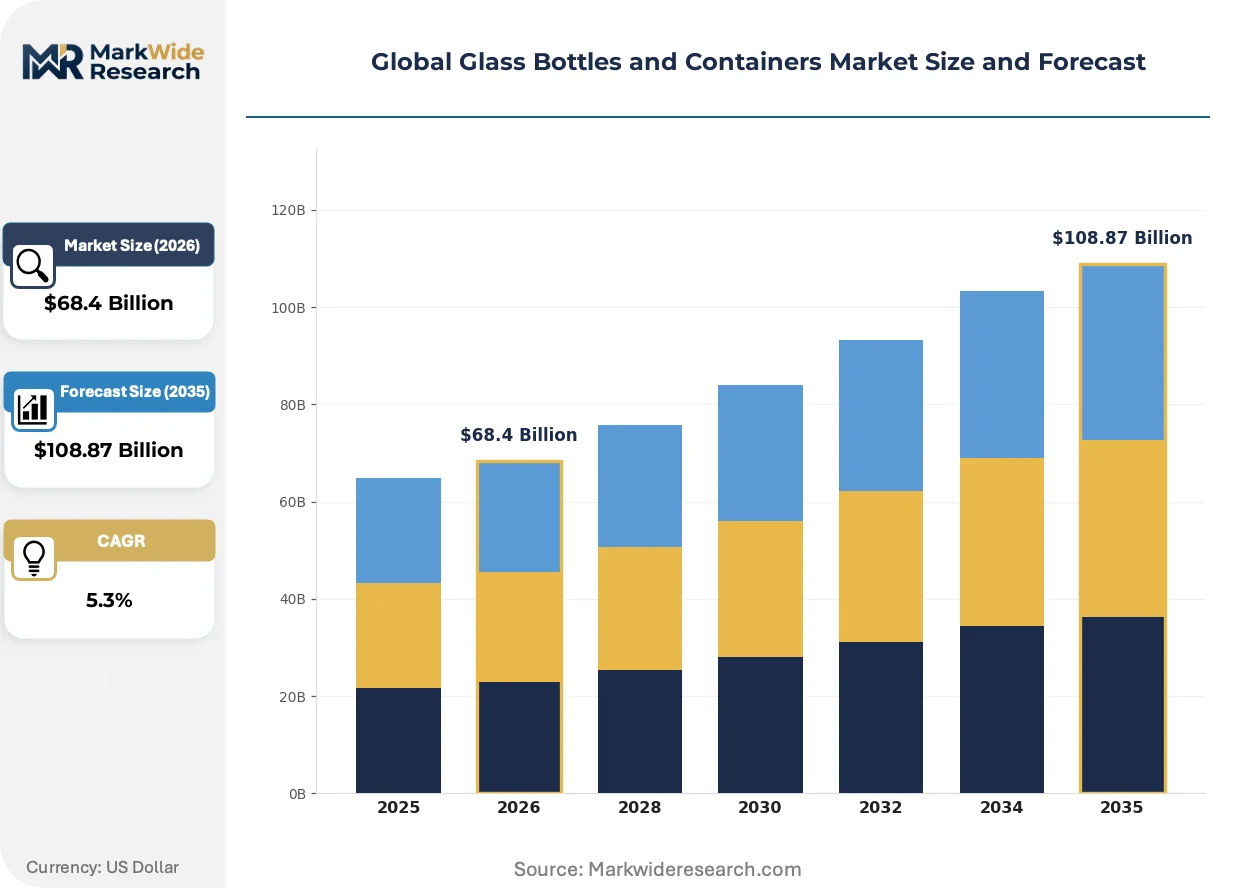
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $108.87 Billion |
| CAGR (2026 – 2036) | 5.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Bottles, Beverage Containers, Pharmaceutical Vials, Cosmetic Jars, Food Jars Material Type: Soda-Lime Glass, Borosilicate Glass, Lead Glass, Flint Glass, Colored Glass End User Industry: Alcoholic Beverage Manufacturers, Pharmaceutical Companies, Personal Care Firms, Food Processing Units, Chemical Producers Packaging Type: Rigid Bottles, Thick-Walled Containers, Thin-Walled Containers, Recycled Glass Containers, Specialty Shapes |
| Companies Covered | Gerresheimer, BA Glass, O-I Glass, Stoelzle Glass Group, Nihon Yamamura Glass, Ardagh Group, Vitro, Vidrala, Verallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Bottles and Containers Market Strategic Shifts & Innovations
Active furnace decarbonization, pharmaceutical barrier specifications, and closed-loop recycling infrastructure are converging to reshape production economics and buyer qualification requirements across glass packaging categories.
Electrified melting with renewable power sourcing is displacing natural gas-fired furnaces in European production bases. Ardagh Group and O-I Glass are piloting all-electric lines in France and Spain to align with EU Green Deal milestones. This shift is compressing carbon intensity metrics in buyer sustainability scorecards and disqualifying legacy fossil-dependent suppliers from premium contract pools.
REACH compliance protocols and extended producer responsibility frameworks are mandating cullet content minimums and full material traceability. ECHA substance restrictions on heavy metal colorants are forcing reformulation of amber and green glass for wine and spirits. German and Italian wine bottlers are responding by qualifying alternative mineral additives that maintain UV protection without chromium or cobalt.
Biopharma procurement teams are consolidating vendor panels around single-source qualification for high-value injectables. Multi-year supply agreements with embedded capacity reservation clauses are replacing spot purchasing for borosilicate vials. This concentration is most visible in Germany's pharmaceutical glass corridor, where Gerresheimer and Schott are capturing locked-in volume commitments from mRNA drug developers.
Global Glass Bottles and Containers Market Segmentation
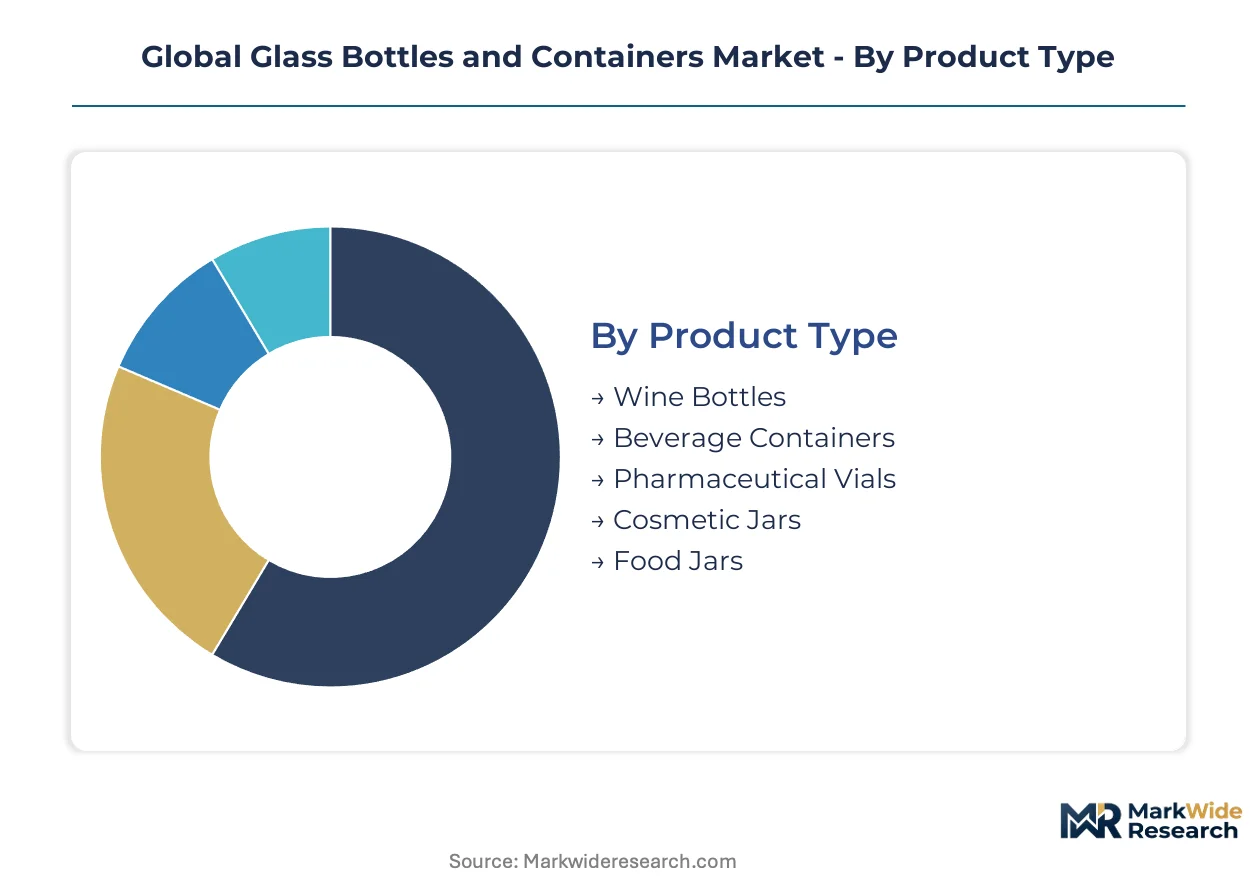
Glass packaging segmentation reflects divergent technical specifications and regulatory compliance burdens across end-use applications. Product and material categories map directly to furnace technology investments and buyer qualification requirements that determine supplier viability.
Product Type:
REACH substance restrictions and FDA Container Closure Guidance create divergent compliance pathways that segment supplier capabilities across pharmaceutical versus beverage applications.
- Pharmaceutical Vials:Borosilicate construction meeting USP Type I standards delivers thermal shock resistance for cold-chain biologics storage. Injectable drug pipelines in Germany and India are consolidating procurement around ISO 15378-certified molders with multi-year capacity reservations.
- Wine Bottles:Amber and green coloration historically relied on chromium and cobalt additives now restricted under ECHA protocols. Italian and French bottlers are qualifying alternative mineral UV barriers to maintain product protection while meeting extended producer responsibility mandates.
- Beverage Containers:Lightweighting technology reduces transport carbon intensity for carbonated and still drinks distributors.
- Cosmetic Jars:Flint and colored variants serve premium skincare and fragrance houses with decoration-ready surfaces.
- Food Jars:Soda-lime dominance faces PET substitution pressure in shelf-stable segments where barrier requirements permit material switching.
Established volume favors Wine Bottles; emerging adoption favors Pharmaceutical Vials.
Material Type:
Cost tier stratification separates commodity melting from premium barrier specifications that command qualification-locked supply agreements.
- Soda-Lime Glass:Silica-soda ash-limestone composition dominates volume production for beverage and food applications due to lower melting energy requirements. Furnace operators in Spain and France are retrofitting natural gas lines to electric or biofuel to align with EU F-Gas Regulation emissions caps.
- Borosilicate Glass:Enhanced thermal stability from boron oxide addition meets pharmaceutical USP standards for injectable containment. German molders Gerresheimer and Schott anchor specialized production corridors serving mRNA drug developers with locked-in volume commitments.
- Flint Glass:Iron-free clarity supports premium cosmetic and spirits presentation where visual purity drives shelf appeal.
- Colored Glass:Reformulated mineral additives replace restricted heavy metals in wine and spirits UV protection applications.
- Lead Glass:Specialized crystal applications persist in luxury tableware with declining packaging relevance due to health restrictions.
Commodity melting favors Soda-Lime Glass; margin expansion favors Borosilicate Glass.
End User Industry:
Customer concentration patterns determine contract structure, with pharmaceutical procurement consolidating around single-source qualification while beverage purchasing fragments across regional distributors.
- Pharmaceutical Companies:Biopharma procurement teams enforce ISO 15378 certification and USP <660> glass grain testing as non-negotiable entry criteria. Qualification cycles stretching 18-24 months lock out uncertified molders from high-value injectables supply chains.
- Alcoholic Beverage Manufacturers:European wine and spirits producers are expanding premium glass orders under EU Green Deal circular economy mandates, with lightweighting requirements reshaping supplier scorecards.
- Personal Care Firms:Premium skincare and fragrance houses demand decoration-ready flint surfaces with direct-to-glass digital printing compatibility.
- Food Processing Units:Shelf-stable segments show accelerating PET and rPET substitution where oxygen barrier requirements permit material switching.
- Chemical Producers:Industrial containment applications require chemical durability specifications distinct from food-contact compliance.
Contract concentration favors Pharmaceutical Companies; volume fragmentation favors Alcoholic Beverage Manufacturers.
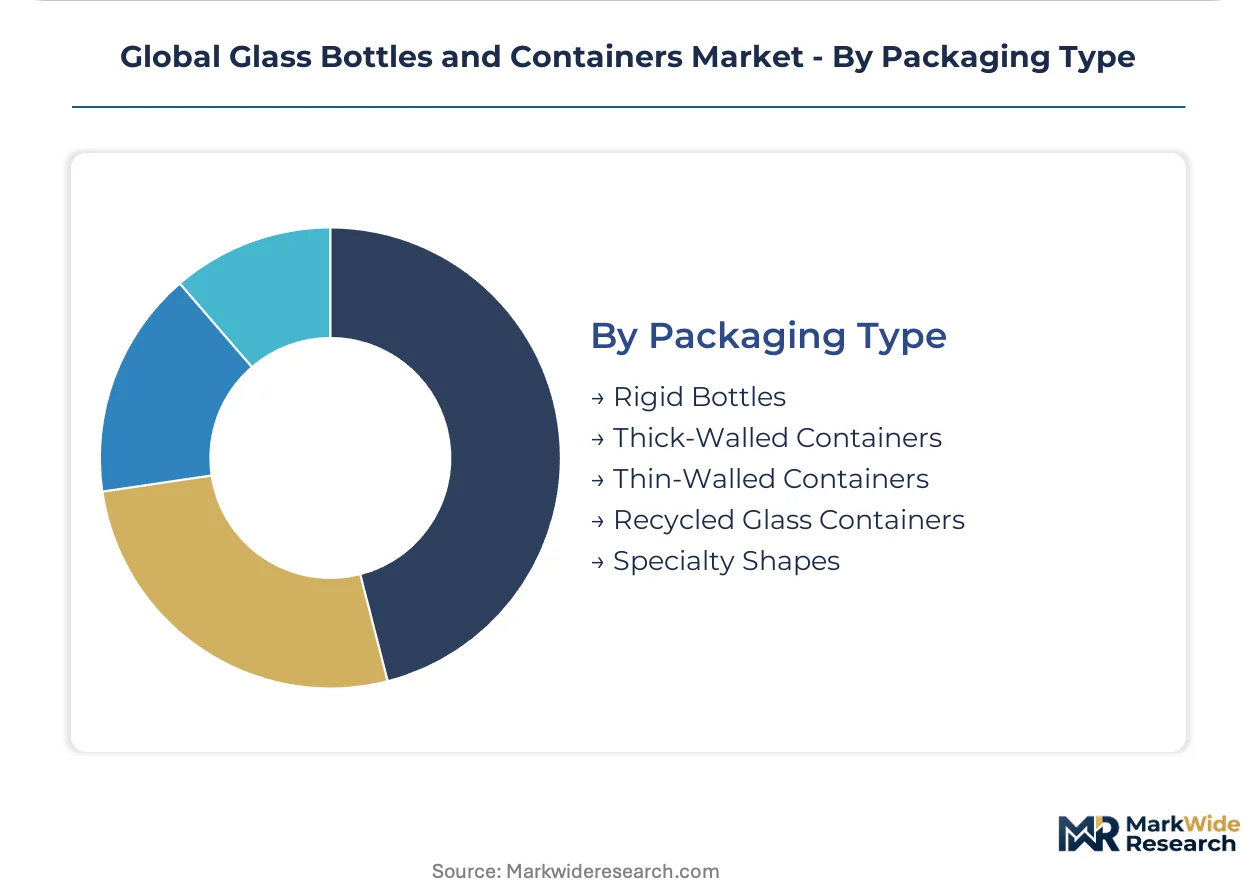
Packaging Type:
Wall thickness and forming process selection directly determine transport economics and cullet recovery rates under evolving extended producer responsibility frameworks.
- Thin-Walled Containers:Reduced glass mass cuts freight costs and carbon intensity per unit for beverage distributors in Germany and France. O-I Glass and Ardagh Group pilot lines demonstrate electric furnace compatibility with lightweight forming.
- Recycled Glass Containers:Cullet content minimums under EU extended producer responsibility mandates are tightening closed-loop supply chain requirements. Pending state-level bottle deposit expansions across the United States would secure feedstock economics for high-recycled-content production.
- Rigid Bottles:Standard blow-and-blow or press-and-blow forming dominates carbonated beverage and spirits applications.
- Thick-Walled Containers:Enhanced structural integrity serves pharmaceutical and chemical containment with thermal mass for temperature stability.
- Specialty Shapes:Custom mold requirements concentrate fabrication demand among German and Italian precision toolmakers, creating supply bottleneck risk.
Cost efficiency favors Thin-Walled Containers; regulatory alignment favors Recycled Glass Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation emissions caps and India's PLI pharmaceutical incentives are redrawing production footprints across glass packaging corridors. National furnace decarbonization timelines and biologics cold-chain expansion now dictate where capacity investments flow.
Germany
Injectable biologics pipelines from BioNTech and CureVac pull demand for USP Type I borosilicate vials. The EU Green Deal mandates electric furnace retrofits by 2030. Gerresheimer and Schott anchor specialized production in the Mainz-Düsseldorf pharmaceutical glass corridor.
United States
Pending state-level bottle deposit expansions in New York and California would secure cullet feedstock for closed-loop recycling. FDA Container Closure Guidance governs pharmaceutical market access. O-I Glass pilots lightweighting technology at Ohio and Pennsylvania beverage facilities.
China
GB 4806.5 food safety standards add compliance costs for exporters targeting domestic contract manufacturing. NMPA pharmaceutical packaging rules tighten barrier specifications. Shandong Peninsula furnace operators face MIIT dual carbon goals pressuring natural gas-to-electric conversions.
India
CDMO expansion under PLI schemes creates demand for imported borosilicate vials as domestic molding capacity lags. BIS certification for food-contact glass layers regulatory burden. Maharashtra and Gujarat pharmaceutical clusters rely on German and Italian mold imports.
France
ECHA substance restrictions on chromium and cobalt force reformulation of amber wine glass. Extended producer responsibility mandates cullet content minimums. Ardagh Group and Verallia pilot all-electric lines in Champagne and Bordeaux bottling regions.
Global Glass Bottles and Containers Market Key Industry Players
Player mix skews toward multinational furnace operators with three-continent networks and mid-cap specialists concentrated in German-Italian precision corridors. The structure splits between consolidated beverage packaging at scale and fragmented pharmaceutical molding requiring ISO 15378 certification. Strategic archetypes include: vertically integrated giants with captive cullet supply, certified pharmaceutical specialists with locked-in biologics contracts, and regional beverage players competing on lightweighting speed. Dominant competitive moves are electric furnace retrofit partnerships with renewable power providers and multi-year capacity reservation clauses with mRNA drug developers.
Among German-anchored specialists, Gerresheimer and Schott exemplify the certification-locked pharmaceutical tier with concentrated borosilicate production for injectable containment. O-I Glass represents the scale-driven beverage archetype with North American lightweighting deployment. These three occupy positions that illustrate how furnace technology investment and regulatory qualification timelines now stratify viable competitors from excluded molders.
| Leading Market Players |
|---|
| Gerresheimer |
| BA Glass |
| O-I Glass |
| Stoelzle Glass Group |
| Nihon Yamamura Glass |
| Ardagh Group |
| Vitro |
| Vidrala |
| Verallia |
| Others |
Cost & Logistics Intelligence
Furnace scale economies in Germany and China anchor global glass packaging cost structures, concentrating high-volume soda-lime production among operators running above 80% utilization while compressing price floors for mid-cap competitors lacking thermal efficiency upgrades.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade borosilicate vials and commodity beverage containers. ISO 15378-certified molders command three-tier pricing structure across premium, standard, and economy levels, with thermal shock resistance specifications and USP Type I compliance driving premium tier separation. Cost compression in commodity soda-lime segments intensifies because natural gas price volatility erodes furnace margins. Alcoholic beverage manufacturers exhibit highest price sensitivity, while biopharma procurement teams prioritize barrier performance over unit economics.
Supply Chain Analysis
Germany and Italy anchor precision mold fabrication for pharmaceutical applications, while China and Spain concentrate high-volume soda-lime furnace operations. Raw material sourcing draws from silica sand deposits in Belgium and Ukraine, soda ash from Wyoming and Kenya, and boron minerals from Turkey. Single-source vulnerability concentrates in German-Italian toolmakers supplying high-precision pharmaceutical molds. Distribution runs through regional cullet collection networks feeding closed-loop furnace operations under EU extended producer responsibility mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass packaging incumbents face sustained substitution pressure from PET and rPET in shelf-stable food segments, requiring defensive positioning around barrier performance and circular economy credentials that plastics cannot replicate.
For Market Incumbents: Consolidate furnace networks through electric retrofit partnerships with renewable power providers in France and Spain, locking in EU Green Deal compliance ahead of 2030 emissions deadlines. Deepen backward integration into captive cullet supply by acquiring regional recycling operators in Germany and the United States. Certification investment in ISO 15378 pharmaceutical standards defends margin pools against plastic substitution in food jars.
For New Entrants and Emerging Players: ISO 15378 fast-track qualification for borosilicate vial production opens white-space in India's pharmaceutical contract manufacturing corridor, where domestic molding capacity lags CDMO expansion under PLI schemes. Target thin-walled beverage container segments in France and Germany where lightweighting technology creates new supplier qualification windows. Direct-to-glass digital printing compatibility offers a differentiated go-to-market angle for premium cosmetic and spirits decoration contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ISO 15378-certified pharmaceutical specialists with multi-year capacity reservation clauses from mRNA drug developers. Long-term viability over the next decade hinges on electric furnace conversion completion and locked-in biologics supply agreements. Acquisition targets should display captive cullet networks and pharmaceutical certification pipelines. The signal to watch is state-level bottle deposit expansion across the United States securing feedstock economics for high-recycled-content production.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit | EU F-Gas Regulation compliance secures premium contract pools from fossil-dependent competitors. |
| ISO 15378 Certification Investment | Pharmaceutical qualification locks out uncertified molders from biologics supply chains. |
| Backward Integration into Cullet Supply | Captive recycling networks tighten closed-loop economics under extended producer responsibility. |
| Lightweighting Technology Deployment | Thin-wall forming cuts transport carbon intensity for beverage distributors in Germany and France. |
| Digital Printing Integration | Direct-to-glass decoration enables SKU proliferation without mold changeover costs for spirits brands. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings and trade data, combining interviews with furnace operations managers, pharmaceutical procurement directors, beverage supply chain planners, and mold fabrication specialists with validation against ECHA substance restriction databases, FDA Container Closure Guidance documents, EU F-Gas Regulation compliance records, and customs import statistics. Bottom-up capacity modeling triangulates against top-down demand aggregation across end-use segments.
Segmentation dimensions modeled include material type, product specification tier, end-use industry concentration, and regional regulatory cluster across the projection horizon. CAGRs derive from installed furnace capacity trajectories, biologics pipeline expansion rates, and electric conversion deployment schedules. Industry-specific forecast inputs incorporate EU Green Deal milestone timelines and pharmaceutical CDMO contract award patterns.
Underlying assumptions cover sustained natural gas price volatility, electric furnace technology maturation, and biologics cold-chain expansion, with deviation risk concentrated in regulatory acceleration or delay on emissions caps and deposit-return scheme adoption. Recalibration cycles align with material shifts in furnace fuel economics and pharmaceutical procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
India Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Vietnam Container Glass Market