
 UAE Cold Chain Logistics Market | 2026-2036
UAE Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Cold Chain Logistics Market Analytics
The capital-intensity divergence between asset-heavy refrigerated warehouse operators and last-mile delivery specialists is redrawing competitive boundaries in UAE cold chain logistics. CEVA Logistics leverages its integrated port-to-warehouse infrastructure across Jebel Ali and Khalifa Port to sustain volume leadership in import consolidation. RSA Cold Chain anchors its position through specialized pharmaceutical handling capabilities that meet Gulf health authority certification standards.
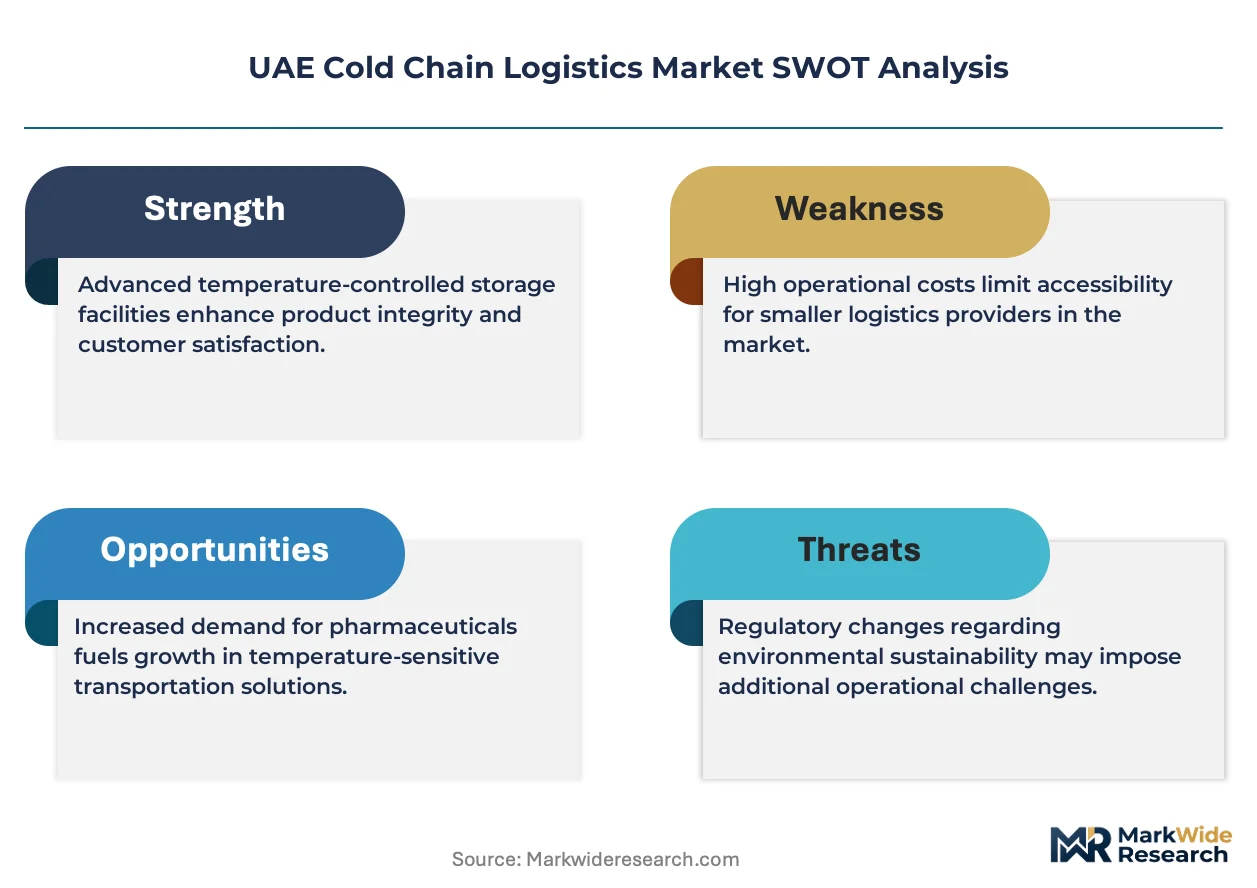
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure—maintaining ranges from deep-frozen minus 25 degrees Celsius to controlled ambient 15-25 degrees Celsius through insulated transport, vapor-compression refrigeration, and real-time telemetry—to preserve product integrity for temperature-sensitive goods. The primary commercial purpose centers on eliminating spoilage, maintaining pharmacological efficacy, and enabling compliant cross-border trade of perishables and regulated biomedical products. Warehousing commands the dominant margin pool due to high barriers in land acquisition and energy-intensive cooling systems, while IoT Solutions represent the fastest-expanding technology segment as shippers mandate sensor-based chain-of-custody documentation. Pharmaceuticals drive premium pricing within product categories, reflecting stringent MOHAP validation requirements and insurance-backed liability structures.
MOHAP enforces temperature excursion reporting and Good Distribution Practice compliance for all medical product movements through UAE ports, directly elevating demand for validated cold storage and audit-ready monitoring systems. The country's central bank and customs authority coordinate on trade finance documentation that ties refrigerated cargo release to real-time temperature log verification. Stakeholders must weigh capital deployment between expanding bonded cold storage capacity in free zones versus investing in predictive analytics platforms that preempt equipment failures before product compromise occurs.
Market Dynamics
MOHAP's mandatory temperature-tracking protocols are compressing compliance timelines across pharmaceutical distribution networks, forcing logistics providers to reconfigure warehouse infrastructure and telemetry systems ahead of enforcement deadlines.
Growth Catalysts
- Biologics import surge:Specialty drug importers are expanding refrigerated capacity to handle temperature-sensitive monoclonal antibodies and cell therapies entering UAE hospital systems.
- Jebel Ali bonded zone expansion:Free zone incentives for cold storage construction are attracting re-export operators serving Saudi Arabia and Egypt pharmaceutical markets.
- MOHAP Good Distribution Practice mandates:Regulatory validation requirements for medical shipments are elevating demand for certified cold chain infrastructure.
Market Restraints
- Energy cost volatility:Diesel-powered reefer transport and warehouse cooling systems face input cost pressure from fluctuating fuel prices.
- Land scarcity in Dubai corridor:Cold storage construction concentrates in Jebel Ali where industrial zoned land availability limits greenfield expansion.
- Refrigerant regulatory friction:UAE alignment with Montreal Protocol phase-down schedules constrains vapor-compression equipment choices.
Strategic Opportunities
- Ras Al Khaimah underpenetration:Northern emirate logistics zones offer lower land costs for pharmaceutical distribution hubs targeting GCC re-export.
- IoT-Blockchain convergence:Immutable temperature logging combined with real-time sensor telemetry creates audit-ready chain-of-custody documentation.
- Direct-to-pharmacy channel innovation:Bypassing traditional wholesale layers through validated last-mile delivery contracts with hospital procurement departments.
Industry Challenges
- Certified technician scarcity:Gulf health authority validation protocols require specialized training that outpaces local refrigeration engineering program output.
- Capex intensity for redundancy:Dual-string cooling systems and backup generator capacity demand capital deployment that strains mid-scale operator balance sheets.
- Legacy WMS integration friction:Warehouse management systems at established UAE cold storage facilities resist seamless API connection with new telemetry platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Cold Chain Logistics Market |
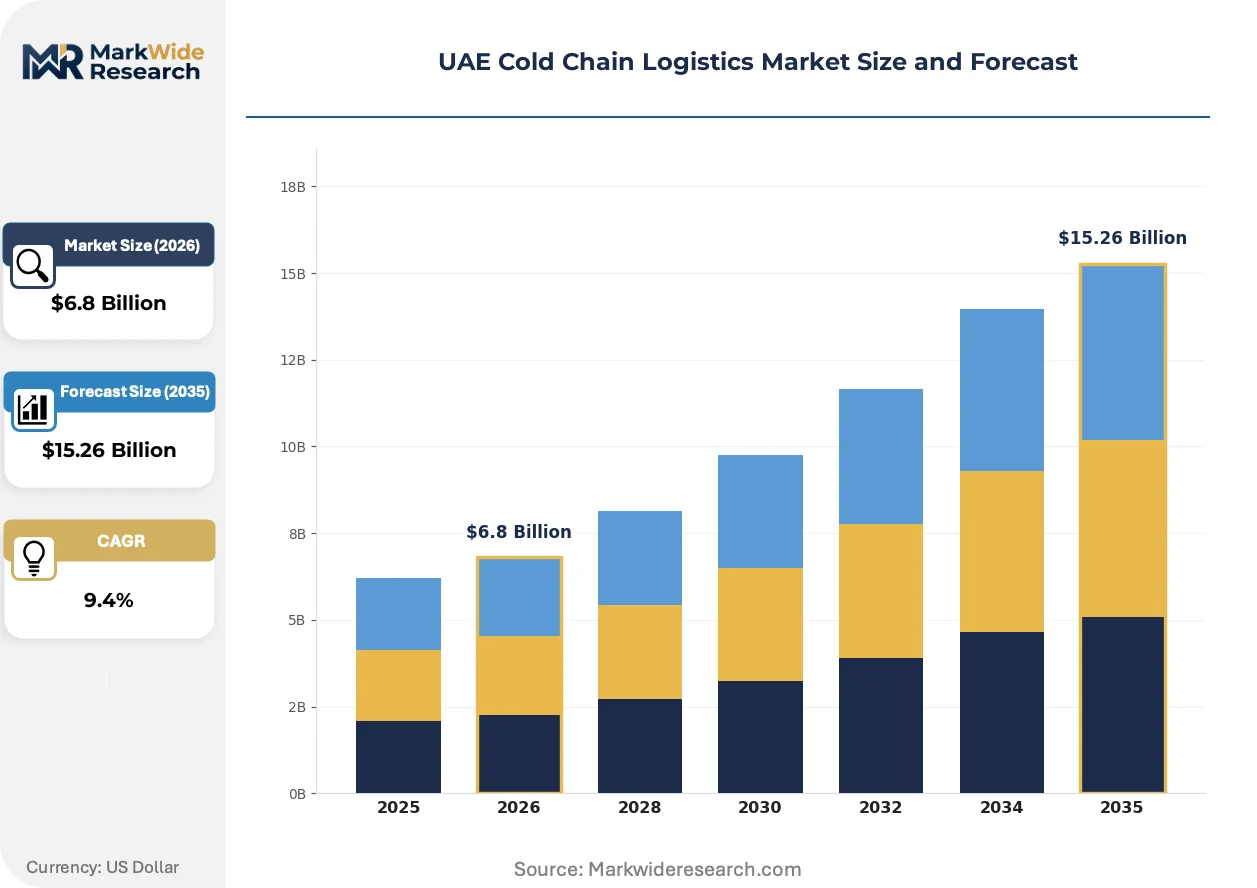
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Packaging Product Type: Pharmaceuticals, Perishables, Chemicals, Beverages Technology: Refrigerated Trucks, Temperature-Controlled Containers, IoT Solutions, Monitoring Software End User: Healthcare Providers, Retail Chains, Food Manufacturers, Logistics Companies |
| Companies Covered | CEVA Logistics, RSA Cold Chain, Agility Logistics, Global Shipping & Logistics LLC, GAC Dubai, Al-Futtaim Logistics, Mohebi Logistics, DB Schenker, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Cold Chain Logistics Market Evolving Landscape
Sensor technology and regulatory digitization are compressing documentation cycles while reconfiguring how pharmaceutical buyers evaluate logistics partners.
Bluetooth Low Energy temperature loggers with embedded NFC chips are replacing USB data loggers in pharmaceutical shipments. Specialty drug importers are mandating these devices for all controlled ambient and refrigerated lanes. The technology is miniaturizing sensor form factors to pill-size dimensions that fit inside individual vaccine vial cartons.
MOHAP's electronic temperature excursion reporting requirements are eliminating paper-based batch records for medical product movements. Logistics providers must now submit real-time data streams to customs release systems before cargo clearance. Pharmaceutical distribution networks in Dubai's free zones are retrofitting warehouse management systems to automate this compliance workflow.
Hospital procurement departments are unbundling cold chain service contracts from traditional freight forwarding agreements. Buyers now separately negotiate storage, transport, and last-mile delivery with specialized operators. This pattern concentrates contract awards in Abu Dhabi and Dubai where validated cold storage density supports multi-provider sourcing strategies.
UAE Cold Chain Logistics Market Segmentation
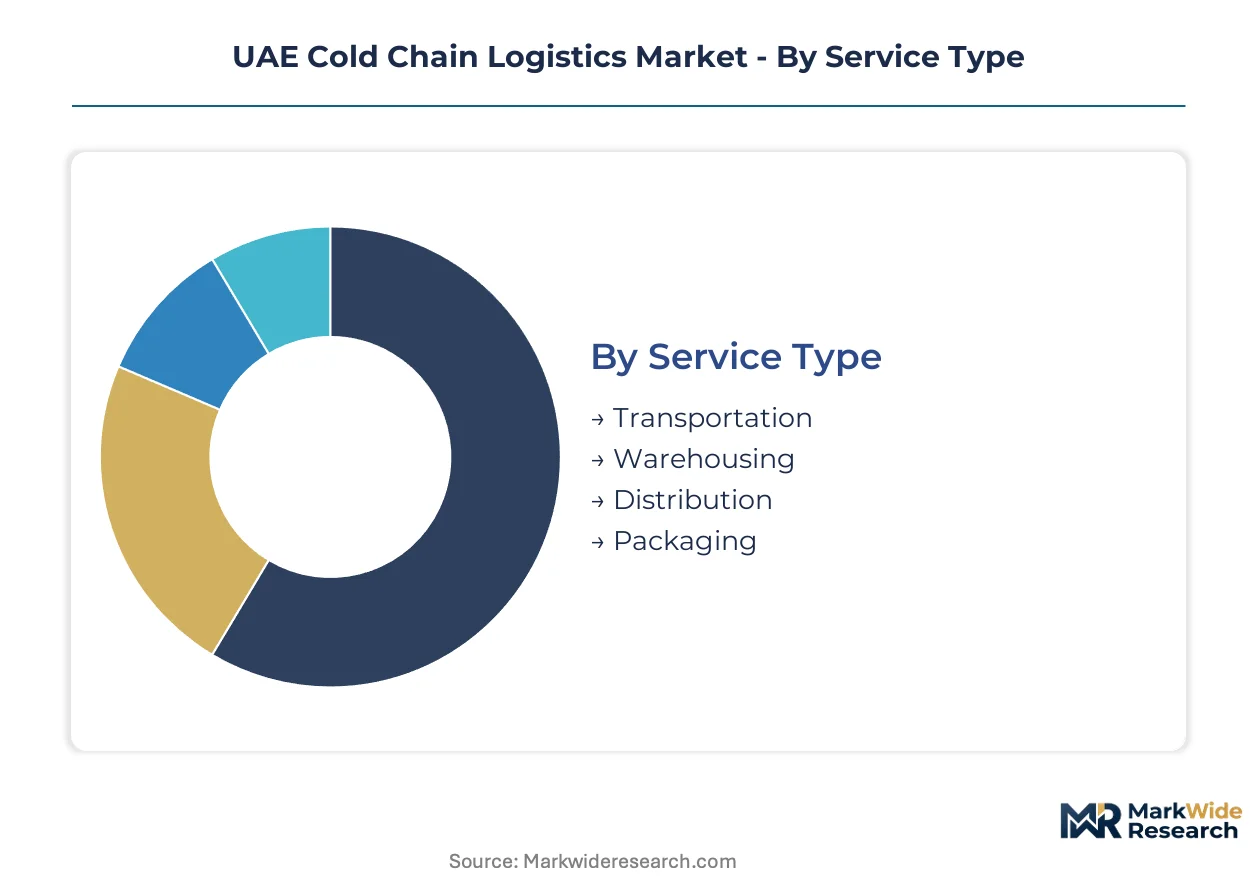
Cold chain logistics in the UAE fragments across service modalities and product categories that demand distinct temperature protocols and regulatory compliance frameworks. Understanding segment interplay reveals where capital deployment concentrates and which technology investments yield compliance advantage.
Service Type:
Transportation and warehousing channels serve fundamentally different customer risk profiles and contract structures across Dubai's Jebel Ali corridor and Abu Dhabi's Khalifa Port zone.
- Transportation:Reefer trucks and specialized vehicle fleets handle lane-specific temperature bands from deep-frozen to controlled ambient. Pharmaceutical distributors in Dubai's free zones are mandating redundant cooling systems and real-time GPS-telemetry for all medical product movements.
- Warehousing:Bonded cold storage facilities command premium lease rates due to MOHAP validation requirements and limited industrial zoned land availability. These assets anchor re-export flows to Saudi Arabia and Egypt pharmaceutical markets.
- Distribution:Consolidation and cross-dock operations bridge port receipt and final delivery, with specialty drug importers demanding validated handling protocols at every transfer point.
- Packaging:Insulated shippers and phase-change materials protect temperature integrity during last-mile delivery to hospital systems and retail pharmacy chains.
By volume, transportation leads. By growth pace, warehousing is ahead.
Product Type:
Margin concentration and regulatory intensity vary sharply across product categories, with pharmaceutical handling commanding certification premiums unavailable to commodity perishables.
- Pharmaceuticals:Biologics, vaccines, and monoclonal antibodies require continuous temperature documentation from manufacturer to patient administration. MOHAP's Good Distribution Practice mandates have elevated demand for validated infrastructure that general perishables handling cannot satisfy.
- Perishables:Fresh produce, dairy, and meat products move through high-velocity import channels serving UAE retail chains. These flows concentrate in Jebel Ali's bonded zones before redistribution to GCC markets.
- Chemicals:Temperature-sensitive industrial compounds and laboratory reagents occupy a specialized niche with distinct hazard classification and storage segregation requirements.
- Beverages:Chilled drinks and temperature-controlled alcohol imports flow through dedicated customs clearance channels with specific duty structures.
Pharmaceuticals capture the highest margin per pallet position. Perishables dominate total throughput tonnage.
Technology:
Equipment choices increasingly determine contract eligibility as shippers mandate sensor-based chain-of-custody documentation for regulatory submission.
- Refrigerated Trucks:Diesel-powered reefer units face energy cost volatility while electric alternatives gain traction for last-mile compliance in Dubai's urban zones. Fleet operators are retrofitting telematics to meet MOHAP electronic excursion reporting requirements.
- Temperature-Controlled Containers:Active and passive container systems protect high-value pharmaceutical shipments during long-haul ocean and air freight legs into UAE ports.
- IoT Solutions:Bluetooth Low Energy loggers with embedded NFC chips are displacing USB data loggers. These miniaturized sensors now fit inside individual vaccine vial cartons for shipment-level tracking.
- Monitoring Software:Cloud-based platforms aggregate sensor streams for automated compliance reporting and predictive equipment maintenance scheduling.
IoT Solutions are expanding most quickly as shippers mandate real-time visibility. Refrigerated trucks retain the largest installed base.
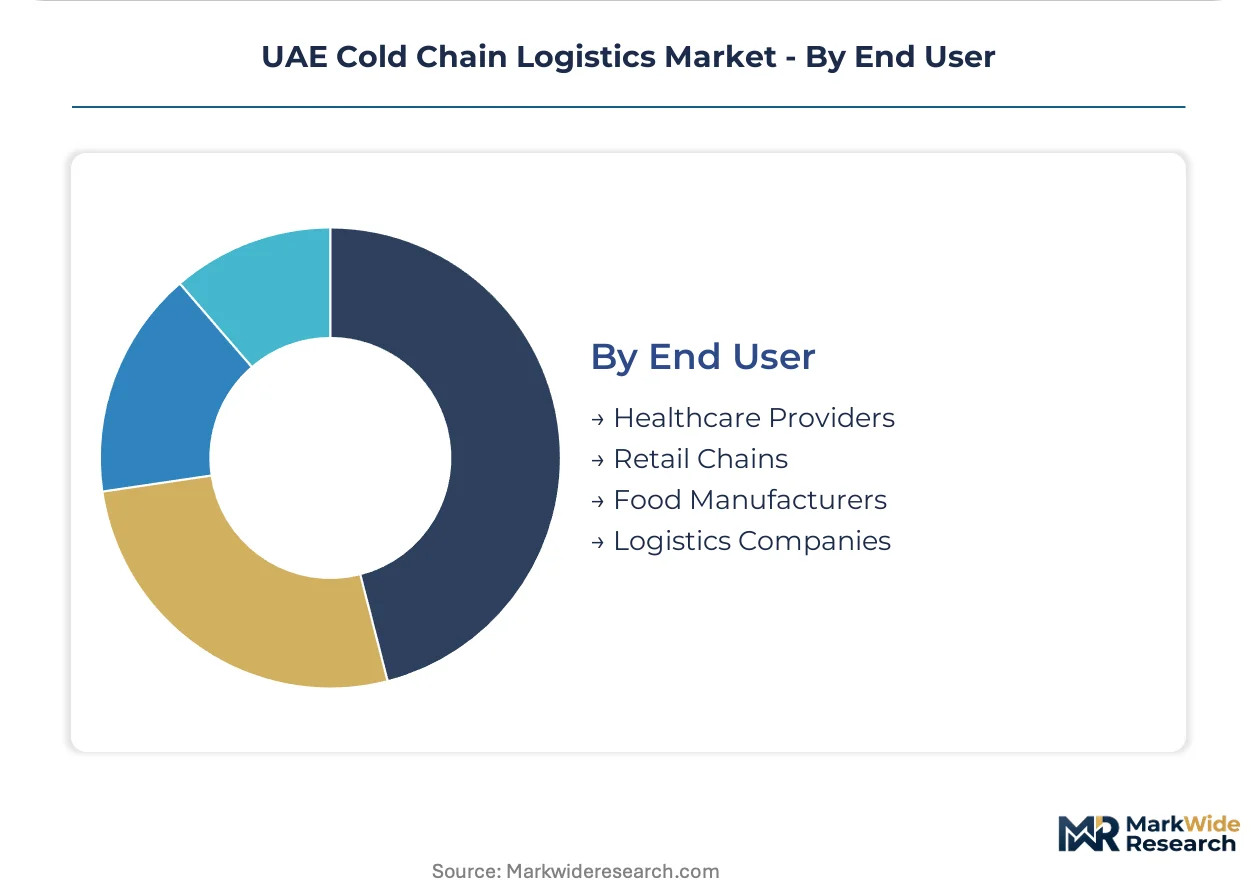
End User:
Procurement sophistication and validation requirements differ markedly between regulated healthcare institutions and commercial retail operations.
- Healthcare Providers:Hospital systems and specialty clinics demand audit-ready temperature documentation for every pharmaceutical receipt. These buyers are unbundling cold chain contracts from traditional freight forwarding agreements.
- Retail Chains:Supermarket and pharmacy operators prioritize cost-efficient consolidation and rapid inventory turns over specialized handling certification.
- Food Manufacturers:Processing facilities and dairy operations require inbound ingredient cold chain integrity and outbound finished goods distribution at scale.
- Logistics Companies:Third-party providers serve as intermediaries, investing in multi-customer infrastructure to capture pharmaceutical and perishables volumes simultaneously.
Healthcare Providers drive premium pricing through compliance requirements. Retail Chains represent the broadest addressable volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Dubai demonstrate the lowest price elasticity for validated pharmaceutical handling, while retail grocery chains operating across the Northern Emirates exhibit acute sensitivity to per-unit storage costs. This demand-elasticity divergence shapes capital deployment patterns across the federation's logistics zones.
Dubai
Jebel Ali's bonded cold storage corridor anchors pharmaceutical re-export flows to Saudi Arabia and Egypt, with specialty drug importers expanding refrigerated capacity for monoclonal antibodies. MOHAP's Good Distribution Practice mandates compress compliance timelines for warehouse operators retrofitting telemetry systems. Dubai South's logistics district is attracting temperature-controlled e-commerce fulfillment investment from regional grocery platforms.
Abu Dhabi
Khalifa Port's integrated port-to-warehouse infrastructure supports CEVA Logistics' volume leadership in import consolidation for hospital systems. The emirate's health authority coordinates with MOHAP on aligned temperature excursion reporting standards. Masdar City's sustainable logistics zone is piloting solar-powered cold storage to reduce diesel generator dependency for backup cooling systems.
Sharjah
Hamriyah Free Zone offers lower land acquisition costs for mid-scale pharmaceutical distributors serving northern GCC markets. The emirate's customs authority is digitizing trade finance documentation to match Dubai's real-time temperature log verification requirements. Sharjah International Airport's cargo terminal is expanding perishables handling capacity for Indian subcontinent re-export flows.
Ras Al Khaimah
Saqr Port's underpenetrated logistics zones present greenfield opportunities for pharmaceutical distribution hubs targeting price-sensitive GCC markets. The emirate's industrial authority is offering extended lease terms to offset capital intensity for dual-string cooling system deployment. Al Hamra Industrial Zone is attracting dairy processors seeking lower energy costs for blast freezing operations.
Fujairah
The emirate's East Coast location enables direct Indian Ocean shipping lanes that bypass Strait of Hormuz congestion for perishables imports. Fujairah Port's hydrocarbon logistics heritage is transferring engineering capabilities to cryogenic handling for industrial gases. Khor Fakkan's container terminal is developing transhipment cold storage for reefer cargo redistribution to Oman and Pakistan.
UAE Cold Chain Logistics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE cold chain logistics market. Integrated global forwarders with port-adjacent warehouse networks command premium contract structures through validated infrastructure density, while regional specialists compete on asset-light flexibility and localized regulatory relationships. Three archetypes dominate: multinational integrated logistics providers with captive free zone real estate, Gulf-based pharmaceutical handling specialists with health authority certifications, and diversified industrial conglomerates leveraging captive demand from affiliated retail and healthcare operations. Competitive dynamics center on M&A activity targeting specialized temperature-controlled capabilities and strategic partnerships with IoT platform vendors for automated compliance documentation.
Among multinational integrated providers, CEVA Logistics and DB Schenker exemplify the port-centric archetype with bonded warehouse networks across Jebel Ali and Khalifa Port zones. RSA Cold Chain occupies a position within the pharmaceutical specialization tier, with MOHAP-validated infrastructure that commands certification premiums unavailable to general perishables handlers. Kuehne + Nagel represents the technology-forward archetype, with sensor-based chain-of-custody platforms that automate electronic temperature excursion reporting for hospital procurement departments. These three anchors illustrate how competitive positioning stratifies across asset intensity, regulatory certification depth, and digital integration sophistication.
| Leading Market Players |
|---|
| CEVA Logistics |
| RSA Cold Chain |
| Agility Logistics |
| Global Shipping & Logistics LLC |
| GAC Dubai |
| Al-Futtaim Logistics |
| Mohebi Logistics |
| DB Schenker |
| Kuehne + Nagel |
| Others |
Value Network & Pricing Analysis
Capacity reservation contracts with hospital procurement departments lock in multi-year refrigerated storage commitments while insulating logistics providers from spot-rate volatility in Dubai's Jebel Ali corridor. These structures bind premium pricing to MOHAP-validated infrastructure access, creating visibility for both operators and buyers across the pharmaceutical distribution network.
Pricing Analysis
Service contract extensions and telemetry platform subscriptions drive lifetime value beyond base warehousing fees. Pricing stratifies across MOHAP-certified premium tiers, standard bonded storage, and economy perishables handling, with certification grade and geographic proximity to Jebel Ali as primary differentiators. Cost compression in standard-tier warehousing intensifies as new free zone entrants compete on lease rates. Retail grocery chains exhibit acute price sensitivity, while hospital systems accept premium positioning for validated cold chain documentation.
Supply Chain Analysis
Inventory buffers for temperature-sensitive biologics stretch lead times from European and North American pharmaceutical manufacturers through UAE ports. Supply concentration centers on Germany, Switzerland, and the United States for specialty drug imports, with active container systems and vapor-compression equipment as critical component dependencies. Single-source vulnerability runs through Jebel Ali's bonded zone dominance for GCC re-export. Distribution runs through port-adjacent consolidation hubs before last-mile pharmacy and hospital delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE cold chain logistics market functions as a defensive-moat sector where MOHAP regulatory entrenchment creates high switching costs for hospital procurement departments. Certification barriers and validated infrastructure requirements protect incumbent positions against asset-light competitors.
For Market Incumbents: Shield market position by deepening backward integration into IoT-telemetry platform development, preempting disintermediation by technology vendors. Expand redundant cooling capacity in Abu Dhabi's Khalifa Port zone before land scarcity intensifies. Prioritize API integration with hospital procurement systems to embed switching costs.
For New Entrants and Emerging Players: Last-mile direct-to-pharmacy delivery gaps in Ras Al Khaimah and Fujairah present white-space opportunities where incumbents under-serve price-sensitive GCC markets. Target dairy processors and regional grocery platforms seeking lower-cost blast freezing alternatives to Dubai corridor rates. Enter through sustainable cold storage pilots leveraging solar backup systems as differentiation.
For Investors and Strategic Acquirers: Pharmaceutical-specialized regional operators with Gulf health authority certifications represent the most defensible acquisition archetype for portfolio exposure. Monitor MOHAP enforcement timelines and electronic excursion reporting adoption rates as inflection signals for compliance-driven consolidation. Long-term viability hinges on regulatory digitization rather than commodity storage economics.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Certification Investment | Validates infrastructure for biologics handling, unlocking hospital system contracts with premium pricing. |
| IoT-Platform Integration | Automates electronic temperature excursion reporting, reducing compliance labor and contract friction. |
| Free Zone Capacity Expansion | Captures re-export flows to Saudi Arabia and Egypt pharmaceutical markets through bonded storage advantages. |
| Backward Integration into Telemetry | Controls sensor data architecture, protecting margin from third-party platform vendor disintermediation. |
| Sustainable Cooling Pilot | Reduces diesel generator dependency, aligning with Masdar City sustainability mandates and lowering energy cost exposure. |
Research Methodology
The analysis maps transportation, warehousing, distribution, and packaging service modalities, each validated through cold chain operations directors, hospital procurement managers, pharmaceutical regulatory affairs leads, and free zone development authorities. Primary fieldwork combined structured interviews with secondary triangulation against MOHAP regulatory filings, UAE customs trade data, GCC pharmaceutical import statistics, and operator facility certification records. Bottom-up service volume estimates and top-down market sizing were reconciled across data streams.
Consistency checks validated volume and value outputs against bonded cold storage capacity disclosures, reefer truck fleet registrations, and pharmaceutical import value trends across the projection horizon. Segmentation modeling incorporated service type, product category, technology tier, and end-user sophistication dimensions. CAGRs were derived from fitted growth curves applied to validated baseline estimates, with biologics import velocity and MOHAP compliance cost inflation as key forecast inputs.
Underlying assumptions cover regulatory enforcement continuity, energy cost stabilization, and free zone incentive persistence, with deviation risk concentrated in MOHAP mandate timing and refrigerant phase-down schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
US Tolling Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market