
 US Confectionery Market | 2026-2036
US Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
US Confectionery Market Intelligence
Heightened consumer focus on sustainable cocoa sourcing and ethical labor practices is realigning purchasing decisions in the US confectionery sector. The Hershey Company leverages its deep-rooted brand recognition within the domestic market. Mars, Incorporated competes on the strength of its extensive global supply chain and marketing power. Mondelez International sustains its market presence through a diverse portfolio that includes both chocolate and other snack formats.
Confectionery comprises food products rich in sugar and carbohydrates, including items derived from cocoa solids, sugar syrups, and gelling agents. These products are manufactured primarily for indulgent consumption and are characterized by their flavor, texture, and sweetness. While chocolate remains the largest product type by value, gummies and sour flavor profiles show significant momentum among younger consumer age groups. Supermarkets and convenience stores dominate distribution, but online retail creates new avenues for specialty brands.
The US Food and Drug Administration (FDA) governs ingredient safety, allergen labeling, and health claims for all confectionery products. Concurrently, USDA organic certification provides a standard for products seeking to appeal to consumers preferring agricultural inputs free from synthetic pesticides. Navigating evolving consumer health perceptions and potential new federal nutrition guidelines will be critical for future product development and market positioning.
Market Dynamics
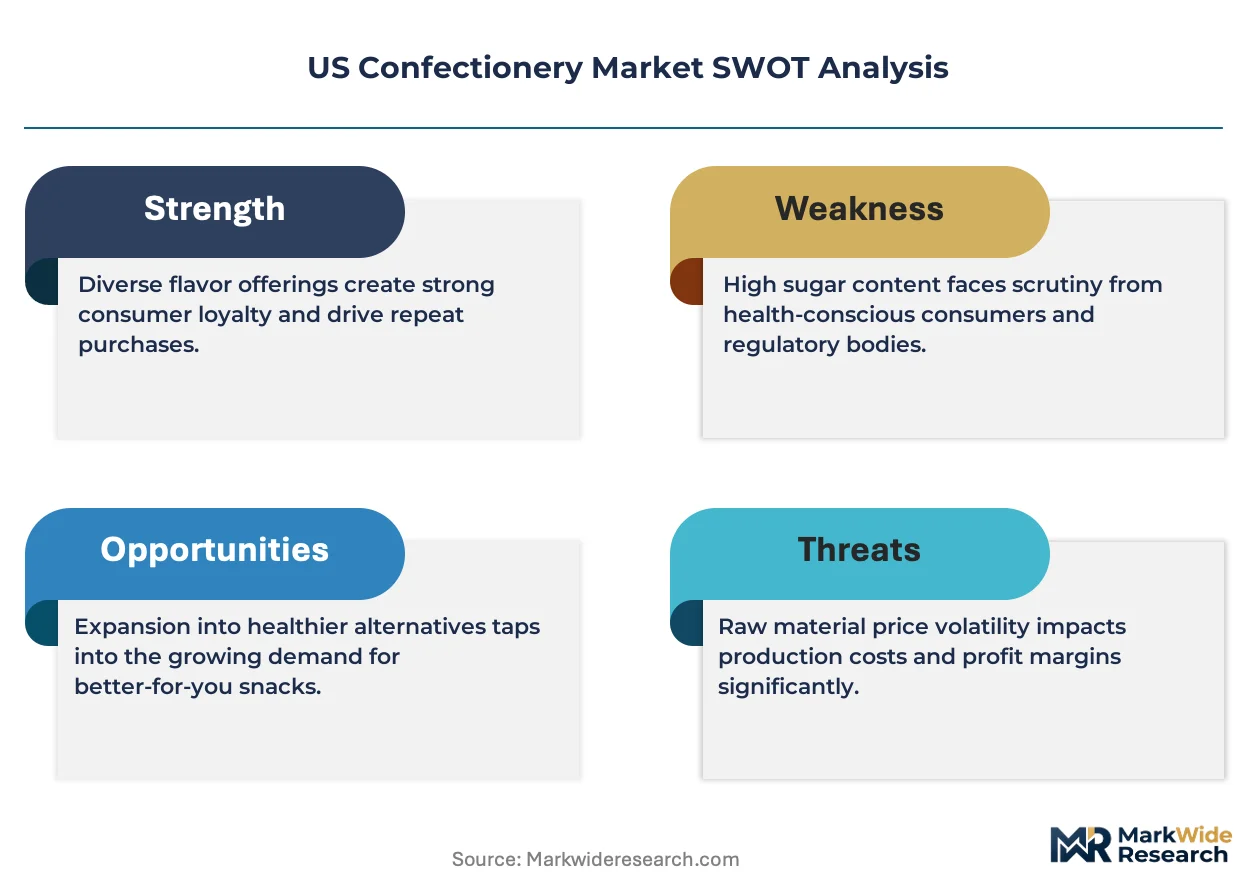
Heightened consumer scrutiny of sugar and artificial ingredients, amplified by potential FDA front-of-package labeling rules, is the central force shaping the US confectionery market. This pressure compels reformulation toward reduced-sugar and natural-ingredient profiles across all product categories.
Growth Catalysts
- Premium Product Lines:Demand from adult consumers in urban centers across California and the Northeast for artisanal and high-cocoa-content chocolates creates significant growth avenues for premium-priced items.
- Online Retail Expansion:The rise of e-commerce and direct-to-consumer platforms enables specialty and craft brands to bypass traditional supermarket gatekeepers and reach a national audience.
- USDA Organic Certification:Consumer preference for products with clean labels and agricultural inputs free from synthetic pesticides drives momentum for confectionery items bearing the USDA organic seal.
Market Restraints
- Cocoa Price Volatility:Dependence on global cocoa supply chains exposes US manufacturers to significant price fluctuations and supply disruptions, impacting cost structures and margin stability.
- FDA Labeling Mandates:Evolving FDA regulations on nutritional labeling and health claims increase compliance costs and limit marketing flexibility, particularly for products high in sugar and fat.
- Snack Category Substitution:Intense competition from healthier snack alternatives, such as protein bars and fruit-based snacks, draws away consumer spending from traditional confectionery products.
Strategic Opportunities
- Plant-Based Formulations:Developing vegan and dairy-free confectionery using alternative ingredients like oat milk offers a significant opportunity to capture a growing consumer segment focused on plant-forward diets.
- Reduced-Sugar Offerings:Reformulating popular products with sugar substitutes to cater to health-conscious adults creates a new market tier for permissible indulgence without sacrificing flavor.
- Automated Retail Channels:Deploying smart vending machines in airports, offices, and university campuses provides a new, low-overhead distribution channel for impulse-purchase confectionery items.
Industry Challenges
- Ethical Sourcing Verification:The operational complexity of ensuring and documenting complete supply chain traceability for ingredients like cocoa to meet ethical labor standards is a major hurdle.
- Manufacturing Labor Scarcity:Attracting and retaining skilled operators for increasingly automated confectionery production lines presents a persistent operational challenge for US-based manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Confectionery Market |
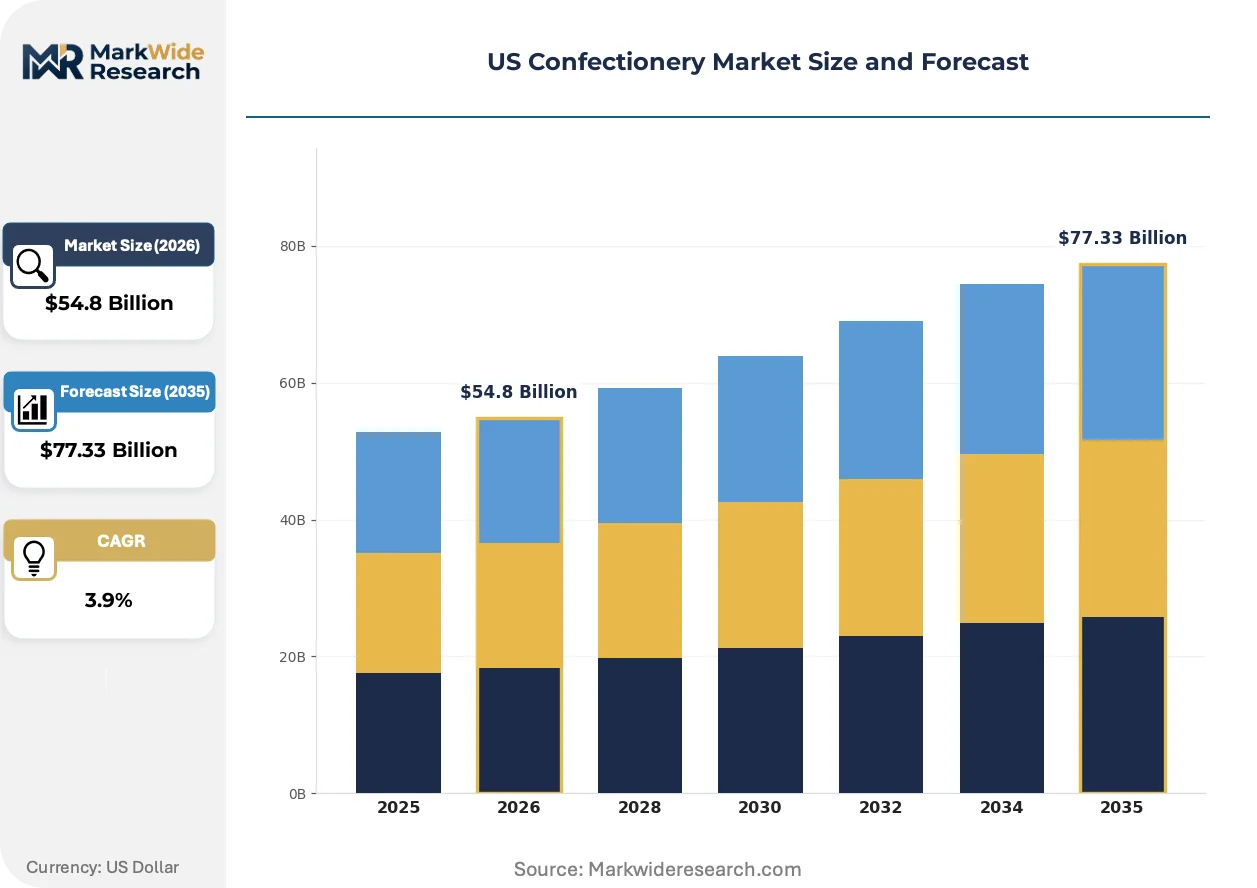
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $77.33 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candy, Licorice Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Consumer Age Group: Children, Teenagers, Adults, Seniors Flavor Profile: Fruity, Mint, Sour, Spicy |
| Companies Covered | The Hershey Company, Mars, Incorporated, Mondelez International, Ferrero International SA, Nestlé S.A., General Mills, Lindt & Sprüngli, Ferrara Candy, Perfetti Van Melle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Confectionery Market Strategic Shifts & Innovations
The fusion of indulgence with personal wellness and ethical considerations is reshaping product development in the US confectionery sector. Manufacturers are innovating beyond flavor to incorporate functional benefits and transparent sourcing narratives into their core value propositions.
Advanced sugar reduction technologies like allulose provide the sweetness of sucrose with fewer calories. Mainstream producers adopt these to reformulate legacy products for health-conscious consumers. This ingredient science is converging with traditional confectionery craftsmanship, enabling low-sugar premium products without compromising taste.
The FDA's proposed rule for front-of-package nutrition labeling aims to give consumers clearer, at-a-glance information. This policy shift is forcing manufacturers to re-evaluate formulations to avoid negative symbols related to high sugar or fat content. The chocolate segment is most affected, prompting preemptive reformulation into reduced-sugar options.
A shift in consumer purchasing prioritizes transparent sourcing and ethical production, often verified by third-party certifications. This disrupts brand loyalty based on flavor alone, with mission-driven brands gaining share in channels like natural food stores. This demand for transparency is most pronounced among younger cohorts in urban markets.
US Confectionery Market Segmentation
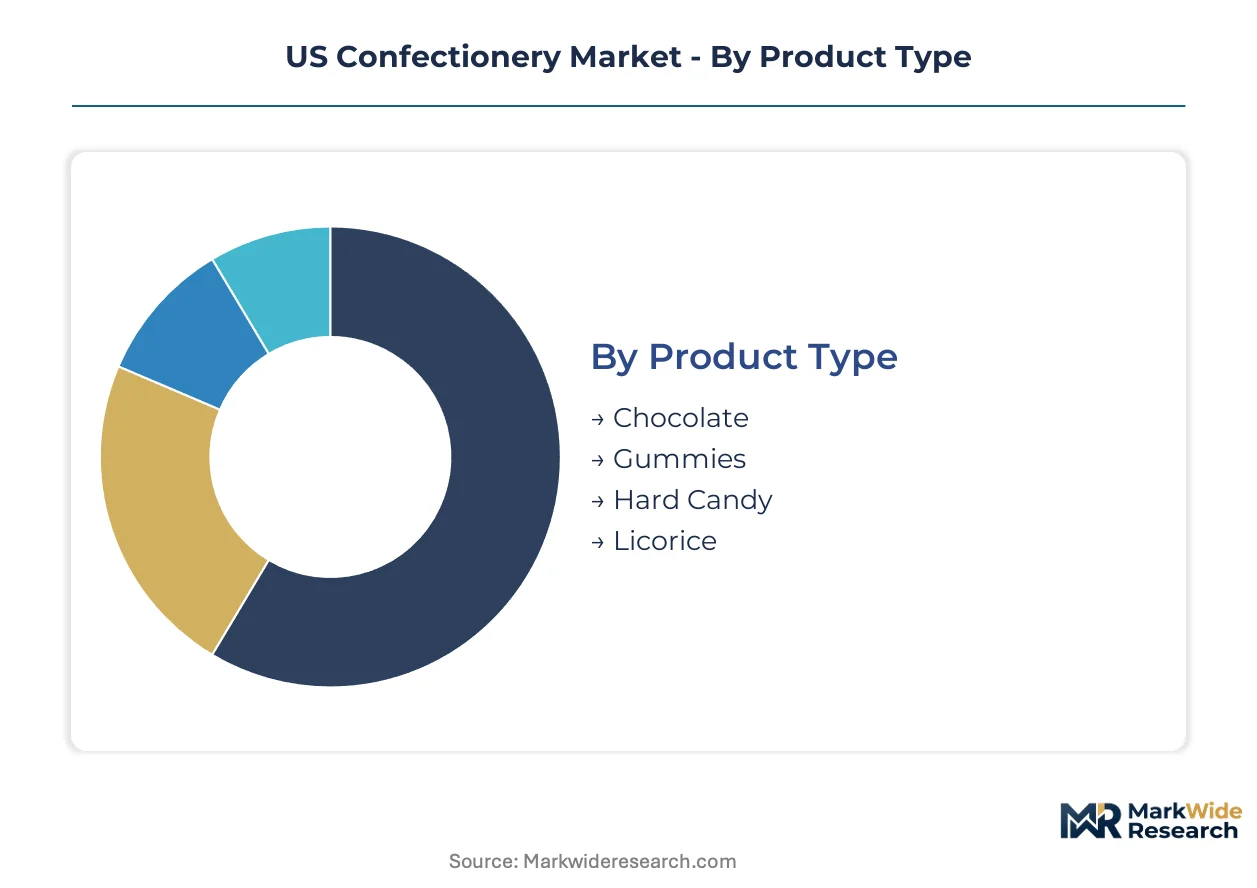
Segmentation analysis provides a granular understanding of the US confectionery market, revealing distinct consumer preferences, product characteristics, and distribution dynamics. This detailed breakdown helps manufacturers and retailers tailor strategies to specific market niches, optimizing product development and market positioning.
Product Type:
Manufacturing confectionery products often requires significant capital investment in specialized machinery for processing and packaging diverse formats.
- Chocolate:Cocoa-based solids, sugar, and milk fats characterize chocolate products, which remain the largest product type by value. Demand for premium, high-cocoa options is strong among adult consumers in urban centers across California, driven by a preference for sophisticated flavor profiles.
- Gummies:These gelatin-based confections offer a chewy texture and diverse fruit flavors, showing significant momentum among younger consumer age groups. Younger consumer age groups drive demand for gummies, particularly those with sour flavor profiles, influencing new product development in the US market.
- Hard Candy:Sugar-based confections are typically boiled to a hard, brittle state, appealing to a broad consumer base seeking long-lasting sweetness.
- Licorice:This confection, derived from the licorice plant root, offers a distinct flavor profile, finding a niche market among specific consumer demographics in the US.
Most installed capacity flows through Chocolate. Expansion is steepest in Gummies.
Distribution Channel:
The diverse distribution channels in the US confectionery market cater to varied consumer purchasing habits and accessibility requirements.
- Supermarkets:Large retail formats offer a wide assortment of confectionery products, benefiting from high foot traffic and bulk purchasing by household consumers across the US. Their extensive shelf space supports both mainstream and private-label brands.
- Online Retail:E-commerce platforms provide direct-to-consumer access for specialty brands, enabling national reach without traditional gatekeepers. This channel facilitates targeted marketing and subscription models for unique confectionery items.
- Convenience Stores:These smaller retail outlets serve impulse purchases and immediate consumption needs, strategically located in high-traffic urban and suburban areas.
- Specialty Shops:Boutique stores focus on artisanal and premium confectionery, attracting consumers seeking unique, high-quality products and gifting options.
High-volume sales frequently occur through Supermarkets. The fastest growth in consumer reach is observed through Online Retail.
Consumer Age Group:
Different consumer age groups exhibit distinct purchasing behaviors and preferences, influencing product formulation and marketing strategies for confectionery manufacturers.
- Children:Confectionery products for children often feature bright colors and playful shapes, with marketing focused on fun and novelty.
- Teenagers:This demographic drives demand for novel flavors, particularly sour and gummy confections. Social media trends and peer influence significantly shape their brand preferences and consumption patterns in the US.
- Adults:This segment increasingly seeks premium, reduced-sugar, and ethically sourced confectionery options. Their purchasing decisions often prioritize indulgence combined with health consciousness, particularly in urban centers.
- Seniors:This group may prefer classic confectionery items and smaller portion sizes, with some attention to reduced-sugar or softer texture options.
Significant product innovation targets Adults. Volume consumption remains substantial among Children.
Flavor Profile:
The diverse flavor profiles available in the US confectionery market cater to evolving consumer palates and regional taste preferences.
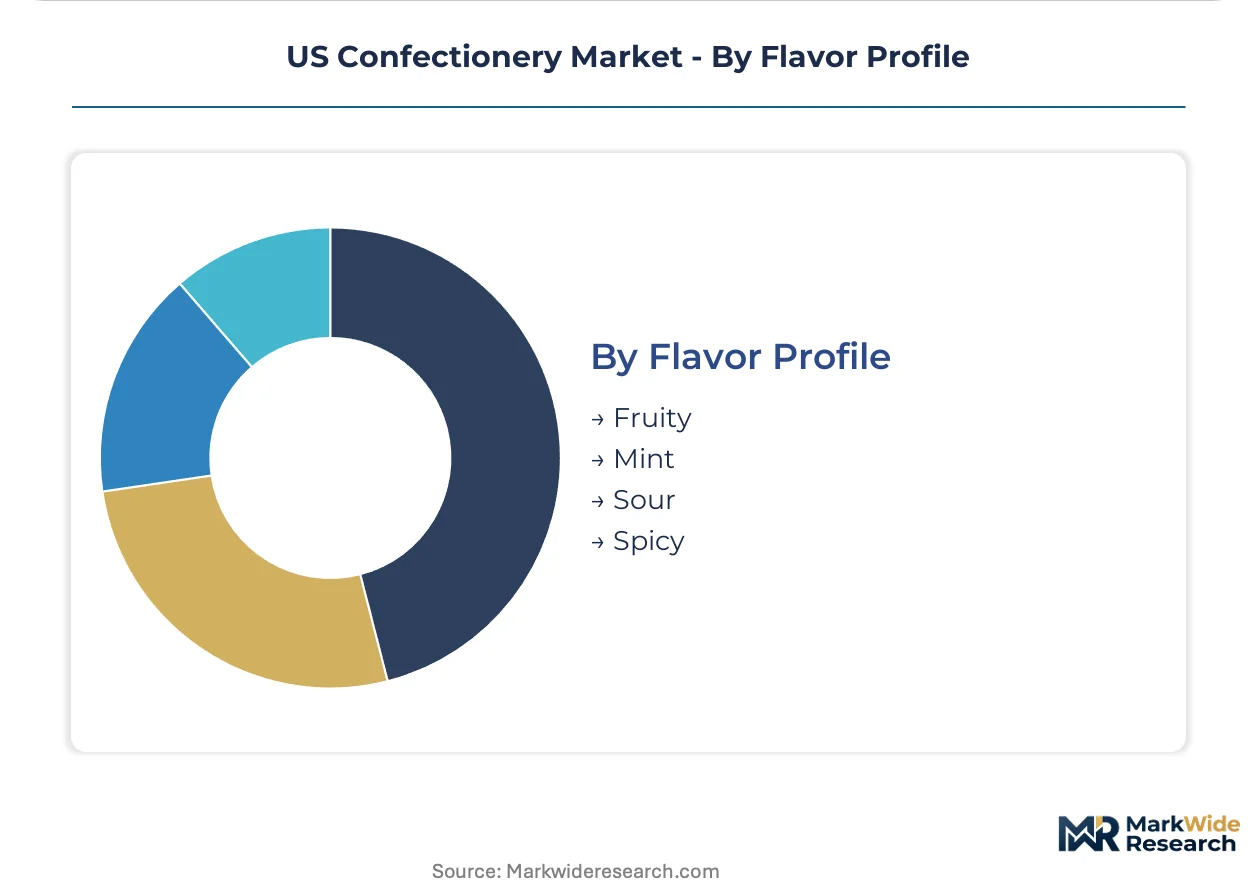
- Fruity:These confectionery items incorporate natural or artificial fruit essences, appealing to a broad consumer base seeking sweet and refreshing tastes. Flavors like strawberry, orange, and cherry remain perennially popular across US demographics.
- Mint:Mint-flavored confections offer a refreshing taste, often associated with after-meal consumption or breath-freshening properties.
- Sour:Characterized by tart and acidic notes, sour confections show significant momentum, especially among younger consumer age groups. Product innovation in this segment often focuses on extreme sourness or new fruit combinations.
- Spicy:This niche flavor profile incorporates chili or other heat-inducing ingredients, appealing to adventurous consumers seeking unique taste experiences.
Traditional consumer preference strongly favors Fruity profiles. The most dynamic innovation occurs within Sour flavors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US confectionery market developed from early colonial sugar refining and chocolate production, scaling significantly with industrialization in the 19th century. Key manufacturing hubs emerged in the Northeast and Midwest, driven by access to raw materials and growing urban populations. This historical foundation shaped current regional concentrations and consumer preferences across the country.
California
Demand for premium, high-cocoa confectionery and plant-based alternatives drives innovation among health-conscious consumers. The FDA's focus on front-of-package labeling influences local product reformulation strategies. Los Angeles and San Francisco host numerous artisanal chocolate makers developing unique, ethically sourced offerings.
Northeast Corridor
Urban centers within the Northeast Corridor exhibit strong demand for specialty and gourmet confectionery, particularly artisanal chocolates. State-level initiatives often complement USDA organic certification efforts, promoting local and sustainable ingredient sourcing. New York City and Boston remain hubs for craft confectioners, innovating with unique flavor profiles and premium ingredients.
Midwest
Traditional confectionery consumption remains strong across the Midwest, with a steady demand for classic chocolate bars and hard candies. Federal food safety guidelines from the FDA ensure consistent product quality across large-scale manufacturing facilities. Chicago and Hershey, Pennsylvania, historically serve as major confectionery manufacturing centers, driving significant production volumes.
Southeast
The Southeast region shows rising demand for convenient snack-sized confectionery and fruit-flavored gummies, appealing to diverse family demographics. Local health departments collaborate with the USDA to ensure compliance with food standards for regional producers. Atlanta and Orlando are emerging as key distribution points, facilitating the flow of mass-market and impulse confectionery items.
US Confectionery Market Key Industry Players
Premium-margin players sit above commodity-margin players across brand recognition and ingredient quality within the US confectionery market. This market exhibits a tiered structure, from large multinational corporations to niche artisanal producers. Three strategic archetypes include global confectionery giants, specialty craft brands, and private-label manufacturers focused on cost efficiency. Portfolio diversification and strategic partnerships represent dominant competitive moves among established players seeking broader consumer reach.
Global confectionery powerhouses, such as The Hershey Company and Mars, Incorporated, exemplify the scale-driven archetype, leveraging extensive distribution networks and deep market penetration. These companies occupy a position defined by broad consumer appeal and established brand loyalty across numerous product lines. Mondelez International, Inc., further anchors the market with its diverse portfolio, representing a strategy of wide product category coverage that extends beyond just chocolate to other snack formats. These entities utilize their operational size and marketing prowess to maintain significant market presence and influence consumer trends.
| Leading Market Players |
|---|
| The Hershey Company |
| Mars, Incorporated |
| Mondelez International |
| Ferrero International SA |
| Nestlé S.A. |
| General Mills |
| Lindt & Sprüngli |
| Ferrara Candy |
| Perfetti Van Melle |
| Others |
Cost & Logistics Intelligence
Advanced sugar reduction technologies simultaneously reshape cost economics and supply concentration in the US confectionery market. These innovations enable manufacturers to meet evolving consumer health demands while navigating volatile raw material prices.
Pricing Analysis
Premium-mid-economy pricing differentiation defines the US confectionery market, reflecting product quality and brand recognition. Certification levels, like USDA organic or ethical sourcing labels, drive significant price premiums for specialty items. Pricing pressure stems from intense competition with healthier snack alternatives. Mass-market consumers exhibit higher price sensitivity compared to adult consumers seeking premium indulgence.
Supply Chain Analysis
Ethical sourcing verification gates access to premium market segments for cocoa and sugar. The US confectionery supply chain draws heavily from West Africa for cocoa beans and Brazil for sugar. Cocoa price volatility represents a significant structural risk, impacting manufacturers' margin stability. Distribution runs through a dual model, with supermarkets dominating volume and online retail capturing specialty sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US confectionery market offers geographic-arbitrage opportunities, particularly given the differing regulatory approaches to sugar labeling between states and federal agencies.
For Market Incumbents: Anchor broad market share by leveraging established distribution networks to introduce reduced-sugar versions of popular brands. Invest in R&D for next-generation sugar substitutes to counter the threat from healthier snack alternatives. Consolidate raw material sourcing to mitigate cocoa price volatility and ensure ethical supply chain compliance.
For New Entrants and Emerging Players: Direct-to-consumer platforms provide an effective route to bypass traditional gatekeepers and reach niche audiences. Target the underpenetrated premium plant-based and functional confectionery segments among health-conscious adults. Focus marketing efforts on transparent sourcing narratives to build brand loyalty in urban centers.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy brands facing significant reformulation costs and declining traditional product sales. Assess specialty craft brands focused on unique flavor profiles or innovative ingredient technologies for acquisition. The implementation timeline of new FDA front-of-package labeling rules is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Introduce Plant-Based Chocolate Lines | The Hershey Company can capture growing demand from consumers seeking vegan and dairy-free options. |
| Invest in Sugar Reduction R&D | Mars, Incorporated can reformulate core products to appeal to health-conscious adult consumers. |
| Expand Direct-to-Consumer Channels | Mondelez International can reach niche markets and offer exclusive premium confectionery items. |
| Strengthen Ethical Sourcing Programs | Ferrero International SA can enhance brand reputation and meet consumer demand for transparent practices. |
| Automate Production Facilities | Nestlé S.A. can improve operational efficiency and reduce manufacturing labor scarcity challenges. |
Research Approach
Coverage spans the US, with primary inputs from California, the Northeast, Midwest, and Southeast regions. This analysis combines primary interviews with product development scientists, retail category managers, and supply chain directors, validated by secondary data. Bottom-up and top-down triangulation ensures robust market sizing and forecast accuracy.
Granularity-level framing modeled the market across product type, distribution channel, consumer age group, and flavor profile. The analytical framework integrated macroeconomic indicators and industry-specific drivers to derive compound annual growth rates over the projection horizon. Key forecast inputs included consumer spending patterns and raw material price forecasts.
Regulatory changes, cocoa price volatility, and shifting consumer health trends are the dominant revision risks for this market. Forecasts reflect assumptions regarding stable trade policies and sustained consumer demand for indulgent products. A model refresh is warranted upon material change in federal nutrition guidelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Ice Cream Coating Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
UK Confectionery Market
Confectionery
South America Confectionery Market
Confectionery
United States and Europe Macarons Market
Confectionery
Europe Compound Chocolate Market
Confectionery
South America Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
South Korea Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Ruby Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Low Calorie Treats Market
Confectionery
Sugar-Free Gummy Market