
 Germany Car Insurance Market | 2026-2036
Germany Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Car Insurance Market Insights
Baden-Württemberg is reconfiguring how actuarial risk pools form across southern Germany's manufacturing belt. Allianz leverages its captive reinsurance architecture to sustain pricing power in comprehensive coverage. HUK-COBURG anchors its position through direct-to-consumer channels that bypass traditional broker commissions. AXA Germany competes by specializing in fleet risk analytics for corporate clients with multi-vehicle portfolios.
Germany Car Insurance constitutes a contractual risk-transfer mechanism where policyholders pay premiums in exchange for indemnification against collision, theft, liability, and weather-related vehicle damage. Insurers price contracts using telematics data, vehicle safety ratings, and regional claims frequency to determine individual risk exposure. Third-Party Liability retains mandatory status under German motor law, though margin pools concentrate in Comprehensive and Telematics segments where data-driven underwriting permits granular pricing. Fleet Operators represent a growing customer segment as logistics firms consolidate vehicle procurement under single-policy frameworks.
BaFin supervises solvency requirements and consumer protection standards, while the EU Insurance Distribution Directive governs broker transparency and product suitability across German distribution channels. The KBA vehicle registration database feeds directly into insurer risk models, linking type-approval data to policy pricing algorithms. Stakeholders must monitor how connected-car data ownership disputes between OEMs and insurers reshape telematics product viability.
Market Dynamics
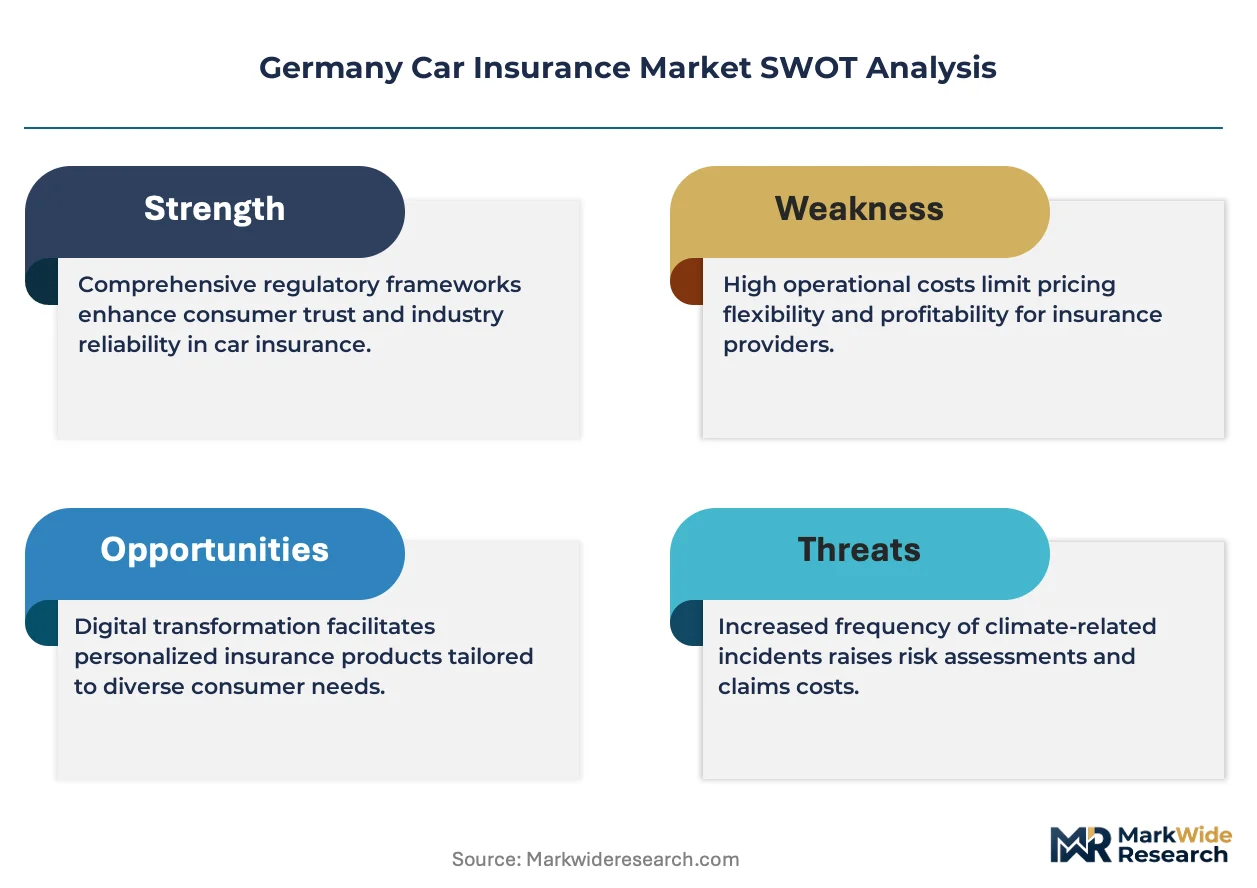
Telematics data ownership disputes between German OEMs and insurers are fragmenting risk-pooling capabilities while BaFin tightens solvency scrutiny under EU Insurance Distribution Directive mandates. This structural tension compresses margins in comprehensive coverage segments.
Growth Catalysts
- Fleet consolidation:Logistics operators bundling multi-vehicle procurement under single-policy frameworks expand commercial premium pools. This segment concentrates in Baden-Württemberg manufacturing corridors.
- EU Green Deal:Emissions-based pricing mandates accelerate usage-based insurance adoption. Insurers redesign products around carbon-intensity metrics tied to KBA registration data.
- Telematics integration:Connected-vehicle sensor feeds enable granular risk segmentation. Real-time driving behavior data replaces traditional actuarial proxies in premium calculation.
Market Restraints
- Data sovereignty conflicts:Volkswagen, BMW, and Mercedes-Benz assert proprietary control over connected-car telemetry streams. Insurers face input cost volatility when negotiating data licensing terms.
- Broker commission structures:Traditional distribution channels capture 15-25% of premium value. Direct-to-consumer models struggle to displace established intermediary relationships in rural Bavaria.
- Third-Party Liability saturation:Mandatory coverage status caps margin expansion. Price competition intensifies in this commoditized segment where differentiation remains technically constrained.
Strategic Opportunities
- Pay-per-mile products:Low-mileage urban households in Berlin and Hamburg remain underpenetrated. Usage-based policies align premiums with actual vehicle utilization patterns.
- Commercial fleet analytics:Risk management services bundling insurance with driver safety programs create recurring revenue. Logistics firms seek integrated solutions beyond pure indemnification.
- CSRD alignment:Corporate sustainability reporting mandates require fleet emissions disclosure. Insurers capture this data to develop carbon-adjusted coverage tiers.
Industry Challenges
- Actuarial talent scarcity:Data science expertise for telematics model development concentrates in Munich and Frankfurt. Regional insurers struggle to recruit predictive analytics specialists.
- Legacy system integration:Core policy administration platforms require multimillion-euro modernization to process real-time sensor feeds. Mid-tier carriers face compressed timelines for BaFin compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Car Insurance Market |
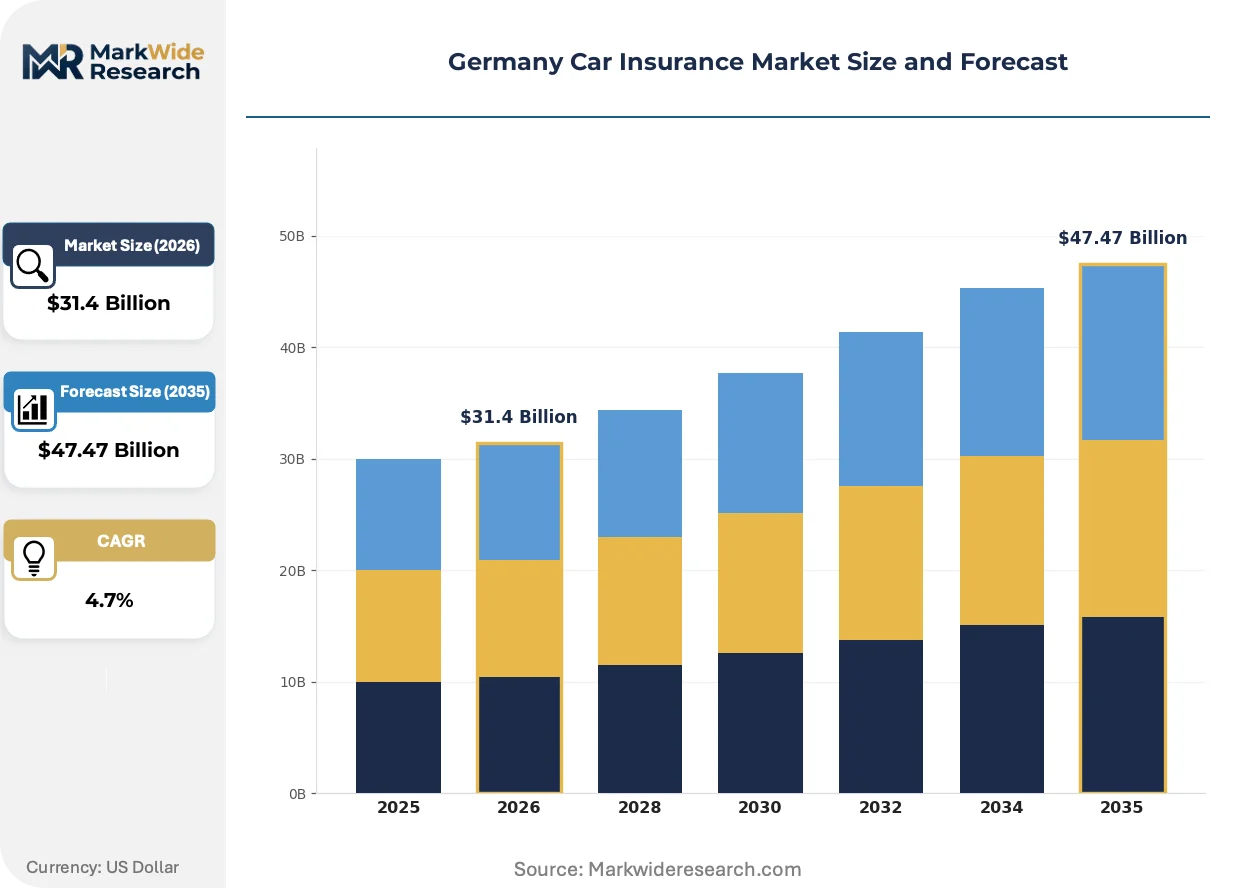
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.47 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Third-Party Liability, Comprehensive, Partial Comprehensive, Telematics Customer Segment: Individuals, Fleet Operators, Corporate Clients, Young Drivers Policy Duration: Short-Term, Annual, Multi-Year, Pay-Per-Mile Distribution Channel: Online, Brokers, Insurance Agents, Direct Sales |
| Companies Covered | Allianz, HUK-COBURG, AXA Germany, R+V Versicherung, LVM Versicherung, Provinzial, DEVK, Zurich Germany, Ergo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Car Insurance Market Trends and Innovations
Connected-vehicle architectures are collapsing traditional risk-assessment methodologies while regulatory pressure accelerates product redesign around emissions transparency. Insurers must rebuild underwriting infrastructure around dynamic data streams rather than static demographic proxies.
AI-powered claims assessment is rendering obsolete manual damage evaluation workflows. Allianz and HUK-COBURG deploy computer vision algorithms to process collision imagery within minutes. This compression eliminates adjuster dispatch costs and accelerates settlement cycles in comprehensive coverage segments.
BaFin's interpretation of EU Insurance Distribution Directive disclosure requirements tightens product suitability documentation. Brokers must demonstrate granular matching between policy features and customer risk profiles. Small intermediaries in Saxony and Thuringia face operational strain from enhanced audit trails.
Fleet procurement managers now demand unbundled risk services separating insurance from vehicle leasing and maintenance contracts. Corporate buyers in North Rhine-Westphalia negotiate modular coverage components through direct insurer relationships. This disintermediation threatens traditional broker consolidation models in commercial segments.
Germany Car Insurance Market Segmentation
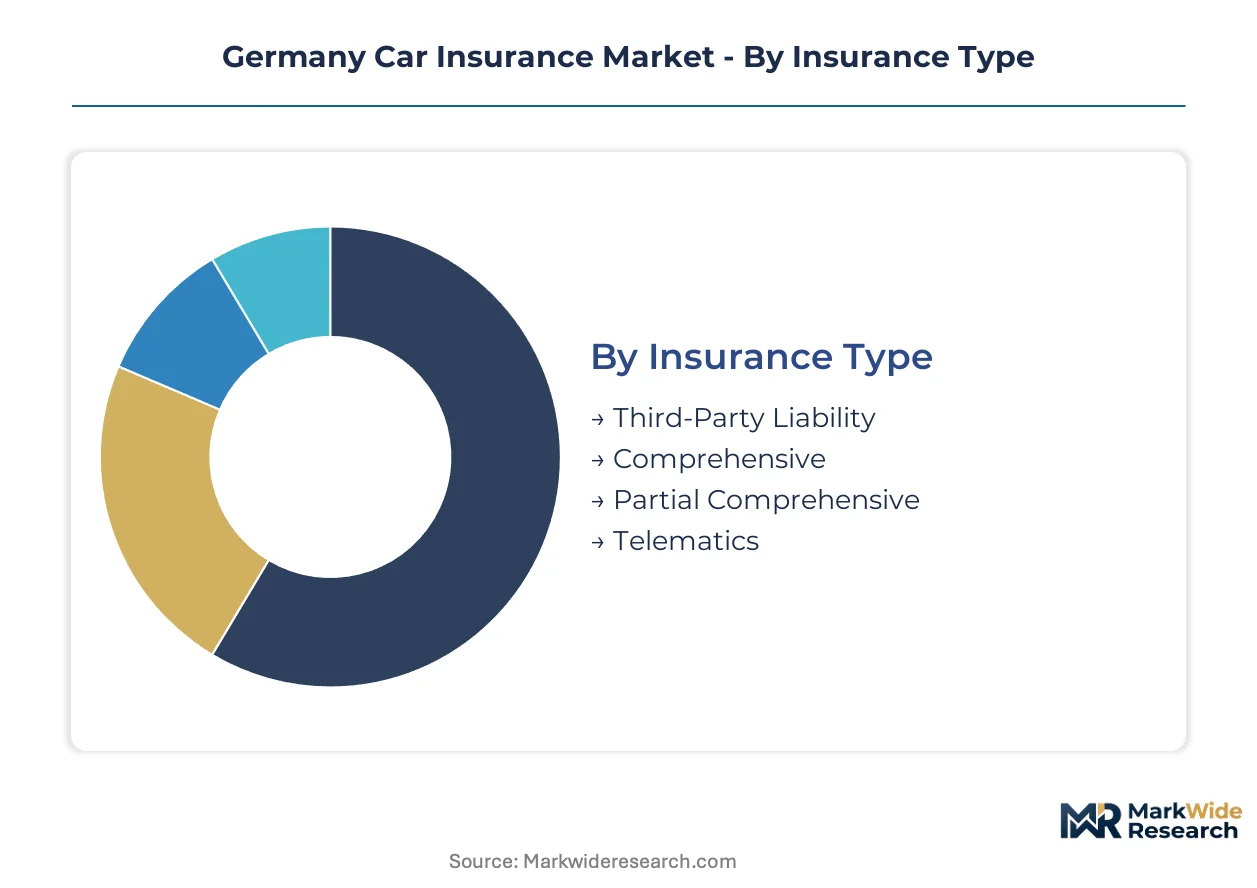
German motor insurers structure product portfolios across four distinct dimensions. Each segmentation axis reveals divergent margin profiles and distribution economics that shape competitive positioning.
Insurance Type:
Cost tier determines both regulatory treatment and pricing flexibility across coverage categories.
- Third-Party Liability:Mandatory motor coverage under German traffic law with standardized minimum limits. Premium compression dominates as price comparison portals drive commoditization in rural Bavaria and Saxony.
- Comprehensive:Full-coverage indemnity against collision, theft, and weather damage with substantial pricing discretion. Demand concentrates in Baden-Württemberg where luxury vehicle density supports higher attachment points.
- Partial Comprehensive:Named-peril coverage excluding collision damage, targeting older vehicle owners seeking cost containment.
- Telematics:Usage-based contracts pricing risk through real-time driving behavior feeds from connected vehicles.
Third-Party Liability commands the established base. The steepest expansion runs through Telematics.
Customer Segment:
Application context shapes risk pooling sophistication and service bundling requirements.
- Individuals:Private vehicle owners purchasing single-policy coverage through comparison platforms or agent networks. Price sensitivity peaks in eastern federal states with lower household vehicle counts.
- Fleet Operators:Commercial vehicle pools procuring unified risk management across logistics and delivery fleets. Procurement managers in North Rhine-Westphalia negotiate modular unbundled services separating insurance from leasing.
- Corporate Clients:Multi-entity enterprises with centralized insurance procurement and dedicated risk managers.
- Young Drivers:First-time policyholders facing elevated risk ratings and restricted coverage options until claims history accumulates.
Individuals command the established base. Fleet Operators are climbing the fastest.
Policy Duration:
Volume commitment depth structures insurer cash flow predictability and customer switching costs.
- Annual:Standard 12-month renewable contracts dominating German motor insurance with established cancellation windows. Regulatory notice periods and automatic renewal provisions lock in recurring premium streams.
- Pay-Per-Mile:Usage-calibrated premiums tracking actual kilometers driven through odometer verification or GPS logging. Low-mileage urban households in Berlin and Hamburg remain underpenetrated despite alignment with mobility patterns.
- Short-Term:Temporary coverage for vehicle transfers, seasonal use, or rental periods.
- Multi-Year:Extended-term contracts with rate guarantees and loyalty discounts.
Annual contracts command the established base. Pay-Per-Mile shows the steepest expansion trajectory.
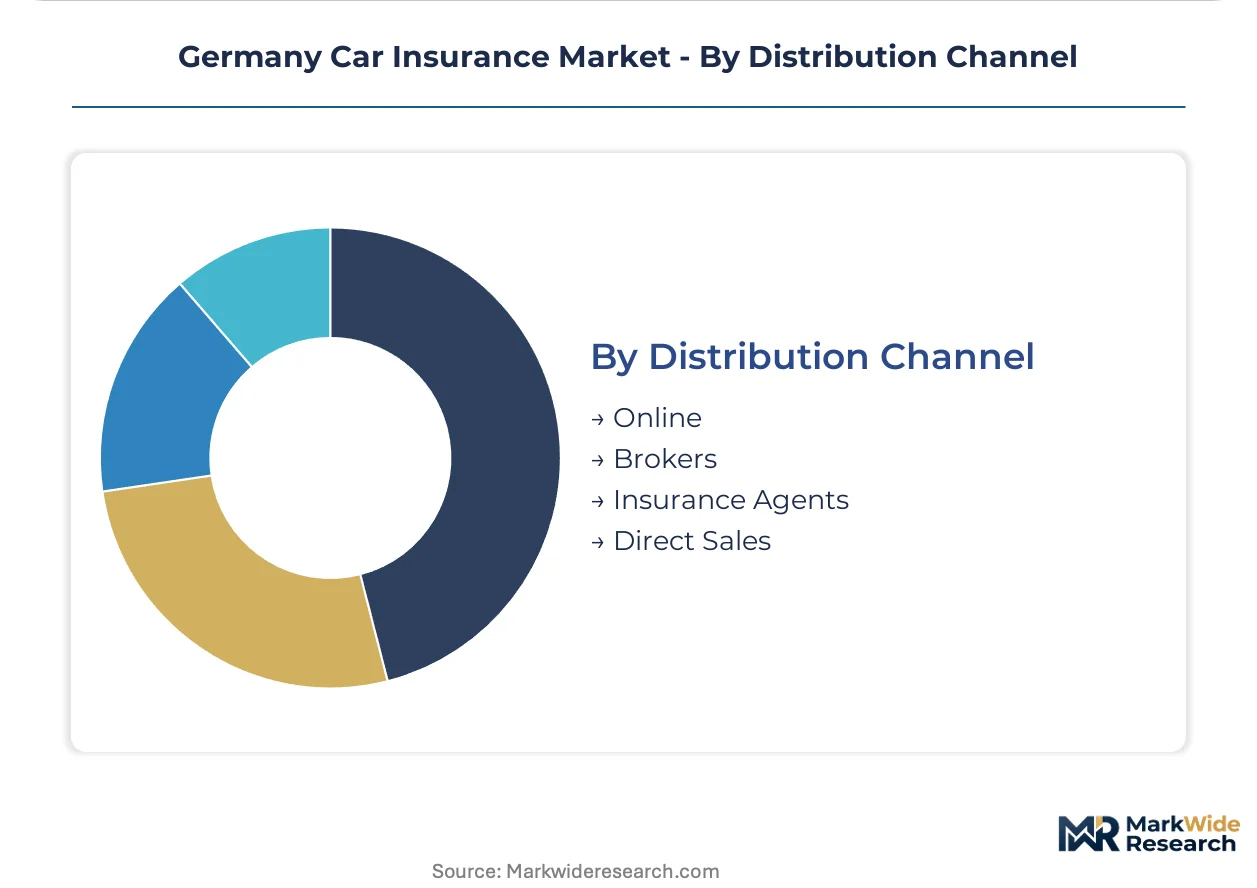
Distribution Channel:
Customer type and geography determine channel economics and intermediary capture rates.
- Brokers:Independent intermediaries commanding 15-25% commission structures with established rural relationships. BaFin's EU Insurance Distribution Directive compliance burdens strain small Saxony and Thuringia operators.
- Online:Digital comparison platforms and direct insurer portals bypassing intermediary commissions. HUK-COBURG anchors market position through direct-to-consumer scale.
- Insurance Agents:Tied representatives serving specific insurer portfolios with localized advisory relationships.
- Direct Sales:Captive insurer channels including telephone and proprietary digital platforms.
Brokers command the established base. Online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BaFin anchors solvency oversight across German motor insurance, with regional policy density tracking automotive manufacturing corridors and urban household vehicle ownership patterns.
Baden-Württemberg
Luxury vehicle manufacturing clusters around Stuttgart and Sindelfingen drive comprehensive coverage demand. The EU Green Deal emissions standards accelerate telematics adoption among premium car owners. Insurers leverage KBA registration data to price risk for high-value vehicle pools concentrated in this southwestern manufacturing belt.
Bavaria
BMW and Audi headquarters anchor Munich-Ingolstadt automotive density, sustaining elevated policy penetration rates. Broker commission structures retain dominance in rural Upper Bavaria despite direct-to-consumer channel expansion. Munich-based actuarial talent pools concentrate predictive analytics expertise for telematics model development.
North Rhine-Westphalia
Logistics corridor density between Cologne and Düsseldorf expands fleet operator procurement of bundled risk management. Corporate buyers negotiate modular unbundled services separating insurance from vehicle leasing contracts. The KBA feeds registration data directly into insurer pricing algorithms for commercial vehicle pools.
Hamburg
Port logistics and maritime commerce sustain commercial fleet density with specialized cargo vehicle coverage needs. Low-mileage urban households remain underpenetrated by pay-per-mile products despite alignment with compact city mobility patterns. Direct-to-consumer channels gain traction faster here than in rural eastern federal states.
Berlin-Brandenburg
Capital region regulatory proximity shapes BaFin compliance infrastructure deployment across eastern Germany. Young driver segments concentrate in Berlin's dense urban core with restricted coverage options until claims history accumulates. Telematics integration accelerates as connected-vehicle adoption outpaces national averages in this technology-forward metro.
Germany Car Insurance Market Competitive Landscape
Capability concentration sits with data-rich incumbents; scale advantage sits with direct-to-consumer specialists. The market structures around three tiers: integrated financial conglomerates with captive reinsurance, mutual insurers with member-owned governance, and international carriers with fleet analytics specialization. Strategic moves center on telematics data licensing negotiations with OEMs and direct channel expansion to capture broker commission pools.
Within the integrated conglomerate tier, Allianz anchors positioning through captive reinsurance architecture. HUK-COBURG exemplifies the mutual model with direct-to-consumer scale bypassing traditional intermediaries. AXA Germany occupies the international specialist position in fleet risk analytics for corporate multi-vehicle portfolios. These three represent divergent competitive archetypes competing for premium pools across liability, comprehensive, and telematics segments.
| Leading Market Players |
|---|
| Allianz |
| HUK-COBURG |
| AXA Germany |
| R+V Versicherung |
| LVM Versicherung |
| Provinzial |
| DEVK |
| Zurich Germany |
| Ergo |
| Others |
Pricing and Supply Chain Analysis
Telematics data sovereignty conflicts between German OEMs and insurers determine both tiered pricing spreads across comprehensive coverage segments and supply chain restructuring toward direct-to-consumer distribution models. This risk vector compresses margins in traditional broker-dependent channels while rewarding carriers that negotiate proprietary data feeds with Volkswagen, BMW, and Mercedes-Benz.
Pricing Analysis
Price differentiation between Baden-Württemberg and eastern federal states reaches three-tier stratification across premium, standard, and economy levels, with luxury vehicle density in Stuttgart manufacturing corridors supporting higher attachment points. Certification through BaFin solvency tiers separates established carriers from mid-tier competitors facing compliance modernization costs. Pricing pressure stems from broker commission capture of 15-25% in rural Bavaria, forcing direct-channel expansion. Fleet operators show least price sensitivity due to bundled risk management procurement, while young drivers in Berlin face restricted coverage options until claims history accumulates.
Supply Chain Analysis
Upstream feedstock of actuarial talent concentrates in Munich and Frankfurt, with predictive analytics expertise drawing from university partnerships and fintech migration patterns. Raw material dependencies center on KBA vehicle registration data, connected-vehicle sensor feeds, and AI-powered claims assessment algorithms. Single-source vulnerability sits with OEM-controlled telemetry streams, where Volkswagen, BMW, and Mercedes-Benz assert proprietary control over driving behavior data. Distribution runs through broker networks in rural regions, direct-to-consumer platforms in Hamburg and Berlin, and captive insurer channels for fleet procurement managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's car insurance market functions as a service-attach opportunity where risk management services bundling driver safety programs with indemnification expand faster than standalone policy growth. Recurring revenue from commercial fleet analytics outpaces premium expansion in commoditized liability segments.
For Market Incumbents: Build data moats through exclusive telematics licensing agreements with German OEMs before competitor negotiations harden terms. Consolidate actuarial talent in Munich through targeted recruitment from fintech analytics pools. Defensive positioning requires core policy administration platform modernization to process real-time sensor feeds under tightening BaFin solvency scrutiny. For New Entrants and Emerging Players: Establish a beachhead in pay-per-mile products for low-mileage urban households in Berlin and Hamburg where incumbent penetration remains thin. Target young driver segments through telematics-enabled dynamic pricing that rewards safe driving behavior with premium reductions. Go-to-market execution should leverage digital-native distribution bypassing traditional broker relationships in eastern federal states. For Investors and Strategic Acquirers: EU Insurance Distribution Directive disclosure mandates reshape the acquisition landscape toward direct-to-consumer specialists with compliant audit infrastructure. Long-term viability favors carriers with captive reinsurance architecture and proprietary data pipelines rather than broker-dependent intermediaries. Watch for inflection signals in OEM-insurer data licensing disputes that could strand telematics-dependent business models.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Licensing Agreement | Secures proprietary driving behavior feeds from BMW and Mercedes-Benz for granular risk segmentation. |
| Direct-to-Consumer Platform Expansion | Bypasses 15-25% broker commissions in rural Bavaria and captures switching customers through digital comparison portals. |
| Fleet Risk Analytics Service Launch | Bundles insurance with driver safety programs for logistics procurement managers in North Rhine-Westphalia. |
| Core System Modernization Investment | Enables real-time sensor feed processing for BaFin compliance and telematics product viability. |
| Actuarial Talent Hub Establishment | Concentrates predictive analytics expertise in Munich to overcome data science recruitment scarcity. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement managers, insurance broker network heads, actuarial directors at Tier 1 carriers, and BaFin compliance officers, then refined through secondary validation. Primary fieldwork combined structured interviews with commercial vehicle pool operators and risk management consultants. Secondary sources encompassed KBA vehicle registration databases, BaFin solvency disclosure filings, EU Insurance Distribution Directive implementation guidelines, and telematics platform technical specifications. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across Baden-Württemberg, Bavaria, and North Rhine-Westphalia.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across insurance type, customer segment, policy duration, and distribution channel dimensions. CAGRs derived from policy count trajectories and average premium per contract movements, incorporating EU Green Deal emissions pricing impacts and fleet consolidation patterns. Industry-specific inputs included KBA registration data flows, connected-vehicle adoption curves, and broker commission structure evolution.
Macroeconomic conditions sit as an overlay; deviation in German automotive production volumes, interest rate movements affecting insurer investment income, or regulatory acceleration of emissions-based pricing would shift the trajectory. Forecasts embed assumptions around OEM data licensing terms and BaFin enforcement intensity that carry material revision risk. Cross-checking against KBA monthly registration releases and BaFin quarterly solvency disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
IoT Insurance Market
Insurance
Africa Microinsurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Business Income Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Property Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Africa Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Embedded Insurance Market
Insurance
Small Business Insurance Market
Insurance
Social Media Analytics-Based Insurance Market