
 Small Business Insurance Market | 2026-2036
Small Business Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Small Business Insurance Market Analysis
Comprehensive coverage tiers is unwinding legacy basic-policy dominance as small businesses confront elevated litigation frequency and cyber exposure. The Hartford sustains its franchise through deep agent relationships and middle-market specialization. Hiscox competes by dominating micro-enterprise direct-to-consumer distribution in professional services. NEXT Insurance leverages proprietary underwriting algorithms to compress quote-to-bind cycles for contractors and gig-economy operators.
Small business insurance constitutes commercial risk-transfer instruments designed for non-corporate entities with annual revenues below established enterprise thresholds, typically incorporating per-occurrence limits, aggregate caps, and industry-specific exclusions calibrated to operational hazard profiles. General liability policies anchor the product mix as the mandatory entry point for commercial leases and vendor contracts. Professional liability is accelerating fastest among technology consultancies and fractional executive services. Workers' compensation retains state-mandated status, creating captive demand pools with limited price elasticity regardless of premium range tier.
US state insurance commissioners, NHTSA for commercial auto classifications, and OSHA workplace safety mandates collectively determine baseline coverage triggers and experience-rating methodologies across carrier portfolios. State-level workers' compensation monopolies in North Dakota, Ohio, Washington, and Wyoming fragment national underwriting strategies and force carriers to navigate divergent residual market mechanisms. Stakeholders must monitor how embedded insurance APIs and real-time payroll integrations reshape distribution economics and agent commission structures.
Market Dynamics
Embedded insurance APIs and real-time payroll integrations are compressing distribution economics while fragmenting traditional agent commission structures across carrier portfolios.
Growth Catalysts
- US Inflation Reduction Act clean-energy contractor provisions:Federal liability mandates for small solar and EV charger installers are expanding mandatory coverage pools and elevating policy minimums.
- Technology consultancies:Fractional executive services and AI implementation shops are driving professional liability attachment rates above historical small-business baselines.
- Texas-Florida-California formation clusters:Small-business density in these three states outpaces national averages, concentrating addressable premium pools and justifying localized underwriting investment.
Market Restraints
- State workers' compensation monopolies:North Dakota, Ohio, Washington, and Wyoming fragment national underwriting strategies and force carriers into residual market mechanisms with limited pricing control.
- Litigation frequency elevation:Social inflation and nuclear verdict trends in general liability lines are compressing combined ratios and restricting capacity for high-hazard classes.
- Cyber exposure asymmetry:Small businesses lack internal security infrastructure, creating adverse selection pools that carriers must segment through invasive data collection.
Strategic Opportunities
- Gig-economy operator expansion:Platform-linked independent contractors represent an underpenetrated segment requiring instantaneous, transaction-triggered micro-policies.
- API-first distribution partnerships:Vertical SaaS providers in construction, healthcare, and professional services offer embedded placement channels with reduced customer acquisition costs.
- OSHA workplace safety mandate alignment:Experience-rated premium programs tied to compliance data create retention mechanisms and loss-ratio improvement pathways.
Industry Challenges
- Actuarial talent scarcity:Small-commercial underwriters with multi-line expertise are concentrated at legacy carriers, constraining expansion velocity for insurtech entrants.
- Legacy system integration friction:Real-time data ingestion from payroll and accounting platforms requires middleware development that delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Business Insurance Market |
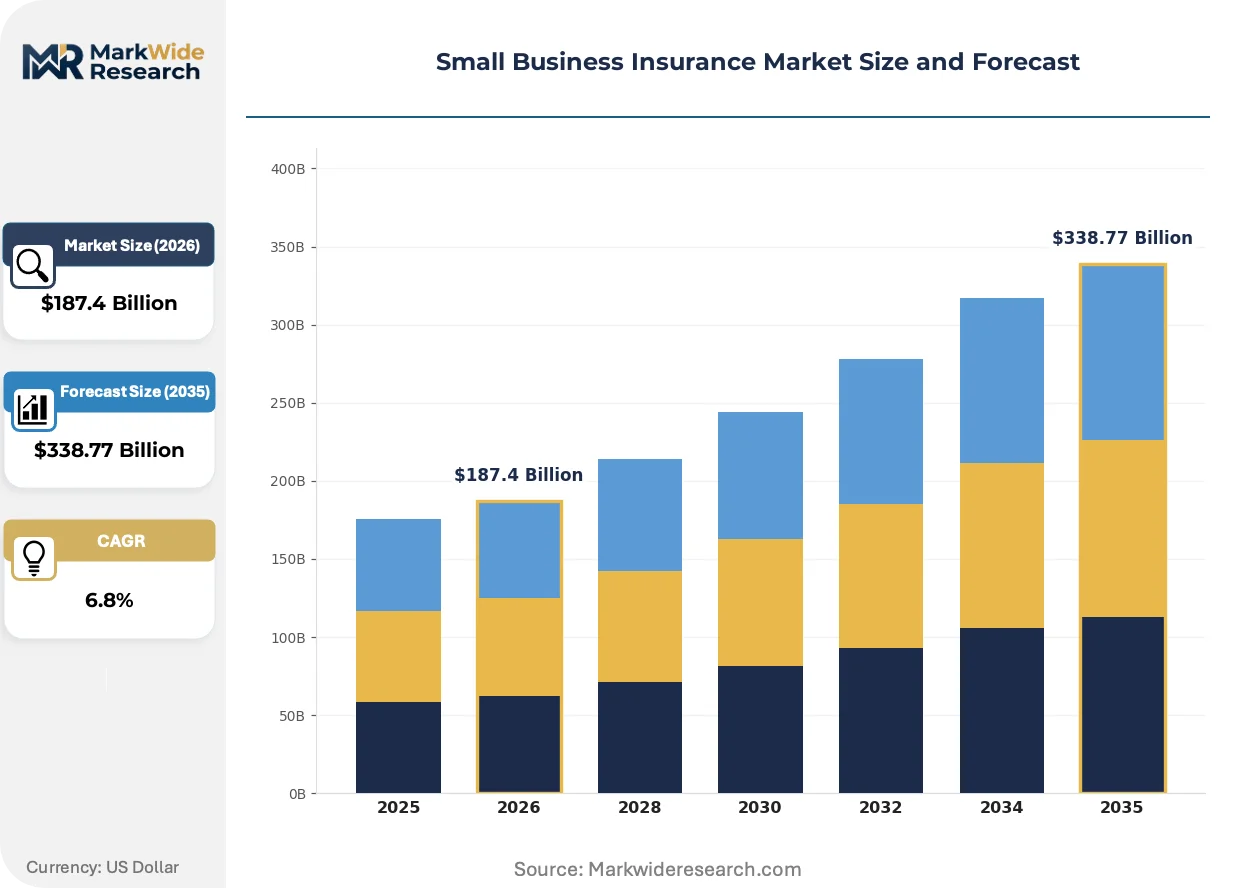
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: General Liability, Professional Liability, Commercial Auto, Workers' Compensation Coverage Level: Basic, Standard, Comprehensive, Umbrella Business Type: Retail, Service, Construction, Technology Premium Range: Low, Medium, High, Flexible |
| Companies Covered | Nationwide, Hiscox, The Hartford, Progressive, Travelers, NEXT Insurance, Thimble, Liberty Mutual, Simply Business, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Business Insurance Market Emerging Trajectories
Algorithmic underwriting engines and usage-based rating models are restructuring how small businesses access coverage, compressing quote-to-bind cycles from days to minutes.
Proprietary underwriting algorithms is supplanting traditional manual risk assessment in small-commercial lines. Technology startups and gig-economy operators now demand instantaneous quotes without agent intermediation. This compression is enabling direct-to-consumer carriers to capture micro-enterprise segments previously served by independent agents.
OSHA workplace safety mandates and state insurance commissioner experience-rating methodologies are converging to reward compliance-linked policyholders. Carriers integrating real-time safety data into renewal pricing gain retention advantages in workers' compensation lines. Construction and logistics verticals in California and Texas are responding fastest to these incentive structures.
Buyers now expect policy procurement embedded within operational software workflows rather than standalone transactions. Vertical SaaS platforms in construction management and healthcare scheduling are disintermediating traditional distribution. This channel migration is most visible among technology consultancies and fractional executive services purchasing professional liability coverage.
Small Business Insurance Market Segmentation
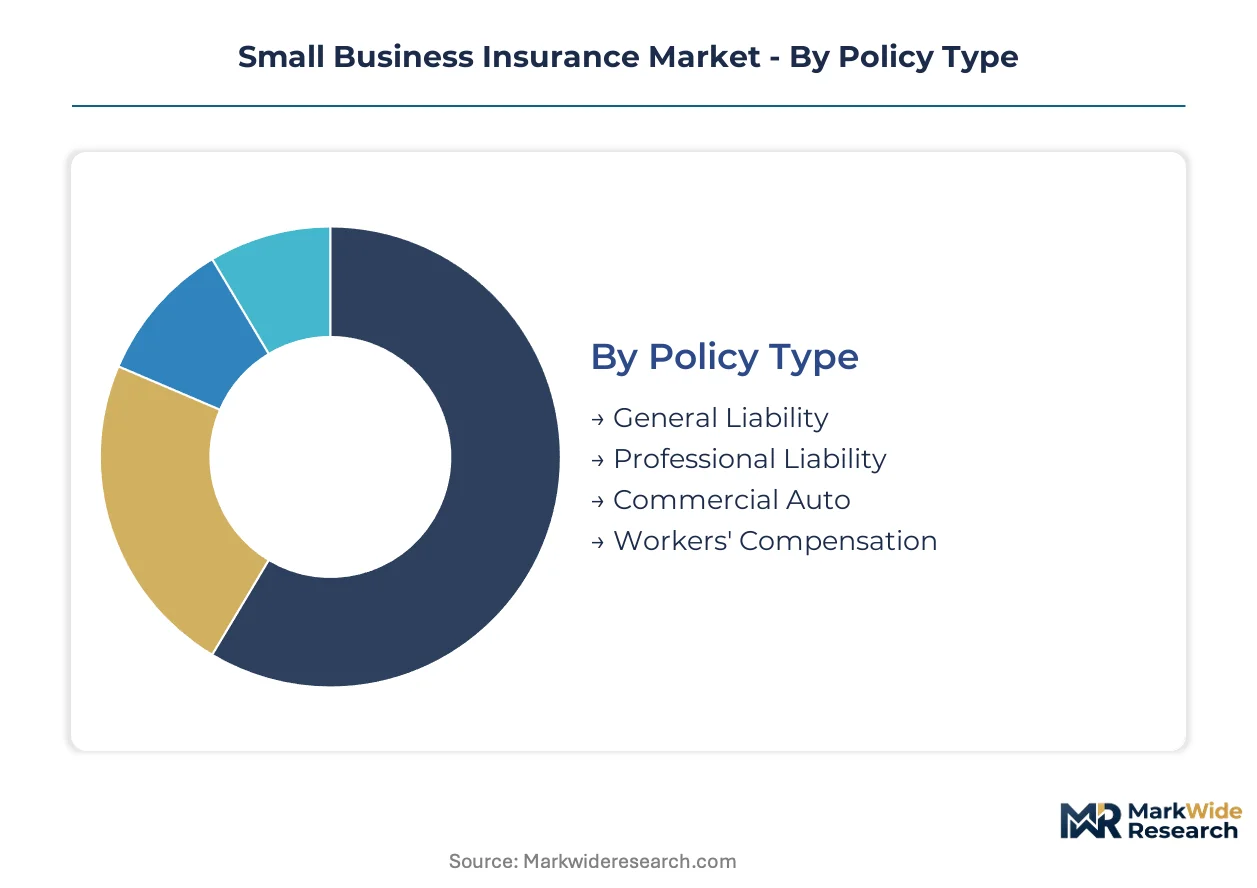
Small business insurance segmentation reveals divergent risk profiles and distribution economics across policy structures and buyer categories. Coverage tiers and business-type classifications determine underwriting complexity, commission structures, and renewal retention mechanics for carriers competing in this market.
Policy Type:
General liability and workers' compensation dominate domestic premium pools, while professional liability and commercial auto show stronger export-linked demand from multinational small enterprises.
- General Liability:Per-occurrence and aggregate coverage for third-party bodily injury and property damage claims. Demand concentrates in Texas, Florida, and California construction corridors where commercial lease mandates and vendor contract requirements create captive purchase obligations. OSHA workplace safety data integration is compressing loss ratios for compliant policyholders.
- Professional Liability:Errors-and-omissions protection for service-based operations including technology consultancies and fractional executive providers. Technology consultancies in California and New York are driving attachment rate expansion above historical small-business baselines as AI implementation risks elevate coverage minimums.
- Commercial Auto:Vehicle fleet coverage with NHTSA commercial classifications determining baseline premium tiers. Logistics operators in high-formation states anchor volume.
- Workers' Compensation:State-mandated wage replacement and medical coverage with experience-rating methodologies varying by jurisdiction. North Dakota, Ohio, Washington, and Wyoming monopolies fragment national underwriting strategies.
General liability holds the largest share; momentum sits with professional liability.
Coverage Level:
Premium tiering reflects litigation exposure escalation and cyber risk asymmetry rather than traditional property-value metrics.
- Basic:Minimal per-occurrence limits satisfying contractual minimums. Retail and food-service operations in low-litigation jurisdictions purchase primarily for lease compliance.
- Standard:Mid-tier aggregate caps with industry-specific exclusions calibrated to operational hazard profiles. Construction contractors in OSHA-monitored states favor this tier for bid eligibility.
- Comprehensive:Bundled multi-line protection incorporating cyber endorsements and employment practices liability. Technology consultancies purchasing through vertical SaaS platforms are climbing the fastest.
- Umbrella:Excess liability layers activating above primary policy limits. High-asset small businesses and clean-energy contractors facing IRA-mandated minimums drive selection.
Comprehensive coverage is displacing basic-policy dominance as nuclear verdict exposure reshapes buyer calculus.
Business Type:
Service and retail segments generate highest quote volume through direct-to-consumer channels, while construction and technology require agent-mediated placement for hazard complexity.
- Retail:Storefront operations with general liability and property bundling. Franchise networks in Texas and Florida concentrate addressable premium.
- Service:Professional and personal services with professional liability attachment. Fractional executive services and marketing agencies show steepest expansion trajectory.
- Construction:Trade contractors with workers' compensation and commercial auto requirements. Clean-energy installers under IRA provisions are expanding mandatory coverage pools.
- Technology:Software consultancies and AI implementation shops with cyber and E&O exposure. Gig-economy platform linkages create demand for instantaneous micro-policies.
Service businesses generate highest policy count; construction commands highest average premium per account.
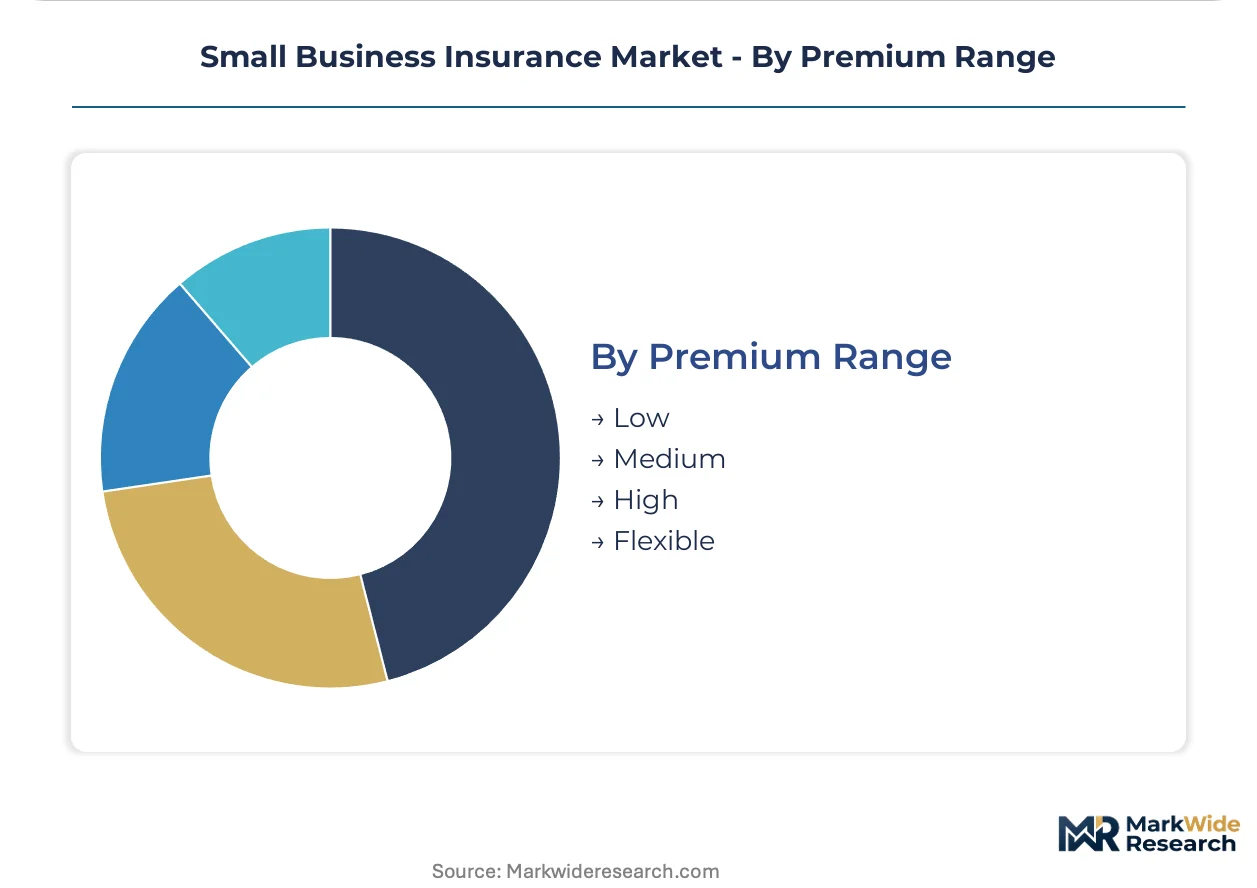
Premium Range:
Flexible pricing structures are gaining traction as usage-based models and real-time payroll integration enable dynamic premium adjustment.
- Low:Sub-thousand-dollar annual premiums for micro-enterprises with limited payroll and asset bases. Sole proprietors in professional services purchase primarily for contract compliance.
- Medium:Mid-market tiers covering businesses with 5-50 employees and moderate hazard profiles. Standard coverage bundles dominate this bracket.
- High:Elevated premiums for high-hazard classes including construction and transportation with elevated litigation frequency. Experience-rating programs tied to safety compliance data create retention mechanisms.
- Flexible:Usage-based and pay-as-you-go structures linked to real-time revenue or headcount fluctuations. Gig-economy operators and seasonal businesses favor this structure for cash-flow alignment.
Medium premium tiers anchor carrier revenue; flexible structures are expanding most quickly among insurtech entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US small business insurance carriers export coverage products to Canadian and Mexican enterprises through cross-border policy riders and multinational endorsements. Premium flows concentrate in states with elevated formation rates and hazard-exposed industries.
Texas
Energy contractors and logistics operators drive workers' compensation and commercial auto demand across the Permian Basin and Houston-Galveston corridor. OSHA workplace safety mandates shape experience-rating methodologies for construction firms bidding on federal infrastructure projects. Dallas-Fort Worth and Austin tech corridors are accelerating professional liability attachment rates among fractional executive services and AI consultancies.
California
Technology consultancies and clean-energy installers generate elevated professional liability and general liability quote volumes. The state's insurance commissioner enforces strict experience-rating transparency requirements that compress carrier pricing discretion. Silicon Valley and Los Angeles Basin clusters show fastest adoption of embedded insurance APIs through vertical SaaS procurement platforms.
Florida
Retail franchises and hospitality operations anchor general liability premium pools amid elevated litigation frequency. State-specific hurricane exposure caps limit capacity for property-catastrophe bundling in coastal counties. Miami-Dade and Tampa Bay metropolitan areas concentrate small-business formation outpacing national averages.
New York
Financial services boutiques and marketing agencies drive errors-and-omissions coverage demand with cyber endorsements. State workers' compensation requirements mandate coverage through the State Insurance Fund or authorized carriers. Manhattan and Brooklyn creative-industry clusters are shifting procurement toward instantaneous digital binding for professional liability.
Illinois
Manufacturing subcontractors and transportation operators sustain commercial auto and umbrella liability demand. The state's Department of Insurance regulates policy form standardization that limits carrier product differentiation. Chicago metropolitan area construction corridors are integrating real-time payroll data into usage-based premium structures.
Small Business Insurance Market Vendor Landscape
Listed leaders compete with private specialists across distribution channel dominance and underwriting technology deployment. The market fragments across three structural tiers: legacy carriers with captive agent networks, direct-to-consumer insurtech platforms, and embedded distribution partnerships through vertical SaaS providers. Strategic archetypes include middle-market generalists, micro-enterprise direct writers, and API-first algorithmic underwriters. Carriers defend position through M&A of data analytics capabilities and exclusive agency relationship consolidation.
Within the legacy carrier tier, The Hartford and Travelers occupy positions defined by deep agent relationships and multi-line bundling expertise. Among direct-to-consumer specialists, Hiscox and NEXT Insurance exemplify divergent approaches to micro-enterprise segmentation.
| Leading Market Players |
|---|
| Nationwide |
| Hiscox |
| The Hartford |
| Progressive |
| Travelers |
| NEXT Insurance |
| Thimble |
| Liberty Mutual |
| Simply Business |
| Others |
Supply Flow & Price Mechanics
OSHA workplace safety mandates and state insurance commissioner experience-rating methodologies gate both carrier qualification and premium differentiation simultaneously, compressing margins for non-compliant underwriters while rewarding integrated safety-data platforms with pricing power in workers' compensation lines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels in small-commercial lines. Premium differentiation rests on safety compliance certification tiers and real-time payroll integration depth, with price erosion running through basic-policy tiers as embedded APIs disintermediate agent commissions. Technology consultancies purchasing through vertical SaaS platforms show least price sensitivity; micro-enterprises in retail and food service exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpiling of actuarial talent dominates carrier hiring patterns, contrasting with just-in-time data partnerships for real-time underwriting feeds. Supply concentrates in the United States for licensed underwriting capacity, the United Kingdom for specialty Lloyd's syndicate expertise, and India for back-office policy administration. Raw material dependencies include proprietary algorithm development, cloud computing infrastructure, and regulatory compliance middleware. Single-source vulnerability in legacy system integration creates chokepoint risk. Distribution runs through captive agent networks, direct-to-consumer platforms, and embedded API partnerships with vertical SaaS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small business insurance operates on a cyclical recovery trajectory as federal infrastructure spending and IRA clean-energy provisions elevate mandatory coverage minimums across contractor classes.
For Market Incumbents: Secure exclusive agency relationships in Texas-Florida-California formation corridors to defend against direct-to-consumer disintermediation. Consolidate data analytics capabilities through targeted capability acquisitions, as algorithmic underwriting expertise concentrates at legacy carriers and constrains expansion velocity for challengers.
For New Entrants and Emerging Players: Anchor in gig-economy platform linkages where instantaneous micro-policy demand remains underpenetrated by traditional distribution. Target fractional executive services and AI implementation consultancies in California and New York corridors, deploying vertical SaaS embedded partnerships as the primary go-to-market channel.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across API-first algorithmic underwriting platforms as middleware development demands escalate. Long-term viability favors carriers with proprietary data ingestion infrastructure and state-level regulatory navigation expertise. Watch embedded insurance penetration rates in construction management and healthcare scheduling software as the inflection signal for distribution economics compression.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Distribution Partnership | Vertical SaaS integration in construction and healthcare compresses customer acquisition costs for professional liability placement. |
| Proprietary Algorithm Development | Real-time risk assessment engines differentiate quote-to-bind speed for gig-economy and contractor segments. |
| State Regulatory Navigation Investment | Workers' compensation monopoly expertise in North Dakota, Ohio, Washington, and Wyoming unlocks residual market access. |
| Safety Data Integration Platform | OSHA compliance-linked experience rating improves retention and loss ratios in construction and logistics verticals. |
| Embedded Insurance Capability Buildout | Transaction-triggered micro-policies capture platform-linked independent contractors outside traditional agent channels. |
Methodological Framework
A spread of perspectives from underwriting executives, independent agency principals, insurtech product managers, and state regulatory affairs directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against NAIC statistical compilations, OSHA enforcement databases, SEC carrier filings, and vertical SaaS platform partnership disclosures. Bottom-up premium pool sizing triangulated against top-down addressable market estimates across the projection horizon.
Segmentation dimensions modeled include policy type, coverage level tier, business type classification, premium range structure, and state regulatory framework cluster. CAGRs derived from historical premium growth trajectories, formation rate projections, and mandatory coverage expansion under federal infrastructure and clean-energy legislation. Industry-specific forecast inputs incorporated real-time payroll integration adoption curves and embedded API penetration rates in target verticals.
Underlying assumptions cover stable state workers' compensation mandate structures and continued IRA clean-energy contractor liability expansion, with deviation risk concentrated in litigation frequency escalation and nuclear verdict trends. Revision becomes warranted when social inflation in general liability lines compresses combined ratios beyond carrier capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Global Sports Insurance Market
Insurance
Boiler Insurance Market
Insurance
US Travel Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Microinsurance Market
Insurance
India Health Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Gap Insurance Market
Insurance
Specialty Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
France Car Insurance Market