
 Property Insurance Market | 2026-2036
Property Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Property Insurance Market Intelligence
A long-standing focus on individual homeowners is unwinding as large corporations with complex global property portfolios command greater underwriting attention. This shift reflects the concentration of asset value in commercial real estate and industrial infrastructure. Chubb specializes in high-value commercial and personal property, targeting complex risks for corporations and high-net-worth individuals. In contrast, State Farm sustains its market position through an extensive agent network focused on homeowners and small businesses. Berkshire Hathaway leverages its significant capital base to underwrite catastrophic risk policies that smaller insurers cannot cover.
Property insurance provides financial protection against physical loss or damage to real or personal property from specified hazards. Policies are defined by their scope, such as 'named perils' coverage which lists specific covered events, or 'all-risk' coverage which includes all losses except those explicitly excluded. Its primary purpose is to transfer risk from a property owner to an insurer. Commercial Property Insurance is expanding faster than the mature homeowners insurance segment, driven by industrial development. While direct sales and agents remain dominant, online platforms are reshaping distribution, particularly for renters and small business policies.
Regulatory frameworks fundamentally shape market access and product design. In the United States, FEMA's administration of the National Flood Insurance Program influences flood risk pricing, while the EU’s Solvency II directive mandates specific capital adequacy ratios for insurers. In Japan, regulations from the Financial Services Agency govern insurer solvency and consumer protection standards. Insurers must now decide how to integrate advanced climate risk modeling into their core underwriting and pricing strategies to maintain solvency and profitability.
Market Dynamics
The integration of advanced climate risk modeling into core underwriting is the central force reshaping the property insurance market, compelling a fundamental re-evaluation of risk pricing, capital allocation, and geographic exposure for insurers globally.
Growth Catalysts
- Commercial Real Estate Expansion:The construction of large-scale logistics facilities and data centers, driven by e-commerce and cloud computing, creates substantial demand for high-value commercial property insurance policies.
- AI-Powered Risk Assessment:The adoption of AI-driven analysis of satellite imagery and other geospatial data allows for more accurate, real-time risk assessment, improving underwriting precision and enabling new product development.
- Climate-Related Demand:Heightened frequency of climate-related perils is concentrating demand for specialized and higher-limit coverage in high-value coastal real estate markets, particularly in the United States and Australia.
Market Restraints
- Regulatory Capital Requirements:The EU’s Solvency II directive imposes stringent capital adequacy ratios, which can limit an insurer's capacity to underwrite new, large-scale risks without securing additional capital or reinsurance.
- Rising Reinsurance Costs:An increase in the frequency and severity of global catastrophic events, from wildfires to floods, is driving up the cost of reinsurance, which insurers pass on through higher premiums.
- Legacy System Inertia:Entrenched legacy IT infrastructure at many large insurers slows the adoption of new technologies like AI-driven analytics and digital-first distribution channels, creating a competitive disadvantage.
Strategic Opportunities
- Parametric Insurance Products:Developing parametric policies that pay out based on a pre-defined trigger, such as a specific hurricane wind speed or earthquake magnitude, offers a new, transparent product line for specific perils.
- Embedded Insurance Channels:Integrating property insurance offers directly into online real estate platforms, property management software, and mortgage origination processes creates a new distribution channel for renters and homeowners policies.
- Industrial Infrastructure in Asia:Expanding specialized coverage for new industrial and manufacturing infrastructure being built across developing economies in Southeast Asia represents a significant geographic growth frontier.
Industry Challenges
- Data Science Talent Scarcity:A shortage of professionals skilled in both climate science and data analytics makes it difficult for insurers to build and maintain the sophisticated risk modeling teams required for modern underwriting.
- Model Integration Complexity:Integrating new, dynamic climate risk models into existing core underwriting, pricing, and policy administration systems is a major technical and operational hurdle for established insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Property Insurance Market |
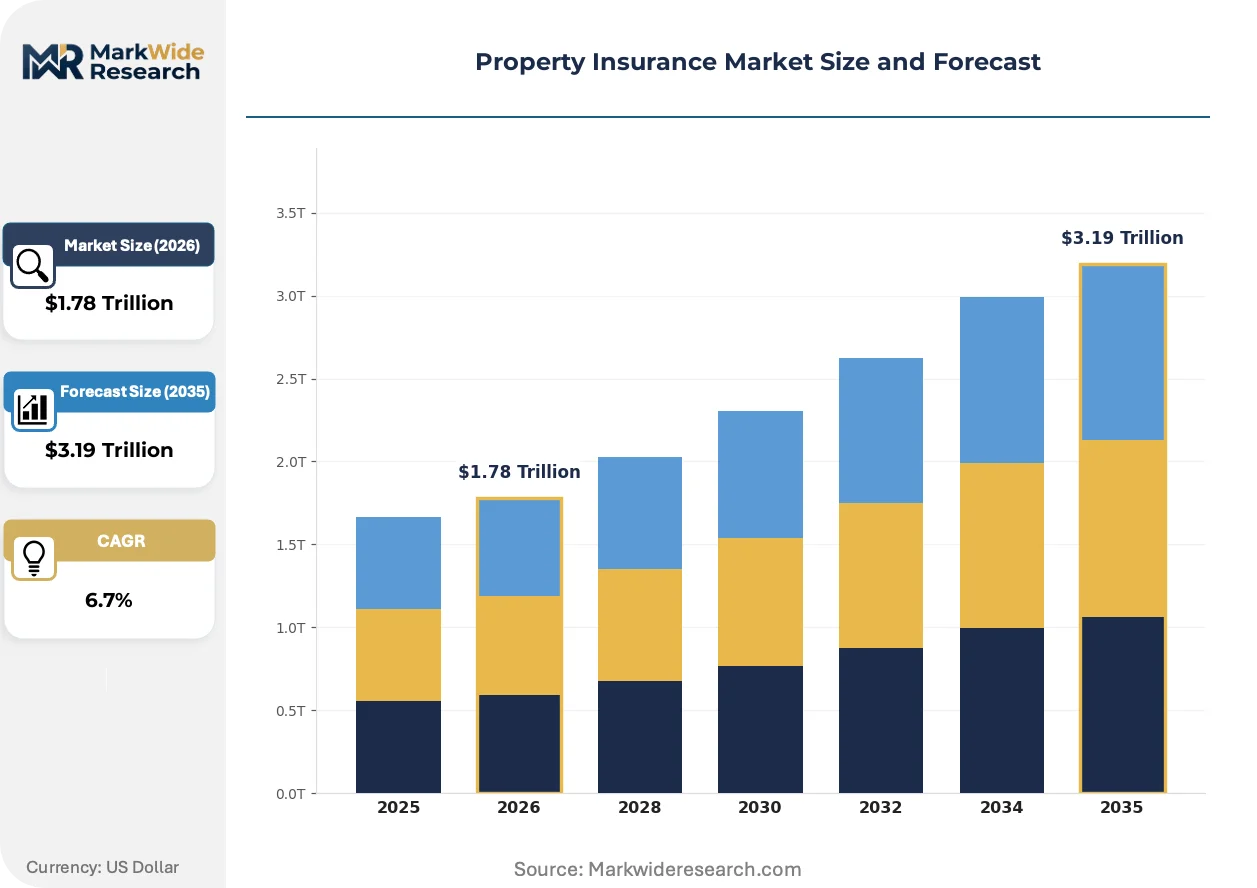
| Market Size in 2026 | $1.78 Trillion |
| Market Size in 2035 | $3.19 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homeowners Insurance, Renters Insurance, Landlord Insurance, Commercial Property Insurance Coverage Type: Liability Coverage, Dwelling Coverage, Personal Property Coverage, Additional Living Expenses Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Customer Type: Individuals, Small Businesses, Corporations, Non-Profits |
| Companies Covered | State Farm, Progressive, Berkshire Hathaway, Allstate, Liberty Mutual, Travelers, USAA, Chubb, Nationwide Mutual Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Property Insurance Market Strategic Shifts & Innovations
Predictive analytics and real-time data are shifting the property insurance industry from a reactive, claims-based model to a proactive, risk-mitigation framework. This evolution is driven by technological advancements, regulatory pressures, and changing customer expectations for tailored, flexible coverage.
AI-powered satellite imagery and IoT sensors provide real-time data on property conditions, local environmental hazards, and weather patterns. Commercial insurers are rapidly adopting this technology to monitor large, high-value property portfolios like industrial parks and data centers. This real-time data stream is displacing traditional, static underwriting assessments that relied on historical claims and infrequent physical inspections.
The EU’s Solvency II directive, alongside similar capital standards enforced by Japan's Financial Services Agency, mandates rigorous risk management and capital adequacy. This forces insurers to hold more capital against potential catastrophe losses, directly impacting their profitability on property lines. Consequently, affected insurers are refining pricing models and sometimes reducing their exposure in high-risk coastal zones to maintain regulatory compliance.
A clear shift toward unbundled, on-demand coverage is emerging, particularly within the small business and renter segments. This model allows customers to purchase specific coverages for defined periods through digital platforms, disrupting the standard annual policy sold via agents. This trend is most visible in North American and European urban markets with high concentrations of renters and small enterprises seeking flexible, customized insurance solutions.
Property Insurance Market Segmentation
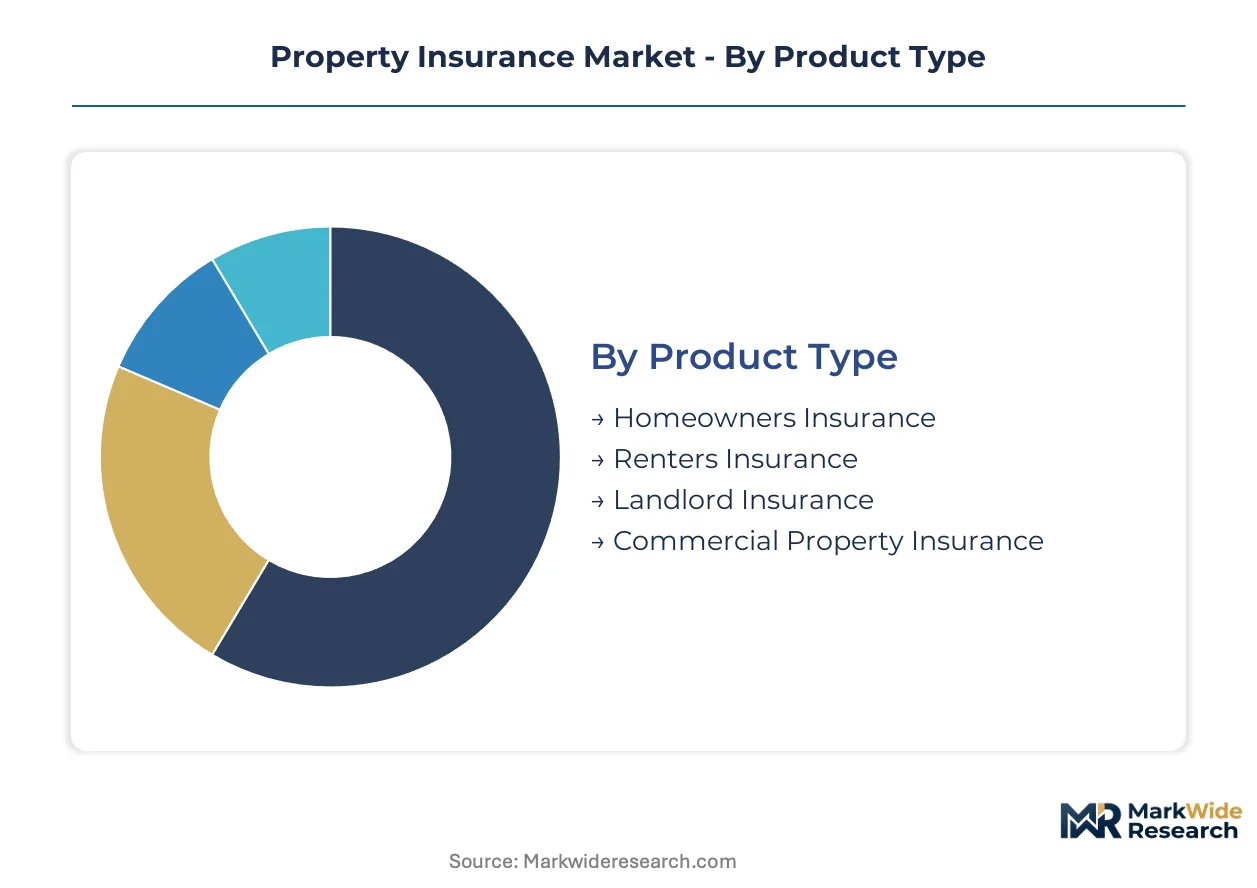
The property insurance market is segmented to effectively address the diverse needs of policyholders and the varied nature of insured assets. These distinctions are crucial for insurers to tailor products, manage risk, and optimize distribution strategies.
Distribution Channel:
The market leverages various distribution channels, each playing a distinct role in connecting insurers with policyholders and facilitating policy sales.
- Agents:These professionals provide personalized advice and policy customization, serving as primary touchpoints for homeowners and small businesses. Their local networks remain crucial for client acquisition.
- Online Platforms:Digital portals and mobile applications offer self-service policy purchasing and management, streamlining access for tech-savvy consumers. This channel demonstrates rapid expansion for less complex policies.
- Direct Sales:Insurers sell policies directly to consumers via company websites or call centers. This approach allows greater control over customer experience and can reduce acquisition costs.
- Brokers:Brokers represent the client, sourcing specialized coverage from multiple insurers for complex risks, particularly for large corporations and high-value commercial properties.
By volume, Agents lead. By growth pace, Online Platforms are expanding most quickly.
Product Type:
Property insurance products categorize by the specific type of property and associated risks they are designed to cover, addressing unique ownership structures.
- Commercial Property Insurance:This segment protects businesses against damage to physical assets like buildings, inventory, and equipment from various perils. Demand concentrates in industrial infrastructure and large-scale data centers, driven by e-commerce.
- Homeowners Insurance:This comprehensive policy covers residential dwellings and personal belongings against a broad range of perils, including liability. The segment serves a vast individual customer base, though its growth is mature.
- Renters Insurance:This policy protects a tenant's personal belongings within a rented property and provides liability coverage, excluding the building structure itself.
- Landlord Insurance:This specialized coverage protects property owners renting out residential properties, covering the dwelling, liability, and often loss of rental income.
Product type directly reflects the asset class protected, with commercial policies often requiring complex underwriting.
Coverage Type:
Property insurance policies offer distinct coverage types, each addressing specific financial exposures from property ownership or tenancy.
- Dwelling Coverage:This foundational component protects the physical structure of the insured property, including the main building and attached structures, against specified perils. It forms the core of homeowners and landlord policies.
- Liability Coverage:This protection covers legal costs and damages if the policyholder is found responsible for injuries or property damage to third parties. It is a critical component across all property insurance types.
- Personal Property Coverage:This insurance protects the policyholder's movable possessions, such as furniture, electronics, and clothing, whether inside or outside the insured dwelling.
- Additional Living Expenses:This coverage reimburses policyholders for increased living costs, such as hotel stays, if their home becomes uninhabitable due to a covered loss.
Each coverage type mitigates a unique aspect of property-related risk, allowing for tailored protection.
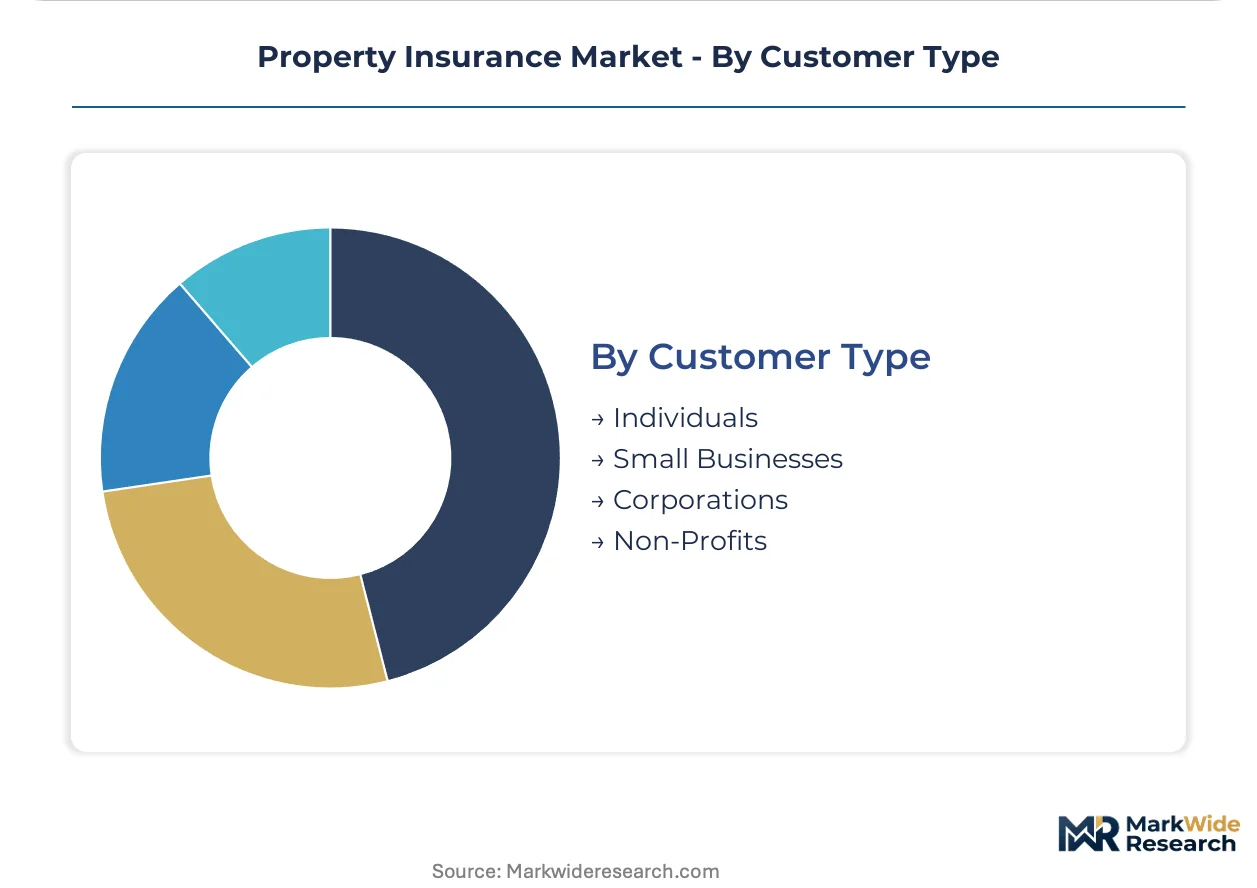
Customer Type:
The market differentiates offerings based on the scale and complexity of the policyholder's assets and their specific risk profile.
- Corporations:These large entities possess extensive, often geographically dispersed property portfolios, including industrial facilities and data centers. Their complex global portfolios command significant underwriting attention.
- Individuals:This segment includes homeowners, renters, and landlords seeking protection for personal residences and belongings. This customer base represents a vast market volume, often served via agent networks.
- Small Businesses:These enterprises require protection for commercial premises, inventory, and equipment, often seeking bundled policies combining property and liability coverage.
- Non-Profits:Organizations operating without a profit motive also require property insurance to protect their facilities and assets, tailored to their specific operational risks.
Customer type defines both insurer risk appetite and the scope of coverage required for asset protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global property insurance market, underpinned by extensive logistics and data center infrastructure, shows differentiated growth across key geographies. These regions are experiencing varied demand for commercial and specialized property coverage, driven by economic development, climate risks, and regulatory environments.
United States
Demand for high-value property insurance in the United States concentrates in coastal real estate markets and rapidly expanding data center hubs. FEMA's administration of the National Flood Insurance Program significantly influences flood risk pricing and availability. Major metropolitan areas like Miami and Houston are seeing increased demand for specialized climate-related coverage.
Australia
Australia's property insurance market experiences heightened demand for specialized coverage in high-value coastal regions due to increasing climate-related perils. The Australian Prudential Regulation Authority (APRA) mandates robust risk management practices for insurers, impacting capital allocation. Sydney and Melbourne metropolitan areas drive demand for both commercial and residential property protection.
Japan
Japan's market for property insurance is shaped by demand for earthquake and typhoon coverage, particularly for industrial infrastructure and urban centers. Regulations from the Financial Services Agency govern insurer solvency and consumer protection standards. The Tokyo metropolitan area, a major economic hub, requires extensive commercial property coverage.
Germany
Germany sees stable demand for commercial property insurance, especially for its advanced manufacturing and logistics facilities. The EU’s Solvency II directive mandates specific capital adequacy ratios, influencing product design and pricing. Industrial clusters in Bavaria and North Rhine-Westphalia generate significant underwriting attention for complex industrial risks.
China
China's property insurance market is expanding rapidly, driven by the construction of large-scale logistics facilities and data centers. The China Banking and Insurance Regulatory Commission (CBIRC) oversees market conduct and solvency requirements for insurers. The Yangtze River Delta region, a key manufacturing and e-commerce hub, requires substantial commercial property protection.
Property Insurance Market Key Industry Players
Listed leaders compete with private specialists across risk appetite and distribution reach within the property insurance market. The market exhibits a tiered structure, with global conglomerates handling complex corporate risks and regional players focusing on individual homeowners and small businesses. Strategic archetypes include diversified insurers, specialized risk underwriters, and digitally-native platforms. Dominant competitive moves involve portfolio diversification into higher-value commercial segments and strategic partnerships to integrate new technologies.
Within the specialized risk segment, Chubb exemplifies a focus on high-net-worth individuals and complex corporate property portfolios, leveraging deep underwriting expertise. State Farm anchors the individual homeowners and small business segment through its extensive agent network, maintaining broad market presence. Berkshire Hathaway occupies a unique position by leveraging its significant capital base to underwrite catastrophic risk policies that smaller insurers cannot cover, representing a powerful capacity provider.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| Berkshire Hathaway |
| Allstate |
| Liberty Mutual |
| Travelers |
| USAA |
| Chubb |
| Nationwide Mutual Insurance |
| Others |
Cost & Logistics Intelligence
Large-scale commercial property development drives significant economies of scale in underwriting, which in turn concentrates specialized risk capacity among a few global insurers, influencing price floors for complex policies.
Pricing Analysis
Volume-based pricing structures dominate the commercial property insurance market, offering discounts for large, multi-asset portfolios. Price differentiation stems from the complexity of the risk profile and the geographic peril exposure of insured assets. Pricing pressure stems from rising reinsurance costs, which insurers pass on through higher premiums for catastrophe-exposed properties. Individuals and small businesses exhibit the most price sensitivity, while large corporations prioritize comprehensive coverage for high-value industrial infrastructure.
Supply Chain Analysis
The United States anchors advanced data center and logistics facility construction, driving demand for specialized property insurance. Supply chain concentration also resides in Germany for manufacturing facilities and China for large-scale logistics hubs. The industry relies on significant capital for underwriting capacity and reinsurance markets for risk transfer. Catastrophic event frequency creates single-source vulnerability within specialized reinsurance capacity. Distribution runs through brokers for complex commercial risks and agents or online platforms for individual policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The property insurance market operates as a substitution defense against self-insurance models, which large corporations increasingly consider for their extensive property portfolios.
For Market Incumbents: Consolidate specialized underwriting expertise for complex commercial risks, particularly in climate-exposed coastal zones. Invest heavily in AI-powered risk assessment technologies to improve pricing precision and reduce claims volatility. This defends against emerging insurtech platforms offering more dynamic, data-driven solutions. Capital investment in advanced climate modeling acts as a critical lever.
For New Entrants and Emerging Players: Digital platform certification as a preferred distribution channel offers a fast-track for new entrants to penetrate the renters and small business segments. Target under-served small businesses and tech-savvy renters in urban markets with flexible, unbundled coverage. Embedded insurance offers within online real estate platforms provide a compelling go-to-market angle for rapid customer acquisition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among insurers specializing in commercial property, given the long-term contracts and high asset values involved. Long-term viability ties directly to industrial development and effective climate risk management. Target insurtech firms with advanced data analytics capabilities or niche commercial insurers with strong climate modeling expertise. Adoption rate of parametric insurance products serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Underwriting | Improves risk assessment precision for large commercial portfolios and reduces claims volatility. |
| Expand Parametric Product Lines | Offers transparent, trigger-based coverage for climate perils, attracting new corporate clients. |
| Acquire Niche Climate Modeling Firms | Integrates advanced climate science into core underwriting processes and pricing strategies. |
| Develop Embedded Insurance Partnerships | Captures renters and small business policies through seamless integration with digital platforms. |
| Target Southeast Asian Industrial Infrastructure | Capitalizes on new industrial development in rapidly expanding economies for commercial coverage. |
Research Approach
The analysis maps commercial property insurance, homeowners insurance, and renters insurance sub-sectors, each validated through extensive interviews with underwriting executives and risk managers. Primary data from insurance brokers, claims adjusters, and regulatory compliance officers informs market dynamics. Secondary data from regulatory filings (FEMA, APRA, FSA Japan), industry association reports, and financial statements of public insurers provides further validation. Bottom-up market sizing from asset values and top-down validation against insurer revenue reports ensures comprehensive triangulation.
Market growth outputs were cross-referenced against global economic indicators and regional construction spending to ensure consistency across the analysis window. The analytical framework models market segmentation across product type, distribution channel, customer type, and geographic region. Compound annual growth rates derive from historical growth patterns and projected demand drivers, including new commercial construction starts and climate-related peril frequency.
The analysis sits within stated boundaries; outcomes outside significant shifts in global climate patterns or regulatory frameworks would require recalibration. Forecasts reflect current geopolitical stability and technological adoption rates, acknowledging unforeseen catastrophic events or sudden changes in capital adequacy requirements as key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Spain Parametric Insurance Market
Insurance
China Online Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Entertainment Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Critical Illness Insurance Market
Insurance
France Car Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Global SME Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
United States Bancassurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market