
 Asia-Pacific Extended Warranty Market | 2026-2036
Asia-Pacific Extended Warranty Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Extended Warranty Market Insights
China's warranty service infrastructure is reconfiguring as domestic insurers build actuarial capabilities for complex electronics coverage. Allianz Partners leverages its automotive OEM relationships to sustain premium positioning across Southeast Asian markets. Assurant Inc. anchors its regional footprint through direct retailer integrations in Japan and South Korea. AmTrust Financial Services competes by specializing in small-business equipment protection across Australian commercial hubs.
An extended warranty constitutes a service contract that transfers repair or replacement liability beyond the manufacturer's original guarantee period, typically covering mechanical breakdown, accidental damage, or total loss events through actuarially priced premiums. These contracts reduce consumer exposure to post-warranty repair costs while generating recurring revenue streams for underwriters and distributors. Electronics protection dominates premium volume due to high replacement costs for smartphones and laptops, while automotive mechanical breakdown coverage captures the fastest expansion as electric vehicle complexity reshapes repair economics. Retailer-mediated distribution through point-of-sale attachments occupies the deepest margin pool, though online direct-to-consumer channels are gaining traction among digitally native customer segments.
Japan's METI enforces strict disclosure standards for warranty contract terms, while Australia's ACCC monitors unfair contract terms in consumer protection plans, and India's BIS mandates quality benchmarks that manufacturers address through bundled extended coverage. These frameworks elevate compliance costs but also legitimize warranty products as regulated financial instruments rather than discretionary add-ons. Stakeholders must monitor how ASEAN harmonization of consumer finance rules affects cross-border warranty underwriting permissions.
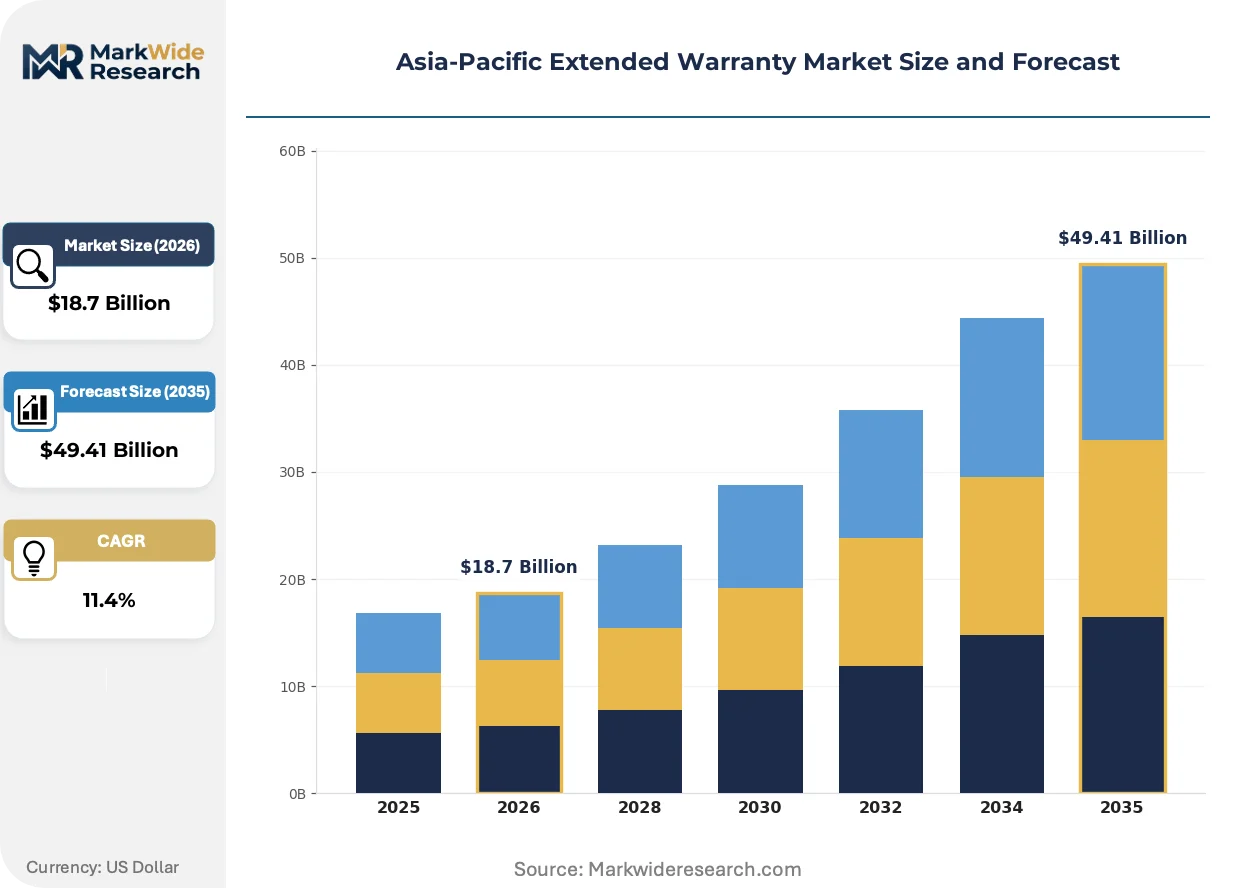
Market Dynamics
Electric vehicle complexity across Southeast Asian commercial fleets is forcing warranty underwriters to rebuild actuarial models around battery degradation curves and software-dependent repair protocols. This shift is compressing traditional mechanical coverage margins while opening premium pricing tiers for telematics-integrated protection plans.
Growth Catalysts
- India's BIS certification mandates:Electronics manufacturers bundle extended coverage at point of sale to meet quality benchmark liabilities, converting compliance cost into recurring premium revenue streams.
- Smart home appliance penetration:China's tier-one cities drive attach rate premiums as connected device complexity elevates consumer willingness to pay for post-warranty protection.
- Automotive durability standards:Southeast Asian fleet operators expand mechanical breakdown coverage for commercial vehicles as regional emissions protocols tighten engine maintenance requirements.
Market Restraints
- Actuarial data scarcity:Insufficient historical failure rates for emerging EV battery chemistries inflate premium reserves and compress underwriting margins across nascent electric vehicle portfolios.
- Repair network concentration:Authorized service capacity clusters in Shanghai, Tokyo, and Sydney, leaving secondary cities with claims fulfillment delays and elevated loss adjustment expenses.
- Cross-border regulatory friction:ASEAN's unharmonized consumer finance permissions prevent standardized warranty underwriting across member states, fragmenting operational scale.
Strategic Opportunities
- Vietnam's underpenetrated retail electronics channel:Point-of-sale warranty attachment rates lag regional benchmarks, creating first-mover advantage for distributor-integrated coverage models.
- Telematics-converged pricing:Real-time vehicle diagnostics enable usage-based premium adjustments, shifting warranty economics from pooled risk to individualized actuarial precision.
- Japan's METI disclosure standardization:Regulatory clarity on contract terms legitimizes extended warranties as regulated financial instruments, accelerating institutional capital deployment.
Industry Challenges
- Embedded systems engineering talent scarcity:Warranty providers lack sufficient firmware diagnosticians to validate claims on software-dependent automotive and appliance failures, extending resolution timelines.
- Legacy claims platform integration:Established underwriters struggle to retrofit telematics data feeds into decades-old policy administration systems, delaying real-time coverage activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Extended Warranty Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Automotive, Home Appliances, Furniture Service Type: Accidental Damage, Mechanical Breakdown, Extended Service, Total Loss Customer Type: Individual Consumers, Small Businesses, Corporations, Retailers Distribution Channel: Online, Retail Outlets, Direct Sales, Telemarketing |
| Companies Covered | American International Group Inc., Allianz Partners, Asurion, Carchex, Endurance Warranty Services, Assurant Inc., AmTrust Financial Services, Edel Assurance, SquareTrade, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Extended Warranty Market Trends and Innovations
Connected device ecosystems across the Asia-Pacific are compressing traditional warranty distribution models while elevating data-driven risk assessment capabilities. This transformation is redrawing competitive boundaries between insurers, OEMs, and retail intermediaries.
Blockchain-enabled smart contracts are digitizing claims settlement workflows for high-frequency electronics protection. Australian retailers pilot automated payout triggers based on verified diagnostic codes, eliminating manual adjuster review for standard mechanical failures. This infrastructure is digitizing the economics of low-value warranty contracts that previously suffered from administrative cost overruns.
Australia's ACCC enforcement against unfair contract terms in consumer protection plans is elevating disclosure requirements across the region. The regulator's 2023 guidance on transparent claims processes is forcing warranty providers to standardize exclusion language, reducing litigation reserves but compressing pricing flexibility. Electronics retailers in Melbourne and Sydney face the steepest compliance recalibration as they rebundle coverage offerings.
Direct-to-consumer subscription models are displacing retailer-mediated point-of-sale attachments among digitally native buyer segments in South Korea. Younger consumers research warranty terms through comparison platforms before purchase, bypassing traditional distributor commissions. This behavioral shift concentrates in Seoul's electronics retail corridors, where online-first warranty startups capture attach opportunities that incumbent underwriters previously controlled through retail exclusivity agreements.
Asia-Pacific Extended Warranty Market Segmentation
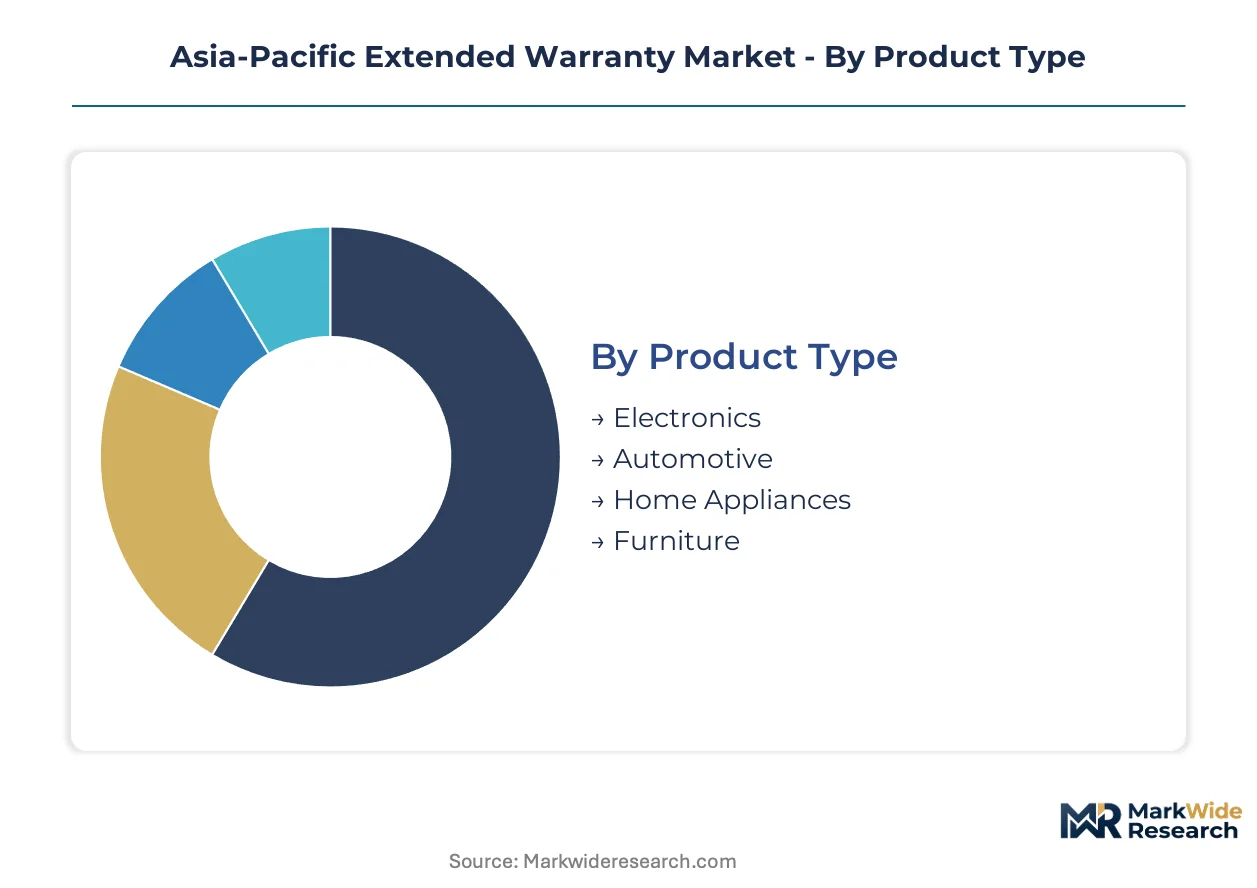
Extended warranty profitability hinges on segment-specific actuarial precision. Product complexity, customer risk profiles, and distribution economics create divergent margin structures across coverage categories.
Product Type:
After-sales-service intensity varies sharply by product durability and repair cost profiles, reshaping underwriting resource allocation.
- Electronics:Smartphone and laptop coverage dominates premium volume due to high replacement costs and short innovation cycles. China's tier-one cities concentrate demand as connected device penetration elevates consumer willingness to pay for post-warranty protection.
- Automotive:Mechanical breakdown contracts capture expanding share as electric vehicle complexity reshapes repair economics. Southeast Asian fleet operators drive volume as regional emissions protocols tighten commercial vehicle maintenance requirements.
- Home Appliances:Smart appliance protection gains traction through manufacturer bundling strategies.
- Furniture:Structural and fabric coverage remains niche, concentrated in premium retail channels.
Electronics holds the largest share; momentum sits with automotive as EV adoption accelerates.
Service Type:
Cost tier differentiation separates high-frequency low-severity events from catastrophic loss exposures.
- Mechanical Breakdown:Core coverage for component failure beyond manufacturer defects, priced through historical failure rate modeling. Australia's commercial equipment sector concentrates demand as small businesses seek predictable maintenance budgeting.
- Accidental Damage:Drop, spill, and impact protection commands premium pricing due to moral hazard exposure. South Korean smartphone users drive attach rates through retailer point-of-sale integration.
- Extended Service:Maintenance and inspection contracts supplement repair coverage.
- Total Loss:Replacement guarantees for irreparable goods, typically capped at depreciated value.
Mechanical breakdown anchors revenue; accidental damage climbs fastest as portable electronics proliferation continues.
Customer Type:
Volume concentration and margin profiles diverge across purchaser sophistication levels.
- Individual Consumers:Retail-mediated purchases dominate, with attachment rates varying by product category and sales channel training. Japan's METI disclosure standards elevate contract comprehension, reducing post-purchase cancellation rates.
- Corporations:Enterprise fleet and equipment coverage demands customized policy structures and dedicated account management. India's manufacturing sector concentrates demand as BIS certification requirements push bundled protection plans.
- Small Businesses:Commercial equipment protection competes on total cost of ownership metrics.
- Retailers:Self-insured warranty programs and third-party administrator relationships.
Individual consumers generate highest volume; corporations deliver steadiest renewal economics.
Distribution Channel:
Geography of customer acquisition determines commission structures and lifetime value capture.
- Retail Outlets:Point-of-sale attachment remains the deepest margin pool, with trained associates converting purchase intent into coverage acceptance. Vietnam's electronics retail corridor presents underpenetrated expansion opportunity.
- Online:Direct-to-consumer platforms displace traditional intermediaries among digitally native segments. Seoul's comparison-platform users research terms independently, bypassing distributor commissions.
- Direct Sales:Manufacturer and insurer owned channels for renewal and upsell campaigns.
- Telemarketing:Regulatory-constrained outbound channels for policy renewals and cross-sells.
Retail outlets command greatest share; online channels gain fastest as digital purchase behavior matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR and India's BIS anchor the regulatory framework across the Asia-Pacific extended warranty landscape, with national quality mandates reshaping how manufacturers bundle protection coverage at point of sale.
China
Smart home appliance penetration in Shanghai, Beijing, and Shenzhen drives premium warranty attach rates as connected device complexity elevates consumer willingness to pay for post-warranty protection. SAMR's consumer protection enforcement tightens disclosure standards for service contract terms. The Yangtze River Delta concentrates authorized service capacity, though secondary cities face claims fulfillment delays that inflate loss adjustment expenses.
India
BIS certification requirements for electronic goods push manufacturers to bundle extended protection plans at retail checkout, converting compliance cost into recurring premium revenue streams. The PLI scheme for electronics manufacturing deepens domestic production of smartphones and laptops that carry high-replacement-cost coverage. Maharashtra and Karnataka host the densest warranty distribution networks through organized retail corridors in Mumbai and Bangalore.
Japan
METI enforces strict disclosure standards for warranty contract terms, reducing post-purchase cancellation rates through elevated contract comprehension. Aging appliance stock in Tokyo and Osaka sustains demand for mechanical breakdown coverage beyond manufacturer guarantee periods. The Kanto region anchors actuarial capability development as domestic insurers build complex electronics coverage expertise.
South Korea
Direct-to-consumer subscription models displace retailer-mediated point-of-sale attachments among digitally native buyer segments in Seoul. Younger consumers research warranty terms through comparison platforms before purchase, bypassing traditional distributor commissions. The Seoul Capital Area concentrates online-first warranty startups that capture attach opportunities previously controlled through retail exclusivity agreements.
Australia
The ACCC monitors unfair contract terms in consumer protection plans, elevating disclosure requirements that force warranty providers to standardize exclusion language. Small-business equipment protection competes on total cost of ownership metrics across Sydney and Melbourne commercial hubs. AmTrust Financial Services specializes in this segment, building regional footprint through dedicated account management for enterprise fleet coverage.
Asia-Pacific Extended Warranty Market Competitive Landscape
Global insurers and regional specialists split the market along distribution-channel lines, with automotive OEM relationships and retail direct integrations forming the primary competitive vectors. The vendor base concentrates around three strategic archetypes: multinational underwriters leveraging balance-sheet scale, automotive-aligned service providers capturing fleet volume, and technology-integrated distributors embedding coverage at digital point of sale. Consolidation pressure runs through M&A activity targeting telematics capabilities and strategic partnerships with electronics retailers seeking turnkey warranty administration.
Within the multinational tier, Allianz Partners and Assurant Inc. anchor premium positioning across divergent geographies. Allianz Partners sustains automotive OEM relationships throughout Southeast Asian markets, while Assurant Inc. builds regional footprint through direct retailer integrations in Japan and South Korea. American International Group Inc. occupies the scale-driven end with balance-sheet capacity for complex commercial equipment portfolios. These three exemplify how global underwriters compete against regional specialists like AmTrust Financial Services, which targets small-business equipment protection through narrow vertical focus rather than broad geographic coverage.
| Leading Market Players |
|---|
| American International Group Inc. |
| Allianz Partners |
| Asurion |
| Carchex |
| Endurance Warranty Services |
| Assurant Inc. |
| AmTrust Financial Services |
| Edel Assurance |
| SquareTrade |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure through India's BIS certification mandates determines both premium tier spreads for electronics protection and the geographic clustering of authorized service networks. Warranty providers absorb compliance costs into point-of-sale bundling economics while concentrating repair capacity in certified metropolitan hubs.
Pricing Analysis
Shanghai and Sydney command 40-60% premiums over Bangkok and Jakarta for equivalent smartphone coverage due to authorized service density and labor cost differentials. Three-tier pricing structure across premium, standard, and economy levels segments buyers by claim response speed and deductible tolerance. Cost compression in economy tiers intensifies because telematics-enabled competitors bypass traditional retail commissions. Small-business equipment purchasers in Australian commercial hubs exhibit lowest price sensitivity due to total cost of ownership framing, while individual consumers in Vietnam's electronics corridors drive hardest bargain on attachment rates.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian assembly hubs dominates warranty underwriting cost structures as electronics manufacturing shifts to Vietnam and Indonesia. Component sourcing draws from South Korean battery suppliers, Taiwanese semiconductor fabricators, and Japanese precision parts manufacturers. Single-source vulnerability concentrates in telematics firmware providers serving connected vehicle protection plans. Distribution runs through retailer-mediated point-of-sale attachments in organized electronics corridors, with direct-to-consumer platforms gaining share in Seoul and Tokyo digital-native segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as connected device ecosystems embed warranty activation into OEM software update cycles, collapsing traditional distribution intermediaries.
For Market Incumbents: Insulate automotive portfolio margins by acquiring telematics diagnostics capabilities before EV battery degradation curves destabilize mechanical breakdown pricing. Deepen vertical integration into authorized service networks across China's Yangtze River Delta to compress loss adjustment expenses. Counter direct-to-consumer entrants through exclusive retailer lockups in Japan's METI-regulated disclosure environment. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated electronics retail corridor where point-of-sale attachment rates trail regional benchmarks by double digits. Target small-business equipment protection in Australian commercial hubs where AmTrust's narrow vertical focus leaves pricing gaps. Launch through comparison-platform partnerships in Seoul's digitally native buyer segments to bypass incumbent retail exclusivity. For Investors and Strategic Acquirers: ASEAN harmonization of consumer finance permissions reshapes the acquisition landscape by enabling cross-border warranty underwriting scale previously fragmented by national licensing. Five-to-ten year viability favors telematics-integrated service providers over legacy mechanical coverage underwriters. Monitor battery chemistry standardization announcements as inflection signal for EV warranty portfolio repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables usage-based premium adjustments for EV fleet coverage through real-time diagnostic feeds. |
| Retailer Direct Integration | Captures point-of-sale attachment economics in Vietnam's expanding electronics retail corridors. |
| Regulatory Compliance Investment | Builds BIS certification bundling capabilities for India's electronics manufacturing PLI beneficiaries. |
| Blockchain Claims Automation | Reduces administrative cost overruns in high-frequency electronics protection through smart contract settlement. |
| Cross-Border Licensing Expansion | Positions for ASEAN consumer finance harmonization enabling standardized regional underwriting. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with warranty underwriting executives, retailer category managers, and automotive fleet procurement officers; and secondary validation through BIS certification databases, SAMR consumer protection filings, and ASEAN regulatory harmonization protocols. Bottom-up triangulation against point-of-sale attachment rate surveys and top-down reconciliation with insurer premium disclosure filings anchored volume estimates.
Forecast inputs span product type segmentation across electronics, automotive, and home appliances; service type tiers from mechanical breakdown to accidental damage; and distribution channel evolution from retail mediation to direct-to-consumer platforms. CAGRs derive from actuarial reserve growth patterns and telematics penetration curves across the analysis window. Battery degradation modeling and smart home appliance replacement cost inflation feed scenario-specific trajectory adjustments.
Sensitivities concentrate around EV battery chemistry standardization timelines and ASEAN regulatory harmonization implementation pace. Forecasts reflect assumptions on telematics adoption rates and retailer commission structures. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cloud Computing in Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Dental Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Canada House Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Property Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Peru Insurance Market
Insurance
Financial Guarantee Market