
 South Africa Property and Casualty Insurance Market | 2026-2036
South Africa Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Property and Casualty Insurance Market Analytics
Market Context
The capital-intensity divergence between legacy balance sheets and digital-first entrants is reorganizing competitive dynamics in South African property and casualty insurance. Santam leverages its extensive reinsurance relationships and agricultural underwriting expertise to sustain dominance in commercial lines. Discovery Insure differentiates through telematics-linked auto products and wellness-integrated risk pricing. Hollard operates across multiple distribution tiers, from direct-to-consumer platforms to broker networks, anchoring volume in the mid-market segment.
Technical Definition and Structural Segments
Property and casualty insurance encompasses risk transfer contracts that indemnify policyholders against physical asset damage, legal liability, and specified peril events through premium-funded pooled reserves. These contracts incorporate technical parameters including loss ratios, combined ratios, and reinsurance attachment points to ensure solvency and claims-paying capacity across stochastic risk events. Auto insurance leads premium generation within the product type dimension, while commercial property insurance captures expanding margin pools as Johannesburg and Cape Town commercial real estate valuations drive higher insured values. The distribution channel structure shows online platforms growing fastest among individual and small business client types, though brokers retain control over corporate placements and complex liability coverage.
Regulatory Framework and Outlook
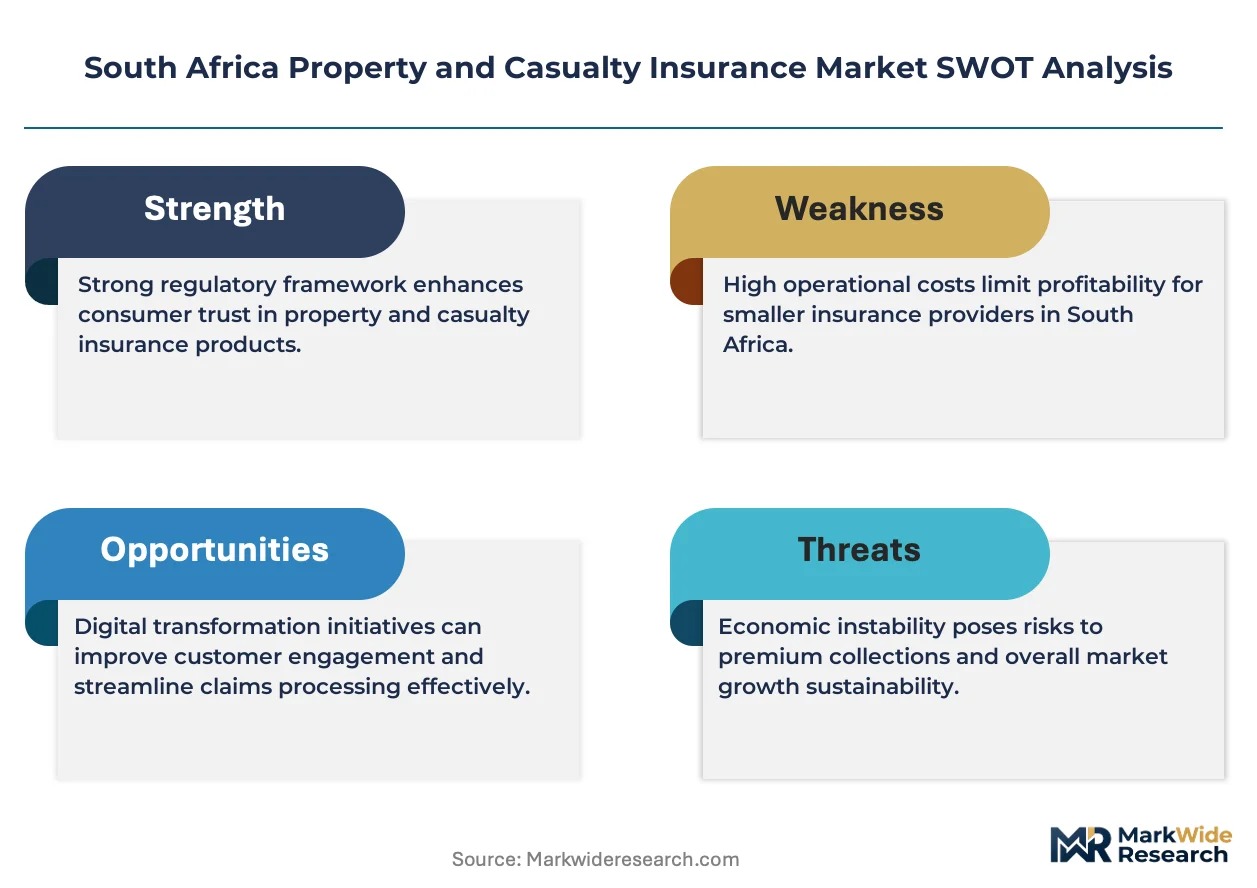
The Prudential Authority and Financial Sector Conduct Authority govern market conduct, capital adequacy, and policyholder protection standards, with the Insurance Act and Treating Customers Fairly framework shaping product design and disclosure obligations. South African Reserve Bank solvency requirements and the conduct regulator's enforcement of fair outcomes are tightening distribution practices and accelerating digital compliance infrastructure investment. Stakeholders must monitor the interplay between climate risk disclosure mandates and premium adequacy as natural peril exposure intensifies across the country's coastal and inland risk zones.
Market Dynamics
The Financial Sector Conduct Authority's Treating Customers Fairly framework is compressing distribution margins and forcing insurers to rebuild digital infrastructure for real-time conduct monitoring and automated disclosure compliance.
Growth Catalysts
- Telematics penetration:Connected vehicle data streams enable dynamic risk pricing for auto policies. Fleet operators in Gauteng province mandate comprehensive coverage expansion.
- Commercial property valuation surge:Rising insured values in Johannesburg and Cape Town commercial real estate drive premium pool expansion. Small businesses seek compliance-aligned coverage packages.
- Climate risk disclosure mandates:Coastal and inland peril exposure intensification requires enhanced natural catastrophe reserves. Reinsurance attachment points adjust upward.
Market Restraints
- Reinsurance cost volatility:Global catastrophe bond spreads and retrocession pricing pressure South African cession strategies. Capital-intensive balance sheets face margin compression.
- Legacy system technical debt:Mainframe-dependent policy administration platforms constrain real-time data integration. Digital-first entrants exploit this latency gap.
- Broker channel concentration:Corporate placements and complex liability coverage remain locked in intermediated distribution. Direct platforms struggle to dislodge established relationships.
Strategic Opportunities
- Underpenetrated agricultural lines:Crop and livestock coverage gaps persist in Free State and KwaZulu-Natal farming belts. Index-based parametric products address basis risk.
- Embedded insurance partnerships:Retail banking and automotive OEM distribution integrations create policy origination at point of sale. Telematics APIs enable seamless underwriting.
- Wellness-integrated risk pricing:Behavioral data from health ecosystems informs life-nonlife convergence products. Policyholder engagement platforms reduce lapse rates.
Industry Challenges
- Actuarial talent scarcity:Stochastic modeling expertise for climate risk and cyber peril pricing remains concentrated among established players. University pipeline output lags demand.
- Legacy-to-cloud migration complexity:Policy administration system modernization requires multi-year capital commitments without immediate revenue uplift. Parallel run environments drain resources.
- Conduct compliance automation:Real-time fair outcomes monitoring demands natural language processing of customer interactions. Regulatory technology vendors struggle with Afrikaans and isiZulu linguistic nuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Property and Casualty Insurance Market |
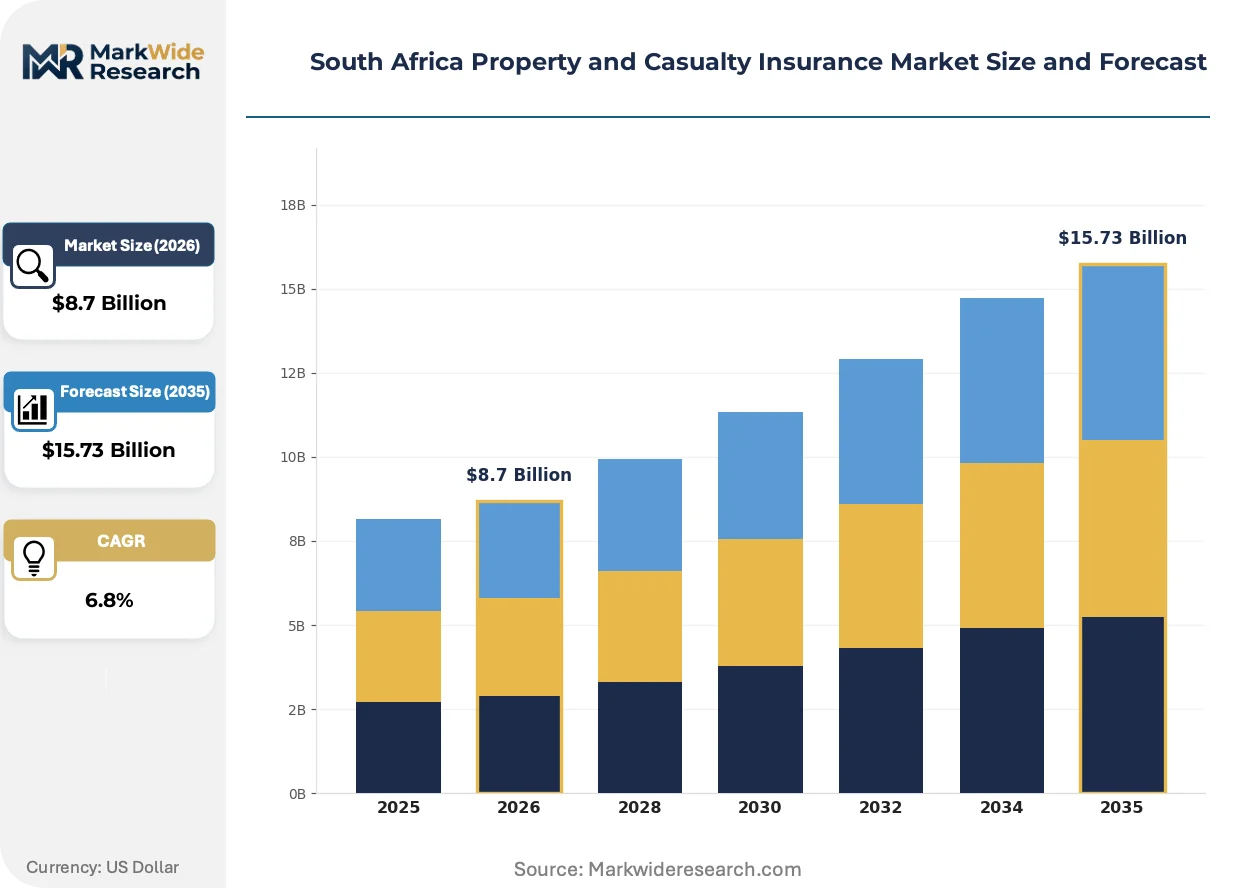
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
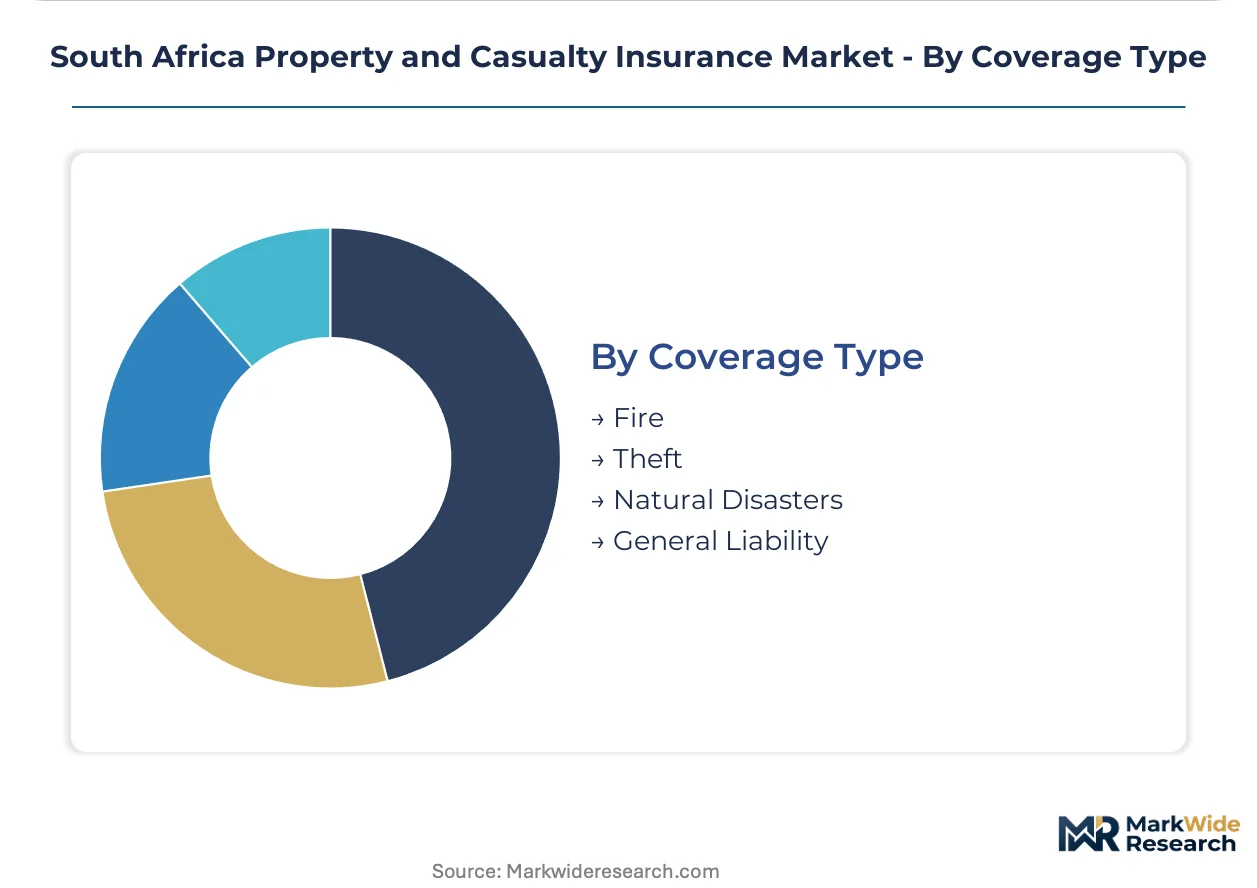
| Segmentation | Product Type: Homeowners Insurance, Commercial Property Insurance, Auto Insurance, Liability Insurance Client Type: Individuals, Small Business, Corporations, Non-Profits Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Coverage Type: Fire, Theft, Natural Disasters, General Liability |
| Companies Covered | OUTsurance, Bryte Insurance, Santam, Discovery Insure, Guardrisk, Hollard, Momentum Insure, Allianz Commercial SA, Old Mutual Insure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Property and Casualty Insurance Market Evolving Landscape
Digital distribution infrastructure and data-driven underwriting models are compressing traditional intermediation layers while forcing incumbents to reconfigure capital deployment toward technology stacks.
Telematics-enabled usage-based insurance is supplanting traditional annual premium models in South African auto coverage. Fleet operators and high-mileage individual policyholders in Gauteng adopt pay-as-you-drive structures at accelerating velocity. This shift compresses risk pool cross-subsidization and rewards granular driving behavior data over demographic proxies.
The Prudential Authority's solvency assessment and management framework tightens capital adequacy requirements for catastrophe exposure. Insurers must hold additional reserves against modeled natural peril losses in coastal provinces. Commercial property underwriters in Durban and Cape Town metropolitan markets respond by elevating reinsurance attachment points and narrowing coverage terms.
Small business buyers increasingly unbundle broker-mediated placement in favor of direct digital platforms for standard commercial packages. This channel migration concentrates among professional services firms and light manufacturing operations in Pretoria and Port Elizabeth. Mid-market segment carriers capture this flow through API-enabled quote-to-bind workflows that compress placement cycles from weeks to hours.
South Africa Property and Casualty Insurance Market Segmentation
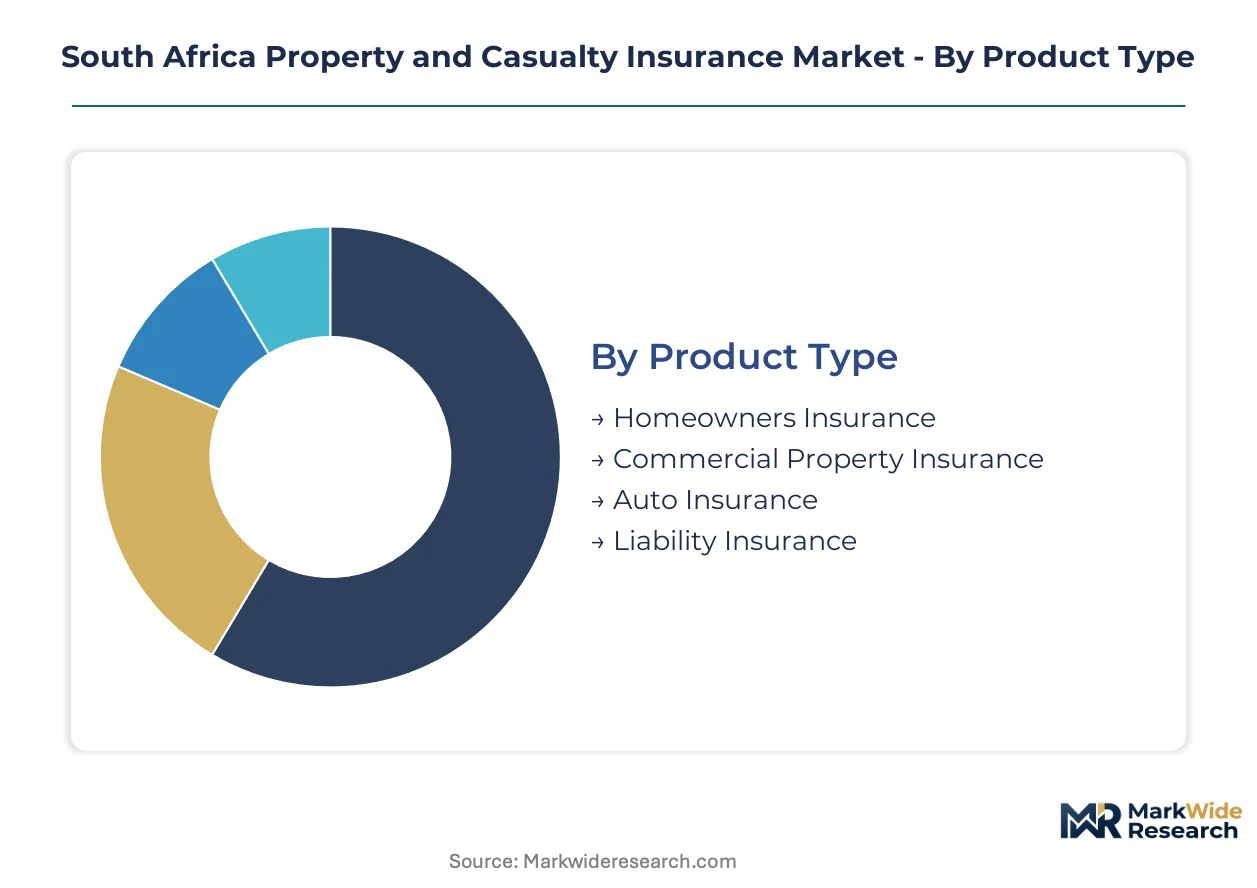
Segmentation in South African property and casualty insurance determines capital allocation, reinsurance structuring, and regulatory compliance pathways. Each dimension shapes how carriers price risk, distribute products, and meet Prudential Authority solvency requirements across divergent client needs.
Product Type:
Channel-mix patterns vary sharply across product lines, with auto and homeowners policies flowing increasingly through direct digital platforms while commercial property and liability coverage remains broker-dependent.
- Auto Insurance:Telematics-enabled policies use real-time driving data to adjust premiums dynamically. Gauteng fleet operators and high-mileage individual policyholders in Johannesburg drive adoption of usage-based structures that reward behavioral data over demographic proxies.
- Commercial Property Insurance:Rising insured values in Johannesburg and Cape Town commercial real estate elevate premium pools. Small businesses navigating Financial Sector Conduct Authority conduct standards seek compliance-aligned coverage packages through simplified digital placement.
- Homeowners Insurance:Coastal peril exposure in Durban and Cape Town metropolitan markets forces reinsurance attachment point adjustments. Standard fire and theft coverage dominates mass-market distribution through direct channels.
- Liability Insurance:Complex corporate placements require specialized broker intermediation. Professional indemnity and directors-and-officers coverage concentrate among Johannesburg-listed enterprises.
Auto insurance dominates installed base. Commercial property insurance is where expansion concentrates.
Client Type:
Margin profiles diverge across customer tiers, with corporations commanding risk-engineering services and individuals driving volume through standardized product templates.
- Corporations:Large enterprises demand bespoke risk engineering and captive insurance structuring. Johannesburg and Cape Town headquartered multinationals negotiate multi-line programs with dedicated account teams.
- Small Business:Professional services firms and light manufacturing operations in Pretoria and Port Elizabeth migrate to API-enabled quote-to-bind platforms. Placement cycles compress from weeks to hours.
- Individuals:Mass-market auto and homeowners coverage flows through direct digital channels. Telematics-linked wellness programs reduce lapse rates through behavioral engagement.
- Non-Profits:Community organizations and educational institutions require specialized liability and property coverage. Broker networks handle placement complexity for mission-driven entities with constrained risk management resources.
Corporations anchor premium value. Small business is climbing the fastest as digital platforms unlock underpenetrated segments.
Distribution Channel:
Capital deployment intensity varies by channel, with online platforms requiring front-loaded technology investment and broker networks demanding relationship maintenance spend.
- Brokers:Corporate placements and complex liability coverage remain locked in intermediated distribution. Established relationships in Johannesburg financial districts resist disintermediation.
- Online Platforms:Direct-to-consumer auto and homeowners policies scale through mobile-first quote engines. Real-time underwriting APIs enable instant bind for standardized risk profiles.
- Direct Sales:Captive agent forces target affluent individual segments with bundled product offerings. Face-to-face consultation supports high-value commercial property placements.
- Agents:Independent producer networks extend geographic reach into secondary cities and rural municipalities. Commission structures align incentives with persistency targets.
Brokers dominate commercial line revenue. Online platforms are gaining share fastest among individual and small business client types.
Coverage Type:
Reserve adequacy requirements and reinsurance pricing vary by peril category, with natural catastrophe exposure commanding heightened capital charges under Prudential Authority frameworks.
- Natural Disasters:Coastal flood and inland storm exposure intensifies across KwaZulu-Natal and Eastern Cape provinces. Catastrophe bond spreads and retrocession pricing pressure reserve margins.
- Fire:Standard peril coverage underpins commercial property and homeowners policy structures. Sprinkler system credits and construction classification drive rate differentiation.
- Theft:Crime-indexed pricing varies by precinct-level loss experience. Gauteng urban centers and cargo transit corridors face elevated premium loadings.
- General Liability:Slip-and-fall and product liability claims concentrate in retail and manufacturing sectors. Defense cost inflation pressures combined ratios in litigious environments.
Fire coverage dominates policy count. Natural disaster protection is expanding most quickly as climate risk disclosure mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Gauteng province demonstrate the highest price elasticity for standard auto coverage, while corporate risk managers in Johannesburg and Cape Town show inelastic demand for complex commercial property and liability programs.
Gauteng Province
Fleet operators and high-mileage individual policyholders drive telematics-enabled auto insurance adoption. The Financial Sector Conduct Authority's Treating Customers Fairly framework mandates real-time conduct monitoring. Johannesburg anchors premium generation as commercial real estate valuations elevate insured values.
Western Cape
Coastal peril exposure intensifies demand for natural catastrophe coverage in Durban and Cape Town metropolitan markets. The Prudential Authority's solvency assessment framework tightens capital adequacy requirements. Cape Town's commercial property underwriters elevate reinsurance attachment points.
KwaZulu-Natal
Index-based parametric crop and livestock products address coverage gaps in farming belts. Climate risk disclosure mandates require enhanced natural catastrophe reserves. Durban's coastal flood exposure drives catastrophe bond spread adjustments.
Eastern Cape
Small professional services firms and light manufacturing operations migrate to API-enabled quote-to-bind platforms. The Insurance Act shapes product design and disclosure obligations. Port Elizabeth concentrates mid-market digital platform adoption.
Free State
Agricultural underwriting expertise sustains dominance in commercial lines for crop and livestock coverage. South African Reserve Bank solvency requirements enforce policyholder protection standards. Bloemfontein anchors agricultural risk transfer contract origination.
South Africa Property and Casualty Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensive balance sheets competing against digital-first entrants for distribution control. The top tier leverages extensive reinsurance relationships and agricultural underwriting expertise to sustain commercial line dominance. Mid-market specialists exploit API-enabled workflows and telematics-linked products to compress placement cycles. Competitive moves concentrate on embedded insurance partnerships and legacy-to-cloud migration for real-time underwriting.
Within the integrated leader tier, Santam and Discovery Insure exemplify divergent strategic archetypes—one leveraging established reinsurance networks, the other deploying wellness-integrated risk pricing. Hollard occupies a position spanning multiple distribution tiers from direct-to-consumer platforms to broker networks. OUTsurance represents the direct-channel specialist archetype with mobile-first quote engines.
| Leading Market Players |
|---|
| OUTsurance |
| Bryte Insurance |
| Santam |
| Discovery Insure |
| Guardrisk |
| Hollard |
| Momentum Insure |
| Allianz Commercial SA |
| Old Mutual Insure |
| Others |
Value Network & Pricing Analysis
Scale economies in reinsurance placement and catastrophe modeling concentrate pricing power among carriers with multi-decade loss experience databases. This concentration elevates premium floors for commercial property coverage while compressing margins for mid-market auto underwriters lacking comparable data depth.
Pricing Analysis
After-sales revenue from policy renewals and cross-sold coverage tiers drives lifetime value in South African property and casualty insurance. Three-tier pricing structure across premium, standard, and economy levels segments buyers by risk profile sophistication and claims history depth. Price differentiation hinges on telematics data granularity and reinsurance backing quality. Cost compression in standard auto tiers is intensifying because digital-first entrants arbitrage legacy carriers' expense ratios. Small business buyers in Pretoria and Port Elizabeth exhibit highest price elasticity, while Johannesburg-listed corporations show inelastic demand for complex liability programs.
Supply Chain Analysis
Reinsurance capacity lead times stretch to six months for catastrophe-exposed commercial property lines during hard market conditions. Risk capital draws from London, Bermuda, and Singapore underwriting hubs for South African catastrophe bonds and retrocession treaties. Raw material dependencies center on actuarial talent pipelines, climate risk modeling software licenses, and claims adjustment service networks. Single-source vulnerability concentrates in legacy policy administration mainframes from 1990s-era technology vendors. Distribution runs through broker networks for corporate placements and direct platforms for standardized individual coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fleet operators and small businesses as digital platforms fragment traditional broker channel concentration. Gauteng province's telematics-mandating fleet buyers now command volume discounts that reshape premium adequacy calculations.
For Market Incumbents: Fortify reinsurance relationships and agricultural underwriting data moats against digital-first entrants exploiting API-enabled quote-to-bind latency gaps. Prioritize cloud migration of policy administration systems to compress expense ratios. Channel control through embedded insurance partnerships with automotive OEMs and retail banking networks anchors placement volume against direct-platform erosion. For New Entrants and Emerging Players: Prudential Authority solvency certification fast-track enables market entry without multi-year capital buildup. White-space targets include underpenetrated crop and livestock coverage in Free State and KwaZulu-Natal farming belts. Go-to-market angle centers on index-based parametric products that eliminate claims adjustment friction for agricultural buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with advanced cloud-native infrastructure and telematics data assets over legacy mainframe-dependent balance sheets. Long-term viability over the next decade rests on climate risk modeling capability and conduct compliance automation infrastructure. Watch catastrophe bond spread movements as inflection indicator for reinsurance cost trajectory and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Legacy-to-Cloud Migration | Real-time underwriting APIs compress placement cycles from weeks to hours for mid-market segments. |
| Telematics Platform Integration | Connected vehicle data streams enable dynamic risk pricing that rewards behavioral data over demographic proxies. |
| Embedded Insurance Partnership | Retail banking and automotive OEM distribution creates policy origination at point of sale with seamless data flow. |
| Agricultural Parametric Product Launch | Index-based coverage addresses basis risk in Free State and KwaZulu-Natal farming belts without traditional loss adjustment. |
| Conduct Compliance Automation Investment | Natural language processing of customer interactions satisfies Financial Sector Conduct Authority real-time monitoring mandates. |
Research Methodology
Desk research of regulatory filings, reinsurance treaty disclosures, and industry association statistical releases preceded structured interviews with chief underwriting officers, distribution channel heads, and actuarial modeling directors. Primary fieldwork with Johannesburg and Cape Town-based risk managers complemented secondary validation through Prudential Authority solvency reports and Financial Sector Conduct Authority enforcement data. Bottom-up premium pool sizing by product line and client tier triangulated against top-down macroeconomic indicators and insurance penetration benchmarks.
Variance decomposition across product type, client segment, distribution channel, and geographic risk zone shaped the analytical framework over the projection horizon. Modeled dimensions encompassed auto, commercial property, homeowners, and liability coverage tiers crossed with corporate, small business, and individual buyer archetypes. CAGRs derived from loss ratio trends, premium rate change indices, and exposure growth assumptions calibrated to reinsurance market cycle positioning.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and catastrophe frequency assumptions; material deviation in climate peril exposure or solvency requirement tightening would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global Fine Art Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Employee Benefit Broker Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Commercial Insurance Market
Insurance
Embedded Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Boiler Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Africa Microinsurance Market
Insurance
Marine Freight Insurance Market