
 Extremity Tissue Expanders Market | 2026-2036
Extremity Tissue Expanders Market Size, Share, and Industry Trends Forecast 2026-2036
Extremity Tissue Expanders Market Analysis
Post-operative monitoring and expansion-protocol management services is consolidating around device manufacturers, blurring the traditional product-only sale. Mentor Worldwide LLC leverages its established silicone implant manufacturing infrastructure to anchor North American supply. Sientra, Inc. competes through specialized reconstructive surgery portfolios. Polytech Health & Aesthetics GmbH dominates European regulatory certification pathways.
Extremity tissue expanders are silicone-shelled, saline-fillable prosthetic devices designed for gradual subcutaneous inflation to generate supplemental skin and soft tissue for subsequent grafting or flap procedures. Controlled-volume expansion protocols typically span weeks to months, with fill volumes calibrated to patient-specific anatomical constraints and vascular perfusion limits. Silicone expanders lead product-type revenue due to established biocompatibility profiles and surgeon familiarity, while reconstructive surgery applications capture the dominant share of clinical utilization against faster-growing but smaller cosmetic surgery volumes. Ambulatory surgical centers represent the fastest-growing end-user channel as outpatient procedural migration accelerates.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern device commercialization, with both frameworks intensifying clinical evidence requirements for silicone-based permanence claims. The EPA and ECHA jointly scrutinize silicone supply chain chemistry, influencing raw material sourcing decisions among manufacturers. Stakeholders must track evolving regulatory divergence between US and European silicone implant standards when configuring regional product registration strategies.
Market Dynamics
Reconstructive surgery units are consolidating procurement around manufacturers that bundle post-operative monitoring with device supply, compressing the traditional product-only sale model and elevating service-integrated contracts as the default commercial arrangement.
Growth Catalysts
- EU MDR conformity assessments:Intensified clinical evidence requirements for silicone-based permanence claims are filtering out marginal competitors and concentrating volume among certified suppliers with established technical files.
- Outpatient procedural migration:Ambulatory surgical centers are capturing expanding case volumes as payors and hospital systems push extremity reconstruction toward lower-cost settings.
- Silicone biocompatibility profiles:Decades of safety data and surgeon familiarity with silicone-shelled devices sustain preference over experimental alternatives in reconstructive protocols.
Market Restraints
- Medical-grade silicone feedstock concentration:Raw material sourcing decisions face joint EPA and ECHA scrutiny over supply chain chemistry, constraining formulation flexibility.
- FDA 510(k) clearance timelines:Intensified review cycles for silicone implant modifications extend time-to-market for iterative device improvements.
- Vascular perfusion limits:Patient-specific anatomical constraints cap maximum fill volumes and expansion rates, restricting protocol standardization.
Strategic Opportunities
- Japan's specialized plastic surgery centers:Clustered demand in metropolitan markets offers concentrated entry points for manufacturers with PMDA-registered portfolios.
- Controlled-volume expansion protocols:Integration with remote patient monitoring platforms enables manufacturers to capture recurring service revenue alongside device sales.
- Germany's reconstructive surgery networks:Hospital system procurement consolidation creates anchor contracts for suppliers with CE-marked portfolios and established clinical training infrastructure.
Industry Challenges
- Expansion-protocol training gaps:Ambulatory surgical centers require specialized nursing competency in gradual inflation management that device manufacturers must subsidize.
- EU MDR technical documentation:Legacy silicone implant designs face retrospective clinical evidence requirements that strain smaller manufacturers' regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extremity Tissue Expanders Market |
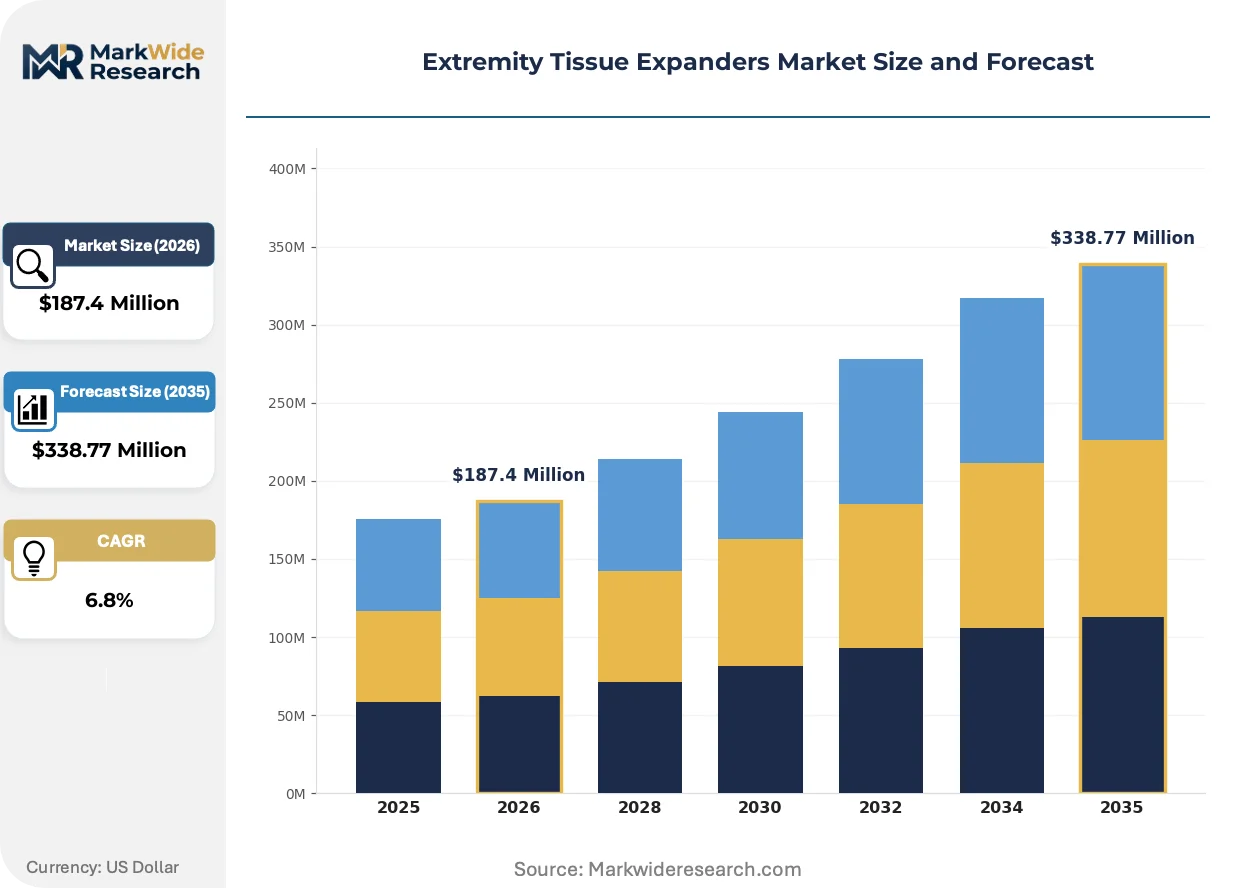
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Expanders, Tissue Expanders, Expandable Implants, Temporary Implants Application: Reconstructive Surgery, Cosmetic Surgery, Burn Treatment, Trauma Management End User: Hospitals, Clinics, Ambulatory Surgical Centers, Healthcare Facilities Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Wholesalers |
| Companies Covered | Sientra, Inc., PMT Corporation, Mentor Worldwide LLC, Allergan PLC, GC Aesthetics, Polytech Health & Aesthetics GmbH, Groupe Sebbin SAS, Guangzhou Wanhe Plastic Materials Co. Ltd., Koken Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extremity Tissue Expanders Market Emerging Trajectories
Digital integration is displacing manual volume tracking in tissue expansion protocols, while regulatory chemistry scrutiny and channel consolidation are simultaneously reshaping how devices reach surgical endpoints.
Remote monitoring platforms are modularizing the traditional expansion-protocol workflow. Ambulatory surgical centers in the United States are adopting Bluetooth-enabled fill-volume logging systems that transmit patient data to manufacturer-managed dashboards. This technology is modularizing accountability for post-operative complications and compressing liability exposure for outpatient facilities.
REACH and RoHS frameworks are tightening silicone supply chain disclosure requirements across European manufacturing. Industrial consequence includes mandatory substitution assessments for certain catalyst residues in medical-grade elastomers. German and Swiss manufacturers with vertically integrated polymer operations are responding by accelerating in-house catalyst development to preempt regulatory disqualification.
After-sales service unbundling is fragmenting the traditional device-only transaction. Reconstructive surgery departments in Japan are negotiating separate contracts for expansion-protocol management, remote monitoring, and complication response. This behavioral shift is most visible in metropolitan hospital systems where procurement committees now evaluate total cost-of-ownership rather than unit device pricing.
Extremity Tissue Expanders Market Segmentation
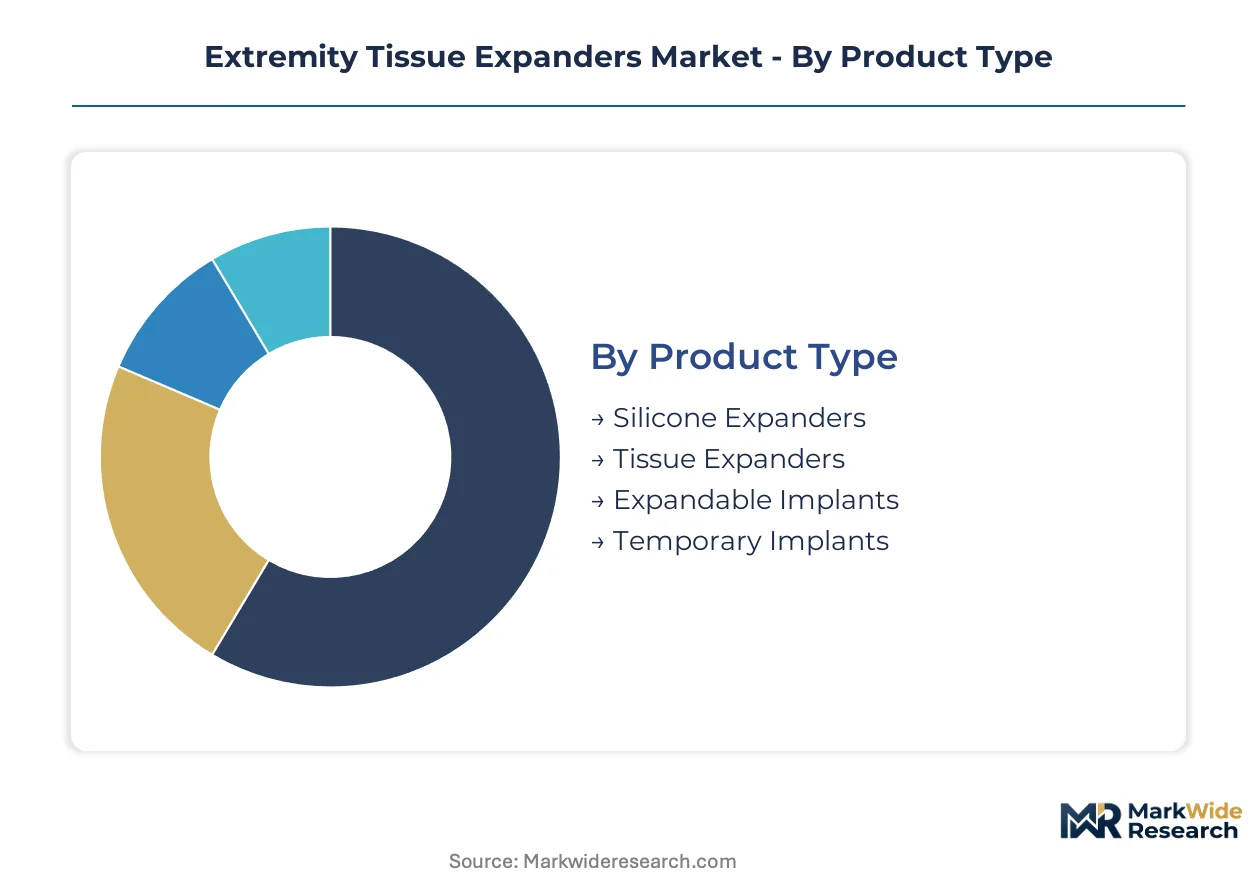
Segmentation in extremity tissue expanders reveals how procurement criteria diverge across surgical settings and regulatory environments. Understanding these splits enables manufacturers to align product configurations with specific channel requirements and clinical protocols.
Product Type:
Replacement cycles vary dramatically by shell material and valve durability, with silicone-based designs commanding longer service intervals than experimental alternatives.
- Silicone Expanders:Biocompatible elastomer shells with integrated injection ports permit gradual saline inflation over weeks to months. Demand concentrates in United States reconstructive surgery centers where FDA 510(k) clearance history and decades of safety data sustain surgeon preference.
- Tissue Expanders:Broader category encompassing shaped and rectangular configurations designed for specific anatomical zones. German hospital systems favor these devices for post-oncological reconstruction where CE-marked technical files demonstrate conformity with EU MDR clinical evidence requirements.
- Expandable Implants:Self-contained expansion mechanisms reduce nursing dependency in outpatient settings.
- Temporary Implants:Short-duration devices for acute trauma cases requiring rapid tissue generation.
Silicone Expanders sits at the top of the volume ranking, with Expandable Implants climbing the fastest.
Application:
Cost tiers separate emergency trauma interventions from elective cosmetic procedures, with reimbursement pathways dicting device selection criteria.
- Reconstructive Surgery:Post-mastectomy and post-trauma cases require staged tissue generation for flap or graft coverage. Japanese specialized plastic surgery centers in metropolitan markets drive concentrated procurement volumes for these protocols.
- Cosmetic Surgery:Elective procedures for aesthetic enhancement utilize smaller-volume expanders with faster inflation schedules. Ambulatory surgical centers in the United States capture expanding case volumes as payors push extremity reconstruction toward lower-cost settings.
- Burn Treatment:Acute and reconstructive phases demand high-compliance silicone formulations.
- Trauma Management:Emergency departments prioritize rapid-deployment configurations for acute soft-tissue loss.
Reconstructive Surgery commands the dominant revenue position, while Ambulatory Surgical Centers within Cosmetic Surgery applications are expanding most quickly.
End User:
Customer type determines service bundling requirements, with hospital systems demanding integrated training and outpatient facilities seeking standalone devices.
- Hospitals:Academic medical centers and community hospital systems operate centralized procurement committees that evaluate total cost-of-ownership including post-operative monitoring services. Germany's reconstructive surgery networks consolidate purchasing around suppliers with established clinical training infrastructure.
- Ambulatory Surgical Centers:Outpatient facilities require specialized nursing competency in gradual inflation management that device manufacturers subsidize through bundled service contracts. These centers represent the fastest-growing channel as procedural migration accelerates.
- Clinics:Private practice settings favor simplified expansion protocols with remote monitoring support.
- Healthcare Facilities:Long-term care and rehabilitation centers utilize expanders for delayed reconstruction cases.
Hospitals retain the largest installed base, with Ambulatory Surgical Centers gaining share fastest.
Distribution Channel:
Supply concentration shapes channel economics, with direct relationships capturing high-volume accounts and intermediaries serving fragmented geographies.
- Direct Sales:Manufacturer representatives negotiate service-integrated contracts with hospital procurement committees. United States reconstructive surgery units increasingly consolidate procurement around manufacturers bundling post-operative monitoring with device supply.
- Medical Distributors:Regional intermediaries stock CE-marked and FDA-cleared inventories for smaller surgical centers. European distribution networks face intensified scrutiny under REACH and RoHS supply chain disclosure requirements.
- Online Sales:Digital procurement platforms serve ancillary supplies and replacement components.
- Wholesalers:Bulk purchasing aggregators support price-sensitive healthcare facilities with standardized configurations.
Direct Sales leads channel volume, with Medical Distributors showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined silicone implant approval pathways. Cost-of-compliance gaps between FDA 510(k) and EU MDR frameworks are accelerating regional specialization in device registration and clinical trial placement.
United States
Reconstructive surgery centers in metropolitan hospital systems drive concentrated procurement volumes for silicone-shelled expanders. FDA 510(k) clearance timelines for iterative device modifications have intensified, compressing time-to-market for product improvements. Mentor Worldwide LLC anchors North American supply from established manufacturing infrastructure serving academic medical centers across the Midwest and Southeast corridors.
Germany
Post-oncological reconstruction protocols in university hospital networks generate sustained demand for CE-marked technical files demonstrating EU MDR conformity. ECHA scrutiny under REACH frameworks constrains catalyst selection in medical-grade elastomer formulations. Polytech Health & Aesthetics GmbH dominates regulatory certification pathways from vertically integrated polymer operations in the Baden-Württemberg industrial cluster.
Japan
Specialized plastic surgery centers in Tokyo and Osaka metropolitan markets create clustered demand for PMDA-registered portfolios. METI oversight of medical device quality management systems shapes supplier qualification requirements. Koken Co. Ltd. occupies a position within the domestic supply base serving reconstructive protocols in the Kanto and Kansai regions.
China
Domestic production capacity for silicone medical implants is expanding under NMPA registration requirements for Class III devices. Provincial health procurement reforms in Guangdong and Jiangsu are consolidating purchasing around manufacturers with established technical documentation. Guangzhou Wanhe Plastic Materials Co. Ltd. exemplifies regional fabrication capabilities serving hospital systems in the Pearl River Delta manufacturing corridor.
France
Aesthetic and reconstructive surgery networks in Paris and Lyon are negotiating service-integrated contracts bundling device supply with post-operative monitoring. ANSM oversight of silicone implant vigilance reporting influences adverse event documentation standards. Groupe Sebbin SAS represents European specialist positioning within the premium-tier reconstructive device segment.
Extremity Tissue Expanders Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with reconstructive surgery procurement committees consolidating around suppliers offering bundled post-operative services. The vendor base concentrates among three tiers: multinational silicone implant portfolios with established regulatory histories, regional specialists with CE-marked or PMDA-registered technical files, and emerging fabricators serving price-sensitive healthcare facilities. Dominant competitive moves include backward integration into medical-grade polymer operations and geographic expansion through distributor partnerships in ambulatory surgical center channels.
Within the multinational tier, Mentor Worldwide LLC and Allergan PLC represent established North American positioning, while Sientra, Inc. exemplifies specialized reconstructive surgery focus. Polytech Health & Aesthetics GmbH and Groupe Sebbin SAS anchor European regulatory certification capabilities. Among Asia-Pacific fabricators, Koken Co. Ltd. and Guangzhou Wanhe Plastic Materials Co. Ltd. occupy positions serving domestic procurement consolidation in Japan and China respectively. PMT Corporation and GC Aesthetics represent mid-scale specialists competing through regional training infrastructure and clinical education programs.
| Leading Market Players |
|---|
| Sientra, Inc. |
| PMT Corporation |
| Mentor Worldwide LLC |
| Allergan PLC |
| GC Aesthetics |
| Polytech Health & Aesthetics GmbH |
| Groupe Sebbin SAS |
| Guangzhou Wanhe Plastic Materials Co. Ltd. |
| Koken Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into medical-grade silicone polymer operations anchors supply position and pricing power for incumbent manufacturers serving FDA-cleared and CE-marked device markets. German and Swiss producers with captive catalyst development capabilities preempt ECHA scrutiny under REACH frameworks, while outsourced polymer sourcing exposes competitors to raw material cost volatility and qualification delays.
Pricing Analysis
Distributor margins compress pricing power for manufacturers reliant on regional intermediaries, while direct-to-hospital contracts capture premium service-integrated arrangements. Three-tier pricing structure across premium CE-marked technical files, standard FDA-cleared configurations, and economy unbranded alternatives separates procurement tiers. Cost compression in economy segments stems from Chinese domestic production scaling under NMPA Class III registration pathways. Ambulatory surgical centers exhibit highest price sensitivity due to bundled reimbursement constraints, whereas academic medical centers prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrates supply among manufacturers with established technical documentation and clinical evidence portfolios. Medical-grade silicone feedstock draws from Germany, Japan, and United States specialty chemical operations. Platinum-cured elastomer formulations, precision-machined injection ports, and sterilization packaging constitute critical input dependencies. Single-source vulnerability in catalyst supply chains intensifies under joint EPA-ECHA chemistry scrutiny. Distribution runs through direct manufacturer representatives for hospital system accounts and regional medical distributors for fragmented ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
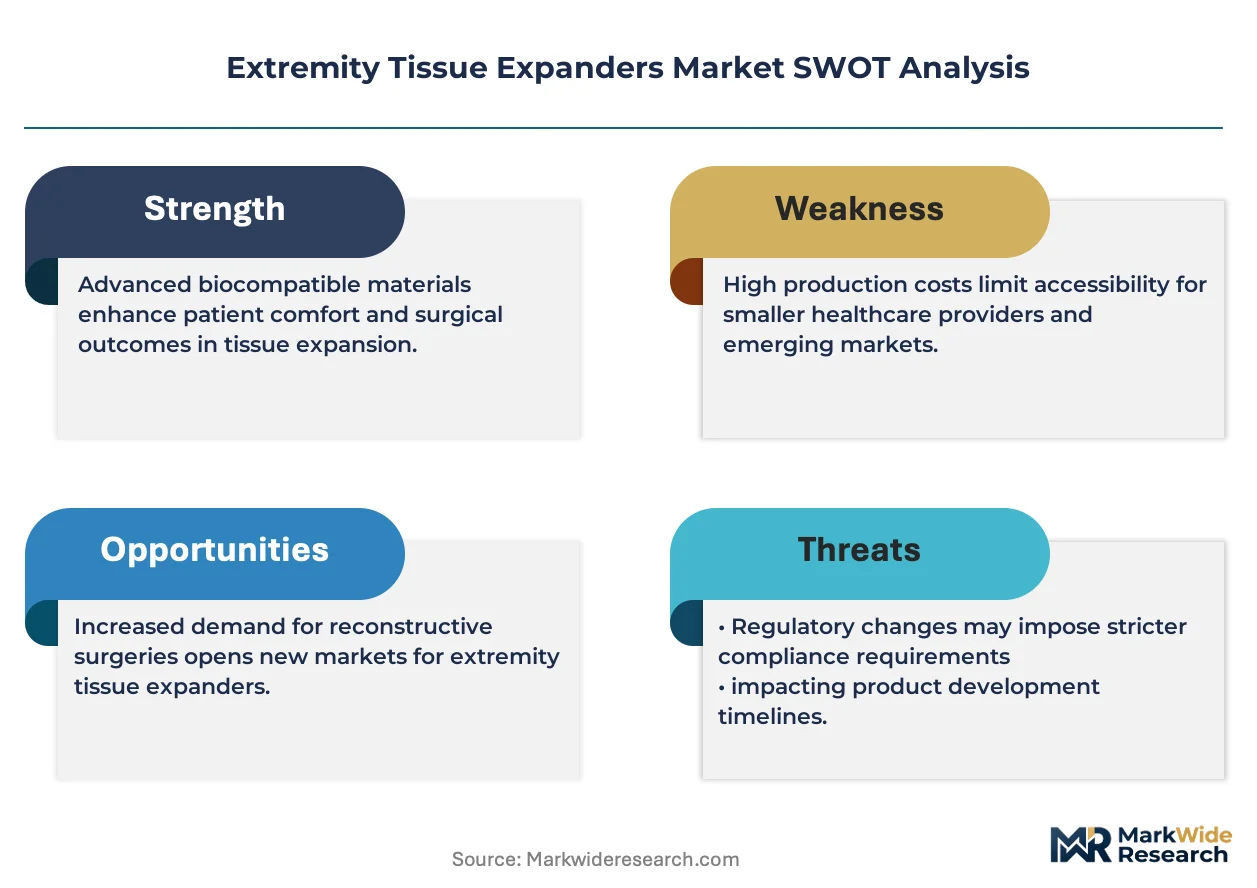
Margin expansion in extremity tissue expanders hinges on service-integrated contract penetration and remote monitoring platform adoption that captures recurring revenue streams alongside device sales.
For Market Incumbents: Deploy remote patient monitoring infrastructure to lock in hospital system procurement committees evaluating total cost-of-ownership. Consolidate position by accelerating backward integration into medical-grade polymer operations ahead of REACH catalyst substitution mandates. Counter emerging Chinese fabricators through differentiated clinical training infrastructure and expansion-protocol management services. For New Entrants and Emerging Players: Capture ambulatory surgical center channel expansion in United States metropolitan markets where procedural migration outpaces incumbent service capacity. Target Japan's specialized plastic surgery centers in Osaka and Kanto regions where PMDA registration barriers filter competition. Pursue white-label manufacturing partnerships with European distributors seeking CE-marked alternatives to established German suppliers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional specialists with established regulatory technical files because EU MDR retrospective evidence requirements strain smaller manufacturers' compliance capacity. Platform consolidation around remote monitoring capabilities and clinical training infrastructure offers defensive moat construction. Watch FDA 510(k) review cycle intensification as signal for accelerated incumbent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR conformity accelerates volume concentration among certified suppliers with technical files. |
| Hospital System Partnership | Service-integrated contracts with German reconstructive surgery networks anchor procurement consolidation. |
| Software Companion Development | Bluetooth-enabled fill-volume logging systems modularize post-operative accountability for ASCs. |
| FDA Submission Acceleration | Streamlined 510(k) pathways for iterative device modifications compress time-to-market gaps. |
| Reimbursement Strategy Alignment | Payor push toward outpatient settings favors ASC channel expansion with bundled monitoring services. |
Methodological Framework
Direct dialogue with reconstructive surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation registries, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up device shipment analysis triangulated against top-down reconstructive surgery procedure volume estimates.
Segmented outputs across product type, application, end-user channel, and regional regulatory cluster informed the analytical framework throughout the projection horizon. CAGRs derived from surgeon adoption curve modeling, procedural migration elasticity to ambulatory settings, and silicone implant replacement cycle dynamics. Forecast inputs incorporated EU MDR implementation timelines, FDA review intensity trends, and REACH catalyst substitution pathway probabilities.
Underlying measurement precision varies by segment; silicone expander volumes in United States reconstructive surgery centers carry tighter precision than emerging economy unbranded alternatives. Forecasts reflect documented assumptions regarding procedural migration velocity and regulatory chemistry scrutiny intensity. A model refresh is warranted upon material change in FDA 510(k) review cycle duration or EU MDR clinical evidence requirement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eye Socket Implants Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Oxygenator Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Inversion Table Market
Medical Devices
Global Sacral Nerve Stimulation Market