
 Medication Dispensing and Packaging Systems Market | 2026-2036
Medication Dispensing and Packaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medication Dispensing and Packaging Systems Market Outlook
Equipment leasing and pharmacy-as-a-service models are rewriting capital deployment patterns for mid-size health systems. Omnicell, Inc. leverages subscription-based automation programs to lower upfront barriers for regional hospitals. Becton, Dickinson and Company anchors its position through integrated medication management platforms spanning dispensing and analytics. McKesson Corporation competes by combining distribution scale with proprietary packaging technologies that tighten pharmacy workflow control.
Medication dispensing and packaging systems comprise electromechanical devices, software-controlled robotics, and serialized packaging equipment engineered to unit-dose or multi-dose specifications with barcode verification and tamper-evident sealing. These systems automate the preparation, labeling, and tracking of pharmaceutical products to eliminate human error and satisfy traceability mandates. Automated dispensers and robotic systems dominate installed value due to labor substitution benefits and error-reduction economics, while smart packaging and IoT integration represent the fastest-expanding margin pool as connectivity becomes standard in hospital and home care settings. Unit dose systems sustain steady replacement demand from acute care facilities prioritizing patient-specific medication protocols.
The FDA enforces drug supply chain security and serialization standards that directly shape packaging equipment specifications and upgrade cycles for domestic manufacturers. HIPAA privacy requirements and the EPA's medical waste regulations constrain system design choices around data handling and disposable material flows. Stakeholders must weigh regulatory compliance roadmaps against automation payback periods when sequencing capital investments across pharmacy networks.
Market Dynamics
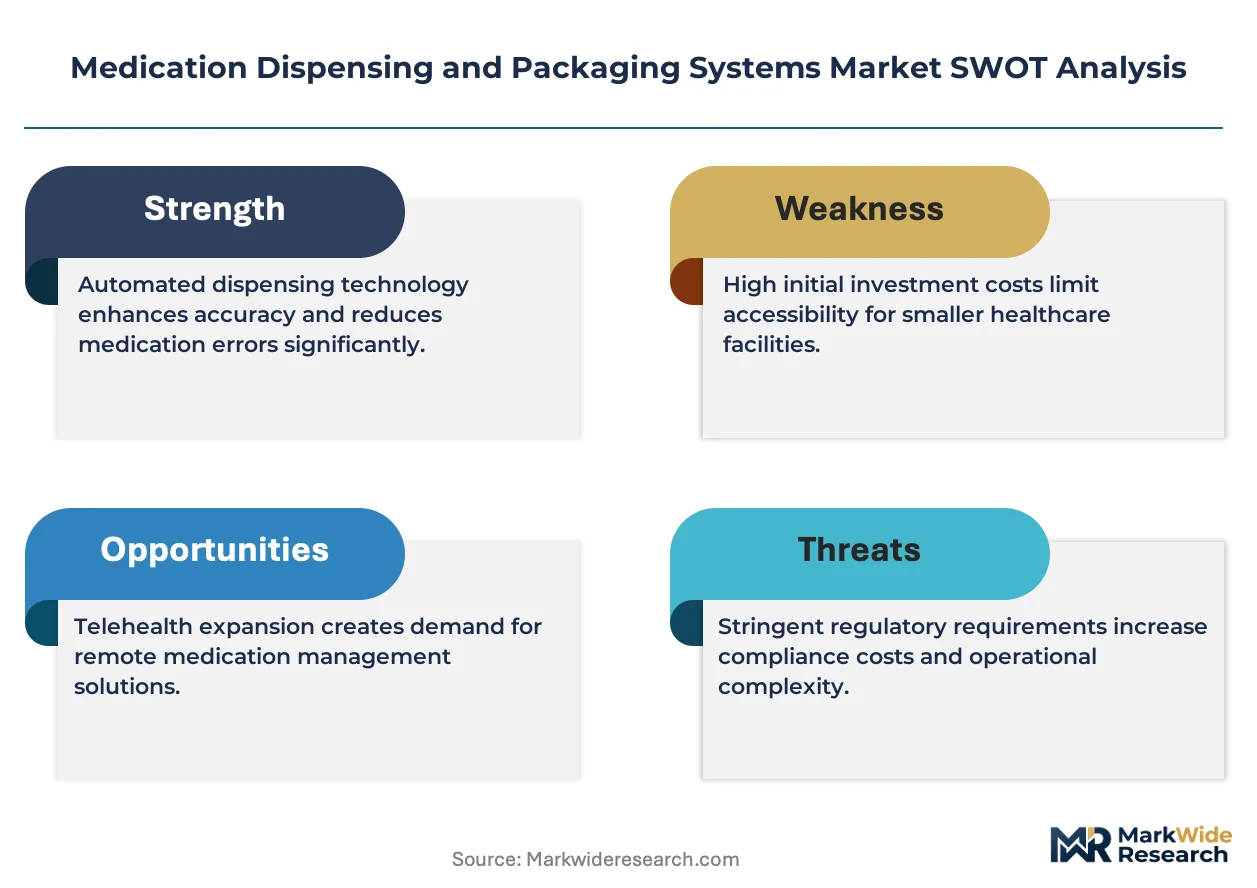
The FDA's Drug Supply Chain Security Act mandates unit-level serialization, forcing packaging equipment upgrades across hospital pharmacy networks and contract manufacturers.
Growth Catalysts
- Acute care error reduction:Hospital systems deploy automated dispensing cabinets to eliminate nursing medication administration mistakes. Joint Commission accreditation standards now reward automation adoption.
- EMA serialization enforcement:European packaging lines require aggregation-capable track-and-trace modules. Manufacturers serving EU markets retrofit equipment to meet Falsified Medicines Directive deadlines.
- Robotic unit-dose compounding:Sterile IV preparation robots replace manual compounding in oncology and pediatric pharmacy cleanrooms. USP <797> revision tightens personnel-free processing requirements.
Market Restraints
- Stainless steel and servo motor cost volatility:Equipment fabricators face margin pressure from commodity input swings. Chinese rare earth supply concentration amplifies actuator pricing uncertainty.
- Legacy system integration friction:Hospital IT departments struggle to bridge HL7 interfaces between new dispensing hardware and decades-old EHR installations. Custom middleware extends deployment timelines.
- Substitution by centralized mail-order pharmacy:Health plan consolidation shifts volume to remote fulfillment centers with industrial-scale automation. Community hospital pharmacy capital budgets contract.
Strategic Opportunities
- Home infusion therapy expansion:Discharged patients require multi-dose adherence packaging with temperature monitoring. Connected blister packs bridge acute-to-home care transitions.
- India's PLI scheme for medical devices:Domestic packaging equipment manufacturing incentives attract component suppliers to Pune and Ahmedabad clusters. Export competitiveness improves for South Asian contract manufacturers.
- AI-driven predictive restocking:Machine learning algorithms forecast ward-level consumption patterns. Cloud-based inventory optimization layers onto existing cabinet hardware without forklift replacements.
Industry Challenges
- Biomedical technician specialization gap:Electromechanical maintenance expertise concentrates in metropolitan health systems. Rural hospitals face extended vendor dispatch waits for robotic arm recalibration.
- 510(k) clearance pathway complexity:Software-as-medical-device submissions for dosing algorithms trigger FDA premarket notification scrutiny. Documentation burdens delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medication Dispensing and Packaging Systems Market |
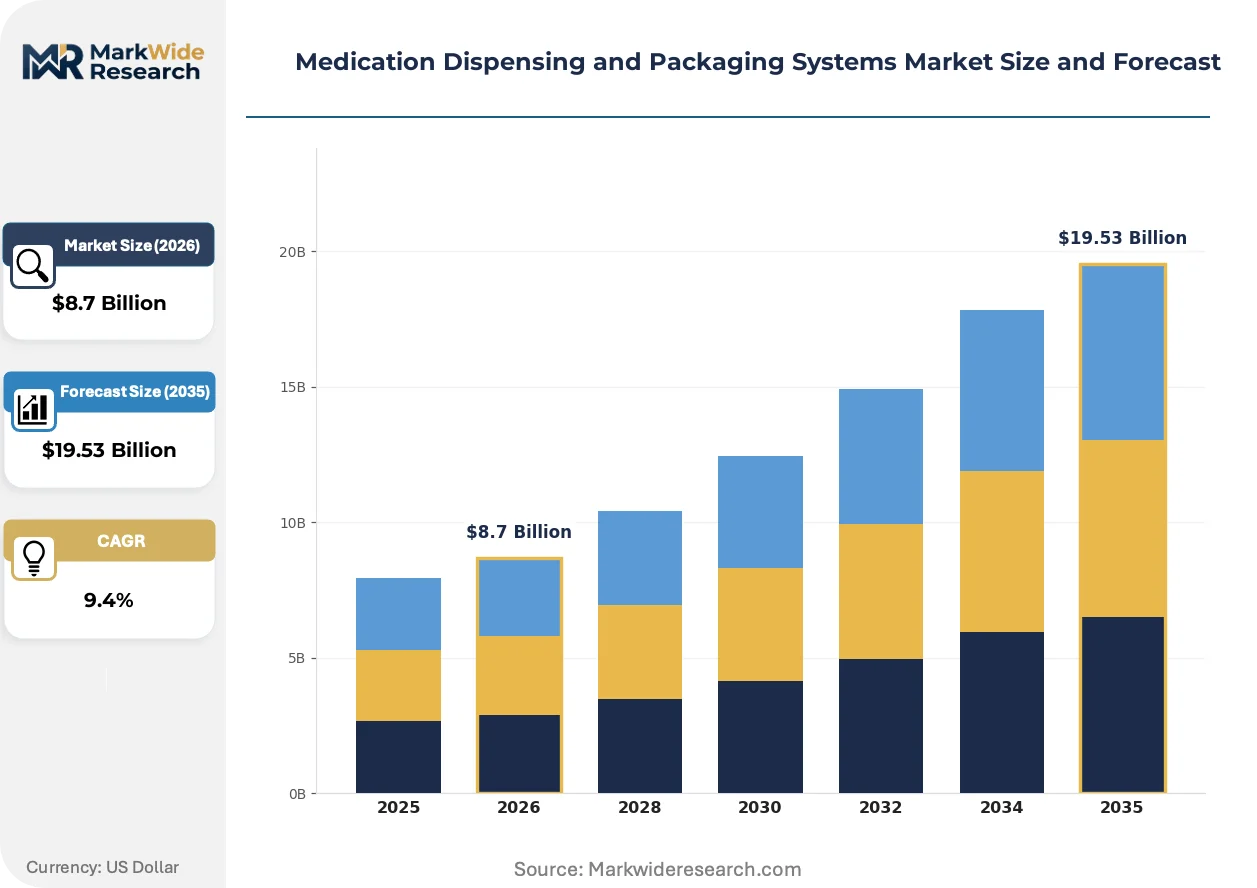
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensers, Unit Dose Systems, Multi-Dose Packaging, Pill Organizers Delivery Mode: Manual Dispensing, Robotic Systems, Smart Packaging, Mobile Applications End User: Pharmacies, Hospitals, Clinics, Home Care Providers Technology: Barcode Scanning, Serialization, RFID, IoT Integration |
| Companies Covered | Becton, Dickinson and Company, Omnicell, Inc., McKesson Corporation, Arxium, Roche, Siemens Healthineers, Yuyama Manufacturing Co., Ltd., Swisslog Holding AG, Takazono Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medication Dispensing and Packaging Systems Market Strategic Shifts
Connectivity architectures and service-based commercial models are compressing equipment ownership cycles while expanding recurring revenue pools for automation vendors.
Vision-guided robotic pick-and-place systems are collapsing the labor economics of high-mix oral solid packaging. Regional hospital pharmacies adopt these units for on-demand unit-dose repackaging of bulk generics. The technology is collapsing minimum efficient scale thresholds, enabling mid-size facilities to insource operations previously sent to central fill centers.
REACH chemical restrictions and EU Green Deal packaging waste directives accelerate biodegradable blister material qualification. European hospital procurement coalitions now specify recyclability in tender documents. German and French health systems pilot paper-based cold-form alternatives to PVC-aluminum laminates.
Subscription-based automation programs displace traditional capital purchase arrangements. Health systems in Texas and Florida convert fixed equipment investments to per-dispense operating expenses. Rural networks gain access to enterprise-grade robotics without bond financing, though total cost of ownership spreads across longer horizons.
Medication Dispensing and Packaging Systems Market Segmentation
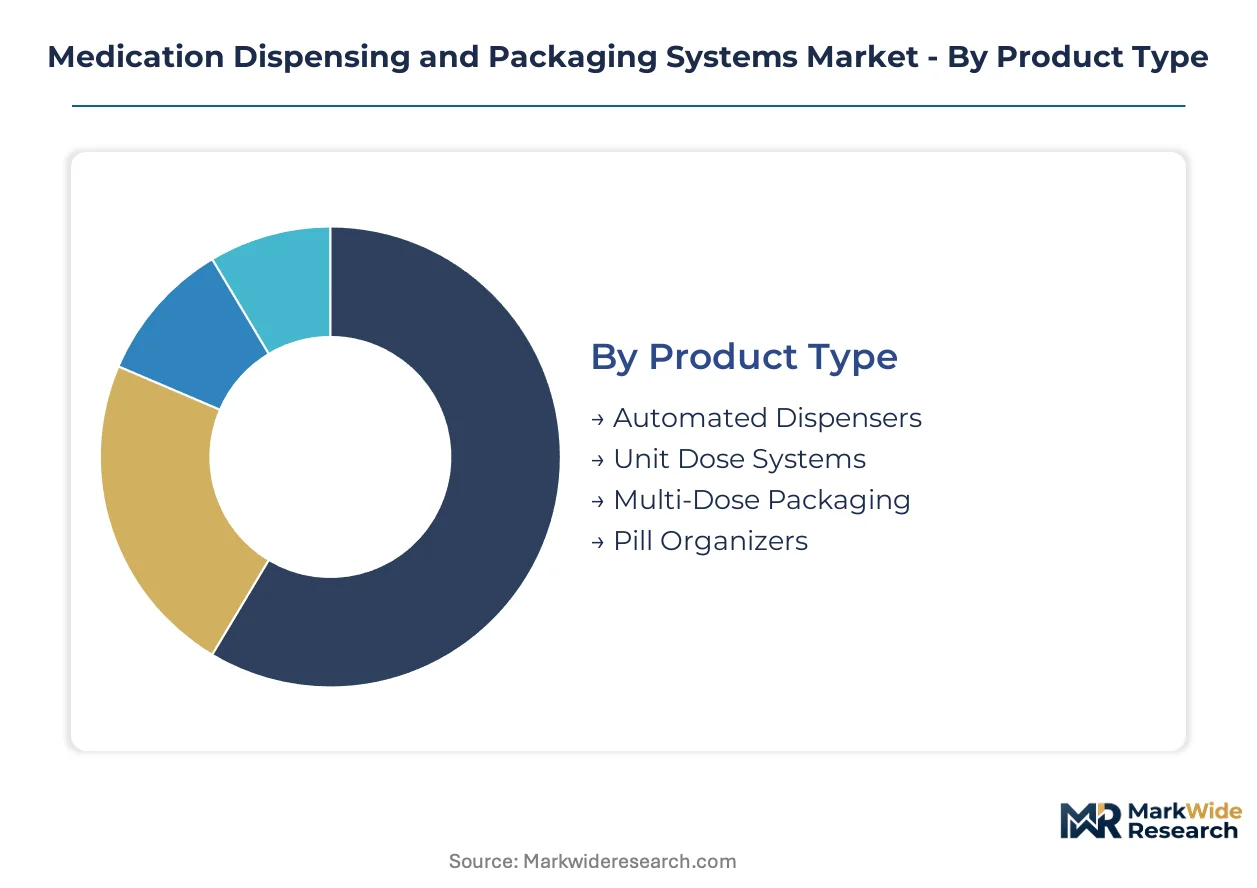
Segmentation in medication dispensing and packaging systems reveals how technology maturity, regulatory pressure, and care setting economics fragment purchasing decisions. Hospital pharmacy directors weigh error-reduction economics against IT integration costs, while home care providers prioritize portability and patient adherence features over clinical-grade specifications.
Product Type:
Equipment selection spans from high-throughput automation for centralized fulfillment to simple adherence aids for discharged patients, with capital intensity and clinical risk tolerance defining the choice set.
- Automated Dispensers:Electromechanical cabinets with controlled access, inventory tracking, and EHR integration secure medication storage in nursing units. Demand concentrates in United States health systems pursuing Joint Commission accreditation advantages through error reduction.
- Unit Dose Systems:Barcoded single-dose packaging equipment prepares patient-specific medications for bedside administration. Acute care facilities in Germany and France specify these systems to meet EMA serialization mandates while streamlining nursing workflows.
- Multi-Dose Packaging:Blister cards and pouch systems package 30- or 90-day medication regimens for chronic disease management. Long-term care pharmacies in Japan deploy these for aging population adherence programs.
- Pill Organizers:Low-cost compartmentalized containers support self-administered therapy without connectivity features. Retail pharmacy chains in India stock these for price-sensitive outpatient markets.
The dominant share belongs to Automated Dispensers, while Unit Dose Systems is closing the gap fastest.
Delivery Mode:
Automation depth determines labor substitution economics, with capital-rich institutions adopting robotics while resource-constrained settings retain manual processes augmented by digital verification.
- Manual Dispensing:Pharmacist-controlled preparation with barcode verification remains prevalent in small community pharmacies and developing markets. Rural clinics in Brazil and Mexico maintain this mode due to technician shortage and infrastructure limitations.
- Robotic Systems:Vision-guided pick-and-place robots and sterile compounding automation execute high-volume or hazardous drug preparation. Oncology pharmacies in South Korea and Australia deploy these to satisfy USP <797> personnel-free processing requirements.
- Smart Packaging:Connected blister packs and temperature-monitored containers transmit adherence and storage data to care teams. Home infusion providers in Texas and Florida pilot these for post-acute monitoring.
- Mobile Applications:Smartphone-based dosing reminders and refill management tools extend pharmacy services without hardware investment. Health systems in Ontario and British Columbia integrate these into patient portal ecosystems.
Robotic Systems command the premium tier by margin, though Smart Packaging is expanding most quickly as connectivity infrastructure matures.
End User:
Purchasing authority and reimbursement structure shape specification priorities, with hospitals demanding enterprise integration and home care providers seeking reimbursement-aligned simplicity.
- Pharmacies:Independent and chain pharmacies balance automation investment against prescription volume and generic dispensing margins. Central fill operations in the United Kingdom consolidate regional volume to justify robotic packaging lines.
- Hospitals:Acute care institutions specify FDA-compliant dispensing cabinets with anesthesia workstation integration. Tertiary medical centers in Saudi Arabia and the UAE prioritize these for medication safety accreditation.
- Clinics:Ambulatory settings require compact dispensing units with limited formulary management. Federally qualified health centers in California and New York adopt these under 340B program compliance pressures.
- Home Care Providers:Visiting nurse organizations and hospice programs need portable, patient-friendly packaging with adherence tracking. Medicare-certified agencies in Illinois and Ohio specify multi-dose pouches with temperature indicators.
Hospitals retain the largest equipment budget share, while Home Care Providers is gaining share fastest as reimbursement shifts toward value-based post-acute models.
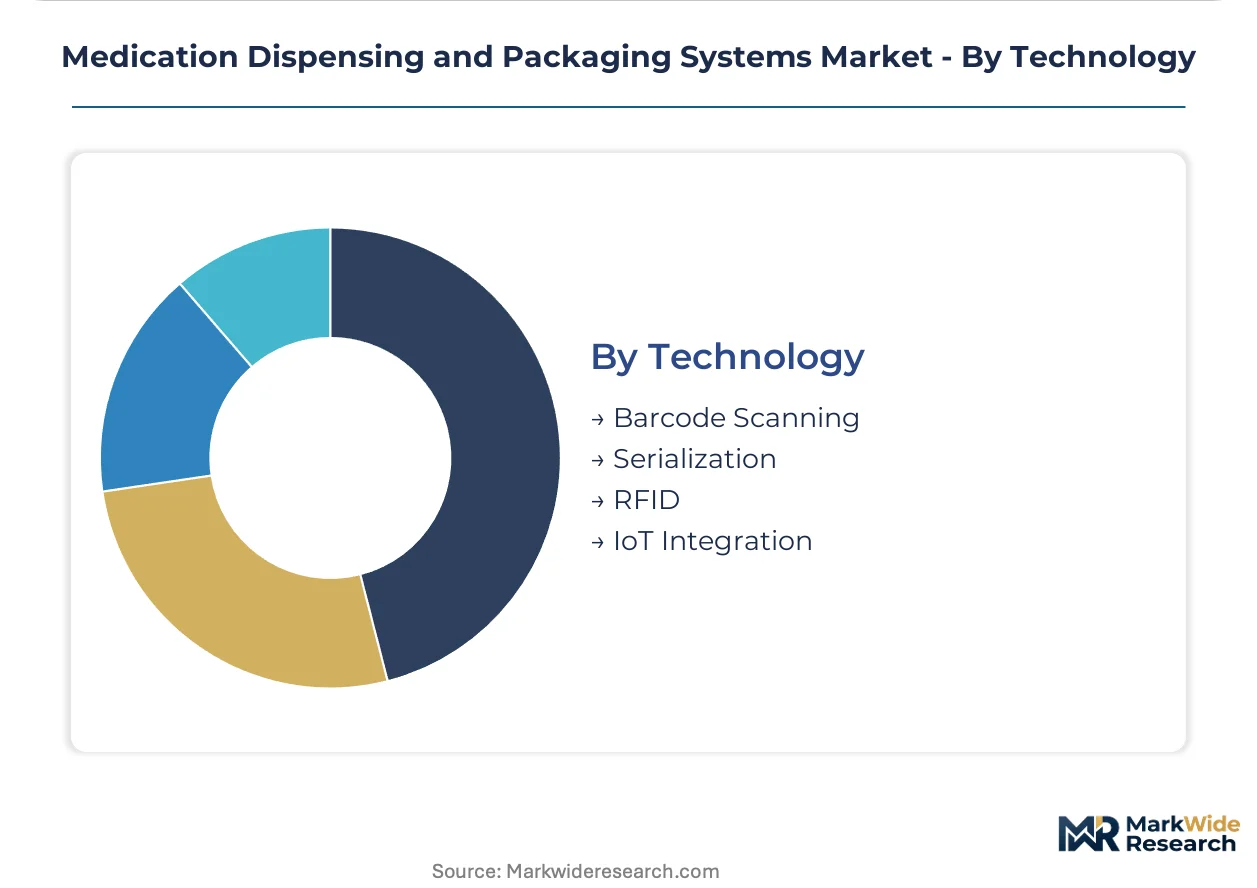
Technology:
Traceability and connectivity layers determine regulatory compliance posture and future upgrade pathways, with serialization mandates forcing hardware refresh cycles.
- Barcode Scanning:Linear and 2D barcode verification enables medication identification at dispensing and administration points. Hospital pharmacies in Italy and Spain deploy these as baseline compliance infrastructure.
- Serialization:Unit-level unique identifiers with aggregation capabilities satisfy FDA Drug Supply Chain Security Act and EMA Falsified Medicines Directive requirements. Contract packaging facilities in Ireland and Singapore invest heavily to maintain EU and US market access.
- RFID:Radio-frequency identification tags enable non-line-of-sight inventory tracking and automated replenishment. Veterans Affairs medical centers in the United States deploy these for high-value medication control.
- IoT Integration:Sensor networks and cloud connectivity enable predictive maintenance, environmental monitoring, and real-time inventory optimization. Research hospitals in Switzerland and the Netherlands pilot these for cold-chain biologics management.
Barcode Scanning holds foundational penetration, though IoT Integration is climbing the fastest as health systems pursue operational data integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and India's PLI scheme for medical devices are redirecting capital flows toward compliant manufacturing hubs and domestic equipment production clusters.
United States
Hospital pharmacy directors prioritize Joint Commission accreditation through automated dispensing cabinet deployment. The FDA's Drug Supply Chain Security Act forces packaging line retrofits with unit-level serialization by 2028. Texas and Florida health systems lead subscription-based automation adoption in Dallas and Miami metro areas.
Germany
Acute care facilities specify unit-dose systems to satisfy EMA Falsified Medicines Directive aggregation requirements. REACH chemical restrictions accelerate biodegradable blister material qualification in procurement tenders. The Stuttgart and Munich medical technology corridors host packaging equipment validation centers serving EU hospital networks.
India
Domestic pharmaceutical manufacturers expand automated packaging capacity to serve export markets under tightened serialization rules. The PLI scheme for medical devices attracts component suppliers to Pune and Ahmedabad clusters. CDSCO alignment with FDA standards drives hospital pharmacy automation tenders in Delhi-NCR and Maharashtra.
Japan
Long-term care pharmacies deploy multi-dose adherence packaging for aging population chronic disease management. METI standards for pharmaceutical traceability shape equipment procurement specifications. The Osaka-Kobe medical device manufacturing belt concentrates robotic packaging system production for domestic and Asian hospital markets.
Saudi Arabia
Tertiary medical centers specify FDA-compliant dispensing cabinets with anesthesia workstation integration for medication safety accreditation. The SFDA implements traceability regulations aligned with international serialization standards. The Riyadh and Jeddah health system modernization programs concentrate automation procurement in centralized pharmacy facilities.
Medication Dispensing and Packaging Systems Market Competitive Environment
On the supply side, the industry is consolidating around integrated medication management platforms that bundle hardware, software, and analytics capabilities. Tier-one players anchor positions through subscription-based commercial models that convert capital expenditures to recurring revenue streams. Strategic archetypes include full-stack automation vendors, distribution-integrated packaging specialists, and robotics-focused hardware fabricators. Dominant competitive moves encompass vertical integration into component manufacturing and strategic partnerships with health system purchasing coalitions.
Within the integrated platform tier, Becton, Dickinson and Company and Omnicell, Inc. exemplify archetypes combining dispensing hardware with enterprise software layers. McKesson Corporation occupies a distribution-anchored position that tightens pharmacy workflow control through proprietary packaging technologies. Yuyama Manufacturing Co., Ltd. represents the specialized robotics fabricator segment with manufacturing lineage evident in its corporate designation. Swisslog Holding AG and Takazono Corporation sit within the automation hardware specialist category, with geographic origins reflected in their respective Swiss and Japanese corporate structures.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Omnicell, Inc. |
| McKesson Corporation |
| Arxium |
| Roche |
| Siemens Healthineers |
| Yuyama Manufacturing Co., Ltd. |
| Swisslog Holding AG |
| Takazono Corporation |
| Others |
Value Chain & Pricing Dynamics
Pune and Ahmedabad equipment manufacturing clusters anchor component supply for domestic and export markets, with capacity utilization swings directly transmitting to regional hospital procurement budgets. Stainless steel servo motor cost volatility from Chinese rare earth concentration amplifies pricing power for integrated platform vendors against fragmented fabricators.
Pricing Analysis
Certification level creates the primary spread between FDA-grade serialization systems and baseline barcode verification units. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with enterprise EHR connectivity commanding substantial premiums over standalone cabinet deployments. Cost compression in mid-market tiers is intensifying because subscription-based automation programs displace capital purchases, stretching total cost of ownership across longer horizons. Independent community pharmacies exhibit highest price sensitivity, while tertiary medical centers prioritize accreditation-aligned specifications over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from tier-one vendors compress cash conversion cycles for regional hospital networks. Component sourcing concentrates in China, Japan, and Germany for precision actuators, vision systems, and control electronics. Equipment fabricators draw from stainless steel feedstock, rare earth magnets, and specialized servo motors, with single-source vulnerability concentrated in Chinese rare earth processing. Distribution runs through health system purchasing coalitions and GPO contracts that consolidate regional volume for price leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical maintenance expertise concentrates in metropolitan health systems, leaving rural hospitals dependent on extended vendor dispatch timelines for robotic recalibration. This capability gap shapes competitive positioning and capital deployment strategies across pharmacy networks.
For Market Incumbents: Pre-empt subscription-based automation displacement by anchoring recurring revenue through predictive restocking algorithms and cloud-based inventory optimization layers. Consolidate component supply through captive production of servo motor assemblies to buffer Chinese rare earth volatility. Secure hospital system purchasing coalition partnerships before regional competitors replicate integrated platform architectures.
For New Entrants and Emerging Players: Mid-size health systems in Texas and Florida represent the most penetrable entry point for pharmacy-as-a-service models that convert fixed capital to per-dispense operating expenses. Rural hospital networks in Illinois and Ohio offer white-space opportunity where vendor dispatch waits create service gaps. Pursue direct equipment leasing arrangements with biomedical technician training bundled to address specialization scarcity.
For Investors and Strategic Acquirers: Long-term, this sits as a connectivity infrastructure play because IoT integration and serialization compliance will force hardware refresh cycles across installed bases. Target acquisition profiles center on robotics-focused fabricators with manufacturing lineage and established hospital validation records. Watch for FDA premarket notification clearance delays on software-as-medical-device submissions as inflection indicator for competitive timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Automation Program | Converts fixed equipment investments to per-dispense operating expenses for mid-size health systems. |
| Backward Integration into Component Manufacturing | Captures servo motor and precision actuator supply to buffer Chinese rare earth concentration risk. |
| Hospital System Purchasing Coalition Partnership | Consolidates regional volume through GPO contracts that tighten workflow control and lock out competitors. |
| Software-as-Medical-Device FDA Submission | Enables dosing algorithm monetization through 510(k) clearance for predictive restocking applications. |
| Biodegradable Blister Material Qualification | Satisfies EU Green Deal procurement specifications for German and French hospital tender compliance. |
Study Parameters
A spread of perspectives from hospital pharmacy directors, biomedical engineers, GPO contracts managers, and equipment procurement specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearances, EMA Falsified Medicines Directive guidance documents, and hospital procurement database records. Bottom-up equipment unit economics triangulated against top-down health system capital expenditure patterns.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product type, delivery mode, end user, and technology layer, with regulatory compliance tier modeled as cross-cutting variable. CAGRs derived from installed base replacement cycles and serialization mandate upgrade timelines, incorporating USP 797 revision impacts on sterile compounding automation and Joint Commission accreditation incentive structures.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices, rare earth export restrictions, or health system bond financing costs would shift the trajectory. Forecasts incorporate documented assumptions around FDA Drug Supply Chain Security Act implementation pacing and EMA aggregation deadline adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Organoids Kits Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market