
 Germanium-68/Gallium-68 Generators Market | 2026-2036
Germanium-68/Gallium-68 Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Germanium-68/Gallium-68 Generators Market Foresight
North American production capacity is narrowing as domestic generator manufacturing scales to offset import dependence for gallium-68 eluate supply. Cardinal Health leverages integrated radiopharmacy distribution networks to sustain hospital and diagnostic center access across the United States. Eckert & Ziegler anchors European supply security through its germanium-68 parent isotope sourcing and generator assembly operations in Germany.
Germanium-68/gallium-68 generators are closed systems containing tin dioxide or titanium dioxide columns adsorbed with Ge-68, which decays via electron capture to yield Ga-68 eluate for positron emission tomography tracer synthesis; typical elution efficiency exceeds 80 percent with germanium-68 breakthrough below specified pharmacopeial limits. Column generator configurations dominate installed base due to established clinical workflow integration and validated elution protocols across nuclear medicine departments. Chromatography-based separation technology leads R&D investment as developers pursue higher specific activity and reduced metal ion contamination for next-generation theranostic applications.
The FDA regulates generators as positron emission tomography drugs under 21 CFR Part 212, while the EMA enforces GMP Annex 3 guidelines for radiopharmaceutical precursor manufacturing across European member states; both frameworks mandate eluate quality testing and generator shelf-life validation that directly shape product development timelines and market access costs. The International Atomic Energy Agency provides additional standards for generator transport and shielding that constrain logistics architecture. Stakeholders must monitor evolving theranostic reimbursement codes and national radioisotope sovereignty initiatives that will determine regional competitive positioning and capital deployment priorities.
Market Dynamics
The theranostic convergence of diagnostic imaging and targeted radionuclide therapy is compressing generator utilization cycles, forcing manufacturers to optimize eluate yield consistency and metal ion purity for same-day synthesis workflows.
Growth Catalysts
- PSMA PET imaging protocols:Prostate cancer staging departments in the United States are expanding gallium-68 DOTATATE and PSMA-11 tracer volumes under FDA-approved indications, driving installed generator base expansion.
- EMA GMP Annex 3 harmonization:Streamlined precursor manufacturing guidelines across European member states are reducing batch validation timelines for generator eluate release.
- Cyclotron-to-generator substitution:Hospital nuclear medicine departments are displacing on-site gallium-68 production with column generator systems to eliminate cyclotron capital burden and technical staffing requirements.
Market Restraints
- Germanium-68 parent isotope concentration:High-energy proton irradiation capacity for zinc-68 target processing concentrates at fewer than six research reactor facilities worldwide, creating single-source vulnerability for generator manufacturers.
- Eluate quality variance:Tin dioxide column chemistries exhibit batch-dependent germanium-68 breakthrough rates that complicate pharmacopeial compliance testing and shelf-life validation protocols.
- Titanium-89 theranostic competition:Emerging alpha-emitting radiopharmaceutical pipelines utilizing actinium-225 and lead-212 are diverting clinical trial investment away from beta-emitting gallium-68 conjugates.
Strategic Opportunities
- Indian diagnostic center penetration:Mumbai and Delhi oncology imaging networks remain underpenetrated by generator-based PET tracer supply, presenting first-mover positioning for distribution partnerships with CDSCO-registered importers.
- Automated synthesis integration:Convergence of column generator elution with single-use cassette radiosynthesizers is enabling decentralized tracer production at satellite diagnostic facilities without hot cell infrastructure.
- Japan PMDA theranostic pathway:The Pharmaceuticals and Medical Devices Agency's accelerated review track for radiopharmaceutical diagnostics creates regulatory tailwind for gallium-68 labeled agent market authorization.
Industry Challenges
- Radiochemist staffing scarcity:Qualified personnel capable of generator elution, quality control testing, and tracer synthesis are concentrated at academic medical centers, constraining community hospital adoption.
- Generator transport logistics:IAEA shielding and surface contamination standards for germanium-68 decay heat management complicate air freight routing and customs clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germanium-68/Gallium-68 Generators Market |
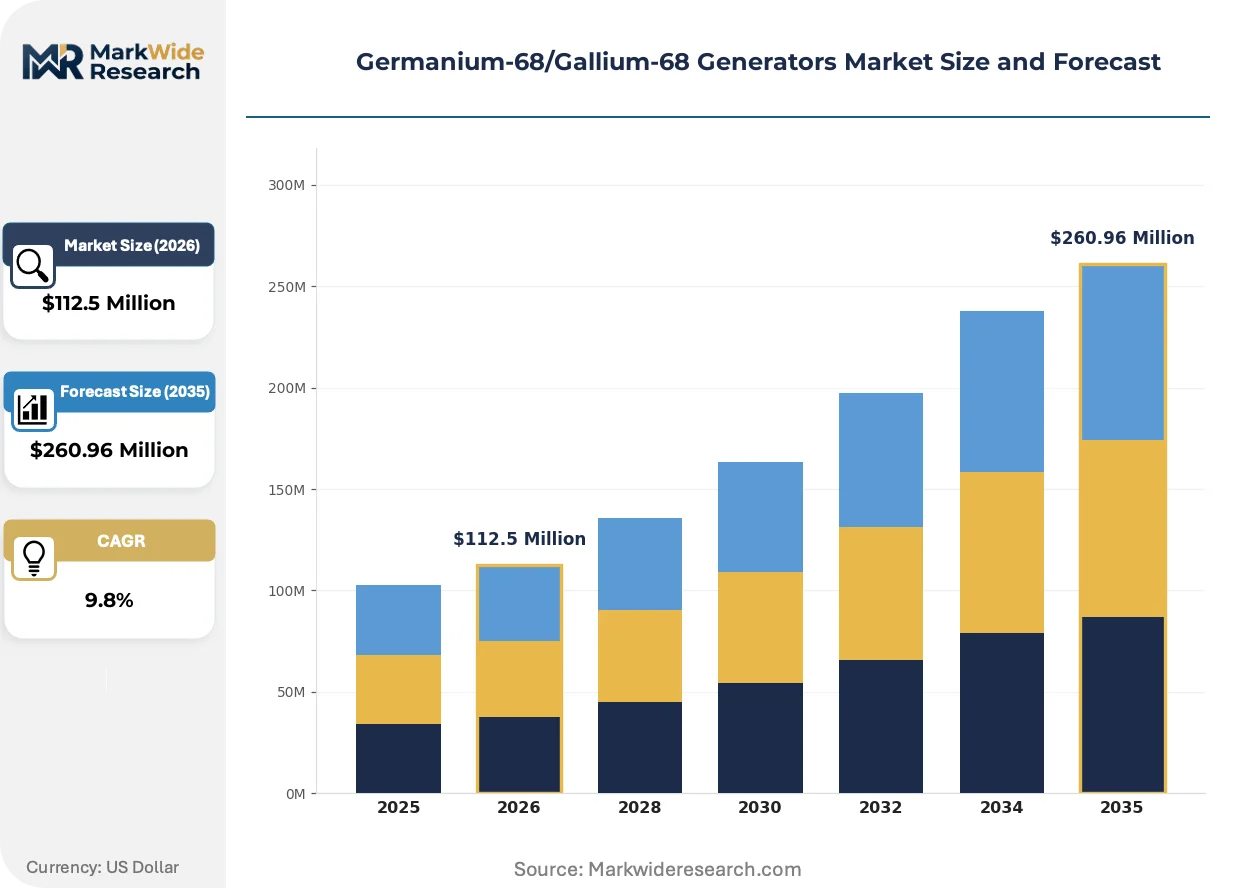
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $260.96 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molten Salt Generator, Column Generator, Dry Generator, Wet Generator Technology: Adsorption, Ion Exchange, Solvent Extraction, Chromatography Application: Oncology Imaging, Neurology Diagnostics, Cardiology Assessment, Infectious Disease Detection End User: Diagnostic Centers, Radiopharmacy Units, Academic Research Institutes, Nuclear Medicine Departments |
| Companies Covered | iThemba LABS, Cardinal Health, Eckert & Ziegler, Isotope JSC, Curium Pharma, IRE ELiT, Cyclotron Co., Ltd., Isotopia Molecular Imaging Ltd, ITM Isotope Technologies Munich SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germanium-68/Gallium-68 Generators Market Shifts & Advancements
Digital integration of generator performance monitoring with hospital information systems is compressing downtime and enabling predictive maintenance scheduling. Three developments are restructuring competitive positioning.
Chromatography-based solid-phase extraction cartridges are digitizing eluate purification workflows by embedding conductivity and UV sensors for real-time germanium-68 breakthrough detection. Nuclear medicine departments at tertiary care centers are adopting these smart generator systems to eliminate manual fraction collection and offline counting steps. The technology is digitizing quality assurance labor, reducing radiopharmacist hands-on time by automating pharmacopeial compliance documentation.
The FDA's 21 CFR Part 212 positron emission drug cGMP enforcement discretion policy for compounded PET drugs is creating regulatory asymmetry between centralized radiopharmacy distributors and hospital-based generator operations. This framework incentivizes Cardinal Health and similar networks to consolidate generator eluate processing under standardized quality systems while independent hospitals face heightened inspection scrutiny. Small-volume hospital generators in the United States are responding by outsourcing tracer synthesis to 503B compounding facilities.
Diagnostic centers are consolidating procurement authority into integrated delivery networks and group purchasing organizations, displacing individual hospital generator purchasing decisions. This concentration is compressing price negotiation cycles and demanding multi-year service contracts with guaranteed eluate specific activity minimums. The shift is most visible in Germany, where university hospital networks are standardizing on single-generator platforms to simplify training and inventory management across regional campuses.
Germanium-68/Gallium-68 Generators Market Segmentation
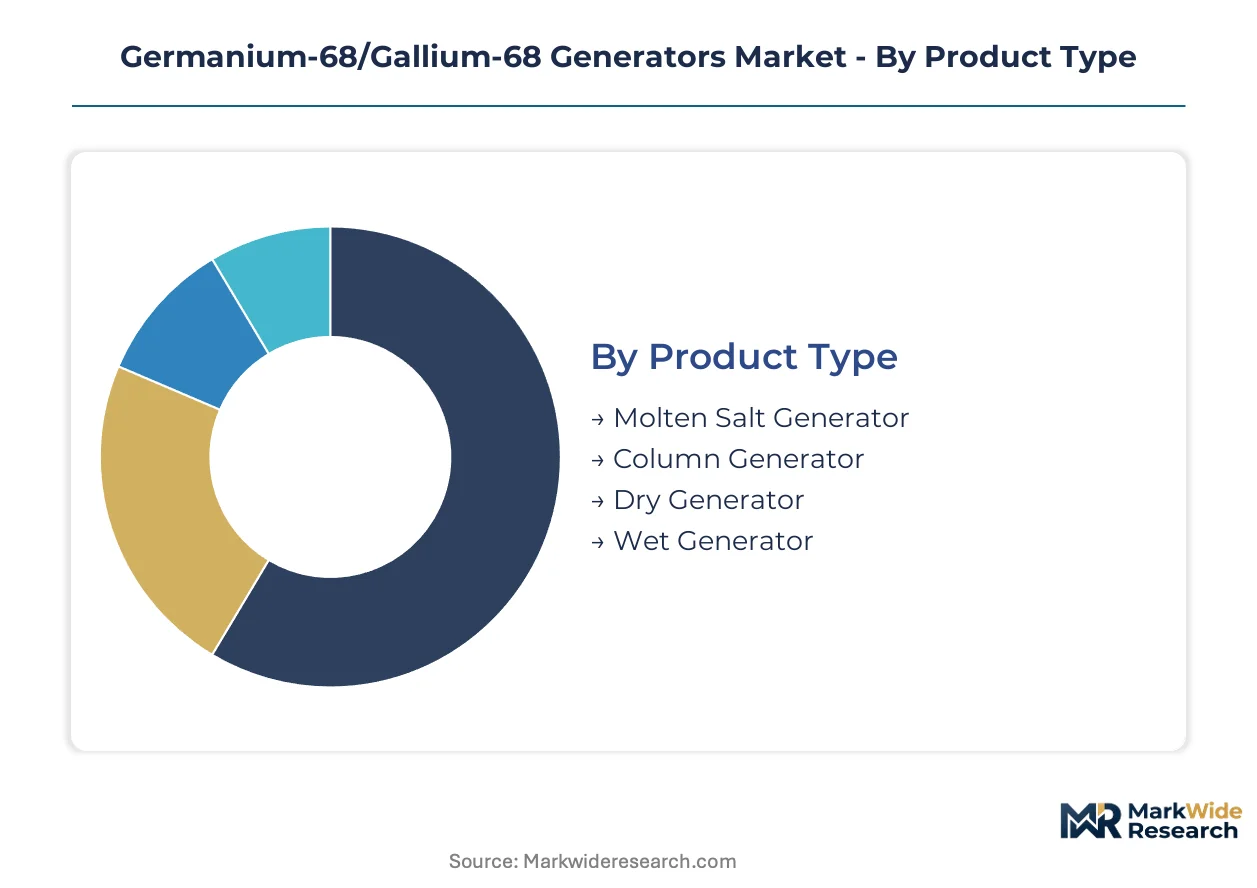
Generator configuration choices determine service contract structures, calibration frequency, and replacement part logistics. Hospital procurement teams weigh elution consistency against capital outlay when selecting across product architectures. Technology selection cascades into regulatory filing complexity and staff training requirements.
Product Type:
After-sales service intensity varies sharply across generator architectures, with column-based systems demanding quarterly performance validation and resin replacement scheduling that molten salt alternatives avoid.
- Column Generator:Tin dioxide or titanium dioxide columns adsorb germanium-68 parent isotope for decay-driven gallium-68 elution. Nuclear medicine departments at German university hospital networks favor these systems for validated pharmacopeial compliance and established workflow integration.
- Molten Salt Generator:Molten salt matrices enable continuous elution cycles with reduced breakthrough variance versus solid-phase alternatives. Research reactor facilities in Belgium and the Netherlands are piloting these configurations for centralized radiopharmacy supply.
- Dry Generator:Lyophilized generator cores extend shelf life through reduced radiolytic degradation during transport.
- Wet Generator:Aqueous-phase systems dominate legacy installed bases requiring minimal protocol modification.
Column Generator holds the largest share; momentum sits with Molten Salt Generator.
Technology:
Cost tier stratification separates premium chromatography systems from baseline adsorption platforms, with ion exchange occupying the mid-market for specific activity optimization.
- Chromatography:Solid-phase extraction cartridges with embedded conductivity and UV sensors enable real-time germanium-68 breakthrough detection. Tertiary care centers in the United States are adopting these smart systems to automate pharmacopeial compliance documentation and reduce radiopharmacist hands-on time.
- Adsorption:Tin dioxide and titanium dioxide chemistries remain the workhorse for routine clinical elution with proven metal ion retention profiles.
- Ion Exchange:Resin-based separation achieves higher specific activity for theranostic tracer synthesis demanding reduced metal contamination.
- Solvent Extraction:Liquid-liquid methods persist in research settings for custom gallium-68 labeling protocols.
Adsorption dominates installed volume; chromatography is climbing the fastest on automation premiums.
Application:
Application concentration reflects reimbursement code availability and radiopharmaceutical pipeline maturity, with prostate cancer staging commanding the densest generator deployment.
- Oncology Imaging:PSMA PET and DOTATATE tracer synthesis for prostate cancer and neuroendocrine tumor staging. Diagnostic centers across the United States are expanding generator capacity under FDA-approved indications for gallium-68 labeled agents.
- Neurology Diagnostics:Amyloid and tau imaging tracer development for Alzheimer's disease staging.
- Cardiology Assessment:Myocardial perfusion and inflammation imaging applications.
- Infectious Disease Detection:Radiolabeled antibiotic and white blood cell tracer synthesis for localization studies.
Oncology Imaging commands the deepest installed base; Neurology Diagnostics shows steepest expansion trajectory on aging-population imaging demand.
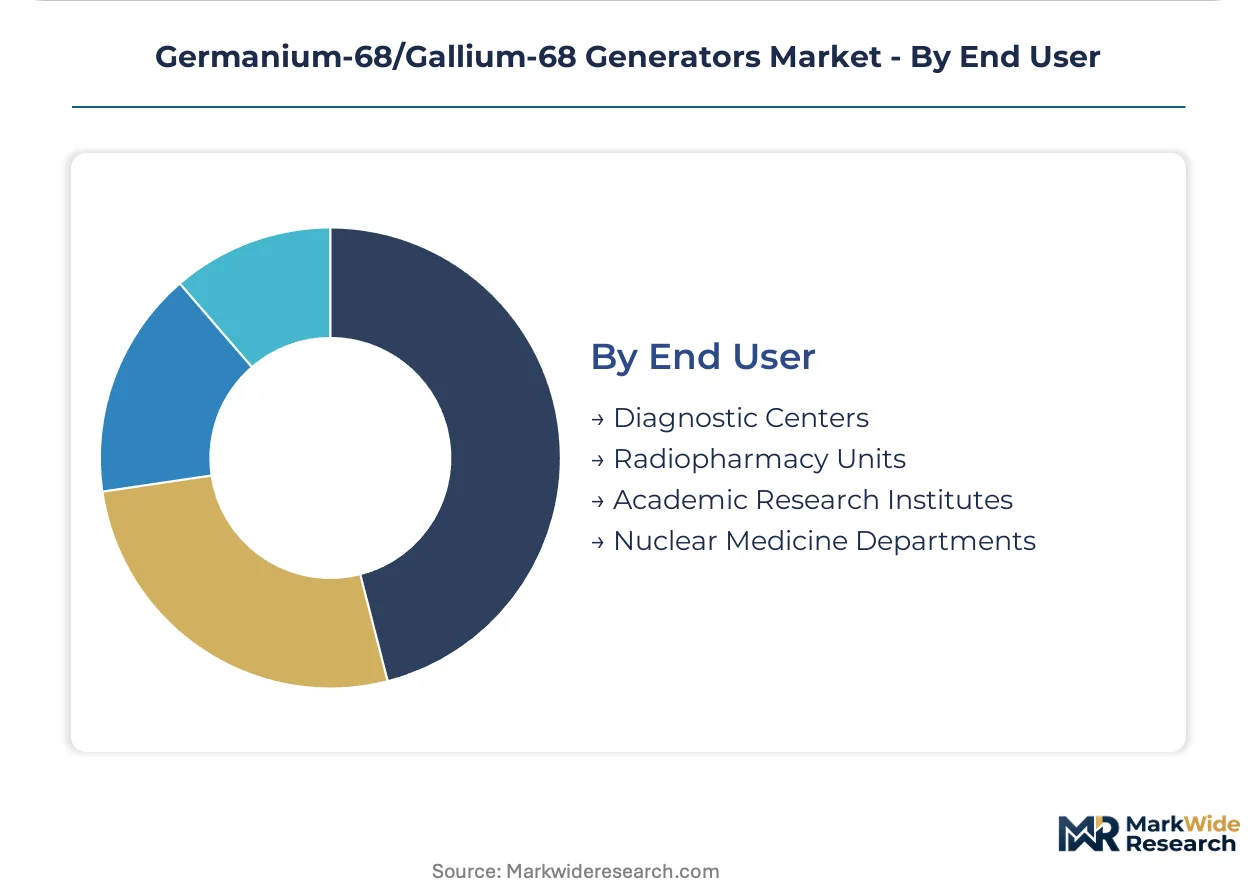
End User:
Customer type dictates procurement authority concentration, with integrated delivery networks displacing individual hospital purchasing decisions across major markets.
- Diagnostic Centers:Independent imaging facilities requiring guaranteed eluate specific activity minimums under multi-year service contracts. Mumbai and Delhi oncology networks remain underpenetrated by generator-based PET tracer supply.
- Nuclear Medicine Departments:Hospital-based operations facing heightened FDA inspection scrutiny under 21 CFR Part 212 enforcement discretion policies.
- Radiopharmacy Units:Centralized 503B compounding facilities consolidating tracer synthesis for satellite distribution.
- Academic Research Institutes:Investigational new drug protocol development for novel gallium-68 conjugates.
Diagnostic Centers represent the broadest addressable base; Radiopharmacy Units are gaining share fastest on outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States diagnostic centers favor decentralized generator installations for same-day tracer synthesis, while European networks concentrate eluate processing at centralized radiopharmacy hubs, and Asian markets remain tethered to cyclotron-dependent supply models with limited generator penetration.
United States
PSMA PET imaging protocols for prostate cancer staging are expanding generator-installed base across oncology departments. FDA enforcement discretion under 21 CFR Part 212 is heightening inspection scrutiny for hospital-based operations while exempting centralized 503B compounding facilities. Cardinal Health leverages integrated radiopharmacy distribution networks across the Midwest and Southeast to sustain hospital access.
Germany
University hospital networks are standardizing on single-generator platforms to simplify training and inventory management across regional campuses. EMA GMP Annex 3 harmonization is reducing batch validation timelines for generator eluate release. ITM Isotope Technologies Munich SE anchors supply capacity in Bavaria, with Eckert & Ziegler reinforcing European security through parent isotope sourcing and assembly operations.
India
Mumbai and Delhi oncology imaging networks remain underpenetrated by generator-based PET tracer supply, presenting first-mover positioning opportunities. CDSCO import registration requirements for radiopharmaceutical precursors constrain rapid market entry for foreign manufacturers. Diagnostic center consolidation in Maharashtra and Karnataka is creating procurement authority concentration favorable to multi-year service contract structures.
Japan
The Pharmaceuticals and Medical Devices Agency's accelerated review track for radiopharmaceutical diagnostics is creating regulatory tailwind for gallium-68 labeled agent market authorization. Aging-population imaging demand for neuroendocrine tumor staging is compressing generator utilization cycles in Kanto and Kansai regions. METI radioisotope sovereignty initiatives are stimulating domestic production capacity investment.
Belgium
Research reactor facilities in Mol are piloting molten salt generator configurations for centralized radiopharmacy supply to neighboring member states. IRE ELiT operates within this cluster, supporting eluate distribution across Benelux and northern France. EMA precursor manufacturing guidelines are streamlining cross-border eluate release protocols.
Germanium-68/Gallium-68 Generators Market Competitive Landscape
Capability concentration sits with specialized isotope technology developers; scale advantage sits with integrated health service distributors. The market structures around a consolidated upstream tier controlling germanium-68 parent isotope irradiation capacity and a fragmented downstream tier of generator assemblers and radiopharmacy distributors. Three archetypes dominate: reactor-linked isotope producers, vertically integrated health service networks, and specialized molecular imaging technology developers. Competitive moves center on backward integration into zinc-68 target processing and strategic partnerships with diagnostic center networks for captive offtake agreements.
Among reactor-linked isotope producers, iThemba LABS and Isotope JSC exemplify the upstream capability archetype, anchoring parent isotope supply security through research reactor access. Eckert & Ziegler occupies a position bridging isotope sourcing and generator assembly, representing the vertically integrated model. Cardinal Health sits within the health service distribution tier, leveraging existing radiopharmacy infrastructure to capture downstream value. ITM Isotope Technologies Munich SE exemplifies the European specialist archetype, with Isotopia Molecular Imaging Ltd and Curium Pharma representing alternative geographic and structural positioning within the competitive set.
| Leading Market Players |
|---|
| iThemba LABS |
| Cardinal Health |
| Eckert & Ziegler |
| Isotope JSC |
| Curium Pharma |
| IRE ELiT |
| Cyclotron Co., Ltd. |
| Isotopia Molecular Imaging Ltd |
| ITM Isotope Technologies Munich SE |
| Others |
Supply & Pricing Matrix
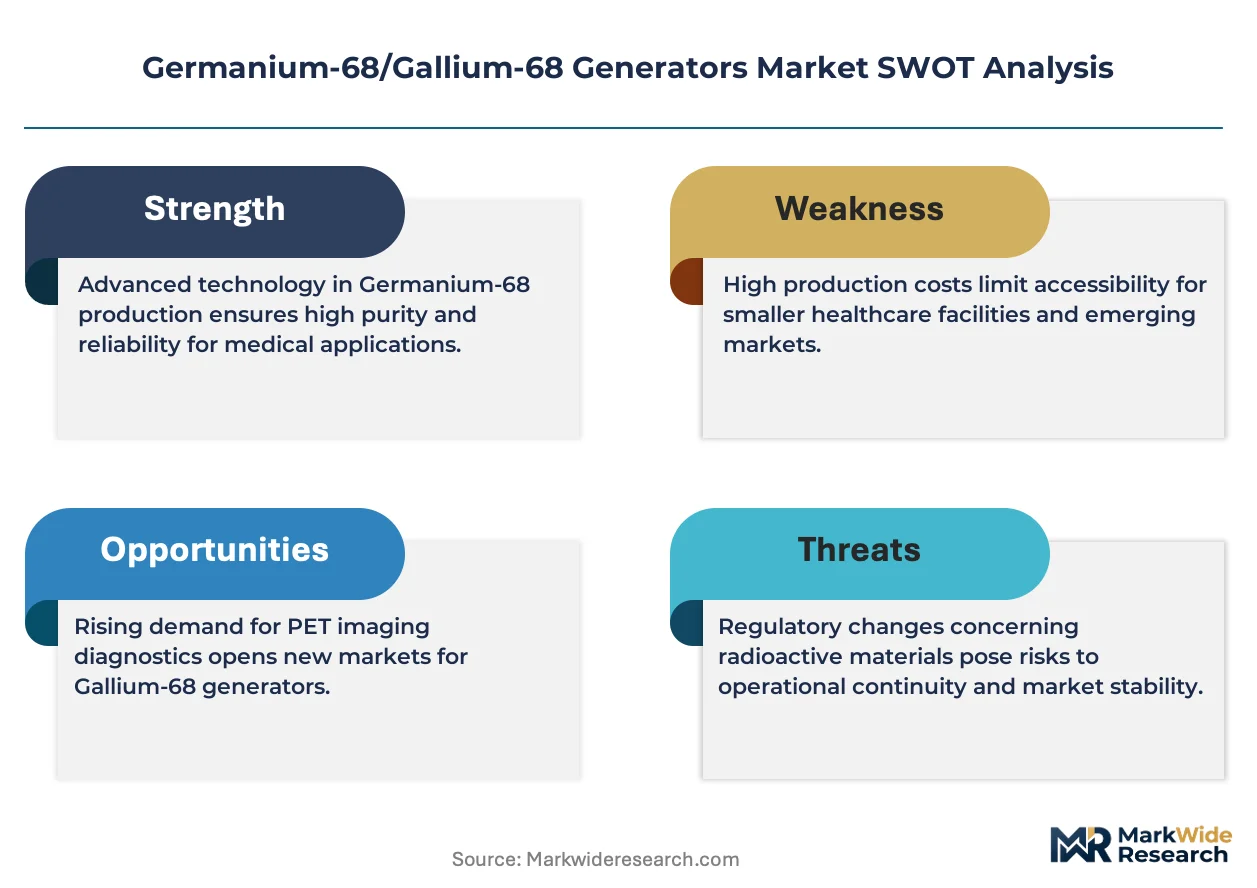
Research reactor facilities in Belgium, South Africa, and Russia concentrate germanium-68 parent isotope irradiation capacity, anchoring margin capture upstream while generator assemblers and radiopharmacy distributors compete for downstream value in oncology imaging networks.
Pricing Analysis
Long-term offtake contracts dominate procurement between generator manufacturers and parent isotope suppliers, insulating buyers from spot-market volatility in zinc-68 target processing. Three-tier pricing structure across premium chromatography systems, standard column generators, and economy-grade wet configurations reflects certification grade and after-sales service bundling. Pricing pressure stems from diagnostic center consolidation into group purchasing organizations demanding guaranteed eluate specific activity minimums. Community hospital nuclear medicine departments exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance consistency over unit cost.
Supply Chain Analysis
Zinc-68 target enrichment and high-energy proton irradiation capacity concentrates in Belgium, South Africa, and Russia, with fewer than six research reactor facilities worldwide processing parent isotope feedstock. Generator assembly draws from tin dioxide and titanium dioxide column chemistries, precision shielding components, and real-time monitoring sensors. Single-source vulnerability in parent isotope supply creates structural risk for manufacturers dependent on reactor scheduling and geopolitical stability. Distribution runs through centralized radiopharmacy hubs in Europe and decentralized hospital-based installations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germanium-68/gallium-68 generator deployment sits in early-cycle expansion as PSMA PET imaging protocols drive installed base growth in prostate cancer staging departments across the United States and Germany.
For Market Incumbents: Pre-empt titanium-89 theranostic competition by accelerating chromatography-based automation R&D and securing captive offtake agreements with consolidating diagnostic center networks in Maharashtra and Karnataka. Backward integration into zinc-68 target processing reduces single-source vulnerability from concentrated reactor capacity. Certification investment under EMA GMP Annex 3 harmonization preserves European market access against heightened inspection scrutiny. For New Entrants and Emerging Players: Pursue distribution partnerships with CDSCO-registered importers to capture first-mover positioning in Mumbai and Delhi oncology imaging networks where generator-based PET tracer supply remains underpenetrated. Automated synthesis integration with single-use cassette radiosynthesizers offers a go-to-market angle for satellite diagnostic facilities lacking hot cell infrastructure. Radiopharmacy unit outsourcing trends present the most penetrable customer segment for new market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed radiopharmacy networks consolidating tracer synthesis capacity under 503B compounding frameworks. Long-term viability over a multi-year horizon rests on theranostic reimbursement code expansion and national radioisotope sovereignty initiatives reshaping regional competitive positioning. Watch for FDA enforcement discretion policy shifts affecting hospital-based generator operations as an inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Capacity Partnership | Secures parent isotope supply through long-term offtake with iThemba LABS or Isotope JSC. |
| Chromatography Automation Launch | Embedded conductivity sensors reduce radiopharmacist hands-on time at tertiary care centers. |
| CDSCO Import Registration | Enables market entry into Mumbai and Delhi oncology networks under Indian pharmaceutical regulations. |
| Integrated Delivery Network Contract | Multi-year service agreements with guaranteed eluate specific activity minimums lock in volume. |
| PMDA Theranostic Pathway Filing | Accelerated review track in Japan creates regulatory tailwind for gallium-68 labeled agents. |
Research Methodology
A spread of perspectives from nuclear medicine department heads, radiopharmacy operations managers, regulatory affairs specialists at generator manufacturers, and GPO contracts managers converged on the working assumptions. Secondary validation drew from FDA 21 CFR Part 212 guidance documents, EMA GMP Annex 3 updates, IAEA transport standards, hospital procurement databases, and CMS reimbursement code filings. Bottom-up generator installation counts and top-down PET tracer volume estimates were triangulated to anchor market sizing.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation dimensions including generator configuration, separation technology, oncology application subtype, and end-user procurement authority. CAGRs were derived from installed base expansion trajectories and elution frequency assumptions tied to PSMA PET protocol adoption. Forecast inputs incorporated cyclotron-to-generator substitution rates and theranostic pipeline progression for neuroendocrine tumor staging.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and radioisotope transport logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding reimbursement code expansion and reactor facility utilization rates. Cross-checking against IAEA radioisotope supply forecasts and national nuclear medicine society procedure volume surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Stethoscope Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Biologic Injectors Market
Medical Devices
Mexico Ophthalmic Devices Market