
 Global Hybrid Fabrics Market | 2026-2036
Global Hybrid Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Fabrics Market Analysis
ISO 9001 and AS9100 certification cycles are reorganizing supplier eligibility across the Global Hybrid Fabrics Market, favoring producers with integrated quality management systems. Toray Industries leverages captive carbon fiber supply chains to dominate aerospace-grade hybrid fabric output. Hexcel Corporation sustains North American defense and commercial aviation relationships through decades-long qualification protocols. SGL Carbon anchors European automotive programs with specialized carbon-glass hybrid solutions for structural battery enclosures.
Hybrid fabrics combine two or more distinct fiber types—commonly carbon, glass, aramid, or basalt—into unified textile architectures with tunable strength-to-weight ratios and controlled thermal expansion coefficients. These engineered materials serve critical load-bearing functions where monofiber solutions fail to balance cost, performance, and damage tolerance across directional stress planes. Woven hybrid fabrics occupy the largest value share due to established processing infrastructure and predictable mechanical behavior under multi-axial loading. Composite-structured variants represent the fastest-expanding category as automotive and aerospace OEMs seek net-shape preforms that reduce layup labor and scrap rates. Non-woven configurations concentrate margin pools in specialized industrial filtration and ballistic protection segments where through-thickness properties govern specification.
FAA airworthiness directives and EASA certification requirements govern hybrid fabric incorporation into primary aircraft structures, creating multi-year qualification barriers that protect incumbent suppliers. EPA emissions standards and EU F-Gas Regulation simultaneously push automotive OEMs toward lighter hybrid composite solutions that improve fleet efficiency without sacrificing crash performance. REACH compliance and evolving ECHA substance restrictions further filter material formulations available to European processors. Stakeholders must monitor evolving CSRD disclosure requirements and carbon border adjustment mechanisms that will reshape sourcing economics for energy-intensive precursor fibers.
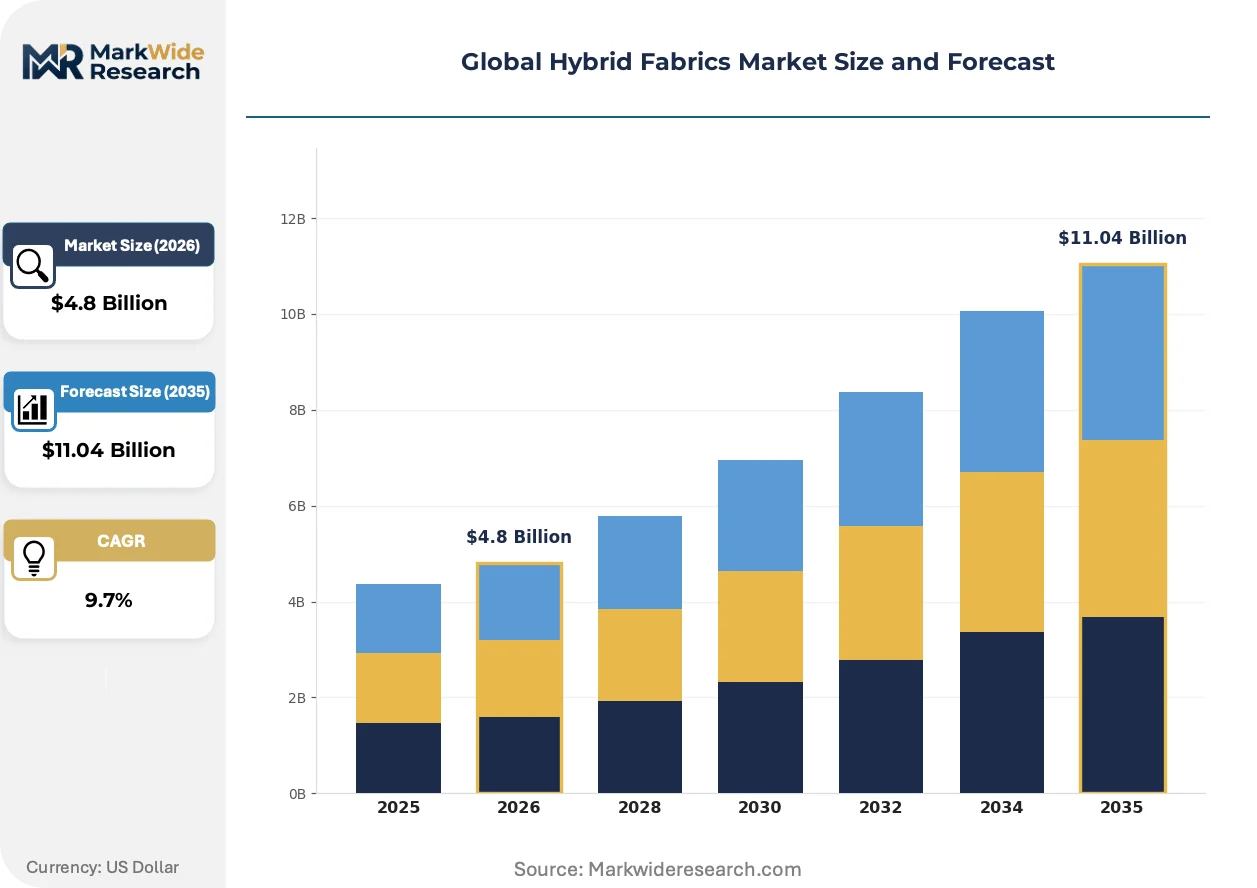
Market Dynamics
EU Green Deal industrial decarbonization mandates are restructuring procurement eligibility for aerospace-grade hybrid fabrics, forcing qualification cycles that favor producers with captive carbon fiber supply chains and integrated AS9100 quality systems.
Growth Catalysts
- Automotive lightweighting mandates:China's SAMR-enforced GB standards accelerate domestic adoption of carbon-glass hybrid prepregs in electric vehicle structural battery enclosures across eastern coastal provinces.
- Aerospace qualification protocols:FAA airworthiness directives and EASA certification requirements for primary aircraft structures create multi-year barriers that protect incumbent suppliers with established resin-fiber interface data libraries.
- Net-shape preform demand:Automotive and aerospace OEMs seek composite-structured hybrid fabrics that reduce layup labor and scrap rates in high-volume production environments.
Market Restraints
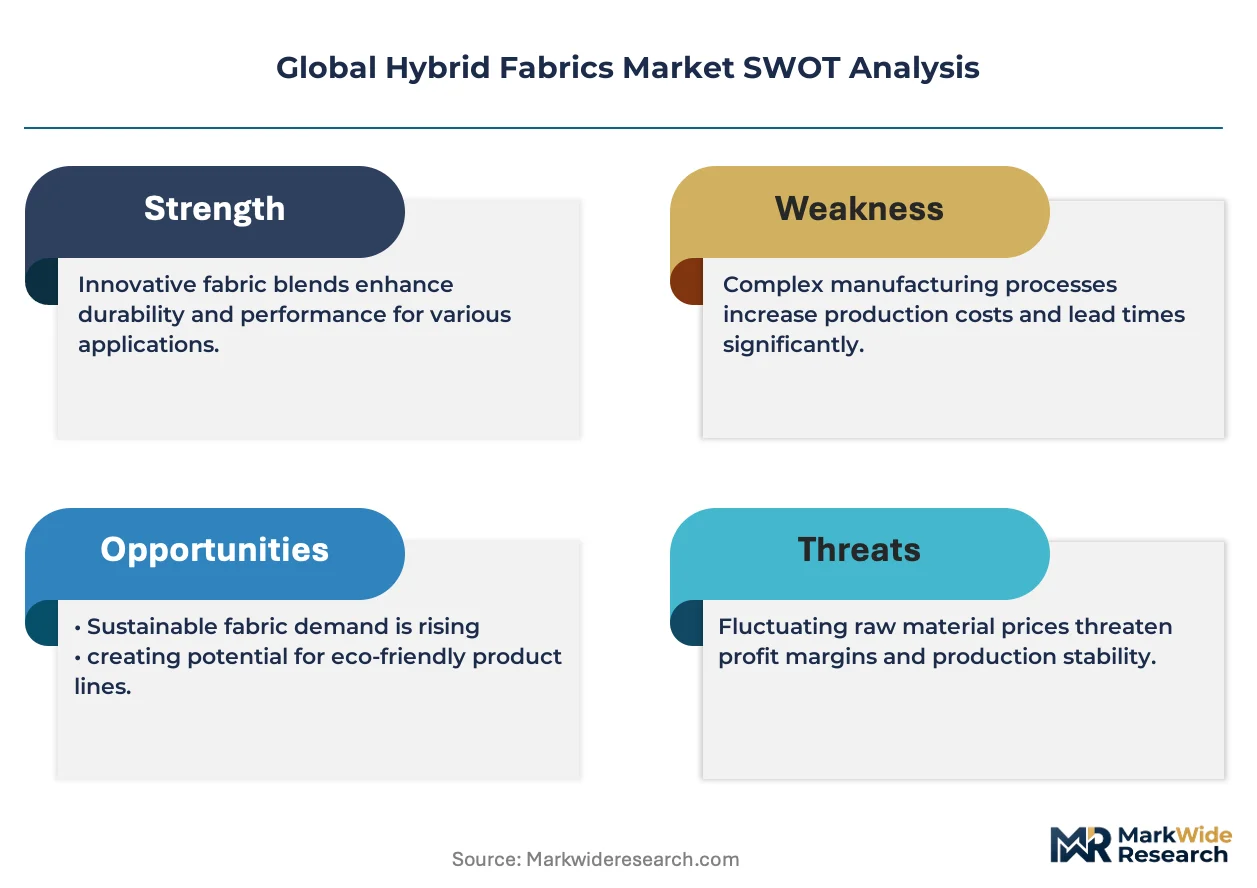
- Precursor fiber cost volatility:Energy-intensive carbon fiber production exposes margins to natural gas and electricity price swings in Germany and Japan.
- Supply concentration risk:Toray Industries and Hexcel Corporation control aerospace-grade carbon fiber tow supply, creating single-source dependencies for hybrid fabric weavers.
- REACH formulation restrictions:ECHA substance restrictions filter epoxy and thermoplastic resin chemistries available to European processors, compressing qualified material portfolios.
Strategic Opportunities
- Underpenetrated industrial filtration:Non-woven hybrid configurations for high-temperature filtration remain underserved in India's petrochemical corridor around Vadodara and Dahej.
- CSRD disclosure tailwinds:Corporate Sustainability Reporting Directive requirements push European automotive OEMs toward documented low-carbon fiber sourcing, favoring suppliers with lifecycle data.
- Aramid-basalt convergence:Ballistic protection manufacturers combine aramid and basalt fibers for enhanced through-thickness energy absorption in multi-hit armor systems.
Industry Challenges
- Multi-year certification timelines:FAA and EASA qualification protocols for primary aircraft structures delay revenue recognition for 3-5 years after initial sample submission.
- Layup automation skill gaps:Net-shape preform production requires robotic fiber placement technicians that aerospace supply chains in France and Germany struggle to recruit.
- Legacy resin system integration:Out-of-autoclave curing workflows clash with established autoclave infrastructure at tier-1 aerostructures suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Fabrics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-Woven, Knitted, Composite End User: Aerospace, Automotive, Sportswear, Construction Application: Protective Clothing, Upholstery, Industrial Textiles, Geotextiles Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Toray Industries, Inc., Hexcel Corporation, Solvay, SGL Carbon, Teijin Limited, DuPont, DSM, Avient Corporation, Gurit Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Fabrics Market Emerging Trajectories
Automated fiber placement and thermoplastic welding are compressing production cycles for hybrid fabric composites, while regulatory carbon accounting forces material provenance documentation upstream to precursor fiber production.
Multiaxial non-crimp fabrics with z-axis stitching are displacing traditional woven prepregs in wind turbine blade root sections and aerospace control surfaces. Vestas and Siemens Gamesa specify these architectures for improved damage tolerance under cyclic loading. The shift is displacing established 2D weaving equipment investments at tier-2 textile converters.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in foaming agents and blowing processes for hybrid fabric sandwich cores. Automotive seating and interior panel suppliers face reformulation deadlines that compress qualification windows. German OEMs are responding by consolidating supplier panels to processors with demonstrated low-GWP material compliance.
Buyers are consolidating supplier relationships around full-service material qualification partners rather than commodity fabric vendors. Tier-1 aerostructures suppliers in Toulouse and Hamburg now require resin transfer molding simulation support and structural test data packages as standard procurement terms. This concentration is most visible in France's aerospace cluster, where Safran and Airbus have reduced qualified hybrid fabric sources by 40 percent since 2020.
Global Hybrid Fabrics Market Segmentation
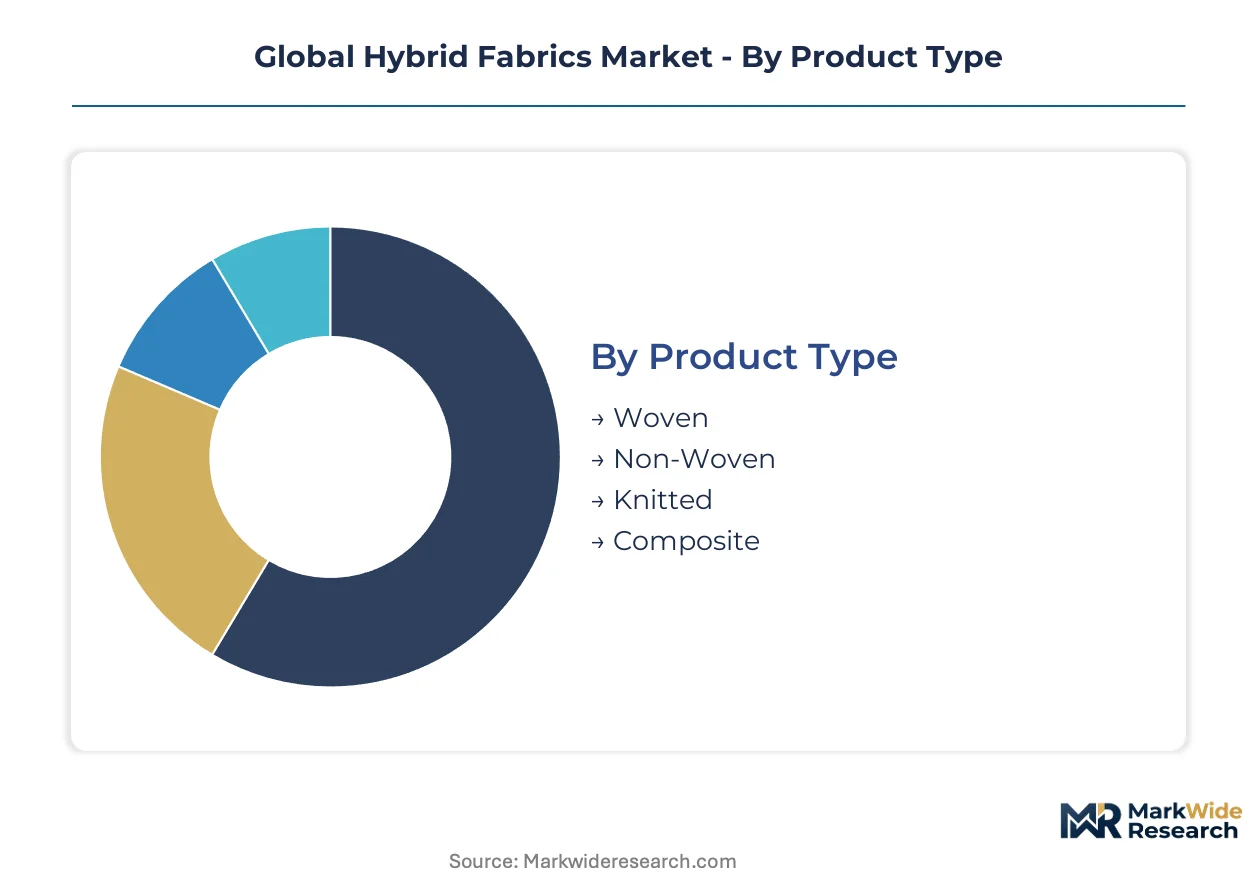
Segmentation in hybrid fabrics reflects divergent technical requirements across load-bearing versus aesthetic applications. Material architecture, end-use performance thresholds, and procurement channel economics each reshape competitive positioning within distinct value pools.
Product Type:
Woven fabrics face intensifying substitution pressure from composite-structured preforms in aerospace and automotive programs seeking labor reduction.
- Woven:Interlaced carbon-glass or aramid-glass architectures deliver predictable mechanical behavior under multi-axial loading. Established processing infrastructure in Germany's textile belt supports qualification-heavy aerospace contracts governed by EASA certification timelines.
- Composite:Net-shape preforms integrate fiber layers with z-axis stitching or resin infusion channels, eliminating manual layup steps. Automotive OEMs in China's eastern coastal provinces specify these for electric vehicle battery enclosures under SAMR-enforced GB lightweighting standards.
- Non-Woven:Random fiber orientation suits filtration media and ballistic protection where through-thickness energy absorption dominates specifications.
- Knitted:Loop-based architectures provide stretch recovery for conformable medical braces and athletic compression garments.
Woven fabrics anchor the volume base while composite configurations gain share at the steepest rate.
End User:
Cost tier stratification separates qualification-intensive aerospace programs from price-sensitive construction commodity purchases.
- Aerospace:Primary aircraft structures demand FAA and EASA certification of resin-fiber interfaces, creating multi-year barriers that protect incumbent suppliers with established data libraries. German and French manufacturers expand carbon-glass hybrid prepreg procurement under EU Green Deal decarbonization mandates.
- Automotive:Structural battery enclosures and crash-absorbing components drive carbon-glass hybrid specification. European OEMs consolidate supplier panels around processors with CSRD-compliant lifecycle documentation.
- Sportswear:Aramid-carbon blends serve high-performance cycling and motorsport protective gear where abrasion resistance meets weight targets.
- Construction:Geotextile and reinforcement applications prioritize cost efficiency over precision engineering, sourcing commodity glass-PP hybrids through distributor networks.
Automotive applications are expanding most quickly as electrification accelerates structural composite penetration, while aerospace retains the highest margin concentration.
Application:
Customer type divergence splits specification-driven industrial buyers from style-conscious consumer markets with divergent technical documentation requirements.
- Industrial Textiles:High-temperature filtration media and process conveyor belts employ non-woven basalt-aramid hybrids. India's petrochemical corridor around Vadodara and Dahej presents underpenetrated demand for these configurations.
- Protective Clothing:Multi-hit ballistic systems combine aramid and basalt fibers for enhanced through-thickness energy absorption, with procurement concentrated in defense and law enforcement channels.
- Geotextiles:Soil stabilization and erosion control deploy commodity glass-polypropylene hybrids through construction distributor networks.
- Upholstery:Aesthetic surface layers in automotive and aviation interiors prioritize drape and color consistency over structural performance.
Industrial textiles anchor the volume base while protective clothing climbs the fastest on defense modernization cycles.
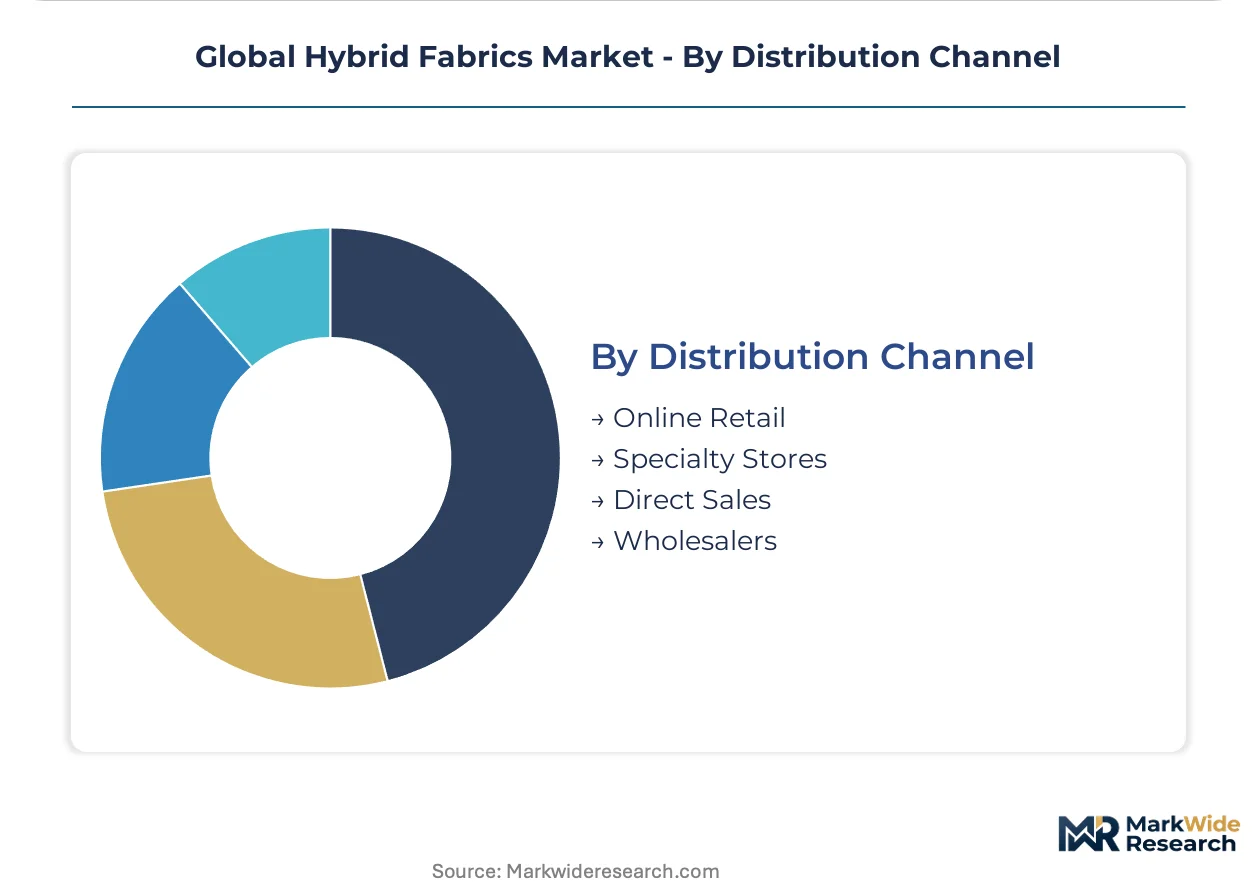
Distribution Channel:
Supply concentration in precursor fiber production shapes channel economics, with direct relationships dominating aerospace and specialty stores serving fragmented industrial buyers.
- Direct Sales:Long-term qualification protocols in Toulouse and Hamburg aerospace clusters lock tier-1 aerostructures suppliers into sole-source or dual-source arrangements with resin transfer molding simulation support.
- Specialty Stores:Regional distributors stock qualified prepregs and fabrics for mid-tier automotive and industrial customers lacking volume for mill-direct procurement.
- Wholesalers:Construction geotextiles and commodity glass fiber products move through broad-line industrial distributors with limited technical service.
- Online Retail:Small-lot specialty fibers and experimental weaves reach research institutions and prototype shops through digital channels.
Direct sales anchor the volume base while specialty stores gain share fastest as mid-tier automotive programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal decarbonization mandates are redirecting aerospace procurement toward qualified carbon-glass hybrid fabric suppliers in Germany and France. China's SAMR-enforced GB standards accelerate domestic lightweighting adoption across eastern coastal manufacturing clusters.
China
SAMR-enforced GB standards for automotive lightweighting drive carbon-glass hybrid prepreg specification in electric vehicle battery enclosures. MIIT dual carbon goals pressure domestic OEMs toward documented low-carbon fiber sourcing. Manufacturing concentrates in Jiangsu and Zhejiang provinces where tier-1 suppliers serve BYD and CATL structural programs.
Germany
EASA certification timelines and EU Green Deal industrial decarbonization mandates expand carbon-glass hybrid procurement for aerospace primary structures. KBA automotive standards push crash-absorbing composite solutions for electric vehicle platforms. Production clusters in Bavaria and Baden-Württemberg anchor Toray and SGL Carbon qualification-heavy supply relationships.
United States
FAA airworthiness directives create multi-year barriers protecting incumbent suppliers with established resin-fiber interface data libraries. EPA emissions standards accelerate hybrid composite adoption in commercial aviation efficiency programs. Aerospace manufacturing concentrates in Washington State and Kansas where Boeing tier-1 suppliers maintain sole-source arrangements.
France
EASA certification requirements and EU F-Gas Regulation phase-down schedules reshape material qualification for Airbus primary structures. CSRD disclosure requirements push documented lifecycle data upstream to precursor fiber production. Toulouse and Nantes aerospace clusters consolidate supplier panels around full-service material qualification partners.
Japan
METI industrial policy supports carbon fiber precursor production for hybrid fabric export markets. JIS standards govern quality management system integration for aerospace-grade textile output. Manufacturing concentrates in Ehime and Aichi prefectures where Toray Industries maintains captive carbon fiber supply chain control.
Global Hybrid Fabrics Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive carbon fiber production. Market structure concentrates around three to four vertically positioned suppliers controlling aerospace-grade tow supply. Strategic archetypes separate carbon fiber originators, specialized composite weavers, and diversified chemical holding companies. Dominant competitive moves include backward integration into precursor production and strategic partnerships for resin system co-development.
Within the integrated chemical conglomerate tier, Toray Industries and Hexcel Corporation occupy positions defined by captive carbon fiber supply chain control. SGL Carbon exemplifies the specialized European automotive-focused archetype. These three entities anchor qualification-heavy supply relationships with tier-1 aerostructures suppliers in Toulouse, Hamburg, and Seattle. Their positioning reflects decades-long protocol adherence rather than transactional commodity supply.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Hexcel Corporation |
| Solvay |
| SGL Carbon |
| Teijin Limited |
| DuPont |
| DSM |
| Avient Corporation |
| Gurit Holding AG |
| Others |
Supply Flow & Price Mechanics
FAA airworthiness directives and EASA certification requirements simultaneously gate supply eligibility and stratify pricing tiers across aerospace-grade hybrid fabric procurement, compressing qualified supplier pools while amplifying premium capture for AS9100-certified incumbents with resin-fiber interface data libraries. This regulatory architecture forces buyers into multi-year qualification cycles that embed certification costs into long-term contract structures, insulating top-tier producers from spot-market volatility while squeezing margin pools for uncertified weavers.
Pricing Analysis
Certification level (AS9100/ISO 9001/EASA-grade) creates the primary spread between premium aerospace contracts and commodity industrial sales. Three-tier pricing structure across aerospace-qualified, automotive-specified, and construction-grade tiers reflects differential qualification burdens and resin system complexity. Cost compression in automotive-specified carbon-glass hybrids is intensifying because SAMR-enforced GB standards proliferate domestic Chinese supply. Construction geotextile buyers exhibit highest price sensitivity, while Toulouse and Hamburg aerospace clusters accept multi-year sole-source premiums for documented airworthiness data.
Supply Chain Analysis
Japan and Germany anchor carbon fiber precursor production for aerospace-grade hybrid fabric output, with Toray Industries in Ehime and SGL Carbon in Bavaria controlling captive tow supply. Manufacturing draws from acrylonitrile feedstock, specialized epoxy resin formulations, and precision weaving equipment concentrated in Baden-Württemberg and Aichi prefecture. Single-source vulnerability runs through Toray and Hexcel Corporation dominance of aerospace-grade carbon fiber tow. Distribution runs through mill-direct relationships for qualified aerospace programs and specialty stores for mid-tier automotive buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern hybrid fabric procurement as Airbus and Safran consolidate supplier panels around full-service material qualification partners rather than commodity vendors, creating interoperability premiums for integrated resin transfer molding simulation and structural test data bundling.
For Market Incumbents: Fortify qualification-heavy supply relationships in Toulouse and Hamburg by deepening captive carbon fiber supply control and accelerating AS9100 recertification ahead of evolving EASA sustainability disclosure requirements. Threat substitution from thermoplastic welding and automated fiber placement demands co-development partnerships with resin system specialists to preserve incumbent positioning in net-shape preform categories. For New Entrants and Emerging Players: Anchor in India's underpenetrated petrochemical filtration corridor around Vadodara and Dahej, where non-woven basalt-aramid configurations for high-temperature media remain underserved by established European and Japanese suppliers. Target mid-tier automotive programs in China's Jiangsu province seeking CSRD-compliant lifecycle documentation for European OEM export qualification, leveraging local MIIT dual carbon policy alignment as market entry wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European automotive-focused hybrid fabric processors lacking aerospace qualification pathways. Long-term viability in this market hinges on backward integration into precursor fiber production or strategic resin system co-development lock-ups. Watch for CSRD disclosure enforcement tightening as the inflection signal favoring suppliers with documented low-carbon fiber provenance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Fiber Production | Toray and Hexcel captive supply control locks in aerospace-grade margin pools against energy cost volatility. |
| AS9100 Recertification Investment | EASA evolving sustainability requirements protect incumbent eligibility for Airbus primary structure contracts. |
| Resin System Co-Development Partnership | Specialized epoxy and thermoplastic formulations differentiate composite-structured preform offerings for automotive OEMs. |
| Net-Shape Preform Capacity Expansion | BYD and CATL structural battery enclosure demand in Jiangsu province accelerates labor-reduction adoption. |
| CSRD-Compliant Lifecycle Documentation | European automotive OEM procurement consolidation favors suppliers with verified low-carbon fiber sourcing data. |
Methodological Framework
A spread of perspectives from aerospace procurement directors at tier-1 aerostructures suppliers, automotive platform engineers specifying battery enclosures, textile plant managers in Germany's Baden-Württemberg cluster, and resin system technical directors converged on the working assumptions driving segmentation splits. Secondary validation drew from EASA certification filings, FAA airworthiness directives, SAMR GB standard publications, SEC 10-K disclosures from listed chemical conglomerates, and customs trade data tracking carbon fiber tow imports. Bottom-up volume builds across end-use applications triangulated against top-down macroeconomic drivers to constrain forecast variance.
Product type, end user industry, application category, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by qualification timeline constraints and regional regulatory enforcement intensity. Industry-specific forecast inputs included EASA certification backlog durations, MIIT dual carbon policy implementation pacing, and REACH formulation restriction evolution affecting qualified resin chemistries.
Material uncertainties — precursor fiber energy cost volatility, multi-year FAA/EASA qualification timeline extensions, and CSRD disclosure requirement enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and aerospace production rate recovery. Recalibration cycles align with material shifts in EU Green Deal industrial decarbonization mandate implementation and SAMR GB standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
E-Textile Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Construction Textile Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Technical Textile Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Webbing Market
Technical Textiles
Military Textile Materials Testing Market