
 Italy Textile Manufacturing Market | 2026-2036
Italy Textile Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Textile Manufacturing Market Foresight
EU Green Deal textile sustainability mandates is restructuring capital allocation across Italian mills, forcing upgrades in wastewater recovery and chemical traceability systems. RadiciGroup leverages its vertically integrated nylon operations to meet recycled-content thresholds ahead of compliance deadlines. Albini Group anchors premium shirting production through direct control of Egyptian long-staple cotton sourcing. Candiani Denim differentiates via proprietary dyeing processes that slash water intensity in its Biellese facilities.
Italy textile manufacturing encompasses the mechanical or chemical transformation of natural and synthetic fibers into yarns, fabrics, and finished textiles, spanning processes from spinning and weaving to dyeing, printing, and technical finishing with specifications often requiring Oeko-Tex Standard 100 or GOTS certification for export eligibility. These outputs serve apparel, automotive interiors, medical filtration, and industrial reinforcement applications where performance-to-weight ratios and tactile properties determine commercial viability. Woven fabrics still dominate value capture in luxury apparel supply chains, while technical textiles represent the fastest-expanding margin pool as automotive and medical OEMs source ballistic-grade and antimicrobial substrates from Como-area specialists. Non-woven fabrics remain comparatively mature in Italy, concentrated in hygiene and filtration applications with limited pricing power against Eastern European competitors.
Italy's Ministry of Enterprise and Made in Italy (MIMIT) enforces origin labeling under Law 55/2019, while REACH and the EU Textile Strategy regulate chemical inputs and extended producer responsibility obligations across the sector. BIS-equivalent conformity assessments for export markets add compliance layers for firms serving Middle Eastern and Asian buyers. Stakeholders must monitor how upcoming digital product passport requirements reshape traceability investments and supplier qualification protocols.
Market Dynamics
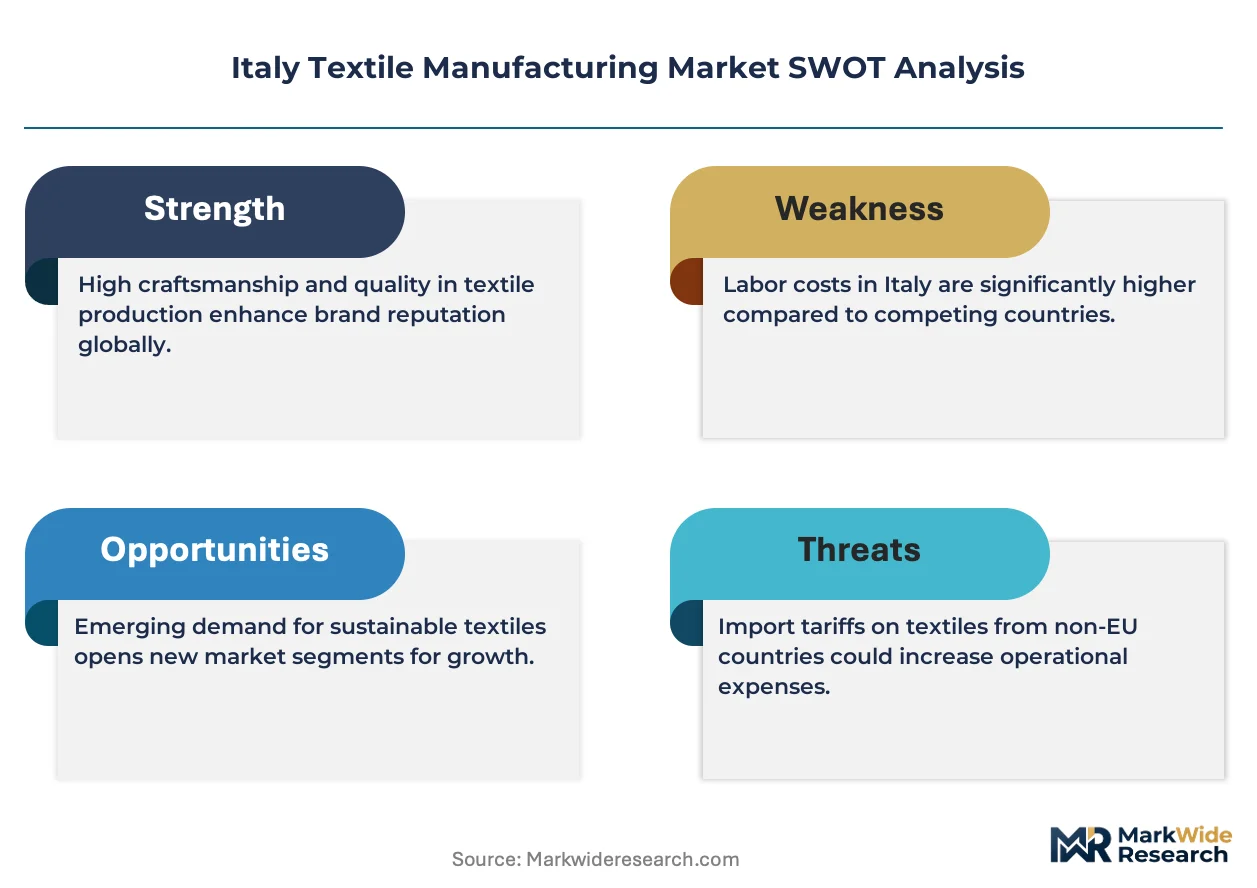
The EU Green Deal's textile sustainability mandates are restructuring capital allocation across Italian mills, forcing urgent upgrades in wastewater recovery, chemical traceability, and recycled-content compliance systems ahead of binding deadlines.
Growth Catalysts
- EU Green Deal textile requirements:Binding recycled-content thresholds and extended producer responsibility obligations are pulling investment into bio-based fiber production and closed-loop dyeing systems across Piedmont and Lombardy.
- Automotive technical fabrics:Luxury EV manufacturers in Germany and domestic marques are expanding procurement of Italian-made ballistic-grade and antimicrobial substrates for interior applications.
- Biella-Como cluster concentration:Specialized wool finishing and silk processing capabilities in northern Italy continue to capture premium apparel supply chain volumes that Eastern European competitors cannot replicate.
Market Restraints
- Energy input cost volatility:Natural gas and electricity price swings in Italy compress operating margins for energy-intensive dyeing and finishing operations, particularly in smaller Como-area mills.
- Raw material import dependence:Egyptian long-staple cotton, Australian merino wool, and Chinese synthetic fiber feedstocks create currency and logistics exposure that domestic spinning operations cannot hedge fully.
- REACH chemical compliance friction:ECHA substance restrictions on certain dyes and finishing agents force reformulation cycles that delay product certification for export markets.
Strategic Opportunities
- Medical filtration substrates:Post-pandemic hospital procurement protocols in Italy and adjacent EU markets are creating demand for antimicrobial non-woven fabrics that Como specialists can supply at premium pricing.
- Digital product passport readiness:Early compliance with upcoming EU traceability mandates positions Italian mills as qualified suppliers for sustainability-focused luxury houses seeking supply chain transparency.
- Blockchain-IoT convergence:Integration of distributed ledger verification with production floor sensors enables real-time origin certification that commands pricing premiums in Japanese and South Korean export markets.
Industry Challenges
- Specialized finishing technician scarcity:Retirement waves among master dyers in the Biella district outpace vocational training pipeline output, constraining capacity expansion for heritage wool processing.
- GOTS-Oeko-Tex dual certification timelines:Parallel audit requirements for organic and safety standards extend qualification periods for new supplier relationships, delaying revenue recognition.
- Legacy ERP integration friction:Digital product passport data architecture must interface with decades-old mill management systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Textile Manufacturing Market |
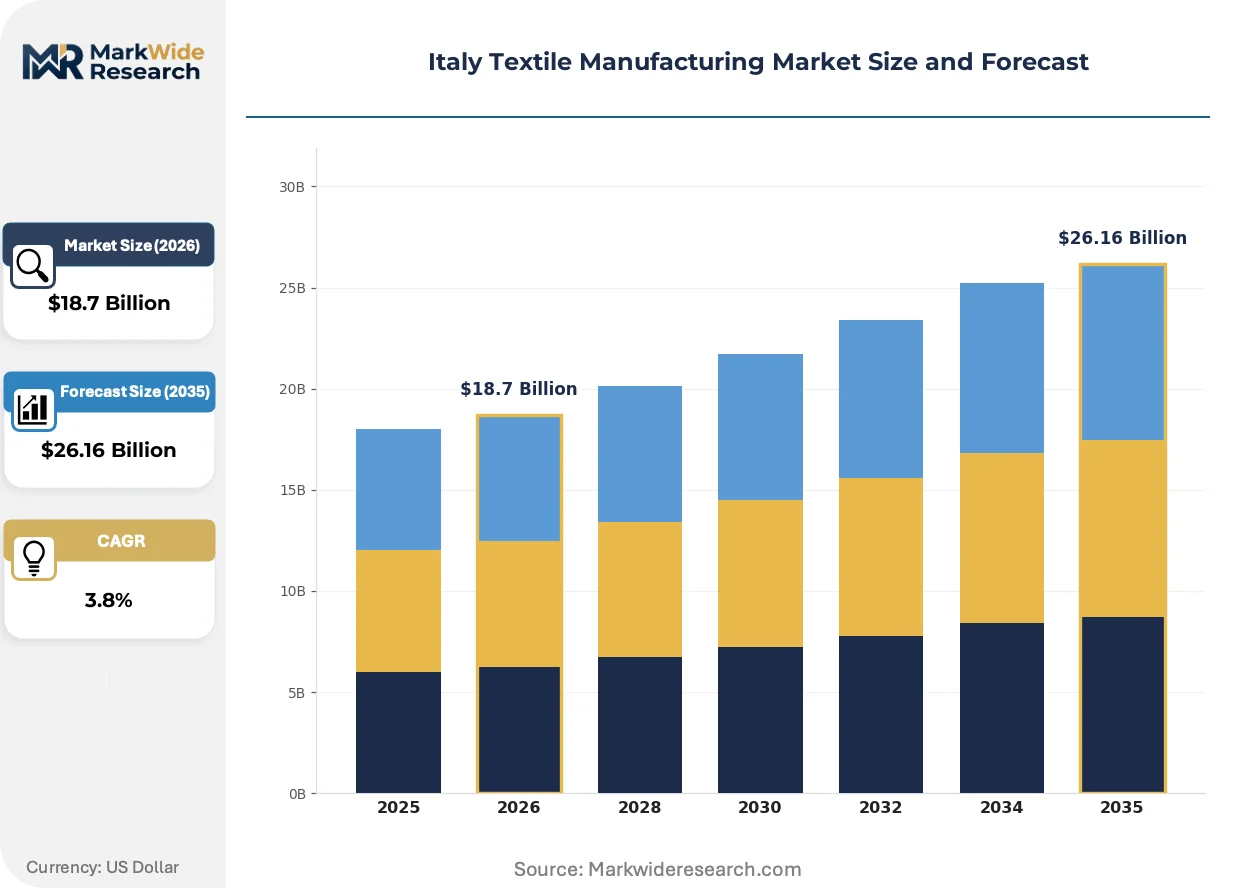
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Non-woven Fabrics, Technical Textiles Application: Apparel, Home Textiles, Industrial Textiles, Automotive Textiles End User: Fashion Brands, Interior Designers, Manufacturers, Retailers Distribution Channel: Online Retail, Direct Sales, Wholesale Distributors, Specialty Stores |
| Companies Covered | RadiciGroup, Aquafil S.p.A., Marzotto Group, Piacenza Group, Ratti S.p.A., Albini Group, Candiani Denim, OVS Group, Miroglio Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Textile Manufacturing Market Shifts & Advancements
Italian textile manufacturing is experiencing a technology-driven capability divergence, where sustainability-linked process innovation separates investable assets from stranded capacity in a market tightening under regulatory pressure.
Plasma-based waterless dyeing is electrifying coloration economics in denim and technical fabric segments. Candiani Denim and select Biellese operators have adopted atmospheric plasma systems that eliminate water baths entirely. Automotive interior suppliers are qualifying these substrates for volume programs, compressing the competitive window for conventional wet-processing competitors who face escalating water discharge compliance costs.
REACH authorization requirements for persistent organic pollutants in textile auxiliaries are forcing reformulation of softeners and flame retardants across the sector. Chemical suppliers must pre-register substitute substances through ECHA, creating a twelve-to-eighteen month lag before mills can certify compliant finished goods. Medical and children's apparel segments, where Oeko-Tex Standard 100 certification is mandatory, are absorbing these transition costs fastest.
Direct mill-to-brand procurement contracts are displacing traditional commission-agent intermediaries in premium shirting and suiting categories. Albini Group and comparable vertically integrated producers now manage Egyptian cotton sourcing, weaving, and finishing under single-entity contracts with Milan and Paris luxury houses. This channel compression is most visible in the made-to-measure segment, where lead time guarantees and lot traceability requirements exceed agent-managed supply chain capabilities.
Italy Textile Manufacturing Market Segmentation
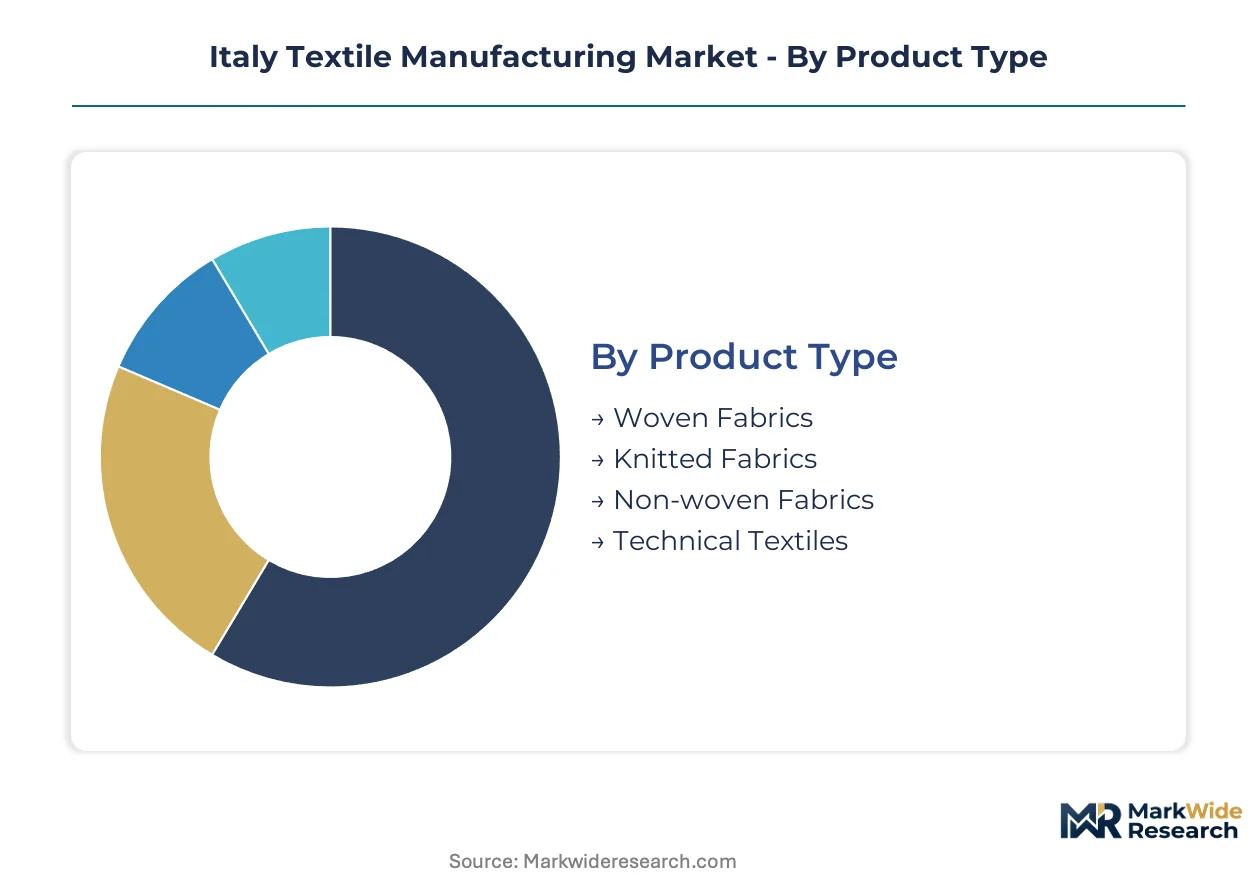
Italian textile manufacturing divides across multiple dimensions that determine sourcing economics and regulatory exposure. Product type governs capital intensity and sustainability compliance burdens. Application and end-user channels dictate margin structures and certification requirements.
Product Type:
Buyers prioritize performance-to-weight ratios and tactile specifications when selecting fabric constructions for their supply chains.
- Woven Fabrics:Interlaced warp and weft constructions deliver structural integrity and dimensional stability required in luxury suiting and shirting. Milan and Florence fashion houses source premium woven substrates from Biella-area mills where heritage finishing techniques command pricing premiums against Eastern European alternatives.
- Technical Textiles:Engineered substrates including ballistic-grade reinforcements and antimicrobial filtration media serve automotive interiors and medical applications. Como-area specialists capture expanding procurement volumes from German luxury EV manufacturers seeking Italian-made performance fabrics with traceable supply chains.
- Knitted Fabrics:Loop-structured constructions provide elasticity and comfort in casual apparel and activewear segments.
- Non-woven Fabrics:Bonded fiber webs dominate hygiene and medical filtration applications with limited differentiation against lower-cost regional competitors.
Volume sits with Woven Fabrics; growth tilts toward Technical Textiles.
Application:
End-use specifications determine Oeko-Tex and GOTS certification requirements that filter supplier qualification.
- Apparel:Finished garments and cut-and-sew operations absorb the majority of Italian fabric output, with luxury menswear and womenswear commanding the highest value per meter. Direct mill-to-brand procurement contracts are displacing traditional commission-agent intermediaries as traceability mandates tighten.
- Automotive Textiles:Interior upholstery, headliners, and reinforcement substrates require flame-retardant and abrasion-resistant specifications that Italian mills meet through proprietary finishing processes. REACH chemical compliance for persistent organic pollutants creates qualification barriers that protect established Biellese suppliers.
- Home Textiles:Decorative and functional fabrics for residential and hospitality interiors.
- Industrial Textiles:Conveyor belts, geotextiles, and composite reinforcements serving non-apparel manufacturing sectors.
Revenue concentrates in Apparel; Automotive Textiles are expanding most quickly.
End User:
Procurement scale and technical sophistication separate volume buyers from specification-driven niche purchasers.
- Fashion Brands:Luxury houses and contemporary labels drive demand for certified sustainable fabrics with documented origin chains. Albini Group and comparable vertically integrated producers now manage Egyptian cotton sourcing through single-entity contracts that guarantee lot traceability.
- Manufacturers:Tier-one suppliers and cut-and-sew contractors purchase greige and finished fabrics for conversion into final products.
- Interior Designers:Specification professionals curating textile selections for residential and commercial projects.
- Retailers:Mass-market and specialty chains sourcing private-label textile products.
Transaction volume favors Manufacturers; margin capture concentrates with Fashion Brands.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to production clusters.
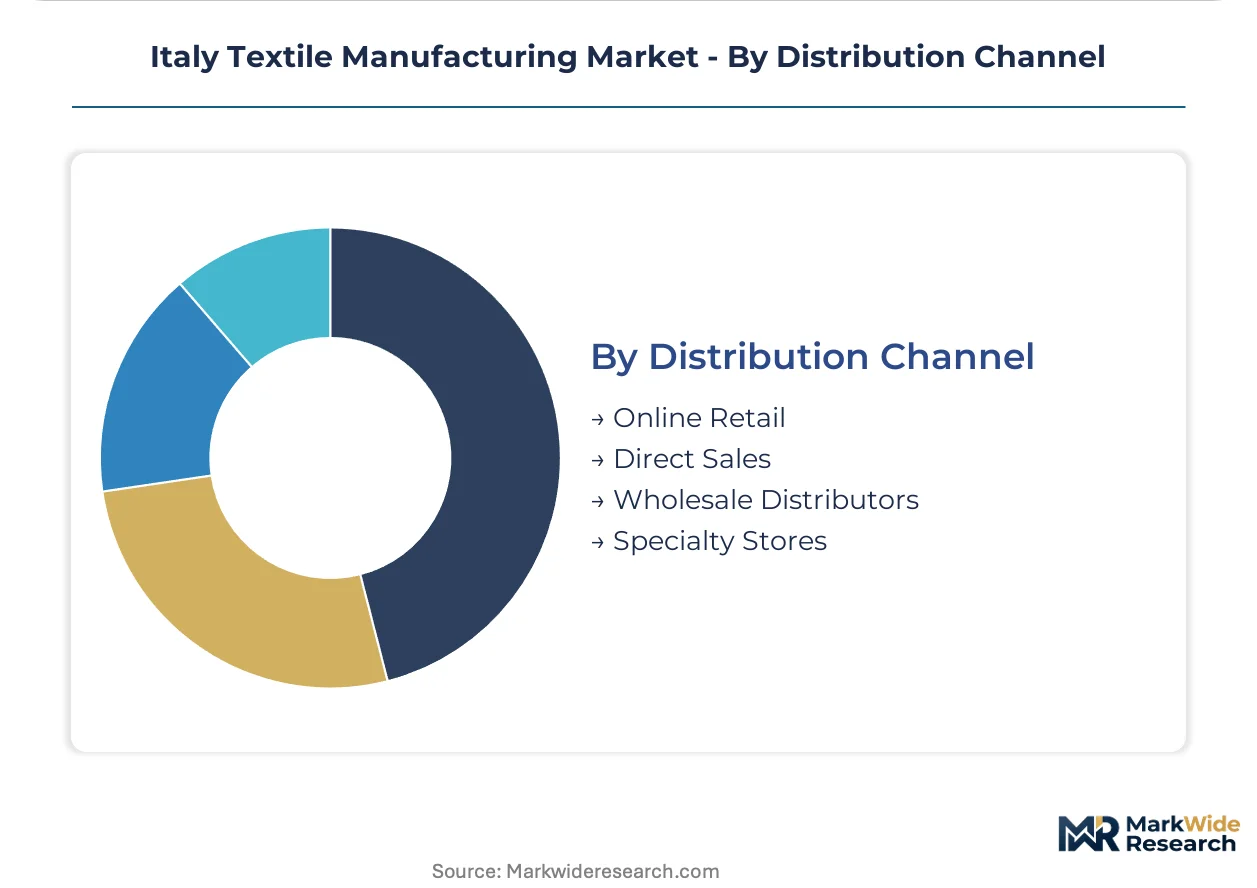
- Direct Sales:Mill-direct relationships dominate premium apparel and automotive procurement where technical collaboration and lead time guarantees outweigh price sensitivity. Candiani Denim and RadiciGroup leverage direct channels to enforce recycled-content compliance ahead of EU Green Deal deadlines.
- Wholesale Distributors:Inventory-keeping intermediaries serve smaller fashion brands and regional manufacturers lacking minimum order volumes for direct mill relationships.
- Online Retail:Digital platforms enabling spot purchasing of standard specifications.
- Specialty Stores:Curated physical retail targeting artisan and craft segments.
Order value concentrates in Direct Sales; channel expansion favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zona Franca Special Economic Zones in northern Italy concentrate the highest-value textile operations through tax-advantaged status and infrastructure proximity. The Biella-Como corridor anchors premium wool and silk finishing capabilities that luxury supply chains cannot replicate elsewhere.
Piedmont
Biella's heritage wool mills supply Milan fashion houses with traceable merino substrates. The region qualifies for EU Just Transition Mechanism funding as it decarbonizes dyeing operations. Candiani Denim operates plasma-based finishing facilities in the Cittadellarte complex.
Lombardy
Como's silk weavers and technical fabric specialists serve German automotive OEMs with ballistic-grade interior substrates. MIMIT enforces Law 55/2019 origin labeling from Milan headquarters. RadiciGroup runs vertically integrated nylon operations across Bergamo and Lecco provinces.
Veneto
Prosecco-adjacent textile districts supply home furnishing and apparel substrates to Austrian and German buyers. The region accesses EU Recovery and Resilience Facility grants for wastewater recovery upgrades. Treviso-area mills specialize in technical non-wovens for medical filtration.
Emilia-Romagna
Carpi's knitwear industrial district feeds fast-fashion supply chains with rapid-turnaround jersey production. Regional energy transition mandates under the Italian National Recovery Plan accelerate gas-to-electric dyeing conversions. Modena hosts prototyping facilities for automotive textile suppliers.
Tuscany
Prato's regenerated wool cluster processes post-industrial fiber waste into premium recycled yarns. The circular district model predates EU Green Deal mandates by decades. Local consortia manage chemical traceability pools that simplify REACH compliance for smaller finishers.
Italy Textile Manufacturing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's textile manufacturing base. The sector exhibits tiered concentration where vertically integrated groups control premium apparel supply chains while smaller mills serve spot markets. Three archetypes dominate: chemical fiber integrators, heritage wool finishers, and denim process innovators. Competitive moves center on backward integration into raw material sourcing and strategic partnerships with luxury fashion houses for digital passport compliance.
Among chemical fiber specialists, RadiciGroup and Aquafil S.p.A. occupy positions exemplifying recycled-content vertical integration. Heritage wool finishers include Marzotto Group and Piacenza Group, representing archetypes of family-controlled premium substrate production. Candiani Denim anchors the process innovation tier through proprietary waterless coloration technology. These named entities illustrate competitive positioning without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| RadiciGroup |
| Aquafil S.p.A. |
| Marzotto Group |
| Piacenza Group |
| Ratti S.p.A. |
| Albini Group |
| Candiani Denim |
| OVS Group |
| Miroglio Group |
| Others |
Supply & Pricing Matrix
Plasma-based waterless dyeing adoption in Biella and Como mills compresses production timelines while concentrating premium capacity among early technology adopters. Candiani Denim and select Biellese operators now command pricing premiums as conventional wet-processing competitors face escalating water discharge compliance costs that erode margin structures.
Pricing Analysis
Lead-time guarantees drive pricing stratification across Italian textile procurement, with made-to-measure contracts commanding substantial premiums over spot inventory transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, where GOTS-Oeko-Tex dual-certified substrates capture highest value. Pricing pressure stems from natural gas and electricity volatility compressing margins for energy-intensive dyeing operations. Small Como-area mills exhibit highest price sensitivity, while vertically integrated groups serving Milan luxury houses maintain pricing power through captive cotton sourcing and proprietary finishing.
Supply Chain Analysis
Regional distribution centers in Milan and Bergamo anchor hub-and-spoke patterns for German automotive OEMs and Paris fashion houses seeking consolidated Italian textile procurement. Supply concentration centers on Egypt for long-staple cotton, Australia for merino wool, and China for synthetic fiber feedstocks. Raw material dependencies create currency exposure that domestic spinning operations cannot fully hedge. Single-source vulnerability in Egyptian cotton channels threatens continuity for premium shirting producers. Distribution runs through direct mill-to-brand contracts displacing traditional commission-agent intermediaries in traceability-mandated segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy textile manufacturing market is accelerating into a vertical-integration race where upstream fiber control and downstream brand partnerships determine competitive viability. Players are pursuing captive supply of Egyptian cotton and Australian wool as the decisive lever for margin defense.
For Market Incumbents: Anticipate REACH authorization delays for substitute textile auxiliaries by accelerating pre-registration timelines with ECHA and building twelve-month inventory buffers for critical finishing agents. Secure backward integration into bio-based fiber production ahead of EU Green Deal recycled-content thresholds. Defend Biella-Como cluster positioning through apprenticeship pipeline investments that counter master dyer retirement waves.
For New Entrants and Emerging Players: Blockchain-IoT convergence platforms for real-time origin certification offer a technology-first wedge into Japanese and South Korean export markets where traceability premiums exceed domestic European benchmarks. Target medical filtration substrates in Veneto and Lombardy where post-pandemic hospital procurement protocols favor antimicrobial non-woven specialists. Pursue digital product passport compliance as the qualifying gate for sustainability-focused luxury house supplier status.
For Investors and Strategic Acquirers: Re-rating potential sits with heritage wool finishers possessing plasma dyeing capabilities given EU wastewater recovery mandates accelerating stranded asset risk for conventional wet processors. Long-term viability across the analysis window favors vertically integrated groups with captive raw material sourcing and direct brand relationships. Monitor ECHA substance restriction announcements as the inflection signal for chemical reformulation cost waves and certification timeline disruptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | Captive supply of Egyptian cotton insulates Albini Group and comparable producers from currency volatility and logistics disruption. |
| Plasma-Based Waterless Dyeing Adoption | Atmospheric plasma systems at Candiani Denim eliminate water discharge compliance costs while qualifying for automotive interior volume programs. |
| Digital Product Passport Readiness | Early EU traceability compliance positions Italian mills as qualified suppliers for sustainability-focused luxury houses seeking supply chain transparency. |
| Apprenticeship Pipeline Investment | Biella district vocational programs counter retirement waves among master dyers that constrain heritage wool processing capacity expansion. |
| REACH Pre-Registration Acceleration | ECHA substance pre-registration for substitute auxiliaries compresses twelve-to-eighteen month certification lags before compliant finished goods qualification. |
Research Methodology
Document review covered MIMIT regulatory filings, ECHA substance restriction announcements, EU Green Deal textile strategy documentation, and Italian National Recovery Plan energy transition mandates, complemented by interviews with mill operations directors, luxury house procurement leads, chemical supplier technical directors, and automotive interior sourcing managers. Secondary validation drew from customs trade data, SEC filings for listed textile groups, and Oeko-Tex certification registry databases. Bottom-up capacity assessments across Piedmont, Lombardy, Veneto, Emilia-Romagna, and Tuscany regions were triangulated against top-down demand projections from apparel and automotive end-use segments.
Segmentation outputs across product type, application, end user, and distribution channel dimensions were generated through the projection horizon using econometric modeling of input cost trajectories and regulatory compliance burden shifts. CAGRs were derived from trend extrapolation of historical investment patterns and announced capacity additions. Industry-specific forecast inputs included natural gas price volatility scenarios, REACH authorization timelines for textile auxiliaries, and digital product passport implementation schedules.
Several conditions sit outside the modeled scope, including unannounced MIMIT regulatory amendments, abrupt ECHA substance bans, and geopolitical disruptions to Egyptian cotton or Australian wool channels. Forecasts reflect documented assumptions regarding EU Green Deal enforcement timelines and vocational training pipeline recovery rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Silica Yarn Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Denim Fabric Market