
 US Geotextile Market | 2026-2036
US Geotextile Market Size, Share, and Industry Trends Forecast 2026-2036
US Geotextile Market Insights
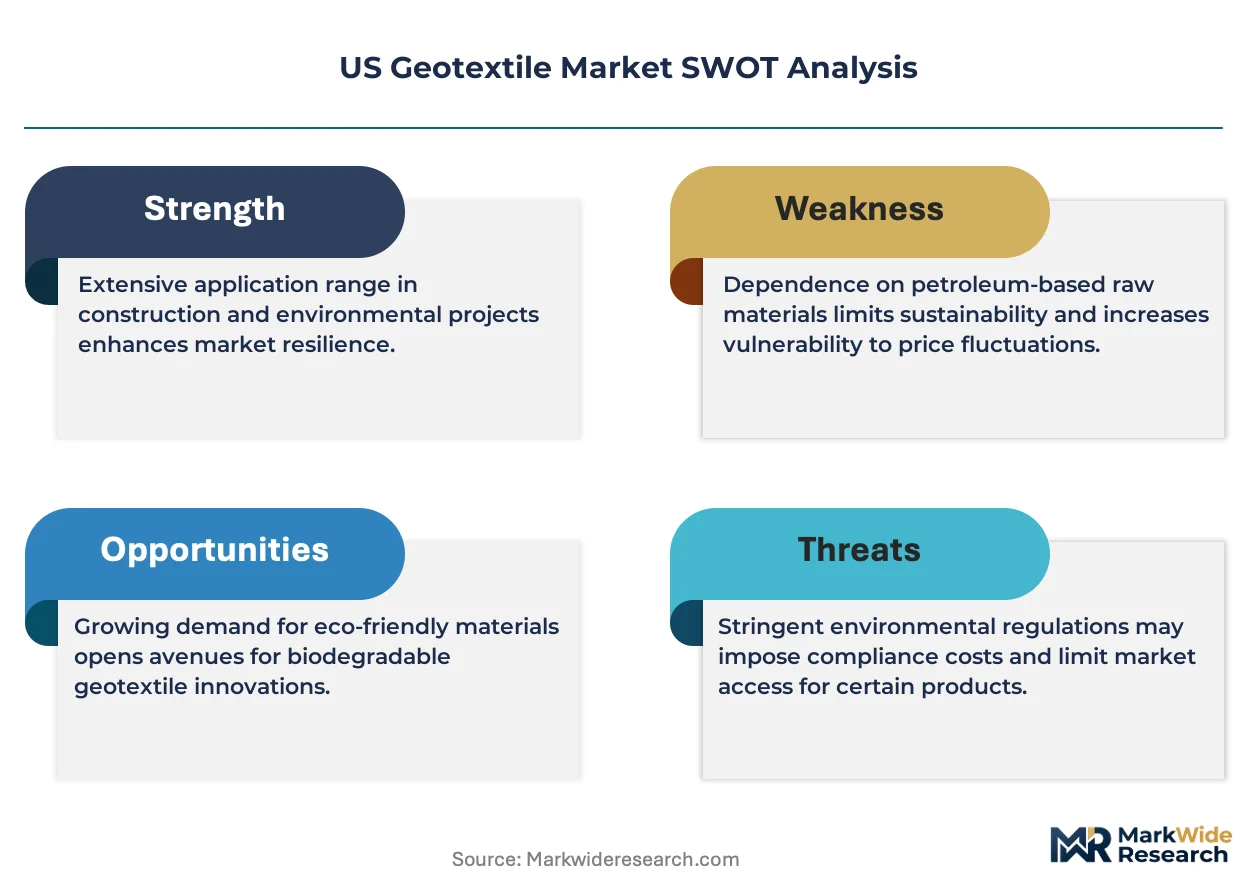
The Infrastructure Investment and Jobs Act is broadening the cost-of-entry calculus for geotextile suppliers bidding on federal transportation contracts. TYPAR Geosynthetics leverages its domestic manufacturing footprint to anchor supply agreements with state DOTs across the Southeast. Belton Industries competes through specialized woven products for coastal erosion control. SKAPS Industries differentiates via vertical control over polypropylene resin sourcing.
Geotextiles are permeable synthetic fabrics engineered from polypropylene or polyester fibers, manufactured through weaving, needle-punching, or heat-bonding processes to achieve specified tensile strengths, puncture resistance, and flow rates for civil engineering applications. Their primary commercial purpose is to separate, filter, reinforce, protect, or drain soils in infrastructure and environmental containment systems. Non-woven geotextiles lead volume due to lower unit costs and simpler deployment in drainage and filtration, while woven products command premium positioning in soil stabilization where tensile modulus requirements are stringent. Composite materials represent the fastest-expanding segment as engineers specify multi-function geosynthetics combining drainage cores with filtration layers for landfill and mining applications.
FHWA design standards, AASHTO material specifications, and EPA stormwater management rules collectively shape product certification requirements and procurement protocols for geotextile installations on federally funded projects. State DOTs in California, Texas, and Florida enforce supplemental testing protocols that exceed national minimums, creating regional compliance tiers that filter supplier participation. Stakeholders must monitor pending updates to AASHTO M-288 specifications and state-level Buy America content thresholds that will determine qualification for infrastructure spending pipelines.
Market Dynamics
Federal infrastructure spending is concentrating geotextile procurement around state DOTs with accelerated project timelines, compressing supplier qualification windows and amplifying compliance-driven vendor selection.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal highway rehabilitation programs are expanding specification volumes for separation and reinforcement applications across state transportation departments.
- Texas and California highway rehabilitation:State DOTs in these jurisdictions are accelerating bid releases for erosion control and subgrade stabilization projects requiring certified geosynthetics.
- Needle-punched non-woven manufacturing:Process improvements in fiber entanglement are reducing unit costs for drainage and filtration specifications in landfill liner systems.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to petrochemical supply chains compress margin predictability for domestic converters.
- Mid-Atlantic manufacturing concentration:Production capacity clusters in Georgia and the Carolinas create regional supply vulnerability to hurricane disruption.
- EPA stormwater performance thresholds:Tightening effluent quality mandates extend product development cycles and certification timelines.
Strategic Opportunities
- Florida coastal resilience programs:State-funded beach nourishment and seawall reconstruction projects are expanding specification opportunities for high-strength woven products.
- Composite geosynthetics:Multi-function materials combining drainage cores with filtration layers are displacing single-layer specifications in mining heap leach pads.
- Buy America content thresholds:Pending federal domestic content requirements will advantage suppliers with captive resin sourcing and domestic manufacturing footprints.
Industry Challenges
- Geotechnical engineer shortage:Limited availability of certified field installation supervisors delays project commissioning and increases warranty exposure.
- AASHTO M-288 certification backlog:Third-party testing laboratory capacity constraints extend product qualification timelines for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Geotextile Market |
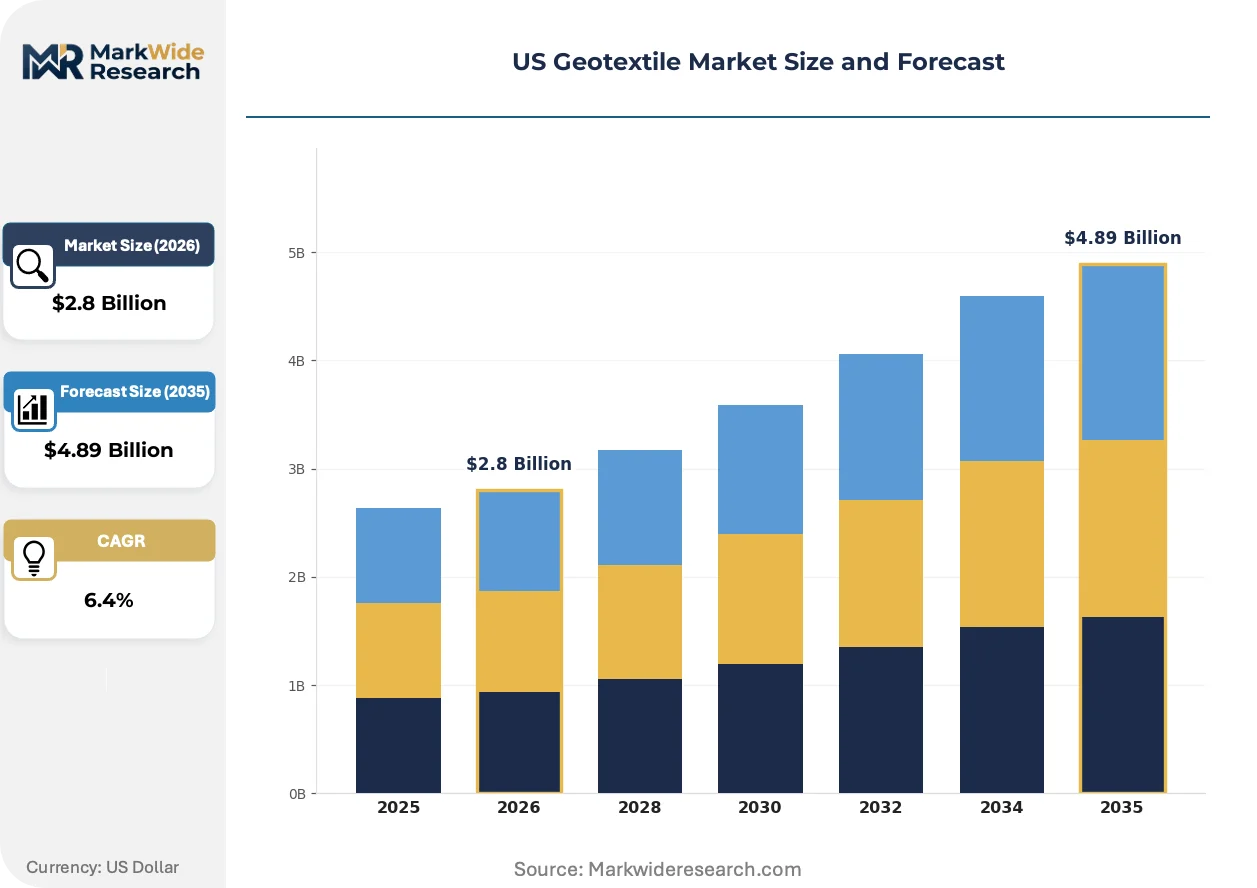
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-Woven, Knitted, Composite Material: Polypropylene, Polyester, Natural Fibers, Nylon Application: Drainage, Erosion Control, Soil Stabilization, Reinforcement End User: Construction, Agriculture, Environmental, Transportation |
| Companies Covered | TYPAR Geosynthetics, Belton Industries, AGRU America, Inc., SKAPS Industries, TenCate Geosynthetics, HUESKER International, GSE Environmental, Solmax International, Inc., Thrace Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Geotextile Market Trends and Innovations
Material science advances and procurement digitization are compressing traditional specification cycles while elevating performance verification requirements across federal and state-funded infrastructure.
Recycled polypropylene feedstocks are electrifying sustainability positioning in highway construction. State DOTs in California and New York are piloting specifications with post-consumer content minimums. This shift is electrifying competitive differentiation for suppliers with verified circular supply chains.
EPA stormwater regulations are tightening material performance requirements for filtration efficiency and long-term durability. Industrial consequence includes mandatory third-party verification for projects receiving federal funding. Landfill liner and mining containment specifications are most affected, with engineers now requiring 100-year design life documentation.
State DOT procurement portals are consolidating vendor pre-qualification into centralized digital platforms. Regional distributors are losing specification influence as engineers direct-buy through approved manufacturer lists. Texas and Florida transportation departments are most advanced in this transition, with California DOT following in 2025.
US Geotextile Market Segmentation
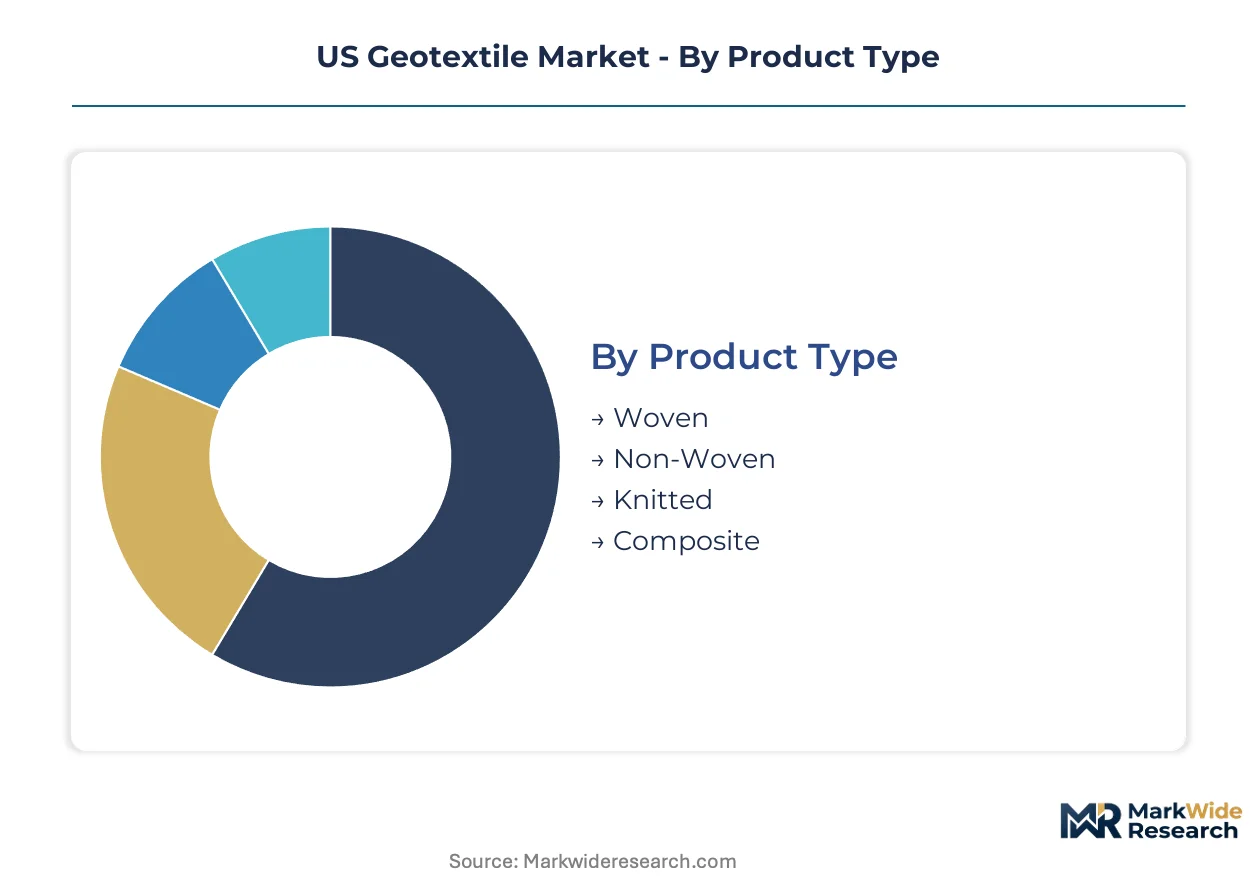
Geotextile procurement patterns diverge sharply across product architecture, feedstock chemistry, and project-scale deployment requirements. Specification engineers weight tensile modulus, permeability coefficients, and installation labor differently depending on infrastructure type and environmental exposure severity.
Product Type:
Production capacity clusters around needle-punching and weaving technologies, with composite manufacturing requiring specialized lamination equipment that limits supplier participation.
- Non-Woven:Needle-punched or heat-bonded polypropylene fibers deliver high permeability at lower unit cost. Texas DOT drainage specifications and California landfill liner projects concentrate demand for this segment, with FHWA M-288 certification shortening vendor qualification cycles.
- Woven:Monofilament or multifilament weaving yields precise tensile strength and dimensional stability. Highway subgrade stabilization across Florida DOT projects and coastal armoring in the Carolinas drive specification volume, where load-bearing requirements exclude non-woven alternatives.
- Knitted:Interlocking loop structures provide multidirectional stretch recovery for turf reinforcement and green infrastructure applications.
- Composite:Bonded drainage cores with geotextile filtration layers serve mining heap leach pads and double-lined landfill systems requiring hydraulic transmissivity verification.
Non-woven geotextiles absorb the bulk of installed capacity; composite materials are expanding most quickly.
Material:
Feedstock selection determines UV resistance, chemical compatibility, and compliance with state-level recycled content mandates.
- Polypropylene:Dominates volume through melt-spun fiber production with superior acid resistance and specific gravity below water for marine deployment. Texas and California DOT specifications standardize on this resin, though Gulf Coast petrochemical supply concentration exposes converters to hurricane disruption risk.
- Polyester:Higher tensile modulus and creep resistance suit permanent soil reinforcement in mechanically stabilized earth walls. Virginia and Pennsylvania transportation projects specify polyester for 75-year design life requirements.
- Natural Fibers:Jute and coir provide biodegradable erosion control for short-term slope stabilization until vegetation establishment.
- Nylon:Superior abrasion resistance serves dynamic loading applications in rail ballast separation and heavy haul road construction.
Polypropylene commands the largest production footprint; polyester is climbing the fastest specification trajectory.
Application:
Engineering function dictates product form, with separation and filtration tolerating lighter specifications than reinforcement or containment.
- Drainage:Permeable geotextiles wrapped around aggregate or installed as standalone filtration layers manage subsurface water in roadway edge drains and sports field subbases. EPA stormwater regulations are tightening effluent quality thresholds for these installations.
- Soil Stabilization:High-strength woven products reinforce soft subgrades beneath embankments and access roads. Louisiana and Mississippi coastal highway reconstruction programs are accelerating bid releases for this application.
- Erosion Control:Temporary and permanent turf reinforcement matrices protect disturbed slopes until root systems mature.
- Reinforcement:Geotextiles integrated with fill materials create composite structures bearing tensile loads in retaining walls and steepened slopes.
Drainage applications absorb the bulk of specification volume; soil stabilization is gaining share fastest.
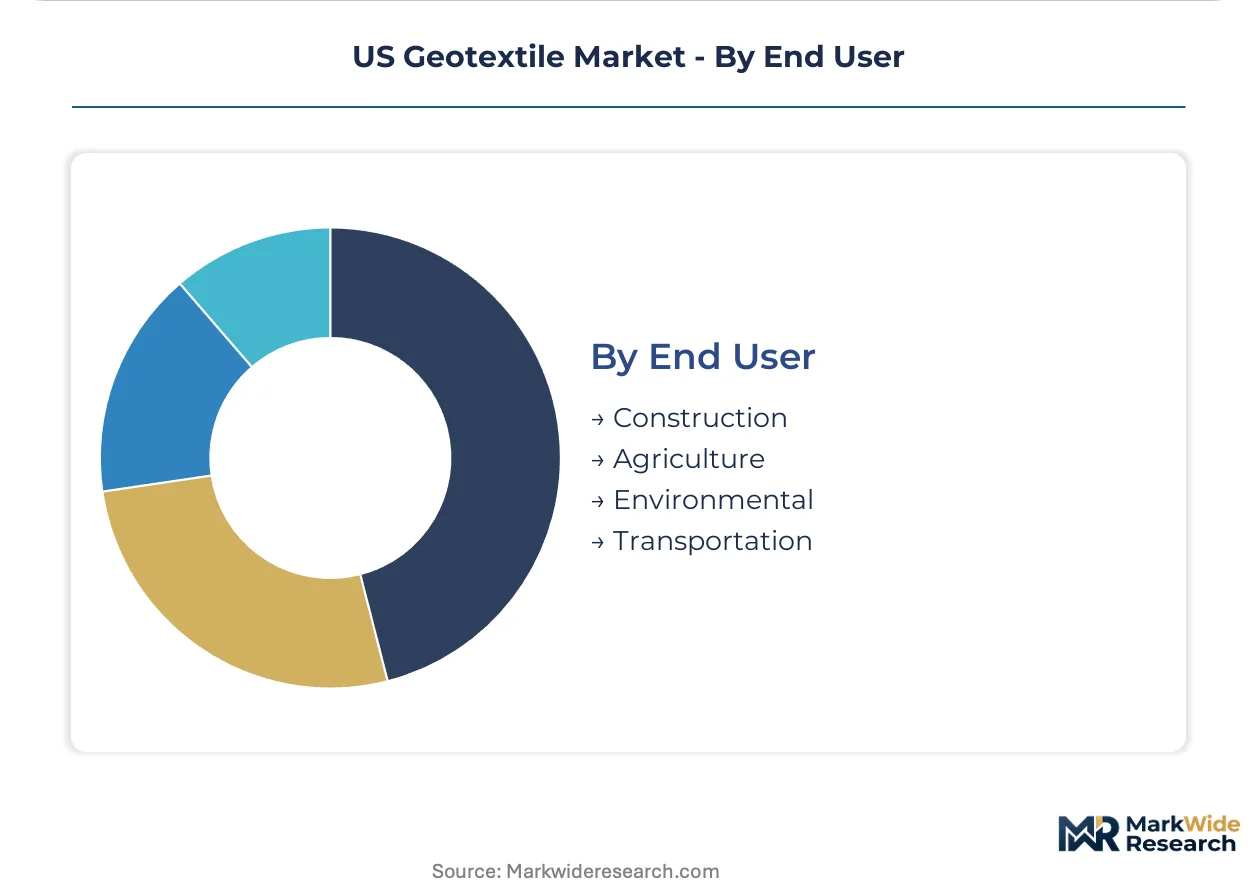
End User:
Procurement scale and compliance rigor vary dramatically across customer categories, with federal funding streams concentrating vendor relationships.
- Transportation:State DOTs and federal highway programs dominate specification volume through AASHTO-compliant material certifications. Infrastructure Investment and Jobs Act disbursements are compressing supplier qualification windows for separation and reinforcement products.
- Construction:Commercial developers and residential builders specify geotextiles for foundation drainage and sediment control, with less stringent certification requirements than transportation infrastructure.
- Environmental:Landfill operators and remediation contractors require 100-year design life documentation and third-party verification under EPA Subtitle D regulations.
- Agriculture:Farm pond liners, drainage tile envelopes, and livestock containment represent fragmented, price-sensitive procurement with limited certification overhead.
Transportation absorbs the bulk of qualified supplier capacity; environmental end users are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and California are concentrating geotextile demand through accelerated highway rehabilitation programs. Federal infrastructure disbursements flow disproportionately to states with active DOT bid pipelines.
Texas
Texas DOT's $18 billion highway reconstruction program is releasing separation and reinforcement specifications at compressed intervals. EPA stormwater regulations mandate third-party filtration verification for federally funded erosion control projects. Manufacturing clusters in Houston and Dallas-Fort Worth are expanding needle-punched non-woven capacity to serve Permian Basin mining containment demand.
California
Caltrans' coastal highway resilience initiatives are specifying high-strength woven products for subgrade stabilization. State-level recycled content mandates are filtering supplier participation toward converters with verified circular feedstock chains. Production facilities in the Central Valley are retooling for composite geosynthetic lamination to meet landfill liner requirements.
Florida
Florida DOT's beach nourishment and seawall reconstruction programs are expanding specification volumes for coastal armoring applications. State procurement portals are consolidating vendor pre-qualification into centralized digital platforms. Manufacturing presence in the Tampa-Orlando corridor is capturing specification flow from Southeast DOT coordination agreements.
Georgia and the Carolinas
Mid-Atlantic manufacturing concentration creates regional supply vulnerability to hurricane disruption. FHWA design standards and AASHTO M-288 specifications shape product certification requirements for federally funded installations. Charleston and Savannah port infrastructure supports resin import logistics for polypropylene fiber production serving the Southeast.
Louisiana and Mississippi
Coastal highway reconstruction programs are accelerating bid releases for soil stabilization applications. State DOTs enforce supplemental testing protocols that exceed national minimums, creating compliance tiers that filter supplier participation. Baton Rouge industrial corridors host resin conversion facilities supplying regional geotextile weavers.
US Geotextile Market Competitive Landscape
Southeast producers anchor one tier; Mid-Atlantic specialists hold specification influence in coastal erosion control. The vendor base organizes around three strategic archetypes: domestic manufacturers with captive resin sourcing, regional converters serving state DOT procurement portals, and composite specialists targeting mining and landfill containment. Capacity expansion and backward integration into polypropylene resin supply represent the dominant competitive moves as Buy America content thresholds tighten.
Among domestic manufacturing anchors, TYPAR Geosynthetics, Belton Industries, and SKAPS Industries exemplify distinct positioning strategies. TYPAR leverages its Southeast footprint to anchor state DOT supply agreements. Belton occupies a position within specialized woven product tiers for coastal applications. SKAPS exemplifies upstream control over feedstock chemistry through captive resin relationships. These three represent archetype diversity across the supplier landscape.
| Leading Market Players |
|---|
| TYPAR Geosynthetics |
| Belton Industries |
| AGRU America, Inc. |
| SKAPS Industries |
| TenCate Geosynthetics |
| HUESKER International |
| GSE Environmental |
| Solmax International, Inc. |
| Thrace Group |
| Others |
Pricing and Supply Chain Analysis
Geotechnical engineer shortages in the Mid-Atlantic and Gulf Coast regions widen labor-cost differentials between premium certified-installation tiers and economy-grade spot-market products. This workforce compression stratifies pricing spreads as DOTs pay premiums for qualified field supervisors while commercial developers accept lower-tier alternatives.
Pricing Analysis
Lead-time premiums dominate contract structures, with state DOTs paying 15-25% markups for guaranteed delivery within compressed project windows while spot inventory clears at discounts. Pricing stratifies across AASHTO M-288 certified premium tiers, standard FHWA-compliant mid-tiers, and economy non-certified grades. Cost compression in economy tiers is intensifying because polypropylene resin volatility squeezes converter margins. Commercial construction buyers exhibit highest price sensitivity; environmental containment contractors show least sensitivity due to 100-year design life requirements.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast petrochemical complexes supplying polypropylene resin feedstock. Manufacturing draws from Georgia, the Carolinas, and Texas, with resin conversion tethered to Houston and Baton Rouge chemical corridors. Hurricane exposure represents the dominant structural risk, capable of disrupting both raw material flows and finished goods distribution. Distribution runs through state DOT procurement portals consolidating vendor pre-qualification, bypassing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive resin sourcing and domestic manufacturing footprints as Buy America thresholds filter out import-dependent players. Federal infrastructure disbursement velocity accelerates this winnowing.
For Market Incumbents: Extend backward integration into polypropylene resin supply to secure qualification under pending domestic content rules. Anchor capacity expansion in Texas and Florida to capture DOT procurement portal specification flow. Certify composite geosynthetic portfolios ahead of AASHTO M-288 updates to preempt new entrant qualification. For New Entrants and Emerging Players: State DOT digital procurement portals offer the most penetrable route for specification influence without legacy distributor relationships. Target environmental containment applications where 100-year design life documentation requirements create specialist barriers. Lead with recycled polypropylene feedstocks to differentiate in California and New York pilot programs. For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with verified circular supply chains and Southeast manufacturing footprints. Five-to-ten-year viability hinges on Buy America compliance positioning rather than scale alone. Monitor AASHTO M-288 certification backlog resolution as the inflection signal for new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing secures Buy America qualification for federal DOT contracts. |
| Composite Geosynthetic Certification | AASHTO M-288 compliance opens mining heap leach and double-lined landfill specifications. |
| Recycled Feedstock Verification | Post-consumer content chains meet California and New York state DOT pilot requirements. |
| Digital Procurement Portal Registration | Texas and Florida DOT platform inclusion displaces traditional distributor intermediation. |
| Southeast Manufacturing Expansion | Georgia and Florida capacity anchors supply agreements with hurricane-vulnerable Mid-Atlantic states. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with state DOT procurement officers, geotechnical engineering consultants, resin conversion plant managers, and environmental containment contractors. AASHTO specification databases, EPA stormwater compliance filings, FHWA project award records, and polypropylene import manifests provided validation layers. Bottom-up project pipeline analysis triangulated against top-down manufacturing capacity estimates.
Data-stream reconciliation across the analysis window modeled volume and value outputs through product type, material chemistry, application function, and end-user procurement scale. CAGRs derived from segment-level growth rate distributions weighted by federal infrastructure disbursement schedules and state DOT bid release calendars. Resin price elasticity coefficients and certification timeline distributions informed composite geosynthetic adoption curves.
The model holds under steady federal infrastructure disbursement velocity and stable petrochemical supply; deviation in hurricane frequency or Buy America threshold acceleration would shift outcomes. Forecasts embed assumptions regarding AASHTO specification update timing and state DOT digital procurement adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Technical Textile Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
E-Textile Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Webbing Market