
 Silk Stocking Market | 2026-2036
Silk Stocking Market Size, Share, and Industry Trends Forecast 2026-2036
Silk Stocking Market Insights
A capital-intensity divergence between integrated cocoon processors and pure downstream weavers is redrawing competitive boundaries in silk hosiery. Sichuan Nanchong Liuhe leverages captive sericulture operations across Sichuan basin farms to secure mulberry silk filament supply. Jiangsu Sutong Cocoon & Silk anchors its position through proprietary reeling technology that reduces filament breakage during stocking knit preparation. LilySilk differentiates via direct-to-consumer channel control, bypassing traditional wholesale markup structures in North American and European markets.
Silk stockings are sheer-to-opaque leg coverings knitted from continuous mulberry silk filament yarns, typically measuring 10-20 denier for sheer grades and 40-80 denier for opaque constructions, prized for moisture-wicking, thermoregulation, and reduced skin friction versus synthetic alternatives. The sheer segment dominates unit volume in temperate climate markets where lightweight hosiery extends seasonal wearability, while opaque grades command premium positioning in professional and cold-weather applications. Online retail channels are capturing disproportionate growth in customer acquisition, though specialty boutiques retain margin concentration through personalized fitting services and exclusive colorway distribution.
REACH compliance through ECHA governs azo dye and formaldehyde residue limits in silk stockings distributed across European markets, while China's GB standards under SAMR mandate fiber content labeling accuracy and restrict harmful substance thresholds in domestic circulation. Fashion professionals and procurement teams must monitor evolving extended producer responsibility frameworks in France and Germany, where textile waste collection mandates are beginning to encompass hosiery categories previously exempt from circular economy obligations.
Market Dynamics
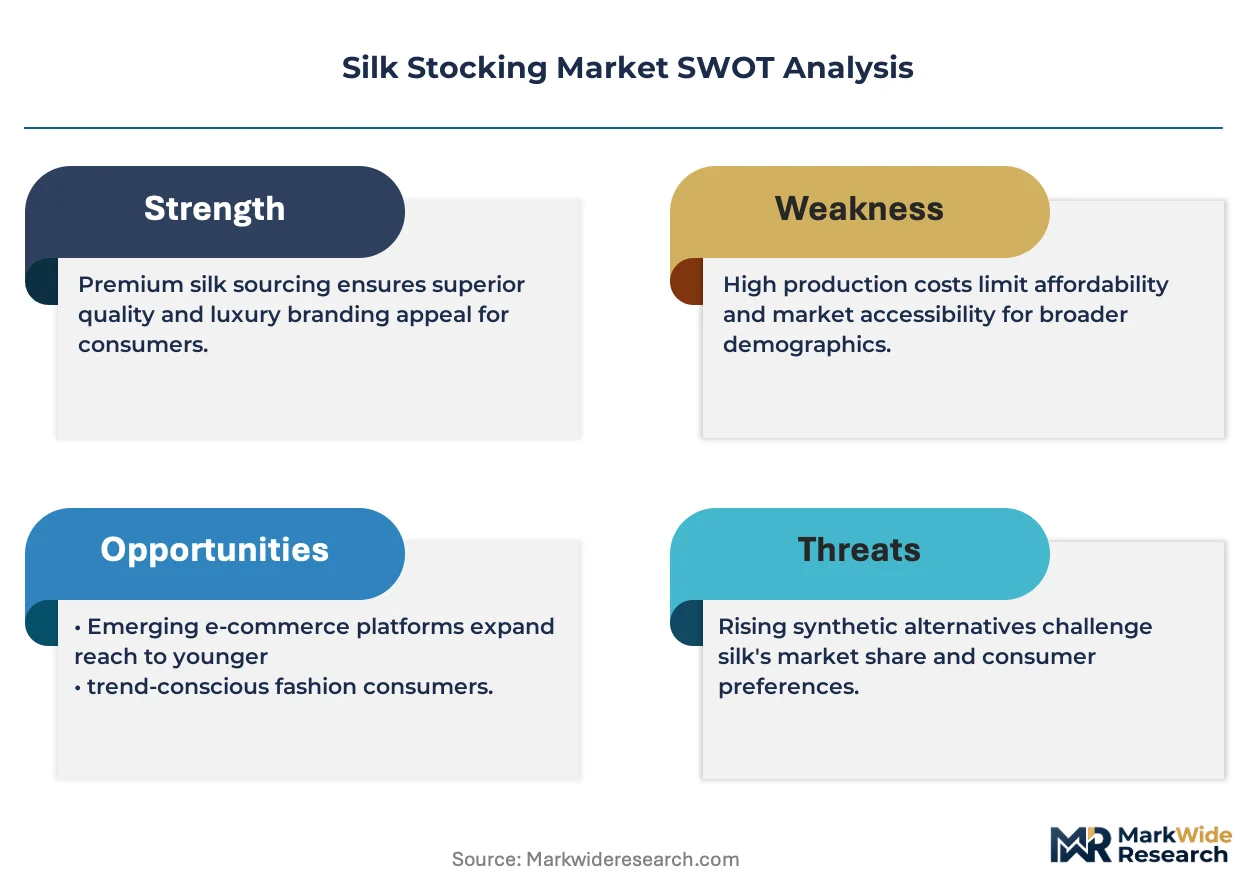
REACH chemical compliance through ECHA is tightening azo dye and formaldehyde residue thresholds, forcing silk suppliers to requalify filament batches and extend certification timelines before European distribution.
Growth Catalysts
- EU Textile Sustainability Standards:Extended producer responsibility frameworks in France and Germany now mandate hosiery collection, creating circular economy infrastructure that premium silk brands leverage for differentiation.
- Metropolitan Fashion Corridors:Luxury hosiery adoption concentrates in urban retail clusters where personalized fitting services and exclusive colorways command sustained margin premiums over mass channels.
- Mulberry Sericulture Clusters:Zhejiang and Jiangsu province processing capacity anchors raw silk supply, with captive cocoon operations reducing filament breakage rates during reeling preparation.
Market Restraints
- Raw Material Volatility:Bombyx mori cocoon harvests fluctuate with temperature anomalies across Sichuan basin farms, compressing processor margins when reeling yields drop below standard filament lengths.
- Geographic Supply Concentration:Over 70 percent of continuous filament reeling capacity sits within 200 kilometers of Hangzhou, exposing downstream weavers to localized logistics disruptions and quality variance.
- Synthetic Substitution Pressure:Microfiber nylon alternatives achieve comparable sheerness at 15-20 percent of silk unit economics, displacing volume in price-sensitive temperate climate segments.
Strategic Opportunities
- Direct-to-Consumer Channel Control:Bypassing wholesale markup structures in North American markets allows proprietary brands to capture full margin and build first-party customer data assets.
- Cold-Weather Opaque Grades:40-80 denier constructions command premium positioning in professional applications where thermoregulation properties justify unit price premiums over sheer alternatives.
- Online Retail Acquisition:Digital channels disproportionately attract fashion enthusiasts seeking extended size ranges and subscription replenishment models unavailable through specialty boutiques.
Industry Challenges
- Reeling Technician Scarcity:Traditional silk reeling requires ten-plus years of apprenticeship to minimize filament breakage during cocoon unwinding, with retiring master craftspeople outnumbering entrants across Jiangsu training institutes.
- Dual Certification Burden:Simultaneous compliance with REACH azo dye limits and China's GB 18401 harmful substance thresholds extends batch release timelines by four to six weeks for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silk Stocking Market |
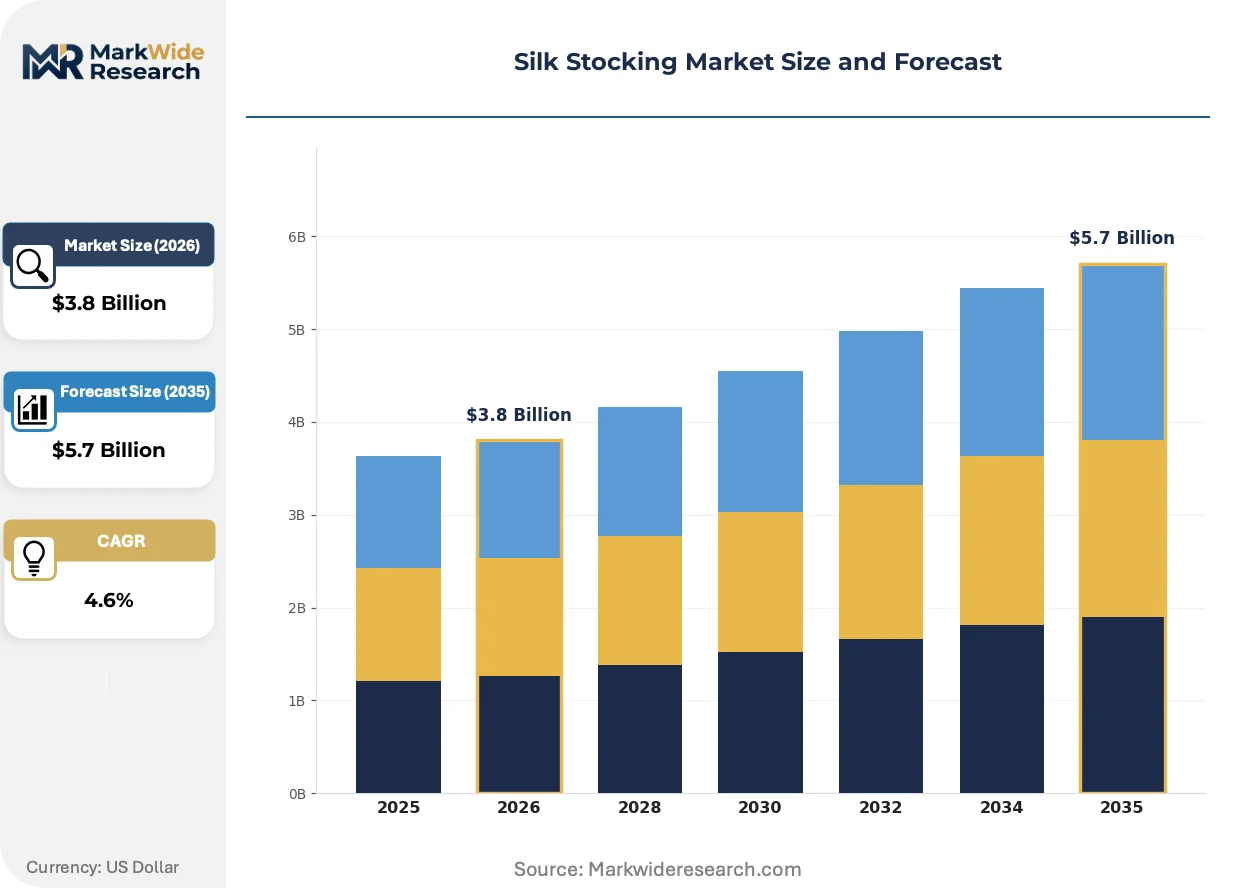
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheer, Opaque, Knee-high, Thigh-high Distribution Channel: Online Retail, Department Stores, Specialty Boutiques, Offline Retail Price Tier: Luxury, Mid-range, Budget, Discount Customer Type: Fashion Enthusiasts, Everyday Consumers, Professionals, Others |
| Companies Covered | Sichuan Nanchong Liuhe, Jiangsu Sutong Cocoon & Silk, Anhui Silk, LilySilk, Jinchengjiang Xinxing Cocoon Silk, Wujiang First Textile, Shengkun Silk, Silkua, Zhejiang Jiaxin Silk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silk Stocking Market Trends and Innovations
Digital sampling and AI-driven color matching are compressing new product development cycles, while regulatory fragmentation between EU circular economy mandates and Asian production standards is reshaping supply chain governance.
Automated circular knitting machines with real-time tension monitoring are displacing manual loom operations in sheer stocking production. Luxury hosiery specialists in Italian manufacturing clusters adopt these systems to achieve consistent 10-15 denier constructions without skilled operator intervention. The technology is displacing traditional piece-rate workshops that previously dominated small-batch premium output.
ECHA's 2023 update to REACH Annex XVII restricted substance lists added formaldehyde release limits for textiles in direct skin contact, including silk hosiery categories. European distributors now require third-party testing documentation from Zhejiang reeling facilities before customs clearance. Opaque grade processors face the steepest compliance burden due to dye fixation chemistry requirements in heavier constructions.
Specialty boutiques are unbundling fitting services from product margins, charging consultation fees separate from stocking purchases. This model spreads across Paris and Tokyo fashion districts where personalized measurement and seasonal colorway curation justify service premiums. North American online retailers respond with virtual try-on tools and free return policies to replicate the boutique experience without physical presence.
Silk Stocking Market Segmentation
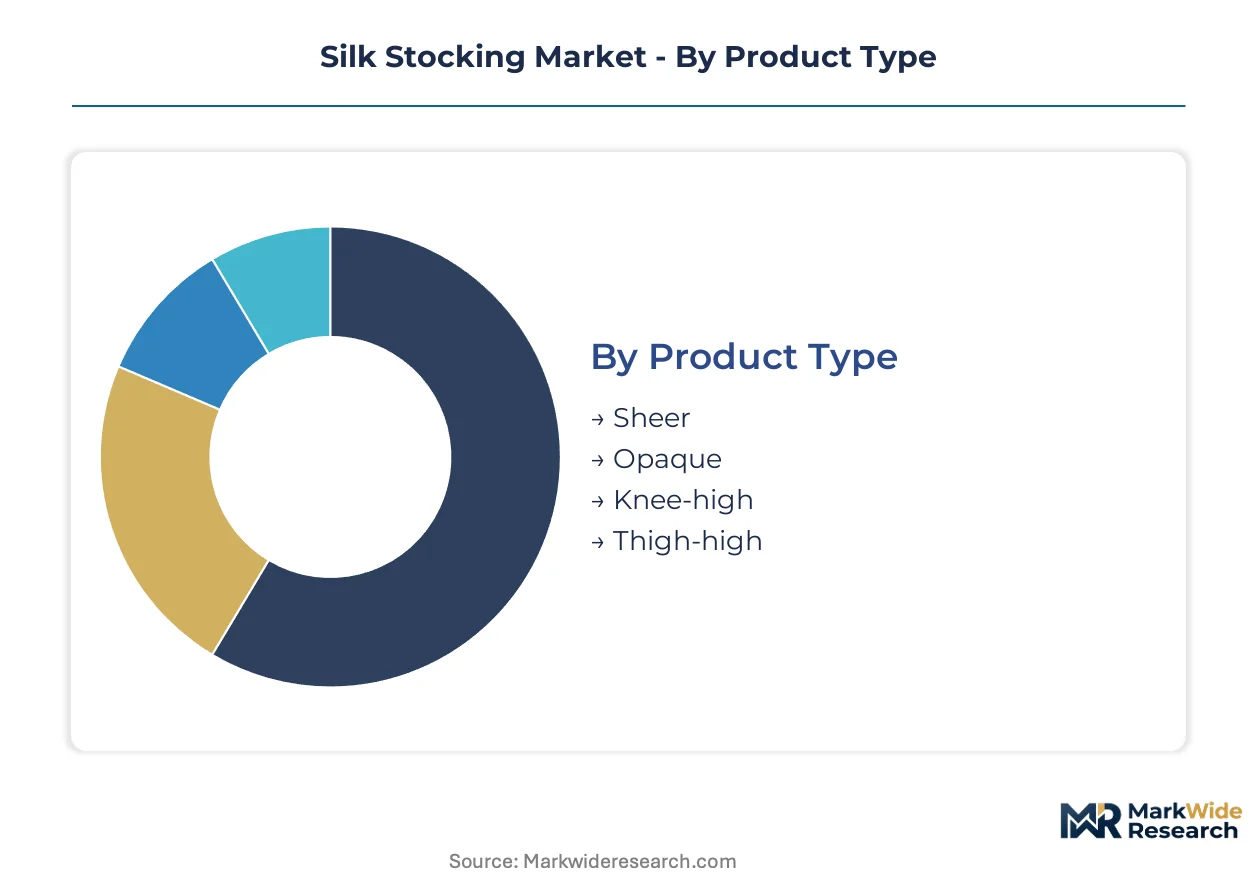
Silk stocking procurement patterns diverge sharply across customer archetypes and purchase occasions, with distribution channel selection often overriding product specification in final purchase decisions. Understanding these segment boundaries clarifies where margin concentration accrues versus where volume flows through commoditized pathways.
Product Type:
Domestic Chinese consumption concentrates in sheer and opaque grades produced within Zhejiang and Jiangsu clusters, while export-led demand from European and North American buyers tilts toward specialty constructions with technical differentiation.
- Sheer:10-20 denier constructions dominate temperate climate markets where lightweight breathability extends seasonal wearability. French and Italian fashion corridors absorb disproportionate volume for evening and formal applications where visible texture is undesirable.
- Opaque:40-80 denier grades command premium positioning in professional and cold-weather segments across Germany and northeastern United States markets. Thermoregulation properties justify unit price premiums over sheer alternatives in corporate dress codes.
- Knee-high:Office-appropriate coverage for business casual environments, concentrated in Japanese and South Korean corporate procurement.
- Thigh-high:Lingerie-adjacent positioning with stay-up silicone band engineering, skewing toward direct-to-consumer channels in North American markets.
Sheer constructions command the established base. The steepest expansion runs through opaque grades as professional dress codes formalize across temperate corporate environments.
Distribution Channel:
Cost tier alignment separates channels: luxury price points concentrate in specialty boutiques with personalized fitting services, while budget tiers flow through high-volume offline retail with minimal service attachment.
- Online Retail:Digital-native brands capture fashion enthusiasts through extended size ranges and subscription replenishment models. Virtual try-on tools replicate boutique fitting experiences without physical presence overhead.
- Department Stores:Mid-range tier consolidation with seasonal colorway exclusives and gift-set merchandising, particularly strong in Japanese department store networks.
- Specialty Boutiques:Paris and Tokyo districts unbundle fitting services from product margins, charging consultation fees separate from purchases. Personalized measurement and curation justify service premiums.
- Offline Retail:Mass-market volume channel with minimal silk-specific expertise, concentrated in Chinese domestic distribution through regional apparel chains.
Specialty boutiques retain margin concentration. Online retail is gaining share fastest through customer acquisition efficiency and data asset accumulation.
Price Tier:
Volume distribution skews toward budget and mid-range tiers in domestic Chinese circulation, while export demand clusters in luxury positioning where provenance certification and filament grade transparency command sustained premiums.
- Luxury:Mulberry silk filament with full provenance documentation and ECHA REACH compliance certification. German and Swiss buyers prioritize batch traceability from cocoon source through reeling facility.
- Mid-range:Blended constructions or lower-grade filament with basic quality assurance, dominant in Japanese mass-market department store placement.
- Budget:Price-competitive positioning for occasional-wear occasions, concentrated in Chinese domestic e-commerce platforms.
- Discount:Promotional and clearance inventory with minimal brand attachment, flowing through offline retail liquidation channels.
Mid-range tiers anchor volume throughput. Luxury positioning is climbing the fastest as sustainability transparency and circular economy credentials reshape premium purchase criteria.
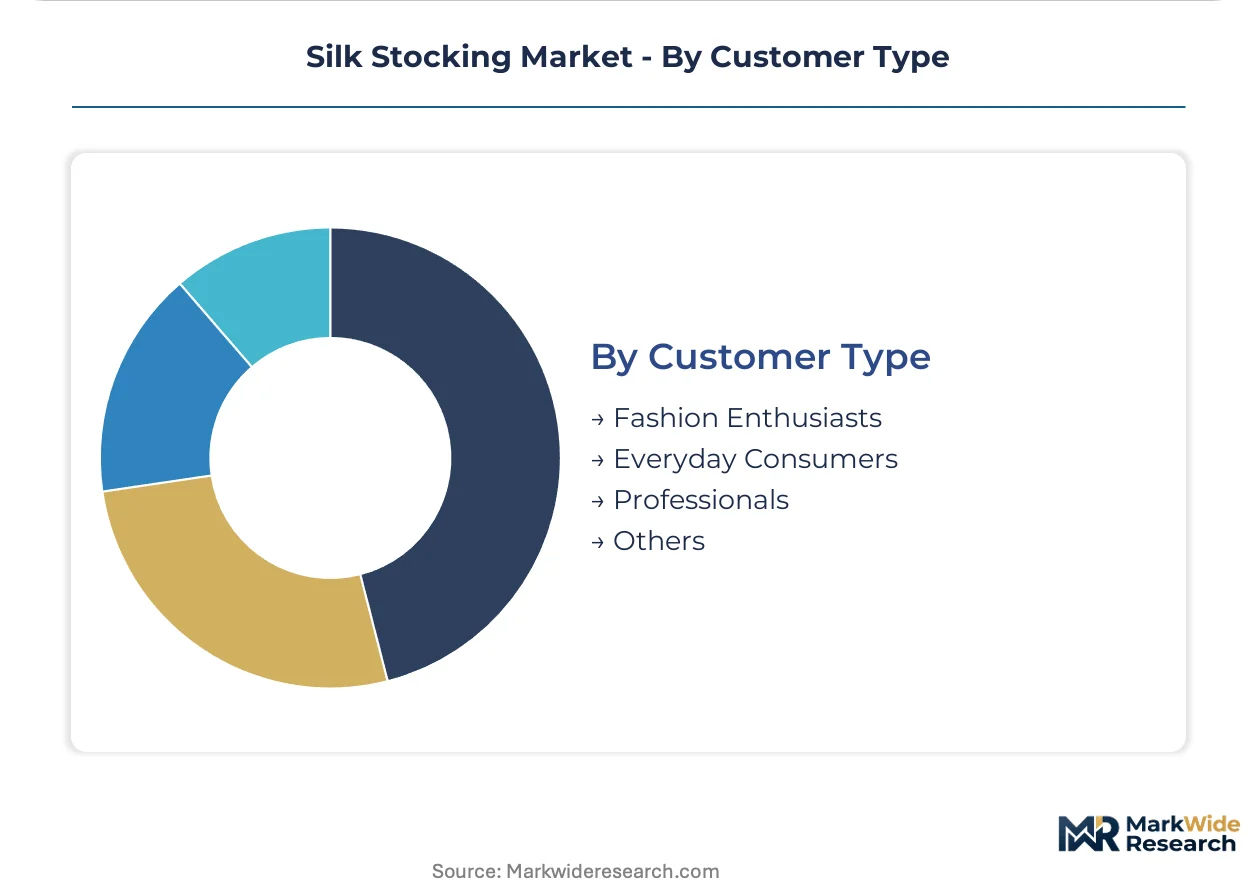
Customer Type:
Application context separates segments: professional and everyday consumption concentrates in opaque, durable constructions, while fashion enthusiast demand rotates through sheer seasonal collections with higher replacement frequency.
- Fashion Enthusiasts:Early adopters of limited colorways and collaborative designer releases, concentrated in metropolitan corridors of Paris, Milan, and Tokyo with high engagement on digital styling platforms.
- Everyday Consumers:Replacement-driven purchase patterns with price sensitivity and durability prioritization, dominant in Chinese domestic market volume.
- Professionals:Corporate dress code compliance with thermoregulation and all-day comfort requirements, concentrated in German and United States financial services sectors.
- Others:Gift purchase occasions and bridal segment specialization with ceremonial wear specifications.
Everyday consumers represent the volume foundation. Fashion enthusiasts are expanding most quickly through social commerce amplification and influencer-driven discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in silk hosiery tilt heavily toward Asian production hubs serving European and North American consumption centers. China maintains a substantial trade surplus in finished silk stockings while importing negligible volumes. Germany and the United States run persistent deficits, sourcing premium grades from Italian and French intermediaries who contract Chinese filament supply.
China
Zhejiang and Jiangsu province clusters process over seventy percent of global mulberry silk filament for hosiery applications. SAMR enforces GB 18401 harmful substance thresholds that extend batch release timelines for export-bound inventory. Hangzhou-area reeling facilities are automating cocoon unwinding to offset retiring master technician cohorts.
Germany
Corporate procurement from financial services and professional services sectors drives opaque grade demand for thermoregulation in climate-controlled offices. ECHA's 2023 REACH Annex XVII update added formaldehyde release limits that now require third-party testing documentation before customs clearance. Berlin and Hamburg specialty boutiques unbundle fitting services from product margins, charging consultation fees separate from purchases.
United States
Direct-to-consumer digital brands capture fashion enthusiasts through subscription replenishment models unavailable through traditional retail. The Federal Trade Commission monitors fiber content labeling accuracy under the Textile Fiber Products Identification Act. New York and Los Angeles metropolitan corridors concentrate luxury hosiery adoption where personalized styling services command sustained premiums.
France
Evening and formal applications in Paris fashion districts absorb disproportionate sheer grade volume where visible texture is undesirable. Extended producer responsibility frameworks now mandate hosiery collection, creating circular economy infrastructure that premium brands leverage for differentiation. Lyon maintains historical silk processing expertise though most filament now originates from Chinese reeling facilities.
Japan
Corporate procurement concentrates in knee-high constructions for business casual environments across Tokyo and Osaka office districts. METI oversees JIS standards for textile quality assurance that align with export market requirements. Department store networks in Shibuya and Ginza districts maintain seasonal colorway exclusives and gift-set merchandising strength.
Silk Stocking Market Competitive Landscape
Concentration sits with integrated cocoon processors who control mulberry sericulture operations through finished stocking output. The vendor base stratifies across three tiers: captive upstream operators with basin farm networks, proprietary reeling technology specialists, and digital-native brands bypassing wholesale markups. Two dominant competitive moves are reshaping positioning: backward integration into sericulture to secure filament supply, and direct-to-consumer channel construction to capture full margin and build first-party data assets.
Among Chinese integrated operators, Sichuan Nanchong Liuhe and Jiangsu Sutong Cocoon & Silk exemplify the upstream-control archetype, anchoring competitive positioning through captive supply chains. LilySilk occupies a distinct tier as a direct-to-consumer specialist, representing the channel-control archetype that bypasses traditional wholesale structures in North American and European markets.
| Leading Market Players |
|---|
| Sichuan Nanchong Liuhe |
| Jiangsu Sutong Cocoon & Silk |
| Anhui Silk |
| LilySilk |
| Jinchengjiang Xinxing Cocoon Silk |
| Wujiang First Textile |
| Shengkun Silk |
| Silkua |
| Zhejiang Jiaxin Silk |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH compliance gates both supplier qualification and price differentiation simultaneously, as European distributors demand third-party testing documentation before customs clearance while premium brands leverage certification transparency to justify sustained margin premiums over uncertified alternatives.
Pricing Analysis
Configured-to-order pricing for bespoke colorways and personalized fitting services commands spreads of 40-60 percent above standard SKUs. Pricing stratifies across luxury, mid-range, and budget tiers driven by filament grade certification and provenance documentation depth. Cost compression in budget tiers intensifies as microfiber nylon alternatives capture price-sensitive volume. Fashion enthusiasts exhibit lowest price sensitivity, prioritizing exclusivity and batch traceability, while everyday consumers in Chinese domestic circulation drive procurement toward economy positioning.
Supply Chain Analysis
Inventory cycles extend four to six weeks for cross-border shipments facing dual REACH and GB 18401 certification burdens. Raw silk supply draws from Zhejiang, Jiangsu, and Sichuan province clusters where over seventy percent of continuous filament reeling capacity concentrates within 200 kilometers of Hangzhou. Bombyx mori cocoon harvest volatility and retiring master reeling technicians constitute structural supply risks. Distribution runs through direct-to-consumer digital channels, specialty boutiques with unbundled service fees, and department store networks with seasonal exclusives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated direct-to-consumer brands and specialized boutique networks, as fragmented wholesale channels lose pricing leverage to vertically integrated suppliers and digital-native entrants with first-party data assets.
For Market Incumbents: Shield filament supply security through captive sericulture operations across Sichuan basin farms, countering synthetic substitution pressure and raw material volatility. Invest in automated reeling technology to offset retiring master technician scarcity. Prioritize ECHA REACH certification maintenance as European extended producer responsibility frameworks tighten compliance thresholds. For New Entrants and Emerging Players: Virtual fitting and subscription replenishment services represent underexploited service-layer gaps where incumbents under-serve North American fashion enthusiasts. Target direct-to-consumer channels with AI-driven color matching and extended size range positioning. Pursue white-label partnerships with Zhejiang reeling facilities to bypass capital-intensive upstream investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated knitting operations as real-time tension monitoring systems displace manual loom workshops. Long-term viability favors integrated operators with captive cocoon supply and proprietary reeling technology. Monitor ECHA regulatory update frequency as signal for compliance cost inflection and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sericulture | Sichuan basin farm networks secure mulberry silk filament against harvest volatility and quality variance. |
| Direct-to-Consumer Channel Launch | LilySilk's North American and European bypass of wholesale markups captures full margin and customer data assets. |
| Automated Reeling Technology Deployment | Jiangsu Sutong's proprietary systems reduce filament breakage rates during stocking knit preparation. |
| REACH Compliance Certification Investment | Third-party testing documentation from Zhejiang facilities enables European customs clearance and premium positioning. |
| Subscription Replenishment Model | Digital-native brands lock in fashion enthusiast replacement cycles unavailable through specialty boutiques. |
Research Methodology
Desk research of customs trade records, SAMR regulatory filings, and ECHA substance restriction updates preceded structured interviews with silk reeling facility managers, specialty boutique buyers, direct-to-consumer brand operators, and European distributor procurement leads. Primary fieldwork across Zhejiang and Jiangsu manufacturing clusters was cross-validated against secondary sources including filament grade certification databases and textile industry association capacity surveys. Bottom-up volume estimates from reeling facility throughput data were triangulated with top-down demand modeling from retail channel sell-through rates.
Variance decomposition across product type, distribution channel, price tier, and customer archetype dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value expansion. Denier construction preferences, regional climate patterns, and professional dress code formalization trends served as industry-specific forecast inputs.
Underlying assumptions cover sustained ECHA enforcement intensity, stable Sichuan basin temperature patterns for cocoon harvests, and continued synthetic substitution pressure in temperate climate segments, with deviation risk concentrated in regulatory timeline acceleration and master technician retirement rates exceeding training pipeline output. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Silk Mask Market
Natural Fibers
Silk Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Global Cotton Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Green Fibers Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market