
 Geosynthetics Market | 2026-2036
Geosynthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Geosynthetics Market Analysis
GRI-GM13 certification for geomembrane quality is rotating supplier eligibility across major infrastructure tenders. Solmax International Inc. leverages integrated polyethylene resin-to-liner manufacturing across North American mining and waste containment projects. Officine Maccaferri S.p.A. anchors its position through specialized steel-grid geocomposite systems for slope stabilization and rockfall protection in European alpine corridors. HUESKER Synthetic GmbH differentiates via high-tenacity polyester geogrid engineering for rail and road base reinforcement.
Geosynthetics are polymeric planar products manufactured from polyethylene, polypropylene, or polyester resins through extrusion, weaving, or needle-punching processes, designed to perform stabilization, filtration, drainage, or containment functions when interfaced with soil, rock, or other geotechnical materials. Geomembranes command substantial value share in hazardous waste landfill and mining heap leach pad applications where chemical resistance and seam integrity determine project viability. Geotextiles sustain volume leadership across road construction and coastal erosion control where permeability and tensile strength specifications govern material selection.
The EPA's Resource Conservation and Recovery ActSubtitle D landfill liner standards and the EU Green Deal circular economy construction material mandates are elevating compliance costs while opening certified-supplier premiums. India's BIS certification requirements for geosynthetics in national highway projects are restricting market access to tested manufacturers. Stakeholders must monitor evolving polymer recycling mandates and carbon-border adjustment mechanisms that will reshape raw material sourcing decisions and product lifecycle accountability.
Market Dynamics
The EPA's Subtitle D landfill liner standards and China's dual carbon goals are tightening material performance specifications, forcing manufacturers to certify against GRI-GM13 and equivalent quality benchmarks to retain tender eligibility across North American and Asian infrastructure projects.
Growth Catalysts
- EPA Subtitle D mandates:Hazardous waste containment projects in the United States require certified geomembrane systems, locking in demand for high-density polyethylene liners with documented seam integrity testing.
- India's coastal protection corridors:National highway expansion and shoreline stabilization projects are specifying polyester geogrids and woven geotextiles for erosion control and subgrade reinforcement.
- Polymer recycling integration:Post-consumer polyethylene feedstock streams are achieving performance parity with virgin resins in non-structural drainage applications, opening circular material pathways for geocomposite manufacturers.
Market Restraints
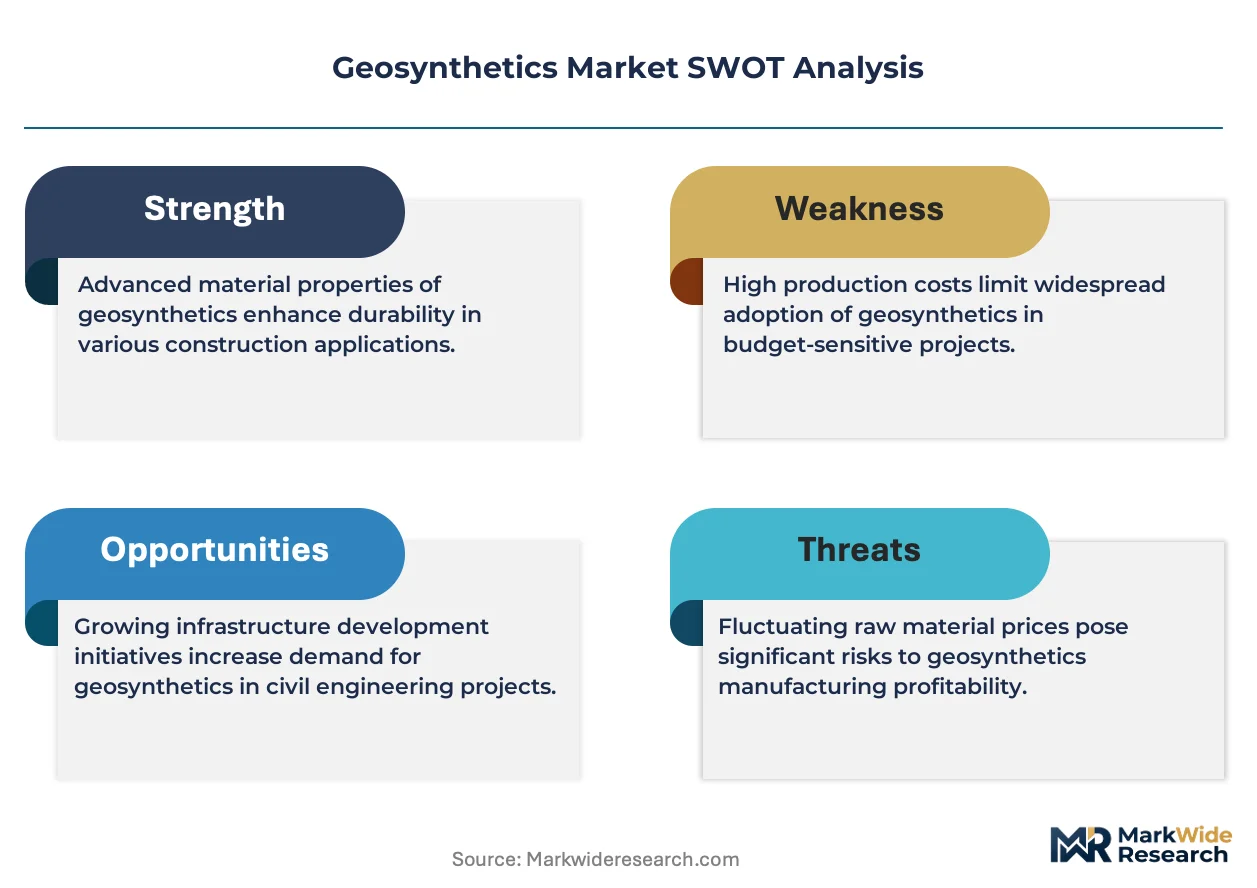
- Petrochemical input volatility:Polypropylene and high-density polyethylene resin prices track crude oil and natural gas feedstock swings, compressing margin predictability for extrusion-based product lines.
- Supplier concentration in liner-grade resins:North American and Middle Eastern petrochemical complexes control specialty polyethylene supply for geomembrane production, creating geographic dependency risk.
- Concrete reinforcement substitution:Steel rebar and fiber-reinforced concrete retain cost advantages in certain soil stabilization applications, limiting geogrid penetration in budget-constrained municipal projects.
Strategic Opportunities
- EU Green Deal circular economy mandates:Construction material recycling quotas and carbon-border adjustment mechanisms are creating certified-supplier premiums for geosynthetics with verified recycled content and lifecycle accountability.
- Rail base reinforcement in Germany and France:High-speed rail corridor upgrades are specifying high-tenacity polyester geogrids for ballast stabilization, displacing traditional granular subbase thickness requirements.
- Smart geosynthetic integration:Embedded fiber-optic sensing and RFID tagging are converging with conventional geotextile manufacturing, enabling real-time strain monitoring and predictive maintenance in critical infrastructure.
Industry Challenges
- GRI-GM13 certification timeline:Third-party testing and documentation requirements for geomembrane quality assurance extend 12-18 months, delaying market entry for new resin formulations and manufacturing processes.
- Seam welding technician scarcity:Thermal fusion and extrusion welding for geomembrane installation require specialized certification that outpaces training program throughput in high-growth markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geosynthetics Market |
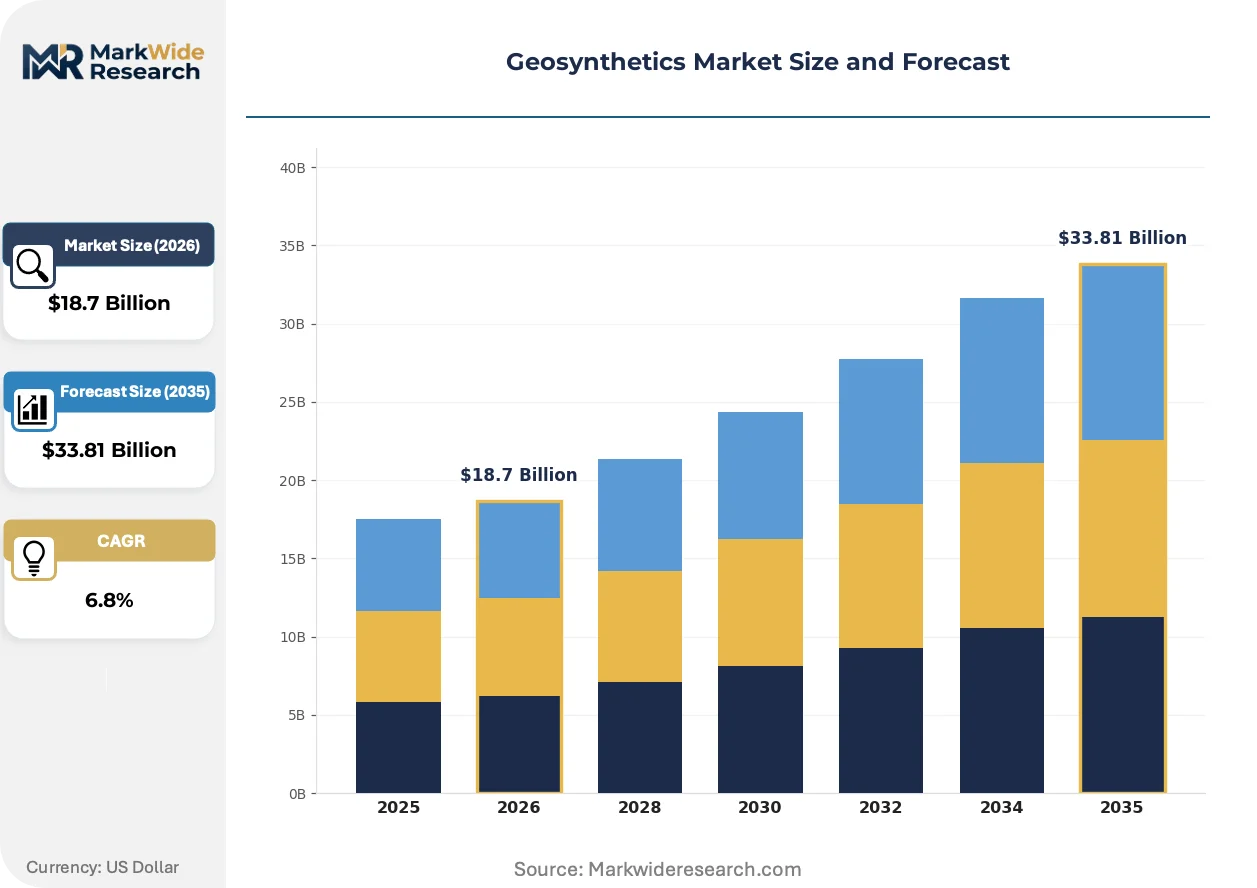
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Geomembranes, Geogrids, Geonets Application: Drainage, Erosion Control, Reinforcement, Separation End Use Industry: Civil Engineering, Environmental, Transportation, Mining Material: Polyethylene, Polypropylene, Polyester, Others |
| Companies Covered | Solmax International Inc., Officine Maccaferri S.p.A., Advanced Drainage Systems, Inc., SKAPS Industries, HUESKER Synthetic GmbH, AGRU America, Inc., Royal Tencate NV, Propex Operating Company, LLC, GSE Environmental, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geosynthetics Market Emerging Trajectories
Material science advances and regulatory tightening are bifurcating the competitive landscape between certified premium suppliers and commodity-grade producers, with performance verification becoming the primary procurement filter across civil engineering tenders.
Multilayer co-extruded geomembranes incorporating conductive layers for leak detection are fragmenting the conventional single-layer HDPE market. Mining heap leach pad operators in Chile and Australia are specifying these systems for real-time integrity monitoring. The technology is compressing project risk premiums and extending warranty terms for containment system suppliers.
REACH chemical substance restrictions and the EU Green Deal circular economy construction material mandates are elevating compliance documentation burdens. Manufacturers must now certify polymer additive packages against Substances of Very High Concern lists. Geotextile producers serving German and Dutch infrastructure tenders are restructuring supply chains to exclude restricted plasticizers and stabilizers.
Engineering firms are consolidating procurement authority for geosynthetic specification, displacing decentralized contractor purchasing. Tier-one civil contractors in India and the United States now mandate pre-approved manufacturer lists with certified test data. This concentration is visible most acutely in national highway projects where BIS and state DOT qualification requirements filter supplier pools before bidding commences.
Geosynthetics Market Segmentation
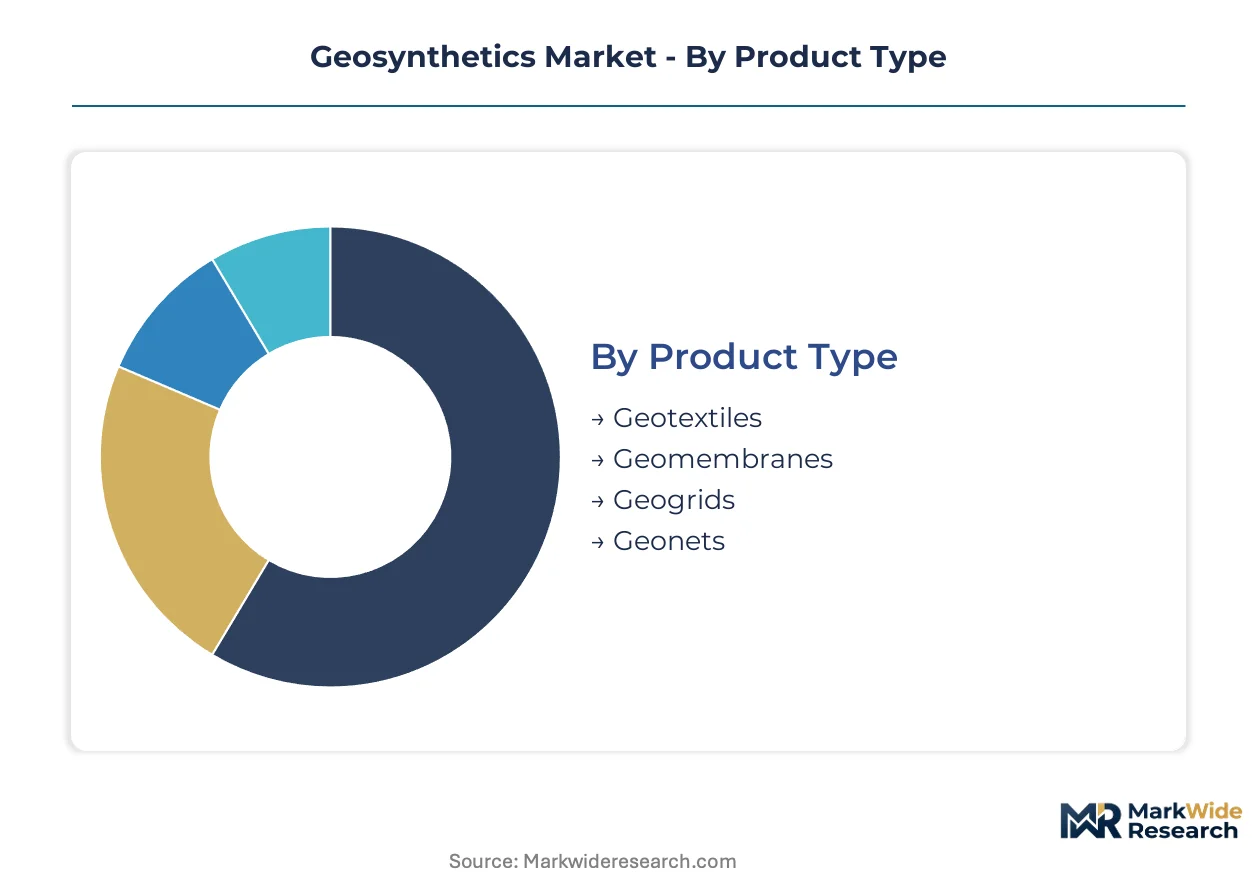
Geosynthetics procurement decisions hinge on functional performance specifications that vary sharply across installation environments. Material substitution pressures from concrete, steel, and natural alternatives reshape competitive dynamics within each segment cluster.
Product Type:
Geomembranes face the most acute substitution threat from compacted clay liners and sprayed concrete in cost-sensitive containment applications, while geogrids compete directly with steel reinforcement in soil stabilization.
- Geomembranes:Impermeable polymeric sheets manufactured through extrusion or calendering, specified for chemical resistance and seam weld integrity. Mining heap leach pads in Chile and Australia specify multilayer conductive geomembranes for real-time leak detection, displacing conventional single-layer HDPE in risk-critical installations.
- Geotextiles:Permeable fabrics produced via weaving, needle-punching, or heat-bonding of polypropylene or polyester fibers. National highway expansion corridors in India specify woven geotextiles for subgrade separation and filtration, with BIS certification requirements restricting supplier eligibility to tested manufacturers.
- Geogrids:Grid-like structures with high tensile strength for soil reinforcement applications.
- Geonets:Net-like drainage geocomposites designed for fluid transmission in landfill and tunnel applications.
Geotextiles anchor the volume base while geomembranes gain share at the steepest rate through premium containment system specifications.
Application:
Cost tier differentiation separates specification-grade applications with certified performance requirements from commodity drainage uses where recycled feedstocks compete on price.
- Reinforcement:Geogrid and high-strength geotextile systems that improve load-bearing capacity of subgrade soils. Germany and France specify polyester geogrids for high-speed rail ballast stabilization, reducing granular subbase thickness requirements by 30-40% in corridor upgrade projects.
- Erosion Control:Biodegradable and synthetic matting systems for slope and shoreline protection. India's coastal protection corridors deploy woven geotextiles and geocellular confinement systems along Gujarat and Tamil Nadu shorelines, driven by National Coastal Mission funding allocations.
- Drainage:Geocomposite and geonet systems for fluid collection and transmission.
- Separation:Geotextile barriers preventing intermixing of dissimilar soil layers.
Reinforcement commands the highest specification premiums while erosion control expands most quickly through climate adaptation infrastructure budgets.
End Use Industry:
Customer procurement concentration shapes segment profitability, with civil engineering and transportation sectors consolidating supplier pre-approval authority.
- Civil Engineering:Road construction, embankment stabilization, and foundation improvement projects. State DOT qualification requirements in the United States filter geosynthetic supplier pools before bidding commences, concentrating procurement authority among tier-one civil contractors.
- Transportation:Rail, highway, and airport infrastructure applications. EPA Subtitle D mandates lock in geomembrane demand for hazardous waste containment adjacent to transportation corridors, with seam integrity documentation required for project closeout.
- Environmental:Landfill liners, caps, and remediation systems.
- Mining:Heap leach pads, tailings containment, and process pond linings.
Civil engineering generates the deepest project backlogs while transportation climbs the fastest through national highway expansion programs.
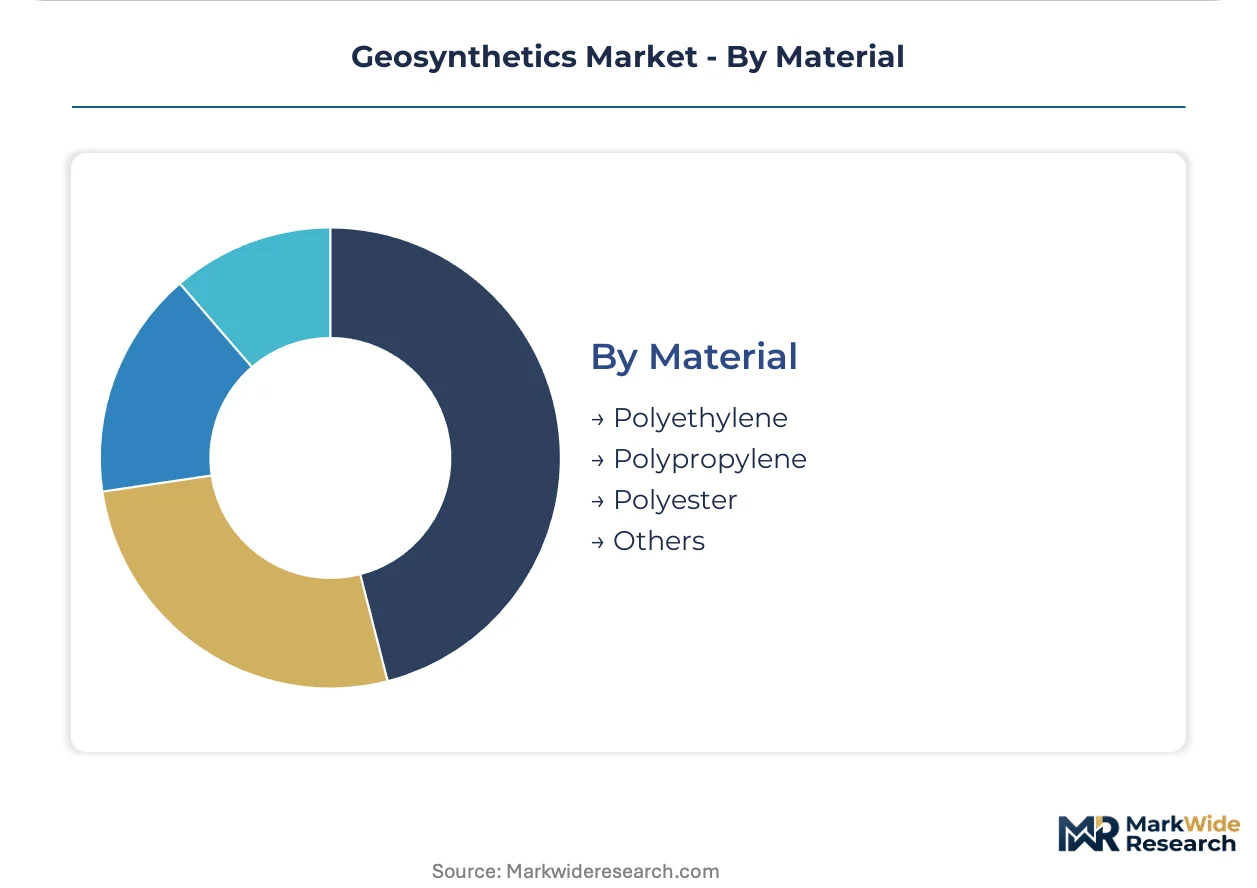
Material:
Supply concentration in petrochemical feedstocks creates geographic dependency risk that varies by polymer chemistry and specialty resin availability.
- Polyethylene:HDPE and LLDPE resins dominate geomembrane production through extrusion and blown film processes. North American and Middle Eastern petrochemical complexes control specialty polyethylene supply for GRI-GM13 certified liner production, creating sourcing bottlenecks for new market entrants.
- Polyester:High-tenacity PET fibers and yarns for geogrid and woven geotextile applications. REACH chemical substance restrictions force German and Dutch infrastructure suppliers to certify additive packages against Substances of Very High Concern lists, elevating compliance documentation burdens.
- Polypropylene:Staple fibers and tapes for nonwoven geotextiles and drainage geocomposites.
- Others:Specialty polymers including PVC, EPDM, and biodegradable alternatives for niche applications.
Polyethylene anchors the value base while polyester gains share fastest through rail and road reinforcement specifications demanding high tensile modulus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Golden Quadrilateral highway network underwrites India's position as the primary demand anchor for polyester geogrids and woven geotextiles in subgrade reinforcement applications.
United States
EPA Subtitle D landfill liner mandates lock in geomembrane demand across hazardous waste containment projects in Texas and California. State DOT qualification requirements filter supplier pools before bidding commences on federal highway corridors. The Permian Basin mining cluster specifies multilayer conductive geomembranes for heap leach pad integrity monitoring.
Germany
High-speed rail corridor upgrades between Frankfurt and Munich specify high-tenacity polyester geogrids for ballast stabilization. REACH chemical substance restrictions force additive package certification against Substances of Very High Concern lists. The Ruhr industrial corridor concentrates geocomposite manufacturing for drainage applications in tunnel and landfill projects.
China
Dual carbon goals tighten material performance specifications for geomembrane systems in municipal waste containment. MIIT standards accelerate certification timelines for polymer recycling integration in non-structural drainage geocomposites. The Yangtze River Delta anchors production capacity for polyethylene resin-to-liner manufacturing serving domestic mining projects.
India
BIS certification requirements restrict geosynthetic supplier eligibility to tested manufacturers in national highway expansion corridors. National Coastal Mission funding allocates resources for shoreline stabilization along Gujarat and Tamil Nadu coastlines. The Delhi-Mumbai Industrial Corridor deploys woven geotextiles for erosion control and subgrade separation in freight rail infrastructure.
Australia
Mining heap leach pad operators in Western Australia specify real-time integrity monitoring systems for containment risk management. State environmental regulators mandate documented seam weld testing for project closeout in Queensland coal seam gas developments. The Pilbara iron ore belt concentrates demand for chemical-resistant geomembrane systems in process pond applications.
Geosynthetics Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and resin integration depth. The vendor base splits between integrated petrochemical players controlling polyethylene supply chains and specialized fabricators focusing on high-tenacity polyester engineering. Three archetypes dominate: resin-integrated liner manufacturers, steel-grid geocomposite specialists, and high-modulus geogrid engineers. Capacity expansion in conductive multilayer systems and backward integration into post-consumer recycling streams represent the dominant competitive vectors reshaping procurement authority.
Within the resin-integrated tier, Solmax International Inc. and AGRU America, Inc. occupy positions anchored in North American polyethylene supply chains. Officine Maccaferri S.p.A. exemplifies the steel-grid geocomposite specialization archetype rooted in European alpine corridor applications. HUESKER Synthetic GmbH represents the high-tenacity polyester engineering segment serving rail base reinforcement specifications in German and French infrastructure tenders.
| Leading Market Players |
|---|
| Solmax International Inc. |
| Officine Maccaferri S.p.A. |
| Advanced Drainage Systems, Inc. |
| SKAPS Industries |
| HUESKER Synthetic GmbH |
| AGRU America, Inc. |
| Royal Tencate NV |
| Propex Operating Company, LLC |
| GSE Environmental, LLC |
| Others |
Supply Flow & Price Mechanics
Resin-to-liner manufacturing scale at North American and Middle Eastern petrochemical complexes establishes minimum efficient scale thresholds that filter out sub-scale competitors and set polyethylene geomembrane price floors across certified and uncertified tiers.
Pricing Analysis
Volume-discount tiering separates GRI-GM13 certified geomembranes from commodity-grade alternatives, with certification documentation and seam integrity testing creating 30-40% price spreads between premium and standard tiers. Price differentiation rests on polymer purity grades and third-party testing overhead rather than brand premiums alone. Cost compression in the commodity drainage segment intensifies as post-consumer recycled feedstocks achieve performance parity, squeezing margins for virgin-resin producers. Municipal contractors exhibit highest price sensitivity in erosion control applications, while mining operators in Chile and Australia absorb premium pricing for multilayer conductive systems with real-time monitoring capabilities.
Supply Chain Analysis
Just-in-time resin delivery dominates geomembrane extrusion operations, though strategic polyethylene stockpiling has gained traction among North American manufacturers facing Gulf Coast petrochemical disruption risks. Raw material sourcing draws from specialty HDPE and LLDPE resin streams concentrated in the United States, Saudi Arabia, and South Korea, with additive packages for UV stabilization and chemical resistance anchored in German and Dutch chemical manufacturing. Single-source vulnerability in liner-grade polyethylene creates geographic dependency exposure for new market entrants lacking long-term offtake agreements. Distribution runs through tier-one civil engineering contractors with pre-approved manufacturer lists, displacing decentralized procurement channels in national highway and landfill containment projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded fiber-optic sensing and RFID tagging convergence with conventional geotextile manufacturing represents a technological inflection that will bifurcate supplier premiums between smart-system integrators and commodity producers.
For Market Incumbents: Consolidate certification authority by accelerating GRI-GM13 testing throughput and backward integration into post-consumer polyethylene recycling streams. Threats from steel-grid geocomposite substitution in European slope stabilization applications demand capacity expansion in high-tenacity polyester geogrid engineering. Channel control through state DOT and BIS pre-approval list maintenance is the critical defensive lever. For New Entrants and Emerging Players: Anchor in India's coastal protection corridor deployment, where National Coastal Mission funding outpaces certified supplier availability for woven geotextile and geocellular confinement systems. The white-space opportunity concentrates in Gujarat and Tamil Nadu shoreline stabilization projects with BIS certification barriers that favor tested manufacturers willing to absorb 12-18 month qualification timelines. A specification-engineer direct sales model bypasses consolidated contractor procurement gates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among resin-integrated geomembrane manufacturers with long-term mining heap leach pad service contracts spanning installation, monitoring, and warranty maintenance. Long-term viability over a 5-10 year horizon favors suppliers with captive polyethylene supply and conductive multilayer technology portfolios. The signal to watch is EPA enforcement intensity on Subtitle D seam documentation requirements, which would accelerate premium-tier demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Recycling | MIIT standards in China and EU Green Deal mandates create certified-supplier premiums for verified recycled content. |
| Conductive Multilayer Geomembrane Capacity Expansion | Mining operators in Western Australia and Chile specify real-time leak detection systems for risk management. |
| GRI-GM13 Certification Fast-Track Investment | EPA Subtitle D and BIS requirements filter supplier pools before bidding commences on infrastructure tenders. |
| Smart Geosynthetic R&D Partnership | Embedded fiber-optic sensing enables predictive maintenance contracts in German high-speed rail corridors. |
| Strategic Stockpile of Specialty Resins | Gulf Coast petrochemical disruption risks justify inventory buffers for HDPE liner-grade supply security. |
Methodological Framework
A spread of perspectives from geomembrane extrusion plant managers, civil engineering procurement leads at tier-one contractors, state DOT materials engineers, and mining heap leach pad operators converged on the working assumptions for demand segmentation and pricing tier boundaries. Primary fieldwork combined structured interviews with secondary validation against EPA Subtitle D enforcement records, BIS certification registries, EU REACH substance restriction updates, and customs data tracking polyethylene resin trade flows. Bottom-up project pipeline analysis across India's Golden Quadrilateral highway network and top-down petrochemical capacity modeling triangulated volume and value estimates.
Segmentation dimensions modeled include product type, application function, end-use industry vertical, polymer material chemistry, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trends in resin-to-liner manufacturing. Industry-specific forecast inputs incorporated GRI-GM13 certification timeline delays and REACH chemical substance restriction compliance cost escalations.
Decision-makers should treat outputs as directional under assumptions of continued EPA enforcement intensity and stable petrochemical feedstock availability; material deviation would warrant model refresh. Revision becomes warranted when polymer recycling integration achieves structural-grade performance parity or carbon-border adjustment mechanisms reshape raw material sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Glass Railing System Market