
 France Oriented Strand Board Market | 2026-2036
France Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
France Oriented Strand Board Market Insights
Capital-intensity divergence between integrated resin producers and commodity panel converters is bifurcating the France Oriented Strand Board Market. Kronospan leverages captive phenolic resin capacity to control input costs across its French mills. EGGER Group anchors its position through continuous press technology investments that sustain thinner-panel output at scale. Swiss Krono Group competes via specialty moisture-resistant grades targeted at Atlantic France's humid construction zones.
Oriented strand board consists of long, thin wood strands arranged in cross-oriented layers and bonded with waterproof phenol-formaldehyde or MDI resin under heat and pressure, yielding engineered panels with directional strength properties suited for load-bearing applications. Structural-grade OSB dominates French volume as building codes mandate its use in timber-frame housing and modular construction systems. Flooring applications represent the fastest-expanding segment, driven by platform-frame methods gaining share in multi-family residential builds across the Paris Basin and Lyon corridor. Wall panel demand remains mature, with margin pools shifting toward prefabricated insulated assemblies that combine OSB sheathing with integrated thermal barriers.
CE marking under the Construction Products Regulation governs structural performance declarations, while France's RE2020 environmental regulation imposes lifecycle carbon thresholds that reshape material selection for new builds. ANR and ADEME administer innovation funding that steers producers toward bio-based binder research and recycled wood content verification systems. Stakeholders must track enforcement granularity of RE2020's upcoming biogenic carbon accounting rules to anticipate which panel specifications secure specification lock-in with national builders.
Market Dynamics
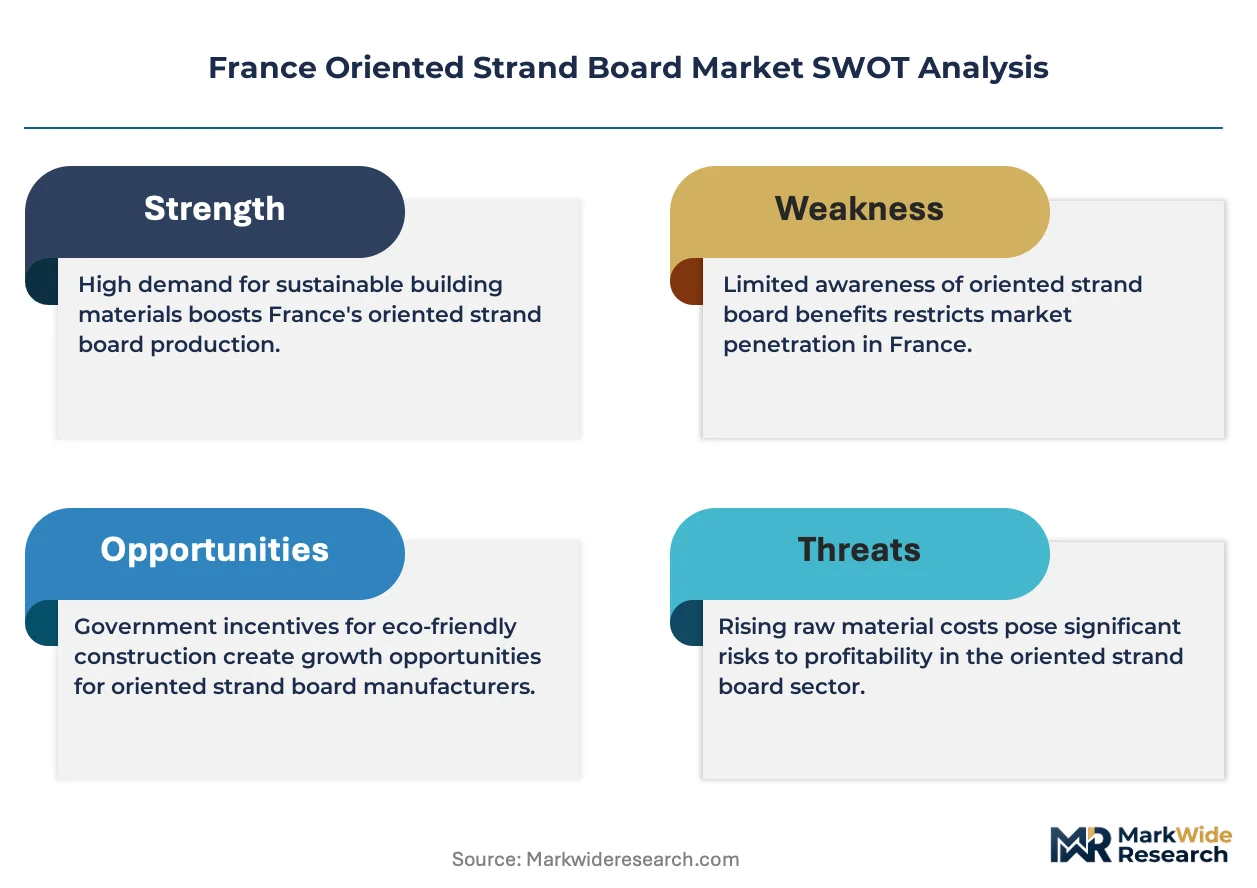
The France Oriented Strand Board Market is being restructured by RE2020's lifecycle carbon thresholds, which are forcing builders to specify low-emission panels and certified wood sourcing. This regulatory pressure is compressing margins for conventional binders while rewarding bio-based alternatives.
Growth Catalysts
- Prefabricated Construction Systems:French timber-frame builders are standardizing OSB-sheathed wall panels for multi-family residential projects. This modular approach reduces on-site labor and accelerates project timelines.
- EU Green Deal Embodied Carbon Rules:Mandatory carbon reporting for construction materials is creating specification pull for panels with verified Environmental Product Declarations. ANR innovation funding supports bio-based binder commercialization.
- Grand Est Timber Cluster Proximity:Concentrated wood processing infrastructure in northeastern France reduces logistics costs for panel manufacturers. Sawmill residuals feed directly into strand production.
Market Restraints
- Phenol-Formaldehyde Resin Cost Volatility:Petrochemical input prices fluctuate with crude oil markets, compressing converter margins when resin costs spike without corresponding panel price recovery.
- Import Dependency for MDI Binders:French panel producers rely on limited European suppliers for methylene diphenyl diisocyanate, creating supply vulnerability during chemical plant maintenance cycles.
- Cross-Laminated Timber Substitution:CLT manufacturers are capturing structural applications in commercial mid-rise construction, displacing OSB in load-bearing wall assemblies above four stories.
Strategic Opportunities
- Nouvelle-Aquitaine Housing Expansion:Bordeaux and Toulouse metropolitan zones are adding residential units faster than national averages, creating unmet panel demand from local builders.
- Moisture-Resistant Specialty Grades:Atlantic coastal humidity zones require enhanced panel specifications that command pricing premiums over commodity structural grades.
- ADEME Circular Economy Incentives:Public funding for recycled wood content verification systems enables producers to differentiate through post-consumer fiber integration.
Industry Challenges
- RE2020 Biogenic Carbon Accounting Expertise Gap:Few French engineering firms possess lifecycle assessment capabilities to document panel carbon sequestration for regulatory compliance.
- Continuous Press Technology Capex Burden:Thin-panel production at scale requires capital investments that strain mid-tier producers without captive resin capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Oriented Strand Board Market |
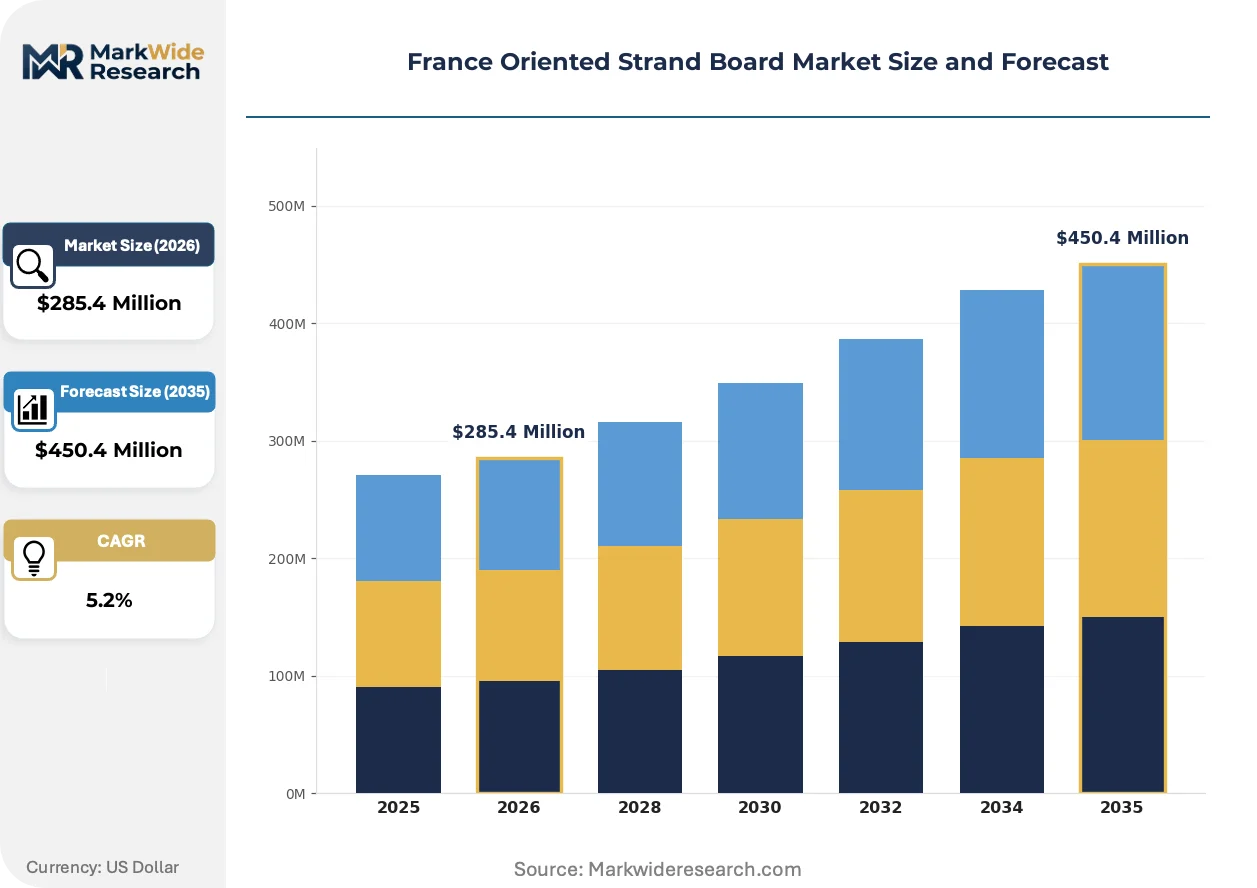
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural, Insulation, Flooring, Furniture End User: Construction, Furniture Manufacturers, Packaging, DIY Enthusiasts Application: Building Materials, Wall Panels, Roof Sheathing, Subflooring Distribution Channel: Direct Sales, Distributors, Retail, Online Stores |
| Companies Covered | Kronospan, Swiss Krono Group, EGGER Group, West Fraser, Sonae Arauco, SMARTPLY Europe, FINSA, Pfleiderer Group, Louisiana-Pacific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Oriented Strand Board Market Trends and Innovations
Panel manufacturing in France is converging around low-carbon binder chemistry and digital production controls. These shifts are reshaping competitive advantage toward integrated supply chains and verified sustainability credentials.
MDI-based adhesive systems are supplanting phenol-formaldehyde binders in moisture-critical applications. Atlantic France construction firms specify MDI-bonded panels for humid coastal zones, compressing demand for conventional resin grades in high-performance segments.
France's RE2020 environmental regulation mandates lifecycle carbon thresholds for new residential construction. Builders must document embodied emissions across material selections, pushing specification committees toward panels with Environmental Product Declarations and certified chain-of-custody documentation.
Prefabricated wall system manufacturers are consolidating procurement around single-source panel suppliers with integrated thermal barrier capabilities. This vertical integration of sheathing and insulation functions is displacing traditional multi-vendor purchasing in timber-frame residential construction across the Paris Basin.
France Oriented Strand Board Market Segmentation
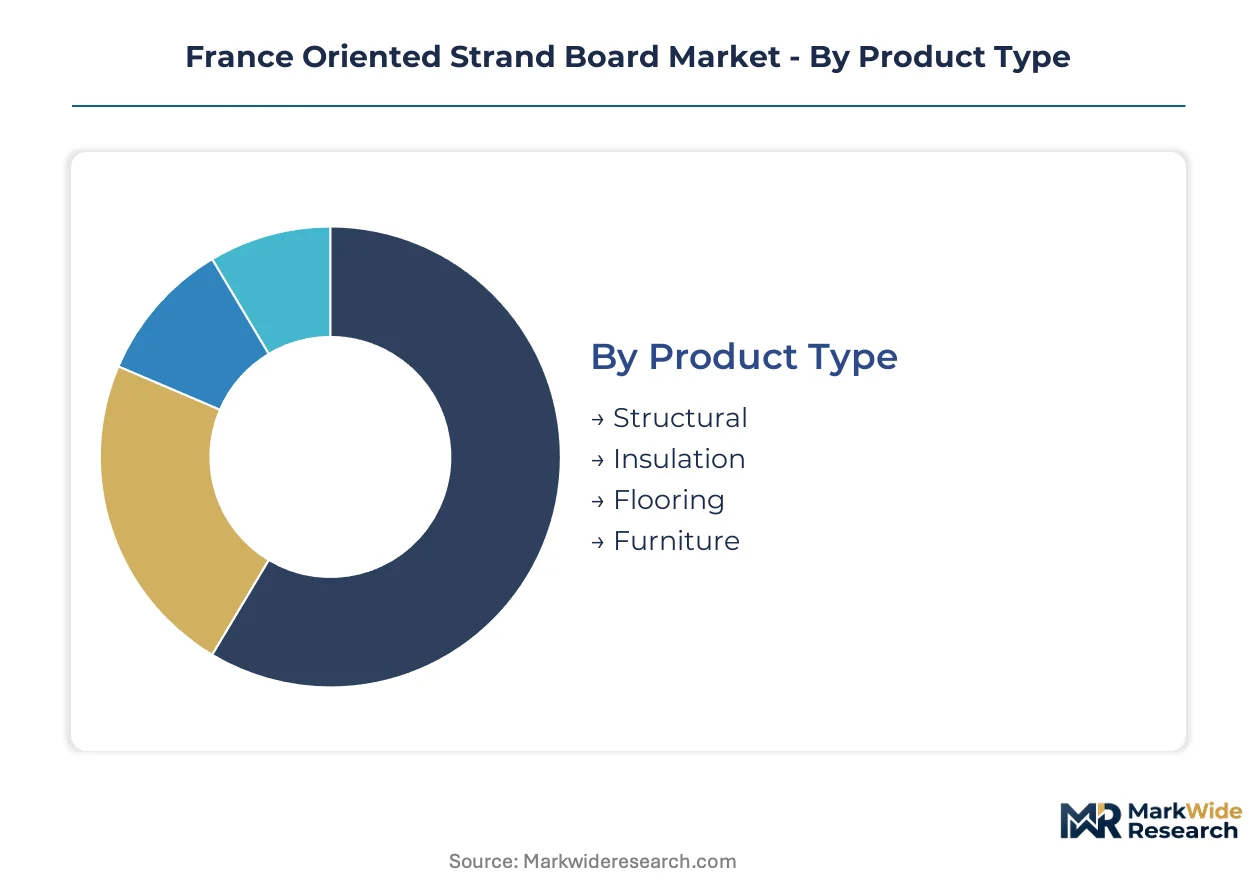
Panel specification committees in France segment procurement by structural performance, end-use liability exposure, and supply chain proximity. These divisions determine binder chemistry selection, certification requirements, and margin capture across the value chain.
Product Type:
Margins pool in moisture-resistant and thermally enhanced grades where RE2020 compliance commands specification premiums over commodity structural panels.
- Structural:Cross-oriented strand layers bonded with phenol-formaldehyde or MDI resin deliver directional load-bearing capacity for timber-frame housing. French building codes mandate structural OSB for platform-frame construction across the Paris Basin and Lyon corridor, with volume concentrated in multi-family residential developments.
- Flooring:Tongue-and-groove edge profiles and enhanced stiffness ratings suit subfloor assemblies in modular construction. Demand is climbing fastest in Bordeaux and Toulouse metropolitan zones where housing starts outpace national averages.
- Insulation:Low-density panels integrate with thermal barrier systems for prefabricated wall assemblies.
- Furniture:Smooth-surface grades serve interior fit-out applications with lower structural requirements.
The dominant share belongs to Structural, while Flooring is closing the gap fastest.
End User:
Volume concentrates with professional builders liable for RE2020 carbon documentation, while furniture and packaging segments compete on price with import substitutes.
- Construction:Timber-frame contractors and modular system manufacturers specify certified panels with Environmental Product Declarations. Procurement concentrates with integrated suppliers capable of thermal barrier integration for prefabricated wall systems.
- Furniture Manufacturers:Interior fit-out producers source lower-density grades for cabinetry and fixture substrates, prioritizing surface finish consistency over structural ratings.
- DIY Enthusiasts:Home improvement retailers move commodity structural grades through distribution networks serving renovation activity in Grand Est and Nouvelle-Aquitaine.
- Packaging:Industrial crating and pallet manufacturers represent price-sensitive demand with minimal certification requirements.
Construction commands the volume lead, yet DIY Enthusiasts are gaining transaction frequency fastest through retail channel expansion.
Application:
Building code mandates and climate zone specifications fragment demand across structural assemblies, with coastal humidity driving specialty grade premiums.
- Wall Panels:Sheathing layers in timber-frame construction combine with integrated insulation for prefabricated assemblies. RE2020 lifecycle thresholds push specification toward low-emission binders and certified wood sourcing.
- Roof Sheathing:Structural panels with enhanced moisture resistance serve pitched roof assemblies in Atlantic France's humid climate zones.
- Subflooring:Tongue-and-groove platform construction in multi-family residential builds drives specification for stiffness-rated grades.
- Building Materials:General structural applications span non-residential and agricultural construction with lower performance requirements.
Wall Panels retain the largest specification share, though Roof Sheathing is expanding most quickly in coastal humidity zones.
Distribution Channel:
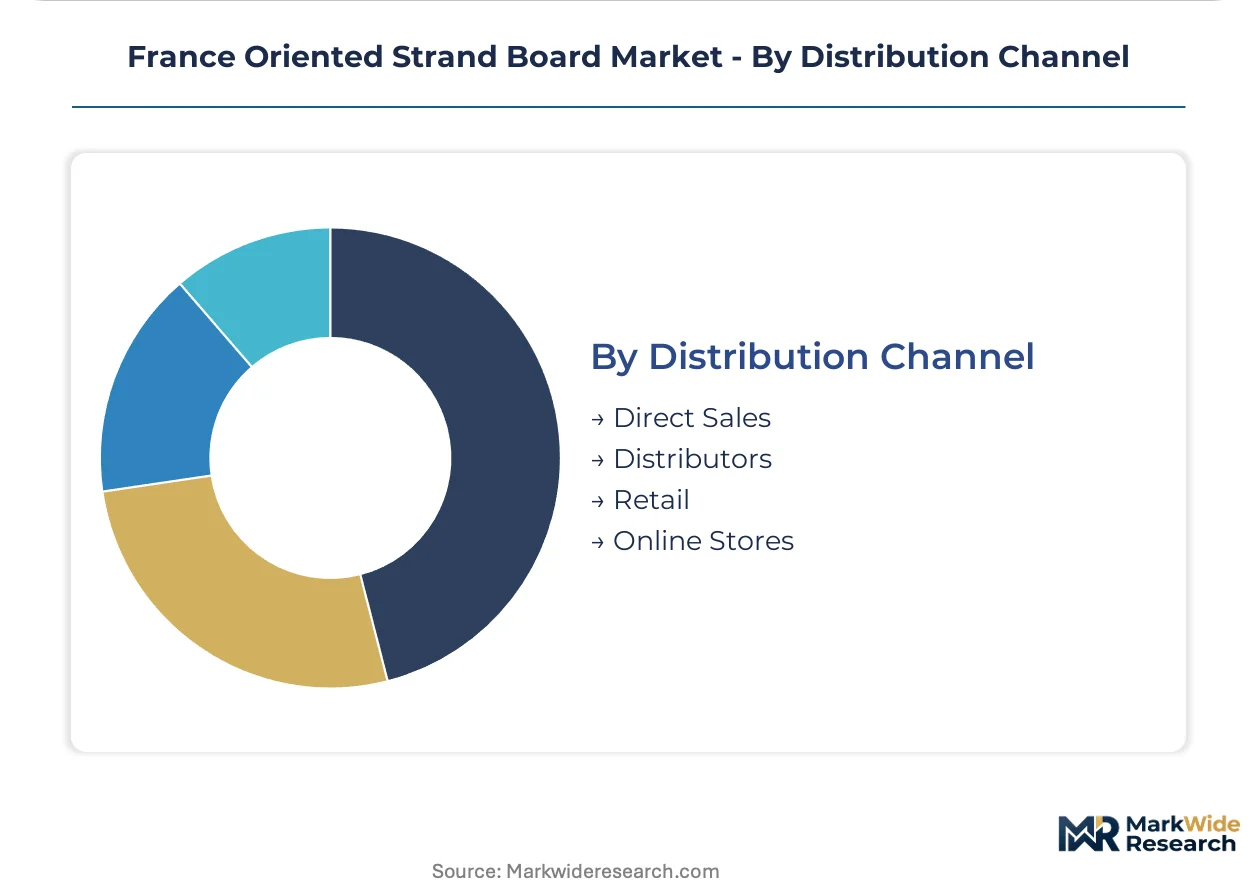
Channel selection tracks project scale and carbon documentation burden, with large builders consolidating around direct supply relationships.
- Direct Sales:National timber-frame builders and modular system manufacturers contract directly with mills for volume procurement with integrated thermal barrier supply.
- Distributors:Regional building material wholesalers serve mid-tier contractors with mixed product portfolios across Grand Est processing clusters.
- Retail:Home improvement centers capture renovation demand with commodity structural grades in bagged and palletized formats.
- Online Stores:Digital procurement channels serve small contractors and DIY segments with limited geographic penetration.
Direct Sales holds the revenue concentration, while Retail is gaining transaction volume fastest through big-box expansion in secondary metropolitan zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across French sub-regions. Grand Est buyers prioritize logistics savings from mill proximity, while Atlantic coastal markets absorb moisture-resistant grade premiums without volume erosion.
Grand Est
Prefabricated wall system manufacturers cluster around Strasbourg and Nancy, pulling structural panels for timber-frame housing. RE2020 lifecycle carbon thresholds push specification toward certified wood sourcing with Environmental Product Declarations. Sawmill residuals feed directly into strand production across the Vosges timber processing belt.
Nouvelle-Aquitaine
Bordeaux and Toulouse metropolitan zones outpace national housing start averages, creating unmet panel demand from modular builders. ANR innovation funding steers producers toward bio-based binder commercialization. The Landes forest corridor anchors wood supply chains with integrated chipping and strand drying infrastructure.
Île-de-France
Platform-frame multi-family construction in the Paris Basin drives specification for tongue-and-groove flooring grades. RE2020 biogenic carbon accounting requirements strain engineering firm capacity for compliance documentation. Big-box retail expansion in secondary metropolitan zones captures renovation demand through palletized commodity distribution.
Auvergne-Rhône-Alpes
Lyon corridor timber-frame contractors consolidate procurement around single-source suppliers with thermal barrier integration. ADEME circular economy incentives enable post-consumer fiber differentiation. The Massif Central wood basin feeds regional mills with softwood residuals for cross-oriented strand layers.
Occitanie
Toulouse aerospace industry spillover sustains demand for industrial crating and pallet applications with minimal certification requirements. Coastal humidity zones in Mediterranean fringe areas command specialty grade premiums over commodity structural panels. Montpellier logistics hubs distribute moisture-resistant specifications toward Atlantic-facing construction zones.
France Oriented Strand Board Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes within the France Oriented Strand Board Market. Integrated resin producers control input cost volatility through captive phenolic capacity, while continuous press specialists sustain thinner-panel output at scale. Three archetypes dominate: integrated chemical-panel producers, technology-scale specialists, and regional moisture-grade specialists. Competitive moves concentrate on capacity expansion in timber-proximate zones and strategic partnerships for prefabricated wall system integration.
Within the integrated producer tier, Kronospan exemplifies captive resin capacity advantages across French mill networks. EGGER Group occupies a position as the technology-scale specialist through continuous press investments. Swiss Krono Group anchors the regional specialist archetype with moisture-resistant grade focus for Atlantic coastal markets. These three represent divergent strategic paths: upstream chemical control, manufacturing technology leadership, and climate-zone product specialization.
| Leading Market Players |
|---|
| Kronospan |
| Swiss Krono Group |
| EGGER Group |
| West Fraser |
| Sonae Arauco |
| SMARTPLY Europe |
| FINSA |
| Pfleiderer Group |
| Louisiana-Pacific Corporation |
| Others |
Pricing and Supply Chain Analysis
CE marking under the Construction Products Regulation gates both supplier qualification and price differentiation in the France Oriented Strand Board Market, compressing margins for uncertified imports while rewarding verified Environmental Product Declarations with specification premiums. Builders facing RE2020 lifecycle carbon thresholds must document chain-of-custody compliance, creating a bifurcated supply base where certified mills capture pricing power and commodity converters compete on logistics proximity alone.
Pricing Analysis
After-sales service contracts for prefabricated wall system integration drive lifetime value beyond commodity panel transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal barrier bundling. Cost compression in economy structural grades is intensifying because phenol-formaldehyde resin volatility transmits directly to converter margins without corresponding panel price recovery. DIY retail channels exhibit highest price sensitivity, while national timber-frame builders absorbing RE2020 compliance costs show lowest sensitivity to per-panel premiums.
Supply Chain Analysis
France and Germany anchor OSB panel manufacturing across the EU, with Belgium and Austria feeding specialized moisture-resistant grades toward Atlantic coastal markets. Strand production draws from Vosges and Massif Central sawmill residuals, while phenolic resin supply rests on German and Dutch petrochemical complexes. Single-source vulnerability concentrates in MDI binder procurement from limited European chemical plant capacity. Distribution runs through regional building material wholesalers serving Grand Est processing clusters, with direct mill contracts capturing national builder volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated construction platform economics are reaching an inflection as wall system manufacturers consolidate procurement around single-source suppliers capable of thermal barrier integration. This interoperability shift rewards integrated panel-insulation capabilities over standalone commodity supply.
For Market Incumbents: Shield specification lock-in by deepening captive phenolic resin capacity across French mill networks. Invest in continuous press technology for thinner-panel output at scale to match EGGER Group's manufacturing leadership. Cross-laminated timber substitution in commercial mid-rise construction threatens load-bearing wall assemblies above four stories, demanding preemptive thermal barrier integration partnerships with modular system manufacturers.
For New Entrants and Emerging Players: Lead with bio-based binder commercialization targeting RE2020 biogenic carbon accounting gaps, where few French engineering firms possess lifecycle assessment capabilities for regulatory compliance. Nouvelle-Aquitaine housing expansion in Bordeaux and Toulouse metropolitan zones offers the most penetrable geography, outpacing national construction starts. Pursue ANR innovation funding to differentiate through post-consumer fiber integration and recycled wood content verification systems.
For Investors and Strategic Acquirers: RE2020's upcoming biogenic carbon accounting rules reshape the acquisition landscape toward producers with verified Environmental Product Declarations and certified chain-of-custody infrastructure. Long-term viability across the next decade hinges on backward integration into resin chemistry or forward integration into prefabricated wall assembly supply. Target mid-tier mills with Grand Est timber cluster proximity and stranded continuous press capacity. Watch enforcement granularity of RE2020 biogenic carbon methodologies as the signal for which panel specifications secure permanent specification lock-in with national builders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | Captive phenolic capacity shields margin compression from petrochemical input volatility. |
| Continuous Press Technology Investment | Thinner-panel output at scale sustains competitive positioning against EGGER Group manufacturing leadership. |
| Bio-Based Binder Commercialization | ANR funding accelerates low-emission alternatives capturing RE2020 specification premiums. |
| Thermal Barrier Integration Partnership | Prefabricated wall system consolidation rewards single-source sheathing-insulation capabilities. |
| Post-Consumer Fiber Verification System | ADEME circular economy incentives enable differentiation through recycled wood content integration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at timber-frame builders, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, SEC filings, French building permit databases, and ADEME funding disclosure records. Bottom-up volume triangulation across Grand Est and Nouvelle-Aquitaine processing clusters converged with top-down construction spend allocation models.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product grade tier, end-use application, distribution channel structure, and regional timber processing hub proximity. CAGRs were derived from housing start trajectories, embodied carbon regulatory phase-in schedules, and prefabricated construction adoption curves. Industry-specific inputs incorporated RE2020 compliance cost pass-through assumptions and MDI binder supply elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained RE2020 enforcement, stable petrochemical input costs, or continued prefabricated construction adoption would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and builder specification behavior. Recalibration cycles align with material shifts in ANR funding allocations, biogenic carbon accounting rule finalization, and cross-laminated timber cost competitiveness inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Sandwich Panel System Market