
 Short-Read Sequencing Market | 2026-2036
Short-Read Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Read Sequencing Market Outlook
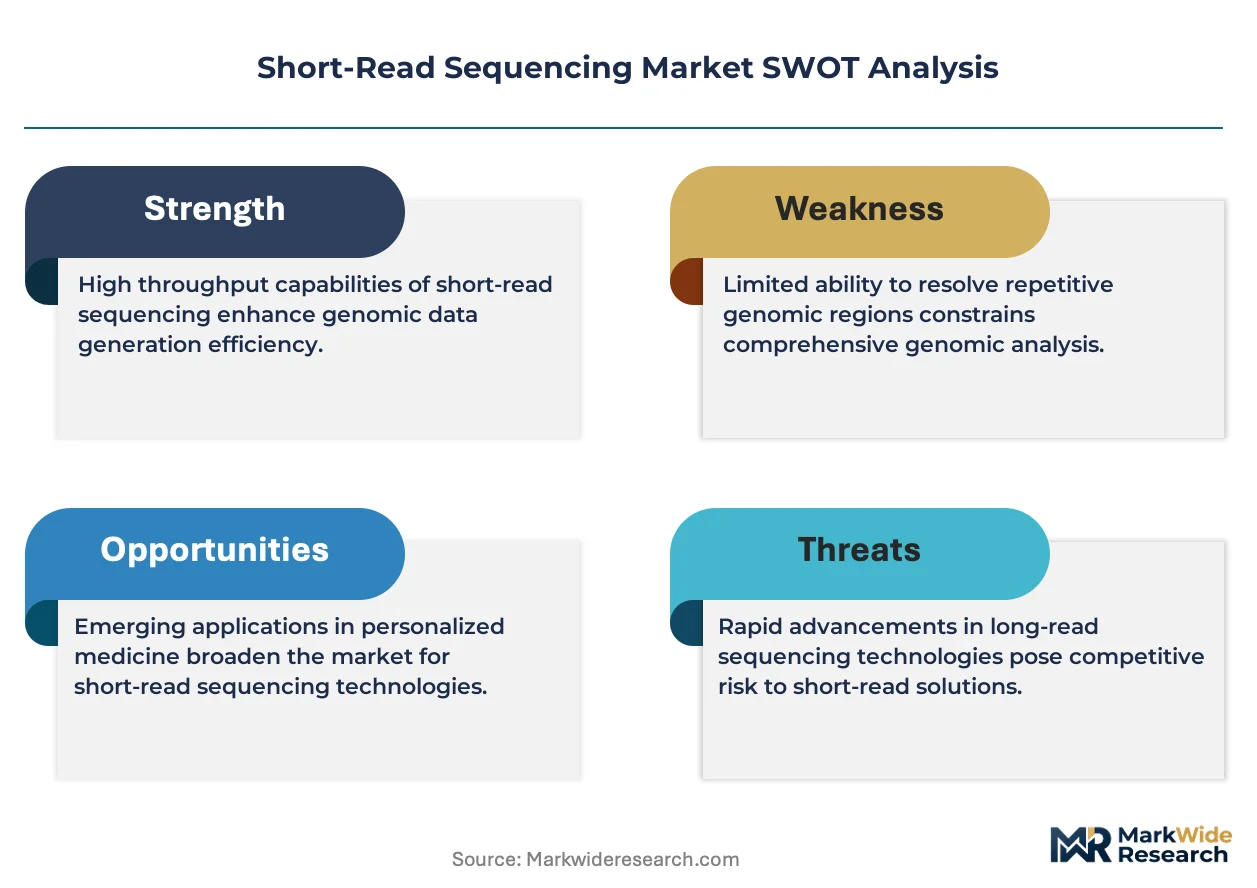
High-accuracy clinical-grade sequencing is collapsing the boundary between research tools and regulated diagnostics. Illumina, Inc. anchors the installed base with its NovaSeq architecture and consumables lock-in. Thermo Fisher Scientific, Inc. leverages its Applied Biosystems Ion Torrent channel to compete in translational labs. QIAGEN specializes in sample-to-insight workflows that extend its library preparation dominance into sequencing-adjacent revenue.
Short-read sequencing determines nucleotide order in DNA or RNA fragments typically under 300 base pairs using reversible terminator or semiconductor detection chemistries, with primary purpose centered on variant calling, gene expression profiling, and microbial identification at massive parallel scale. Library preparation kits capture the fastest-expanding margin pool as automation reduces hands-on time and reagent standardization improves. Among applications, clinical diagnostics outpaces genomic research in growth velocity, though agricultural biotechnology remains an underdeveloped avenue for platform vendors.
FDA oversight of next-generation sequencing-based diagnostics shapes product development timelines and evidence requirements for 510(k) and PMA pathways, while ISO 13485 certification governs manufacturing quality for instruments entering regulated markets. EMA's In Vitro Diagnostic Regulation in Europe imposes parallel conformity assessment burdens that filter market access for non-compliant suppliers. Stakeholders must monitor evolving reimbursement codes for molecular diagnostics, as coverage determinations by CMS and analogous national health technology assessment bodies will dictate the addressable clinical volume for sequencing platforms.
Market Dynamics
Clinical laboratories are consolidating sequencing workflows onto integrated platforms, compressing the vendor landscape as FDA-cleared assays displace research-grade protocols in diagnostic settings.
Growth Catalysts
- NIH funding intensity:Sustained federal investment in genomic medicine accelerates platform procurement at academic medical centers and translational research institutes across the United States.
- Library preparation automation:Automated liquid handling systems reduce hands-on time from hours to minutes, enabling clinical labs to scale test throughput without proportional staffing increases.
- FDA 510(k) pathway expansion:Streamlined premarket notification processes for next-generation sequencing-based diagnostics compress time-to-market for assay developers.
Market Restraints
- Consumables cost concentration:Proprietary reagent lock-in with single-source suppliers elevates per-run economics and limits vendor switching flexibility.
- Semiconductor supply fragility:Ion Torrent platforms depend on specialized chip fabrication concentrated in East Asian foundries, exposing production schedules to geopolitical disruption.
- Short-read assembly limitations:Fragment lengths below 300 base pairs constrain resolution of complex structural variants and repetitive genomic regions.
Strategic Opportunities
- Agricultural biotechnology underpenetration:Crop breeding programs and livestock genomic selection remain underserved by clinical-focused platform vendors.
- Sample-to-insight convergence:Integration of primary analysis pipelines with laboratory information management systems creates stickier customer relationships.
- EMA IVDR transition window:European diagnostic manufacturers face 2027-2028 conformity deadlines that favor pre-certified platform suppliers.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical labs struggle to recruit computational biologists capable of validating variant calling pipelines under CAP/CLIA requirements.
- Instrument qualification timelines:IQ/OQ/PQ documentation for regulated environments extends deployment cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Read Sequencing Market |
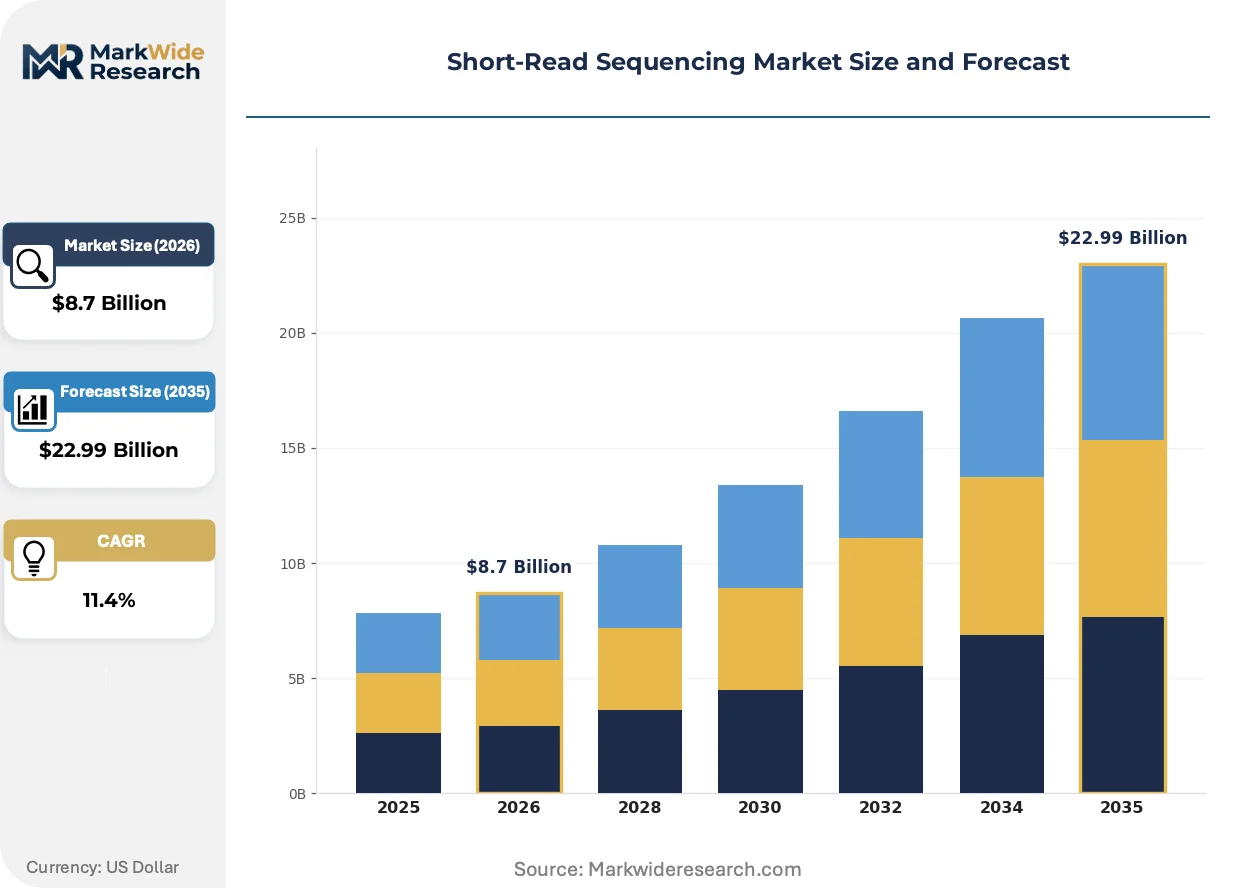
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencers, RNA Sequencers, Library Preparation Kits, Consumables Application: Genomic Research, Clinical Diagnostics, Therapeutics Development, Agricultural Biotechnology End User: Research Institutions, Hospitals, Pharmaceutical Companies, CROs Technology: Sanger Sequencing, Illumina Sequencing, Ion Torrent, Next-Generation Sequencing |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Inc., BGI, Agilent Technologies, QIAGEN, Pacific Biosciences of California, Inc., Psomagen, Azenta US, Inc., PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Read Sequencing Market Strategic Shifts
Sequencing hardware and assay chemistries are converging toward point-of-care deployment, eroding the historical separation between centralized reference labs and distributed testing sites.
Portable sequencing devices are miniaturizing optical and semiconductor detection systems into benchtop footprints suitable for hospital pathology departments. Community hospitals and regional health systems are adopting these compact platforms to retain oncology and infectious disease testing locally. This footprint reduction is miniaturizing the capital barrier that previously concentrated sequencing capability at academic centers.
EMA's In Vitro Diagnostic Regulation imposes parallel conformity assessment burdens that filter market access for non-compliant suppliers. Manufacturers must maintain technical documentation and quality management systems exceeding prior CE-mark requirements. European diagnostic labs are prioritizing platform vendors with established notified body relationships to mitigate transition risk.
Service unbundling is separating instrument placement from reagent supply and bioinformatics support. Hospital procurement departments are negotiating reagent rental agreements that convert capital expenditure into operational budgets. This financing shift is most pronounced in United States health systems responding to CMS reimbursement compression for molecular diagnostics.
Short-Read Sequencing Market Segmentation
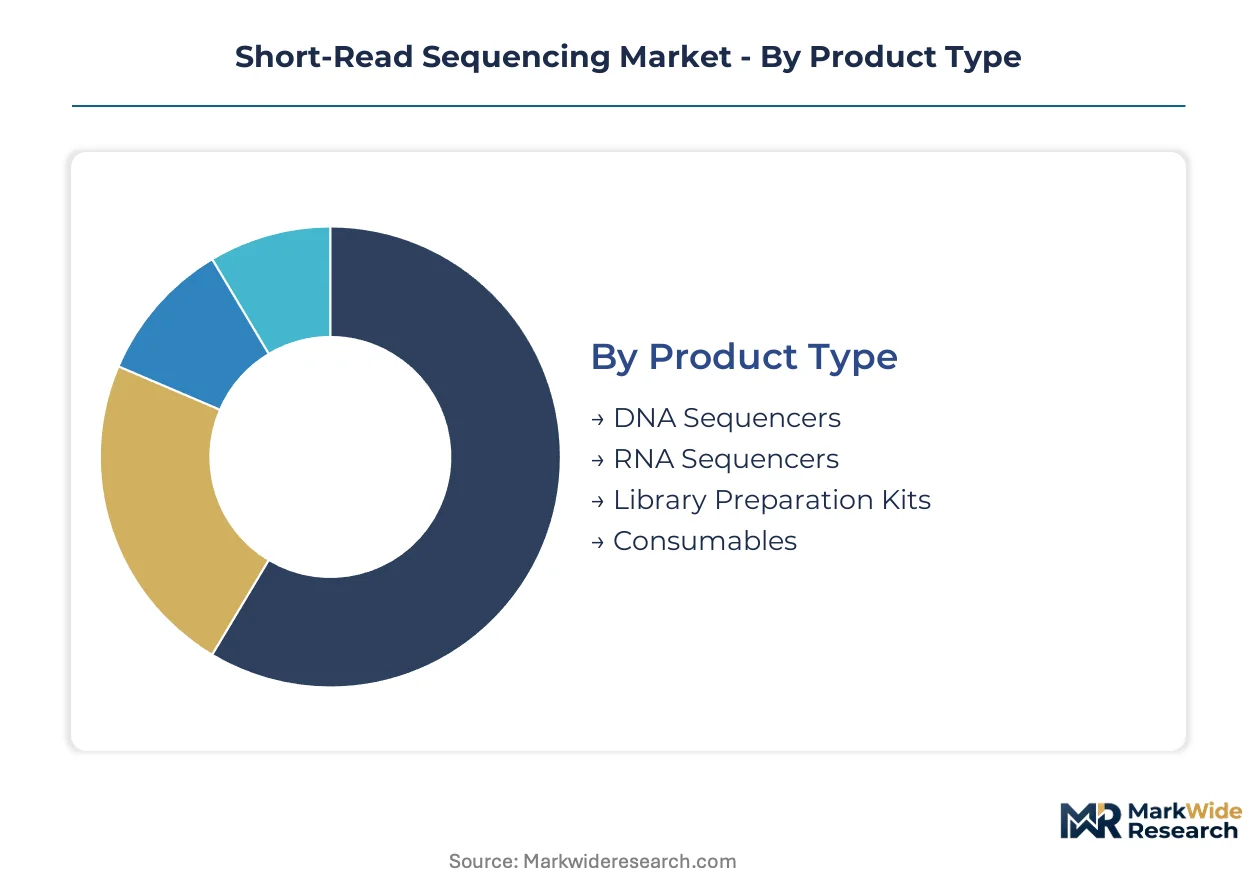
Segmentation in short-read sequencing reveals distinct procurement patterns across product categories, with channel economics dictating how platforms and consumables reach end-users. Understanding these flows enables vendors to optimize pricing architecture and distributor relationships.
Product Type:
Channel distribution varies sharply by product form—capital equipment moves through direct sales with field service contracts, while consumables flow via distribution partnerships and group purchasing organizations.
- DNA Sequencers:High-throughput instruments deploy reversible terminator chemistry with optical detection systems. Demand concentrates at academic medical centers in the United States, where NIH instrumentation grants sustain replacement cycles despite capital budget pressures.
- RNA Sequencers:Specialized configurations optimize for transcriptome complexity and strandedness requirements. Pharmaceutical companies in Cambridge, Massachusetts and South San Francisco drive procurement for target discovery pipelines, prioritizing throughput over per-run cost.
- Library Preparation Kits:Automated workflows reduce hands-on time for clinical labs.
- Consumables:Flow cells and reagents generate recurring revenue through proprietary lock-in.
By volume, Consumables leads. By growth pace, Library Preparation Kits is climbing the fastest.
Application:
Cost tier stratification separates research-grade protocols from FDA-cleared diagnostic workflows, with reimbursement codes determining addressable market size.
- Genomic Research:Discovery-focused applications prioritize breadth over regulatory compliance. Research institutions in the United States and Germany sustain this segment through institutional funding mechanisms, though budget constraints are lengthening replacement cycles.
- Clinical Diagnostics:Regulated assays require CAP/CLIA validation and FDA clearance. Hospitals in the United States are consolidating oncology and infectious disease testing onto integrated platforms, with CMS coverage determinations dictating test menu expansion.
- Therapeutics Development:Companion diagnostic requirements drive precision medicine adoption.
- Agricultural Biotechnology:Crop breeding programs remain underserved by clinical-focused vendors.
By revenue concentration, Clinical Diagnostics dominates. By expansion trajectory, Agricultural Biotechnology shows the steepest untapped potential.
End User:
Customer type determines purchasing authority structure—institutional procurement committees versus hospital supply chain departments versus R&D budget holders.
- Research Institutions:Academic labs prioritize grant-funded instrument access and shared core facilities. Universities in the United States negotiate multi-year service contracts, with NSF and NIH funding cycles driving placement timing.
- Hospitals:Integrated delivery networks centralize molecular diagnostics under laboratory medicine departments. Health systems in Texas and California are deploying benchtop sequencers to retain oncology testing locally rather than outsourcing to reference labs.
- Pharmaceutical Companies:Internal sequencing capacity supports target validation and biomarker programs.
- CROs:Contract providers offer sequencing as a service to biotech without capital investment.
By installed base, Research Institutions holds the largest footprint. By procurement velocity, Hospitals is gaining share fastest.
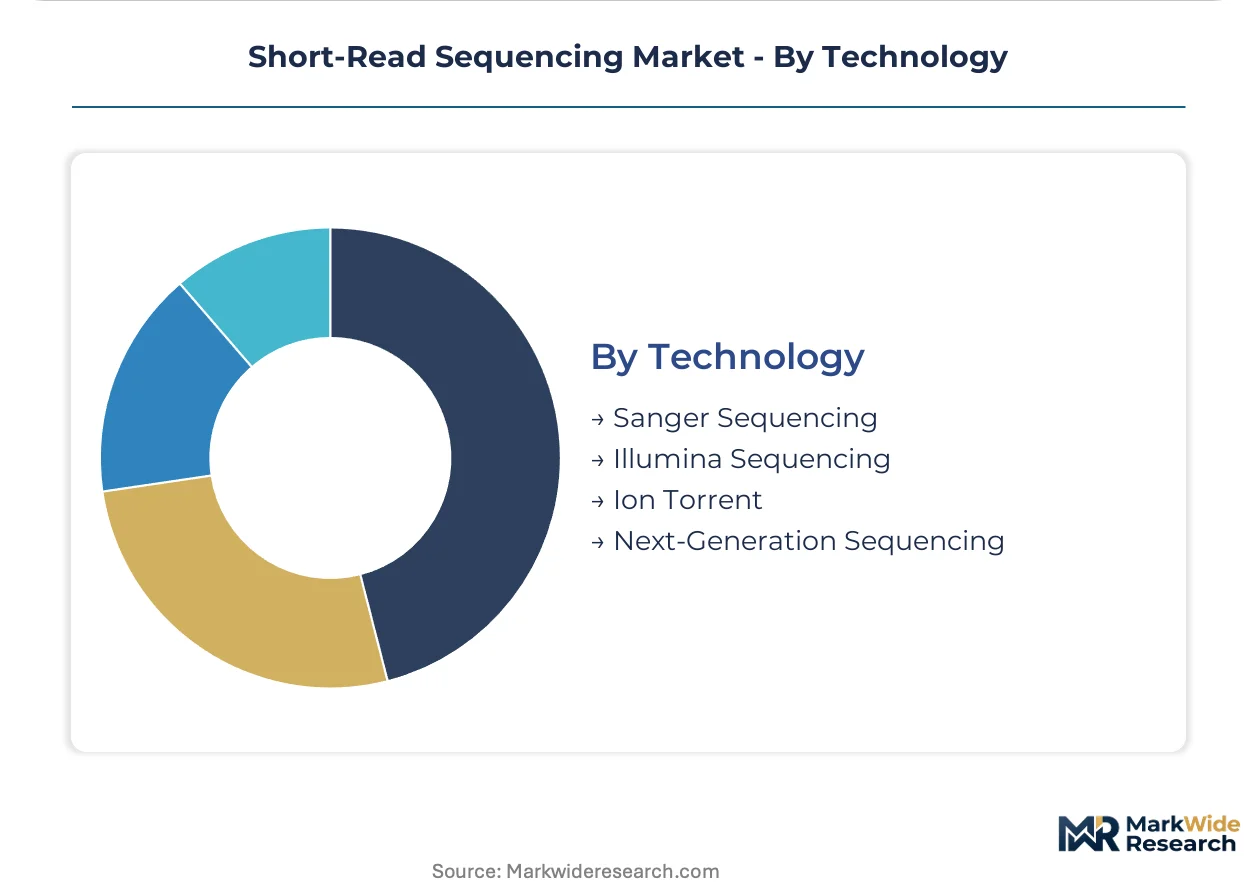
Technology:
Maturity curves separate established chemistries from next-generation platforms, with semiconductor detection challenging optical systems in specific throughput tiers.
- Sanger Sequencing:First-generation capillary electrophoresis remains essential for targeted validation and forensics. Forensic laboratories in the United States and judicial systems across Europe sustain demand for mitochondrial DNA and short tandem repeat analysis.
- Illumina Sequencing:Reversible terminator chemistry dominates high-throughput applications. Clinical labs in the United States standardize on this platform architecture, creating consumables lock-in that competitors struggle to displace.
- Ion Torrent:Semiconductor detection offers faster run times for targeted panels.
- Next-Generation Sequencing:Umbrella category encompassing emerging chemistries beyond dominant platforms.
By revenue scale, Illumina Sequencing leads. By technical differentiation, Ion Torrent shows the fastest adoption in translational settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing instrument and consumable trade flows concentrate in research-intensive economies with established biomedical manufacturing bases. The United States maintains net exporter status for high-throughput platforms, while China and Germany balance substantial domestic production against significant reagent imports.
United States
NIH instrumentation grants and FDA-cleared diagnostic applications sustain platform procurement at academic medical centers in Boston and San Francisco. The 21st Century Cures Act accelerated regulatory pathways for breakthrough devices. The Research Triangle in North Carolina hosts contract sequencing providers scaling clinical test menus for hospital networks.
China
Domestic sequencer manufacturing expands alongside precision medicine initiatives under the 14th Five-Year Plan. NMPA streamlined registration pathways for innovative medical devices in 2023. The Yangtze River Delta cluster around Shanghai concentrates reagent production and clinical validation partnerships.
Germany
Industrial genomics demand from pharmaceutical companies in Frankfurt and Munich drives high-throughput platform adoption. EMA's In Vitro Diagnostic Regulation imposes conformity assessment requirements filtering non-compliant suppliers. The Munich biotech corridor integrates sequencing into automated laboratory workflows for clinical diagnostics.
United Kingdom
Genomics England contracts and NHS genomic medicine service expansion sustain instrument placement at regional hubs. MHRA operates parallel recognition routes for FDA-cleared diagnostics post-Brexit. The Cambridge-Oxford-London triangle concentrates target discovery sequencing for biotechnology companies.
Japan
Aging-related disease research and companion diagnostic requirements from PMDA sustain platform demand at university hospitals in Tokyo and Osaka. METI funding for healthcare innovation supports domestic sequencer development initiatives. The Kansai biomedical cluster integrates sequencing into pathology workflows for oncology testing.
Short-Read Sequencing Market Competitive Environment
Listed leaders compete with private specialists across platform architecture and consumables supply. The market exhibits tiered concentration with dominant installed-base holders controlling reagent economics. Three archetypes prevail: integrated platform-consumables providers, sample-to-insight workflow specialists, and semiconductor-detection challengers. Competitive moves center on strategic partnerships for assay development and geographic expansion into underpenetrated clinical markets.
Within the integrated platform tier, Illumina, Inc. and Thermo Fisher Scientific, Inc. occupy positions as archetypal installed-base anchors with consumables lock-in mechanisms. QIAGEN exemplifies the sample-to-insight specialist archetype, extending library preparation dominance into sequencing-adjacent revenue streams. These three companies collectively represent the competitive structure governing procurement decisions at academic medical centers, hospital laboratories, and pharmaceutical research divisions.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| BGI |
| Agilent Technologies |
| QIAGEN |
| Pacific Biosciences of California, Inc. |
| Psomagen |
| Azenta US, Inc. |
| PerkinElmer, Inc. |
| Others |
Value Chain & Pricing Dynamics
Reagent rental agreements lock in multi-year consumables commitments for hospital laboratories, binding price visibility to instrument placement contracts across United States health systems responding to CMS reimbursement compression.
Pricing Analysis
Pharmaceutical companies anchor consumables pricing through high-volume offtake contracts for precision medicine pipelines. Pricing stratifies across FDA-cleared diagnostic tiers, research-grade protocols, and agricultural applications, with certification level commanding measurable premiums. Cost compression in clinical workflows intensifies as integrated delivery networks consolidate vendor relationships. Reference laboratories exhibit highest price sensitivity due to thin margin structures, while biopharmaceutical R&D divisions prioritize throughput over per-run economics.
Supply Chain Analysis
Flow cell inventory cycles extend lead times for clinical laboratories during semiconductor fabrication disruptions. Manufacturing concentrates in the United States, China, and Germany, with specialized chip production anchored in East Asian foundries. Supply chains draw from optical components, proprietary polymerases, and semiconductor substrates. Single-source vulnerability around Ion Torrent chip fabrication exposes production schedules to geopolitical friction. Distribution runs through direct sales for capital equipment and group purchasing organizations for recurring consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in short-read sequencing hinge on consumables lock-in mechanisms, with interoperability emerging as the critical battleground as hospital systems demand seamless LIMS integration.
For Market Incumbents: Consolidate installed-base defenses through deeper backward integration into library preparation chemistries and expanded field service contracts. Threat from semiconductor-detection challengers in translational settings demands accelerated FDA 510(k) pathway investment for assay menu expansion. Channel control through exclusive reagent supply agreements remains the priority lever against research-grade protocol displacement. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market access for point-of-care sequencing platforms targeting community hospital pathology departments. Agricultural biotechnology applications remain the most penetrable white-space, with crop breeding programs underserved by clinical-focused vendors. Go-to-market positioning should emphasize benchtop footprint reduction and local oncology test retention. For Investors and Strategic Acquirers: Sample-to-insight workflow specialists with established notified body relationships capture EMA IVDR transition premiums. Long-term viability over the coming decade rests on regulatory moat depth rather than raw technical specifications. Signal to watch: CMS coverage determination velocity for liquid biopsy applications as inflection indicator for clinical volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Backward Integration | Captive reagent supply secures margin pools against third-party kit displacement in clinical labs. |
| FDA Breakthrough Device Pathway | Expedited premarket review compresses time-to-revenue for diagnostic assay developers. |
| LIMS Platform Integration | Seamless data pipeline connectivity creates switching costs for hospital laboratory customers. |
| Agricultural Biotechnology Expansion | Livestock genomic selection and crop breeding open untapped volume outside saturated clinical markets. |
| EMA Notified Body Pre-Certification | Established quality management systems filter competitor access during IVDR transition windows. |
Study Parameters
Initial hypotheses were tested against primary input from clinical laboratory directors, pharmaceutical biomarker program leads, and sequencing core facility managers and refined through secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, NIH instrumentation grant databases, and CMS coverage determination records. Bottom-up instrument placement modeling triangulated against top-down consumables revenue estimates.
Variance decomposition across the projection horizon isolates volume drivers from price mix effects. Segmentation dimensions span product type, application tier, end-user category, and technology chemistry, with regulatory pathway status modeled as an orthogonal dimension. CAGRs derive from logistic adoption curves fitted to historical platform replacement cycles and NIH funding intensity projections. Forecast inputs include semiconductor fabrication capacity constraints and EMA conformity assessment timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal research funding or stable trade flows would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code expansion and regulatory pathway streamlining. Semiconductor supply disruptions or IVDR implementation delays represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Genetic Testing Panels Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
UAE Genetic Testing Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Single-Cell Omics Market
Genomics
Glycan Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Predisposition Biomarkers Market
Genomics
Europe Digital PCR Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Alagille Syndrome Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market