
 Immunogenetics Market | 2026-2036
Immunogenetics Market Size, Share, and Industry Trends Forecast 2026-2036
Immunogenetics Market Foresight
CLIA certification for high-complexity molecular diagnostics is rotating the competitive landscape toward laboratories and platform vendors with proven quality management systems. Illumina leverages its installed base of sequencing instruments to dominate HLA typing workflows in North American transplant networks. Thermo Fisher Scientific sustains broad portfolio coverage across reagents, instruments, and analytical software for immunogenetics applications. QIAGEN competes through specialized sample preparation technologies that integrate with downstream sequencing and PCR-based HLA analysis.
Immunogenetics encompasses the study of genetic influences on immune responses, including HLA gene polymorphism analysis, antibody repertoire sequencing, and cytokine gene expression profiling using quantitative PCR and next-generation sequencing methods with sensitivity thresholds reaching single-digit variant allele frequencies. Its primary commercial purpose centers on matching donors and recipients for organ and stem cell transplantation, predicting autoimmune disease risk, and stratifying patients for immunotherapy in oncology. Gene therapy segments within product type categories show the fastest expansion as CAR-T and gene-edited cell therapies require precise immunogenetic characterization to prevent graft rejection and immune-related adverse events. Transplantation applications maintain the largest revenue share due to mandatory HLA matching protocols in solid organ and hematopoietic stem cell procedures across accredited medical centers.
FDA oversight of companion diagnostics and cell therapy products shapes product development timelines and clinical validation requirements for immunogenetics platforms, while CLIA and CAP accreditation standards govern laboratory operations and test report reliability. ISO 15189 medical laboratory standards and the EU In Vitro Diagnostic Regulation create parallel compliance pathways for vendors seeking multi-jurisdictional market access. Stakeholders must monitor evolving reimbursement policies for molecular HLA typing and cell therapy companion testing as these determinations will dictate which technology platforms achieve sustainable adoption in clinical practice.
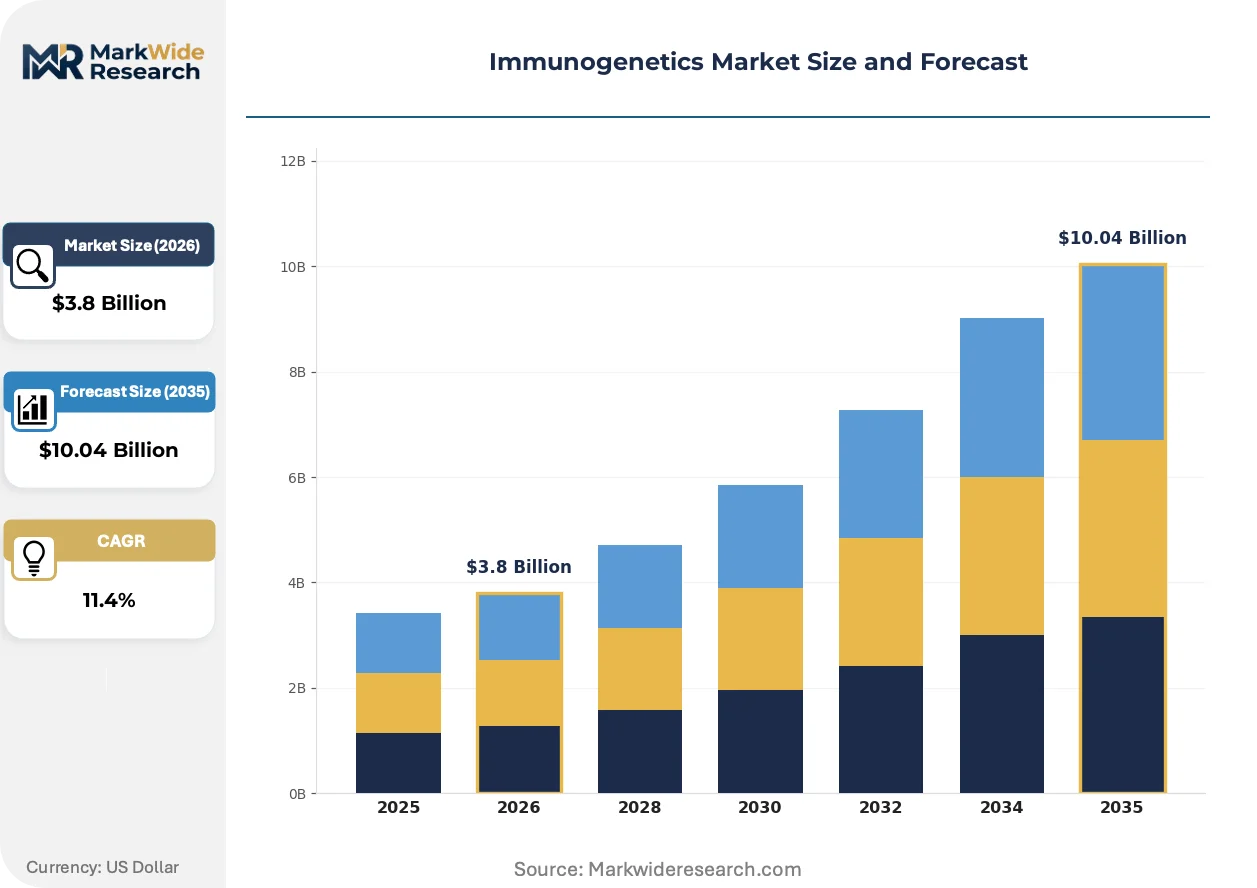
Market Dynamics
Next-generation sequencing platforms are compressing HLA typing turnaround times from weeks to days, forcing transplant centers to restructure laboratory workflows and capital allocation around molecular immunogenetics infrastructure.
Growth Catalysts
- FDA companion diagnostics guidance:Accelerating clinical validation investments for immunogenetics platforms used in cell therapy manufacturing and transplant matching protocols across accredited US medical centers.
- CAR-T manufacturing expansion:Gene-edited cell therapies require precise HLA characterization to prevent graft rejection, creating sustained demand for high-resolution typing services in bioprocessing facilities.
- Academic research institutes:Expanding adoption of antibody repertoire sequencing and cytokine profiling for autoimmune disease biomarker discovery drives instrument placement and reagent consumption.
Market Restraints
- Reagent supply concentration:Specialized enzymes and fluorescent probes for quantitative PCR-based HLA analysis originate from limited qualified suppliers, creating vulnerability to batch variability and allocation constraints.
- EU In Vitro Diagnostic Regulation compliance costs:Technical documentation and performance study requirements for Class C devices impose capital barriers for smaller platform developers seeking CE marking.
- Long-read sequencing substitution:Emerging nanopore technologies threaten incumbent short-read platforms for complex HLA allele resolution, potentially obsoleting installed base investments.
Strategic Opportunities
- India's transplant infrastructure expansion:Government initiatives to establish organ allocation networks create first-mover positioning for HLA typing service providers in underserved metropolitan hospital clusters.
- Cloud-based analytical software:Remote bioinformatics pipelines enable reference laboratories to access enterprise-grade variant calling without on-premise compute infrastructure, lowering entry barriers for mid-tier facilities.
- ISO 15189 accreditation convergence:Harmonized medical laboratory standards across Middle Eastern healthcare systems create pathway for multi-jurisdictional platform deployment and service contracts.
Industry Challenges
- Bioinformatics specialist scarcity:Interpretation of complex HLA allele combinations and pharmacogenomic variants requires hybrid molecular biology-computational expertise that outpaces training pipeline output.
- CLIA high-complexity certification timelines:Laboratory accreditation for molecular diagnostics involves protracted proficiency testing and inspection cycles that delay revenue recognition for new test launches.
- Legacy LIS integration friction:Immunogenetics platforms must interface with established laboratory information systems through proprietary data formats, complicating workflow automation and result reporting standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunogenetics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Cytokines, Gene Therapy, Vaccines Application: Autoimmune Disorders, Infectious Diseases, Cancer Therapy, Transplantation End User: Academic Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Healthcare Providers Technology: Genomics, Proteomics, CRISPR, Cell Therapy |
| Companies Covered | QIAGEN, Illumina, CareDx, Omixon, Thermo Fisher Scientific, GenDx, Bio-Rad Laboratories, Immucor, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunogenetics Market Shifts & Advancements
Artificial intelligence is penetrating variant interpretation workflows, while regulatory frameworks on both sides of the Atlantic tighten quality requirements for diagnostic outputs used in clinical decision-making.
Third-generation sequencing is fragmenting the HLA typing market structure. Oxford Nanopore's real-time basecalling enables point-of-need allele resolution without centralized laboratory infrastructure. Transplant centers in Australia and Saudi Arabia are piloting decentralized protocols that bypass reference laboratory queues. This capability is fragmenting volume concentration away from established high-throughput sequencing hubs toward distributed hospital-based testing.
REACH chemical registration requirements in Europe are restricting fluorophore and polymerase formulations used in quantitative PCR reagents. Manufacturers must submit extensive toxicity dossiers for novel chemistries, extending development timelines by eighteen to thirty-six months. Immunogenetics reagent suppliers are responding by reformulating existing dye conjugates rather than introducing novel detection chemistries, slowing innovation velocity in the European market.
Reference laboratories are unbundling analytical software from instrument hardware contracts, enabling transplant centers to select best-of-breed bioinformatics pipelines independent of sequencing platform vendor lock-in. This purchasing autonomy is disrupting traditional reagent rental business models that subsidized instrument placement through consumable commitments. The United States exhibits the most pronounced unbundling behavior, where CLIA-certified laboratories prioritize interoperability over integrated stack solutions.
Immunogenetics Market Segmentation
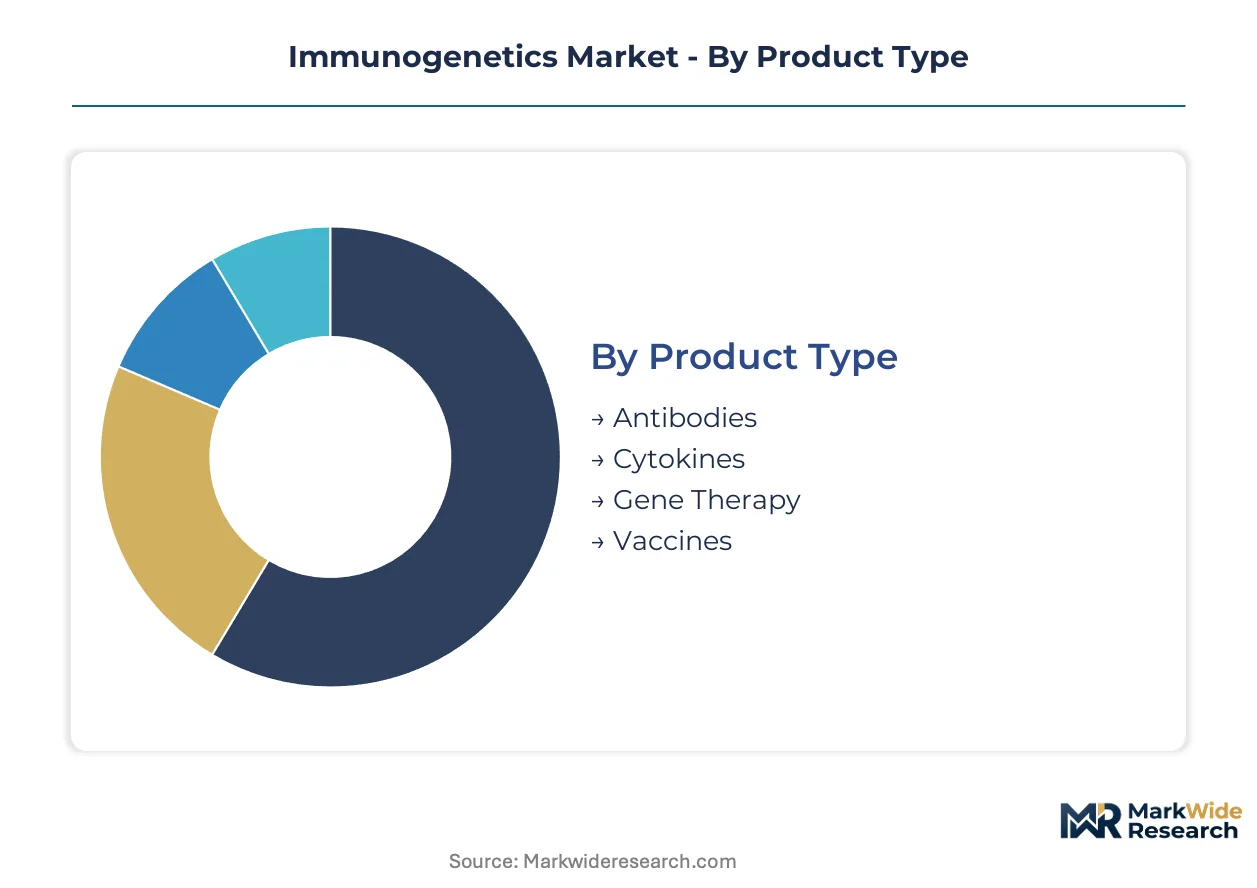
Immunogenetics market segmentation reveals divergent margin structures across molecular platforms and therapeutic applications. Product type categories separate high-value gene therapy reagents from commodity antibody supplies, while end-user concentration in transplant centers versus academic labs creates distinct purchasing power dynamics.
Product Type:
Gene therapy reagents command premium pricing due to regulatory validation requirements and batch certification complexity, whereas antibody products compete on scale economies.
- Gene Therapy:Viral vector characterization and CAR-T cell engineering demand precise HLA compatibility testing. Contract development organizations in the United States and Germany drive sustained consumption of clinical-grade immunogenetic assays for IND-enabling studies.
- Cytokines:Quantitative PCR panels measuring interleukin gene expression profiles support pharmacodynamic monitoring in immuno-oncology trials. Academic medical centers in Boston and San Francisco represent concentrated procurement nodes for multiplex cytokine analysis platforms.
- Antibodies:Therapeutic antibody development relies on immunogenetic screening for immunogenicity risk assessment.
- Vaccines:Adjuvant response profiling uses HLA typing to stratify clinical trial cohorts by predicted immunogenicity.
Gene therapy holds installed capacity. Cytokines is rotating up the share rankings.
Application:
Transplantation protocols mandate HLA matching with near-perfect compliance rates, creating predictable revenue streams, whereas cancer therapy applications exhibit variable adoption depending on immuno-oncology pipeline maturity.
- Transplantation:Solid organ and hematopoietic stem cell procedures require high-resolution HLA typing for donor-recipient matching. UNOS-accredited centers across the United States maintain dedicated molecular diagnostics laboratories with continuous reagent consumption.
- Cancer Therapy:Checkpoint inhibitor companion diagnostics use tumor mutational burden and HLA class I loss analysis. MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center pilot neoantigen prediction algorithms requiring immunogenetic data integration.
- Autoimmune Disorders:HLA-B27 and HLA-DRB1 allele testing supports ankylosing spondylitis and rheumatoid arthritis diagnosis.
- Infectious Diseases:Host genetic susceptibility profiling informs vaccine response prediction and antiviral therapy selection.
Transplantation anchors procurement volume. Cancer therapy is climbing the fastest.
End User:
Diagnostic laboratories concentrate instrument purchasing authority through CLIA-certified high-complexity testing designations, while pharmaceutical companies spread demand across discovery and clinical development phases.
- Diagnostic Laboratories:Reference laboratories such as LabCorp and Quest Diagnostics operate centralized HLA typing facilities serving hospital networks. CAP accreditation requirements enforce standardized quality systems that favor established platform vendors with proven analytical validation packages.
- Pharmaceutical Companies:Cell therapy manufacturers internalize immunogenetics capabilities to support autologous product release testing. Bristol Myers Squibb and Novartis maintain captive testing laboratories for CAR-T product characterization.
- Academic Research Institutes:National Institutes of Health-funded investigators drive antibody repertoire sequencing adoption for basic immunology research.
- Healthcare Providers:Hospital-based transplant programs increasingly outsource molecular testing to reference laboratory networks.
Diagnostic laboratories dominate capital deployment. Pharmaceutical companies are gaining share fastest.
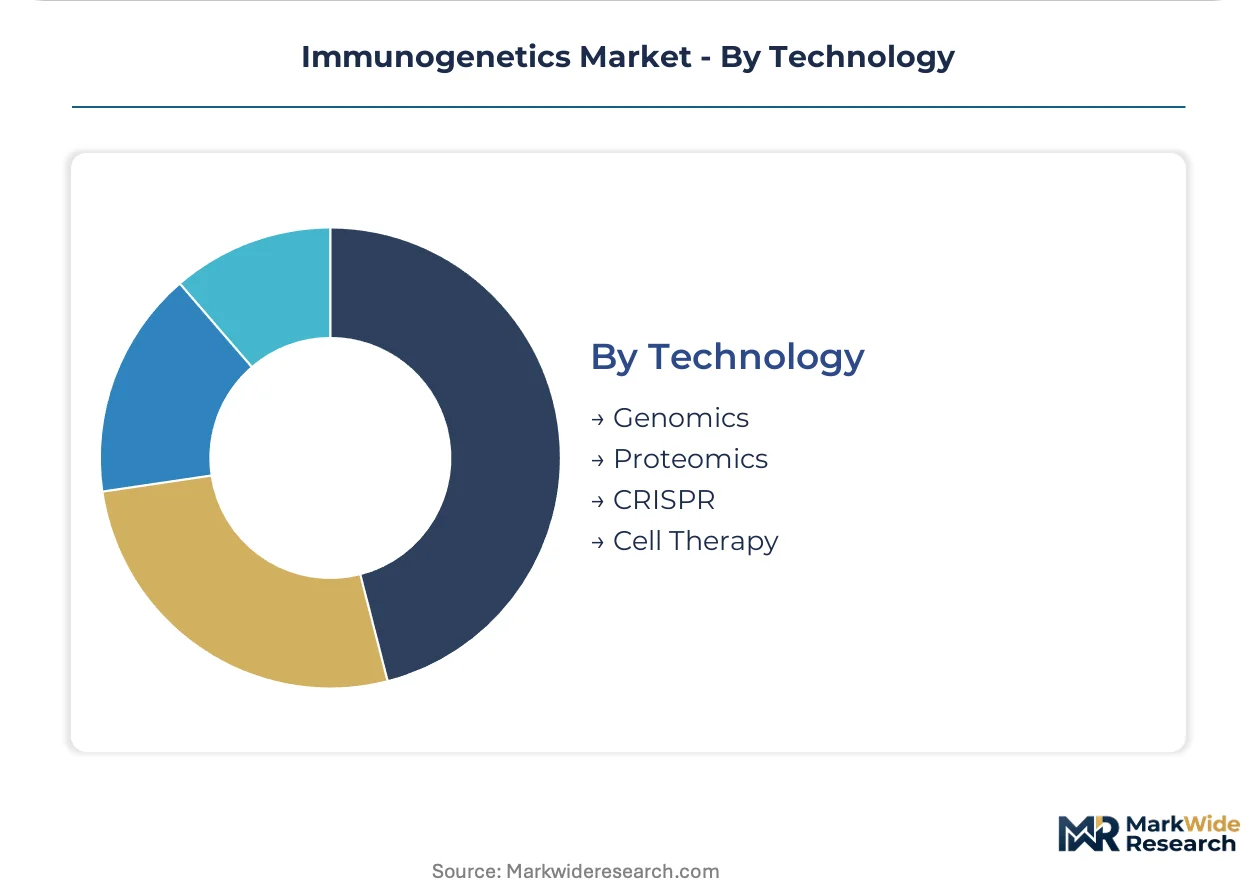
Technology:
Genomics platforms capture recurring reagent revenue through sequencing consumables, while proteomics approaches face substitution pressure from nucleic acid-based methods.
- Genomics:Next-generation sequencing enables comprehensive HLA allele resolution with single-molecule sensitivity. Illumina's MiSeq and NovaSeq instruments anchor installed bases in transplant centers across the United States, Germany, and Japan.
- CRISPR:Gene editing workflows require immunogenetic screening to assess off-target effects and HLA-mediated immune responses. Editas Medicine and Intellia Therapeutics integrate HLA typing into donor cell selection for allogeneic cell therapy programs.
- Proteomics:Mass spectrometry-based HLA peptide presentation analysis supports neoantigen discovery in personalized cancer vaccines.
- Cell Therapy:Ex vivo expansion protocols use immunogenetic markers to monitor immune cell phenotype stability.
Genomics holds installed capacity. CRISPR is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transplant centers and reference laboratories concentrate procurement authority in mature healthcare systems with established organ allocation networks and CLIA-equivalent accreditation frameworks. Academic medical centers in metropolitan clusters drive instrument placement for research applications. Cell therapy manufacturing facilities in biopharma hubs create secondary demand nodes for immunogenetic characterization services.
United States
UNOS-accredited transplant centers in Houston and Pittsburgh maintain dedicated molecular diagnostics laboratories with continuous reagent consumption. FDA companion diagnostics guidance accelerates clinical validation investments for platforms supporting cell therapy manufacturing. The Boston-Cambridge biotech corridor anchors CAR-T development programs requiring precise HLA compatibility testing.
Germany
Contract development organizations in Munich and Heidelberg drive sustained consumption of clinical-grade immunogenetic assays for IND-enabling studies. EU In Vitro Diagnostic Regulation compliance costs impose capital barriers for platform developers seeking CE marking. The Rhine-Main metropolitan region concentrates gene therapy manufacturing facilities with captive immunogenetics capabilities.
Japan
PMDA oversight of regenerative medicine products shapes validation requirements for immunogenetics platforms used in allogeneic cell therapy programs. METI funding initiatives support academic medical centers in Osaka and Yokohama adopting antibody repertoire sequencing for autoimmune disease biomarker discovery. The Kanto region anchors high-resolution HLA typing services for hematopoietic stem cell transplantation networks.
Australia
TGA accreditation standards govern laboratory operations for molecular diagnostics serving transplant programs in Sydney and Melbourne. Third-generation sequencing pilots in Queensland and Western Australia enable point-of-need allele resolution bypassing reference laboratory queues. The Therapeutic Goods Administration's evolving framework on companion diagnostics shapes platform selection criteria for oncology applications.
India
Government initiatives to establish organ allocation networks create first-mover positioning for HLA typing service providers in Mumbai and Delhi hospital clusters. CDSCO regulatory pathways for in vitro diagnostics influence product registration timelines for multinational platform vendors. The National Organ and Tissue Transplant Organization's infrastructure expansion drives procurement of molecular immunogenetics workflows in underserved metropolitan centers.
Immunogenetics Market Competitive Landscape
Player mix skews toward integrated life science conglomerates with sequencing instrument installed bases and specialized molecular diagnostics firms with regulatory validation expertise. Market structure concentrates around vendors with CLIA-certified quality management systems and proven analytical validation packages. Strategic archetypes include platform-integrated conglomerates, sample preparation specialists, and transplant-focused service laboratories. Competitive moves center on unbundling analytical software from hardware contracts and cloud-based bioinformatics partnerships.
Among platform-integrated conglomerates, Illumina and Thermo Fisher Scientific occupy positions anchored by sequencing instrument installed bases in North American transplant networks. QIAGEN exemplifies the sample preparation specialist archetype, competing through technologies that integrate with downstream sequencing and PCR-based HLA analysis. These three entities represent distinct competitive vectors: instrument platform dominance, broad portfolio coverage, and specialized workflow integration.
| Leading Market Players |
|---|
| QIAGEN |
| Illumina |
| CareDx |
| Omixon |
| Thermo Fisher Scientific |
| GenDx |
| Bio-Rad Laboratories |
| Immucor |
| Takara Bio |
| Others |
Supply & Pricing Matrix
CLIA certification requirements for high-complexity molecular diagnostics simultaneously gate supplier qualification and stratify price tiers, forcing transplant centers to pay premiums for validated reagent batches while reference laboratories absorb extended proficiency testing cycles that compress their procurement leverage.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate gene therapy reagent procurement, where clinical-grade enzyme suppliers pass through fluorophore and polymerase cost fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated companion diagnostic kits from research-use-only reagents and unvalidated bulk chemistry. Price differentiation hinges on ISO 13485 certification tier and after-sales analytical support bundling. Margins are tightening in the standard tier due to cloud-based bioinformatics unbundling that erodes instrument-lock-in subsidies. Academic research institutes exhibit highest price sensitivity, while CAR-T manufacturers demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
The United States and Germany anchor reagent formulation and analytical instrument manufacturing, while Japan and South Korea concentrate specialized fluorescent probe synthesis. Raw material dependencies include semiconductor-grade optical components, recombinant polymerase enzymes, and synthetic oligonucleotide libraries. Single-source vulnerability concentrates in qualified suppliers of long-read sequencing chemistries, where Oxford Nanopore's membrane technology lacks second-source alternatives. Distribution runs through CLIA-certified reference laboratory networks that enforce cold-chain integrity and lot-traceability documentation for transplant center deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immunogenetics sits in early-cycle expansion as CAR-T manufacturing scale-up and decentralized HLA typing adoption create penetration tailwinds that outpace mature diagnostic market saturation patterns.
For Market Incumbents: Compound installed base advantages through backward integration into clinical-grade reagent manufacturing, capturing margin pools currently absorbed by qualified enzyme suppliers. Accelerate ISO 15189 accreditation packages for Middle Eastern healthcare systems before regional harmonization locks in preferred vendor relationships. Long-read sequencing substitution threatens short-read platform obsolescence, demanding R&D allocation to nanopore-compatible assay chemistries. For New Entrants and Emerging Players: Anchor in India's metropolitan hospital clusters where government organ allocation network expansion outpaces domestic HLA typing capacity. India's transplant infrastructure gap offers lowest competitive density among major population centers. Cloud-native bioinformatics pipelines enable mid-tier reference laboratory market entry without capital-intensive compute infrastructure, bypassing Illumina and Thermo Fisher instrument-lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based analytical software sub-segments as remote variant calling eliminates on-premise server requirements. Five-to-ten year viability favors platform-agnostic bioinformatics specialists with proven CLIA validation packages over hardware-dependent instrument vendors. Watch FDA companion diagnostics guidance expansion into cell therapy manufacturing as signal for reagent demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | CAP-accredited laboratories command premium pricing from UNOS transplant centers requiring validated HLA typing workflows. |
| Cloud-Based Bioinformatics Partnership | Remote variant calling platforms enable reference laboratories to bypass Thermo Fisher and Illumina software lock-in. |
| Long-Read Sequencing Assay Development | Oxford Nanopore-compatible chemistries capture point-of-need testing volume fragmenting away from centralized hubs. |
| India Transplant Infrastructure Joint Venture | NOTTO-accredited hospital clusters in Mumbai and Delhi create first-mover positioning for HLA typing service providers. |
| ISO 15189 Accreditation Convergence | Harmonized medical laboratory standards across Saudi Arabia and UAE enable multi-jurisdictional platform deployment contracts. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and ClinicalTrials.gov immunogenetic intervention records preceded structured interviews with transplant center laboratory directors, CAR-T manufacturing quality leads, and reference laboratory procurement managers. Secondary validation drew from CAP proficiency testing reports, CMS Medicare reimbursement databases, and GPO contract disclosure filings. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down market sizing from sequencing platform vendor disclosures.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured gene therapy reagent premium tiers, transplantation versus cancer therapy application splits, diagnostic laboratory versus pharmaceutical company purchasing authority, and genomics platform versus CRISPR technology adoption curves. CAGRs derived from logistic penetration curves fitted to HLA typing workflow conversion data and CAR-T manufacturing facility expansion announcements.
Material uncertainties — regulatory delays in FDA companion diagnostics guidance, EU MDR Class C device certification bottlenecks, and nanopore sequencing accuracy inflections — sit outside the modeled envelope. Forecasts reflect assumptions about transplant center outsourcing trajectories and cloud bioinformatics adoption velocity. Recalibration cycles align with material shifts in CAR-T manufacturing capacity announcements and CLIA certification requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Hereditary Cancer Testing Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Whole Genome Amplification Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Global NGS Sample Preparation Market
Genomics
DNA Methylation Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Global Gene Amplification Technologies Market
Genomics
DNA Sequencing Services Market
Genomics
Human Genetics Market
Genomics
Next Generation Sequencing Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Genetic Testing Service Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
AI in Genomics Market
Genomics
DNA Sequencing Market