
 Genetic Analysis Services Market | 2026-2036
Genetic Analysis Services Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Analysis Services Market Foresight
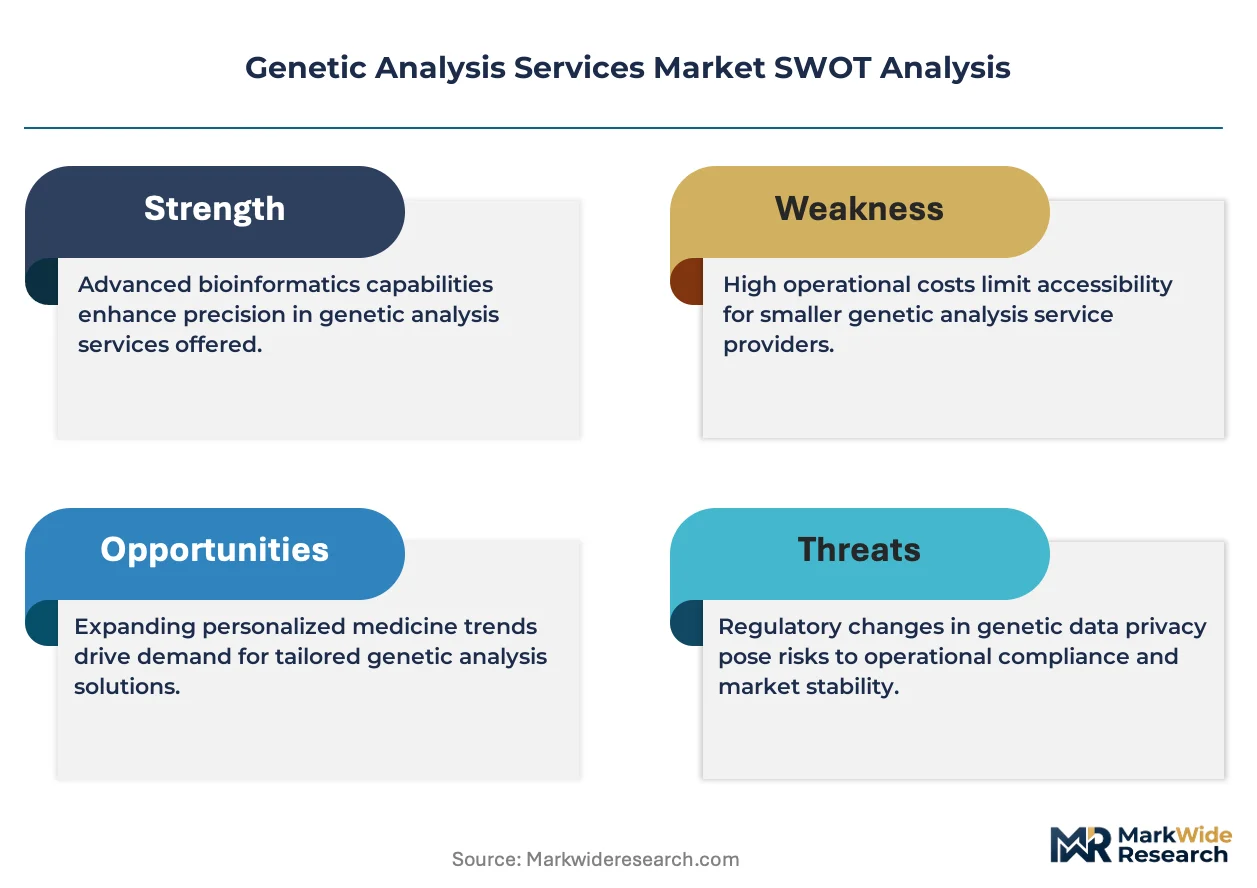
CLIA certification and CAP accreditation cycles are redrawing competitive boundaries in genetic analysis services. Illumina Inc. leverages its vertically integrated sequencing platform to dominate instrument-to-service workflows. Thermo Fisher Scientific Inc. anchors its position through extensive R&D infrastructure spanning sample prep through bioinformatics. Quest Diagnostics Incorporated sustains geographic density through its national laboratory network and direct patient access channels.
Genetic analysis services encompass DNA and RNA characterization through sequencing, genotyping, and expression profiling, typically requiring sample extraction, library preparation, and computational interpretation to deliver clinically actionable or research-grade genomic data. Next-Generation Sequencing commands the largest revenue share due to throughput scalability, though Mass Spectrometry-based approaches are gaining traction for targeted variant validation. Pharmacogenomics applications attract premium pricing from biopharmaceutical sponsors, while Ancestry Testing has matured into a volume-driven, lower-margin segment. Contract Research Organizations now represent the fastest-growing end user category as sponsors outsource genomic components of drug development programs.
FDA oversight of laboratory-developed tests, CLIA quality standards, and the EU AI Act's risk-classification framework for diagnostic algorithms collectively shape service provider compliance burdens and market access conditions. CAP accreditation requirements for clinical reporting and HIPAA data governance rules further constrain operational architecture for US-based laboratories. Stakeholders must monitor evolving payer coverage determinations for multi-gene panels and whole-exome sequencing, as reimbursement policy shifts will determine which service categories achieve sustainable unit economics.
Market Dynamics
Biopharmaceutical sponsors are consolidating genomic outsourcing decisions, compressing vendor lists from dozens to preferred partnerships with full-service providers holding both CLIA certification and CAP accreditation.
Growth Catalysts
- Pharmacogenomic trial integration:Drug developers embed genetic stratification into Phase II/III protocols, creating recurring demand for companion diagnostic validation services.
- FDA laboratory-developed test oversight:Tighter premarket scrutiny elevates demand for quality-accredited service partners capable of navigating 510(k) and PMA pathways.
- Long-read sequencing maturation:Pacific Biosciences and Oxford Nanopore workflows resolve structural variants previously invisible to short-read platforms, opening new clinical indications.
Market Restraints
- Reagent supply concentration:Three suppliers control over 80% of sequencing consumables, exposing service labs to input cost volatility and allocation constraints.
- Bioinformatician talent scarcity:Pipeline development and variant interpretation require specialized computational biology expertise that academic programs produce insufficiently.
- EU AI Act algorithmic risk classification:Diagnostic AI modules face mandatory conformity assessments, extending validation timelines and compliance expenditures.
Strategic Opportunities
- Direct-to-consumer ancestry pivot:Mature ancestry testing providers redirect capacity toward health-risk reporting and wellness applications with higher reimbursement potential.
- CMS coverage expansion:National coverage determinations for whole-exome sequencing in undiagnosed rare disease create predictable reimbursement for clinical service lines.
- CRISPR validation services:Gene therapy sponsors require off-target analysis and editing confirmation, spawning specialized analytical service categories.
Industry Challenges
- CLIA-CAP dual certification timelines:New laboratory facilities face 18-24 month accreditation cycles before accepting clinical samples.
- Legacy LIMS integration:Established service providers struggle to retrofit decades-old laboratory information management systems for cloud-based bioinformatics pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Analysis Services Market |
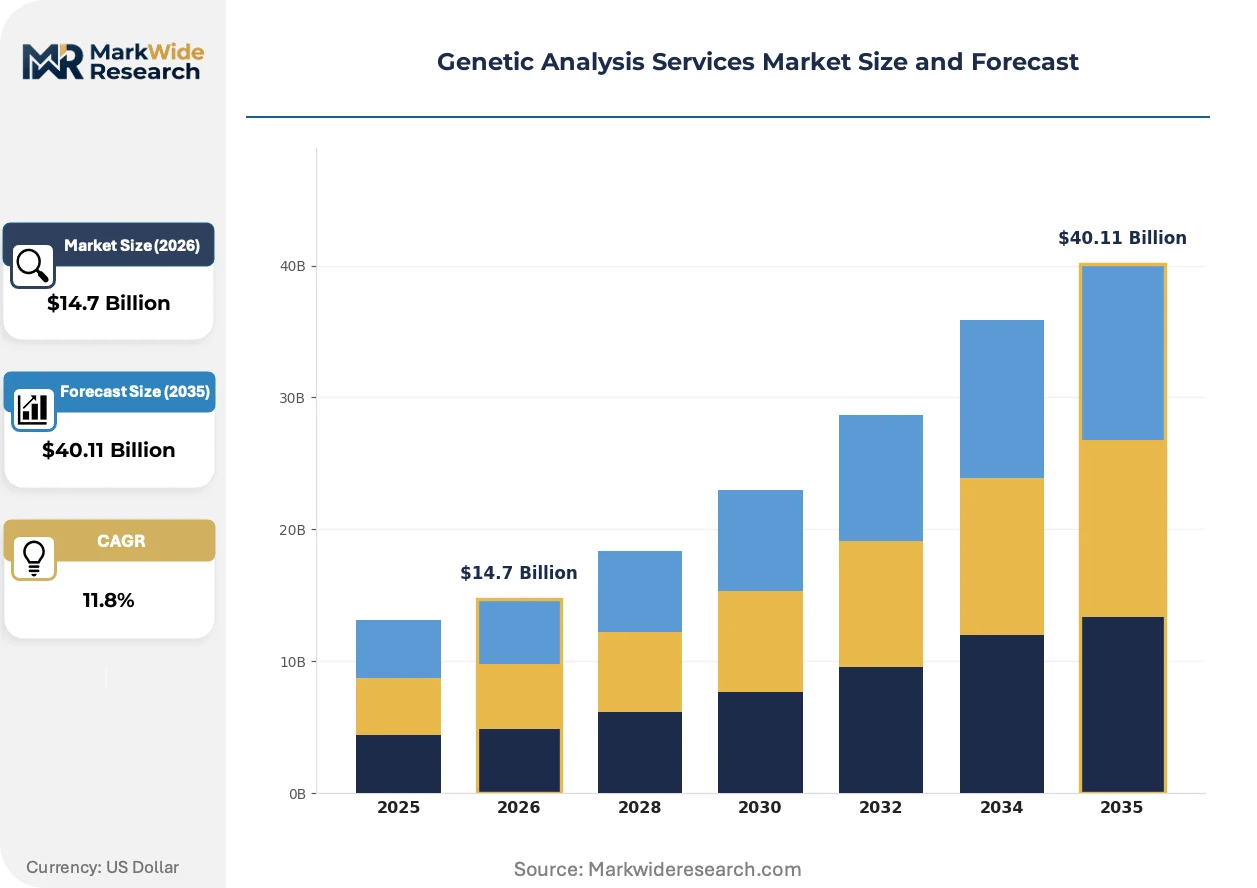
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $40.11 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Gene Sequencing, Genotyping, Mutation Analysis, Epigenetic Profiling, Transcriptome Analysis Application: Pharmacogenomics, Agrigenomics, Forensic Analysis, Personalized Medicine, Ancestry Testing End User: Research Institutes, Biopharmaceutical Companies, Diagnostic Laboratories, Academic Centers, Contract Research Organizations Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing, Mass Spectrometry |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., Hoffmann-La Roche Ltd., Quest Diagnostics Incorporated, Eurofins Scientific, QIAGEN, Danaher Corporation, Laboratory Corporation of America Holdings, Myriad Genetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Analysis Services Market Shifts & Advancements
Service provider architectures are fragmenting into specialized tiers as sequencing commoditizes and interpretation becomes the value-capture layer. Three developments are compressing competitive positioning.
Third-generation sequencing is decomposing the historical dominance of Illumina short-read workflows in clinical applications. Pediatric genetics and oncology centers adopt long-read platforms for resolving complex structural variants and methylation patterns. The technology is decomposing the assumption that higher throughput alone determines platform selection, forcing service providers to maintain multi-platform redundancy.
EU AI Act risk-classification rules for diagnostic algorithms are restructuring software validation obligations across European service operations. High-risk AI modules supporting variant pathogenicity calls now require notified body review and post-market surveillance. German and French clinical laboratories are front-loading conformity documentation to maintain market access ahead of enforcement deadlines.
Biopharmaceutical procurement patterns are consolidating genomic service contracts under master service agreements with tiered performance metrics. Sponsors are unbundling sample processing from bioinformatics interpretation, creating separate vendor pools for each function. This bifurcation is most advanced in Massachusetts and California, where top-20 pharmaceutical sponsors have reduced preferred vendor lists by 60% over 24 months.
Genetic Analysis Services Market Segmentation
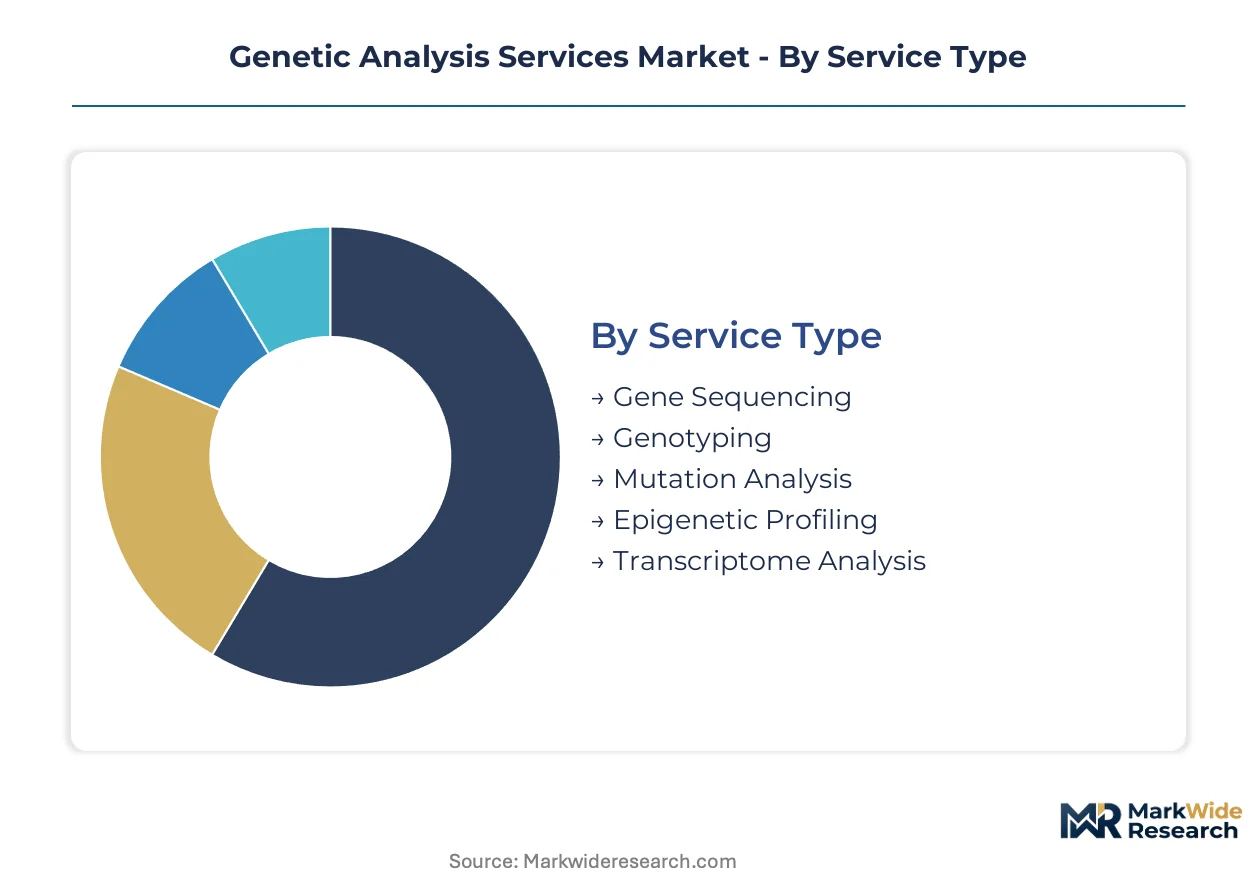
Genetic analysis services fragment across multiple intersecting dimensions that determine pricing power, regulatory burden, and customer loyalty. Service providers configure operational capabilities around specific segment combinations rather than pursuing horizontal coverage. Understanding these divisions reveals where margin concentrates and where commoditization threatens.
Service Type:
Gene sequencing and genotyping services generate predominantly domestic revenue within major biopharma clusters, while mutation analysis and epigenetic profiling travel more frequently across borders to specialized reference laboratories.
- Gene Sequencing:High-throughput DNA readout encompassing whole-genome, whole-exome, and targeted panel configurations. Demand concentrates in the United States around Cambridge and South San Francisco biopharma corridors, driven by companion diagnostic validation requirements for FDA submissions.
- Genotyping:Single-nucleotide polymorphism detection at scale for population cohorts and clinical trials. European agricultural biotechnology sponsors in the Netherlands and Denmark represent the primary export destination for North American service providers.
- Mutation Analysis:Targeted variant confirmation in hereditary cancer and rare disease contexts. Clinical laboratories in Germany and France drive cross-border specimen flow.
- Epigenetic Profiling:DNA methylation and histone modification mapping for oncology biomarker discovery. Academic medical centers in Switzerland and Sweden anchor demand.
- Transcriptome Analysis:RNA sequencing and expression quantification for drug mechanism studies. Biopharmaceutical sponsors in Massachusetts and California sustain volume.
Gene sequencing commands the established base. The steepest expansion runs through epigenetic profiling.
Application:
Margin structures diverge sharply across applications, with pharmacogenomics and personalized medicine sustaining premium pricing while ancestry testing compresses toward commodity economics.
- Pharmacogenomics:Genetic stratification for drug response prediction and adverse event risk assessment. Biopharmaceutical companies in the United States embed these services into Phase II/III trial protocols, creating recurring revenue streams with multi-year master service agreements.
- Personalized Medicine:Treatment selection based on tumor profiling or germline risk assessment. Oncology centers in Texas and Florida generate concentrated demand as CMS reimbursement policies expand coverage for comprehensive genomic profiling.
- Agrigenomics:Crop and livestock genetic improvement through marker-assisted selection. Seed companies in Iowa and research stations in Brazil drive seasonal specimen volumes.
- Forensic Analysis:DNA profiling for criminal casework and missing persons identification. State crime laboratories across the United States maintain steady contract flow with certified service providers.
- Ancestry Testing:Consumer-facing lineage reconstruction through SNP array analysis. Utah and California providers dominate volume but face margin erosion as the segment matures.
Pharmacogenomics delivers the highest average revenue per project. Personalized medicine is gaining share fastest as reimbursement frameworks stabilize.
End User:
Procurement sophistication varies dramatically, with biopharmaceutical companies demanding integrated quality systems while academic centers prioritize cost minimization.
- Biopharmaceutical Companies:Integrated drug developers and biotechnology sponsors requiring GLP-compliant data packages for regulatory submissions. These buyers consolidate vendor relationships under preferred provider programs spanning multiple therapeutic areas.
- Contract Research Organizations:Outsourced clinical trial service providers acting as intermediaries for sponsor genomic needs. CROs in North Carolina and Pennsylvania are expanding fastest as sponsors unbundle genomic components from full-service contracts.
- Research Institutes:Government and private nonprofit laboratories pursuing basic science objectives. NIH-funded centers in Maryland and California maintain substantial sequencing budgets.
- Diagnostic Laboratories:Hospital-affiliated and independent clinical labs seeking CLIA-certified interpretation services. Regional networks in Ohio and Texas concentrate purchasing power.
- Academic Centers:University medical schools and teaching hospitals with mixed research-clinical missions. Grant-funded principal investigators drive highly price-sensitive demand.
Biopharmaceutical companies anchor the revenue base. Contract research organizations are climbing the fastest as outsourcing patterns shift.
Technology:
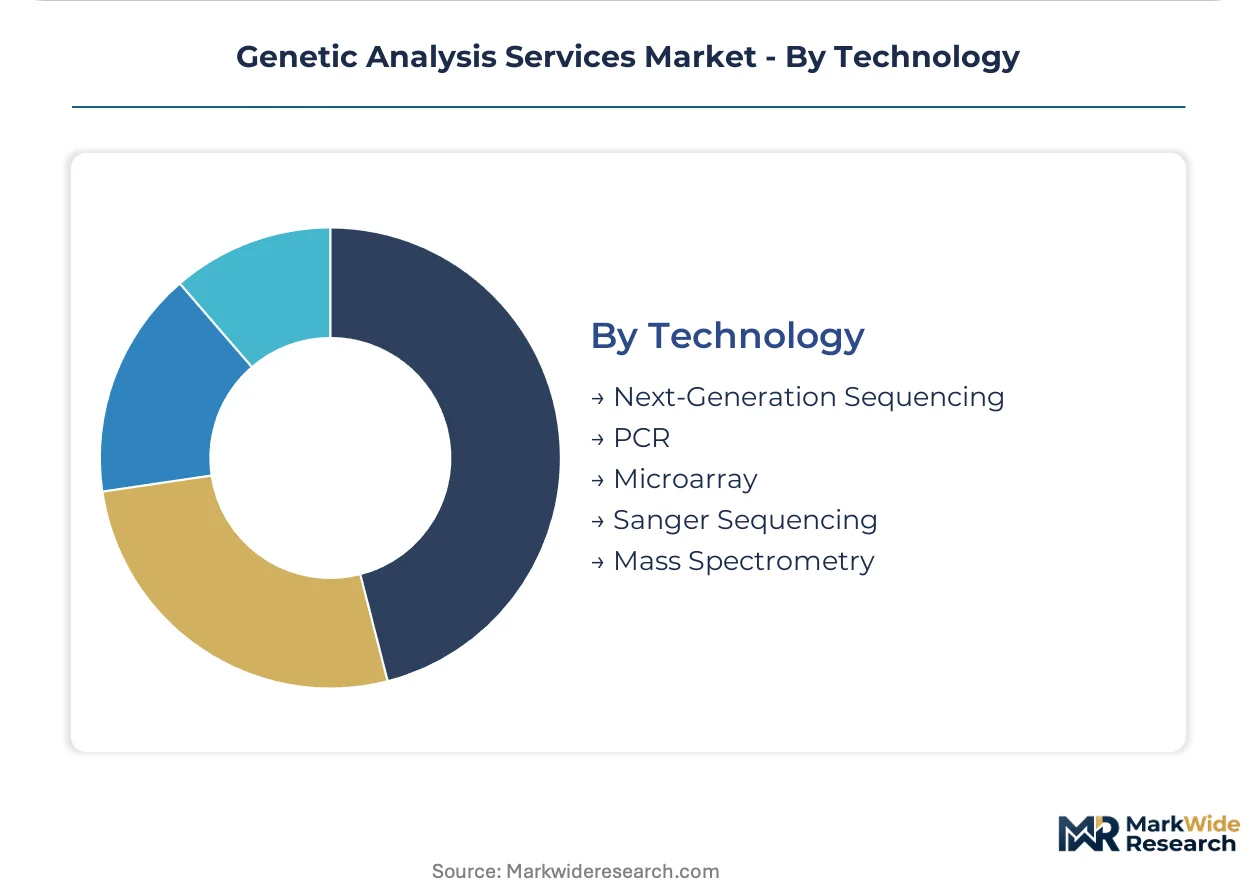
Platform selection determines capital intensity, reagent lock-in, and competitive defensibility across service provider business models.
- Next-Generation Sequencing:Massively parallel short-read platforms dominating clinical and research throughput. Illumina instrument placements in the United States and United Kingdom create geographic density in service provision.
- Mass Spectrometry:High-resolution molecular detection for proteogenomics and metabolite identification. Specialist laboratories in Germany and Switzerland maintain distinctive capability.
- PCR:Targeted amplification for known variant detection with rapid turnaround. Point-of-care testing networks in Florida and Arizona sustain distributed demand.
- Microarray:Fixed-content SNP and CNV analysis for standardized screening applications. Agricultural biotechnology sponsors in the Midwest retain substantial volume.
- Sanger Sequencing:Gold-standard confirmation sequencing for regulatory submissions. FDA submission requirements in the United States preserve this technology's relevance despite lower throughput.
Next-generation sequencing commands the established base. Mass spectrometry is expanding most quickly as proteogenomics applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-to-San Francisco biotech corridor anchors North American genetic analysis infrastructure, while European high-speed rail networks enable rapid specimen transport between specialized reference laboratories.
United States
CMS reimbursement policies for whole-exome sequencing and companion diagnostics concentrate purchasing power in Massachusetts and California biopharma clusters. FDA oversight of laboratory-developed tests elevates compliance costs for CLIA-certified facilities. Cambridge service providers process the majority of Phase II/III pharmacogenomic validation work for top-20 pharmaceutical sponsors.
Germany
Academic medical centers in Heidelberg and Munich drive demand for rare disease mutation analysis and epigenetic profiling services. The EU AI Act's risk-classification framework for diagnostic algorithms imposes conformity assessment burdens on Berlin-based bioinformatics operations. Bavarian clinical laboratories are front-loading validation documentation ahead of enforcement deadlines.
United Kingdom
NHS Genomic Medicine Service contracts consolidate sequencing volume through designated genomic laboratory hubs in London and Manchester. MHRA alignment with FDA premarket pathways streamlines dual submission strategies for companion diagnostic developers. Oxford and Cambridge research parks sustain substantial outsourced transcriptome analysis demand from biotechnology sponsors.
China
NMPA regulatory reforms for innovative diagnostics accelerate local laboratory accreditation requirements in Shanghai and Beijing. Government-funded precision medicine initiatives channel sequencing investment toward tumor profiling and pharmacogenomic applications. Yangtze River Delta biotech parks attract foreign service providers seeking joint venture structures for market access.
Switzerland
Swissmedic's streamlined review timelines for companion diagnostics attract pharmaceutical sponsors to Basel and Zurich service partnerships. Academic medical centers in Geneva and Lausanne anchor European demand for long-read sequencing applications in pediatric genetics. The country's central rail position enables rapid specimen logistics to German and French reference laboratories.
Genetic Analysis Services Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded diagnostics conglomerates holding instrument-to-service integration advantages while venture-backed bioinformatics boutiques capture interpretation-layer margins. The vendor base stratifies around three archetypes: platform-integrated conglomerates with captive sequencing hardware, full-service clinical laboratories with geographic density, and specialized bioinformatics providers with algorithmic differentiation. Dominant competitive moves include CLIA-CAP dual certification pursuit for clinical market access and strategic partnerships with biopharmaceutical sponsors under multi-year master service agreements.
Within the platform-integrated tier, Illumina Inc. and Thermo Fisher Scientific Inc. exemplify instrument-to-service workflow control, while Quest Diagnostics Incorporated occupies a position among full-service clinical laboratory networks with direct patient access channels. These three entities represent contrasting strategic archetypes: sequencing hardware captivity, R&D infrastructure breadth, and geographic density respectively.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| Hoffmann-La Roche Ltd. |
| Quest Diagnostics Incorporated |
| Eurofins Scientific |
| QIAGEN |
| Danaher Corporation |
| Laboratory Corporation of America Holdings |
| Myriad Genetics Inc. |
| Others |
Supply & Pricing Matrix
Multi-year master service agreements with biopharmaceutical sponsors lock in sequencing capacity and stabilize unit economics across volatile reagent markets. These contracts bundle CLIA-certified interpretation services with guaranteed throughput minimums, insulating service providers from spot-market pricing swings while embedding FDA compliance costs into predictable fee structures.
Pricing Analysis
Certification level (CLIA-CAP dual accreditation versus research-grade only) creates the primary spread between premium clinical reporting and commodity sequencing. Three-tier pricing structure across premium, standard, and economy levels reflects turnaround time guarantees and bioinformatics depth. Cost compression in ancestry testing is intensifying because consumer-facing providers redirect capacity toward health applications. Academic centers exhibit highest price sensitivity while biopharmaceutical sponsors accept premium rates for regulatory submission packages.
Supply Chain Analysis
Sequencing reagent inventories stretch 8-12 weeks as suppliers allocate consumables against contracted instrument placements. Manufacturing concentrates in the United States, Singapore, and Ireland around Illumina and Thermo Fisher production facilities. Service providers draw from proprietary sequencing chemistries, flow cells, and library preparation kits vulnerable to single-source dependency. Tariff exposure on Chinese-sourced plasticware and solvents threatens margin stability. Distribution runs through temperature-controlled logistics networks connecting biopharma clusters to CLIA-certified laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopharmaceutical R&D cycle normalization following pandemic-era disruptions positions genetic analysis services for cyclical recovery. Sponsor consolidation of genomic outsourcing under preferred provider programs concentrates volume with full-service laboratories holding dual accreditation.
For Market Incumbents: Secure CLIA-CAP dual certification for new facility expansions before enforcement deadlines tighten under FDA laboratory-developed test oversight. Deepen bioinformatics interpretation capabilities to capture unbundled contract value as sponsors separate sample processing from variant analysis. Long-read sequencing platform adoption by Pacific Biosciences and Oxford Nanopore threatens Illumina-centric incumbents lacking multi-platform redundancy. For New Entrants and Emerging Players: Bioinformatics-only service gaps where incumbents under-serve present immediate white-space opportunity. Target CRISPR validation services for gene therapy sponsors requiring off-target analysis and editing confirmation. European reference laboratories face EU AI Act compliance burdens that specialized conformity documentation providers can exploit. Go-to-market through CRO intermediaries accelerates sponsor access without direct procurement certification hurdles. For Investors and Strategic Acquirers: Boutique bioinformatics providers with algorithmic differentiation in variant pathogenicity scoring represent compelling acquisition targets. Long-term viability hinges on interpretation-layer margin capture as sequencing commoditizes. Signal to monitor: CMS national coverage determinations for whole-exome sequencing in undiagnosed rare disease, which would validate clinical service line economics.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-CAP Dual Certification Pursuit | Unlocks clinical sample access and companion diagnostic validation contracts under FDA oversight. |
| Long-Read Sequencing Platform Investment | Resolves structural variants for pediatric genetics and oncology applications beyond short-read limits. |
| Bioinformatics Interpretation Layer Buildout | Captures premium pricing as sponsors unbundle analysis from sample processing workflows. |
| EU AI Act Conformity Documentation | Maintains European market access for diagnostic algorithms facing notified body review requirements. |
| CRISPR Validation Service Development | Addresses gene therapy sponsor demand for off-target analysis and editing confirmation. |
Research Methodology
Desk research of FDA 510(k) and PMA filings, CMS national coverage determinations, and EMA companion diagnostic assessments preceded structured interviews with biopharmaceutical development executives, clinical laboratory directors, regulatory affairs specialists, and CRO procurement leads. Secondary validation drew from ClinicalTrials.gov genomic biomarker protocols, SEC 10-K instrument placement disclosures, and EU AI Act implementation guidance. Bottom-up service provider capacity modeling triangulated against top-down biopharmaceutical R&D spend allocation.
Variance decomposition across service type, application, end user, technology, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segment-level CAGRs derived from throughput capacity expansion rates, reimbursement policy trajectories, and sponsor outsourcing intensity indices. Long-read sequencing adoption curves, pharmacogenomic trial integration timelines, and CMS coverage expansion scenarios served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA laboratory-developed test oversight and EU AI Act enforcement regimes; material policy shifts would require re-modeling. Reagent supply allocation constraints, bioinformatician talent scarcity, and payer coverage determination volatility represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Global Metagenomics Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Alagille Syndrome Market
Genomics
North America DNA Sequencing Products Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Genotyping Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Mitochondrial DNA Market
Genomics
Microbiome Sequencing Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Prenatal Genetic Testing Market
Genomics
Next Generation Molecular Assay Market
Genomics
Retail Genomics Market
Genomics
Pharmacogenomics Technology Market