
 Global Automotive Tappet Market | 2026-2036
Global Automotive Tappet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Tappet Market Analysis
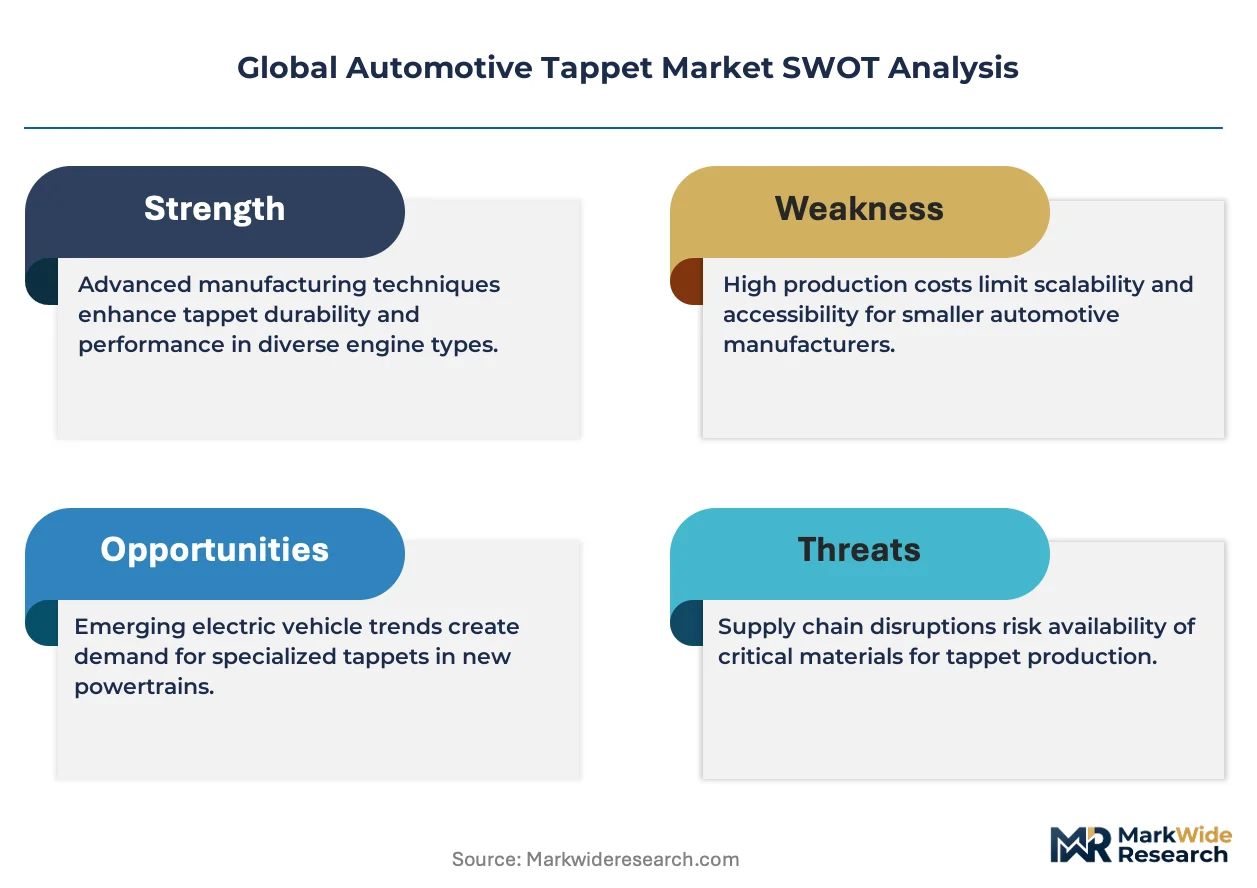
A shift from outsourced tappet procurement to captive in-house production is hardening among tier-one powertrain suppliers. Schaeffler AG leverages its integrated valve train division to sustain margin control across European OEM programs. SKF anchors its position through precision grinding capabilities that dominate roller tappet geometries for high-performance engines. Eaton Corporation competes on scale, operating forged steel tappet lines that supply Detroit-based light-truck manufacturers.
An automotive tappet is a precision-machined cylindrical component that transfers camshaft motion to engine valves, typically manufactured from alloy steel or chilled cast iron through CNC grinding and heat treatment to achieve surface hardness exceeding 58 HRC. Its primary purpose is maintaining precise valve timing and lash adjustment under cyclic thermal and mechanical loads across internal combustion engine architectures. Hydraulic tappets lead installed volumes due to self-adjusting lash compensation that reduces maintenance intervals, while roller tappets capture the fastest growth trajectory as direct-acting overhead cam designs proliferate in downsized turbocharged engines. Steel remains the dominant material category, though titanium and composite variants are penetrating racing and hypercar niches where reciprocating mass reduction commands premium pricing.
EPA tailpipe standards, EU F-Gas Regulation, and China's GB 18352 emission limits collectively mandate friction reduction across valve train subsystems, directly accelerating demand for low-lash hydraulic and roller tappet configurations. NHTSA fuel economy benchmarks in the United States and EMA automotive material directives in Europe further constrain allowable wear rates and oil consumption, tightening supplier qualification protocols. Stakeholders must monitor powertrain electrification timelines and residual ICE production commitments to calibrate capacity allocation between conventional tappet families and emerging electromechanical valve actuation technologies.
Market Dynamics
Engine downsizing and forced induction architectures are compressing valve train operating envelopes, forcing tappet suppliers to reconcile hydraulic lash compensation with reduced camshaft lobe profiles and higher spring rates.
Growth Catalysts
- EPA Tier 3 tailpipe standards:Friction reduction mandates across valve train subsystems are accelerating specification of low-lash hydraulic tappets in US passenger vehicle programs.
- Direct-acting overhead cam designs:Roller tappet geometries are capturing volume as turbocharged downsized engines proliferate in German and Chinese OEM lineups.
- Powertrain manufacturing clusters:Concentrated procurement in Stuttgart, Shanghai, and Detroit is consolidating demand around qualified tappet suppliers with localized heat treatment capabilities.
Market Restraints
- Alloy steel input volatility:Chrome-molybdenum bar stock pricing swings compress margin predictability for forged tappet producers serving high-volume light-truck segments.
- Supplier concentration in Baden-Württemberg:European roller tappet capacity clusters around precision grinding specialists, creating geographic single-source exposure for OEMs.
- Electromechanical valve actuation:Camless engine architectures threaten hydraulic and mechanical tappet demand in long-term powertrain electrification scenarios.
Strategic Opportunities
- India passenger vehicle production:Localized tappet sourcing gaps exist as Maruti Suzuki and Hyundai Motor India expand engine manufacturing in Manesar and Sriperumbudur.
- Titanium reciprocating mass reduction:Racing and hypercar niches command premium pricing for titanium tappets where gram-level weight savings justify material cost multiples.
- EU F-Gas Regulation compliance services:Tappet suppliers can bundle friction testing documentation with component sales to ease OEM certification burden.
Industry Challenges
- CNC grinding skill scarcity:Precision machinists capable of maintaining sub-micron roller profile tolerances are concentrated among aging workforces in Germany and Japan.
- Heat treatment capex cycles:Vacuum carburizing furnace investments require seven-year payback periods against uncertain ICE production volume commitments.
- GB 18352 certification timelines:Chinese emission testing protocols for valve train subsystems extend supplier qualification cycles by 8-14 months versus historical baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Tappet Market |
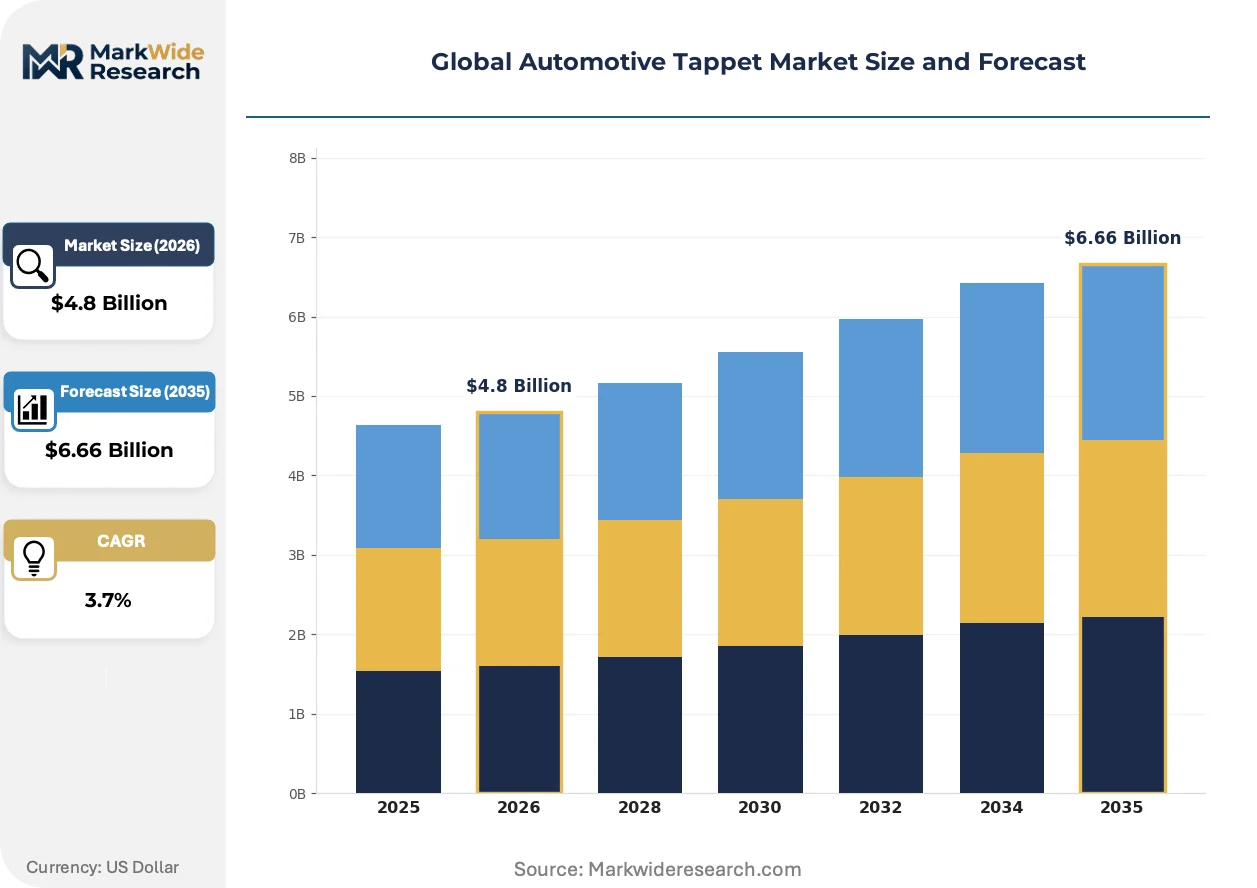
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Tappets, Mechanical Tappets, Roller Tappets, Solid Tappets Material: Steel, Aluminum, Composite, Titanium End User: Original Equipment Manufacturers, Aftermarket, Repair Shops, Automotive Enthusiasts Installation Type: Overhead Camshaft, Pushrod, Dual Overhead Cam, Others |
| Companies Covered | Schaeffler AG, SKF, Eaton Corporation, Federal-Mogul LLC, NSK Ltd, Rane Engine Valve Limited, Wuxi Xizhou Machinery Co Ltd, Competition Cams Inc, Crower Cams & Equipment Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Tappet Market Emerging Trajectories
Material science advances and regulatory friction mandates are converging to transform tappet specification criteria from pure durability metrics toward system-level efficiency optimization.
Composite-reinforced polymer tappet inserts are rewriting the mass-production feasibility of non-metallic valve train components. BMW M GmbH and Porsche Motorsport have validated carbon-fiber-reinforced PEEK tappets in endurance racing environments. This validation is rewriting procurement criteria for performance engine builders previously wedded to steel and titanium.
EU F-Gas Regulation phase-down schedules are tightening permissible friction coefficients in passenger vehicle climate systems, indirectly pressuring valve train efficiency. The regulation cascades into tappet surface finish specifications, with EMA automotive material directives now referencing valve train subsystem friction in type-approval documentation. German OEMs are responding by specifying diamond-like carbon coatings on roller tappet contact surfaces.
Powertrain suppliers are consolidating valve train subsystem procurement under single-source accountability models. Tier-one buyers now bundle tappet, camshaft, and lash adjuster specifications into integrated supplier contracts rather than discrete component purchases. This consolidation is most visible in Detroit-based light-truck programs where Eaton Corporation and Schaeffler AG compete on subsystem integration breadth rather than component pricing alone.
Global Automotive Tappet Market Segmentation
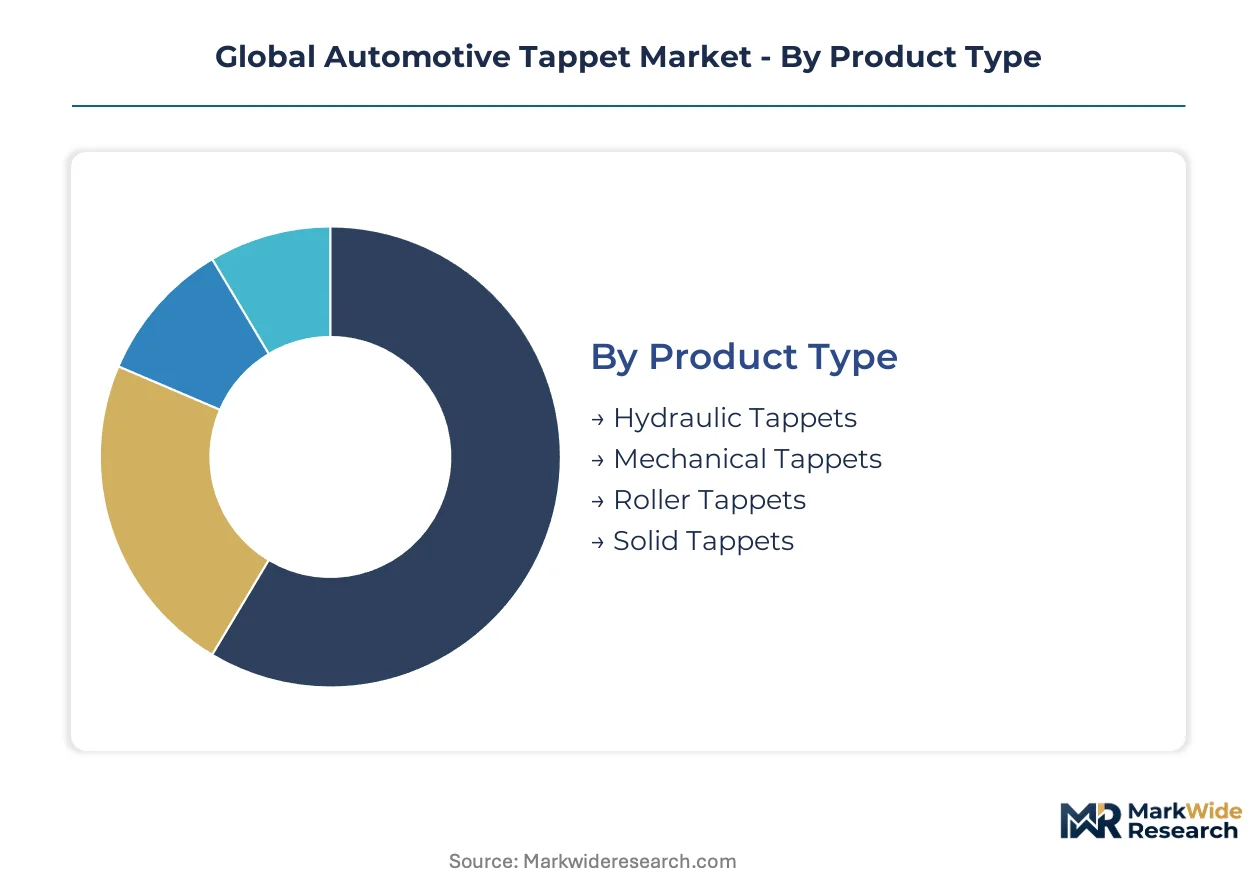
Segmentation in the automotive tappet market reveals divergent capital requirements and margin profiles across product architectures. Suppliers calibrate heat treatment and grinding investments against volume commitments in each segment tier.
Product Type:
Capital intensity peaks with roller tappet geometries requiring sub-micron CNC grinding capabilities and vacuum carburizing furnaces.
- Hydraulic Tappets:Self-adjusting lash compensation mechanisms manufactured through precision grinding of alloy steel bodies with internal plunger assemblies. Passenger vehicle OEMs in Stuttgart and Detroit specify these for friction reduction under EPA Tier 3 mandates. Maintenance interval extension drives fleet adoption.
- Roller Tappets:Needle bearing-equipped cylindrical bodies that reduce sliding friction against camshaft lobes. Direct-acting overhead cam designs from German and Chinese OEMs concentrate demand here. Downsized turbocharged engines require these for reduced valve train friction.
- Mechanical Tappets:Solid one-piece designs requiring periodic lash adjustment via shims.
- Solid Tappets:Racing applications favor these for absolute stability at extreme RPM ranges.
Hydraulic tappets absorb the bulk of installed capacity; roller tappets are expanding most quickly.
Material:
Raw material cost tiers stratify supplier positioning from commodity steel to aerospace-grade titanium.
- Steel:Chrome-molybdenum and bearing-grade alloy bars dominate forged tappet production through induction hardening to 58+ HRC. Detroit light-truck manufacturers anchor volume demand here. Heat treatment capex cycles extend seven years for vacuum carburizing capacity.
- Composite:Carbon-fiber-reinforced PEEK inserts validated by BMW M GmbH and Porsche Motorsport for reciprocating mass reduction. Endurance racing environments command premium pricing multiples. Material science advances are rewriting procurement criteria for performance engine builders.
- Aluminum:Limited to low-load auxiliary applications in emerging market vehicles.
- Titanium:Gram-level weight savings justify material cost multiples in hypercar and Formula 1 niches.
Steel commands the majority of production tonnage; composite formulations are climbing the fastest.
End User:
Customer type determines qualification protocols and contract structures across the value chain.
- Original Equipment Manufacturers:Tier-one powertrain suppliers bundle tappet specifications into integrated valve train subsystem contracts. Schaeffler AG and Eaton Corporation compete on integration breadth rather than component pricing alone. Single-source accountability models now dominate procurement.
- Aftermarket:Independent distributors serve aging vehicle parc with replacement hydraulic units. Service interval timing creates predictable demand cyclicality.
- Repair Shops:Technician-installed lash adjusters for maintenance events.
- Automotive Enthusiasts:Performance builders source solid and roller variants for engine rebuilds.
OEM channels concentrate the highest value contracts; aftermarket volume scales with vehicle parc aging.
Installation Type:
Engine architecture selection dictates tappet geometry and supplier technical capabilities.
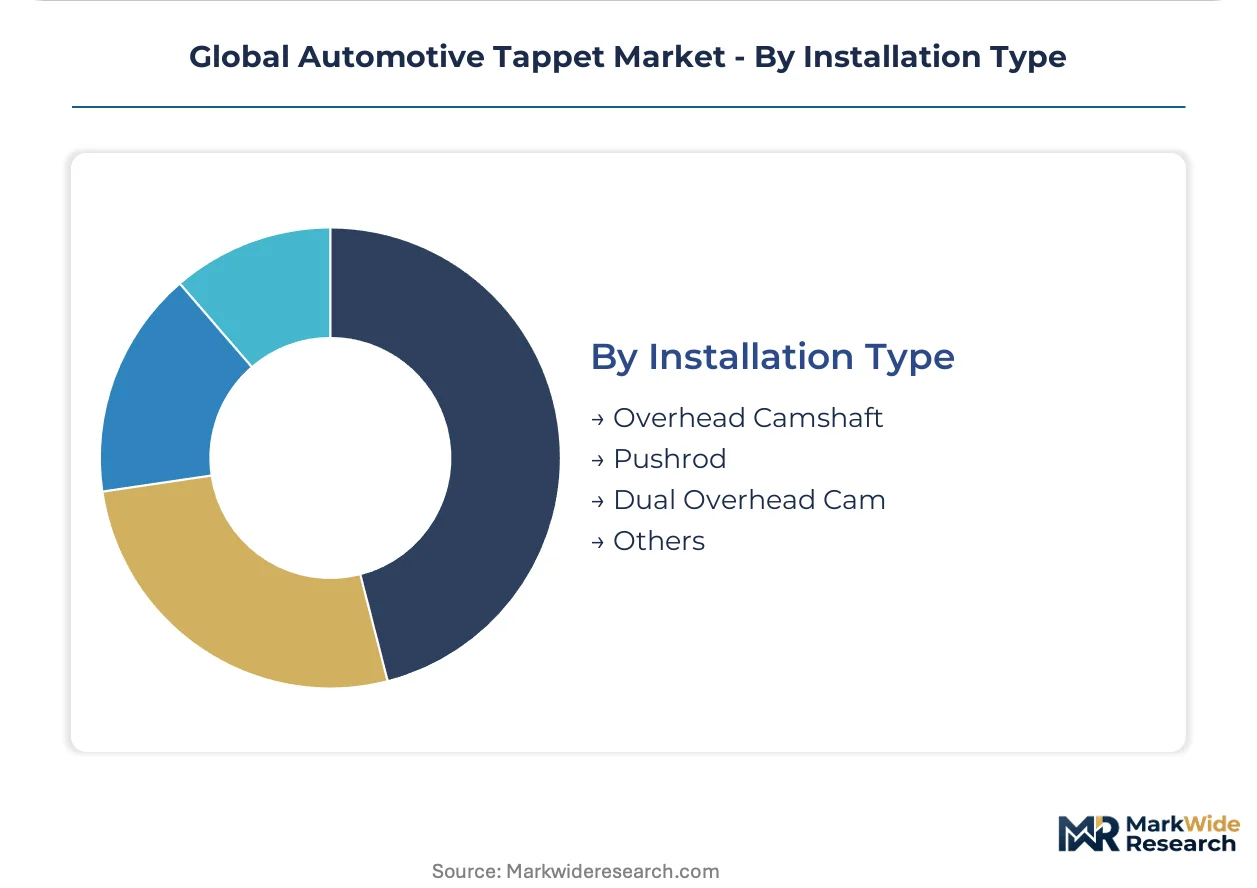
- Overhead Camshaft:Direct-acting designs eliminate pushrods and place tappets in immediate contact with cam lobes. Chinese and German OEM lineups favor this configuration for downsized turbocharged engines. Reduced reciprocating mass enables higher RPM operation.
- Dual Overhead Cam:Separate intake and exhaust camshafts require paired tappet sets with matched tolerances. High-performance applications specify these for precise valve timing control.
- Pushrod:Traditional V8 architectures in Detroit light-trucks maintain demand for cylindrical body designs.
- Others:Specialized racing and industrial engine formats.
Overhead camshaft formats absorb dominant engineering resources; dual overhead cam variants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chrome-molybdenum bar stock availability and vacuum carburizing furnace density anchor automotive tappet manufacturing geography. Demand concentrates where powertrain engineering clusters intersect with precision machining heritage and emission regulation stringency.
China
Downsized turbocharged engine programs from SAIC Motor and Geely Auto drive hydraulic tappet procurement volumes. GB 18352 emission testing protocols extend supplier qualification cycles, favoring domestic heat treatment specialists. Shanghai and Changchun host concentrated camshaft-tappet subsystem integration facilities serving local OEM lineups.
Germany
Direct-acting overhead cam designs for premium passenger vehicles specify sub-micron tolerance roller tappets. EU F-Gas Regulation friction mandates cascade into valve train subsystem documentation requirements. Stuttgart and Baden-Württemberg precision grinding specialists dominate European roller tappet capacity.
United States
Detroit-based light-truck manufacturers sustain forged steel tappet demand through V8 pushrod architectures. EPA Tier 3 tailpipe standards accelerate low-lash hydraulic specifications in passenger vehicle programs. Michigan and Ohio heat treatment corridors supply localized induction hardening capacity.
India
Maruti Suzuki and Hyundai Motor India engine manufacturing expansion in Manesar and Sriperumbudur creates localized sourcing gaps. BIS automotive component standards govern material certification for domestic valve train procurement. Tamil Nadu and Haryana powertrain clusters attract tier-one supplier heat treatment investments.
Japan
Dual overhead cam high-performance applications from Toyota and Honda sustain matched-tolerance tappet set demand. METI energy efficiency directives constrain allowable valve train friction coefficients in type-approval testing. Aichi and Kanagawa precision machining corridors maintain CNC grinding skill concentrations for roller profile tolerances.
Global Automotive Tappet Market Vendor Landscape
Backward integration into captive heat treatment and precision grinding dominates the current landscape as tier-one suppliers consolidate valve train subsystem accountability. The vendor base stratifies across three tiers: integrated powertrain specialists with full valve train capability, precision grinding-focused component suppliers, and regional forged steel producers serving high-volume segments. Two archetypes define competitive positioning: subsystem integrators competing on specification breadth, and precision machining specialists defending margin through geometric tolerance capability. M&A activity and geographic capacity expansion represent the dominant competitive moves as suppliers calibrate seven-year heat treatment capex cycles against uncertain ICE production commitments.
Within the integrated subsystem tier, Schaeffler AG and Eaton Corporation exemplify archetypes competing on valve train bundling rather than discrete component pricing. SKF occupies a position among precision grinding specialists where sub-micron roller geometry capability anchors supplier qualification. These three entities represent the competitive spectrum from full subsystem integration to geometric specialization.
| Leading Market Players |
|---|
| Schaeffler AG |
| SKF |
| Eaton Corporation |
| Federal-Mogul LLC |
| NSK Ltd |
| Rane Engine Valve Limited |
| Wuxi Xizhou Machinery Co Ltd |
| Competition Cams Inc |
| Crower Cams & Equipment Company Inc |
| Others |
Supply Flow & Price Mechanics
Sub-micron tolerance certification divergence separates captive heat treatment specialists from commodity forged steel suppliers, with pricing power accumulating among precision grinding operations that can document GB 18352 friction compliance while commodity producers face margin compression from chrome-molybdenum bar stock volatility.
Pricing Analysis
Warranty-bundled friction testing documentation commands premium positioning among German OEM procurement teams, while unbundled component-only pricing dominates Detroit light-truck volume contracts. Three-tier pricing structure across premium roller geometries, standard hydraulic assemblies, and economy mechanical designs reflects certification grade and heat treatment traceability. Cost compression in forged steel tappets is intensifying because alloy input volatility outpaces contract renegotiation cycles. Aftermarket distributors exhibit highest price sensitivity; racing and hypercar builders show least sensitivity due to gram-level performance requirements.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit operate hub-and-spoke patterns that consolidate precision grinding output before final OEM assembly line delivery. Manufacturing concentration rests on Germany, China, and the United States where vacuum carburizing furnace density intersects with camshaft-tappet subsystem integration facilities. Chrome-molybdenum bar stock, needle bearing assemblies, and diamond-like carbon coating feedstock anchor raw material dependencies. Single-source vulnerability concentrates around Baden-Württemberg precision grinding specialists. Distribution runs through tier-one powertrain supplier networks rather than direct OEM component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive tappet competitive dynamics have become a vertical-integration race as seven-year heat treatment capex cycles force suppliers to secure captive precision grinding capability or risk disqualification from integrated valve train subsystem contracts.
For Market Incumbents: Lock in GB 18352 certification documentation capabilities to defend against Chinese domestic heat treatment specialists expanding into subsystem integration. Prioritize vacuum carburizing furnace investments in Tamil Nadu and Haryana to capture Maruti Suzuki and Hyundai Motor India localized sourcing requirements before competitor furnace commissioning. Electromechanical valve actuation prototyping programs represent the priority R&D hedge against long-term ICE volume erosion.
For New Entrants and Emerging Players: EPA Tier 3 in the United States opens a window for low-lash hydraulic tappet specialists that can bundle friction testing services with component sales, bypassing capital-intensive heat treatment investments. India passenger vehicle production expansion presents the most penetrable geography given documented localized sourcing gaps in Manesar and Sriperumbudur. Pursue joint development agreements with domestic heat treatment specialists rather than greenfield furnace construction.
For Investors and Strategic Acquirers: Re-rating potential sits with precision grinding specialists possessing sub-micron roller geometry capability given EU F-Gas Regulation friction documentation requirements tightening OEM qualification protocols. Long-term viability hinges on calibrating heat treatment capex cycles against residual ICE production commitments across the analysis window. Monitor electromechanical valve actuation patent filing velocity as inflection indicator for tappet demand displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive vacuum carburizing capacity secures Schaeffler AG margin control across European OEM programs. |
| Precision Grinding Capability Expansion | Sub-micron tolerance achievement anchors SKF supplier qualification for German direct-acting overhead cam designs. |
| Localized Sourcing Facility Development | Heat treatment investments in Tamil Nadu capture Hyundai Motor India engine manufacturing expansion requirements. |
| Friction Testing Documentation Bundling | EU F-Gas Regulation compliance services reduce OEM certification burden and command premium pricing. |
| Composite Material Validation Programs | Carbon-fiber-reinforced PEEK endurance racing validation by BMW M GmbH rewrites performance engine procurement criteria. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and precision grinding operations managers. Vehicle production databases, EPA emission certification records, EU type-approval documentation, and heat treatment equipment manufacturer order books provided quantitative foundations. Bottom-up tappet unit demand estimates triangulated against top-down powertrain production forecasts across the analysis window.
Granularity-level modeling distinguished hydraulic, roller, mechanical, and solid tappet architectures; steel, composite, aluminum, and titanium material tiers; and overhead camshaft, dual overhead cam, and pushrod installation configurations. CAGRs derived from segment-level volume trajectories calibrated to OEM production commitments and emission regulation phase-in schedules. Electromechanical valve actuation technology readiness levels and ICE production residual curves informed long-term demand displacement assumptions.
The model assumes a particular technology adoption path; alternative pathways for electromechanical valve actuation would alter the outlook if camless engine architectures achieve cost parity ahead of projected timelines. Forecasts reflect documented assumptions regarding emission regulation stringency, powertrain electrification rates, and alloy steel input pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Carburetor Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Global Automotive Dyno Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
EV Powertrain Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
North America Torque Vectoring Market
Powertrain
Gas Engine Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Turbocharger Actuators Market
Powertrain
Power Steering Filter Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Car Drive System Market