
 Gear Oil Market | 2026-2036
Gear Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Oil Market Analysis
Asset-light lubricant blending and toll-manufacturing arrangements are reconfiguring competitive entry barriers for mid-tier suppliers. FUCHS Petrolub SE leverages its captive additive technology to sustain premium positioning in synthetic gear oils. ExxonMobil Corporation anchors volume supply through integrated base-oil production and direct OEM relationships. Chevron Corporation differentiates via specialized mining and power-generation gearbox service programs.
Gear oil is a high-viscosity lubricant formulated with extreme-pressure additives such as sulfur-phosphorus compounds, designed to protect meshing gear teeth from wear, scuffing, and micro-pitting under boundary lubrication conditions across automotive, industrial, and marine drivetrain systems. Synthetic formulations command margin premiums due to extended drain intervals and thermal stability in wind turbine and heavy-duty mining gearboxes, while mineral-based products retain cost-driven volume in mature industrial maintenance markets. API GL-5 specifications dominate automotive axle applications, whereas SAE J306 viscosity grades structure demand across precision industrial gearboxes where OEM fill specifications determine supplier selection.
EPA regulations on used-oil recycling and disposal shape reformulation priorities for US-manufactured gear lubricants, while REACH compliance in Europe restricts certain sulfur-based extreme-pressure additives and drives substitution toward ashless alternatives. China's GB standards and MEE environmental enforcement tighten volatile organic compound limits in domestic blending operations. Stakeholders must monitor evolving OEM factory-fill specifications and regional chemical restriction timelines to align R&D pipelines with compliance-ready product portfolios.
Market Dynamics
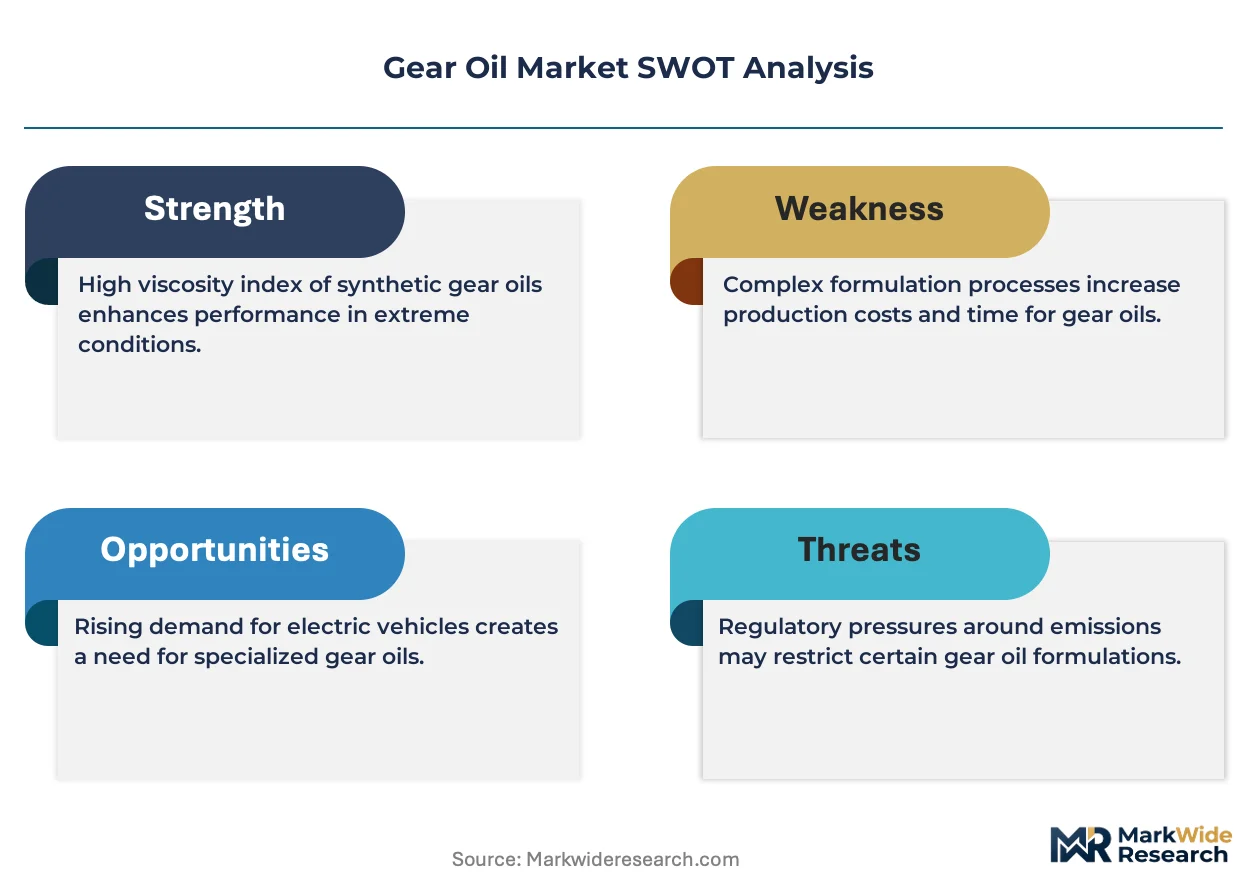
Wind turbine OEMs are consolidating factory-fill specifications around synthetic polyalphaolefin formulations, compressing supplier qualification timelines and elevating technical barriers for regional blenders serving aftermarket channels.
Growth Catalysts
- EPA emissions rules:Tightening volatile organic compound limits in US manufacturing are accelerating reformulation toward low-VOC synthetic base stocks that extend drain intervals in heavy-duty gearboxes.
- Steel and cement plants:China's industrial corridor cities are expanding preventive maintenance programs for large-scale gear systems, driving procurement volume for high-performance extreme-pressure lubricants.
- Offshore wind installation:Marine gearbox OEMs in the North Sea are specifying corrosion-resistant synthetic formulations to withstand salt spray and humidity during turbine commissioning.
Market Restraints
- Group III+ base oil supply:Refinery capacity concentration in the US Gulf Coast and Singapore creates input cost volatility for synthetic gear oil producers during turnaround seasons.
- REACH chemical restrictions:ECHA's tightening limits on sulfur-phosphorus extreme-pressure additives are forcing European blenders toward ashless alternatives with unproven field performance in legacy mining equipment.
- Mineral oil substitution:Cost-driven maintenance managers in mature industrial markets continue specifying Group I/II mineral formulations, capping premium synthetic penetration in price-sensitive segments.
Strategic Opportunities
- Indian wind energy:Gujarat and Tamil Nadu state renewable mandates are creating factory-fill demand for synthetic gear oils in domestically manufactured nacelles and yaw drives.
- Predictive maintenance integration:Sensor-enabled oil condition monitoring is converging with lubricant supply contracts, enabling performance-based pricing models tied to gearbox reliability metrics.
- Brazilian mining:ANVISA's streamlined chemical registration pathway for industrial lubricants is reducing market entry timelines for specialized open-gear formulations serving iron ore extraction.
Industry Challenges
- Additive chemist scarcity:Formulation expertise in sulfur-phosphorus and ashless extreme-pressure chemistry is concentrating among retirees, constraining R&D pipeline velocity for mid-tier blenders.
- OEM qualification timelines:Wind turbine gearbox manufacturers require 18-24 month field validation protocols before approving alternative lubricant suppliers, freezing competitive rotation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Oil Market |
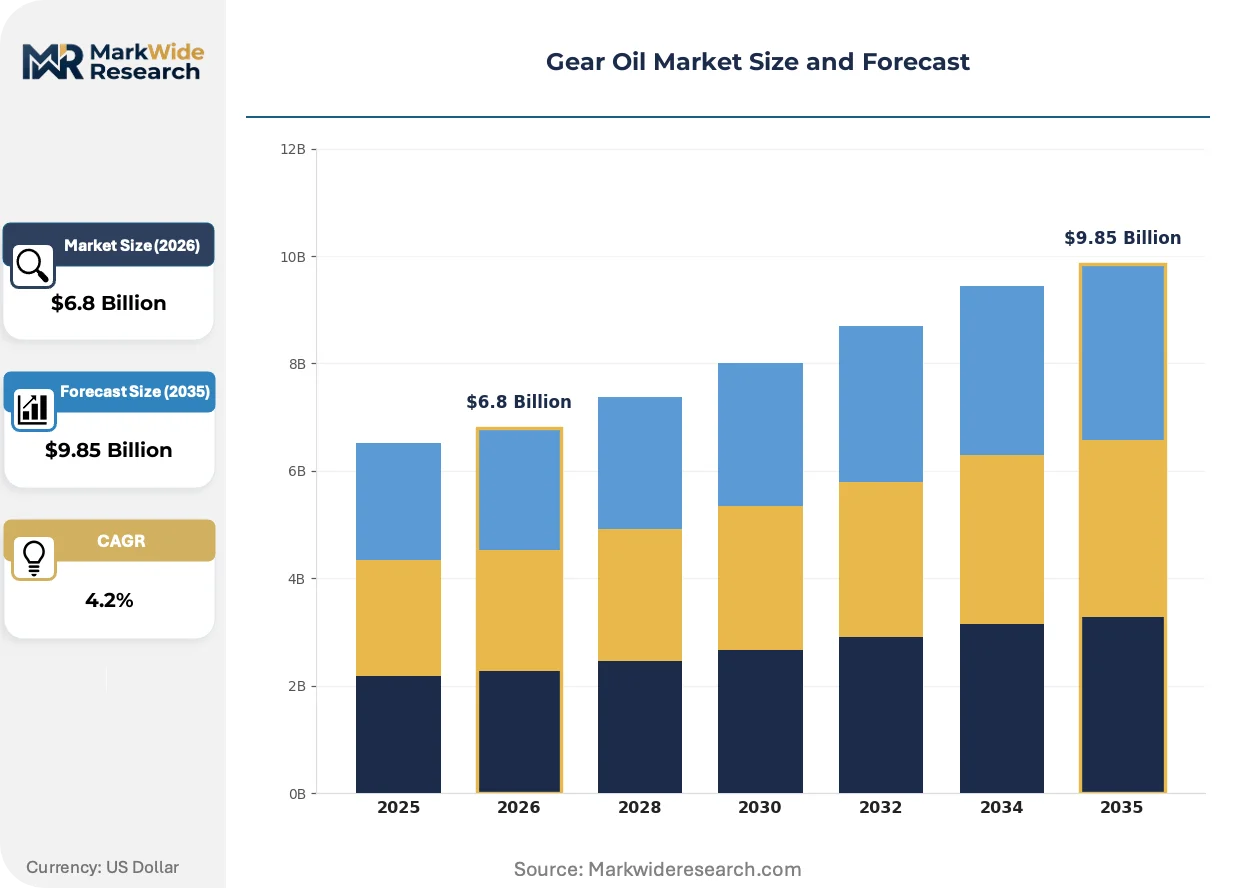
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-Synthetic, Biodegradable Application: Automotive Transmissions, Industrial Gearboxes, Marine Applications, Agricultural Machinery Performance Level: API GL-4, API GL-5, API GL-6, SAE J306 Packaging Type: Bulk, Drums, Bottles, Sachets |
| Companies Covered | BP plc, FUCHS Petrolub SE, ExxonMobil Corporation, Valvoline, Castrol, Shell plc, TotalEnergies SE, Kluber Lubrication, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Oil Market Emerging Trajectories
Digital oil analysis platforms are compressing maintenance decision cycles and rewiring distributor value capture in industrial lubricant supply chains.
Sensor-embedded gear oil monitoring is digitizing condition-based maintenance workflows in wind turbine and mining operations. Siemens Gamesa and Vestas service divisions are deploying real-time viscosity and particle-count telemetry across offshore fleets. This infrastructure is digitizing lubricant procurement from scheduled drum orders to algorithm-triggered replenishment contracts.
REACH Annex XVII restrictions on boron and chlorine compounds are accelerating ashless phosphorus-ester additive adoption in European industrial gearboxes. German gearbox OEMs Flender and SEW-Eurodrive are revising factory-fill specifications ahead of 2026 enforcement deadlines. Mining operators in Poland and Sweden are trialing compliant formulations in high-load kiln and mill applications.
Direct procurement from blenders is displacing traditional distributor intermediaries among large fleet operators. US Class 8 trucking companies with centralized maintenance facilities are negotiating volume contracts with ExxonMobil and Chevron lubricant divisions. This channel compression is most visible in the Texas Permian Basin, where oilfield service companies consolidate lubricant purchasing across drilling rig and pressure pumping fleets.
Gear Oil Market Segmentation
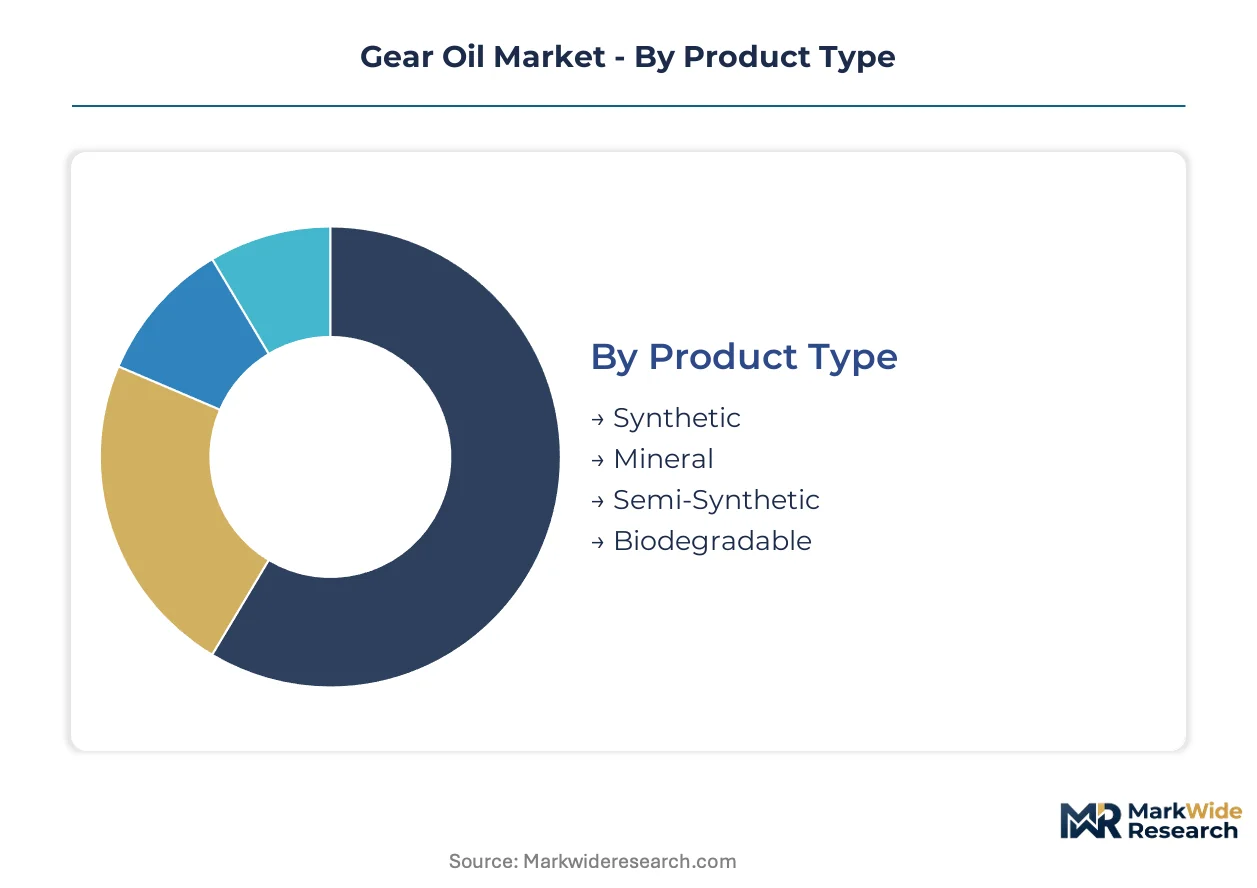
Gear oil segmentation reflects divergent procurement rhythms across product chemistry, application severity, and packaging economics. Cycle times range from quarterly drum orders in mining maintenance to multi-year factory-fill contracts in wind turbine OEM supply.
Product Type:
Synthetic formulations turn over fastest in aftermarket channels due to extended drain intervals compressing replenishment frequency, while mineral oils cycle slowly through mature industrial accounts with legacy equipment.
- Synthetic:Polyalphaolefin and ester-based formulations deliver thermal stability above 150°C and oxidation resistance extending drain intervals. Demand concentrates in Vestas and Siemens Gamesa wind turbine service contracts where salt-laden offshore environments accelerate fluid degradation.
- Mineral:Group I and II base stocks blended with sulfur-phosphorus extreme-pressure additives serve cost-driven maintenance programs. Steel mills in China's Hebei province specify these formulations for open-gear kiln drives where contamination rates mandate frequent replacement regardless of base oil quality.
- Semi-Synthetic:Group III base oils with synthetic additive packages balance performance and cost for mid-tier fleet operators.
- Biodegradable:Vegetable-derived esters formulated for environmentally sensitive waterways and agricultural runoff zones.
Mineral oil dominates installed base across legacy industrial machinery. Synthetic formulations are where expansion concentrates as OEM factory-fill specifications tighten.
Application:
Volume flows heaviest through automotive transmission channels with standardized API specifications, while margin concentrates in specialized marine and mining applications requiring corrosion-resistant additive chemistry.
- Automotive Transmissions:Hypoid gear lubricants meeting API GL-5 specifications protect axle differentials against scuffing under high-torque acceleration. Class 8 trucking fleets in the Texas Permian Basin negotiate direct blender contracts bypassing distributor markups.
- Industrial Gearboxes:ISO VG 68 through 680 viscosity grades serve precision gear trains in cement kilns and steel rolling mills. Preventive maintenance programs at China National Building Material plants drive drum-volume procurement of extreme-pressure formulations.
- Marine Applications:Corrosion-inhibited synthetics withstand salt spray in offshore wind turbine commissioning.
- Agricultural Machinery:Universal tractor transmission oils lubricating final drives, hydraulics, and wet brakes in seasonal operating patterns.
Automotive transmission represents the largest volume channel. Industrial gearbox applications are climbing the fastest as predictive maintenance programs expand.
Performance Level:
Specification tiering separates premium factory-fill approvals from price-competitive aftermarket alternatives, with OEM qualification timelines creating sticky supplier relationships at the top tier.
- API GL-5:Extreme-pressure hypoid gear oils with sulfur-phosphorus chemistry prevent scoring in automotive differentials under boundary lubrication. Ford and General Motors axle assembly plants specify these formulations for factory-fill programs with 18-24 month supplier validation protocols.
- API GL-4:Moderate extreme-pressure protection for synchronized manual transmissions where yellow metal compatibility limits sulfur content. Aftermarket demand persists in Latin American commercial vehicle rebuild markets.
- API GL-6:Obsolete specification retained in limited high-offset hypoid axle applications.
- SAE J306:Viscosity grade classification structuring industrial gearbox oil selection across multigrade and monograde products.
API GL-5 dominates automotive axle specifications. SAE J306 industrial grades are gaining share fastest as precision gearbox OEMs tighten viscosity control requirements.
Packaging Type:
Packaging economics track customer scale and logistics infrastructure, with bulk supply capturing fleet concentration and unit packaging serving fragmented agricultural and aftermarket channels.
- Bulk:Tanker-truck delivery to centralized maintenance facilities with on-site storage and dispensing systems. US oilfield service companies in the Permian Basin consolidate 10,000-gallon orders across drilling rig and pressure pumping fleets.
- Drums:55-gallon steel containers remain standard for industrial accounts lacking bulk storage infrastructure. Mining contractors in Western Australia specify drum delivery to remote excavation sites.
- Bottles:Retail quart and gallon containers for passenger vehicle DIY maintenance.
- Sachets:Single-use pouches for field service applications and emerging market affordability.
Drum packaging dominates installed base in industrial maintenance. Bulk supply is where expansion concentrates as fleet operators centralize lubricant procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in base oils and finished lubricants tilt toward net-import dependence in industrializing economies, while established refining hubs sustain trade surpluses in Group II and III base stocks. Regional formulation capabilities diverge sharply between markets with captive additive production and those reliant on imported packages.
United States
Gulf Coast petrochemical complexes supply Group II and III base oils to domestic blenders serving wind turbine service fleets in Texas and Oklahoma. EPA emissions rules on volatile organic compounds are accelerating reformulation timelines for gear lubricants manufactured in Houston and Baytown facilities. The Permian Basin oilfield services corridor concentrates bulk procurement contracts for heavy-duty axle and transmission fluids.
China
Steel mills in Hebei province and cement plants across the Yangtze River Delta are expanding preventive maintenance programs for kiln drives and rolling mill gearboxes. MEE environmental enforcement is tightening volatile organic compound limits at blending plants in Shanghai and Ningbo. Industrial corridor cities in Shandong and Jiangsu provinces are driving drum-volume procurement of extreme-pressure formulations.
Germany
Wind turbine gearbox OEMs in Bavaria and North Rhine-Westphalia are consolidating factory-fill specifications around synthetic polyalphaolefin formulations ahead of REACH deadlines. ECHA restrictions on sulfur-phosphorus extreme-pressure additives are forcing blenders toward ashless alternatives validated in Flender and SEW-Eurodrive equipment. The Ruhr industrial basin maintains demand for high-viscosity industrial gear oils in steel and heavy machinery applications.
India
Gujarat and Tamil Nadu state renewable energy mandates are creating factory-fill demand for synthetic gear oils in domestically manufactured wind turbine nacelles. BIS standards alignment with international viscosity classifications is streamlining import substitution for industrial gearbox formulations. Manufacturing clusters in Pune and Chennai are expanding blending capacity to serve mining and construction equipment aftermarket channels.
Brazil
Iron ore extraction operations in Minas Gerais and Pará states are specifying open-gear lubricants for mill and kiln applications in beneficiation plants. ANVISA's streamlined chemical registration pathway is reducing market entry timelines for specialized extreme-pressure formulations. The São Paulo industrial corridor sustains demand for automotive axle fluids in commercial vehicle assembly and aftermarket rebuild markets.
Gear Oil Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in additive chemistry and base oil refining. The market structures around three to five vertically integrated majors with captive supply chains, flanked by regional blenders dependent on toll-manufacturing arrangements. Strategic archetypes separate integrated energy majors with refinery-backed lubricant divisions, independent lubricant specialists with formulation IP, and toll-blenders serving price-sensitive aftermarket channels. Competitive moves concentrate on backward integration into additive manufacturing and direct procurement contracts that displace distributor intermediaries.
Among the integrated majors, ExxonMobil Corporation and Shell plc anchor volume supply through refinery-integrated base oil production and direct OEM relationships. FUCHS Petrolub SE occupies a position within the independent specialist tier, exemplifying premium positioning through captive additive technology. Chevron Corporation represents the mining and power-generation service program archetype, with specialized gearbox maintenance offerings. These three companies illustrate the competitive spectrum from scale-driven commodity supply to formulation-differentiated premium positioning.
| Leading Market Players |
|---|
| BP plc |
| FUCHS Petrolub SE |
| ExxonMobil Corporation |
| Valvoline |
| Castrol |
| Shell plc |
| TotalEnergies SE |
| Kluber Lubrication |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
Refinery undercapacity in the US Gulf Coast during turnaround seasons drives both input cost volatility for synthetic gear oil blenders and pricing power concentration among integrated majors with captive base oil production. This utilization squeeze feeds through to contract negotiations, where buyers face compressed supplier alternatives and extended lead times for Group III+ stocks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium synthetic, standard semi-synthetic, and economy mineral tiers. Price differentiation rests on certification level—factory-fill approvals from Vestas or Flender command substantial premiums over aftermarket alternatives—and volume scale, with Permian Basin oilfield services securing bulk discounts unavailable to fragmented mining contractors. Cost compression in the mineral tier is intensifying because steel mills in China's Hebei province prioritize drum-volume procurement over performance specifications. Fleet operators with centralized maintenance facilities exhibit lowest price sensitivity; legacy equipment maintenance managers in mature industrial markets remain most cost-conscious.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for additive package sourcing. Geographic supply concentration centers on the US Gulf Coast, Singapore, and Rotterdam for Group II and III base oil refining. Raw material dependencies draw from sulfur-phosphorus extreme-pressure additive chemistry, polyalphaolefin base stocks, and corrosion inhibitor packages. Single-source vulnerability in qualified wind turbine OEM factory-fill specifications locks blenders into 18-24 month validation cycles. Distribution runs through direct procurement contracts displacing traditional distributor intermediaries among large fleet operators, with drum logistics serving fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gear oil demand sits in early-cycle expansion as wind turbine installation rates accelerate factory-fill specification consolidation around synthetic formulations. Predictive maintenance integration creates new performance-based contract structures that reward technical differentiation over commodity supply.
For Market Incumbents: Entrench factory-fill relationships by accelerating additive chemistry R&D ahead of REACH sulfur-phosphorus restrictions, while securing captive supply of Group III+ base oils through refinery joint ventures in Singapore or the US Gulf Coast. Ashless extreme-pressure formulations from emerging European blenders threaten premium positioning; backward integration into additive manufacturing provides defensive moat. For New Entrants and Emerging Players: Build out toll-blending capacity in Gujarat and Tamil Nadu to capture Indian wind energy factory-fill demand before domestic majors consolidate supply relationships. The Brazilian mining aftermarket offers most penetrable white-space, with ANVISA's streamlined registration reducing entry friction for open-gear specialists. A technical service partnership model—embedding lubricant engineers at iron ore beneficiation plants—differentiates against commodity distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic formulation capacity as REACH compliance and OEM qualification timelines extend working capital cycles. Five-to-ten year viability favors blenders with captive additive IP and direct OEM channel control over toll-dependent regional players. The signal to watch is sensor-enabled oil condition monitoring adoption rates, which compress maintenance decision cycles and reward algorithm-triggered replenishment contract providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive sulfur-phosphorus and ashless chemistry production secures margin control against REACH supply disruptions. |
| Direct OEM Factory-Fill Contracts | Wind turbine gearbox manufacturers like Flender and SEW-Eurodrive consolidate specifications around validated synthetic suppliers. |
| Predictive Maintenance Platform Partnerships | Siemens Gamesa and Vestas service divisions deploy sensor telemetry that triggers algorithmic lubricant replenishment. |
| Regional Blending Capacity Expansion | Gujarat and Tamil Nadu state mandates create localized supply requirements for domestically manufactured nacelles. |
| REACH-Compliant Formulation Development | German OEMs revise factory-fill specifications ahead of ECHA enforcement deadlines for ashless alternatives. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with wind turbine service directors, mining maintenance managers, lubricant blending plant engineers, and industrial procurement leads; and secondary validation through customs trade data, EPA emissions filings, ECHA restriction timelines, and SEC disclosures from integrated energy majors. Bottom-up triangulation against top-down sectoral demand models anchored volume estimates across synthetic, mineral, and semi-synthetic product tiers.
Forecast inputs considered base oil capacity utilization rates, OEM factory-fill specification evolution, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions modeled include product chemistry, application severity, performance certification tier, packaging economics, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating wind energy installation pipelines and steel sector maintenance cycle patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier blenders or accelerated REACH enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Crankshaft Market
Powertrain
Car Oil Filter Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Clutch Friction Plate Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Camless Engine Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Yaw Damper Market
Powertrain
Crate Engines Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Car Active Purge Pump Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market