
 Car Active Purge Pump Market | 2026-2036
Car Active Purge Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Car Active Purge Pump Market Insights
A capital-intensity divergence between integrated system suppliers and component specialists is redrawing competitive boundaries in the Car Active Purge Pump Market. Continental AG leverages its in-house semiconductor and sensor capabilities to bundle purge pumps with full evaporative emission management systems. Robert Bosch GmbH anchors its position through extensive R&D spending on electronic control architectures that govern pump modulation cycles. Denso Corporation competes by dominating thermal management integration, linking purge pump operation to engine cooling system demands across Asian OEM platforms.
A car active purge pump is an electromechanical or pneumatic device that extracts fuel vapors from the charcoal canister and delivers them to the engine intake manifold for combustion, typically operating at flow rates between 15 and 40 liters per minute depending on canister volume and engine displacement. The device prevents hydrocarbon venting to atmosphere, satisfying evaporative emission control mandates while maintaining optimal air-fuel mixture ratios. Electric purge pumps command the dominant share of value given their precision modulation capability and compatibility with start-stop and hybrid powertrains, whereas mechanical pump demand is contracting as legacy internal combustion architectures phase out. Electronic control technology leads investment intensity as OEMs demand real-time diagnostic feedback and over-the-air calibration updates.
The EPA enforces evaporative emission test procedures under CFR Title 40 Part 86, compelling pump manufacturers to validate zero-leak performance across temperature extremes from minus 40 to plus 150 degrees Celsius. California Air Resources Board operates LEV III standards that mandate near-zero evaporative emissions, creating a de facto national benchmark that NHTSA references in corporate average fuel economy compliance pathways. Stakeholders must monitor pending revisions to Euro 7 emission limits from EMA frameworks, as tighter hydrocarbon limits would force redesigns of pump sealing materials and valve response times before regulatory deadlines crystallize.
Market Dynamics
The EPA's Tier 3 standards and California's LEV III regulations are compressing hydrocarbon emission limits, forcing automakers to replace passive purge valves with electronically modulated active pumps across powertrain architectures.
Growth Catalysts
- Hybrid Powertrain Proliferation:Start-stop systems and plug-in hybrid architectures require precise vapor extraction timing that only electric purge pumps can deliver.
- LEV III Compliance Mandates:California Air Resources Board standards for near-zero evaporative emissions are cascading into national EPA enforcement pathways.
- German Manufacturing Cluster:Continental AG and Robert Bosch GmbH anchor advanced pump production, concentrating R&D spillovers in Stuttgart and Hanover.
Market Restraints
- Semiconductor Input Volatility:Pump control modules depend on automotive-grade microcontrollers subject to foundry allocation constraints.
- Legacy ICE Phase-Out:Mechanical purge pump demand contracts as internal combustion production lines wind down in European and North American assembly plants.
- Material Specification Rigor:CFR Title 40 Part 86 mandates fluorocarbon-elastomer seals rated for minus 40 to plus 150 degrees Celsius, limiting supplier qualification pools.
Strategic Opportunities
- Over-the-Air Calibration:Electronic control architectures enable remote pump parameter updates, creating recurring service revenue streams for Tier 1 suppliers.
- Thermal Management Convergence:Linking purge pump operation to engine cooling system demands opens integration contracts with HVAC module manufacturers.
- Indian Passenger Vehicle Segment:Stringent Bharat Stage VI emission norms are forcing domestic automakers to adopt active purge systems previously absent in budget vehicle classes.
Industry Challenges
- Embedded Software Certification:Functional safety validation per ISO 26262 ASIL ratings extends development cycles for pump control firmware.
- Cross-Platform Integration:Purge pump modules must interface with disparate engine management systems across OEM lineups, multiplying validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Active Purge Pump Market |
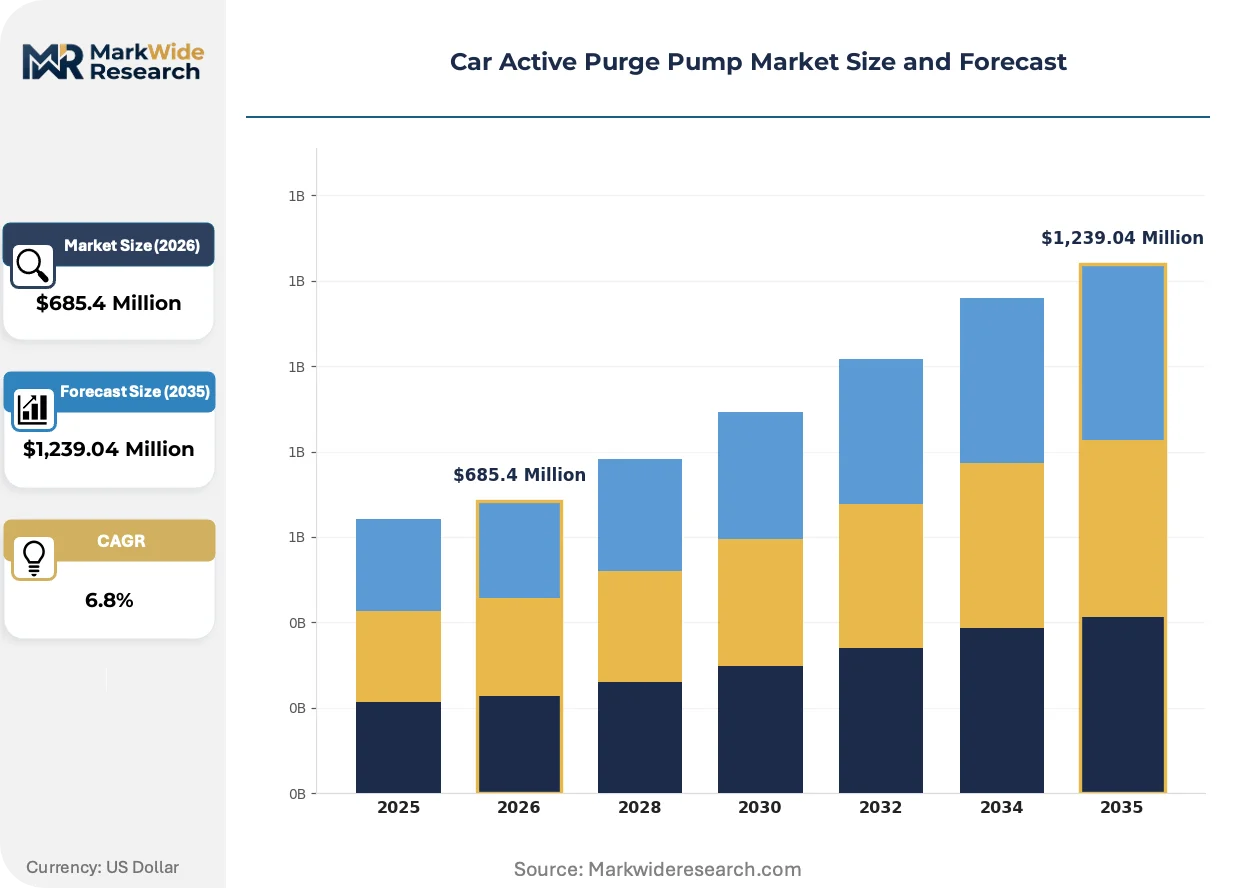
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Purge Pumps, Vacuum Pumps, Solenoid Pumps, Mechanical Pumps Technology: Variable Valve Technology, Dual Injection Technology, Electronic Control Technology, Pneumatic Activation Technology End User: OEMs, Aftermarket Service Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy-Duty Trucks |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Vitesco Technologies, Agilent Technologies, Rheinmetall Automotive, Schaeffler Group, HELLA GmbH & Co. KGaA, Hyundai Kefico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Active Purge Pump Market Trends and Innovations
Electronic modulation architectures are displacing pneumatic actuation across evaporative emission systems, while real-time diagnostic feedback loops are becoming standard procurement specifications.
Brushless DC motor designs with integrated Hall-effect sensors are supplanting brushed motor configurations in next-generation purge pumps. Tier 1 suppliers are adopting these architectures for hybrid vehicle programs requiring million-cycle durability. The shift is compressing supplier margins on legacy electromechanical platforms while rewarding semiconductor-integrated system houses.
REACH regulation amendments targeting per- and polyfluoroalkyl substances are forcing seal material reformulations across European supply chains. Compound suppliers must validate hydrogenated nitrile butadiene rubber alternatives for hydrocarbon resistance. Pump manufacturers serving BMW and Mercedes-Benz platforms face accelerated retesting timelines before 2026 model year certification deadlines.
Fleet operators and leasing companies are unbundling purge pump replacement from comprehensive maintenance contracts, creating direct aftermarket procurement channels. Independent repair networks in the United States are sourcing replacement modules through e-commerce platforms rather than franchised dealer parts operations. The pattern is most pronounced in California, where extended warranty mandates lengthen vehicle retention periods and concentrate wear-item demand.
Car Active Purge Pump Market Segmentation
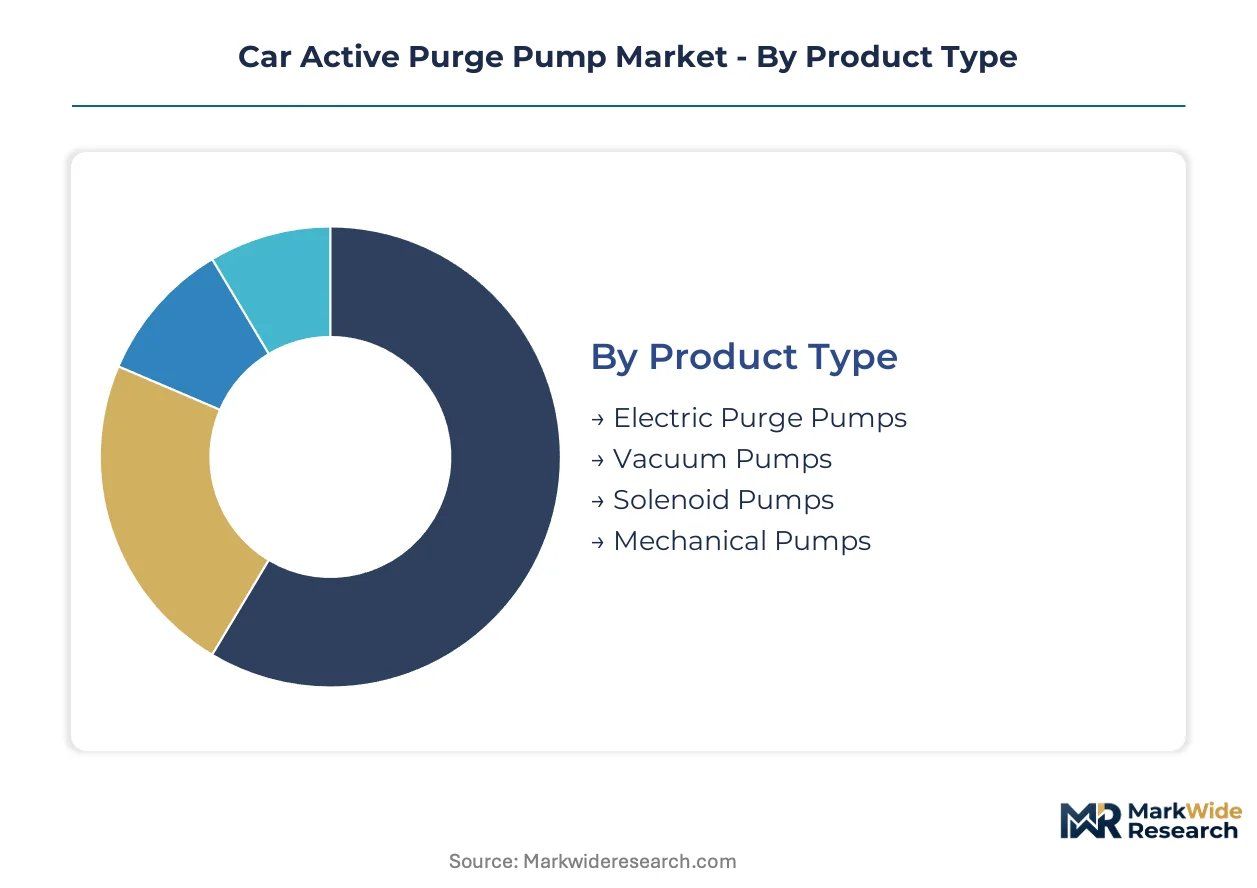
Segmentation in the Car Active Purge Pump Market reveals how regulatory stringency and powertrain electrification reshape procurement priorities across product architectures. Each dimension exposes divergent margin structures and qualification barriers that determine supplier competitiveness.
Product Type:
EPA Tier 3 and California LEV III standards enforce zero-leak performance across temperature extremes, forcing material and design differentiation that separates compliant from non-compliant pump categories.
- Electric Purge Pumps:Brushless DC motor architectures with integrated Hall-effect sensors deliver precision modulation for start-stop and hybrid powertrains. Demand concentrates in Germany where Continental AG and Robert Bosch GmbH anchor production for European OEM platforms facing Euro 7 pre-compliance deadlines.
- Vacuum Pumps:Pneumatic actuation systems leveraging engine manifold pressure differential serve legacy internal combustion architectures. Procurement contracts are contracting in North American assembly plants as electrification accelerates, though residual demand persists in commercial vehicle segments with extended ICE production timelines.
- Solenoid Pumps:Electromagnetic valve configurations enable rapid response times for canister purge cycles. Japanese OEMs favor these architectures for compact passenger vehicle platforms.
- Mechanical Pumps:Cam-driven or belt-actuated designs lack electronic feedback capability. Production volumes are declining across European and North American markets as passive purge valve replacement mandates take effect.
Established volume favors Electric Purge Pumps; emerging adoption favors Vacuum Pumps in residual commercial applications.
Technology:
Cost tier differentiation separates semiconductor-intensive architectures from pneumatic legacy systems, with software certification burdens creating margin compression at the premium end.
- Electronic Control Technology:Real-time diagnostic feedback and over-the-air calibration capability require ISO 26262 ASIL-rated firmware. Tier 1 suppliers invest heavily in embedded software validation for hybrid vehicle programs.
- Variable Valve Technology:Proportional solenoid control enables flow rate modulation between 15 and 40 liters per minute. German automotive clusters drive specification adoption for precision emission management.
- Dual Injection Technology:Coordinated purge timing with direct and port fuel injection systems optimizes combustion efficiency. Asian OEM platforms integrate these architectures for thermal management convergence.
- Pneumatic Activation Technology:Manifold pressure-dependent actuation lacks modulation precision. Demand is retreating to budget vehicle classes in markets with delayed emission enforcement.
Margin concentration sits with Electronic Control Technology; volume scaling favors Variable Valve Technology.
End User:
Customer type determines warranty liability exposure and replacement cycle predictability, with fleet operators unbundling maintenance contracts to create direct procurement channels.
- OEMs:Platform-level integration contracts require cross-engine management system validation. Procurement specifications mandate million-cycle durability for hybrid powertrain applications.
- Fleet Operators:Extended vehicle retention periods in California concentrate wear-item demand. Independent repair networks source replacement modules through e-commerce platforms rather than franchised dealer parts operations.
- Aftermarket Service Providers:Post-warranty replacement demand is expanding as Bharat Stage VI compliance forces adoption in Indian passenger vehicle segments previously absent active purge systems.
- Vehicle Assemblers:Contract manufacturing arrangements for regional production hubs face compressed qualification timelines for seal material reformulations under REACH amendments.
Contract security favors OEMs; margin expansion favors Fleet Operators.
Application:
Vehicle mass and duty cycle determine canister volume requirements and pump flow rate specifications, with light truck segments presenting hybrid architecture transition complexity.
- Passenger Vehicles:Compact canister designs and start-stop compatibility requirements dominate procurement specifications. German and Japanese OEM platforms lead electric purge pump adoption.
- Light Trucks:Dual-use duty cycles combining urban stop-start with highway cruising demand flexible modulation architectures. North American OEMs face integration complexity across diverse powertrain lineups.
- Commercial Vehicles:Extended idle operation and larger fuel tank volumes require higher-capacity purge systems. Fleet emission compliance deadlines in California drive retrofit demand.
- Heavy-Duty Trucks:Severe-duty thermal environments stress seal materials across the minus 40 to plus 150 degrees Celsius validation range. Fluorocarbon-elastomer specifications limit supplier qualification pools.
Technology leadership sits with Passenger Vehicles; retrofit volume expansion favors Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in active purge pump components track regulatory enforcement intensity rather than manufacturing cost alone. Germany and the United States anchor component sourcing networks, while India and China emerge as demand expansion zones under tightening emission mandates.
United States
California Air Resources Board operates LEV III standards that mandate near-zero evaporative emissions, forcing automakers to replace passive purge valves with active pumps across hybrid lineups. EPA enforces Tier 3 vehicle emission standards under CFR Title 40 Part 86, compelling manufacturers to validate zero-leak performance across temperature extremes. Detroit-Warren-Dearborn automotive cluster concentrates procurement specifications for light truck platforms requiring flexible modulation architectures.
Germany
Continental AG and Robert Bosch GmbH anchor Stuttgart and Hanover manufacturing clusters serving European OEM platforms facing Euro 7 pre-compliance deadlines. ECHA operates REACH regulation amendments targeting per- and polyfluoroalkyl substances, forcing seal material reformulations before 2026 model year certification. Bavaria-based suppliers invest in brushless DC motor architectures with integrated Hall-effect sensors for million-cycle durability requirements.
China
Domestic automakers accelerate hybrid powertrain adoption under MIIT dual carbon goals, expanding procurement of electric purge pumps for start-stop compatibility. NMPA enforces GB standards for evaporative emission control that align with tightening international benchmarks. Yangtze River Delta automotive corridor concentrates demand for thermal management convergence linking purge pump operation to engine cooling systems.
India
Bharat Stage VI emission norms force domestic automakers to adopt active purge systems previously absent in budget passenger vehicle classes. Central Pollution Control Board implements stringent hydrocarbon capture requirements that cascade from commercial to light-duty segments. Tamil Nadu and Maharashtra vehicle assembly hubs face compressed qualification timelines for seal material validation under accelerated compliance deadlines.
Japan
Denso Corporation dominates thermal management integration for Asian OEM platforms, linking purge pump operation to engine cooling system demands. METI oversees automotive component standards that emphasize real-time diagnostic feedback and over-the-air calibration capability. Kansai-Osaka industrial corridor concentrates R&D investment on electronic control architectures governing pump modulation cycles.
Car Active Purge Pump Market Competitive Landscape
Concentration sits with integrated system suppliers possessing in-house semiconductor and sensor capabilities. Three strategic archetypes dominate: full-system bundlers combining purge pumps with evaporative emission management, electronic control specialists investing in ISO 26262 ASIL-rated firmware validation, and thermal management integrators linking pump operation to HVAC modules. Dominant competitive moves include backward integration into automotive-grade microcontroller supply and strategic partnerships for cross-platform engine management system validation.
Among Germany-based integrated suppliers, Continental AG and Robert Bosch GmbH exemplify the full-system bundler archetype, while Denso Corporation represents the thermal management convergence approach. These three anchors occupy positions defined by geographic manufacturing clusters and powertrain platform specialization rather than interchangeable component supply.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Vitesco Technologies |
| Agilent Technologies |
| Rheinmetall Automotive |
| Schaeffler Group |
| HELLA GmbH & Co. KGaA |
| Hyundai Kefico |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade microcontroller foundry capacity utilization above 85 percent in Taiwan and South Korea concentrates bargaining power among semiconductor-integrated system houses, compressing margins for component specialists while elevating price floors for EPA Tier 3 compliant pump modules. Scale economies in brushless DC motor production anchor Continental AG and Robert Bosch GmbH in Stuttgart and Hanover, creating regional price leadership that smaller suppliers cannot match without backward integration into sensor fabrication.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for million-cycle durability pumps, with premium-mid-economy pricing differentiation separating ISO 26262 ASIL-D certified architectures from standard firmware configurations. Price differentiation hinges on certification grade and volume scale, with hybrid powertrain procurement commanding 40-60 percent volume premiums over legacy ICE applications. Cost compression in economy-tier mechanical pumps is intensifying because REACH amendment compliance accelerates fluorocarbon-elastomer reformulation expenses. Fleet operators exhibit highest price sensitivity due to unbundled maintenance contracts, while German OEM platform engineers demonstrate lowest sensitivity given Euro 7 pre-compliance liability exposure.
Supply Chain Analysis
Inventory cycles extending 16-20 weeks for automotive-grade Hall-effect sensors reflect foundry allocation constraints that propagate through Tier 1 supplier production schedules. Manufacturing concentrates in Germany, China, and Mexico, with Stuttgart and Hanover anchoring European precision pump output while Yangtze River Delta facilities serve domestic Chinese hybrid adoption. Raw material dependencies center on neodymium magnet feedstocks, hydrogenated nitrile butadiene rubber compounds, and fluorocarbon-elastomer seals. Single-source vulnerability in Taiwan semiconductor foundries presents structural risk given EPA zero-leak validation requirements for electronic control modules. Distribution runs through franchised dealer parts operations in North America and direct OEM platform integration contracts in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against solid-state vapor recovery architectures that threaten electromechanical pump relevance as battery-electric vehicle penetration advances. Incumbents must fortify positions before electronic modulation becomes commoditized.
For Market Incumbents: Secure captive supply of automotive-grade microcontrollers through foundry partnerships or in-house wafer fabrication investments, insulating against allocation shocks that disrupt EPA Tier 3 validation timelines. Deepen thermal management integration capabilities linking purge pump operation to HVAC modules, creating switching costs that resist Denso Corporation platform dominance in Asian OEM sourcing.
For New Entrants and Emerging Players: ISO 26262 ASIL-B certification fast-tracks enable qualification for Indian Bharat Stage VI retrofit programs where domestic automakers lack established supplier relationships. Target Tamil Nadu and Maharashtra vehicle assembly hubs with localized seal material validation capabilities, exploiting compressed compliance deadlines that disadvantage distant competitors. Pursue direct e-commerce distribution to California independent repair networks bypassing franchised dealer capture.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-integrated system houses with in-house sensor and firmware capabilities over pure-play mechanical component manufacturers. Long-term viability through 2030 hinges on hybrid powertrain content persistence as battery-electric transition rates remain uncertain. Monitor EPA Tier 4 pre-rulemaking signals as inflection indicator for extended electromechanical pump demand or accelerated solid-state substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcontroller Supply | Captive foundry capacity insulates Continental AG and Robert Bosch GmbH against semiconductor allocation constraints disrupting EPA validation. |
| Thermal Management Convergence Partnership | Linking purge pump operation to HVAC modules creates platform-level integration contracts with BMW and Mercedes-Benz engineering teams. |
| Bharat Stage VI Certification Fast-Track | Accelerated qualification timelines in Tamil Nadu unlock Indian passenger vehicle segments previously absent active purge systems. |
| Over-the-Air Calibration Infrastructure | Remote parameter update capability generates recurring service revenue streams from California fleet operator extended retention periods. |
| REACH Amendment Seal Material Reformulation | Hydrogenated nitrile butadiene rubber validation ahead of 2026 model year deadlines secures European OEM platform continuity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads; and secondary validation against EPA CFR Title 40 Part 86 filings, California Air Resources Board LEV III enforcement data, ECHA REACH amendment documentation, and vehicle production databases from IHS Markit. Bottom-up triangulation across pump unit demand curves and top-down reconciliation with evaporative emission system market aggregates anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression-adjusted adoption curves incorporating hybrid powertrain penetration rates and regulatory enforcement phase-in schedules. Key forecast inputs included semiconductor foundry capacity expansion announcements and Euro 7 pre-compliance engineering timelines from EMA framework consultations.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Tier 3 enforcement and gradual Euro 7 crystallization; material deviation in battery-electric transition velocity or semiconductor supply normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Turbocharger Actuators Market
Powertrain
Steering Damper Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Drive Shaft Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Clutch Hub Puller Market
Powertrain
CNG Powertrain Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Timing Belt Market
Powertrain
Yaw Damper Market