
 GCC Trailer Market | 2026-2036
GCC Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Trailer Market Insights
Market Context
Saudi Arabia's domestic trailer production capacity is shifting toward aluminum-intensive designs as regional smelters expand alloy supply. Schmitz Cargobull AG leverages its European engineering base to serve GCC fleets demanding corrosion-resistant specifications for desert operating conditions. Fahrzeugwerk Bernard Krone anchors its regional position through specialized temperature-controlled platforms serving pharmaceutical and food logistics chains. Wabash National competes on lightweight composite technology that reduces fuel consumption across long-haul desert routes between Gulf Cooperation Council member states.
Technical Definition and Segment Structure
A trailer is a non-powered wheeled vehicle designed for towing by a tractor unit, constructed with steel, aluminum, or composite chassis structures and rated for payloads typically exceeding twenty metric tons in heavy commercial configurations; its primary purpose is to extend cargo capacity for land-based freight distribution across fixed-route and point-to-point logistics networks. Flatbed configurations dominate construction and project cargo applications where dimensional flexibility outweighs weather protection requirements, while tanker trailers command premium margin pools in petroleum and chemical transport segments given specialized welding certifications and hazardous materials compliance overhead. Aluminum-intensive material selection is displacing traditional steel dominance in long-haul fleets where tare weight reduction translates directly to payload revenue recovery across high-frequency Gulf corridor routes.
Regulatory Framework
Gulf Standardization Organization (GSO) technical regulations govern brake performance, lighting, and coupling standards across Saudi Arabia, the UAE, Kuwait, Qatar, Bahrain, and Oman, while national transport authorities in each member state enforce axle load limits and periodic inspection regimes that determine fleet replacement economics. Dubai's Roads and Transport Authority (RTA) and Saudi Arabia's General Authority for Transport implement overlapping but distinct commercial vehicle registration protocols that shape cross-border trailer interoperability specifications. Stakeholders must monitor evolving GSO electrification readiness standards and carbon intensity benchmarking for trailer manufacturing as Gulf states advance national decarbonization commitments that will eventually cascade into procurement criteria for logistics operators.
Market Dynamics
GSO brake performance and coupling standards are compressing fleet replacement cycles across Saudi Arabia and the UAE, forcing logistics operators to accelerate procurement of compliant trailers while regional smelters expand aluminum alloy supply to meet lightweight chassis demand.
Growth Catalysts
- Flatbed trailer procurement:Construction and project cargo operators in Dubai's Jebel Ali corridor are expanding dimensional-flexibility fleets to serve port-linked distribution infrastructure.
- GSO harmonization:Gulf Standardization Organization vehicle safety codes are accelerating compliance-driven replacement cycles for refrigerated platforms serving pharmaceutical cold chains.
- Aluminum-intensive designs:Regional smelter capacity expansion is enabling tare weight reduction that translates directly to payload revenue recovery across high-frequency Saudi Arabia-UAE corridor routes.
Market Restraints
- Specialized welding certification scarcity:Tanker trailer production faces hazardous materials compliance overhead that limits qualified fabrication capacity for petroleum and chemical transport segments.
- Cross-border registration friction:Dubai's RTA and Saudi Arabia's General Authority for Transport maintain overlapping but distinct commercial vehicle protocols that complicate trailer interoperability specifications.
- Steel price volatility:Traditional chassis material costs fluctuate against aluminum alloy pricing, complicating fleet manager total-cost-of-ownership calculations for long-haul desert operating conditions.
Strategic Opportunities
- Oman logistics corridor development:Underpenetrated port-linked distribution infrastructure between Sohar and Duqm offers first-mover positioning for temperature-controlled platform operators.
- GSO electrification readiness standards:Evolving carbon intensity benchmarking for trailer manufacturing will cascade into procurement criteria as Gulf states advance national decarbonization commitments.
- Telematics-chassis integration:Sensor-enabled fleet management systems are converging with lightweight composite structures to enable real-time cargo monitoring across Kuwait-Bahrain feeder routes.
Industry Challenges
- Axle load inspection regime fragmentation:National transport authorities in each GCC member state enforce distinct periodic inspection timelines that complicate unified fleet management across Saudi Arabia-UAE-Kuwait operations.
- Composite repair technician shortage:Lightweight material damage assessment and field repair capabilities lag behind Wabash National-style composite technology deployment across long-haul desert routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Trailer Market |
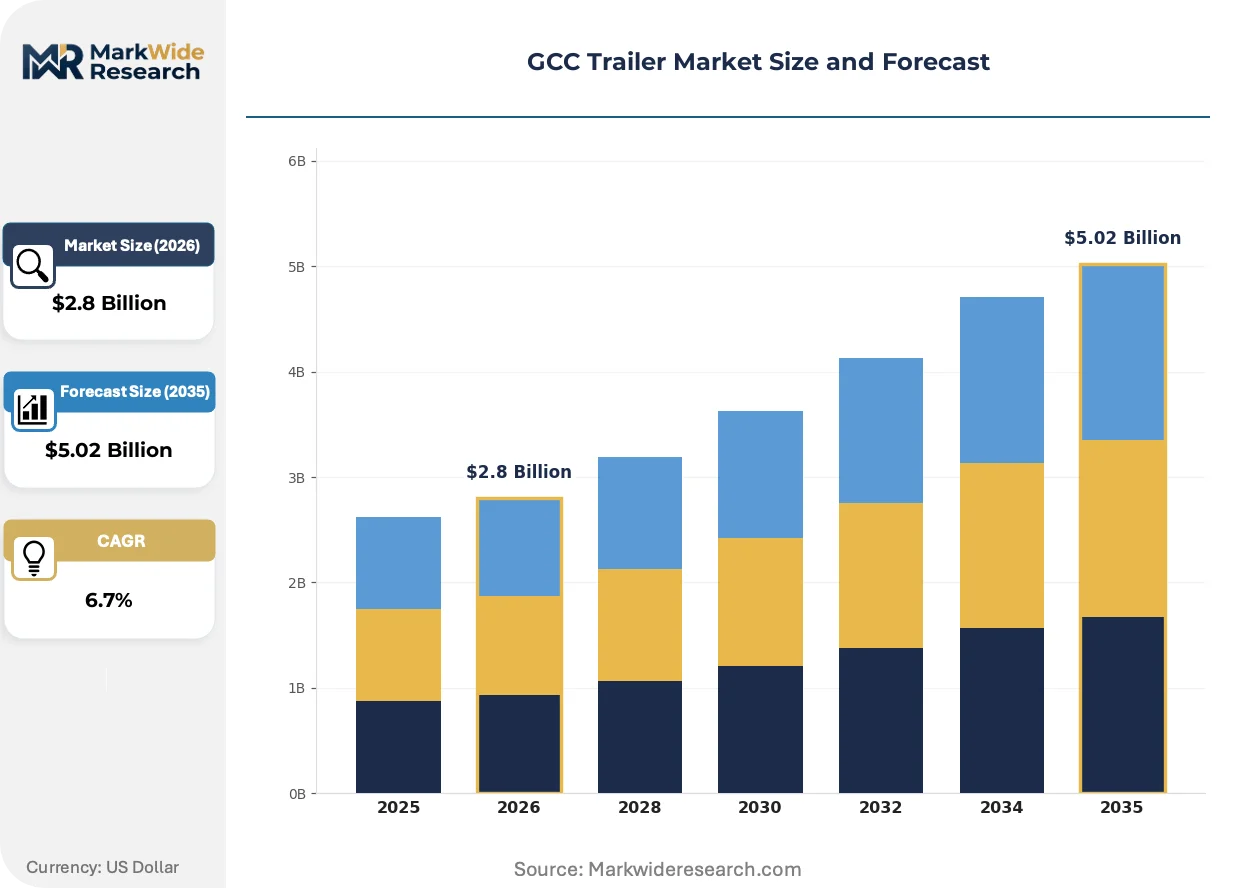
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flatbed, Lowboy, Step Deck, Tanker Material: Steel, Aluminum, Composite, Fiberglass Application: Construction, Logistics, Agriculture, Waste Management End User: Transport Companies, Contractors, Retailers, Government Agencies |
| Companies Covered | Schmitz Cargobull AG, Fahrzeugwerk Bernard Krone, China International Marine Containers, Wabash National, Utility Trailer Manufacturing Company, Great Dane, Hyundai Translead, CIMC Vehicles, Kogel, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Trailer Market Trends and Innovations
Active telematics integration and aluminum alloy substitution are restructuring trailer specification priorities across GCC logistics fleets, while regulatory pressure on carbon intensity accelerates material selection decisions.
Aluminum-intensive chassis construction is converging with corrosion-resistant coating systems to extend service intervals in desert operating conditions. Saudi Arabia's Eastern Province fleet operators are adopting these specifications at accelerated pace for pharmaceutical and food logistics chains. The technology is converging with payload optimization software to compress total-cost-of-ownership advantages against traditional steel platforms.
Gulf Standardization Organization electrification readiness standards are mandating wiring harness and power distribution architectures compatible with future tractor electrification. Trailer manufacturers must now engineer modular electrical systems that anticipate regional decarbonization commitments. Temperature-controlled platforms serving UAE pharmaceutical distribution networks face the most immediate compliance redesign cycles.
Logistics operators are consolidating procurement decisions at the fleet level rather than delegating to individual route managers. This concentration is displacing fragmented spot-market trailer acquisition across Dubai's Jebel Ali corridor. Saudi Arabia's domestic production capacity is capturing expanded share of this consolidated demand through direct manufacturer-fleet partnerships.
GCC Trailer Market Segmentation
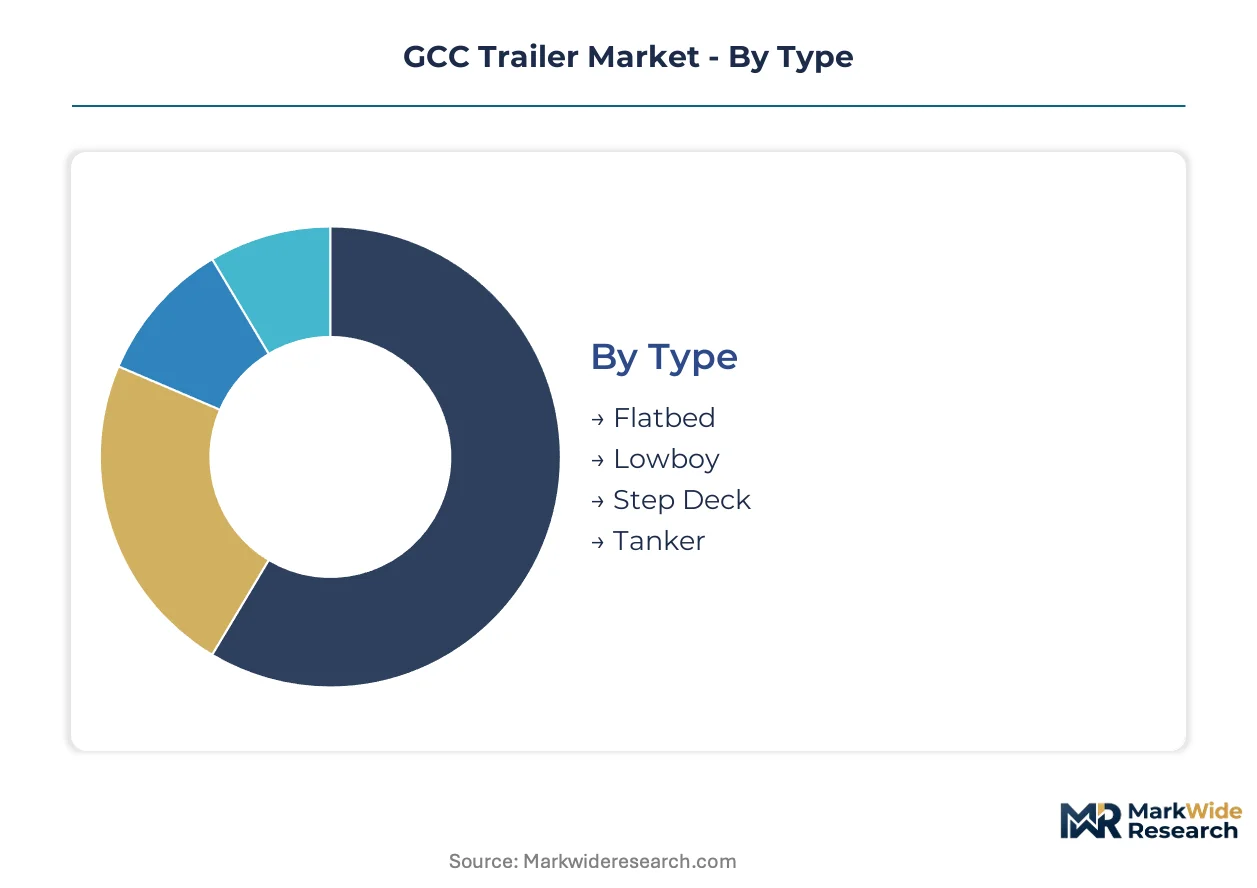
Trailer procurement decisions across Saudi Arabia and the UAE hinge on material certification, axle load compliance, and end-use operating conditions. Fleet managers weight total-cost-of-ownership calculations differently across construction, logistics, and temperature-controlled applications, driving specification divergence that shapes manufacturer product portfolios.
Type:
GSO brake performance and coupling standards impose distinct certification burdens across trailer configurations, with hazardous materials transport requiring specialized welding protocols beyond standard commercial vehicle registration.
- Flatbed:Open-deck platforms with steel or aluminum flooring support dimensional flexibility for construction machinery and project cargo. Demand concentrates in Dubai's Jebel Ali corridor where port-linked distribution infrastructure commands corrosion-resistant specifications for desert operating conditions.
- Lowboy:Drop-deck designs with minimal ground clearance accommodate heavy equipment transport requiring permit-escorted movements. Saudi Arabia's Eastern Province fleet operators are expanding procurement for oilfield services and infrastructure project logistics where axle load distribution determines route eligibility.
- Step Deck:Dual-level platforms combine lower deck height with upper deck length for mixed freight profiles. GSO harmonization of dimensional regulations is standardizing cross-border interoperability specifications.
- Tanker:Cylindrical vessels with hazardous materials compliance overhead serve petroleum and chemical transport segments. Specialized welding certification scarcity limits qualified fabrication capacity across GCC member states.
Leading the category by volume: Flatbed. Expanding most quickly: Tanker.
Material:
Regional smelter capacity expansion is rebalancing material cost structures, with aluminum alloy pricing displacing traditional steel dominance in long-haul fleet calculations.
- Steel:Conventional chassis construction dominates entry-level procurement where initial acquisition cost outweighs fuel consumption penalties. Price volatility against aluminum complicates fleet manager lifecycle calculations.
- Aluminum:Alloy-intensive designs reduce tare weight to enable payload revenue recovery across high-frequency Saudi Arabia-UAE corridor routes. Saudi Arabia's domestic production capacity is shifting toward aluminum-intensive designs as regional smelters expand supply.
- Composite:Lightweight structures from Wabash National-style manufacturers reduce fuel consumption across long-haul desert routes. Composite repair technician shortage limits field service capabilities.
- Fiberglass:Corrosion-resistant paneling extends service intervals in temperature-controlled applications. Pharmaceutical cold chain operators in the UAE specify fiberglass-reinforced enclosures for humidity resistance.
Dominant by fleet share: Steel. Gaining adoption fastest: Aluminum.
Application:
End-use operating cycles determine maintenance interval economics, with construction applications demanding reinforced suspension systems absent from line-haul logistics specifications.
- Construction:Heavy-duty configurations with reinforced chassis serve project cargo and equipment transport. Dubai's infrastructure development pipeline is sustaining flatbed and lowboy procurement.
- Logistics:E-commerce fulfillment networks across Saudi Arabia and the UAE are expanding refrigerated and dry van trailer fleets. Temperature-controlled platforms face immediate compliance redesign cycles under evolving GSO standards.
- Agriculture:Livestock and bulk commodity transport requires ventilation and washdown specifications. Kuwait-Bahrain feeder routes sustain specialized livestock trailer demand.
- Waste Management:Roll-off and hook-lift containers serve municipal and industrial collection contracts. Government procurement protocols favor domestic assembly content.
Highest equipment utilization: Logistics. Steepest specification upgrade cycle: Construction.
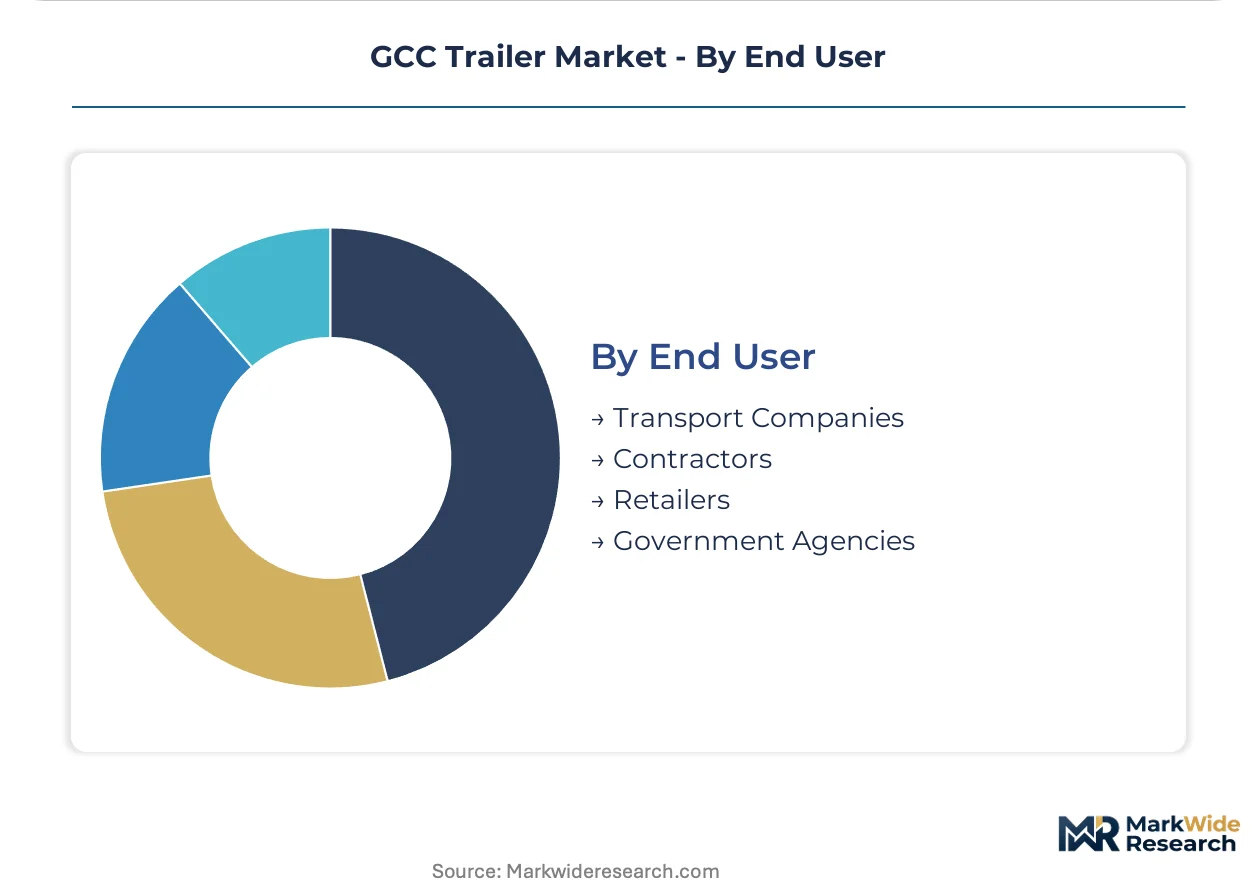
End User:
Fleet scale determines procurement centralization, with large transport companies consolidating manufacturer-direct relationships while contractors rely on dealer networks for spot acquisitions.
- Transport Companies:Fleet-level procurement decisions are displacing fragmented spot-market acquisition across consolidated logistics operators. Direct manufacturer partnerships capture volume pricing and specification customization.
- Contractors:Project-based trailer requirements favor short-term leasing and used equipment markets. Equipment utilization rates vary with construction cycle timing.
- Retailers:Private fleet operations for last-mile distribution specify lightweight configurations for urban delivery efficiency. Cold chain compliance drives refrigerated platform investment.
- Government Agencies:Municipal and infrastructure authority procurement follows domestic content requirements and extended warranty terms. Inspection regime compliance shapes replacement timing.
Concentrating procurement authority: Transport Companies. Fastest fleet modernization: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelter capacity in the Arabian Peninsula anchors GCC trailer production economics, with alloy supply proximity reshaping fleet procurement patterns across Saudi Arabia, the UAE, Kuwait, Qatar, and Oman.
Saudi Arabia
Eastern Province logistics clusters drive refrigerated and flatbed trailer demand for port-linked distribution serving pharmaceutical cold chains. The General Authority for Transport enforces axle load limits and periodic inspection regimes that compress fleet replacement cycles. Dammam and Jubail industrial zones concentrate domestic aluminum-intensive chassis fabrication as regional smelters expand alloy supply.
United Arab Emirates
Dubai's Jebel Ali corridor commands premium trailer specifications for e-commerce fulfillment networks and construction project cargo. The Roads and Transport Authority maintains commercial vehicle registration protocols that shape cross-border interoperability with Saudi fleets. Abu Dhabi's Khalifa Port logistics zone is expanding temperature-controlled platform procurement for food and pharmaceutical distribution.
Kuwait
Feeder route operations between Kuwait City and Bahrain sustain specialized livestock and dry van trailer demand for agriculture and logistics applications. The country's national transport authority implements GSO brake performance standards with distinct inspection timelines. Shuwaikh Port industrial areas concentrate fleet maintenance capabilities for cross-border Saudi Arabia-UAE corridor operations.
Qatar
Construction and infrastructure project logistics drive lowboy and flatbed trailer procurement for heavy equipment transport requiring permit-escorted movements. The Ministry of Transport enforces GSO harmonized vehicle safety codes for commercial fleet registration. Ras Laffan industrial zone generates tanker trailer demand for petroleum and chemical transport segments with hazardous materials compliance requirements.
Oman
Underpenetrated port-linked distribution infrastructure between Sohar and Duqm offers expansion opportunities for temperature-controlled platform operators. The Ministry of Transport aligns with GSO electrification readiness standards for future tractor compatibility. Sohar Port freezone is developing logistics capabilities to capture transshipment traffic from Saudi Arabia-UAE corridor routes.
GCC Trailer Market Competitive Landscape
Global majors compete with regional champions across material technology and compliance engineering, creating a tiered structure where European engineering subsidiaries anchor premium specifications while domestic fabricators capture volume procurement. The vendor base separates into three archetypes: alloy-intensive chassis specialists, temperature-controlled platform engineers, and composite lightweighting innovators. Consolidation pressures favor direct manufacturer-fleet partnerships over fragmented dealer networks. Capacity expansion and specification customization represent the dominant competitive moves.
Within the European engineering tier, Schmitz Cargobull AG and Fahrzeugwerk Bernard Krone occupy positions exemplifying corrosion-resistant and temperature-controlled platform specialization for desert operating conditions. Wabash National represents the composite lightweighting archetype, with its technology profile aligning with fuel consumption reduction priorities across long-haul routes. These three anchors illustrate how competitive positioning stratifies across material science capabilities rather than geographic coverage alone.
| Leading Market Players |
|---|
| Schmitz Cargobull AG |
| Fahrzeugwerk Bernard Krone |
| China International Marine Containers |
| Wabash National |
| Utility Trailer Manufacturing Company |
| Great Dane |
| Hyundai Translead |
| CIMC Vehicles |
| Kogel |
| Others |
Pricing and Supply Chain Analysis
Aluminum alloy substitution in chassis fabrication is compressing cost differentials between regional and imported trailers while concentrating procurement leverage with fleet operators in Saudi Arabia's Eastern Province. This production-method transition simultaneously reduces fuel consumption penalties and rewards manufacturers with captive smelter access.
Pricing Analysis
Extended warranty and field-service bundling separate premium European engineering subsidiaries from unbundled domestic fabricators competing on acquisition cost alone. Three-tier pricing structure across premium corrosion-resistant specifications, standard GSO-compliant platforms, and economy-grade steel chassis reflects certification grade and after-sales coverage depth. Cost compression in the economy tier is intensifying because regional smelter expansion is narrowing aluminum-steel cost gaps. Contractor segments exhibit highest price sensitivity due to project-based utilization, while consolidated transport companies prioritize total-cost-of-ownership metrics over upfront expenditure.
Supply Chain Analysis
Direct-to-fleet channels handle consolidated logistics operator demand while dealer networks serve fragmented contractor spot procurement across Dubai's Jebel Ali corridor. Manufacturing draws from Saudi Arabia, the UAE, and Germany for chassis fabrication, axle assemblies, and braking systems respectively. Raw material flows rest on aluminum alloy billet, high-tensile steel coil, and composite panel feedstock. Single-source vulnerability concentrates in specialized welding certification capacity for tanker trailer production. Distribution runs through manufacturer-direct partnerships for volume fleets and regional dealer infrastructure for project-based buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as alloy supply proximity determines margin capture, with upstream smelter partnerships and downstream fleet service contracts representing the critical levers players are pursuing.
For Market Incumbents: Deepen captive aluminum alloy supply arrangements with Saudi Arabian smelter expansions to defend against Chinese import price pressure. Consolidate field service networks across the Saudi Arabia-UAE corridor to capture aftermarket revenue and lock in fleet replacement cycles. Certification investment in GSO electrification readiness standards will differentiate specifications before compliance mandates harden. For New Entrants and Emerging Players: Telematics-integrated lightweight chassis technology offers entry into temperature-controlled platform segments where pharmaceutical cold chain compliance creates specification stickiness. Oman's underpenetrated Sohar-Duqm corridor presents the most penetrable geography for first-mover fleet partnerships. Go-to-market positioning should emphasize modular electrical architectures compatible with evolving tractor electrification standards. For Investors and Strategic Acquirers: Re-rating potential sits with composite lightweighting specialists given fuel consumption reduction mandates across long-haul desert routes. Long-term viability favors manufacturers with backward integration into aluminum processing and forward integration into fleet telematics platforms. Watch GSO carbon intensity benchmarking announcements as the inflection signal for procurement criteria shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Smelter Partnership Integration | Captive aluminum alloy supply from Saudi Arabian smelters locks in material cost advantages against steel volatility. |
| Telematics Platform Deployment | Sensor-enabled cargo monitoring converges with GSO electrification standards for pharmaceutical fleet compliance. |
| Field Service Network Expansion | Direct technician coverage across the Eastern Province-Jebel Ali corridor captures aftermarket revenue from consolidated fleets. |
| Composite Repair Certification | Wabash National-style lightweight structure deployment requires technician training investment to overcome service capability gaps. |
| GSO Compliance Pre-Certification | Early brake performance and coupling standard alignment accelerates fleet replacement cycle capture before competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fleet procurement directors, trailer manufacturer engineering leads, GSO technical committee members, and smelter sales executives provided operational validation. Secondary sources included Gulf Standardization Organization technical regulations, Saudi General Authority for Transport inspection protocols, UAE Roads and Transport Authority registration databases, and aluminum alloy pricing indices. Bottom-up trailer procurement surveys across Saudi Arabia and the UAE triangulated against top-down regional logistics fleet capacity estimates.
Segment-level granularity modeled trailer type, material composition, application end-use, and fleet scale across the projection horizon. Type segmentation captured flatbed, lowboy, step deck, and tanker configurations with distinct GSO certification burdens. Material analysis tracked steel, aluminum, composite, and fiberglass adoption curves against regional smelter capacity expansion. CAGRs derived from fleet replacement timing, e-commerce fulfillment network buildouts, and cross-border corridor traffic growth assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to Saudi Arabia-UAE corridor trade flows, abrupt GSO regulatory timeline acceleration, and steel-aluminum price inversion scenarios. Forecasts reflect assumptions about smelter capacity commissioning schedules and fleet consolidation trajectories. Periodic stress-testing of base assumptions is recommended against carbon intensity benchmark announcements and electrification readiness standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Intralogistics Containers Market