
 Hong Kong Freight and Logistics Market | 2026-2036
Hong Kong Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Freight and Logistics Market Foresight
Modular service bundling is decoupling across Hong Kong's logistics sector, with buyers unbundling end-to-end contracts into standalone warehousing, forwarding, and last-mile components. Kerry Logistics Network leverages its Greater Bay Area depot footprint to sustain multi-modal contract wins. SITC International Holdings Company anchors intra-Asia ocean feeder capacity through dedicated regional vessel networks. Janco Holdings Limited competes in niche project cargo segments where specialized handling commands premium positioning.
Hong Kong freight and logistics encompasses the planning, execution, and control of goods movement via air, sea, road, and rail modes through one of Asia's busiest container transshipment hubs, handling over 18 million TEU annually across Kwai Tsing container terminals. The primary commercial purpose centers on reducing inventory carrying costs and transit times for manufacturers and retailers sourcing from or distributing into mainland China. Air freight and ocean freight delivery modes absorb the dominant share of cross-border value, with air cargo premium margins concentrated in pharmaceutical and electronics verticals requiring temperature-controlled chain integrity. Warehousing services are expanding fastest among service types, driven by bonded storage demand and e-commerce inventory pre-positioning near Shenzhen border crossings.
Hong Kong's Customs and Excise Department enforces the Trade Single Window initiative, compressing documentary clearance timelines and shaping freight forwarder technology investments in automated declaration systems. The Civil Aviation Department coordinates slot allocation and security protocols at Hong Kong International Airport, directly influencing air cargo carrier network planning and perishables handling certification requirements. Stakeholders must monitor Greater Bay Area infrastructure integration timelines, as port and bridge capacity expansions in Shenzhen and Zhuhai reroute cargo flows and redefine Hong Kong's transshipment value proposition.
Market Dynamics
Modular service unbundling is fragmenting Hong Kong's logistics value chain, with shippers decoupling warehousing, customs brokerage, and last-mile delivery into separately contracted components. The Greater Bay Area's manufacturing corridor generates cross-border volume that demands specialized handling capabilities and bonded facility proximity.
Growth Catalysts
- Trade Single Window:Hong Kong's Customs and Excise Department initiative compresses documentary clearance timelines, forcing freight forwarders to automate declaration systems and reduce manual processing overhead.
- Pharmaceutical cold chain:Temperature-controlled air cargo for biologics and vaccines commands premium handling fees, driving investment in certified perishables infrastructure at Hong Kong International Airport.
- Shenzhen-Dongguan manufacturing belt:Electronics and medical device production clusters generate continuous demand for just-in-time inventory positioning and bonded warehousing near border crossings.
Market Restraints
- Land scarcity:Limited industrial zone availability in Hong Kong proper elevates warehouse rental costs above regional competitors in Dongguan and Zhuhai.
- Feeder vessel concentration:Intra-Asia ocean capacity relies on a narrow base of regional operators, creating vulnerability during port congestion or vessel redeployment cycles.
- Cross-border regulatory friction:Divergent customs protocols between Hong Kong and mainland China generate documentation complexity and unpredictable clearance timelines.
Strategic Opportunities
- Zhuhai corridor expansion:The Hong Kong-Zhuhai-Macau Bridge unlocks direct road freight routing to western Pearl River Delta manufacturing zones previously served only by sea.
- E-commerce fulfillment densification:Bonded warehouse networks near Shenzhen border checkpoints enable same-day delivery into mainland consumer markets without full import clearance.
- Dual-carbon policy alignment:Hong Kong's commitment to carbon neutrality by 2050 creates demand for electric last-mile fleets and renewable-powered cold storage facilities.
Industry Challenges
- Customs automation talent gap:Shortage of specialists capable of integrating Trade Single Window APIs with legacy enterprise resource planning systems delays compliance upgrades.
- Multi-modal coordination complexity:Synchronizing sea-air transshipment schedules requires real-time data exchange between terminal operators, carriers, and forwarders with incompatible IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Freight and Logistics Market |
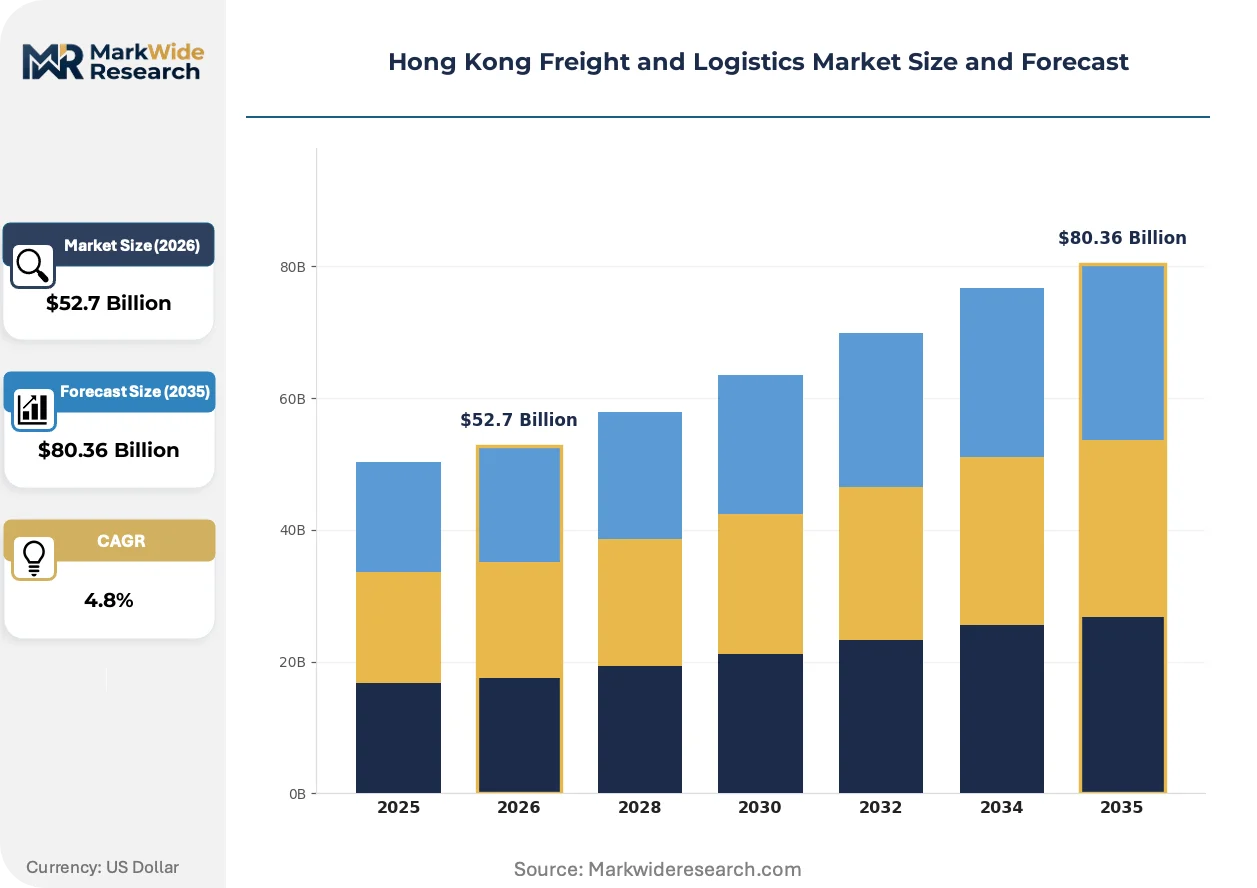
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Delivery Mode: Air Freight, Ocean Freight, Road Transportation, Rail Transport Customer Type: Manufacturers, Retailers, E-commerce, Wholesalers Technology: Supply Chain Management, Tracking Systems, Automation, IoT Solutions |
| Companies Covered | Guangdong Yueyun Transportation Company, Janco Holdings Limited, SITC International Holdings Company, SEKO Global Logistics, Sinotrans Limited, Kerry Logistics Network, CN Logistics International Holdings, Crane Worldwide Logistics, Kuehne+Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Freight and Logistics Market Shifts & Advancements
Digital freight platforms and automated warehouse systems are compressing coordination costs across Hong Kong's logistics networks. Operational technology investments now prioritize real-time visibility over physical asset expansion.
Autonomous mobile robots are integrating into e-commerce fulfillment centers at Kwai Chung and Tsing Yi. Third-party logistics operators deploy these systems to reduce picking labor dependency during peak seasonal volumes. The technology is integrating warehouse management systems with robotic fleet orchestration, collapsing order cycle times from hours to minutes.
Hong Kong's Customs and Excise Department mandates phased adoption of the Trade Single Window for all cargo declarations. This regulatory push compels forwarders to retire paper-based processes and migrate to structured data exchange protocols. Air cargo handlers face the tightest compliance deadlines, with perishables and pharmaceuticals segments requiring validated system integrations by regulatory cutoffs.
Shippers are consolidating vendor relationships around integrated service providers capable of spanning warehousing, customs brokerage, and final delivery. This procurement concentration displaces fragmented forwarder networks in favor of operators with owned assets across the Greater Bay Area. Electronics manufacturers with just-in-time supply chains demonstrate the most aggressive consolidation behavior, seeking single-accountability partners for cross-border movements.
Hong Kong Freight and Logistics Market Segmentation
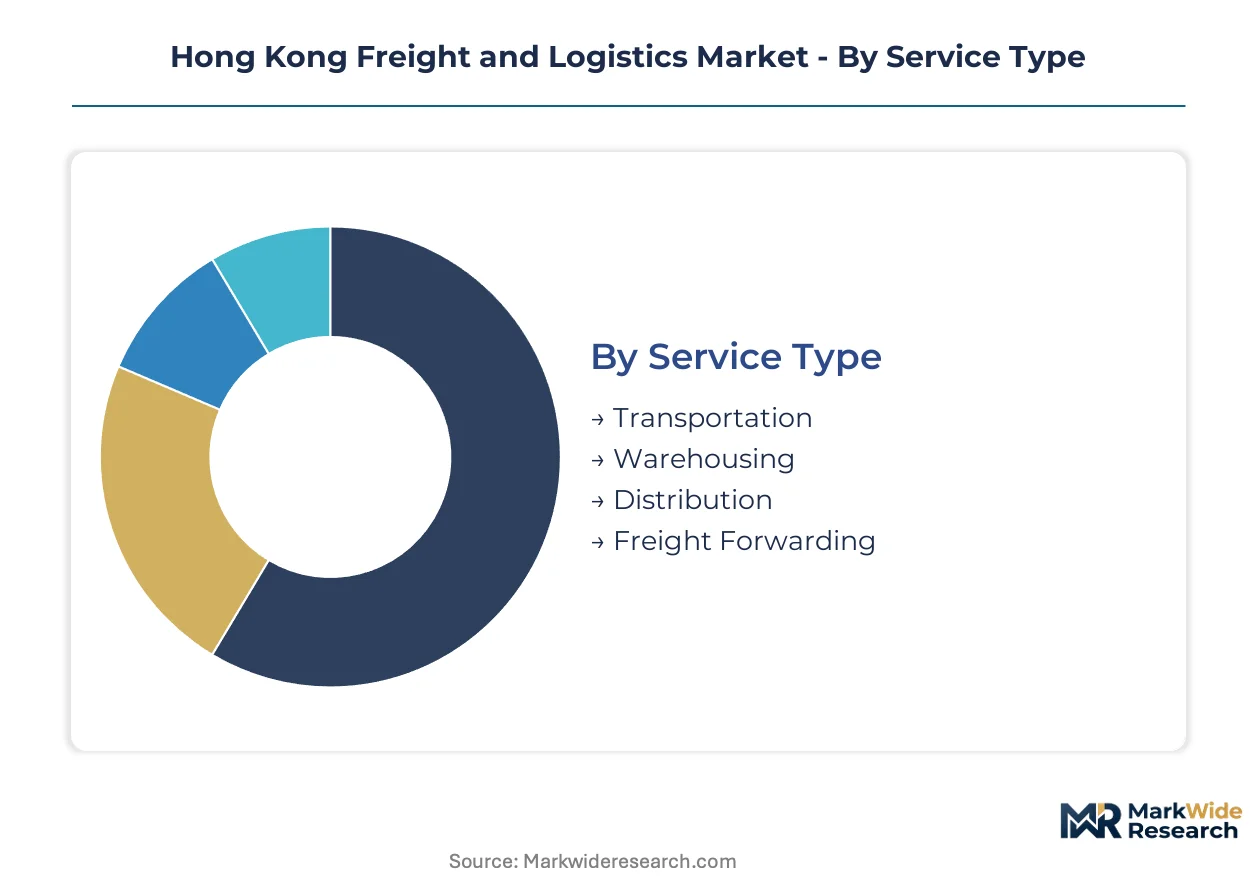
Segmentation in Hong Kong's logistics market reveals how capital deployment, regulatory exposure, and technology intensity vary across service lines. Buyers select segments based on cargo value density, customs complexity, and speed-to-market requirements.
Service Type:
Capital intensity varies sharply across these segments, with fixed asset requirements determining barrier-to-entry and margin structure.
- Transportation:Fleet ownership and driver certification dominate upfront costs. Container drayage between Kwai Tsing terminals and Shenzhen border crossings absorbs the highest vehicle deployment, with demand concentrated among electronics manufacturers requiring just-in-time delivery to Dongguan assembly plants.
- Warehousing:Land scarcity in Hong Kong proper drives facility investment toward automated high-bay structures. Bonded storage near Lok Ma Chau and Man Kam To border checkpoints commands premium rates from e-commerce platforms pre-positioning inventory for mainland same-day delivery.
- Distribution:Network density determines competitive position. Last-mile operators serving Hong Kong Island and Kowloon urban cores face route optimization challenges distinct from New Territories coverage.
- Freight Forwarding:Working capital intensity exceeds fixed asset needs. Customs brokerage licenses and Trade Single Window integration capabilities differentiate providers handling cross-border documentation complexity.
Transportation absorbs the bulk of installed capacity; warehousing is expanding most quickly.
Delivery Mode:
Cost tier separation shapes procurement decisions, with modal choice driven by cargo value-to-weight ratios and delivery urgency.
- Air Freight:Temperature-controlled pharmaceutical and electronics verticals command premium handling fees. Hong Kong International Airport's perishables certification requirements concentrate demand among biologics shippers requiring validated cold chain integrity.
- Ocean Freight:Intra-Asia feeder networks anchor volume throughput. Regional vessel operators serving the Greater Bay Area manufacturing corridor generate continuous demand for Kwai Tsing transshipment services.
- Road Transportation:Hong Kong-Zhuhai-Macau Bridge unlocks direct trucking to western Pearl River Delta zones previously served only by sea. Cross-border permit scarcity limits fleet expansion.
- Rail Transport:Guangzhou-Shenzhen-Hong Kong Express Rail Link cargo services remain underdeveloped relative to passenger volume. Infrastructure investment lags behind road and sea alternatives.
Ocean freight handles the greatest cargo volume; air freight captures the steepest margin expansion.
Customer Type:
Application complexity determines service bundling preferences, with supply chain sophistication varying by sector.
- Manufacturers:Electronics and medical device producers in the Shenzhen-Dongguan belt require synchronized inbound component flows and outbound finished goods distribution. Just-in-time inventory positioning demands bonded warehouse proximity to border crossings.
- E-commerce:Platform operators pre-position inventory in Hong Kong bonded facilities to enable mainland same-day delivery without full import clearance. Seasonal volume spikes drive automation investment in fulfillment centers.
- Retailers:Department store and specialty chains consolidate vendor relationships around integrated providers spanning warehousing and final delivery.
- Wholesalers:Traditional trading companies exhibit fragmented forwarder relationships, with procurement patterns shifting toward single-accountability partners.
Manufacturers represent the largest revenue base; e-commerce is climbing the fastest.
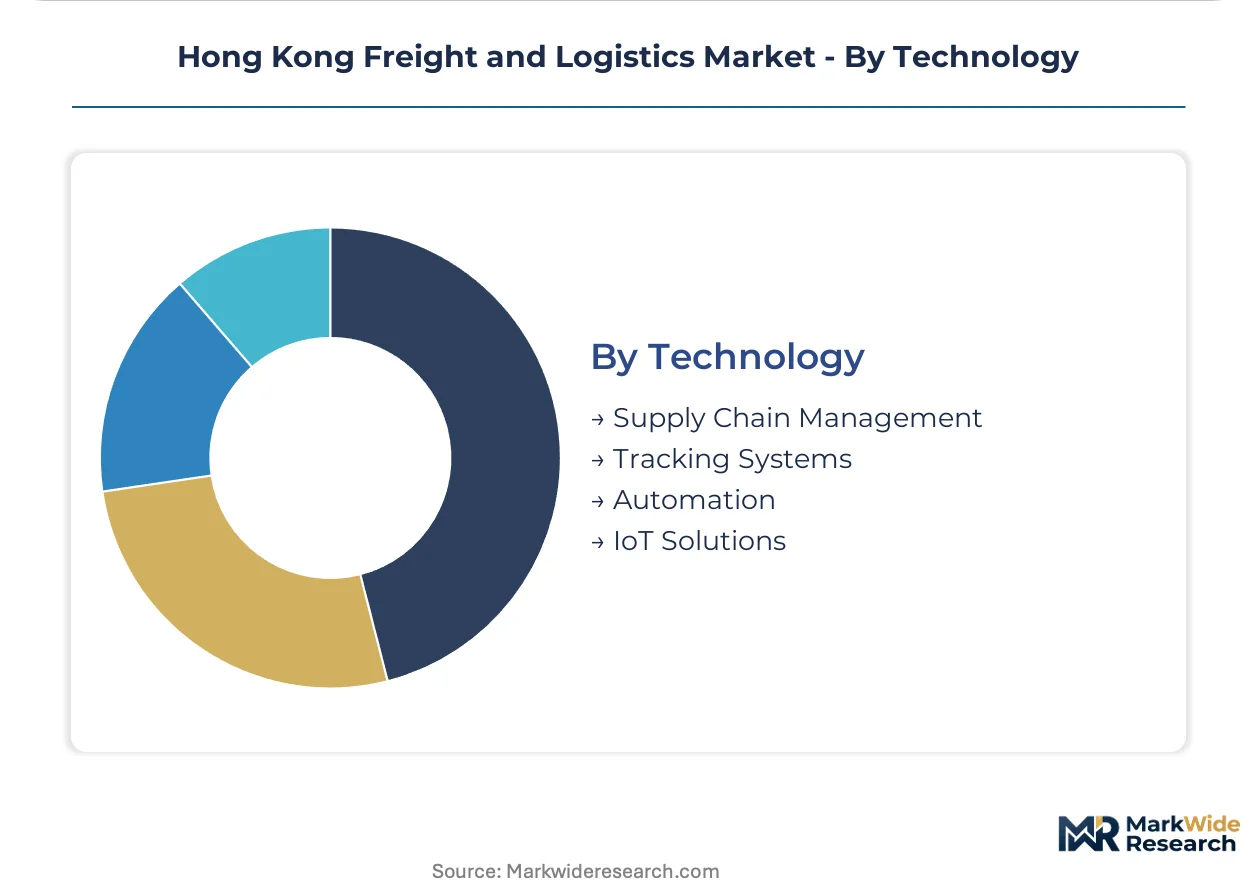
Technology:
Maturity gaps separate established systems from emerging platforms, with integration complexity determining adoption timelines.
- Supply Chain Management:Enterprise resource planning integration with Trade Single Window APIs requires specialized talent scarce in the Hong Kong market. Legacy system migration delays compliance upgrades for mid-sized forwarders.
- Automation:Autonomous mobile robots in Kwai Chung and Tsing Yi fulfillment centers reduce picking labor dependency. Warehouse management system integration collapses order cycle times from hours to minutes.
- Tracking Systems:Real-time visibility platforms coordinate multi-modal handoffs between sea-air transshipment schedules. Data exchange standardization remains incomplete across terminal operators and carriers.
- IoT Solutions:Cold chain monitoring for pharmaceutical cargo requires sensor deployment across handling points. Certification validation demands redundant system architecture.
Supply chain management commands the deepest installed base; automation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in mainland China's Pearl River Delta generate outbound cargo flows that Hong Kong transships, while consumption demand concentrates in Greater Bay Area cities. The region's logistics architecture responds to this manufacturing-to-market divide.
Shenzhen
Electronics manufacturers in Nanshan and Bao'an districts drive just-in-time component imports through Lok Ma Chau border crossings. China's Customs General Administration enforces Advanced Manifest filing rules that compress pre-arrival documentation windows. Yantian Port's deep-water berths handle ultra-large container vessels, diverting transshipment volume from Hong Kong's Kwai Tsing terminals.
Guangzhou
Automotive assembly plants in Panyu and Nansha districts require synchronized inbound parts flows from regional suppliers. The Guangdong Provincial Development and Reform Commission coordinates port capacity expansion across the Pearl River estuary. Nansha Free Trade Zone bonded warehouses enable duty-deferred manufacturing for export-oriented enterprises.
Dongguan
Medical device fabricators in Songshan Lake and Chang'an townships generate temperature-controlled air cargo demand for Hong Kong International Airport. China's National Medical Products Administration enforces Good Distribution Practice certification for cross-border pharmaceutical movements. Humen Port's barge connections feed containerized exports into Hong Kong's ocean freight networks.
Zhuhai
Appliance manufacturers in Xiangzhou and Jinwan districts access Hong Kong via the Hong Kong-Zhuhai-Macau Bridge truck corridors. The bridge's customs joint inspection facility compresses cross-border clearance timelines for road freight. Hengqin New Area bonded logistics parks attract e-commerce inventory pre-positioning for Macau and western Pearl River Delta delivery.
Macau
Hospitality supply chains and perishables imports generate niche air cargo demand handled through Hong Kong's transshipment infrastructure. Macau's Economic and Technological Development Bureau administers cross-border goods movement permits for the bridge corridor. Cotai Strip integrated resorts consolidate procurement through Hong Kong-based forwarders serving their just-in-time F&B and retail operations.
Hong Kong Freight and Logistics Market Competitive Landscape
The competitive structure tilts toward diversified regional networks with integrated asset ownership. Market concentration remains moderate, with distinct capability tiers separating global forwarders from Greater Bay Area specialists. Two archetypes dominate: multi-modal network operators controlling owned terminals and fleets, and niche project cargo handlers commanding premium positioning in specialized segments. Capacity expansion and customs technology integration represent the prevailing competitive moves across both tiers.
Among Greater Bay Area-integrated operators, Kerry Logistics Network and SITC International Holdings Company exemplify the asset-heavy archetype with depot and vessel networks anchoring regional contract positions. Janco Holdings Limited occupies a position within the specialized handling tier, where project cargo expertise commands differentiated pricing. SEKO Global Logistics and CN Logistics International Holdings sit within the forwarder tier, where customs brokerage capabilities and Trade Single Window integration determine competitive standing.
| Leading Market Players |
|---|
| Guangdong Yueyun Transportation Company |
| Janco Holdings Limited |
| SITC International Holdings Company |
| SEKO Global Logistics |
| Sinotrans Limited |
| Kerry Logistics Network |
| CN Logistics International Holdings |
| Crane Worldwide Logistics |
| Kuehne+Nagel |
| Others |
Supply & Pricing Matrix
Cross-border customs brokerage specialists concentrated in Hong Kong's Kwai Chung industrial zone command wage premiums that widen spreads between premium-certified and standard-tier logistics providers. Labor-cost differentials between Hong Kong-licensed operators and mainland China competitors translate directly into three-tier pricing structure across premium, standard, and economy levels for bonded warehousing and freight forwarding services.
Pricing Analysis
Margin tightening in standard-tier forwarding reflects automation-driven deskilling of customs declaration processing under Hong Kong's Trade Single Window mandate. Pricing stratifies across premium, standard, and economy tiers based on certification level (AEO-authorized economic operator status versus standard license) and volume scale (enterprise contract minimums versus spot-market transactions). Cost compression accelerates in economy tiers as digital freight platforms disintermediate traditional broker networks. Electronics manufacturers with just-in-time supply chains demonstrate lowest price sensitivity, while commodity traders exhibit highest elasticity.
Supply Chain Analysis
Certified cold-chain qualification gates air cargo handling at Hong Kong International Airport, concentrating pharmaceutical-grade logistics capacity among operators with GDP-compliant warehouse infrastructure. Supply anchors in China (Shenzhen-Dongguan manufacturing belt), Hong Kong (transshipment hub), and Vietnam (diversified electronics assembly). Raw material dependencies include bonded warehouse space, cross-border trucking permits, and refrigerated container equipment. Single-source vulnerability runs through feeder vessel operators serving intra-Asia routes. Distribution runs through multi-modal corridors connecting Kwai Tsing terminals to Greater Bay Area manufacturing zones via road, barge, and rail links.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's freight and logistics market functions as a cost-of-compliance arena where Hong Kong Customs and Excise Department's Trade Single Window mandates erect technology barriers that favor incumbent forwarders with automated declaration systems. This regulatory moat protects compliant players while accelerating displacement of paper-based operators.
For Market Incumbents: Acquire automated customs declaration technology assets to consolidate market share as Trade Single Window deadlines eliminate manual-process competitors. Integrate backward into bonded warehouse capacity near Lok Ma Chau and Man Kam To border checkpoints to capture e-commerce fulfillment demand. Defensive positioning requires real-time visibility platform investments that synchronize multi-modal handoffs against emerging digital freight platform threats.
For New Entrants and Emerging Players: API-first customs brokerage automation offers a technology-first wedge into mid-tier manufacturer segments underserved by legacy forwarders. White-space targets include pharmaceutical cold-chain logistics for Dongguan medical device exporters and Zhuhai corridor road freight optimization via Hong Kong-Zhuhai-Macau Bridge capacity. Go-to-market positioning should emphasize Trade Single Window compliance-as-a-service for mainland China logistics providers lacking Hong Kong regulatory expertise.
For Investors and Strategic Acquirers: Re-rating potential sits with Greater Bay Area-integrated operators possessing owned terminal and fleet assets given infrastructure consolidation catalysts. Long-term viability favors asset-heavy networks over pure-play forwarders as procurement concentration around single-accountability partners accelerates. Acquisition target archetype: mid-cap operators with AEO certification and automated warehouse infrastructure. Signal to watch: Shenzhen port capacity expansion timelines that redirect transshipment volume flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Trade Single Window Compliance Automation | Hong Kong Customs and Excise Department mandates eliminate manual-process competitors through structured data exchange requirements. |
| Bonded Warehouse Network Expansion | Facilities near Lok Ma Chau and Man Kam To border checkpoints capture e-commerce inventory pre-positioning demand from mainland platforms. |
| Pharmaceutical Cold Chain Certification | GDP-compliant infrastructure at Hong Kong International Airport secures biologics and vaccine handling contracts with premium margins. |
| Multi-Modal Corridor Integration | Synchronized sea-air-road coordination via Kwai Tsing terminals and Hong Kong-Zhuhai-Macau Bridge unlocks western Pearl River Delta access. |
| Autonomous Warehouse Robotics Deployment | AMR integration at Tsing Yi and Kwai Chung fulfillment centers collapses order cycle times during seasonal volume spikes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across freight forwarder operations managers, customs brokerage specialists, warehouse automation engineers, and Greater Bay Area manufacturing supply chain directors. Hong Kong Customs and Excise Department Trade Single Window documentation, Civil Aviation Department air cargo statistics, and Greater Bay Area port authority throughput disclosures supplied quantitative foundations. Bottom-up service-line sizing and top-down regional economic indicators underwent cross-validation to ensure consistency.
Granularity-level modeling operated at service-type, delivery-mode, and customer-segment dimensions across the projection horizon, with technology adoption curves and regulatory compliance timelines incorporated as exogenous variables. CAGRs derived from logistic growth curve fitting against historical throughput data and infrastructure capacity expansion schedules. Forecast inputs included Hong Kong-Zhuhai-Macau Bridge truck volume trajectories and Shenzhen port transshipment diversion scenarios.
Several conditions sit outside the modeled scope, including geopolitical disruptions to cross-border permit regimes, abrupt shifts in mainland China import duty structures, and pandemic-scale logistics network interruptions. Forecasts embed assumptions regarding continued Greater Bay Area economic integration and phased Trade Single Window enforcement timelines. A model refresh is warranted upon material change in Hong Kong-mainland China customs protocol harmonization or port capacity allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market