
 Government and Education Logistics Market | 2026-2036
Government and Education Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Government and Education Logistics Market Foresight
ISO-certified cold chain and tamper-evident handling standards are collapsing into baseline procurement requirements for federal contract logistics. Deutsche Post DHL Group leverages its European government postal heritage to anchor public-sector tender wins across continental capitals. FedEx competes through specialized document-security protocols for classified material transport. DSV sustains margin pools in project logistics for overseas defense education equipment.
Government and education logistics encompasses the planning, execution, and control of physical goods movement for public institutions, encompassing temperature-sensitive meal distribution, secure document transit, and time-critical textbook fulfillment with chain-of-custody documentation. Transportation services dominate contract value where fuel surcharge pass-through mechanisms protect carrier margins against volatility. Warehousing segments for government agencies exhibit fastest growth as FEMA and defense logistics agencies consolidate regional stockpiles under single-source managed service contracts. Inventory control solutions within the solution category mature slowly due to legacy ERP integration barriers in university procurement systems.
The Federal Acquisition Regulation shapes vendor qualification pathways through cost accounting standards and domestic sourcing preferences. EPA emissions mandates for heavy-duty fleets force carrier capital redeployment toward alternative fuel vehicles. OSHA workplace safety protocols govern warehouse staffing ratios in federally funded education supply depots. Stakeholders must monitor how procurement rule revisions alter small-business set-aside thresholds and bond requirements for contract participation.
Market Dynamics
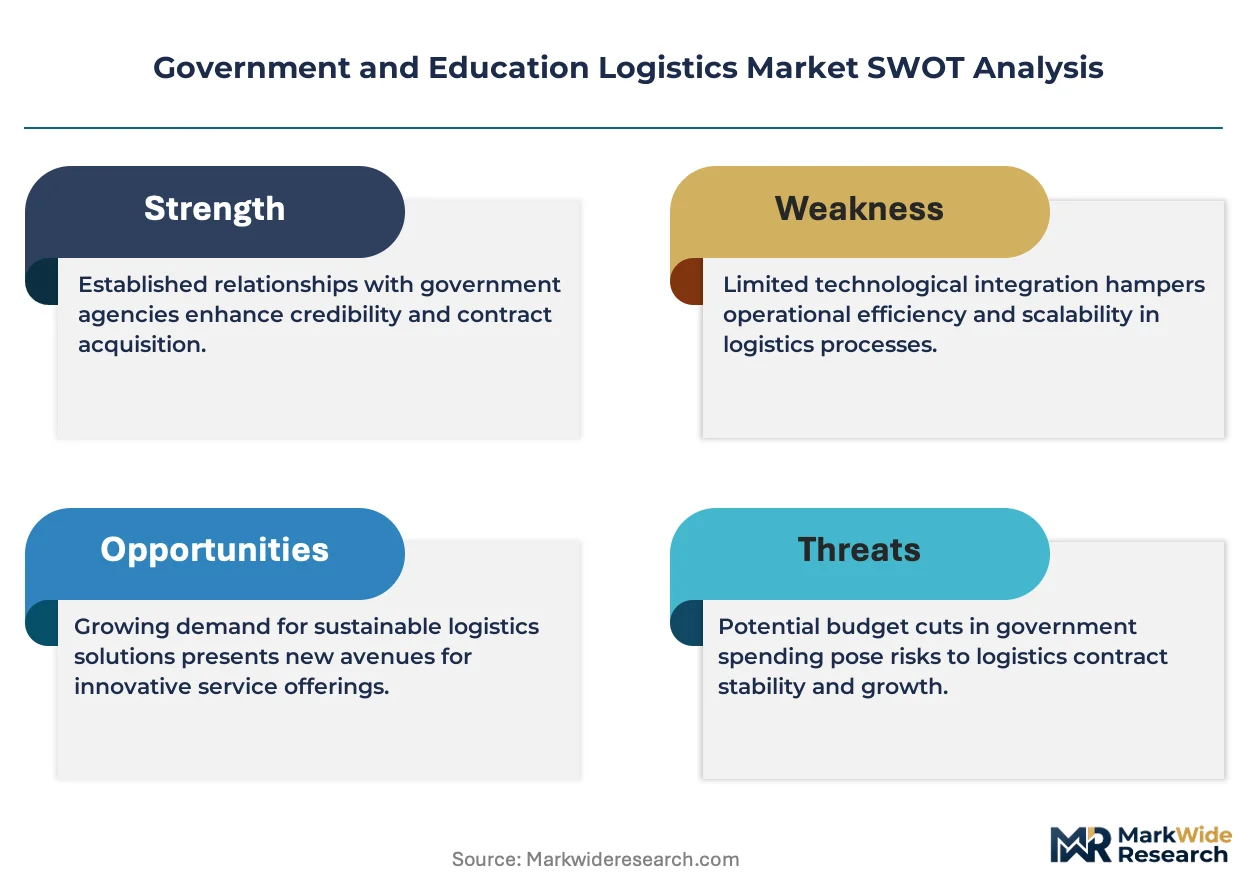
EPA fleet electrification mandates are forcing carriers to restructure capital deployment toward alternative fuel vehicles, while FEMA regional stockpile consolidation creates single-source contract concentration that reshapes vendor qualification pathways.
Growth Catalysts
- Clean School Bus Program:Federal electrification subsidies accelerate fleet turnover in California, Texas, and Florida school districts, generating procurement volume for zero-emission vehicle logistics infrastructure.
- FEMA Consolidation:Defense logistics agencies are merging regional warehousing operations under unified managed service contracts, expanding demand for integrated inventory control platforms.
- ISO Cold Chain Standards:Temperature-sensitive meal distribution mandates for K-12 nutrition programs are elevating tamper-evident handling protocols to baseline contract requirements.
Market Restraints
- Domestic Sourcing Preferences:Federal Acquisition Regulation cost accounting standards restrict vendor pools to US-incorporated carriers with certified cost submission capabilities.
- Legacy ERP Integration:University procurement systems exhibit slow solution adoption due to incompatible inventory control architectures.
- Fuel Surcharge Volatility:Transportation contract value remains exposed to diesel price swings despite pass-through mechanisms.
Strategic Opportunities
- Secure Document Transit:Classified material handling protocols present expansion vectors for carriers with federal security clearance infrastructure.
- Overseas Defense Education Equipment:Project logistics for international military training supply chains offers margin differentiation through specialized handling requirements.
- Centralized Distribution Centers:State education budget allocations in high-population jurisdictions fund purpose-built K-12 supply chain hubs.
Industry Challenges
- OSHA Warehouse Staffing Ratios:Federally funded education supply depots face operational complexity from mandated safety protocols governing labor deployment.
- Small-Business Set-Aside Thresholds:Procurement rule revisions alter bond requirements and participation eligibility, creating administrative burden for contract bidders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Government and Education Logistics Market |
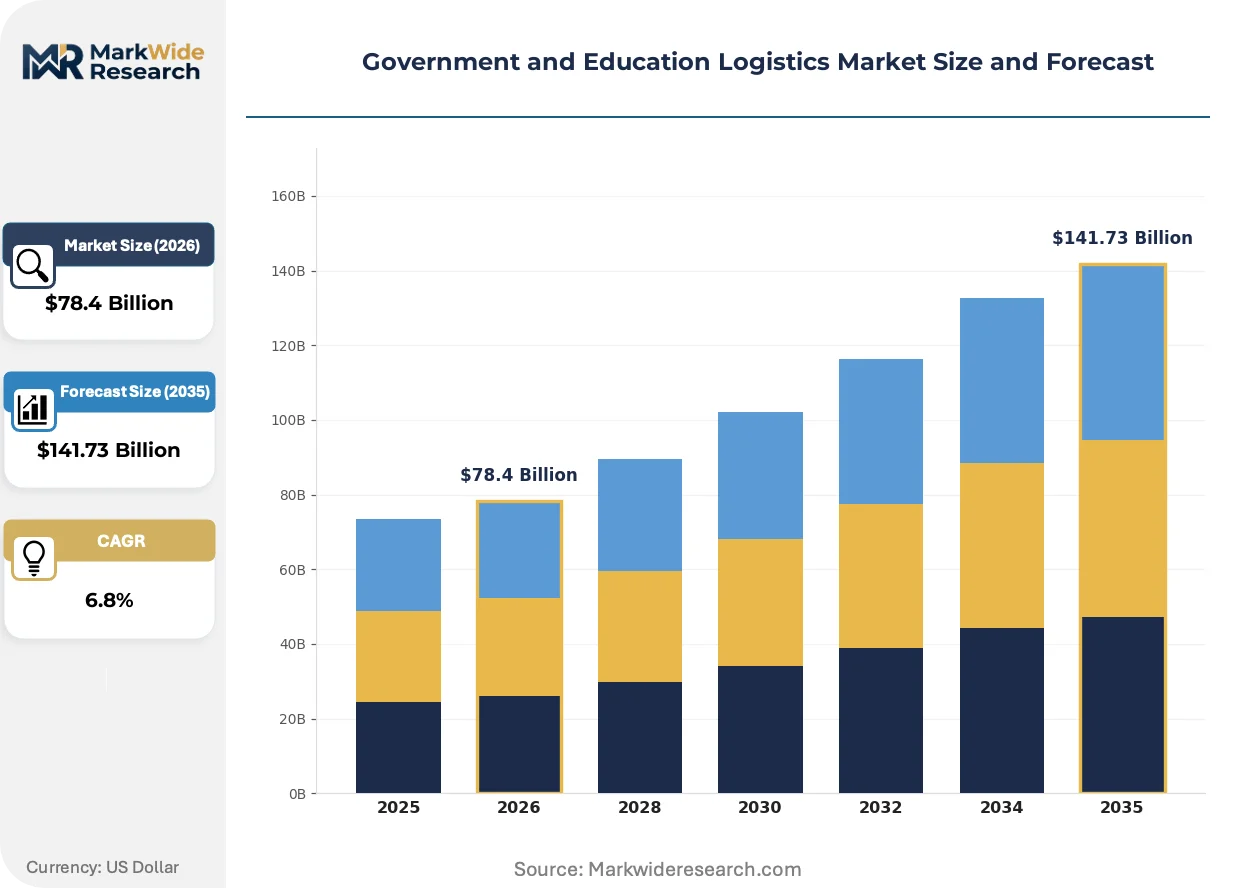
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Government Agencies, Universities, Nonprofits, Education Providers Solution: Supply Chain Management, Inventory Control, Logistics Analytics, Asset Tracking Delivery Model: On-Demand, Scheduled, Contract-Based, Managed Services |
| Companies Covered | Deutsche Post DHL Group, DSV, DB Schenker, UPS, FedEx, C.H. Robinson, SEKO Logistics, Agility, Scan Global Logistics A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Government and Education Logistics Market Shifts & Advancements
Electrification infrastructure and digital chain-of-custody systems are reconfiguring how public institutions validate, track, and fulfill physical goods movement across distributed supply networks.
Telematics-enabled fleet monitoring is bifurcating carrier competitive positioning between asset-heavy operators with captive charging infrastructure and asset-light brokers aggregating third-party electric capacity. California school districts with EPA grant funding are deploying these systems fastest. The technology is compressing contract renewal cycles as performance data becomes auditable in real time.
REACH chemical substance restrictions in Europe are extending to vehicle maintenance supply chains, forcing logistics providers to document cleaning agent compliance for cross-border equipment rotation. German defense education equipment exports now require full material disclosure. Continental carriers with European government postal heritage are adapting certification protocols fastest.
Performance-based contract structures are displacing fixed-rate transportation agreements in federal textbook fulfillment, with penalties tied to documented delivery windows and condition verification. State procurement offices in Texas and Florida are piloting these models. K-12 supply chain managers now prioritize carriers with integrated warehouse management systems over pure transport specialists.
Government and Education Logistics Market Segmentation
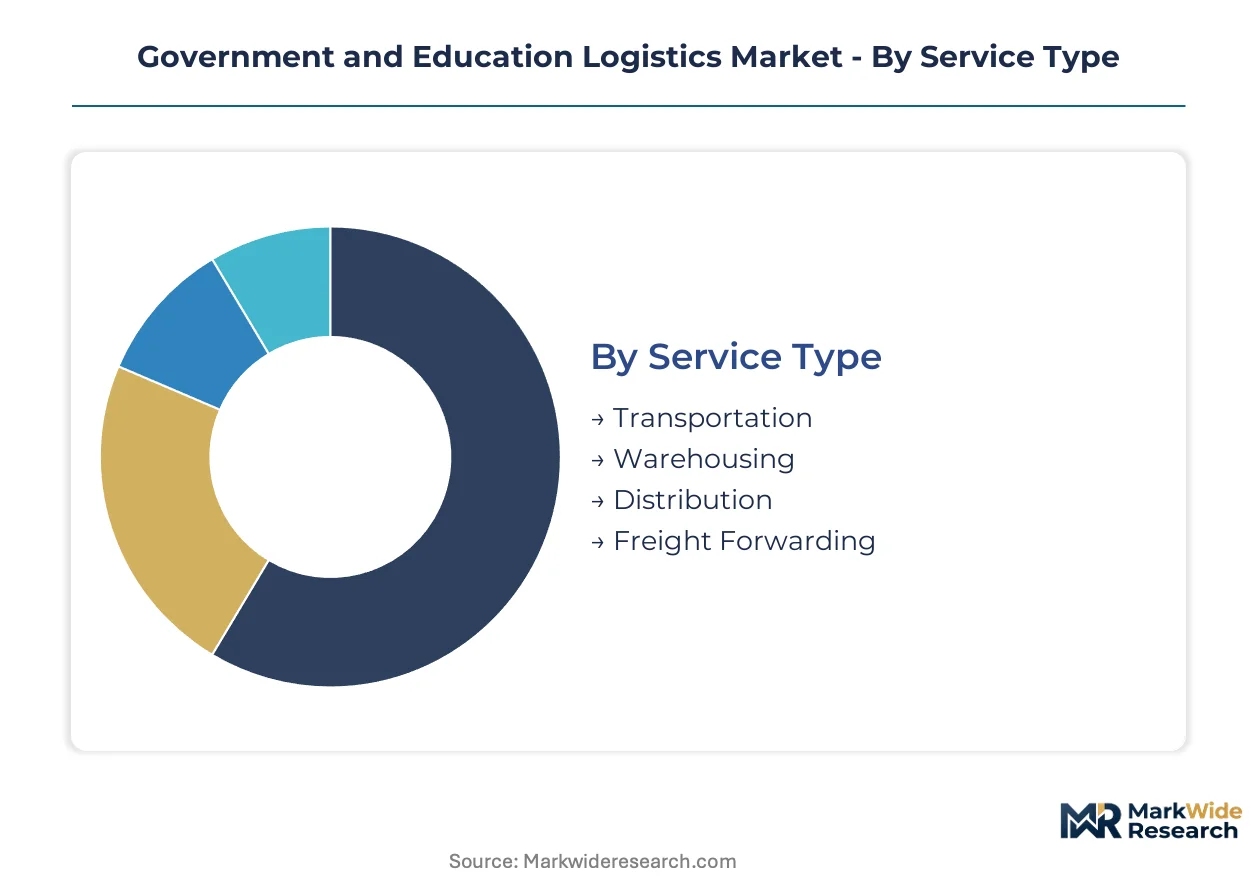
Segmentation in government and education logistics reveals how procurement channels, regulatory requirements, and institutional budgets reshape service delivery. Contract structures vary sharply between federal agencies with multi-year appropriations and school districts with annual funding cycles.
Service Type:
Transportation services flow through fuel-surcharge-protected contracts, while warehousing contracts consolidate under FEMA-managed regional hubs.
- Transportation:Heavy-duty fleet operations with EPA-mandated electrification timelines dominate contract value. California, Texas, and Florida school districts generate concentrated demand for zero-emission vehicle infrastructure as Clean School Bus Program subsidies accelerate procurement.
- Warehousing:Temperature-controlled facilities with OSHA-mandated staffing ratios serve federally funded education supply depots. FEMA regional stockpile consolidation is elevating single-source managed service contracts as the preferred procurement vehicle.
- Distribution:Last-mile networks for K-12 meal programs with ISO cold chain certification requirements.
- Freight Forwarding:Cross-border coordination for defense education equipment with REACH chemical disclosure mandates.
By volume, Transportation leads. By growth pace, Warehousing is expanding most quickly.
End User:
Cost tier separation distinguishes federal agencies with certified cost accounting capabilities from education providers with simpler procurement thresholds.
- Government Agencies:Defense logistics and FEMA operations with FAR-mandated domestic sourcing preferences. Federal security clearance infrastructure requirements restrict vendor pools to carriers with documented chain-of-custody protocols.
- Universities:Research material transport with legacy ERP integration barriers slowing inventory control adoption. Campus procurement systems exhibit fragmented vendor management across decentralized purchasing departments.
- Nonprofits:Grant-funded program logistics with restricted overhead allocation rules.
- Education Providers:K-12 textbook fulfillment with performance-based contract penalties tied to delivery window documentation.
By contract value, Government Agencies dominate. By procurement flexibility, Education Providers are climbing the fastest.
Solution:
Application maturity separates established supply chain platforms from emerging analytics tools with limited public-sector deployment.
- Supply Chain Management:Integrated platforms consolidating transportation, warehousing, and inventory functions. Federal agencies in California and Texas are piloting unified systems for textbook and meal program coordination.
- Inventory Control:Legacy ERP-dependent solutions facing slow adoption in university procurement architectures. Integration barriers with existing financial management systems delay deployment timelines.
- Logistics Analytics:Telematics-enabled fleet monitoring with real-time performance auditing capabilities.
- Asset Tracking:RFID and GPS-based chain-of-custody documentation for classified material handling.
By installed base, Supply Chain Management leads. By deployment velocity, Asset Tracking is gaining share fastest.
Delivery Model:
Margin structure differentiates asset-heavy operators with captive infrastructure from asset-light brokers aggregating third-party capacity.
- On-Demand:Emergency response logistics with premium pricing for unscheduled capacity. FEMA disaster relief operations generate intermittent demand spikes requiring surge-ready carrier networks.
- Scheduled:Recurring K-12 meal and textbook distribution with fixed-route optimization. State education budget allocations in high-population jurisdictions fund predictable delivery windows.
- Contract-Based:Multi-year federal agreements with cost accounting standard compliance requirements.
- Managed Services:Single-source responsibility for integrated warehousing and transportation operations.
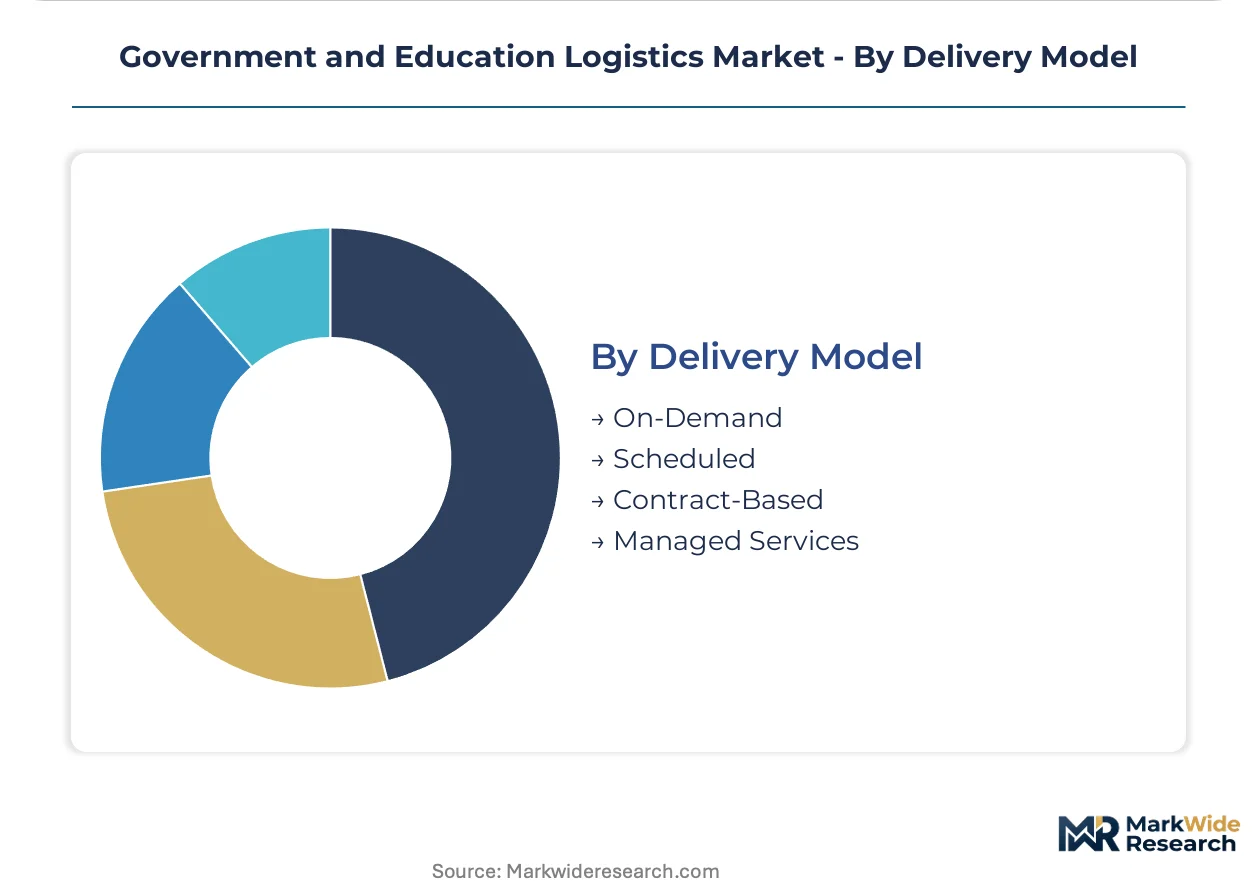
By revenue stability, Contract-Based leads. By margin expansion, Managed Services shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in government logistics equipment are reshaping regional procurement patterns. The United States runs a structural deficit in electric bus chassis, forcing school districts to source from specialized European and Asian suppliers. Defense education equipment flows from Germany and France toward Middle Eastern training facilities, while cold chain meal distribution systems concentrate in high-population federal markets.
United States
California, Texas, and Florida school districts generate concentrated demand for zero-emission vehicle infrastructure through EPA Clean School Bus Program subsidies. The Federal Acquisition Regulation mandates domestic sourcing preferences that restrict vendor pools to US-incorporated carriers with certified cost accounting capabilities. FEMA regional stockpile consolidation in Atlanta and Denver is elevating single-source managed service contracts for integrated warehousing operations.
Germany
Deutsche Post DHL Group leverages its government postal heritage to anchor public-sector tender wins across Berlin and continental capitals. REACH chemical substance restrictions extend to vehicle maintenance supply chains, forcing logistics providers to document cleaning agent compliance for cross-border equipment rotation. Bavaria-based defense education equipment exports now require full material disclosure under evolving ECHA protocols.
France
Secure document transit protocols for classified material handling present expansion vectors for carriers with federal security clearance infrastructure. The country's national defense procurement agency shapes vendor qualification pathways through cost accounting standards and domestic sourcing preferences. Logistics clusters around Paris and Lyon are adapting certification protocols fastest for overseas military training supply chains.
United Kingdom
Performance-based contract structures are displacing fixed-rate transportation agreements in federal textbook fulfillment, with penalties tied to documented delivery windows. State procurement offices are piloting these models across Greater London and the Midlands. K-12 supply chain managers now prioritize carriers with integrated warehouse management systems over pure transport specialists.
Japan
Telematics-enabled fleet monitoring is compressing contract renewal cycles as performance data becomes auditable in real time. METI standards govern warehouse staffing ratios in federally funded education supply depots. Logistics providers in the Tokyo-Osaka corridor are restructuring capital deployment toward alternative fuel vehicles under accelerating emissions mandates.
Government and Education Logistics Market Competitive Landscape
Listed leaders compete with private specialists across contract scale and security clearance depth. The vendor base organizes around three tiers: integrated parcel carriers with federal infrastructure, project logistics specialists in defense education equipment, and regional brokers aggregating third-party capacity. Two strategic archetypes dominate—asset-heavy operators with captive charging infrastructure and asset-light platforms optimizing electric vehicle networks. Competitive moves concentrate on securing multi-year FEMA managed service contracts and acquiring ISO-certified cold chain capabilities for K-12 meal programs.
Within the integrated carrier tier, Deutsche Post DHL Group and FedEx exemplify divergent positioning. DHL leverages its European government postal heritage to anchor tender wins requiring cross-border compliance documentation. FedEx occupies a position emphasizing specialized document-security protocols for classified material transport. DSV represents the project logistics archetype, sustaining margin pools in overseas defense education equipment through specialized handling requirements. These three companies illustrate how carrier selection increasingly hinges on regulatory certification depth rather than pure transport economics.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| DSV |
| DB Schenker |
| UPS |
| FedEx |
| C.H. Robinson |
| SEKO Logistics |
| Agility |
| Scan Global Logistics A/S |
| Others |
Supply & Pricing Matrix
Ninety-day textbook fulfillment lead times for K-12 districts concentrate pricing power with carriers possessing integrated warehouse management systems, while fuel surcharge pass-through mechanisms insulate margins against diesel volatility in transportation contracts.
Pricing Analysis
Federal agency buyers anchor contract-based pricing structures with multi-year appropriations and certified cost accounting compliance requirements. Three-tier pricing stratification separates ISO-certified cold chain operators from standard freight brokers and economy document couriers. Cost compression in the education provider tier intensifies because state budget cycles compress procurement windows and elevate penalty exposure for delivery failures. University procurement departments exhibit highest price sensitivity due to fragmented purchasing authority across decentralized campuses, while defense logistics agencies show lowest sensitivity given security clearance infrastructure requirements.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for electric bus chassis sourced from South Korean and Chinese manufacturers, forcing California school districts to extend procurement timelines. Component supply concentrates in Germany for precision vehicle electronics, Mexico for nearshored assembly operations, and domestic US territories for final-stage electrification retrofit kits. Raw material dependencies span lithium-ion battery cells, specialized refrigerants for cold chain units, and tamper-evident packaging substrates. Single-source vulnerability runs through EPA-certified zero-emission vehicle platforms where qualified supplier pools remain narrow. Distribution runs through FEMA regional hubs in Atlanta and Denver consolidating previously fragmented stockpiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EPA Clean School Bus Program subsidies accelerate fleet electrification procurement volumes across high-population states, creating structural demand tailwinds for qualified logistics infrastructure.
For Market Incumbents: Compound certification advantages by acquiring ISO cold chain capabilities and federal security clearance infrastructure before procurement rule revisions tighten small-business set-aside thresholds. Integrate telematics platforms with warehouse management systems to defend against asset-light brokers aggregating third-party electric capacity. Prioritize multi-year FEMA managed service contracts in Atlanta and Denver regional hubs. For New Entrants and Emerging Players: Differentiate on REACH chemical disclosure compliance for cross-border defense education equipment rotation, a capability gap among mid-tier carriers. Target university procurement systems in Texas and Florida where legacy ERP integration barriers slow incumbent solution deployment. Pursue white-label partnerships with established carriers lacking European government postal heritage for continental tender access. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because federal procurement standards and EPA emissions mandates create durable moats around qualified vendor pools. Acquisition targets should display integrated warehouse-transportation capabilities with documented chain-of-custody protocols. Monitor EPA grant disbursement velocity as the signal indicating inflection in zero-emission vehicle logistics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | EPA Clean School Bus Program subsidies require qualified zero-emission vehicle infrastructure partners for California and Texas districts. |
| ISO Cold Chain Certification | Temperature-sensitive K-12 meal distribution mandates elevate tamper-evident handling to baseline contract eligibility. |
| FEMA Regional Hub Consolidation | Single-source managed service contracts in Atlanta and Denver reshape vendor qualification pathways toward integrated operators. |
| Secure Document Transit Infrastructure | Federal security clearance requirements restrict classified material handling to carriers with documented chain-of-custody protocols. |
| Telematics Platform Integration | Real-time performance auditing compresses contract renewal cycles and favors asset-heavy operators with captive charging infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with K-12 supply chain managers, FEMA logistics officers, defense procurement leads, university purchasing directors, and carrier fleet operations heads. Secondary validation drew from EPA grant disbursement records, Federal Acquisition Regulation amendment filings, Clean School Bus Program procurement databases, and FEMA regional stockpile consolidation announcements. Bottom-up contract value aggregation and top-down market sizing triangulation reconciled segment-level estimates.
Across the analysis window, the forecasting framework modeled service type segmentation by transportation, warehousing, distribution, and freight forwarding; end user segmentation by government agencies, universities, and education providers; and solution segmentation by supply chain management, inventory control, logistics analytics, and asset tracking. CAGRs derived from historical appropriation growth patterns, EPA mandate implementation schedules, and state education budget allocation trajectories. Industry-specific inputs included electrification infrastructure deployment curves and ISO certification adoption rates.
The analysis sits within stated boundaries; outcomes outside continued federal subsidy authorization, stable diesel-fuel price corridors, and unaltered domestic sourcing preferences would require recalibration. Forecasts reflect documented assumptions regarding procurement rule stability and emissions mandate enforcement consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
France Parcel Market