
 France Cold Chain Logistics Market | 2026-2036
France Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
France Cold Chain Logistics Market Foresight
Aftermarket service revenue is fragmenting across France's cold chain logistics sector as asset owners seek to decouple equipment maintenance from transport contracts. STEF leverages its domestic depot network to control refrigerated fleet servicing across regional produce routes. DHL Supply Chain anchors pharmaceutical-grade compliance capabilities through validated temperature monitoring infrastructure. GEODIS competes on cross-border pharmaceutical corridors linking French manufacturing sites to Benelux distribution hubs.
France cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods within a strict thermal band, typically minus 25°C to plus 25°C depending on product classification, utilizing insulated vehicles, refrigerated warehouses, and real-time telemetry systems to preserve product integrity. The primary commercial purpose centers on extending shelf life and ensuring safety for pharmaceuticals, fresh food, and biotechnology materials subject to degradation outside defined thermal limits. Refrigerated transport dominates service type revenue due to fragmented final-mile requirements across French urban and rural geographies, while temperature-controlled warehousing commands superior margins where pharmaceutical clients demand redundant backup power and continuous monitoring. Third-party logistics channels sustain the fastest structural expansion as food processors and hospital networks outsource compliance liability to specialized operators.
ANSM pharmaceutical distribution guidelines, EU GDP standards for medicinal products, and France's DGCCRF market surveillance framework collectively mandate auditable temperature records and qualified equipment validation across the national cold chain. These requirements elevate capital barriers for new entrants while concentrating procurement authority with certified logistics providers capable of documentary traceability. Stakeholders must monitor refrigerant transition timelines under EU F-Gas Regulation to avoid stranded asset risk in warehouse cooling infrastructure and transport refrigeration units.
Market Dynamics
France's cold chain logistics sector faces structural pressure from the EU F-Gas Regulation refrigerant phase-down, compelling fleet operators and warehouse owners to accelerate equipment replacement cycles while managing stranded asset exposure across temperature-controlled infrastructure.
Growth Catalysts
- Biologics pipeline expansion:French pharmaceutical manufacturers are deepening vaccine and cell therapy portfolios, requiring validated minus 70°C to minus 20°C distribution networks that only specialized logistics providers can construct.
- ANSM GDP enforcement:France's national medicines safety agency is tightening qualification requirements for temperature monitoring systems, concentrating procurement with certified third-party logistics operators capable of documentary traceability.
- Ile-de-France import gateway concentration:Paris-region fresh food terminals and pharmaceutical clusters command premium cold storage capacity, pulling investment toward the corridor's multimodal connectivity.
Market Restraints
- Hydrofluorocarbon refrigerant cost volatility:EU F-Gas quota reductions are compressing HFC supply, elevating re-gassing expenses for transport refrigeration units and stationary warehouse cooling systems.
- Specialized technician scarcity:France's refrigeration maintenance workforce lacks sufficient F-Gas-certified engineers to execute the mandated fleet retrofit timeline across national transport networks.
- Pharmaceutical client consolidation:Sanofi and other major French drug manufacturers are narrowing their logistics vendor panels, squeezing mid-tier cold chain operators out of high-margin compliance segments.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur produce export corridors:Mediterranean port cold storage infrastructure remains underdeveloped relative to northern European competitors, creating first-mover advantage for temperature-controlled consolidation facilities serving North African markets.
- Natural refrigerant technology convergence:CO2 transcritical systems paired with Internet-of-Things telemetry are enabling warehouse operators to satisfy both F-Gas mandates and pharmaceutical clients' redundant backup power requirements simultaneously.
- Hospital network outsourcing acceleration:French public health institutions are divesting in-house pharmaceutical storage assets, opening contract logistics opportunities for GDP-qualified regional depot networks.
Industry Challenges
- Multi-temperature trailer configuration complexity:Food retailers are demanding single vehicles capable of simultaneous minus 25°C frozen, 2°C chilled, and 15°C ambient compartments, straining refrigeration engineering and loading dock scheduling.
- GDP validation timeline compression:Pharmaceutical distributors must complete equipment qualification, mapping studies, and protocol documentation within narrowing windows between product launch and commercial distribution authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Cold Chain Logistics Market |
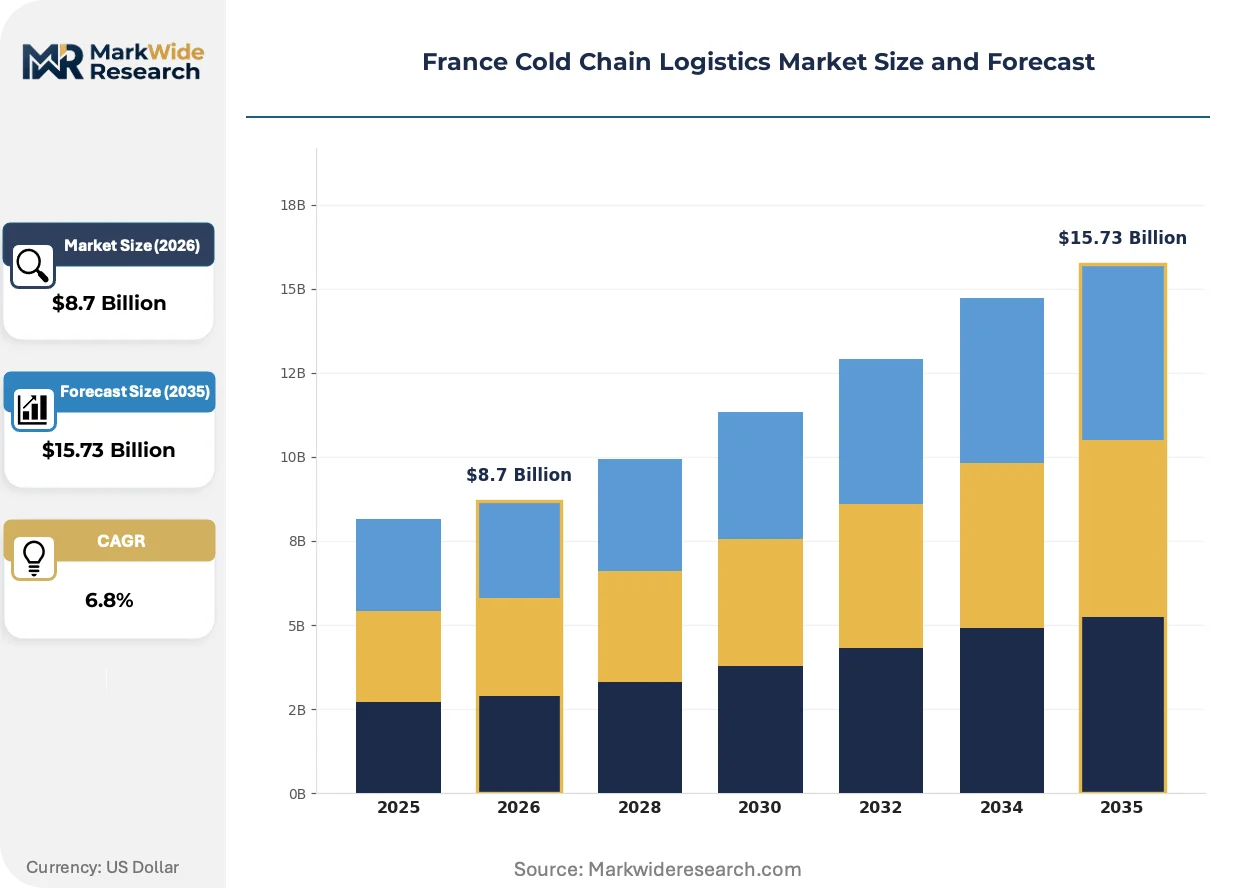
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refrigerated Transport, Temperature-Controlled Warehousing, Cold Storage, Packaging Solutions, Inventory Management Application: Pharmaceuticals Distribution, Frozen Food Delivery, Fresh Produce Handling, Biotechnology, Floral Supply End User: Hospitals, Retail Chains, Food Processors, Research Laboratories, E-Commerce Providers Distribution Channel: Direct Supply, Third-Party Logistics, Cold Chain Integrators, Wholesale Distributors, Online Marketplaces |
| Companies Covered | DSV, DHL Supply Chain, STEF, Olano Group, GEODIS, Kuehne + Nagel, XPO Logistics, IRIS Logistics, Sofrilog, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Cold Chain Logistics Market Shifts & Advancements
Telematics and natural refrigerant technologies are restructuring how French cold chain operators manage thermal compliance and energy consumption across transport and warehouse assets.
Blockchain-enabled temperature logging is digitizing pharmaceutical distribution audit trails. French hospital networks and drug manufacturers are mandating immutable ledger records for shipments of high-value biologics. This architecture compresses dispute resolution cycles between logistics providers and healthcare procurement departments.
The EU F-Gas Regulation is forcing refrigerant transition across French cold storage infrastructure. Warehouse operators must retire R-404A and R-507A systems before quota depletion accelerates re-gassing costs. Pharmaceutical-grade facilities in the Ile-de-France corridor are responding with CO2 transcritical installations paired with battery-backed monitoring redundancy.
Consolidation of fresh produce procurement is restructuring distributor relationships. Large French retail chains are bypassing wholesale markets to contract directly with regional growers, displacing traditional temperature-controlled aggregation points. This pattern concentrates refrigerated transport demand on direct farm-to-store routes through Brittany and Pays de la Loire vegetable production zones.
France Cold Chain Logistics Market Segmentation
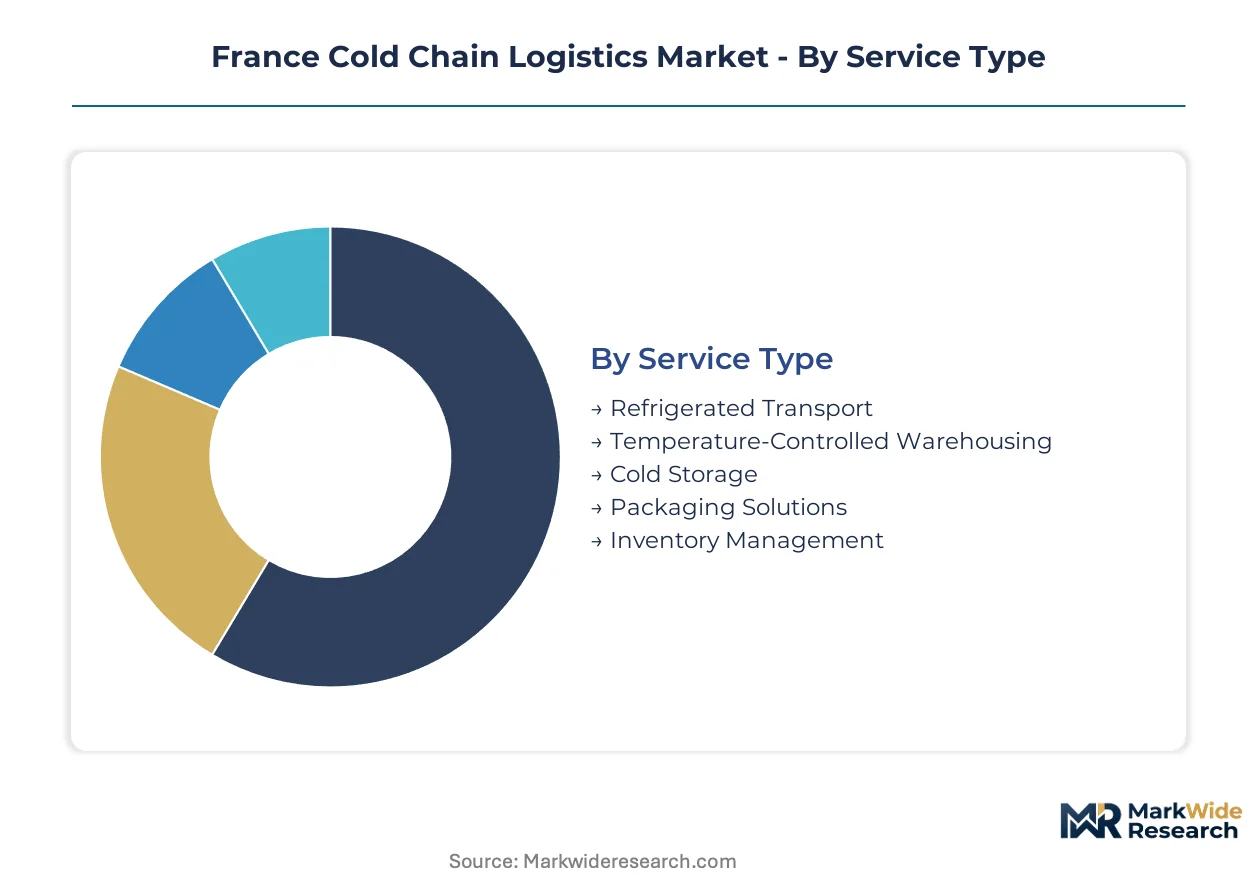
Cold chain logistics segmentation in France reflects divergent compliance intensities across pharmaceutical GDP mandates and food safety protocols. Service configuration and channel selection determine capital deployment patterns and margin capture potential for operators navigating the Ile-de-France corridor and regional produce networks.
Service Type:
Cost tier differentiation separates asset-heavy infrastructure plays from variable-cost service layers, with capital intensity escalating from transport through specialized warehousing.
- Refrigerated Transport:Insulated vehicles with multi-temperature zone capability handle final-mile distribution across fragmented French urban and rural geographies. Demand concentrates on produce routes through Brittany and Pays de la Loire, where direct farm-to-store retail contracts displace traditional wholesale aggregation points.
- Temperature-Controlled Warehousing:Stationary facilities with redundant backup power and continuous monitoring infrastructure serve pharmaceutical clients demanding validated minus 70°C to plus 25°C storage bands. Ile-de-France pharmaceutical clusters command premium capacity rates due to multimodal connectivity and ANSM compliance density.
- Cold Storage:Bulk frozen inventory facilities with blast freezing capability support seasonal agricultural harvests and import buffer stock.
- Packaging Solutions:Insulated shippers with phase-change materials provide temporary thermal protection for small-parcel pharmaceutical and biotech shipments.
- Inventory Management:WMS-integrated stock rotation and expiry tracking services reduce waste for food processors and hospital pharmacies.
Refrigerated transport commands the established base. The steepest expansion runs through temperature-controlled warehousing as biologics pipelines deepen validated storage requirements.
Application:
End-use thermal specifications create distinct equipment qualification burdens, with pharmaceutical applications demanding documentary traceability that food segments do not require.
- Pharmaceuticals Distribution:GDP-compliant networks handle vaccines, cell therapies, and biologics requiring continuous temperature monitoring with immutable audit trails. ANSM enforcement is tightening qualification requirements, concentrating procurement with certified third-party logistics operators capable of blockchain-enabled temperature logging.
- Frozen Food Delivery:Minus 25°C chains preserve prepared meals and ice cream through retail distribution networks. Large French retail chains are narrowing vendor panels, squeezing mid-tier operators unable to meet simultaneous multi-temperature trailer configurations.
- Fresh Produce Handling:0°C to 15°C controlled atmosphere systems extend shelf life for fruits and vegetables. Provence-Alpes-Côte d'Azur export corridors to North African markets remain underdeveloped relative to northern European competitors.
- Biotechnology:Ultra-low minus 70°C cryogenic chains support cell and gene therapy clinical trial materials.
- Floral Supply:Humidity-controlled 2°C to 8°C transport maintains ornamental plant viability through auction and retail channels.
Frozen food delivery anchors volume throughput. Biotechnology applications are climbing the fastest as French manufacturers deepen cell therapy portfolios requiring specialized distribution infrastructure.
End User:
Customer organizational scale determines contract structure, with consolidated procurement authority shifting toward integrated health networks and national retail banners.
- Hospitals:Public health institutions are divesting in-house pharmaceutical storage assets, opening contract logistics opportunities for GDP-qualified regional depot networks.
- Retail Chains:Centralized buying departments negotiate direct farm contracts, bypassing wholesale markets and restructuring temperature-controlled aggregation points.
- Food Processors:Manufacturers outsource compliance liability to specialized operators capable of handling multi-temperature product portfolios.
- Research Laboratories:Academic and commercial R&D facilities require validated sample transport with chain-of-custody documentation.
- E-Commerce Providers:Meal-kit and grocery delivery platforms demand flexible last-mile refrigerated capacity with narrow delivery windows.
Retail chains dominate contract value. Hospital network outsourcing is gaining share fastest as public health institutions accelerate asset divestment.
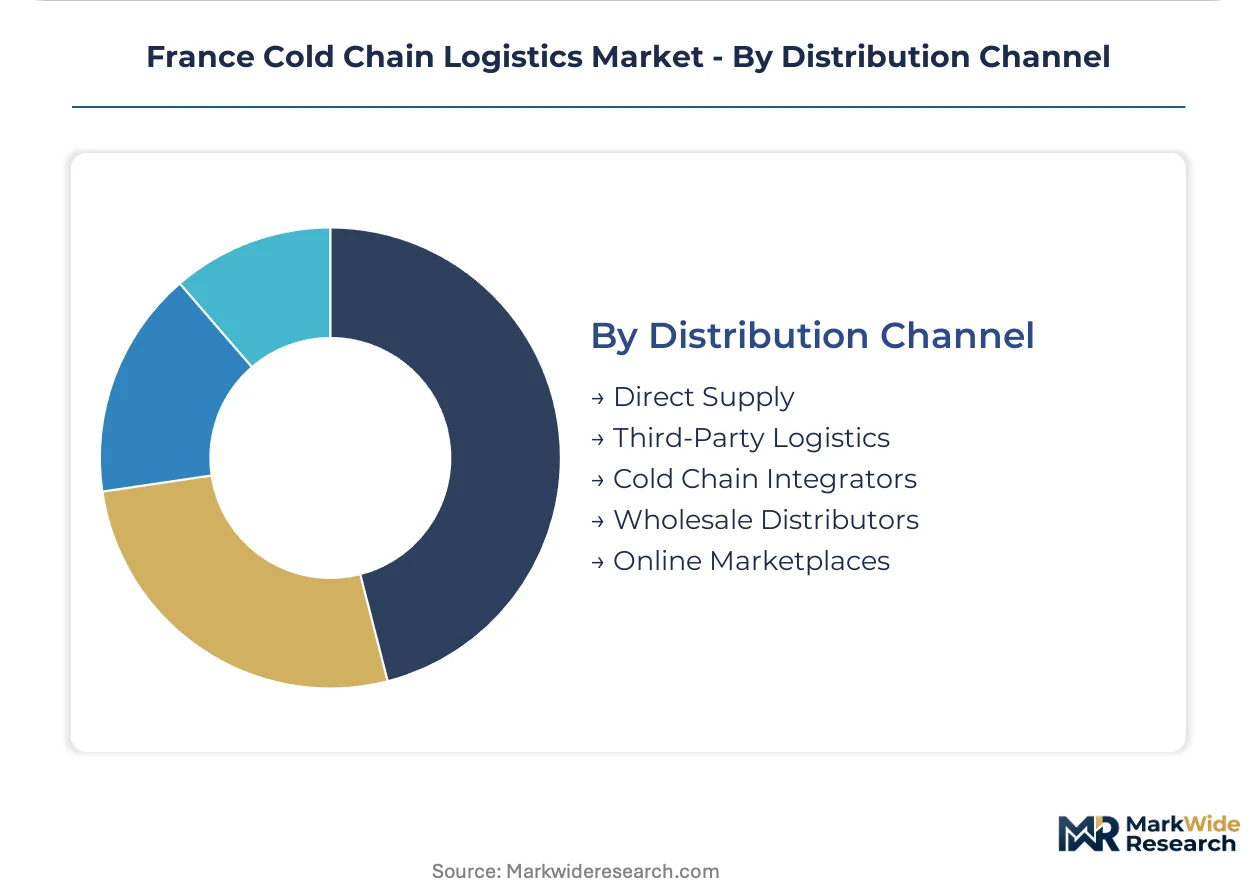
Distribution Channel:
Channel selection reflects risk transfer preferences, with pharmaceutical clients prioritizing compliance certification over cost minimization.
- Third-Party Logistics:Specialized cold chain operators assume temperature liability through validated equipment and documented procedures. GDP certification requirements elevate capital barriers for new entrants while concentrating procurement authority with established providers.
- Cold Chain Integrators:End-to-end network managers coordinate transport, warehousing, and packaging across multiple subcontractor tiers. Sanofi and other major French drug manufacturers are narrowing vendor panels, favoring integrators with pharmaceutical-grade compliance capabilities.
- Direct Supply:Producer-controlled fleets serve captive distribution needs for large food processors and pharmaceutical manufacturers.
- Wholesale Distributors:Traditional temperature-controlled aggregation points face displacement as retail chains source directly from regional growers.
- Online Marketplaces:Digital freight platforms match spot refrigerated capacity with seasonal demand surges.
Third-party logistics holds the installed base. Cold chain integrators are expanding most quickly as pharmaceutical clients consolidate vendor relationships and outsource compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France consumes cold chain services differently than peripheral French regions, concentrating pharmaceutical-grade warehousing and multimodal import capacity while agricultural zones prioritize refrigerated transport for produce export corridors.
Île-de-France
Paris-region pharmaceutical clusters and fresh food import gateways command premium cold storage capacity, pulling investment toward multimodal connectivity. ANSM enforcement tightens GDP qualification requirements for temperature monitoring systems, concentrating procurement with certified operators. Roissy-Charles de Gaulle logistics zones anchor validated minus 70°C to plus 25°C storage infrastructure for biologics distribution.
Auvergne-Rhône-Alpes
Lyon-based pharmaceutical manufacturing sites generate outbound cold chain demand toward Benelux distribution hubs. EU F-Gas Regulation mandates accelerate warehouse equipment retrofits across the region's temperature-controlled infrastructure. Saint-Quentin-Fallavier cold storage parks expand capacity to capture vaccine and cell therapy logistics contracts.
Provence-Alpes-Côte d'Azur
Mediterranean produce export corridors to North African markets remain underdeveloped relative to northern European competitors. The region's port cold storage infrastructure requires consolidation facility investment to capture temperature-controlled volume. Marseille-Fos port zones attract first-mover operators targeting Moroccan and Algerian fresh food distribution.
Brittany
Direct farm-to-store retail contracts displace traditional wholesale aggregation points across vegetable production zones. Large French retail chains negotiate centralized procurement agreements with regional growers, restructuring refrigerated transport demand. Rennes logistics corridors specialize in multi-temperature trailer configurations for simultaneous frozen, chilled, and ambient compartment distribution.
Hauts-de-France
Calais-Dunkirk port complexes serve as UK-facing cold chain gateways, handling Brexit-adjusted pharmaceutical and fresh food transit. The region's cross-Channel ferry and rail freight connections demand redundant backup power systems for customs-delayed cargo. Lille metropolitan logistics parks develop GDP-qualified depot networks for hospital network outsourcing contracts.
France Cold Chain Logistics Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical-grade operators; scale advantage sits with integrated global logistics networks. The sector exhibits tiered competition between GDP-certified specialists and diversified transport conglomerates. Three archetypes dominate: domestic depot network operators controlling regional produce routes, global integrators anchoring pharmaceutical compliance infrastructure, and cross-border corridor managers linking manufacturing to distribution hubs. Competitive dynamics center on fleet retrofit acceleration under F-Gas timelines and vendor panel consolidation by major drug manufacturers.
Within the domestic specialist tier, STEF leverages its regional depot network across French produce corridors, while DHL Supply Chain anchors pharmaceutical-grade compliance capabilities through validated temperature monitoring infrastructure. GEODIS occupies a position on cross-border pharmaceutical corridors connecting French manufacturing sites to Benelux distribution hubs. These three exemplify divergent strategic positions: STEF represents asset-heavy regional coverage, DHL Supply Chain exemplifies global compliance certification, and GEODIS sits within the European corridor integration archetype. Mid-tier operators face squeeze pressure as Sanofi and other major French drug manufacturers narrow vendor panels, favoring integrators with pharmaceutical-grade capabilities over diversified transport providers.
| Leading Market Players |
|---|
| DSV |
| DHL Supply Chain |
| STEF |
| Olano Group |
| GEODIS |
| Kuehne + Nagel |
| XPO Logistics |
| IRIS Logistics |
| Sofrilog |
| Others |
Supply & Pricing Matrix
Roissy-Charles de Gaulle logistics zones anchor France's pharmaceutical-grade cold storage capacity, concentrating premium pricing power with GDP-certified operators capable of validated minus 70°C infrastructure. This Ile-de-France cluster leverages multimodal connectivity and ANSM enforcement density to sustain margin premiums unavailable in regional produce corridors.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical distribution, with Sanofi and major French drug manufacturers locking in multi-year agreements with certified integrators. Price differentiation hinges on GDP certification tier and redundant backup power configuration, with hospital networks showing highest sensitivity to per-pallet storage rates. Cost compression in frozen food transport intensifies as retail chains consolidate vendor panels and demand simultaneous multi-temperature trailer capability. Biotechnology clients exhibit lowest price sensitivity, prioritizing validated cryogenic chains over cost minimization.
Supply Chain Analysis
Carrier Transicold and Thermo King manufacturing concentration in France and Germany shapes domestic transport refrigeration availability. Equipment fleets draw from HFC refrigerant quotas regulated under EU F-Gas Regulation, with CO2 transcritical systems emerging as the primary alternative technology. Single-source vulnerability concentrates in F-Gas-certified technician pools, where workforce scarcity threatens retrofit timeline compliance. Distribution runs through third-party logistics channels for pharmaceutical clients, while fresh produce segments retain direct supply arrangements with regional grower cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's cold chain logistics sector sits in early-cycle expansion as biologics pipelines deepen validated infrastructure requirements and hospital network outsourcing accelerates asset divestment.
For Market Incumbents: Entrench pharmaceutical-grade compliance capabilities through CO2 transcritical warehouse retrofits ahead of F-Gas quota depletion. Expand GDP-certified depot networks into Auvergne-Rhône-Alpes vaccine manufacturing corridors to capture cell therapy logistics contracts. Vertical integration into F-Gas-certified technician training programs addresses workforce scarcity threatening fleet retrofit timelines.
For New Entrants and Emerging Players: Establish a beachhead in Provence-Alpes-Côte d'Azur produce export corridors, where Mediterranean port cold storage infrastructure remains underdeveloped relative to northern European competitors. Target direct farm-to-store retail contracts in Brittany vegetable production zones, bypassing wholesale aggregation points displaced by centralized procurement. Lead with natural refrigerant technology convergence paired with Internet-of-Things telemetry to satisfy simultaneous F-Gas mandates and pharmaceutical backup power requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because ANSM enforcement and EU GDP standards elevate capital barriers while concentrating procurement authority with certified operators. Acquisition candidates include regional depot networks with F-Gas transition progress and existing hospital network relationships. Monitor biologics pipeline announcements from French pharmaceutical manufacturers as inflection indicators for validated cryogenic storage demand.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical System Deployment | EU F-Gas Regulation compliance pairs with pharmaceutical backup power requirements in Ile-de-France facilities. |
| GDP-Certified Depot Network Expansion | Hospital network outsourcing in Lille metropolitan logistics parks captures public health institution divestment. |
| Multi-Temperature Trailer Configuration | Simultaneous frozen-chilled-ambient capability addresses retail chain consolidation of direct farm contracts. |
| Blockchain-Enabled Temperature Logging | Immutable audit trails compress dispute resolution cycles with ANSM-mandated documentary traceability. |
| F-Gas-Certified Technician Training Programs | Workforce development secures retrofit execution capacity across national transport refrigeration fleets. |
Research Methodology
The analysis maps refrigerated transport, temperature-controlled warehousing, and cold storage segments, each validated through fleet operations managers, pharmaceutical supply chain directors, and hospital procurement officers. Primary interviews with GDP compliance auditors and F-Gas certification specialists combined with secondary validation from ANSM regulatory filings, EU F-Gas Regulation quota tracking, and customs cold chain trade data. Bottom-up equipment fleet sizing and top-down pharmaceutical distribution value chain modeling provided triangulation checks.
Assumptions held fixed include EU F-Gas Regulation enforcement timelines and ANSM GDP qualification standards, while variables included biologics pipeline progression rates and hospital outsourcing acceleration. Segmentation dimensions modeled cover service type, application thermal specification, end-user organizational scale, and distribution channel risk-transfer structure across the analysis window. CAGRs derived from equipment replacement cycle analysis and pharmaceutical storage capacity absorption rates, with cryogenic chain infrastructure buildout and natural refrigerant adoption curves as key forecast inputs.
Stress conditions across F-Gas refrigerant cost volatility, pharmaceutical client vendor panel consolidation, and Mediterranean export corridor development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions with acknowledged sensitivity to regulatory enforcement intensity and biologics commercialization timelines. Quarterly review of ANSM inspection citation trends and EU F-Gas quota market pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Warehousing and Distribution Logistics Market