
 Singapore Freight and Logistics Market | 2026-2036
Singapore Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Freight and Logistics Market Analytics
Air-sea intermodal corridors is reconfiguring cargo flows through Changi and PSA terminals. DHL Group leverages its integrated express network to dominate time-critical pharmaceutical shipments. PSA International anchors container throughput expansion through its Tuas port automation investments. Kuehne+Nagel differentiates via specialized perishable logistics serving ASEAN agricultural exporters.
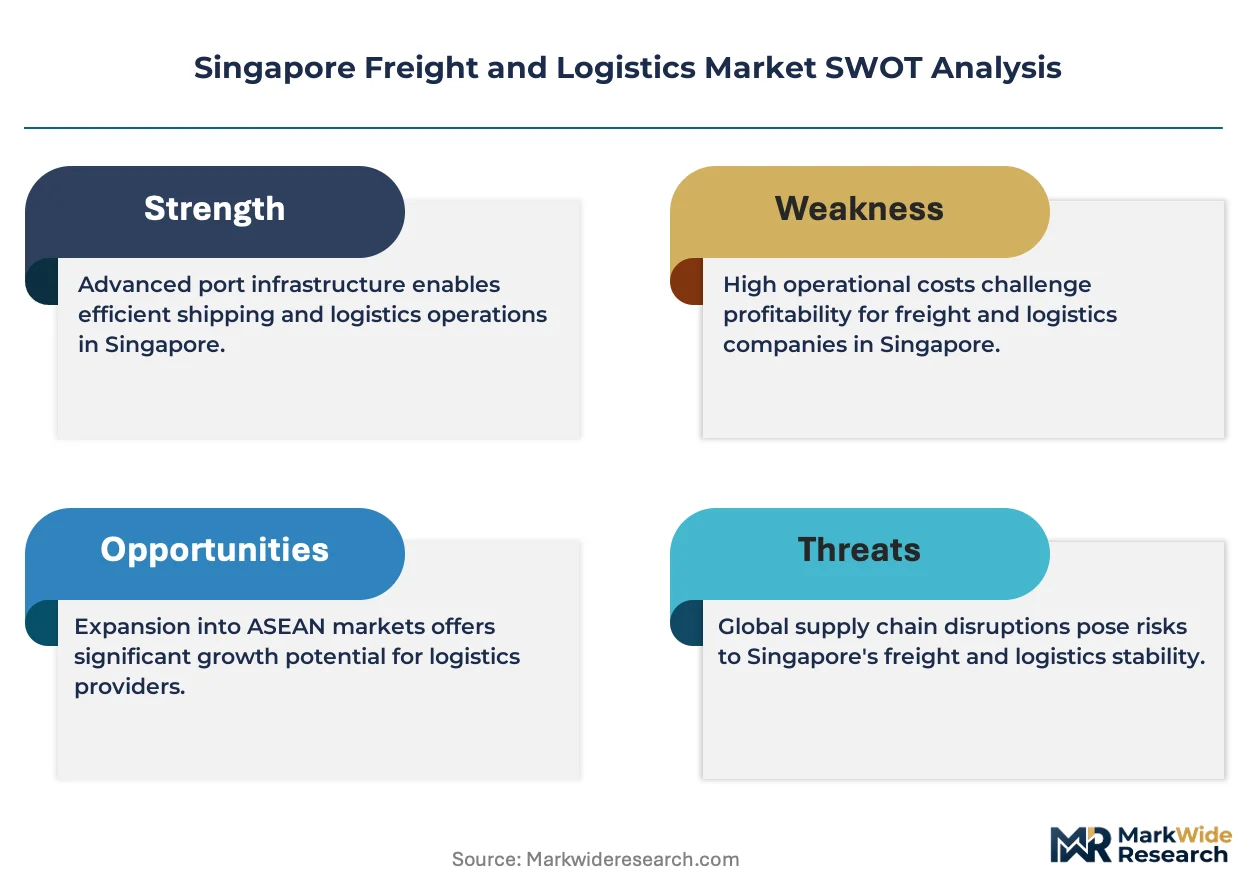
Singapore freight and logistics encompasses the coordinated movement, storage, and information management of goods across multimodal transport nodes with container handling capacities exceeding 40 million TEU annually at PSA terminals. The sector functions as a transshipment hub connecting 600 ports across 120 countries through automated quay cranes and real-time vessel scheduling systems. Freight forwarding services capture premium margins from customs brokerage and trade documentation complexity across ASEAN free trade agreements. Warehousing segments are expanding fastest in cold chain and bonded facilities serving pharmaceutical end users with temperature-validated storage protocols. Sea transportation mode retains volume dominance while air freight commands value concentration in electronics and biologics shipments.
Singapore's Maritime and Port Authority enforces environmental standards through the Maritime Singapore Green Initiative, mandating low-sulfur fuel transitions and shore power connectivity at berth. The Land Transport Authority regulates heavy vehicle emissions and driver hour limits affecting last-mile road distribution networks. Enterprise Singapore administers productivity grants accelerating warehouse management system and blockchain traceability adoption. Stakeholders must weigh automation capital commitments against labor tightening from foreign worker quota reductions.
Market Dynamics
Tuas mega-port automation investments are compressing container handling costs while forcing legacy terminal operators to accelerate digitization timelines or surrender transshipment volumes to PSA International's integrated ecosystem.
Growth Catalysts
- Maritime Singapore Green Initiative:Mandates for low-sulfur fuel transitions and shore power connectivity at berth are driving retrofit demand for vessel operators and creating specialized bunkering service opportunities.
- E-commerce fulfillment acceleration:Pharmaceutical and electronics end-users are demanding temperature-validated automated warehousing solutions with real-time inventory visibility.
- Smart Nation infrastructure investments:Government-funded blockchain traceability pilots and warehouse management system productivity grants are lowering adoption barriers for mid-tier freight forwarders.
Market Restraints
- Foreign worker quota tightening:Land Transport Authority enforcement of heavy vehicle driver hour limits combined with Ministry of Manpower permit reductions is constraining last-mile road distribution capacity expansion.
- Automation capital intensity:Automated quay cranes and real-time vessel scheduling systems require eight-figure capital commitments that smaller terminal operators cannot access.
- Jurong Island land scarcity:Petrochemical cluster warehousing expansion faces physical constraints from island geography and competing industrial zoning priorities.
Strategic Opportunities
- Cold chain underpenetration:ASEAN agricultural exporters lack temperature-controlled consolidation facilities, creating white space for bonded cold storage investments near Changi air cargo terminals.
- Air-sea intermodal convergence:Integration of express networks with container terminals enables pharmaceutical shippers to optimize cost-speed trade-offs across multimodal corridors.
- Enterprise Singapore productivity grants:Remaining funding pools for warehouse robotics and predictive maintenance systems offer subsidized entry points for automation laggards.
Industry Challenges
- Legacy system integration complexity:Terminal operators face technical debt from decades-old cargo management systems that resist API connectivity with modern IoT sensor networks.
- Specialized talent scarcity:Maritime cybersecurity and predictive analytics skill gaps exceed local training pipeline output, forcing reliance on expensive foreign contractor arrangements.
- Trade documentation standardization delays:ASEAN free trade agreement complexity creates friction for customs brokerage automation despite digital trade corridor initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Freight and Logistics Market |
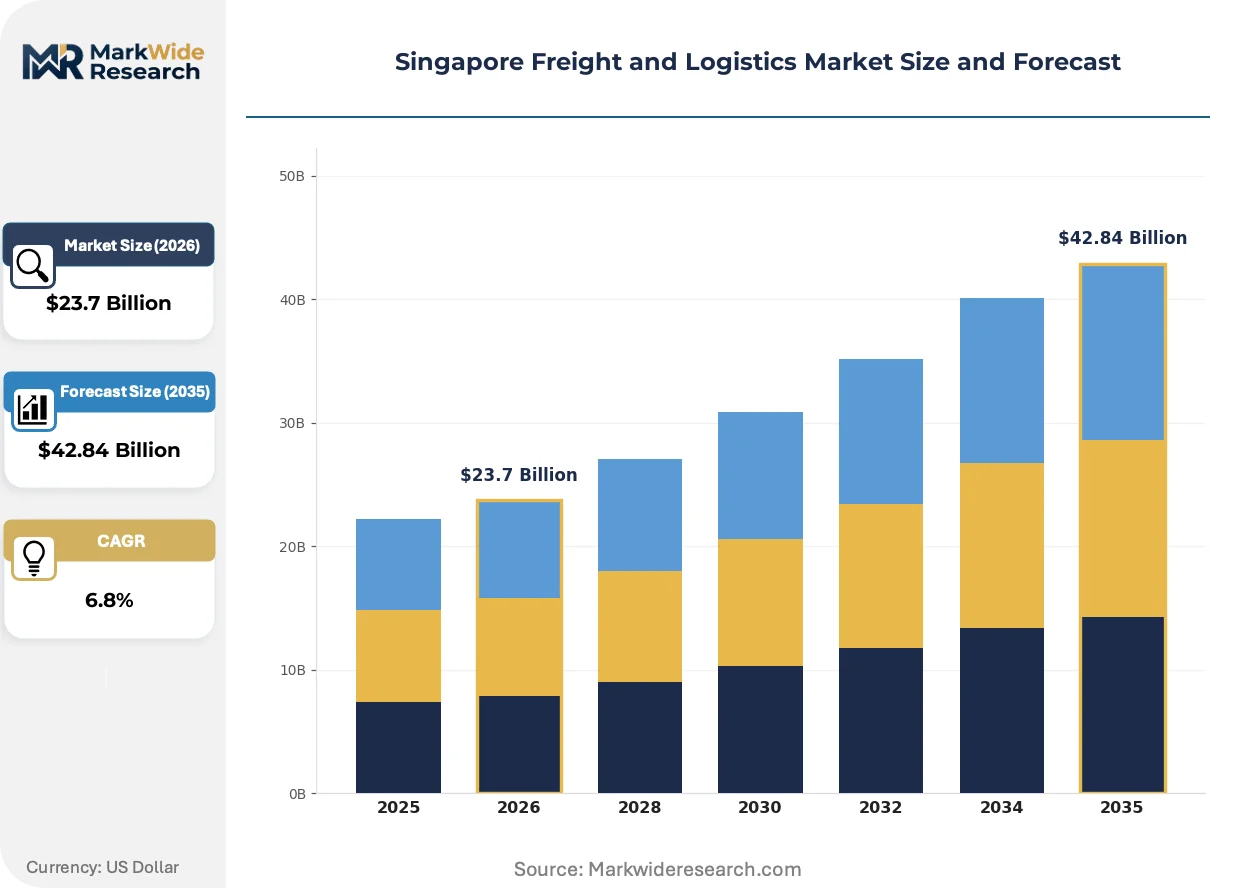
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Transportation Mode: Air, Sea, Rail, Road End User: E-Commerce, Manufacturing, Retail, Pharmaceuticals Technology: GPS Tracking, TMS, WMS, Blockchain |
| Companies Covered | DHL Group, DSV, Kuehne+Nagel, FedEx, PSA International, DB Schenker, CEVA Logistics, YCH Group, A.P. Moller - Maersk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Freight and Logistics Market Evolving Landscape
Digital twin technology and autonomous yard equipment are compressing vessel turnaround times while redefining labor requirements across Singapore's port ecosystem. These shifts are accelerating consolidation among technology-lagging operators.
Autonomous guided vehicles in container yards are rendering obsolete manual straddle carrier operations at Tuas terminal phases. PSA International is deploying these systems across new berths, eliminating driver fatigue constraints and enabling 24-hour continuous stacking operations without shift-change downtime. The technology is rendering obsolete traditional labor-intensive yard management contracts that anchored third-party logistics pricing for decades.
Maritime Singapore Green Initiative Phase Two mandates shore power connectivity for vessels above specified gross tonnage thresholds by enforced deadlines. This regulatory pressure is accelerating shore-side electrical infrastructure investments and creating new revenue streams for terminal operators selling cold-ironing services. Pharmaceutical and reefer container segments are most affected, with carriers prioritizing berth assignments at electrified terminals to avoid fuel-switching penalties.
Shippers are unbundling express forwarding from integrated supply chain contracts, opting instead for spot-market digital freight platforms on non-critical lanes. This procurement fragmentation is compressing margins for traditional forwarders while expanding addressable volume for technology-native booking platforms. Electronics manufacturers with high shipment frequency and predictable scheduling are driving this shift most aggressively in Singapore-to-ASEAN corridors.
Singapore Freight and Logistics Market Segmentation
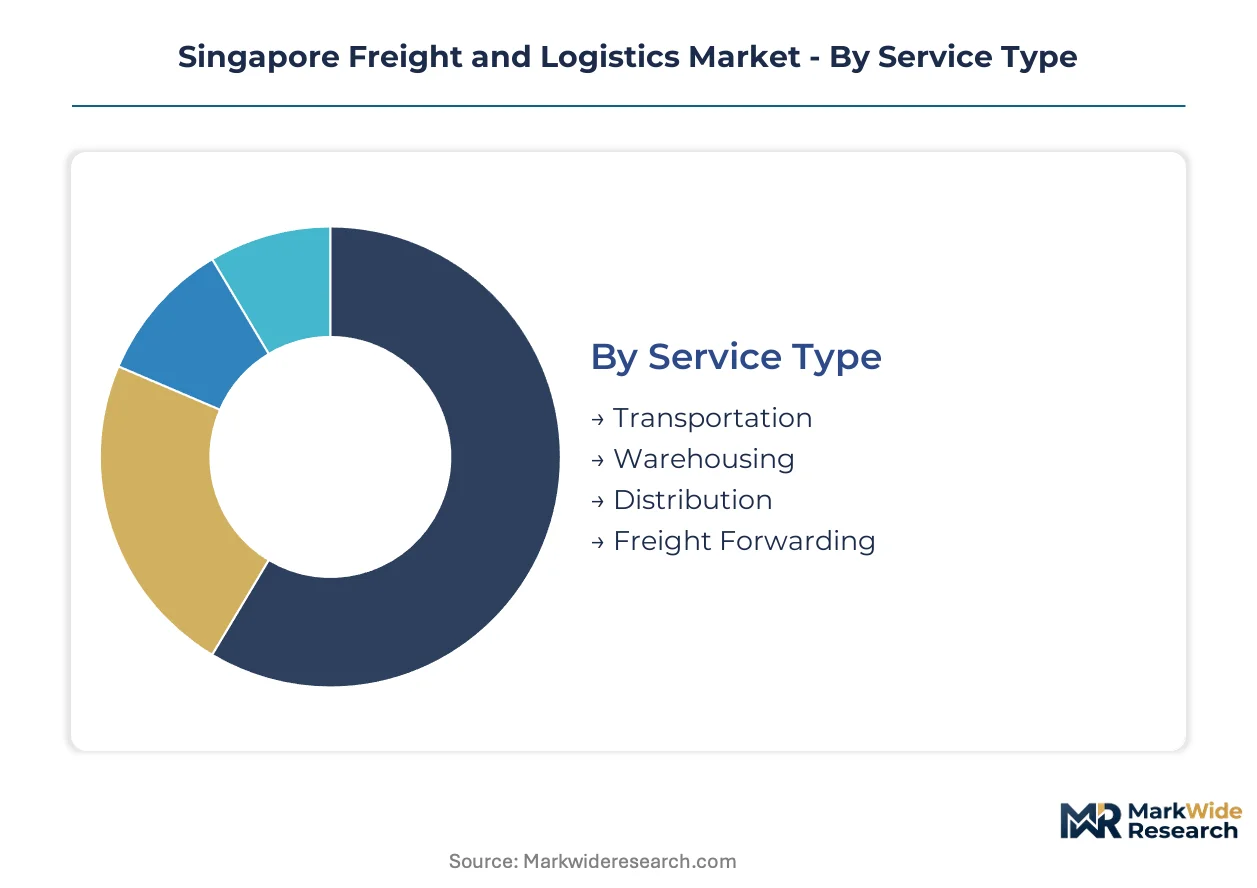
Segmentation in Singapore freight and logistics reveals how service specialization, modal choice, and technology adoption stratify margin capture across the city-state's transshipment hub. Each dimension exposes distinct competitive dynamics from PSA International's terminal automation to cold chain demands near Changi.
Service Type:
Mature consolidation in transportation contrasts with emerging sophistication in value-added warehousing and integrated forwarding solutions.
- Transportation:Container haulage and last-mile road distribution dominate volume throughput, with Land Transport Authority emissions regulations forcing fleet electrification investments. Jurong Island petrochemical corridors and Tuas mega-port feeder routes concentrate demand from integrated energy and shipping conglomerates.
- Warehousing:Temperature-validated facilities serving pharmaceutical end-users command premium rents through bonded status and cold chain certification. E-commerce fulfillment centers near Changi air cargo terminals are expanding fastest as ASEAN cross-border retail volumes surge.
- Distribution:Consolidated last-mile networks integrate PSA terminal flows with urban delivery nodes, constrained by foreign worker quota tightening on heavy vehicle operations.
- Freight Forwarding:Customs brokerage and trade documentation services capture margins from ASEAN free trade agreement complexity, though spot-market digital platforms are fragmenting procurement on non-critical lanes.
Transportation handles the majority of throughput; warehousing is expanding most quickly on share as pharmaceutical and e-commerce verticals deepen requirements.
Transportation Mode:
Cost tiers separate high-volume sea freight from premium air cargo, with rail and road serving intermodal connectivity functions.
- Sea:PSA terminals process container volumes exceeding 40 million TEU annually through automated quay cranes and real-time vessel scheduling. Maritime Singapore Green Initiative mandates are accelerating shore power retrofit investments and low-sulfur fuel transitions.
- Air:Changi air cargo terminals concentrate value in electronics and biologics shipments, with DHL Group and integrated express networks dominating time-critical pharmaceutical corridors. Temperature-controlled handling infrastructure differentiates premium service tiers.
- Rail:Limited domestic network connects Tuas industrial zones to Malaysia's freight corridors, serving as a modal bridge rather than standalone volume channel.
- Road:Heavy vehicle distribution faces Land Transport Authority driver hour limits and Ministry of Manpower permit reductions, constraining capacity expansion despite last-mile demand growth.
Sea handles the majority of throughput; air is climbing the fastest as pharmaceutical and electronics shippers prioritize speed-to-market.
End User:
Application intensity varies from standardized retail flows to compliance-heavy pharmaceutical protocols requiring validated cold chain documentation.
- E-Commerce:Cross-border ASEAN retail volumes are driving automated warehousing investments with real-time inventory visibility requirements. Enterprise Singapore productivity grants are subsidizing warehouse management system adoption for mid-tier fulfillment operators.
- Manufacturing:Electronics and precision component shipments dominate air-sea intermodal planning, with just-in-time inventory models demanding predictive scheduling accuracy.
- Retail:Traditional import distribution faces margin compression from direct-to-consumer e-commerce disintermediation, forcing consolidation among legacy wholesale logistics providers.
- Pharmaceuticals:Temperature-validated storage protocols and blockchain traceability pilots are reshaping facility specifications near Changi and Tuas zones, with Enterprise Singapore grants accelerating compliance investments.
E-commerce handles the majority of throughput growth; pharmaceuticals is gaining share fastest as ASEAN biologics manufacturing expands export requirements.
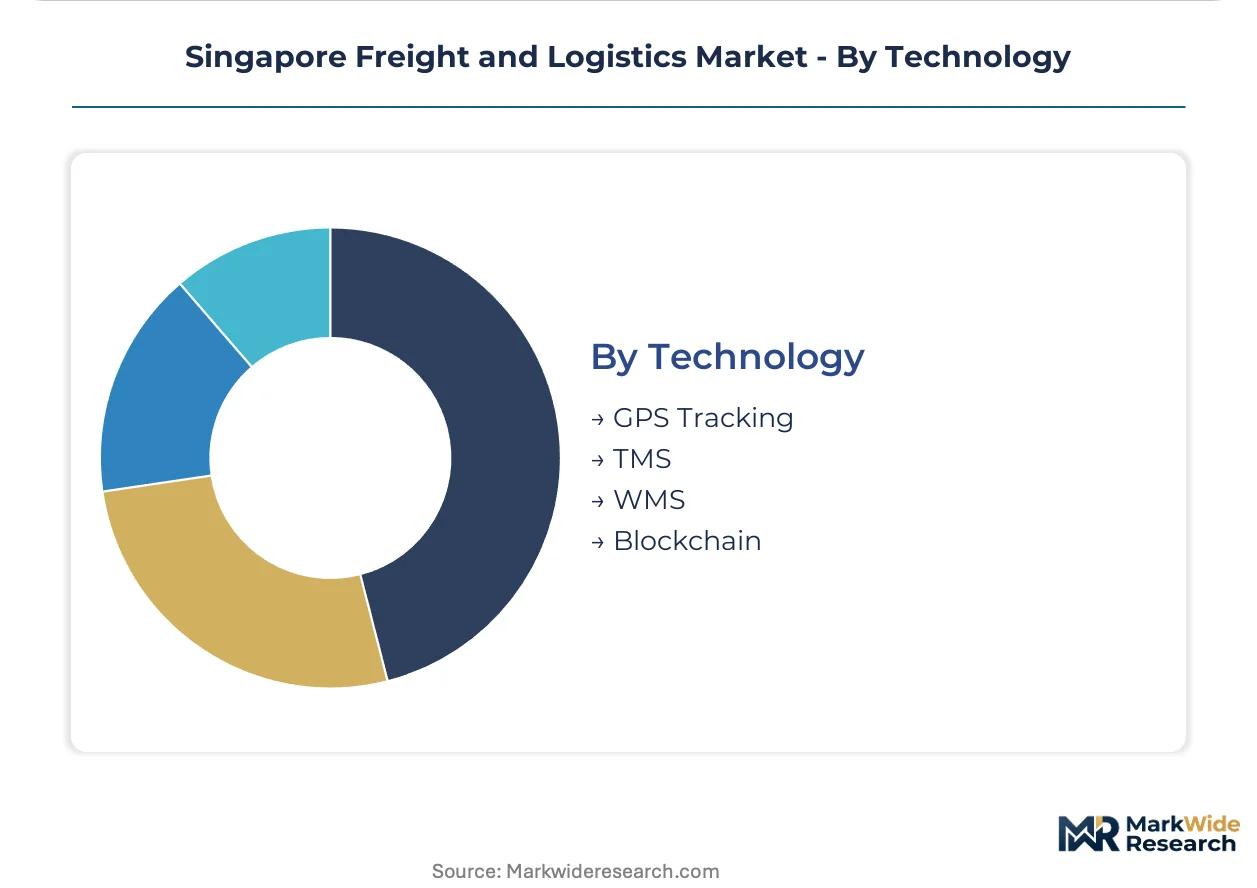
Technology:
Adoption maturity spreads from ubiquitous GPS tracking through emerging blockchain traceability implementations with uneven interoperability standards.
- GPS Tracking:Real-time fleet visibility is baseline across road distribution and container yard operations, with autonomous guided vehicles at Tuas terminals eliminating manual straddle carrier dependencies.
- TMS:Transport management systems optimize multimodal routing across PSA terminal integrations, though legacy cargo management systems resist API connectivity with modern IoT sensor networks.
- WMS:Warehouse management systems are the primary target of Enterprise Singapore productivity grants, with predictive maintenance modules and warehouse robotics receiving subsidized deployment support.
- Blockchain:Government-funded traceability pilots are lowering adoption barriers for pharmaceutical and perishable segments, though ASEAN trade documentation standardization delays limit cross-border interoperability.
GPS tracking handles the majority of installed base; blockchain is on the steepest expansion trajectory as regulatory pressure mounts for supply chain transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore's Tuas mega-port zone while Malaysian ports capture transshipment overflow through cost-advantaged feeder routes. This asymmetry is reshaping capital allocation across Southeast Asian logistics corridors.
Malaysia
Port Klang and Tanjung Pelepas absorb container volumes displaced by Singapore's automation transition. The Malaysia Digital Economy Blueprint subsidizes warehouse management system adoption in Johor logistics parks. Iskandar Malaysia special economic zone anchors cold storage investments serving Singapore pharmaceutical demand.
Indonesia
Batam and Bintan free trade zones leverage proximity to Singapore for electronics component consolidation. Indonesia's National Logistics Ecosystem program mandates digital trade documentation standardization by enforced deadlines. Greater Jakarta industrial corridors concentrate e-commerce fulfillment center construction.
Thailand
Eastern Economic Corridor development expands Laem Chabang port capacity for ASEAN automotive supply chains. Thailand Board of Investment grants accelerate automated warehousing adoption in Chonburi and Rayong provinces. Bangkok metropolitan logistics networks face last-mile congestion from commercial vehicle hour restrictions.
Vietnam
Hai Phong and Da Nang ports capture manufacturing relocation flows from China-plus-one strategies. Vietnam's Logistics Development Strategy prioritizes cold chain infrastructure for agricultural export corridors. Northern industrial provinces concentrate electronics contract manufacturer warehousing requirements.
Singapore Freight and Logistics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in niche service segments. The Singapore freight and logistics sector exhibits consolidated terminal operations alongside fragmented forwarding and warehousing tiers. Three archetypes dominate: integrated global forwarders with express networks, state-linked port operators with automation scale, and regional specialists in perishable or pharmaceutical verticals. Competitive moves center on Tuas port capacity expansion and productivity grant capture for warehouse robotics deployment.
Among integrated global forwarders, DHL Group and Kuehne+Nagel exemplify platform-scale archetypes with multimodal network density. PSA International anchors the state-linked operator tier through Tuas mega-port automation investments. These three entities represent divergent strategic positions: express-forwarding integration, specialized perishable logistics, and terminal infrastructure control.
| Leading Market Players |
|---|
| DHL Group |
| DSV |
| Kuehne+Nagel |
| FedEx |
| PSA International |
| DB Schenker |
| CEVA Logistics |
| YCH Group |
| A.P. Moller - Maersk |
| Others |
Value Network & Pricing Analysis
Tuas mega-port undercapacity during phased automation rollouts is compressing spot rates at PSA terminals while forcing shippers toward longer-term contract commitments to secure berth priority. This utilization squeeze simultaneously elevates premium pricing for guaranteed slot access and accelerates supplier consolidation among forwarders with terminal integration.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical logistics and standard container haulage spans contract-based long-term offtake for validated cold chain against commodity spot pricing for dry freight. Price differentiation rests on certification level—GDP-compliant temperature validation commands substantial premiums over baseline warehousing—and volume scale, with electronics manufacturers extracting discounts through shipment frequency commitments. Cost compression in standard freight forwarding is intensifying because spot-market digital platforms fragment procurement on non-critical ASEAN lanes. E-commerce fulfillment operators exhibit highest price sensitivity due to thin retail margins, while biologics shippers remain least sensitive given compliance-driven procurement criteria.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard among integrated express networks, with supply-chain finance facilities emerging as competitive differentiators for mid-tier forwarders. Geographic supply concentration draws from China for automated material handling equipment, South Korea for vessel tracking systems, and Germany for predictive maintenance software. Raw material dependencies center on lithium-ion batteries for electric yard tractors, specialized steel for quay crane fabrication, and semiconductor components for IoT sensor networks. Single-source vulnerability in autonomous guided vehicle software creates structural risk. Distribution runs through PSA terminal gate complexes into bonded warehouse clusters at Jurong Island and Changi air cargo zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore freight and logistics represents high-growth disruption anchored by Maritime Singapore Green Initiative Phase Two mandates that are rewiring terminal electrification requirements and capital allocation priorities across the port ecosystem.
For Market Incumbents: Entrench terminal automation advantages through accelerated digital twin deployment at Tuas berths, while securing backward integration into shore power infrastructure to capture cold-ironing revenue streams threatened by PSA International's integrated ecosystem. Foreign worker quota tightening demands immediate warehouse robotics deployment using remaining Enterprise Singapore productivity grant pools. For New Entrants and Emerging Players: Build out bonded cold storage capacity near Changi air cargo terminals, where ASEAN agricultural exporter consolidation demand exceeds current temperature-validated facility supply. Target pharmaceutical verticals with blockchain-traceable warehousing as the most penetrable segment given compliance-driven procurement and limited specialist competition. Pursue go-to-market partnerships with existing express networks rather than standalone terminal access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated warehousing sub-segments as Enterprise Singapore grant exhaustion approaches, favoring asset-heavy operators with deployed robotics infrastructure over technology-light forwarding intermediaries. Long-term viability over the coming decade rests on regulatory compliance capabilities and terminal integration depth. Acquisition target archetype: regional cold chain specialists with GDP certification and Changi zone real estate. Monitor PSA International berth allocation policy shifts as the critical inflection signal for forwarder margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Scale-Up | PSA International's Tuas deployment eliminates labor constraints while compressing competitor margins through faster vessel turnaround. |
| Shore Power Infrastructure Investment | Maritime Singapore Green Initiative Phase Two mandates create captive revenue streams from carrier cold-ironing service purchases. |
| Warehouse Robotics Deployment | Enterprise Singapore productivity grants subsidize predictive maintenance systems that offset foreign worker quota tightening impacts. |
| Blockchain Traceability Pilot | Government-funded pharmaceutical segment pilots lower adoption barriers for customs brokerage automation across ASEAN trade corridors. |
| Cold Chain Facility Expansion | Bonded temperature-validated storage near Changi captures premium rents from biologics export growth and agricultural consolidation demand. |
Research Methodology
The analysis maps transportation, warehousing, freight forwarding, and distribution sub-sectors, each validated through terminal operations directors, pharmaceutical supply chain managers, customs brokerage leads, and e-commerce fulfillment operators. Primary interview intelligence triangulates against secondary sources including Maritime and Port Authority regulatory filings, Land Transport Authority emissions enforcement records, Enterprise Singapore grant disbursement databases, and ASEAN trade documentation standardization protocols. Bottom-up service provider revenue estimates reconcile with top-down national logistics output metrics.
Assumptions held fixed include Maritime Singapore Green Initiative enforcement timelines and Tuas mega-port phased commissioning schedules, while oil price volatility and foreign worker permit policy trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled encompass service type, transportation mode, end-user vertical, and technology adoption tier alongside port zone geographic clustering. CAGRs derive from capacity utilization projections and automation investment cycle timing. Forecast inputs incorporate vessel size distribution shifts and pharmaceutical cold chain compliance cost curves.
Sensitivities concentrate around Ministry of Manpower permit policy revisions and ASEAN digital trade corridor implementation pace. Forecasts embed documented assumptions regarding infrastructure commissioning schedules and regulatory enforcement intensity. Macroeconomic contraction, accelerated electrification mandates, or autonomous vehicle technology breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market