
 China Local Courier Market | 2026-2036
China Local Courier Market Size, Share, and Industry Trends Forecast 2026-2036
China Local Courier Market Insights
Last-mile delivery worker availability is redrawing competitive boundaries across China's courier sector. JD Logistics sustains market position through captive warehousing and in-house fleet control across tier-one cities. ZTO Express anchors its network on automated sorting hubs that compress unit costs in high-volume corridors. YTO Express Group Co., Ltd. differentiates through rural penetration strategies that extend coverage into county-level markets.
China local courier services encompass parcel collection, sorting, and final-mile distribution operations typically completed within metropolitan or provincial boundaries, utilizing hub-and-spoke networks with same-day or next-day service level commitments. These services function as critical infrastructure connecting e-commerce sellers, manufacturers, and retail endpoints to end consumers. Express delivery commands the dominant revenue share due to premium pricing on speed-guaranteed shipments, while same-day delivery represents the fastest-expanding segment driven by grocery and pharmaceutical urgency. E-commerce customers generate the highest volume throughput, though small business accounts yield superior per-package margins through contractual pricing structures.
SAMR enforces service quality standards and consumer protection rules that shape pricing transparency and complaint resolution protocols across the sector. The MIIT coordinates drone delivery pilot zones and autonomous vehicle testing corridors that redefine permissible operating modes. GB standards for packaging recyclability and emissions thresholds progressively tighten compliance requirements. Stakeholders must weigh fleet electrification timelines against autonomous delivery scale economics as regulatory sandboxes expand.
Market Dynamics
Live-streaming commerce volumes are compressing delivery windows across China's courier networks, forcing operators to reconfigure hub-and-spoke infrastructure around same-day density corridors rather than traditional next-day batch processing.
Growth Catalysts
- GB standards for packaging recyclability:MIIT-mandated green logistics timelines are accelerating electric vehicle fleet conversions among tier-one operators, creating compliance-driven hardware refresh cycles.
- Live-streaming commerce:Real-time sales events generate unpredictable parcel surges that reward networks with elastic sorting capacity and dynamic route optimization systems.
- Yangtze River Delta corridor:Same-day delivery density in Shanghai-Hangzhou-Suzhou clusters creates economies of scale that subsidize rural network extension.
Market Restraints
- Last-mile labor availability:Urban delivery worker shortages in tier-one cities constrain peak-season capacity expansion regardless of infrastructure investment.
- Automated sorting capex concentration:High-throughput hub deployment requires capital commitments that favor operators with captive cash flows over asset-light competitors.
- County-level route economics:Sparse return-trip density in rural penetration zones forces subsidized outbound pricing that compresses network-wide margins.
Strategic Opportunities
- Drone delivery pilot zones:MIIT-coordinated autonomous corridor testing in designated airspace creates first-mover regulatory advantages for compliant operators.
- Pharmaceutical cold chain:Temperature-controlled same-day urgency in therapeutic distribution commands premium pricing unavailable to ambient parcel segments.
- County-level consolidation:Underserved rural markets beyond county boundaries offer volume aggregation points before competitors achieve comparable coverage depth.
Industry Challenges
- Dynamic route algorithm talent:Scarcity of operations research specialists capable of real-time dispatch optimization limits network efficiency gains from hardware investments.
- SAMR complaint resolution protocols:Service quality enforcement creates operational friction requiring dedicated compliance infrastructure that smaller operators struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Local Courier Market |
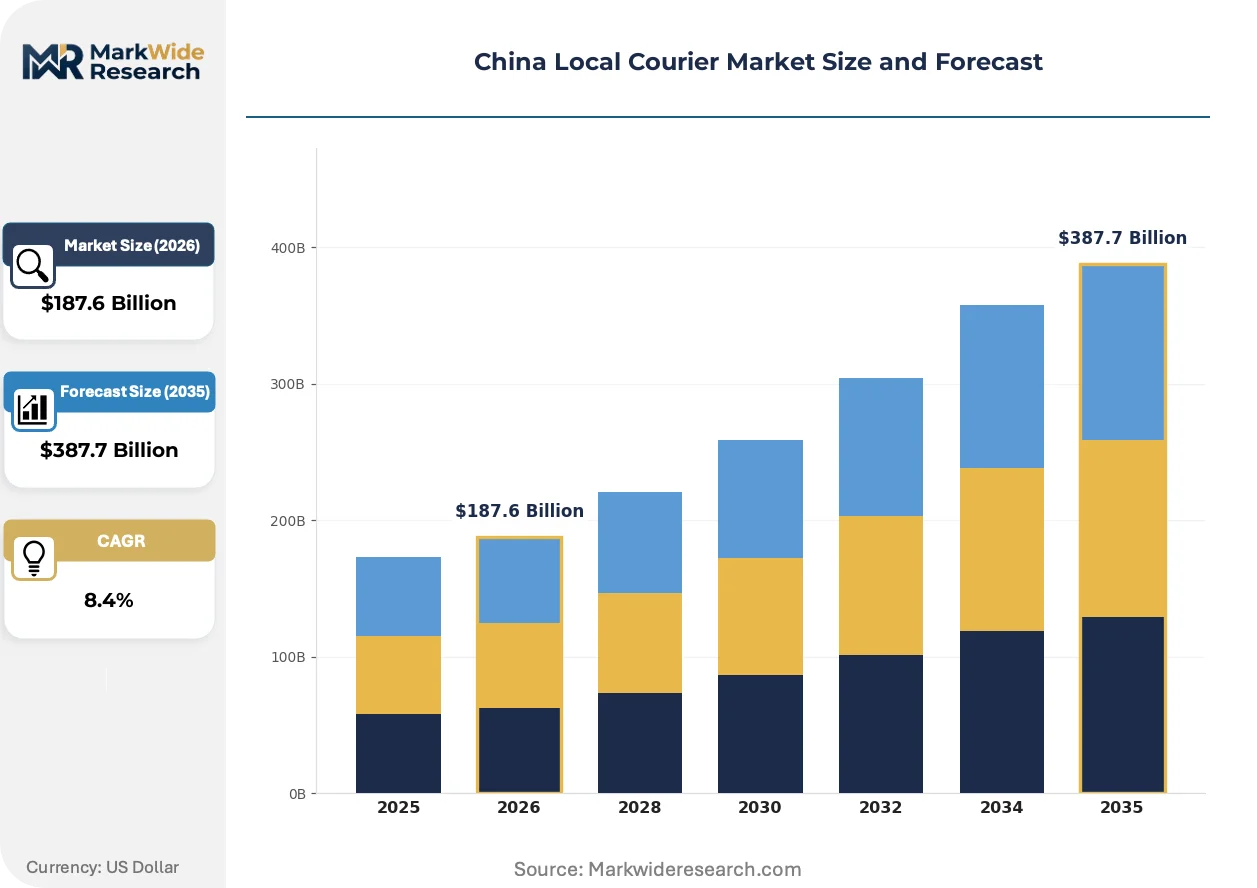
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Delivery, Next-Day Delivery, Scheduled Delivery Customer Type: Consumers, Small Businesses, E-commerce, Corporations Technology: Mobile Apps, GPS Tracking, Automation, Route Optimization Delivery Mode: Bicycle Courier, Motorcycle Courier, Van Transport, Drone Delivery |
| Companies Covered | S.F. Holding Co., Ltd., JD Logistics, YTO Express Group Co., Ltd., ZTO Express, STO Express Co., Ltd., Yunda Express, China Post, Deppon Logistics Co., Ltd., Best Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Local Courier Market Trends and Innovations
Autonomous vehicle testing corridors and electric fleet mandates are rewriting capital allocation priorities across Chinese courier networks, separating operators with captive technology development from those dependent on vendor solutions.
Autonomous delivery pods operating within MIIT-designated testing corridors are displacing human-staffed vehicles for fixed-route B2B distribution between sorting hubs and enterprise clients. JD Logistics and ZTO Express have deployed pilot fleets across designated Shanghai and Suzhou zones, compressing labor cost exposure in high-frequency corridor movements. The technology is displacing third-party logistics contracts for predictable, high-volume routes where geofenced operation limits liability exposure.
GB standards for packaging recyclability and emissions thresholds are tightening compliance windows for fleet operators, with MEE enforcement timelines accelerating electric vehicle conversion mandates. Operators face stranded asset risk in diesel fleet holdings as provincial implementation varies across compliance deadlines. Express delivery segments with premium pricing power absorb compliance costs more readily than economy-tier services competing on unit cost.
Grocery and pharmaceutical urgency is compressing delivery window expectations from next-day to same-day across tier-one urban markets. E-commerce platforms are unbundling logistics services from marketplace commissions, forcing courier operators to negotiate direct contracts with high-volume sellers. This shift is most visible in Shanghai and Hangzhou, where fresh food live-streaming events generate demand spikes that reward networks with dedicated cold-chain capacity and dynamic labor pooling.
China Local Courier Market Segmentation
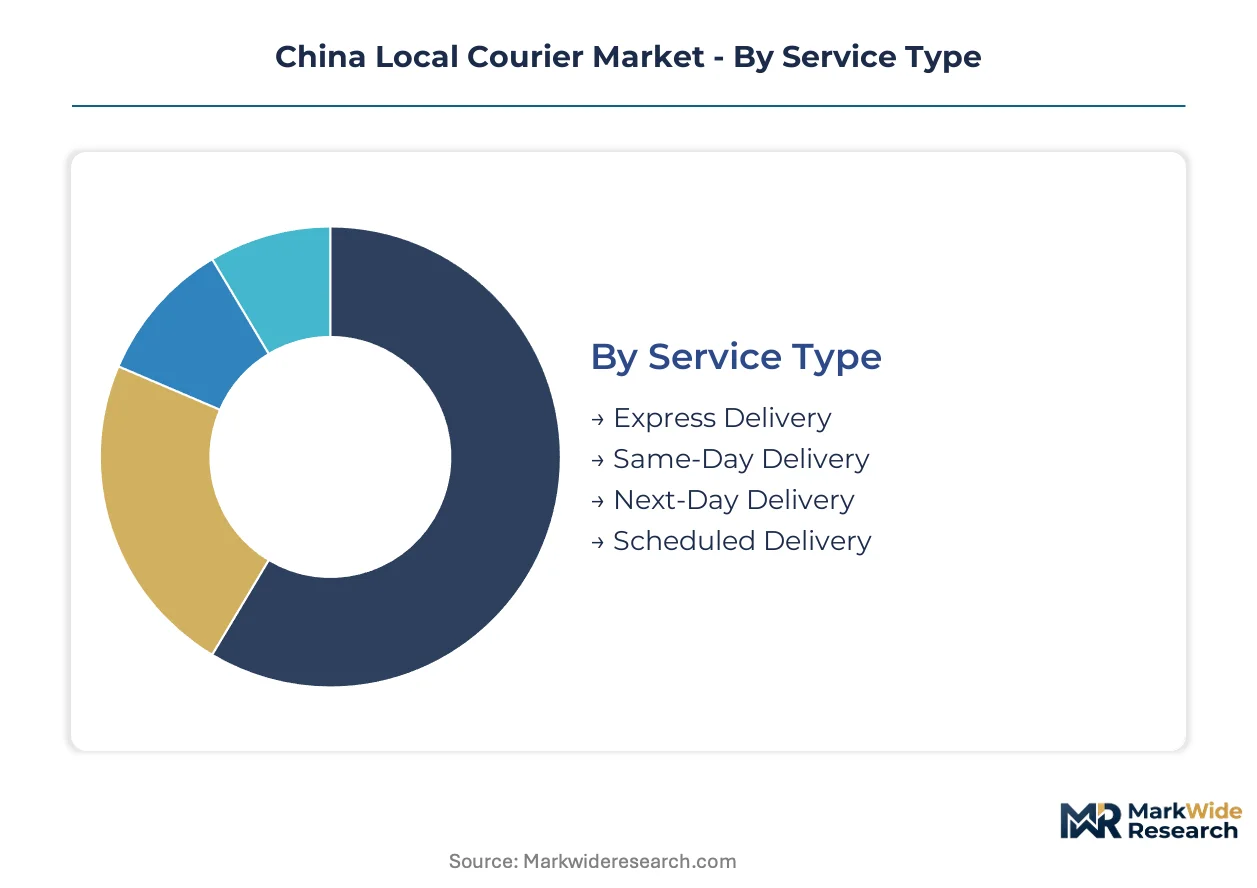
Segmentation in China's local courier market reveals how service tiers align with distinct channel economics and infrastructure requirements. Express and same-day segments concentrate in dense urban corridors where hub-and-spoke density justifies premium positioning, while scheduled and next-day services extend reach into cost-sensitive peripheral markets.
Service Type:
Express delivery commands the highest revenue per parcel through speed-guaranteed commitments, while same-day services concentrate in grocery and pharmaceutical urgency channels where delivery windows compress below four hours.
- Express Delivery:Premium-priced shipments with guaranteed transit times under 24 hours dominate corporate document flows and high-value e-commerce corridors. MIIT-designated autonomous vehicle testing zones in Shanghai and Suzhou enable operators to reduce labor exposure on fixed hub-to-hub movements.
- Same-Day Delivery:Compressed fulfillment windows driven by live-streaming commerce surges require dynamic labor pooling and dedicated cold-chain capacity. Yangtze River Delta clusters generate sufficient order density to sustain sub-four-hour service levels at unit costs below national averages.
- Next-Day Delivery:Batch-processed parcels moving through overnight sorting cycles serve price-sensitive SME accounts with predictable volume patterns.
- Scheduled Delivery:Appointment-based windows for bulky goods and B2B freight align with manufacturing procurement calendars rather than consumer impulse cycles.
By volume, next-day delivery leads through e-commerce standard shipping. By growth pace, same-day delivery is climbing the fastest as grocery platforms expand cold-chain coverage.
Customer Type:
Margin structures diverge sharply across customer categories, with contractual B2B accounts yielding superior per-package economics compared to fragmented consumer volumes.
- E-commerce:Platform-integrated sellers generate the highest absolute parcel throughput, though unbundling of logistics commissions is forcing direct contract negotiations that compress operator margins.
- Corporations:Enterprise accounts with centralized procurement and predictable routing patterns command dedicated fleet allocation and volume-based pricing tiers.
- Small Businesses:Merchant accounts on marketplace platforms balance volume scale with sufficient pricing power to sustain mid-tier service levels.
- Consumers:Individual senders represent the most price-elastic demand pool, concentrated in document and gift segments with minimal loyalty stickiness.
By revenue concentration, e-commerce dominates. By margin per shipment, corporations maintain the strongest position.
Technology:
Technology deployment separates operators with captive development capabilities from those dependent on vendor solutions, particularly in real-time dispatch systems.
- Route Optimization:Dynamic algorithmic dispatch compresses last-mile costs in high-density corridors where traffic variability demands sub-minute recalculation.
- Automation:High-throughput sorting hubs with robotic parcel handling reduce unit labor exposure in volume spikes generated by live-streaming events.
- Mobile Apps:Consumer-facing interfaces consolidate booking, tracking, and payment functions while generating behavioral data for demand forecasting.
- GPS Tracking:Real-time location transparency supports SAMR-mandated service quality documentation and complaint resolution protocols.
By capital intensity, automation absorbs the largest share. By deployment velocity, route optimization is gaining share fastest.
Delivery Mode:
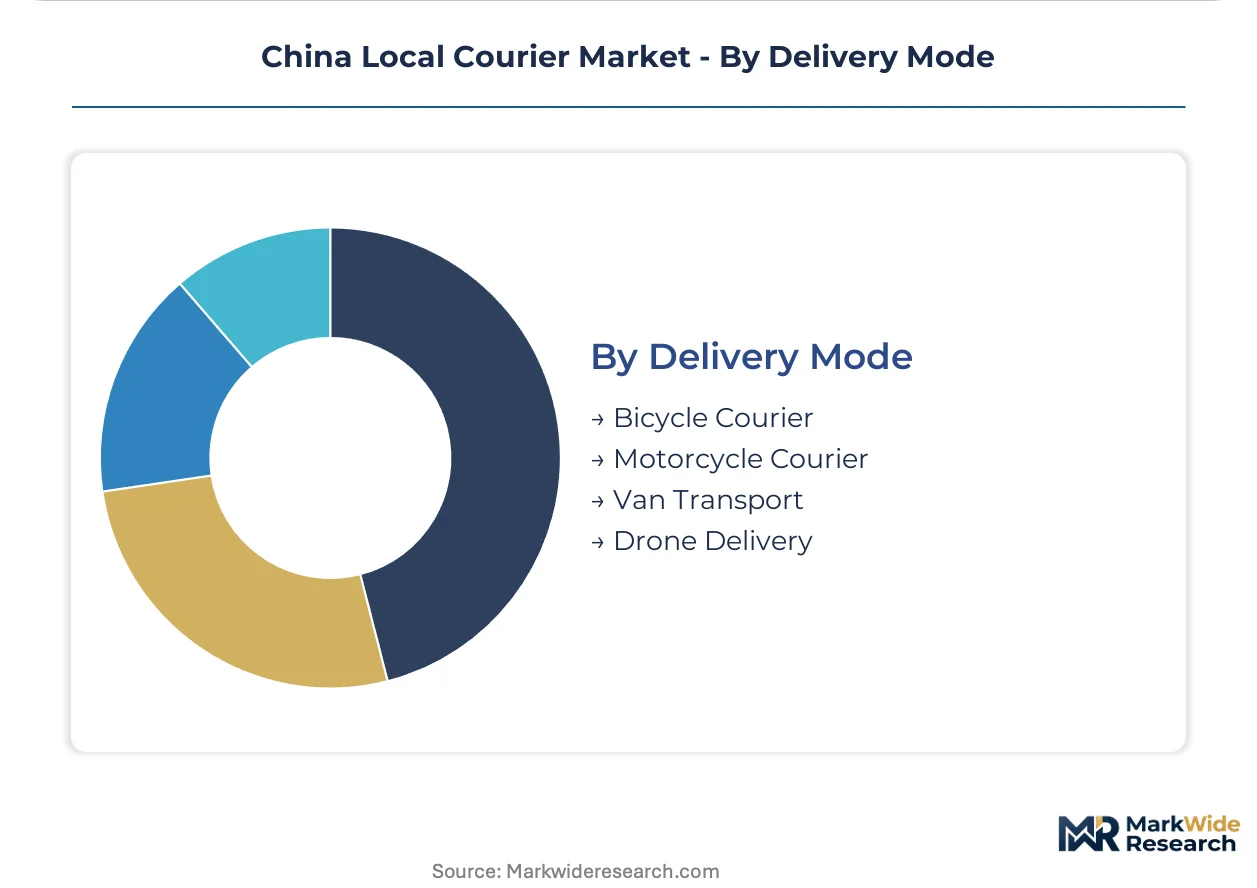
Fleet composition reflects regulatory pressure from MEE emissions mandates and MIIT green logistics timelines, with electrification timelines varying by vehicle class.
- Van Transport:Diesel-to-electric conversion cycles dominate capital allocation for tier-one operators, with stranded asset risk concentrated in older fleet holdings.
- Motorcycle Courier:Two-wheel electric vehicles serve as the primary last-mile modality in dense urban cores where parking constraints eliminate van economics.
- Bicycle Courier:Human-powered final delivery persists in historic districts and pedestrian zones where motorized access faces municipal restrictions.
- Drone Delivery:Autonomous aerial systems operate within MIIT-designated pilot corridors, displacing ground transport for predictable B2B hub movements.
By fleet size, motorcycle couriers dominate. By regulatory investment priority, van electrification is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Same-day delivery premiums in Shanghai command 40% higher unit economics than comparable services in inland provinces, creating a pricing-power asymmetry that subsidizes network extension into lower-density corridors.
Yangtze River Delta
Live-streaming commerce surges from Hangzhou and Suzhou generate parcel volumes that justify dedicated cold-chain infrastructure and dynamic labor pooling. MIIT-designated autonomous vehicle testing corridors in Shanghai enable pilot deployments of hub-to-hub autonomous delivery pods. Same-day density in the Shanghai-Hangzhou-Suzhou cluster reaches peak intensity, with operators achieving sub-four-hour fulfillment windows at unit costs below national averages.
Pearl River Delta
Cross-border e-commerce integration through Shenzhen and Guangzhou drives express delivery demand for time-sensitive manufacturing components and consumer electronics. GB standards for packaging recyclability tighten compliance timelines for fleet operators serving the manufacturing belt. Dongguan and Foshan industrial zones concentrate B2B scheduled delivery contracts tied to just-in-time procurement calendars.
Beijing-Tianjin-Hebei
Pharmaceutical cold-chain urgency from Beijing's therapeutic distribution hubs commands premium pricing unavailable to ambient parcel segments. SAMR service quality enforcement creates operational friction requiring dedicated compliance infrastructure. The Tianjin port corridor anchors scheduled delivery networks for bulky manufacturing inputs serving northern industrial zones.
Sichuan-Chongqing
County-level market penetration strategies extend coverage into western China's underserved rural markets beyond municipal boundaries. MEE provincial implementation of emissions mandates varies across compliance deadlines, creating stranded asset risk in diesel fleet holdings. Chengdu's logistics parks function as volume aggregation points before competitors achieve comparable coverage depth in the western interior.
Shandong Peninsula
Agricultural product live-streaming from Weifang and Yantai generates seasonal parcel surges that reward networks with elastic sorting capacity. Dual carbon goals accelerate electric vehicle conversion mandates for operators serving the peninsula's manufacturing and export processing zones. Qingdao's port infrastructure supports scheduled delivery consolidation for bulky freight moving through northern maritime corridors.
China Local Courier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's courier sector. The market structure consolidates around tier-one operators with captive infrastructure, while mid-tier competitors compete on rural penetration and specialized verticals. Three strategic archetypes dominate: integrated logistics platforms with warehousing control, hub-and-spoke specialists with automated sorting scale, and rural network extenders with county-level coverage depth. Competitive moves concentrate on fleet electrification timelines and autonomous delivery pilot zone access.
Among integrated logistics platforms, JD Logistics exemplifies captive warehousing and in-house fleet control across tier-one cities. ZTO Express and YTO Express Group Co., Ltd. occupy positions within the hub-and-spoke and rural extension archetypes respectively, with the former anchoring automated sorting scale in high-volume corridors and the latter representing county-level market penetration strategies. These three operators collectively illustrate the strategic segmentation separating technology-intensive urban operations from cost-optimized rural coverage.
| Leading Market Players |
|---|
| S.F. Holding Co., Ltd. |
| JD Logistics |
| YTO Express Group Co., Ltd. |
| ZTO Express |
| STO Express Co., Ltd. |
| Yunda Express |
| China Post |
| Deppon Logistics Co., Ltd. |
| Best Inc. |
| Others |
Pricing and Supply Chain Analysis
Volume-based contractual offtakes between e-commerce platforms and tier-one operators lock in multi-year capacity reservations that stabilize unit economics while exposing carriers to margin compression during live-streaming demand surges. These arrangements concentrate pricing power with high-volume senders in the Yangtze River Delta corridor, where same-day density subsidizes network-wide cost structures.
Pricing Analysis
Shanghai-Hangzhou-Suzhou same-day premiums run 40% above inland province rates, creating geographic arbitrage that operators exploit to cross-subsidize rural extensions. Pricing stratifies across express, same-day, next-day, and scheduled tiers, with speed guarantees and cold-chain certification commanding the widest spreads. Cost compression in economy-tier segments is intensifying because e-commerce platforms unbundle logistics commissions and force direct contract negotiations. Small business accounts on marketplace platforms exhibit the highest price sensitivity, while pharmaceutical distributors demonstrate the lowest due to therapeutic urgency requirements.
Supply Chain Analysis
Sorting hub inventory cycles compress to under four hours during peak live-streaming events, forcing just-in-time labor pooling and elastic capacity activation. Electric vehicle manufacturing concentrates in China, South Korea, and Japan, with battery cell supply drawing from domestic CATL and BYD facilities alongside Korean LG Energy Solution imports. Stranded asset risk in diesel fleet holdings threatens operators with MEE compliance deadline mismatches across provincial implementations. Distribution runs through hub-and-spoke networks with automated sorting centers feeding last-mile motorcycle courier pools in dense urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce platform consolidation is shifting buyer power toward a shrinking pool of high-volume accounts capable of dictating contract terms across multiple carrier networks.
For Market Incumbents: Fortify captive warehousing positions in tier-one cities through automated sorting scale investments that preserve unit cost advantages against asset-light competitors. Accelerate electric fleet conversion timelines ahead of MEE provincial deadlines to avoid stranded asset exposure. Prioritize MIIT autonomous vehicle testing corridor access in Shanghai and Suzhou to secure regulatory first-mover positioning. For New Entrants and Emerging Players: Lead with county-level consolidation strategies in Sichuan-Chongqing western corridors where coverage gaps persist beyond municipal boundaries. Target pharmaceutical cold-chain urgency segments in Beijing-Tianjin-Hebei where premium pricing sustains newcomer margins. Deploy dynamic route optimization technology as the primary go-to-market differentiator against hub-and-spoke incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward integrated logistics platforms with captive warehousing control and demonstrated same-day density economics in Yangtze River Delta clusters. Long-term viability over the coming decade hinges on fleet electrification execution and autonomous delivery pilot zone access rather than pure volume scale. Monitor MIIT expansion of drone delivery corridor designations as the critical inflection signal for regulatory-enabled technology displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | MEE compliance deadlines and MIIT green logistics timelines accelerate hardware refresh cycles across diesel holdings. |
| Autonomous Delivery Deployment | MIIT-designated testing corridors in Shanghai and Suzhou enable pilot fleets that compress labor cost exposure. |
| Cold-Chain Infrastructure Expansion | Pharmaceutical and grocery urgency segments command premium pricing unavailable to ambient parcel services. |
| County-Level Network Extension | Underserved rural markets beyond municipal boundaries offer volume aggregation before competitors achieve comparable depth. |
| Dynamic Route Optimization Investment | Real-time dispatch algorithms address scarcity of operations research talent limiting network efficiency gains. |
Research Methodology
Cross-validation between primary interviews with logistics operations directors, e-commerce platform procurement leads, last-mile fleet managers, and SAMR regulatory affairs specialists anchors the qualitative findings against secondary validation. Trade customs data, MIIT green logistics policy filings, operator SEC disclosures, and provincial MEE implementation notices provide quantitative grounding. Bottom-up parcel volume modeling and top-down market sizing triangulate across independent estimation approaches.
Sensitivity analysis around live-streaming commerce growth trajectories and electric vehicle conversion cost curves shapes the analytical framework across the projection horizon. Segmentation dimensions include service type, customer category, technology deployment, and delivery mode, with regional density corridors modeled as a courier-specific dimension. CAGRs derive from trend extrapolation adjusted for regulatory inflection points, incorporating fleet electrification timelines and autonomous delivery scale economics as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce platform consolidation or accelerated MIIT autonomous corridor expansion would require recalibration. Forecasts reflect assumptions regarding labor availability in tier-one cities and provincial MEE compliance synchronization. Revision becomes warranted when last-mile worker shortage severity or drone delivery regulatory authorization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Europe Chemical Logistics Market