
 GCC Soundbar Market | 2026-2036
GCC Soundbar Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Soundbar Market Intelligence
Saudi Arabia's expanding electronics manufacturing zone near Riyadh is fragmenting traditional import-dependent supply routes for GCC audio equipment. Samsung Electronics leverages its regional distribution hubs to sustain premium positioning across Gulf retail networks. Sony Corporation anchors its competitive stance through specialized acoustic engineering for high-heat desert climates. LG Electronics differentiates via integrated smart home protocols that dominate UAE residential specifications.
A soundbar constitutes a loudspeaker enclosure designed to project audio from a wide, elongated cabinet, typically housing multiple drivers including tweeters, mid-range cones, and dedicated subwoofer channels with power ratings spanning 100 to 500 watts for residential applications. The device serves primarily to deliver cinematic audio reproduction in space-constrained living environments where discrete multi-speaker installations prove impractical. Active soundbars with built-in amplification and wireless subwoofer pairing capture the dominant margin pool across Gulf markets due to simplified installation requirements. Dolby Atmos-enabled configurations represent the fastest-expanding technology segment as broadcasters and streaming platforms in the UAE and Saudi Arabia expand immersive content libraries. Smart soundbars integrating voice assistants and multi-room Wi-Fi streaming are displacing basic Bluetooth models in premium residential channels across Doha and Kuwait City.
SASO's energy efficiency labeling requirements and UAE's ECAS conformity schemes shape product certification costs and import clearance timelines for soundbar manufacturers serving the Gulf. TRAI-equivalent spectrum coordination across GCC telecom regulators affects wireless audio transmission standards, particularly for Wi-Fi and Bluetooth protocol implementations in multi-device households. Stakeholders must monitor evolving e-waste directives under the UAE's circular economy policy framework and Saudi Arabia's expanding consumer protection enforcement to anticipate compliance-driven product redesign cycles and channel restructuring obligations.
Market Dynamics
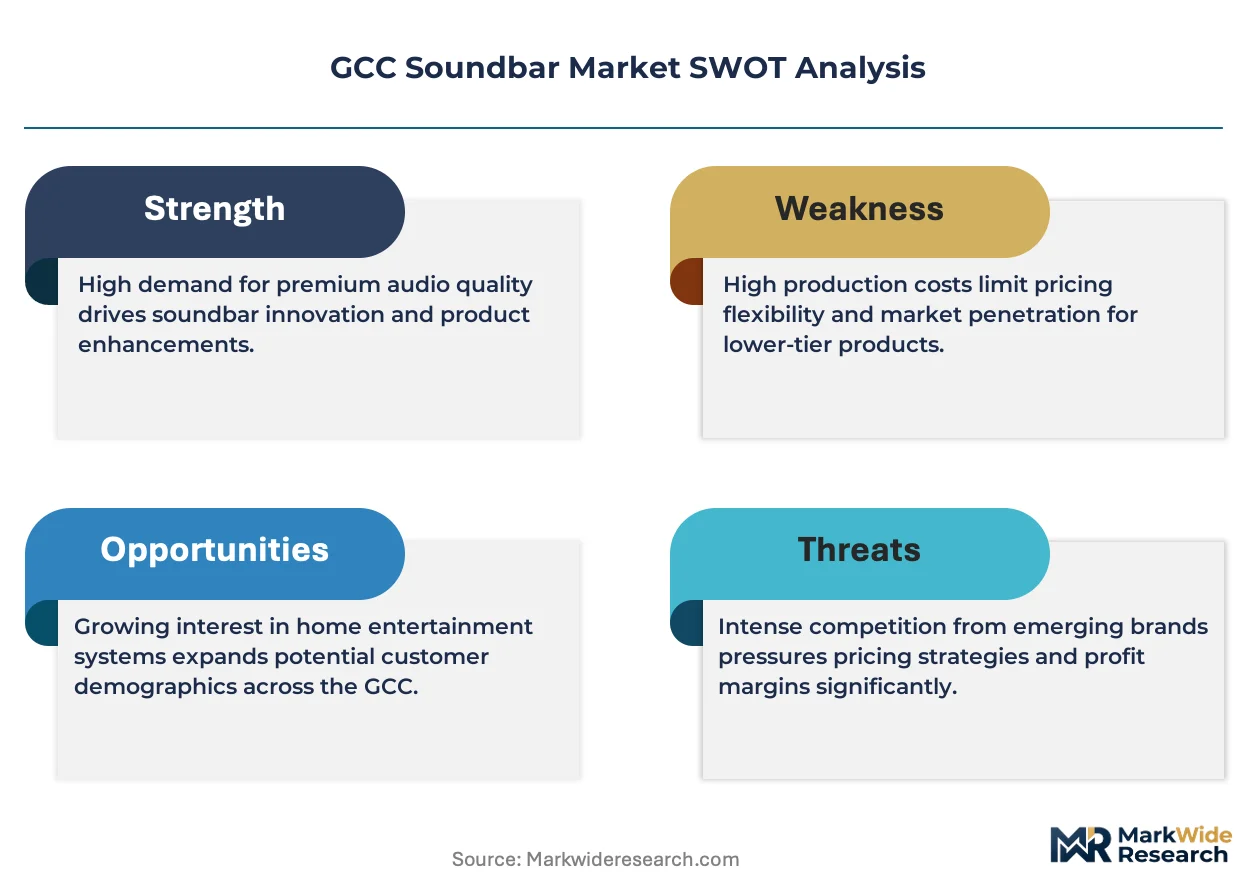
Dolby Atmos-enabled configurations are compressing replacement cycles across GCC residential channels as streaming platforms in the UAE and Saudi Arabia expand immersive content libraries. This technology migration is redistributing margin pools toward acoustic engineering capabilities and away from basic Bluetooth assembly.
Growth Catalysts
- Smart Home Integration Mandates:UAE building codes in Dubai and Abu Dhabi now specify multi-room audio infrastructure in premium residential developments, pulling soundbar specifications into architectural planning stages.
- SFDA-aligned Consumer Protection:Saudi Arabia's expanding enforcement of product quality standards is filtering low-grade imports and elevating certified manufacturer margins.
- Immersive Content Proliferation:Regional broadcasters and streaming services are expanding Atmos-encoded libraries, creating hardware refresh pressure in Doha and Kuwait City households.
Market Restraints
- Driver Component Concentration:High-performance acoustic transducers depend on a narrow supplier base concentrated in East Asian manufacturing clusters, exposing GCC assemblers to input volatility.
- Certification Cost Escalation:SASO energy efficiency labeling and UAE ECAS conformity schemes are extending import clearance timelines and compressing working capital cycles for distributors.
- Wireless Protocol Fragmentation:TRAI-equivalent spectrum coordination gaps across GCC telecom regulators are creating interoperability friction for Wi-Fi and Bluetooth implementations in multi-device households.
Strategic Opportunities
- Kuwait and Bahrain Penetration:These markets exhibit lower smart home audio saturation than the UAE or Saudi Arabia, offering first-mover positioning for integrated protocol specialists.
- E-Waste Circular Economy:UAE's circular economy policy framework and Saudi Arabia's emerging producer responsibility mandates are creating refurbishment and take-back service revenue streams.
- Voice Assistant Convergence:Multi-room Wi-Fi streaming paired with localized Arabic-language voice control is opening specification wins in premium Riyadh and Jeddah villa installations.
Industry Challenges
- Acoustic Engineering Talent Scarcity:GCC universities produce limited graduates in transducer design and thermal management for desert climate operation, forcing manufacturers to import specialized personnel.
- Certification Timeline Compression:SASO's tightening compliance thresholds are accelerating product redesign cycles while shortening market entry windows for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Soundbar Market |
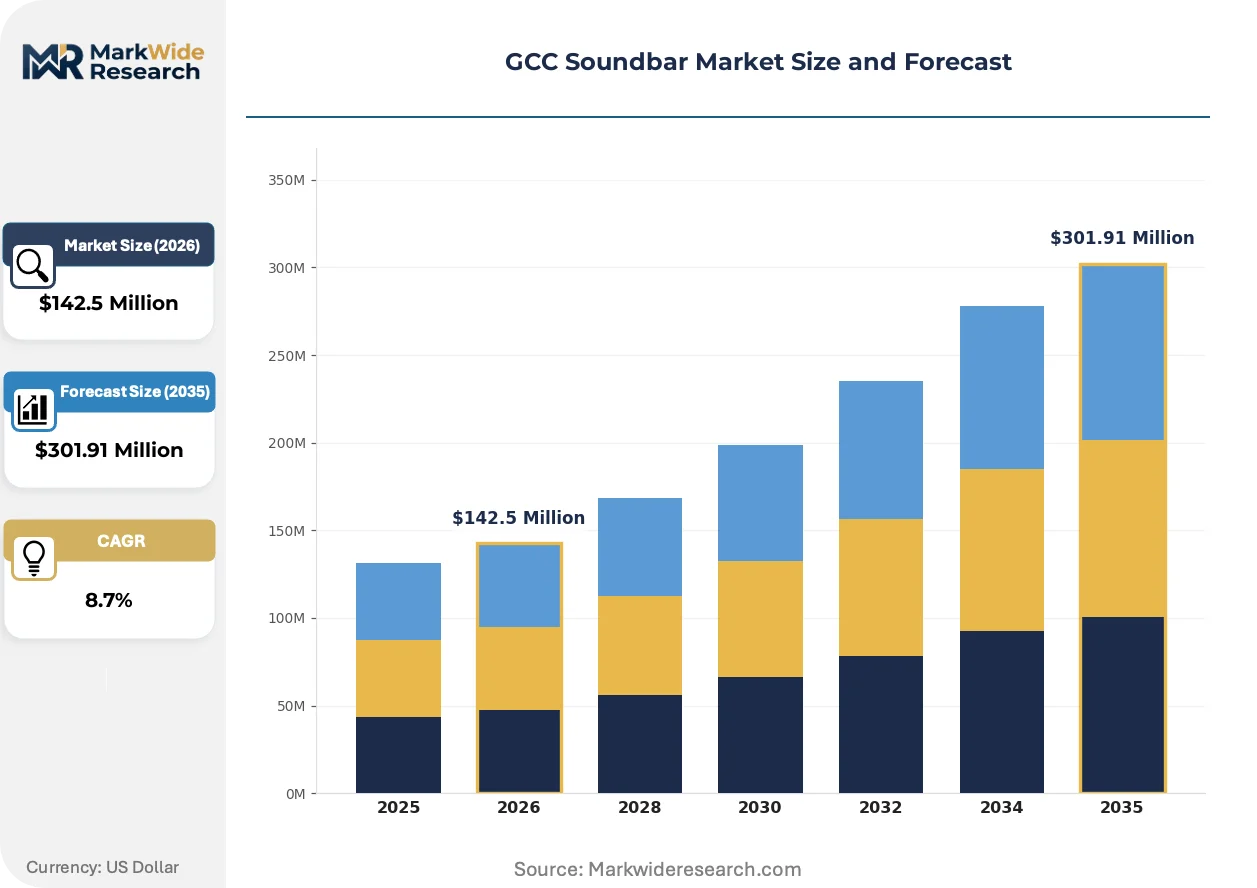
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Soundbars, Passive Soundbars, Soundbases, Smart Soundbars Technology: Dolby Atmos, DTS:X, Bluetooth, Wi-Fi End User: Residential Users, Commercial Spaces, Cinemas, Gaming Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Specialty Stores |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Bose Corporation, Yamaha Corporation, Hisense Home Appliance Group Co. Ltd, Koninklijke Philips NV, Panasonic Corporation, Sennheiser Electronic GmbH & Co. KG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Soundbar Market Strategic Shifts & Innovations
Audio reproduction technology is digitizing signal processing pathways while regulatory frameworks harden efficiency mandates. These forces are compressing the competitive set toward integrated platform providers and away from standalone hardware assemblers.
Dolby Atmos object-based audio rendering is digitizing how Gulf households experience cinematic sound. Saudi villa owners and UAE apartment developers are specifying height-channel configurations at accelerating rates. This capability shift is digitizing traditional 5.1 discrete speaker markets into compact soundbar form factors with virtualized surround processing.
SASO energy efficiency mandates are tightening compliance thresholds for consumer electronics imports into Saudi Arabia. Manufacturers must now submit third-party testing documentation covering standby power and active consumption metrics. Premium product tiers are absorbing these certification costs while economy segments face margin compression or exit pressure.
Smart home audio procurement is consolidating around integrated platform specifications rather than standalone device selection. UAE systems integrators and Saudi contracting firms are bundling soundbar deployment with whole-home automation contracts. This pattern is most visible in Dubai's high-rise residential towers where single-vendor protocols dominate installation standards.
GCC Soundbar Market Segmentation
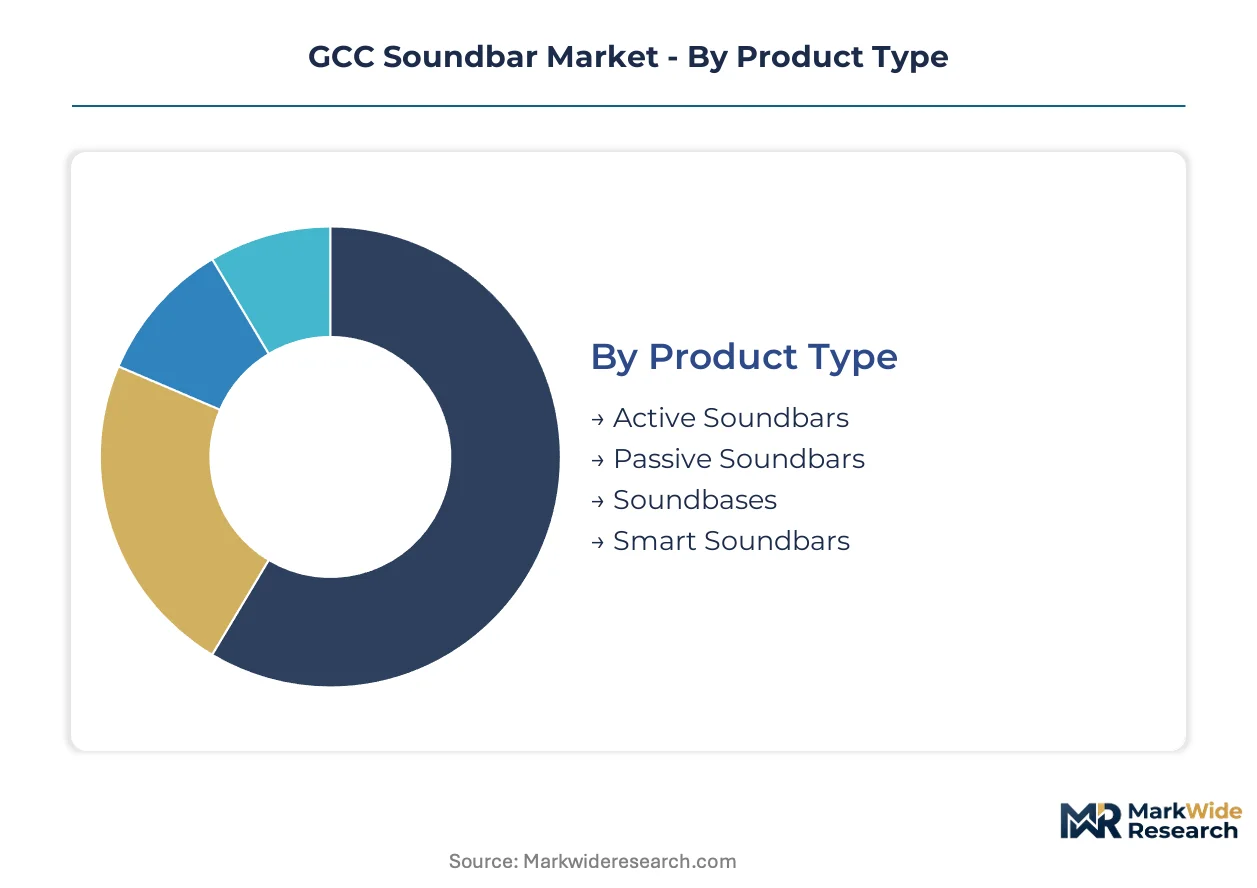
Soundbar procurement patterns across the GCC diverge sharply by installation complexity and post-purchase service requirements. Warranty fulfillment networks and on-site calibration demands reshape channel economics differently for each product configuration.
Product Type:
After-sales intensity varies dramatically across enclosure architectures, with integrated amplification systems requiring specialized technical support that passive configurations rarely demand.
- Active Soundbars:Built-in amplification eliminates external receiver dependency, simplifying installation for Saudi villa contractors and UAE apartment developers. Demand concentrates in Dubai's high-rise residential towers where space constraints and smart home integration mandates drive specification. Built-in wireless subwoofer pairing reduces cabling complexity but elevates firmware update and thermal management service calls.
- Smart Soundbars:Voice assistant integration and multi-room Wi-Fi streaming protocols embed these units deeply into whole-home automation ecosystems. Riyadh and Jeddah premium residential channels show accelerating specification as Arabic-language voice control matures. These configurations generate recurring service revenue through software updates and protocol compatibility maintenance.
- Passive Soundbars:Require external amplification, appealing to audiophile segments in Kuwait City and Doha seeking component upgrade flexibility.
- Soundbases:Flat enclosure designs suit television pedestal mounting, finding niche adoption in Bahrain's compact urban apartments.
By volume, Active Soundbars lead. By growth pace, Smart Soundbars is ahead.
Technology:
Certification costs and content ecosystem maturity stratify technology adoption across Gulf households with varying entertainment infrastructure investment levels.
- Dolby Atmos:Object-based audio rendering with height virtualization creates immersive soundfields from compact enclosures. UAE and Saudi streaming platform expansion drives hardware refresh cycles in premium residential segments. Height-channel configurations are displacing traditional 5.1 discrete speaker installations in new Riyadh villa construction.
- Bluetooth:Ubiquitous wireless pairing protocol dominates economy-tier procurement through supermarket and online retail channels. Basic connectivity without smart home integration meets budget-constrained demand in secondary GCC cities. Margin compression from protocol commoditization is accelerating manufacturer exit from standalone Bluetooth-only models.
- DTS:X:Competing immersive audio format with flexible speaker configuration requirements, gaining traction among gaming-oriented households in Doha.
- Wi-Fi:Multi-room streaming backbone for whole-home audio networks, specified increasingly by UAE systems integrators in bundled automation contracts.
By install base, Bluetooth leads. By specification momentum in premium channels, Dolby Atmos is expanding most quickly.
End User:
Usage intensity and acoustic environment constraints reshape product durability requirements and warranty claim patterns across customer categories.
- Residential Users:Space-constrained living rooms and bedrooms in Gulf urban centers drive compact form factor preference. Saudi villa owners and UAE apartment dwellers prioritize aesthetic integration with interior design schemes. Dust filtration and thermal management specifications are critical for desert climate reliability.
- Commercial Spaces:Hospitality venues and corporate lobbies in Dubai and Abu Dhabi require 24/7 operational durability and centralized control interfaces. Installation scale creates procurement leverage for property management groups.
- Cinemas:Small-format theater installations in Saudi entertainment zones adopt soundbar arrays for supplementary channel coverage.
- Gaming:Low-latency audio synchronization demands from console and PC gamers in Kuwait City and Manama drive specialized product variants.
By unit volume, Residential Users lead. By average transaction value, Commercial Spaces shows steepest expansion trajectory.
Distribution Channel:
Channel selection determines installation support depth and return handling complexity, with divergent working capital requirements for inventory financing.
- Electronics Stores:Physical demonstration environments and trained sales staff drive premium product conversion in Saudi Arabia's Riyadh and Jeddah retail corridors. Immediate technical consultation and warranty registration support reduce post-purchase friction. These outlets capture the dominant margin pool for Dolby Atmos configurations requiring explanation of height-channel virtualization.
- Online Retail:Price transparency and comparison shopping tools concentrate economy and mid-tier transactions. UAE and Saudi e-commerce platform logistics networks now support same-day delivery in metropolitan zones, compressing traditional electronics store foot traffic. Return rates exceed physical channels due to acoustic expectation mismatches in home environments.
- Specialty Stores:Home theater boutiques in Dubai's Mall of the Emirates and Riyadh's Riyadh Park serve enthusiast segments seeking audition facilities.
- Supermarkets:Impulse and gift purchases of compact Bluetooth models through hypermarket chains in Doha and Manama.
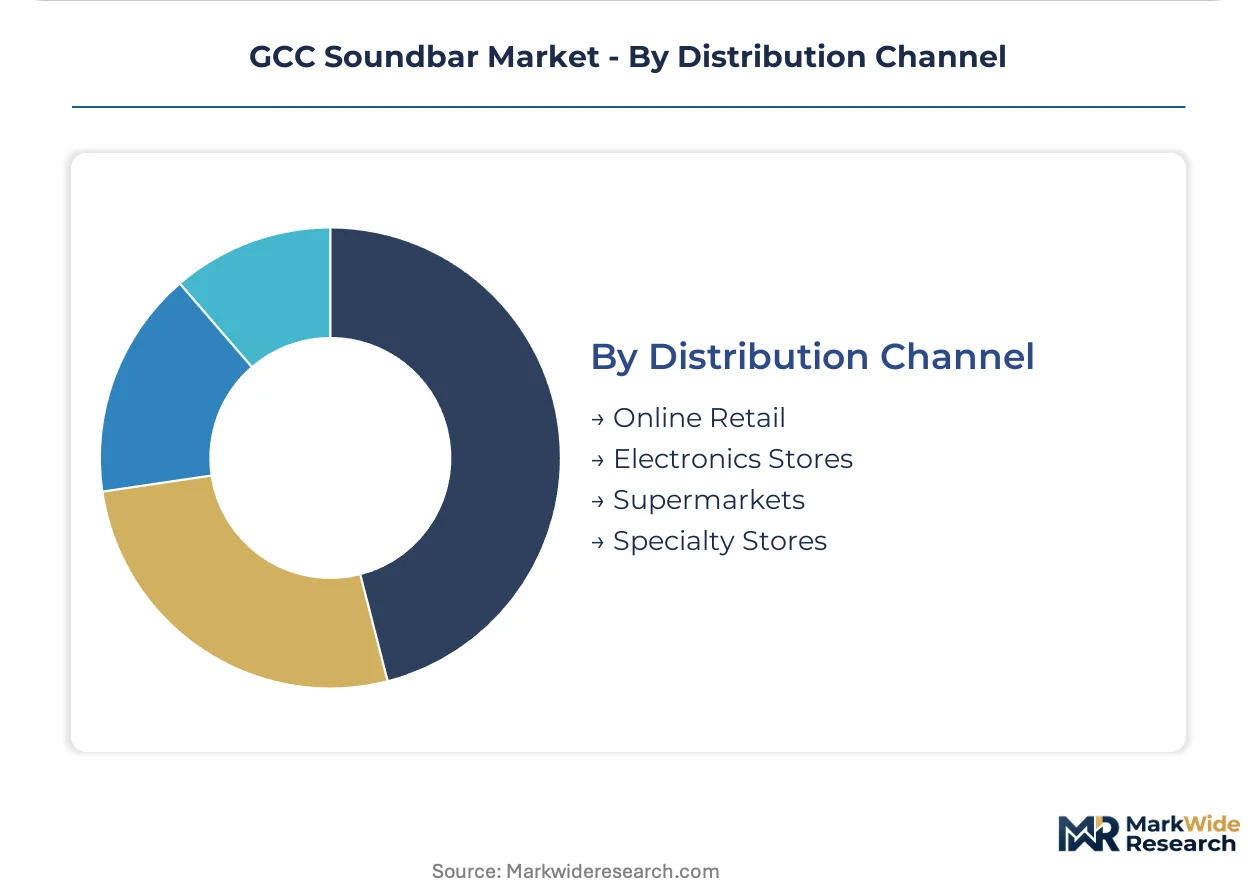
By transaction volume, Online Retail leads. By premium product mix and margin contribution, Electronics Stores is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the GCC diverge sharply between Saudi villa installations demanding immersive home theater configurations and UAE apartment developments prioritizing space-constrained smart integration. The six Gulf states exhibit distinct procurement rhythms shaped by real estate development cycles and regulatory enforcement intensity.
Saudi Arabia
Riyadh and Jeddah villa construction is specifying Dolby Atmos-enabled soundbar arrays at accelerating rates as entertainment infrastructure investment intensifies. SASO energy efficiency labeling mandates now require third-party testing documentation covering standby power metrics, extending import clearance timelines for distributors. The King Abdullah Economic City electronics manufacturing zone near Jeddah is fragmenting traditional import-dependent supply routes for audio equipment.
United Arab Emirates
Dubai and Abu Dhabi emirates lead Gulf smart home integration rates, with building codes now specifying multi-room audio infrastructure in premium residential towers. ECAS conformity schemes shape product certification costs and working capital cycles for importers serving the UAE market. Systems integrators in Dubai Marina and Downtown Dubai are bundling soundbar deployment with whole-home automation contracts.
Qatar
Doha households are refreshing hardware cycles as regional streaming platforms expand immersive content libraries, creating replacement pressure for basic Bluetooth models. The Qatar General Authority of Customs enforces conformity assessment procedures that parallel UAE ECAS frameworks. West Bay and The Pearl-Qatar residential clusters show concentrated specification of voice-integrated smart soundbars.
Kuwait
Kuwait City exhibits lower smart home audio saturation than UAE or Saudi counterparts, offering positioning opportunities for integrated protocol specialists. The Public Authority for Industry administers quality mark requirements for consumer electronics imports. Salmiya and Sharq commercial districts concentrate electronics retail channels where premium product demonstration drives conversion.
Bahrain
Manama's compact urban apartments favor soundbase configurations suited to television pedestal mounting in space-constrained living environments. The Bahrain Standards and Metrology Directorate implements technical regulations aligned with GCC standardization frameworks. Seef Mall and City Centre Bahrain anchor retail traffic for mid-tier consumer electronics procurement.
GCC Soundbar Market Key Industry Players
Capability concentration sits with acoustic engineering specialists; scale advantage sits with diversified electronics conglomerates. The vendor base stratifies across three tiers: integrated smart home platform providers commanding premium specification channels, dedicated audio specialists defending enthusiast segments, and diversified consumer electronics manufacturers capturing volume through retail distribution networks. Dominant competitive moves include portfolio diversification into multi-room Wi-Fi streaming ecosystems and strategic partnerships with regional systems integrators for bundled automation contracts.
Within the diversified electronics tier, Samsung Electronics and LG Electronics anchor regional distribution strategies across Gulf retail networks. Sony Corporation exemplifies the acoustic engineering specialist archetype, occupying a position defined by climate-adapted product development. Hisense Home Appliance Group Co. Ltd represents the scale-driven manufacturing segment, sitting within competitive dynamics shaped by certification cost absorption capacity.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Bose Corporation |
| Yamaha Corporation |
| Hisense Home Appliance Group Co. Ltd |
| Koninklijke Philips NV |
| Panasonic Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Regulatory certification chokepoints at SASO and UAE ECAS frameworks determine both pricing tier spreads and supply chain shape across GCC soundbar procurement channels. These compliance thresholds force manufacturers to absorb third-party testing costs into premium product tiers while economy segments face margin compression or exit pressure.
Pricing Analysis
Price spreads between Dubai and Riyadh retail channels exceed those found in secondary GCC cities due to logistics fragmentation and certification timeline differentials. Three-tier pricing structure across premium, standard, and economy levels stratifies by Dolby Atmos capability, smart home protocol integration, and after-sales service bundling. Pricing pressure stems from SASO's tightening energy efficiency thresholds as manufacturers redesign products to meet standby power mandates. Residential villa contractors in Saudi Arabia show lowest price sensitivity due to specification-driven procurement, while supermarket Bluetooth model buyers in Doha exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor components for audio DSP chips limit flows from certain East Asian manufacturing clusters into GCC assembly operations. Acoustic transducer production concentrates in China, South Korea, and Vietnam, with high-performance driver units drawing from a narrow supplier base. Neodymium magnet dependencies and voice coil copper supplies face commodity price volatility amid energy transition demand competition. Distribution runs through Jebel Ali free zone hubs for UAE re-export, with direct Jeddah port clearance gaining share for Saudi-bound volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dolby Atmos content proliferation across regional streaming platforms constitutes a technological inflection reshaping GCC soundbar demand patterns. This disruption compresses replacement cycles and redistributes margin pools toward acoustic engineering capabilities.
For Market Incumbents: Insulate premium positioning by deepening backward integration into thermal management component supply and securing exclusive UAE systems integrator partnerships for bundled automation contracts. SASO's accelerating compliance timelines threaten working capital cycles for distributors lacking certification pre-clearance capabilities.
For New Entrants and Emerging Players: Kuwait City and Manama residential clusters offer underpenetrated smart home audio specification opportunities relative to Dubai and Riyadh saturation levels. Voice-integrated Wi-Fi streaming protocols with Arabic-language localization present the most penetrable wedge for first-mover positioning in these secondary markets.
For Investors and Strategic Acquirers: SASO's producer responsibility mandate expansion reshapes the acquisition landscape toward refurbishment and take-back service capabilities. Long-term viability favors targets with circular economy infrastructure and certified remanufacturing workflows. Monitor e-waste directive enforcement intensity as the signal indicating margin shift timing toward service-based revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| Dolby Atmos Certification Investment | Unlocks premium specification channels in Riyadh villa construction and Dubai high-rise developments. |
| Arabic Voice Assistant Integration | Captures smart home bundling opportunities with UAE systems integrators and Saudi contracting firms. |
| SASO Pre-Certification Partnership | Compresses import clearance timelines and reduces working capital drag for Saudi Arabia market entry. |
| Refurbishment Service Buildout | Aligns with UAE circular economy policy and Saudi emerging producer responsibility mandates. |
| Multi-Room Wi-Fi Protocol Development | Secures architectural specification wins in premium residential towers across Dubai Marina and Downtown Dubai. |
Research Approach
The analysis maps active soundbar, smart soundbar, passive soundbar, and soundbase sub-sectors, each validated through product managers at audio equipment manufacturers, procurement leads at UAE systems integrators, retail category buyers at Saudi electronics chains, and customs clearance specialists at Jebel Ali and Jeddah ports. Secondary sources include SASO technical regulation filings, UAE ECAS conformity assessment databases, Gulf customs trade records, and streaming platform content library disclosures. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Assumptions held fixed include current SASO energy efficiency labeling thresholds and UAE building code multi-room audio infrastructure mandates; variables tested include Dolby Atmos content library expansion rates and voice assistant localization maturity. Segmentation dimensions span product architecture, immersive audio technology, end-user category, and distribution channel. CAGRs derive from regression analysis against historical replacement cycle compression patterns and smart home penetration trajectories. Industry-specific inputs include thermal management specification requirements for desert climate operation and wireless protocol interoperability standards across GCC telecom regulatory frameworks.
The forecast holds incumbent behavior within observed patterns; aggressive certification pre-investment moves by mid-tier manufacturers or rapid e-waste mandate acceleration by Saudi regulators would shift outcomes beyond modeled ranges. Cross-checking against streaming platform content spend disclosures and real estate development permit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
4K Television Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market