
 Digital Cloud Picture Frame Market | 2026-2036
Digital Cloud Picture Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Cloud Picture Frame Market Insights
Cloud-based subscription services for remote content management is shifting the revenue model from hardware-only sales to recurring software streams. Aura leverages its proprietary mobile app ecosystem to lock in household users with automatic photo syncing. Nixplay sustains brand loyalty through family-oriented sharing features that reduce churn on its premium tiers. PhotoSpring Inc. differentiates by specializing in touch-enabled frames with parental control layers for educational deployments.
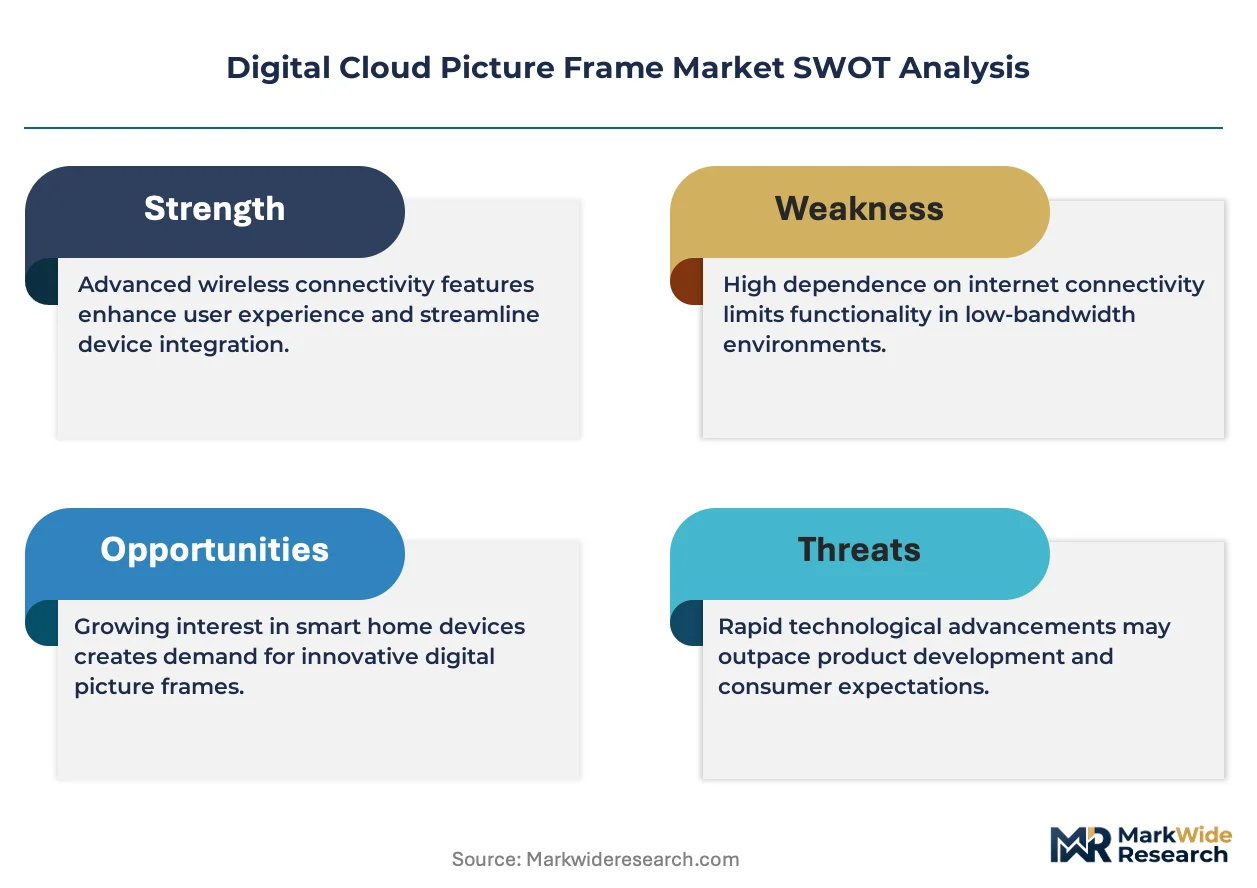
A digital cloud picture frame is a networked display device with integrated Wi-Fi or cellular connectivity, typically featuring IPS or TFT-LCD panels between seven and fifteen inches, designed to receive, store, and render digital images from remote servers without local file transfers. The device serves commercial and consumer markets by enabling real-time content updates across distributed display networks. Wi-Fi frames capture the largest installed base among connectivity segments due to their compatibility with existing residential and enterprise infrastructure. Cloud-enabled screens represent the fastest-expanding product category as businesses replace static signage with remotely programmable displays. Advertising usage scenarios command the deepest margin pools where hospitality and retail chains pay premium rates for programmatic content scheduling.
FCC equipment authorization governs radio frequency emissions for devices sold in the United States, while GDPR in Europe restricts biometric data collection from frames with facial detection features. The EU AI Act further classifies certain emotion-recognition capabilities as high-risk, forcing design teams to strip or rearchitect affected software modules. Stakeholders must monitor how fragmented data sovereignty rules across jurisdictions reshape cloud server placement and cross-border photo synchronization architectures.
Market Dynamics
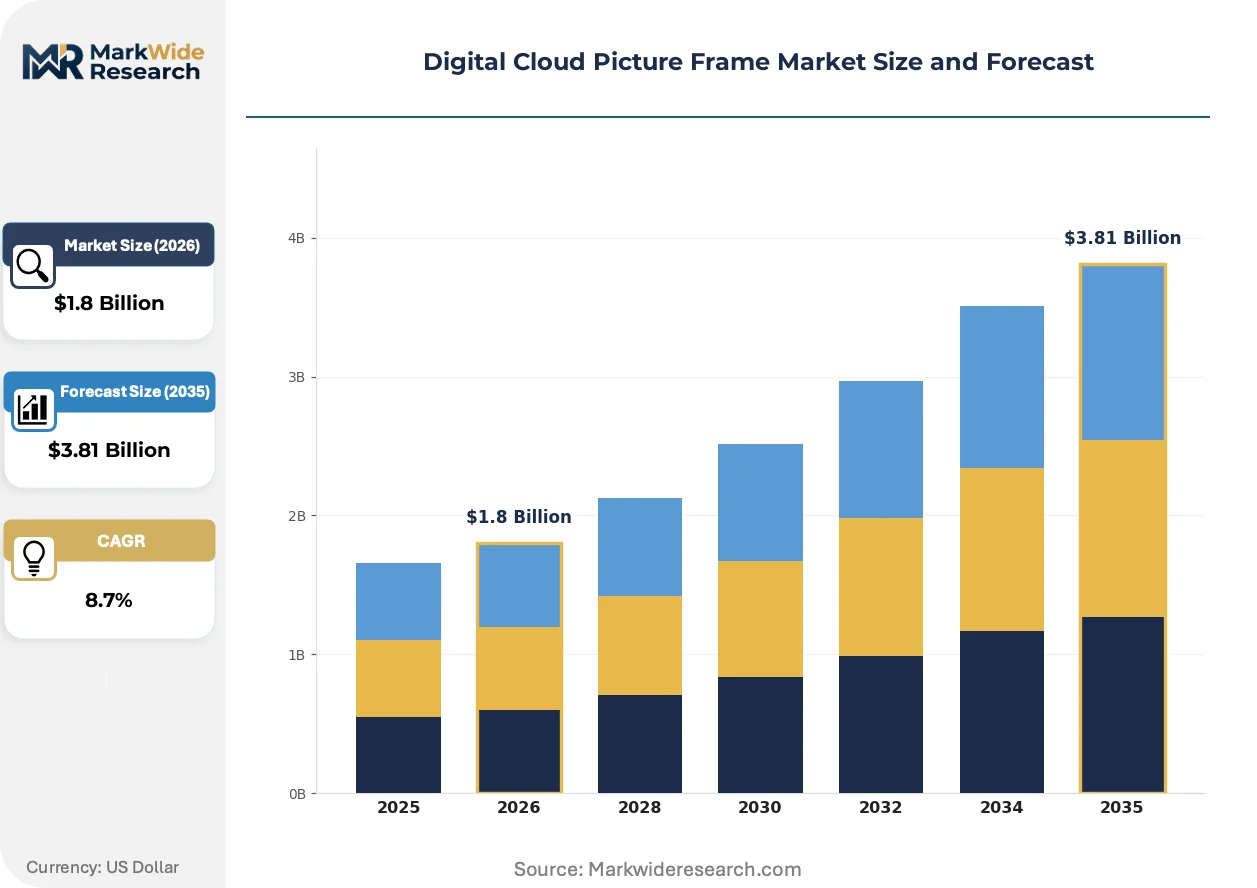
Cloud-enabled subscription revenue streams are displacing hardware-only sales models across the digital cloud picture frame value chain. This structural shift concentrates margin capture with platform operators who control remote content management infrastructure.
Growth Catalysts
- Hospitality Digital Signage Replacement:Hotel chains in Germany and France are retiring static lobby displays for programmable cloud-connected screens. This end-use vertical drives bulk procurement volumes.
- GDPR-Compliant Facial Recognition:The EU AI Act's biometric data protocols force design teams toward privacy-preserving architectures. Manufacturers who certify early capture institutional buyers.
- Cellular Connectivity Modules:Embedded LTE/5G radios eliminate Wi-Fi dependency for rural healthcare and field marketing deployments. This technology expands addressable geography beyond infrastructure-rich zones.
Market Restraints
- Display Panel Cost Volatility:IPS and TFT-LCD substrate prices fluctuate with semiconductor foundry capacity allocation. Asian panel suppliers concentrate 70% of global output.
- GDPR Cross-Border Data Friction:The regulation restricts cloud server placement for EU citizen photo synchronization. This forces redundant infrastructure investment.
- Smartphone Screen Substitution:Large-format phones with always-on displays compete for casual photo viewing use cases. This substitute compresses entry-tier frame pricing power.
Strategic Opportunities
- Educational Touch-Frame Deployments:K-12 institutions in the United States seek parental-controlled devices for classroom content distribution. This application remains underpenetrated relative to consumer households.
- EU Green Deal E-Waste Incentives:The framework subsidizes repairable electronics with modular component design. Cloud frames with swappable connectivity modules qualify for public procurement preference.
- Voice-Assistant Convergence:Integration with Alexa and Google Home ecosystems creates hands-free content navigation. This technology pairing opens senior living facility contracts.
Industry Challenges
- FCC Equipment Authorization Timelines:Radio frequency certification for new cellular variants extends 12-18 months. This delays product launches relative to Wi-Fi-only competitors.
- Legacy PMS Integration Complexity:Hospitality property management systems require custom API bridges for programmatic content scheduling. Each chain demands bespoke middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Cloud Picture Frame Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Frames, Digital Displays, Wi-Fi Frames, Cloud-enabled Screens End User: Households, Businesses, Educational Institutions, Hospitality Usage Scenario: Personal Display, Advertising, Event Sharing, Social Media Integration Connectivity: Wi-Fi, Bluetooth, USB, Cloud Storage |
| Companies Covered | Aura, Nixplay, PhotoSpring Inc., Glimpse LLC, Aluratek Inc., ViewSonic Corp., Sungale Inc., Sony Group Corp., LG Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Cloud Picture Frame Market Trends and Innovations
Edge AI inference engines are migrating photo curation algorithms from cloud servers to local frame processors. This architectural shift responds to data sovereignty pressures while reducing latency for real-time content personalization.
E-ink color panels with reflective display technology are absorbing ambient light rather than emitting it. Museum and gallery buyers in Italy and Spain are adopting these units for permanent exhibition installations. The technology is absorbing premium positioning from backlit LCD alternatives by eliminating glare and power consumption constraints.
The EU AI Act's emotion-recognition classification as high-risk AI forces facial detection feature removal from European SKUs. Manufacturers must maintain parallel software branches: biometric-capable for US FCC jurisdictions, stripped-down for GDPR markets. Hospitality chains with cross-border deployments face SKU fragmentation and compliance documentation multiplication.
Subscription bundling with photo printing services is altering household purchase calculus. Retail channels in Germany now lead with lifetime cloud storage plus quarterly print delivery packages. This model displaces pure hardware margin extraction with recurring revenue streams that reduce price sensitivity at point of sale.
Digital Cloud Picture Frame Market Segmentation
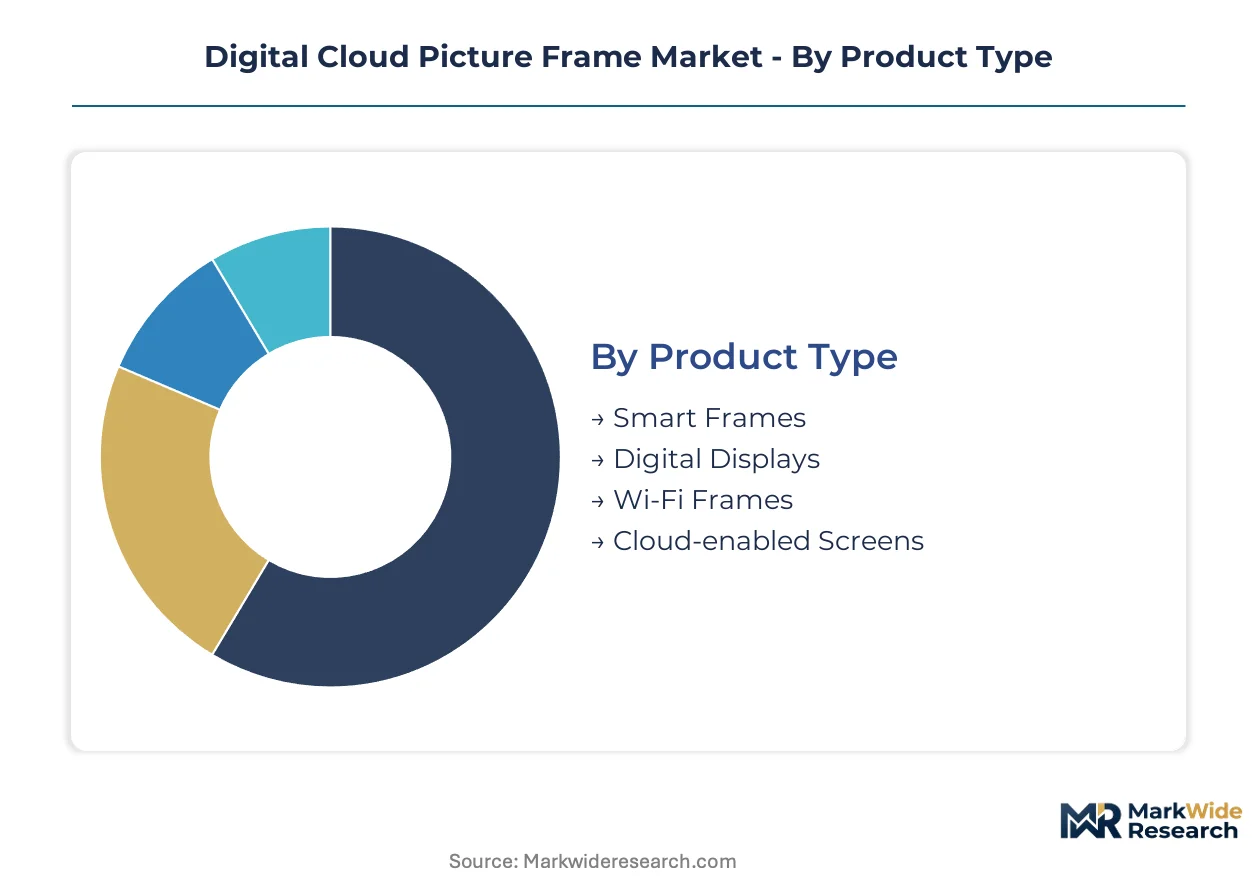
Digital cloud picture frames fragment across four structural axes that reshape procurement patterns and margin capture. Product type determines hardware-versus-subscription revenue splits. End user concentration in hospitality chains versus household units dictates sales cycle length and customization depth.
Product Type:
Display technology and cloud integration depth separate hardware-only purchases from recurring revenue platforms.
- Smart Frames:Embedded processors run local photo curation algorithms with edge AI inference. Hospitality chains in Germany deploy these for GDPR-compliant lobby displays that minimize cloud data exposure.
- Cloud-enabled Screens:Full remote management infrastructure supports programmatic content scheduling across distributed networks. Retail and hotel chains pay premium rates for real-time update capabilities without on-site IT intervention.
- Digital Displays:Static panels without native cloud connectivity require manual content loading via USB or SD card. These units serve price-sensitive household segments and legacy signage replacement cycles.
- Wi-Fi Frames:Networked displays leverage existing residential and enterprise infrastructure for photo synchronization. Compatibility with standard routers drives volume penetration in consumer markets.
Wi-Fi Frames lead on scale; Cloud-enabled Screens lead on momentum.
End User:
Customer type determines procurement complexity, with institutional buyers demanding API integration and compliance documentation.
- Hospitality:Hotel chains in France and Germany procure bulk volumes for lobby and guest room deployments. Property management system integration requirements extend sales cycles but deepen contract values.
- Households:Family-oriented sharing features drive subscription attachment rates. Mobile app ecosystems lock in recurring revenue through automatic photo syncing from smartphones.
- Businesses:Corporate deployments emphasize brand consistency across distributed office networks. Custom middleware bridges connect frames to internal content management systems.
- Educational Institutions:K-12 schools in the United States seek parental-controlled touch-enabled units for classroom content distribution. This application remains underpenetrated relative to consumer households.
Hospitality commands the deepest contract values; Educational Institutions offer the steepest expansion trajectory.
Usage Scenario:
Application context separates passive viewing from active revenue-generating deployments.
- Advertising:Programmatic content scheduling enables hospitality and retail chains to monetize display real estate. These deployments generate recurring platform fees rather than one-time hardware margins.
- Personal Display:Family photo viewing in residential settings drives hardware-plus-subscription bundling. Quarterly print delivery packages now accompany cloud storage plans in German retail channels.
- Event Sharing:Temporary installations at weddings and corporate gatherings favor rental models over purchase. Short-term deployment cycles compress customer lifetime value.
- Social Media Integration:Direct feeds from Instagram and Facebook reduce friction for younger demographics. API dependency creates platform risk if social networks restrict third-party access.
Advertising generates the highest revenue per unit; Personal Display captures the widest installed base.
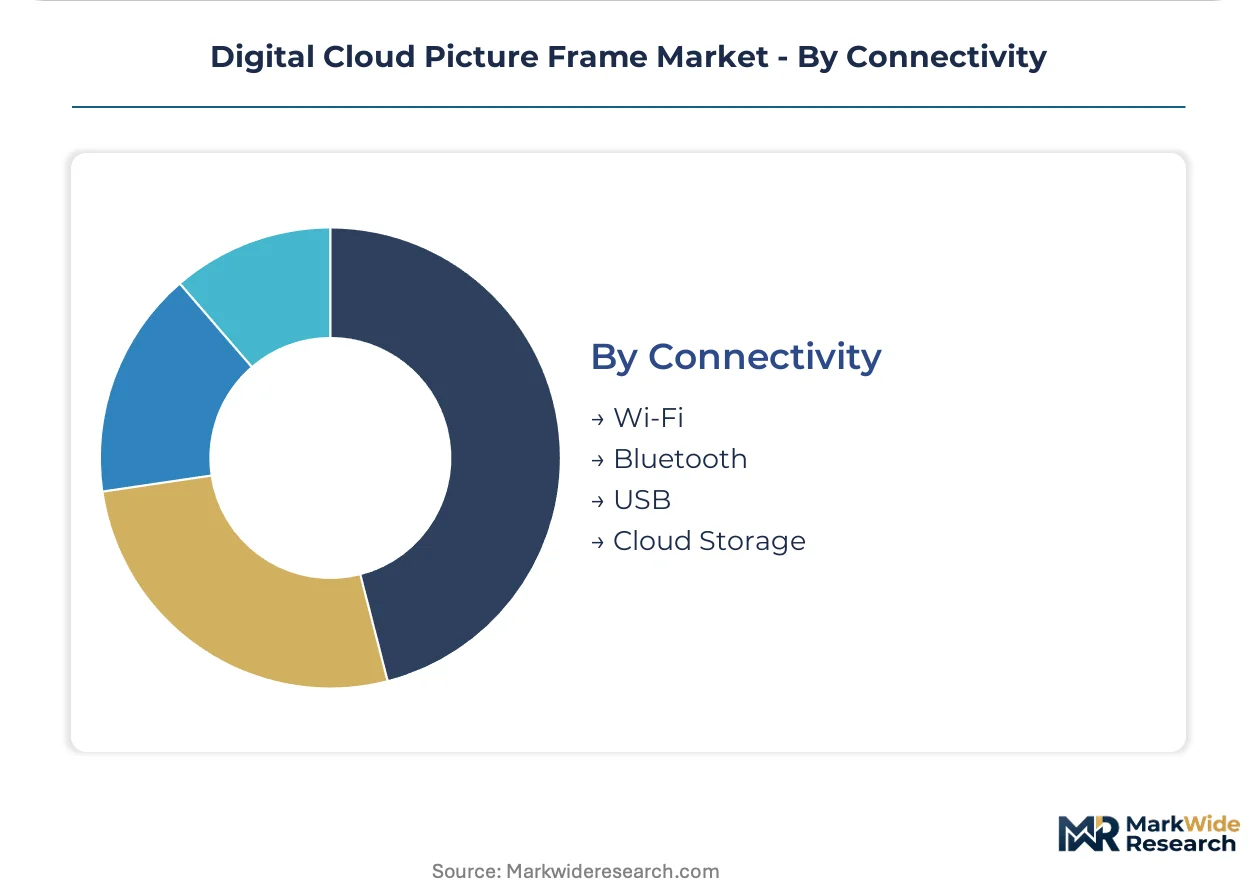
Connectivity:
Network architecture determines deployment flexibility and infrastructure dependency.
- Wi-Fi:Compatibility with existing residential and enterprise networks drives lowest total cost of ownership. FCC equipment authorization governs radio frequency emissions for devices sold in the United States.
- Cloud Storage:Direct server synchronization bypasses local network limitations for rural healthcare and field marketing deployments. GDPR cross-border data friction forces redundant EU infrastructure investment.
- Bluetooth:Short-range pairing suits single-user content loading without internet dependency. Limited range constrains commercial applications requiring remote management.
- USB:Physical media transfer serves air-gapped environments and legacy workflow integration. Manual processes exclude real-time content updates.
Wi-Fi dominates installed volume; Cloud Storage is gaining share fastest as cellular modules expand addressable geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospitality sector outpaces France in cloud-connected lobby display procurement, while the United States leads educational touch-frame adoption for K-12 classrooms. Regulatory divergence between GDPR jurisdictions and FCC-governed markets forces parallel product architectures.
United States
K-12 institutions drive demand for parental-controlled touch-enabled frames, with California and Texas school districts piloting classroom content distribution networks. FCC equipment authorization governs radio frequency emissions for Wi-Fi and cellular variants, extending certification timelines to 12-18 months for new product launches. Greater Boston hosts edtech procurement clusters where institutional buyers evaluate GDPR-compliant architectures for future-proofing.
Germany
Hotel chains in Bavaria and North Rhine-Westphalia retire static lobby displays for programmable cloud-connected screens, generating bulk procurement volumes. The EU AI Act's biometric data protocols force design teams toward privacy-preserving architectures without facial detection. Berlin-Brandenburg concentrates smart home penetration and digital signage replacement cycles ahead of neighboring European markets.
France
Hospitality property management systems in Paris and Lyon demand custom API bridges for programmatic content scheduling, extending sales cycles but deepening contract values. GDPR cross-border data friction restricts cloud server placement for citizen photo synchronization, forcing redundant infrastructure investment. Auvergne-Rhône-Alpes hosts manufacturing clusters evaluating modular component designs for EU Green Deal e-waste compliance.
China
Panel substrate suppliers concentrate 70% of global IPS and TFT-LCD output, with Yangtze River Delta foundries allocating capacity across consumer electronics verticals. MIIT radio type approval governs cellular connectivity modules for domestic and export markets. Pearl River Delta assembly clusters serve both branded specialists and contract manufacturers with component ecosystem density.
Japan
METI efficiency standards shape display power consumption requirements for residential and commercial deployments. Kanto region electronics retailers bundle subscription services with hardware sales, shifting revenue models toward recurring software streams. Osaka-based hospitality groups test voice-assistant convergence with Alexa and Google Home ecosystems for senior living facility contracts.
Digital Cloud Picture Frame Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform operators capturing margin from remote content management infrastructure while hardware fabricators compete on panel sourcing and assembly cost. The vendor base organizes around three strategic archetypes: mobile-app ecosystem builders, hospitality-focused system integrators, and display panel OEMs with downstream brand licensing. M&A activity concentrates on cloud software capabilities, while capacity expansion targets cellular module integration for rural healthcare and field marketing deployments.
Within the mobile-app ecosystem tier, Aura and Nixplay exemplify platform-first positioning where proprietary synchronization technology anchors household user retention. PhotoSpring Inc. occupies a specialist position in touch-enabled educational deployments with parental control architectures. ViewSonic Corp. and Sony Group Corp. represent diversified electronics conglomerates leveraging display panel supply chain integration across consumer and commercial product lines.
| Leading Market Players |
|---|
| Aura |
| Nixplay |
| PhotoSpring Inc. |
| Glimpse LLC |
| Aluratek Inc. |
| ViewSonic Corp. |
| Sungale Inc. |
| Sony Group Corp. |
| LG Corp. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into panel substrate sourcing anchors pricing power for display OEMs while compressing margins for pure-play assemblers. The Yangtze River Delta concentration of IPS and TFT-LCD foundries creates tiered procurement leverage, with volume buyers securing preferential allocation during semiconductor capacity crunches.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for entry-tier Wi-Fi frames. Three-tier pricing structure across premium, standard, and economy levels separates cloud-enabled screens with cellular modules from basic USB-loading units. Price differentiation rests on GDPR certification tier and hospitality PMS integration depth. Cost compression in the economy tier is intensifying because smartphone screen substitution erases casual viewing use cases. Educational institutions exhibit highest price sensitivity; hospitality chains with cross-border deployments show lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Rotterdam, and Los Angeles form a hub-and-spoke pattern for finished goods deployment. Panel substrate supply concentrates in China, South Korea, and Taiwan, with Yangtze River Delta foundries allocating capacity across consumer electronics verticals. Component dependencies include IPS/TFT-LCD substrates, cellular modem chipsets, and cloud storage infrastructure. Single-source vulnerability in Asian panel suppliers exposes procurement timelines to foundry capacity reallocation. Distribution runs through branded OEM direct channels, hospitality system integrators, and consumer electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hospitality procurement shifts toward GDPR-compliant architectures with edge AI inference and modular repairability. Premium specifications now dominate replacement cycles over entry-tier hardware.
For Market Incumbents: Extend cloud software capabilities through acquisition of niche platform operators to deepen subscription revenue attachment. Fortify panel supply agreements with Yangtze River Delta foundries before capacity reallocation to automotive displays. Cellular module integration represents the priority R&D vector for rural healthcare and field marketing expansion. For New Entrants and Emerging Players: Enter via the underpenetrated K-12 educational segment in the United States, where parental-controlled touch-enabled frames lack established vendor relationships. Voice-assistant convergence for senior living facilities offers a second white-space target with lower competitive density. A direct-to-school procurement model bypasses consumer retail slotting fees. For Investors and Strategic Acquirers: Roll-up economics work for mobile-app ecosystem builders because household subscription retention creates predictable recurring revenue streams with low churn. The 5-10 year viability window favors platform operators over hardware fabricators as margin capture shifts to remote content management infrastructure. Watch for inflection signals in FCC equipment authorization timelines for cellular variants, as delays compress launch windows relative to Wi-Fi-only competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Proprietary mobile app ecosystems lock in household users with automatic photo syncing from Aura and Nixplay. |
| Regulatory Certification Investment | Early GDPR and EU AI Act compliance certification captures institutional hospitality buyers in Germany and France. |
| Cellular Module Integration | Embedded LTE/5G radios from Qualcomm and MediaTek expand addressable geography beyond Wi-Fi infrastructure zones. |
| Backward Integration | Captive panel sourcing from Yangtze River Delta foundries secures allocation priority during semiconductor capacity crunches. |
| Voice-Assistant Partnership | Alexa and Google Home integration opens senior living facility contracts in Japan's Kanto region. |
Research Methodology
Coverage spans Germany, the United States, France, China, and Japan, with primary inputs from each regional cluster. The approach combines structured interviews with hospitality procurement directors, K-12 technology coordinators, display panel supply chain managers, and cloud platform product leads with secondary validation. Secondary sources include FCC equipment authorization filings, EU AI Act implementation guidance, MIIT radio type approval records, METI efficiency standard disclosures, and customs trade data for panel substrate flows. Bottom-up unit shipment modeling triangulates against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, end user archetype, usage scenario, and connectivity architecture, with regulatory jurisdiction modeled as an overlay dimension given GDPR and FCC divergence. CAGRs derive from fitted growth curves against historical replacement cycle data and hospitality capital expenditure patterns. Industry-specific inputs include property management system integration complexity scores and educational procurement budget elasticity estimates.
Inputs from hospitality procurement databases and K-12 technology adoption surveys were available through the study window; gaps in real-time panel substrate pricing introduce uncertainty bands around hardware margin projections. Forecasts reflect documented assumptions regarding replacement cycle duration and regulatory implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Camera Case Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Ereader Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Global Home Audio System Market