
 Sports Electronics Market | 2026-2036
Sports Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Electronics Market Analytics
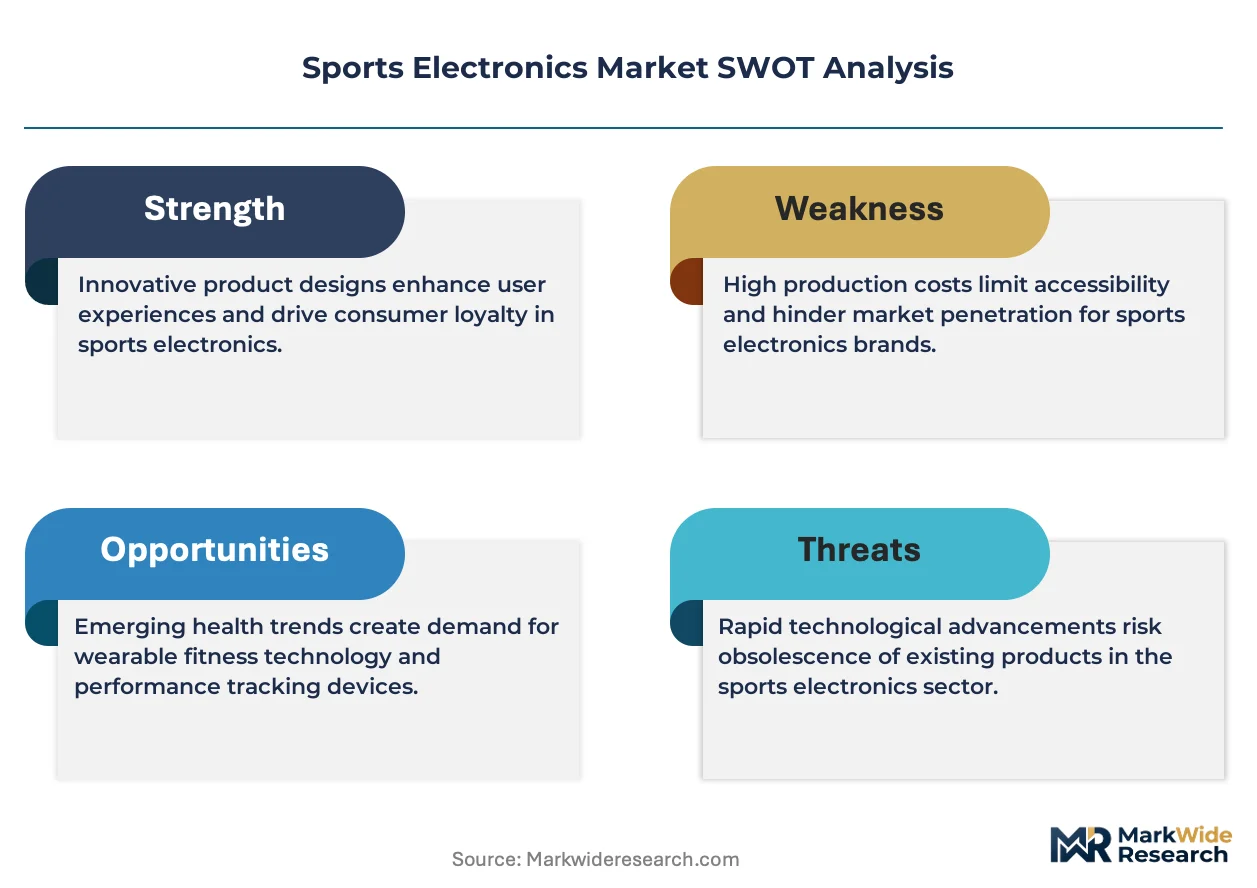
The sports electronics industry is restructuring around a sharp divergence between premium medical-grade wearables and commodity fitness bands. Garmin Ltd. anchors the premium tier through its proprietary GPS chipset architecture and aviation-grade durability standards. Apple Inc. competes by leveraging its vertically integrated ecosystem of health sensors and mobile software. Polar Electro Oy differentiates through specialized heart-rate variability algorithms designed for elite endurance athletes.
Sports electronics encompass devices that capture, transmit, and analyze physiological and kinematic data during athletic activity, typically integrating MEMS accelerometers, optical photoplethysmography sensors, and low-energy wireless protocols to monitor performance metrics in real time. Their primary commercial purpose is to translate raw biomechanical signals into actionable training intelligence for coaches, medical staff, and self-directed athletes. Wearables and fitness trackers occupy the dominant revenue position within product type segments, while GPS and motion sensor technologies command the highest attachment rates in professional team deployments. IoT-enabled devices represent the fastest-expanding technology category as cloud analytics platforms deepen their integration with hardware endpoints.
FDA oversight of software-as-medical-device classifications and FCC certification requirements for radio-frequency transmitters shape product development timelines and market entry pathways for US-focused manufacturers. The EU AI Act and GDPR impose additional algorithmic transparency and data residency obligations on vendors serving European athletic organizations. Stakeholders must monitor evolving interoperability standards between competing health data platforms as federation-level procurement begins favoring open-ecosystem architectures over proprietary silos.
Market Dynamics
Professional sports franchises now mandate biometric monitoring as a contractual condition, forcing device manufacturers to absorb medical-grade certification costs into consumer-tier pricing structures.
Growth Catalysts
- Collegiate athletic procurement:NCAA Division I programs in the United States deploy GPS-enabled performance trackers across football, basketball, and soccer rosters, creating institutional demand pipelines that cascade into professional leagues.
- EU AI Act compliance:Algorithmic transparency requirements for health data processing are accelerating vendor investment in explainable machine learning models for athlete performance prediction.
- MEMS sensor miniaturization:Advances in microelectromechanical systems enable multi-axis motion capture within form factors compatible with compression apparel and mouthguards.
Market Restraints
- Lithium battery supply concentration:Cell production for wearable power systems clusters in East Asian manufacturing corridors, exposing device assemblers to geopolitical freight disruptions and raw material quota volatility.
- FCC certification timelines:Radio-frequency transmitter approvals for low-energy Bluetooth and ultra-wideband protocols extend hardware release cycles by eight to fourteen months for US-market entrants.
- Optical sensor accuracy ceilings:Photoplethysmography-based heart rate monitoring degrades significantly during high-impact collision sports, limiting addressable market penetration in American football and rugby applications.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentive structures for electronics manufacturing invite contract assembly relocation to Gujarat and Tamil Nadu industrial corridors, reducing landed cost exposure for price-sensitive fitness band segments.
- Recovery analytics white space:Sleep architecture and autonomic nervous system monitoring remain underdeveloped relative to exertion metrics, presenting opening for specialized algorithm vendors.
- Telehealth platform integration:Post-pandemic remote patient monitoring reimbursement codes in the United States create channel for sports electronics data streams to flow into clinical cardiovascular risk assessment workflows.
Industry Challenges
- Firmware security talent scarcity:Embedded systems engineering capable of implementing FDA cybersecurity guidance for software-as-medical-device classifications commands premium compensation that strains mid-tier vendor operating models.
- Interoperability standard fragmentation:Competing health data exchange protocols between Apple HealthKit, Google Fit, and Garmin Connect force developers into redundant API maintenance burdens.
- GDPR data residency enforcement:European athletic organizations now require physiological data storage within EU jurisdictional boundaries, complicating cloud analytics architectures built on US-centric server infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Electronics Market |
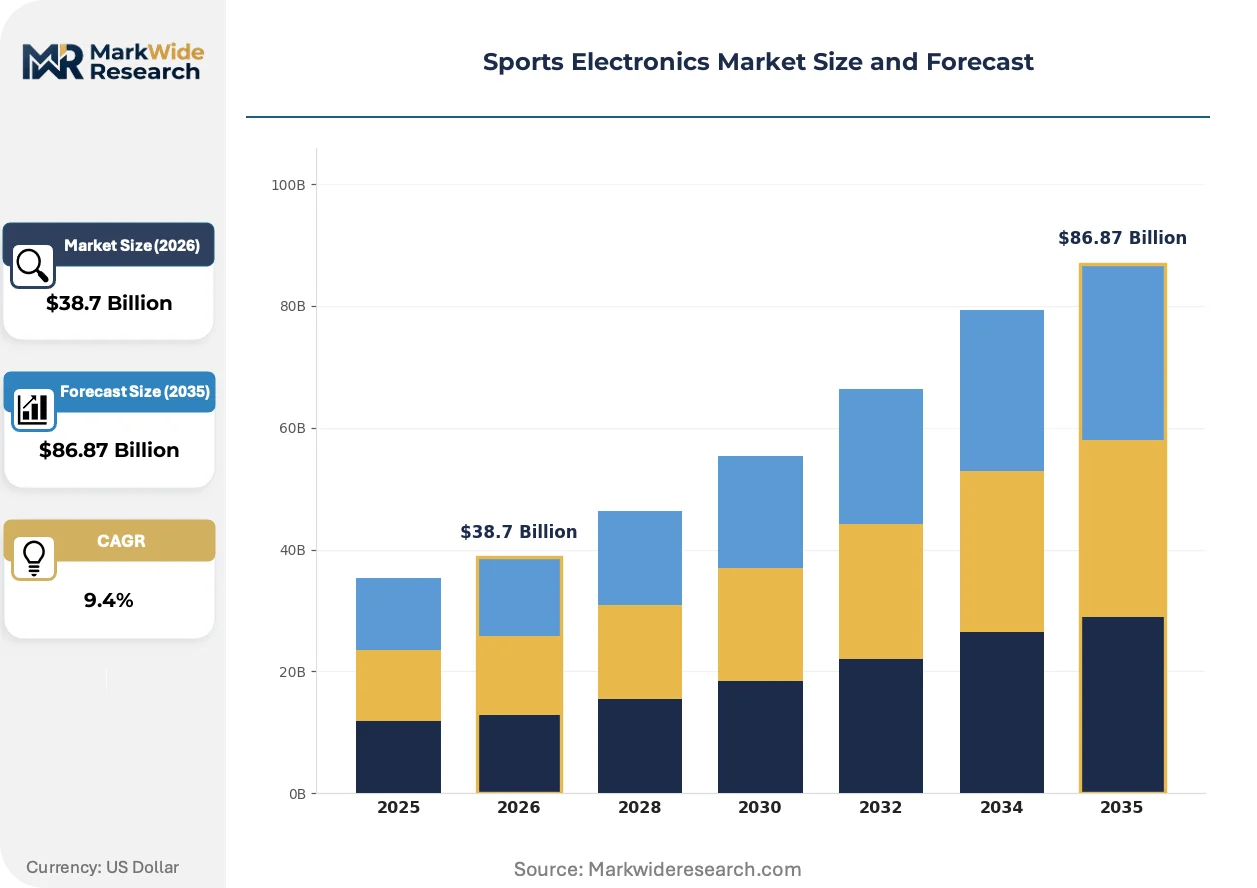
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Fitness Trackers, Smart Glasses, Headphones Technology: IoT, Bluetooth, GPS, Motion Sensors End User: Athletes, Coaches, Fitness Enthusiasts, Sports Teams Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Garmin Ltd., Fitbit (Google LLC), Apple Inc., Samsung Electronics Co., Ltd., Polar Electro Oy, Suunto Oy, Under Armour, Inc., Huawei Technologies Co., Ltd., Catapult Group International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Electronics Market Evolving Landscape
Sensor fusion architectures are collapsing the distinction between training-load management and clinical cardiac monitoring, redefining competitive boundaries between consumer electronics and medical device incumbents.
Photoplethysmography arrays with multi-wavelength LED configurations now enable continuous blood oxygen saturation and hydration status estimation from wrist-worn devices. Olympic training centers and professional cycling teams have adopted these systems for altitude camp monitoring. This capability expansion is absorbing functionality previously exclusive to pulse oximetry medical devices into consumer-accessible price bands.
The EU AI Act's risk classification framework for biometric identification systems now captures predictive injury algorithms deployed by elite sports organizations. Device vendors serving European football clubs must document training data provenance and algorithmic decision logic for regulatory inspection. German Bundesliga medical departments have initiated procurement clauses requiring such documentation as a contractual precondition.
Athletic departments at US universities now bundle wearable subscriptions into scholarship packages, converting capital equipment purchases into recurring service relationships. Equipment managers negotiate enterprise licensing across entire rosters rather than individual athlete retail transactions. This restructuring concentrates purchasing authority with procurement officers in Texas, Florida, and California institutional systems.
Sports Electronics Market Segmentation
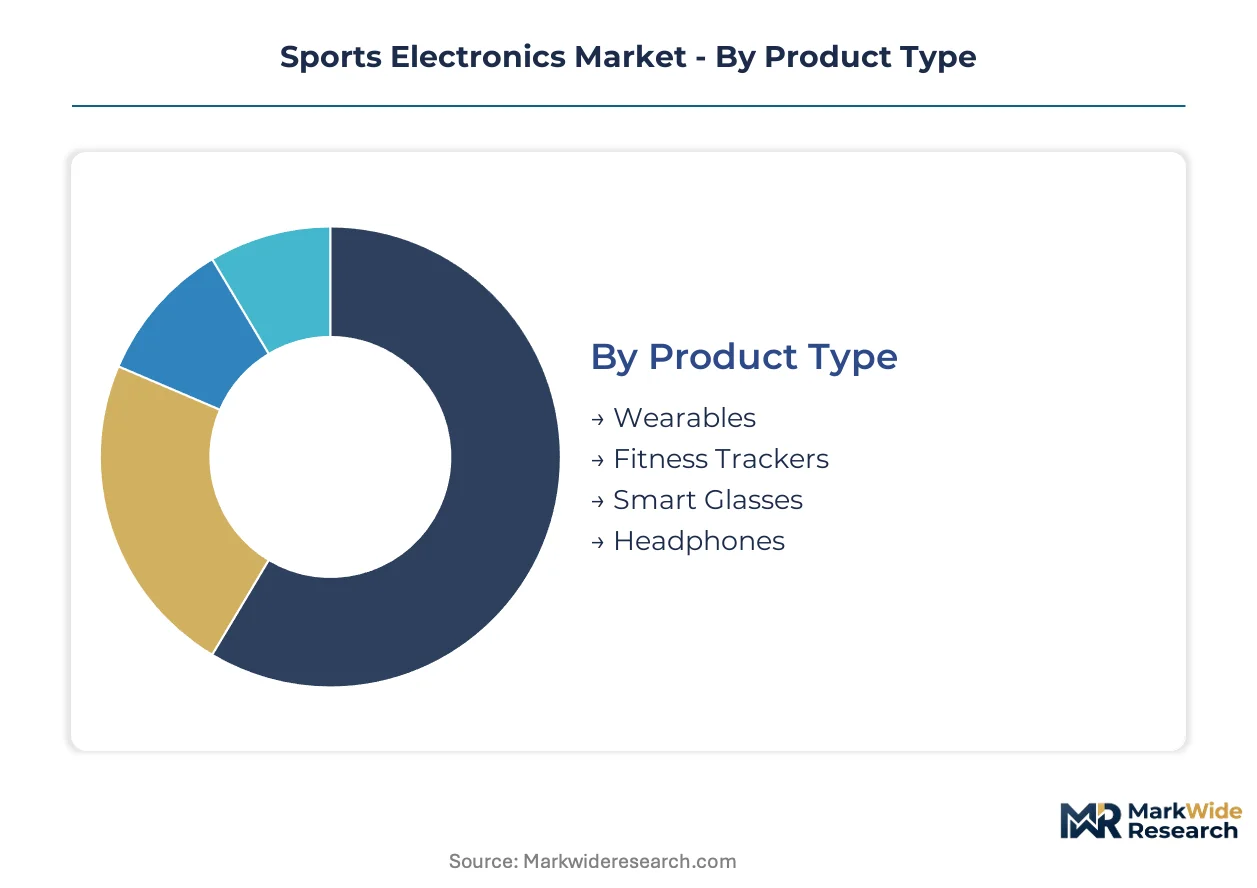
Sports electronics manufacturers calibrate product roadmaps around distinct upgrade cycles that vary sharply by user sophistication. Collegiate athletic departments replace GPS-enabled team systems on three-year refresh schedules, while individual fitness enthusiasts exhibit longer replacement intervals for wrist-worn devices.
Product Type:
Replacement velocity diverges dramatically between institutional procurement and consumer self-purchase, with enterprise buyers demanding backward compatibility during hardware transitions.
- Wearables:Compression garments and smart textiles integrate textile-embedded electrodes with conductive thread circuitry for continuous electromyography monitoring. NCAA Division I football programs in Texas and Florida drive bulk procurement of full-body sensor suits for practice-load quantification.
- Fitness Trackers:Wrist-worn devices combine optical photoplethysmography with tri-axial accelerometry for step-count and heart-rate surveillance. Garmin's proprietary Elevate sensor stack commands premium positioning among amateur endurance athletes in Germany and Switzerland.
- Smart Glasses:Heads-up displays overlay real-time pace and power metrics within cyclist and runner fields of vision.
- Headphones:Bone-conduction audio systems preserve situational awareness during outdoor training while delivering biometric feedback cues.
Volume placements concentrate in Fitness Trackers; the faster expansion belongs to Wearables.
Technology:
Component cost tiers separate professional-grade deployments from consumer accessibility, with certification requirements adding disproportionate overhead to certain protocol stacks.
- IoT:Cloud-connected architectures stream encrypted physiological batches to analytics platforms for longitudinal performance trending. Bundesliga medical departments in Germany now mandate EU AI Act-compliant algorithmic documentation for predictive injury models running on these pipelines.
- Bluetooth:Low-energy protocols enable smartphone tethering for firmware updates and social sharing functionality. FCC certification timelines for radio-frequency transmitters extend hardware release cycles by eight to fourteen months for US-market entrants.
- GPS:Multi-constellation receivers access satellite networks for positional accuracy within one meter for outdoor pace and distance calculation.
- Motion Sensors:MEMS accelerometers and gyroscopes capture three-dimensional kinematic data for technique analysis and impact detection.
Bluetooth dominates unit shipments; IoT-enabled systems are climbing the fastest as cloud analytics deepen hardware integration.
End User:
Buyer sophistication determines acceptable price points and required feature depth, with institutional purchasers demanding medical-grade documentation unavailable to casual consumers.
- Athletes:Individual competitors prioritize battery longevity and water resistance for autonomous training sessions. Olympic training centers in Switzerland and Australia deploy multi-wavelength photoplethysmography arrays for altitude camp monitoring.
- Coaches:Staff members require dashboard aggregation across entire rosters for training-load balancing and injury risk stratification. NCAA equipment managers negotiate enterprise licensing rather than individual retail transactions.
- Fitness Enthusiasts:Recreational users drive volume through smartphone-integrated step counting and sleep scoring.
- Sports Teams:Franchise procurement officers mandate contractual biometric monitoring clauses that force manufacturers to absorb medical certification costs.
Individual Athletes generate the highest unit volumes; Sports Teams show the steepest expansion trajectory as contractual monitoring mandates spread.
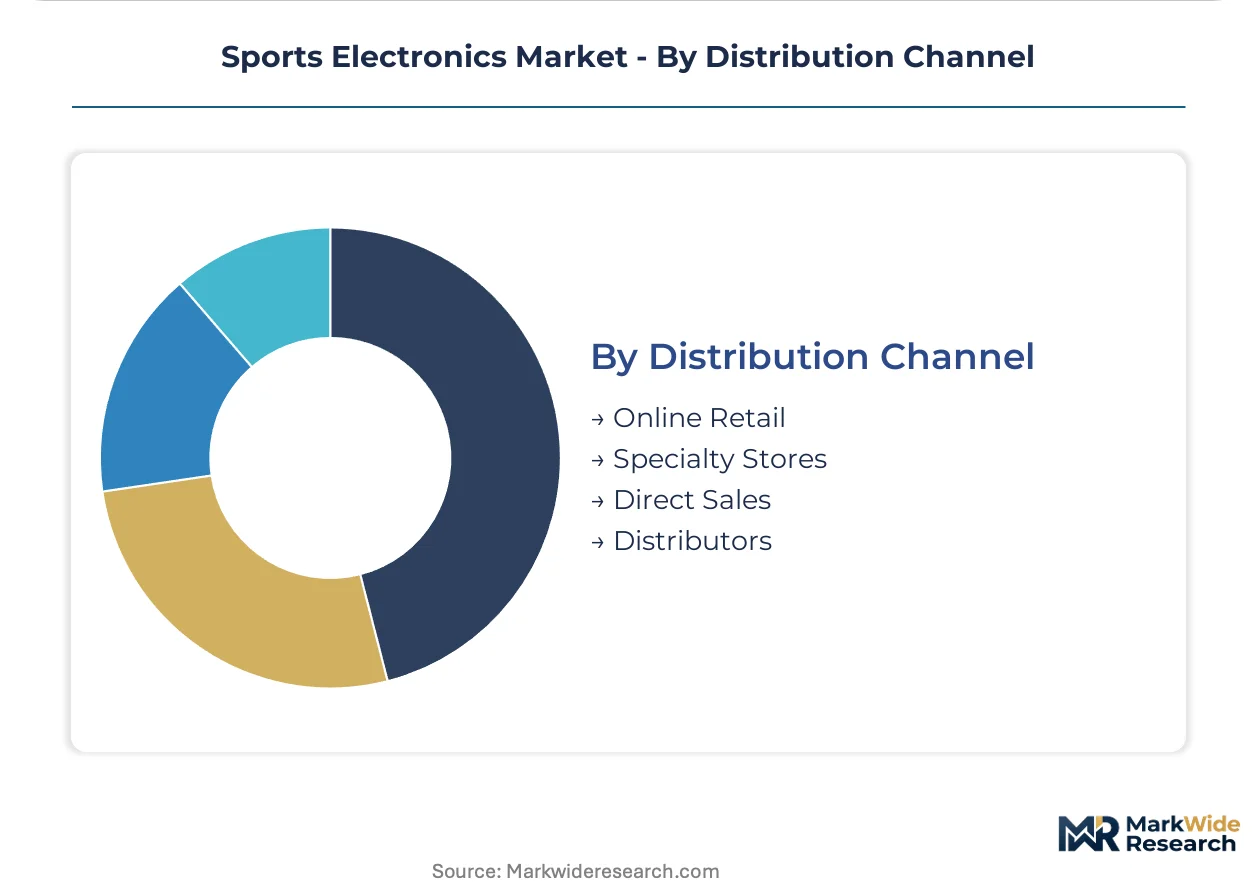
Distribution Channel:
Channel economics favor recurring service relationships over one-time hardware transactions, with enterprise accounts demanding dedicated support infrastructure unavailable through retail.
- Online Retail:Direct-to-consumer platforms enable subscription bundling for software analytics and cloud storage. India's production-linked incentive schemes for electronics manufacturing reduce landed costs for price-sensitive fitness band segments sold through these channels.
- Specialty Stores:Running and cycling shops provide fitting services and technical consultation for GPS watch selection. Staff expertise justifies premium positioning in Switzerland and Germany.
- Direct Sales:Manufacturer field teams negotiate enterprise agreements with collegiate athletic departments and professional franchises.
- Distributors:Regional wholesalers aggregate demand across smaller retail accounts in fragmented geographic markets.
Online Retail captures the greatest transaction volume; Direct Sales channels are expanding most quickly as institutional procurement concentrates purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global sports electronics assembly through its dense concentration of MEMS foundries and battery pack integrators serving wearable OEMs.
United States
NCAA Division I athletic departments in Texas and Florida drive institutional procurement of GPS-enabled performance trackers for football and basketball rosters. FDA software-as-medical-device classifications and FCC radio-frequency transmitter certifications shape product development timelines for domestic manufacturers. Greater Boston hosts specialized firmware security firms supplying embedded systems engineering for FDA cybersecurity guidance compliance.
Germany
Bundesliga medical departments mandate EU AI Act-compliant algorithmic documentation for predictive injury models deployed across professional football clubs. GDPR data residency enforcement requires physiological data storage within EU jurisdictional boundaries, complicating cloud analytics architectures. Bavaria's industrial corridor around Munich concentrates precision sensor manufacturing for endurance sports applications.
China
Domestic demand for fitness trackers accelerates through smartphone-integrated health ecosystems and municipal smart-city wellness programs. MIIT certification requirements for radio-frequency devices and GB standards for electronic product safety govern market entry pathways. The Yangtze River Delta around Shanghai and Suzhou hosts the world's densest concentration of lithium battery cell production for wearable power systems.
India
Production-linked incentive schemes for electronics manufacturing invite contract assembly relocation to Gujarat and Tamil Nadu industrial corridors, reducing landed costs for price-sensitive fitness band segments. BIS certification requirements for electronic goods and TRAI regulations on wireless device imports shape domestic market access. Bangalore's technology cluster incubates algorithm vendors specializing in recovery analytics and sleep architecture monitoring.
Switzerland
Olympic training centers deploy multi-wavelength photoplethysmography arrays for altitude camp monitoring of endurance athletes. Swissmedic medical device regulations and alignment with EU MDR standards govern clinical-grade wearable certifications. The Lake Geneva region hosts specialized R&D facilities for precision optical sensors and heart-rate variability algorithms.
Sports Electronics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade tiers, with medical-device documentation requirements forcing cost absorption into consumer pricing structures. The vendor base stratifies between vertically integrated ecosystem operators, specialized endurance-sports algorithm vendors, and contract-assembled volume producers serving price-sensitive segments. Three archetypes dominate: GPS chipset architects with proprietary RF engineering, health-sensor platform integrators leveraging mobile software ecosystems, and team-system specialists focused on institutional procurement channels. Competitive moves concentrate on M&A for algorithm talent acquisition and geographic expansion through production-linked incentive schemes in South Asian manufacturing corridors.
Within the premium-tier vector, Garmin Ltd. and Apple Inc. occupy positions defined by proprietary hardware-software integration and ecosystem lock-in strategies. Polar Electro Oy exemplifies the specialized endurance-sports archetype through its focus on heart-rate variability algorithms for elite athletic applications. Catapult Group International Ltd represents the institutional procurement specialist model serving professional team sports with GPS-enabled performance analytics. These three anchors demonstrate how competitive positioning diverges between consumer retail, medical-grade certification, and enterprise service contract business models.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Fitbit (Google LLC) |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Polar Electro Oy |
| Suunto Oy |
| Under Armour, Inc. |
| Huawei Technologies Co., Ltd. |
| Catapult Group International Ltd |
| Others |
Value Network & Pricing Analysis
NCAA Division I athletic procurement officers in Texas and Florida concentrate purchasing authority for GPS-enabled team systems, locking vendors into enterprise subscription models that bundle hardware refresh cycles with cloud analytics licensing.
Pricing Analysis
Value-based pricing anchored to athlete injury reduction outcomes now dominates professional team contracts, with Bundesliga medical departments in Germany paying premium rates for EU AI Act-compliant algorithmic documentation. Three-tier pricing structure across medical-grade certification, enterprise team licensing, and consumer retail separates Garmin's aviation-grade durability positioning from contract-assembled fitness bands serving India's price-sensitive segments. Cost compression in consumer wrist-worn devices intensifies as India's PLI schemes reduce landed costs for Gujarat-assembled units. Individual fitness enthusiasts exhibit highest price sensitivity, while collegiate athletic departments accept medical-grade premiums for contractual biometric monitoring mandates.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and China's MIIT certification requirements are reshaping sourcing patterns for wearable OEMs seeking tariff-advantaged assembly locations. MEMS foundry capacity clusters in Shenzhen, lithium battery cell production concentrates in the Yangtze River Delta around Shanghai, and precision optical sensor manufacturing localizes in Bavaria and the Lake Geneva region. Component sourcing draws from Taiwanese semiconductor fabs, Japanese gyroscope specialists, and South Korean display panel suppliers. Single-source vulnerability in East Asian battery pack integration exposes assemblers to geopolitical freight disruptions. Distribution runs through direct sales teams for institutional accounts and online retail platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware security engineering talent scarcity props pricing for medical-grade certification tiers, constraining mid-tier vendor capacity expansion and sustaining premium capture by vertically integrated ecosystem operators.
For Market Incumbents: Anchor proprietary GPS chipset architecture and aviation-grade durability standards against commoditization pressure from India's PLI-enabled contract assemblers. Absorb FDA cybersecurity guidance compliance costs into enterprise subscription pricing to lock out mid-tier competitors lacking embedded systems engineering depth. Control team-system distribution channels through dedicated field sales coverage of Texas and Florida collegiate athletic departments. For New Entrants and Emerging Players: Multi-wavelength photoplethysmography arrays for sleep architecture and autonomic nervous system monitoring offer technology-first wedge into recovery analytics white space underserved by exertion-focused incumbents. Target Bangalore's algorithm development cluster for R&D partnerships specializing in heart-rate variability algorithms. Pursue telehealth platform integration route through remote patient monitoring reimbursement codes in the United States. For Investors and Strategic Acquirers: The window for entry favors specialized endurance-sports algorithm vendors with EU AI Act-compliant documentation capabilities ahead of Bundesliga procurement mandate expansion. Long-term viability hinges on acquisition targets possessing proprietary sensor fusion IP and established clinical validation pathways. Watch FDA software-as-medical-device classification expansion as inflection signal for medical-grade wearable market boundary shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Bundesliga medical departments now mandate algorithmic documentation as contractual precondition for vendor selection. |
| India PLI Scheme Leverage | Gujarat and Tamil Nadu assembly relocation reduces landed costs for price-sensitive fitness band segments. |
| Telehealth Platform Integration | Remote patient monitoring reimbursement codes in the United States create clinical data channel expansion opportunity. |
| MEMS Sensor Miniaturization R&D | Multi-axis motion capture within compression apparel form factors enables new product category creation. |
| Firmware Security Talent Acquisition | FDA cybersecurity guidance compliance demands embedded systems engineering capabilities commanding premium compensation. |
Research Methodology
SEC filings from Garmin, Apple, and Catapult Group, EU AI Act regulatory documentation, and NCAA procurement contract disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers at Olympic training centers, equipment managers at Texas and Florida collegiate athletic departments, and regulatory affairs leads at FDA-cleared device manufacturers validated secondary estimates. Bottom-up unit shipment analysis across wearables, fitness trackers, and team GPS systems triangulated against top-down value projections from enterprise subscription revenue disclosures.
Historical trendline analysis of collegiate athletic department refresh cycles and professional team contractual biometric monitoring adoption informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, technology protocol stack, end-user sophistication tier, and distribution channel structure. CAGRs derived from regression analysis of institutional procurement pipeline data and consumer replacement interval surveys. Forecast inputs included MEMS sensor cost curves, lithium battery cell pricing volatility, and FCC certification timeline impacts on hardware release cycles.
Several conditions sit outside the modeled scope, including potential EU AI Act enforcement expansion beyond biometric identification systems, unforeseen FDA reclassification of consumer-grade heart-rate monitors as software-as-medical-device, and geopolitical disruptions to East Asian battery supply corridors. Forecasts reflect assumptions around continued collegiate athletic subscription bundling and stable reimbursement code eligibility for sports electronics data streams. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Vape Market
Consumer Electronics
Europe Cigarette Lighter Market
Consumer Electronics
FMCG Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Headsets for PC Market